
 Asia-Pacific Power Plant Maintenance Market | 2026-2036
Asia-Pacific Power Plant Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Power Plant Maintenance Market Analytics
Channel relationships between original equipment manufacturers and third-party service providers is tilting toward long-term asset management contracts. Siemens Energy AG leverages its turbine installed base to anchor comprehensive service agreements across Southeast Asian markets. Doosan Enerbility Co. Ltd. competes through localized heavy-component repair capabilities in South Korea and Vietnam. KEPCO KPS dominates nuclear and thermal maintenance within South Korea's regulated utility structure.
Asia-Pacific power plant maintenance encompasses inspection, repair, overhaul, and life-extension activities performed on thermal, nuclear, renewable, and gas-fired generation assets to sustain rated output and reliability. These services apply non-destructive testing protocols, thermal spray coatings, and precision alignment procedures to restore boiler tubes, turbine blades, and generator windings to original equipment specifications. Predictive maintenance segments are gaining structural priority as utilities deploy condition monitoring sensors to shift from calendar-based to failure-mode-driven intervention schedules. Corrective maintenance retains the largest revenue pool across the region's aging coal fleet, though digital twins technology is attracting accelerated capital allocation for fleet-wide risk modeling.
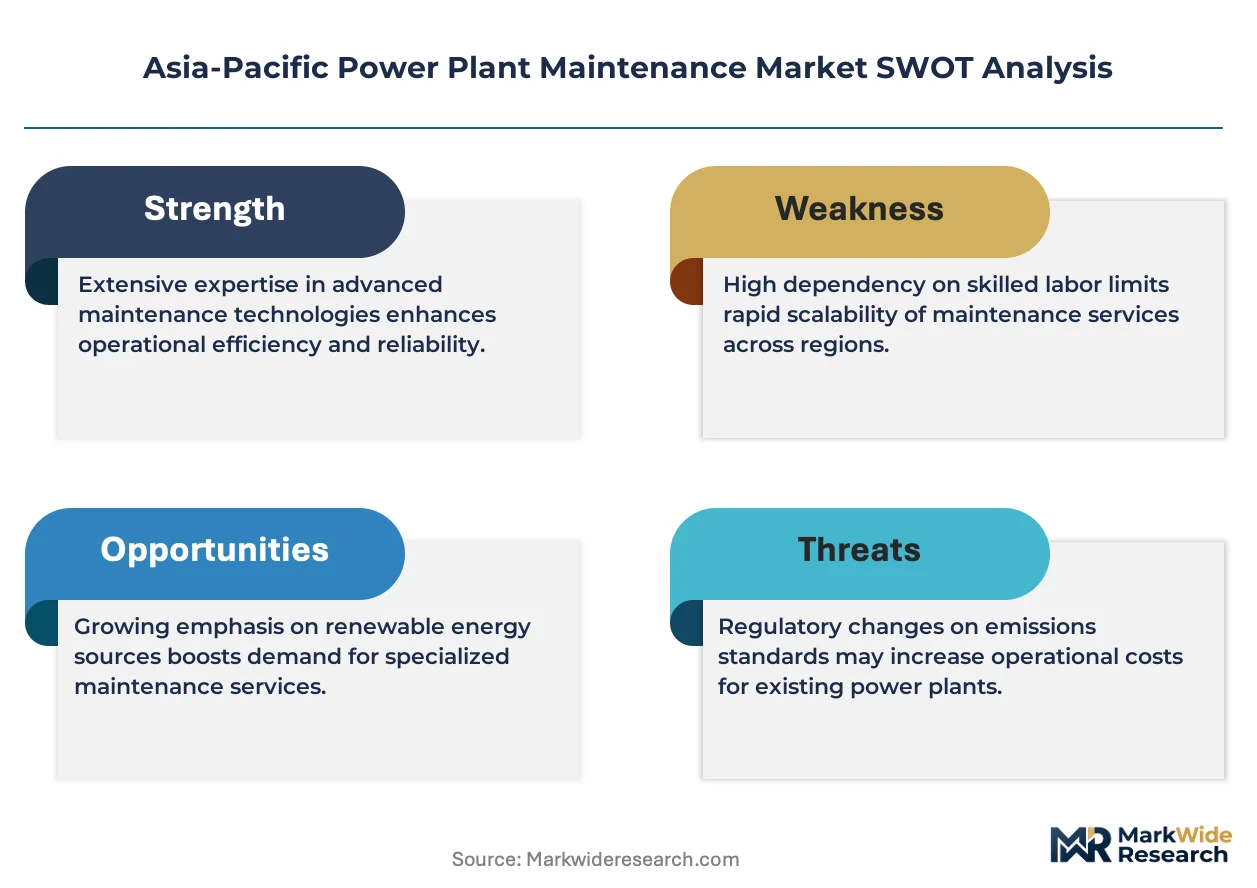
India's Central Electricity Authority enforces mandatory outage reporting that shapes procurement timelines and contractor qualification requirements for domestic power producers. Japan's METI oversees nuclear restart protocols that dictate specialized maintenance standards for idled reactor fleets seeking operational reinstatement. Australia's national electricity market regulator imposes reliability obligations that sustain consistent investment in transmission-connected plant upkeep. Stakeholders must weigh technology transition risks against the extended operational life of existing thermal assets when calibrating maintenance portfolios across divergent national energy strategies.
Market Dynamics
Indonesia's PLN dominates thermal capacity rehabilitation, while India's Central Electricity Authority tightens outage reporting mandates. These dual pressures—state utility procurement concentration and regulatory compliance escalation—are compressing contractor qualification timelines across Southeast Asian markets.
Growth Catalysts
- CEA Outage Mandates:India's Central Electricity Authority requires granular failure reporting and equipment certification, forcing domestic power producers to expand contracted maintenance scope and accelerate procurement cycles.
- Life-Extension Services:Aging coal and gas fleets across Southeast Asia require continuous boiler tube replacement, turbine blade restoration, and generator rewinding to sustain rated output beyond original design life.
- Condition Monitoring Sensors:Utilities deploy vibration analysis and thermal imaging systems to shift from calendar-based maintenance to failure-mode-driven intervention schedules, expanding predictive service revenue pools.
Market Restraints
- Specialized Welding Alloy Costs:Nickel-based superalloys for turbine blade repair face price volatility tied to mining supply from Indonesian and Philippine ore deposits, squeezing heavy-component overhaul margins.
- Nuclear Restart Protocols:Japan's METI imposes specialized maintenance standards for idled reactor fleets seeking operational reinstatement, creating regulatory friction that limits service provider entry.
- Digital Twin Substitution:Software-based fleet risk modeling reduces physical inspection frequency for some asset classes, threatening traditional corrective maintenance volume in premium service tiers.
Strategic Opportunities
- Vietnam Thermal Expansion:New coal and gas capacity additions create greenfield maintenance contract opportunities for providers establishing localized heavy-component repair capabilities.
- Renewable Hybrid Integration:Battery energy storage systems co-located with solar farms require novel thermal management and inverter maintenance protocols, opening service white space outside traditional generation.
- Australian Reliability Obligations:The national electricity market regulator mandates transmission-connected plant upkeep standards, sustaining consistent investment in high-availability maintenance services.
Industry Challenges
- Non-Destructive Testing Certification:ASME and ISO weld inspection qualifications require 18-24 month training pipelines, creating technician shortages that delay outage completion schedules.
- Legacy Control System Integration:Digital twin deployment requires data architecture bridges to 1980s-era distributed control systems, complicating sensor retrofit programs at aging coal stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Power Plant Maintenance Market |
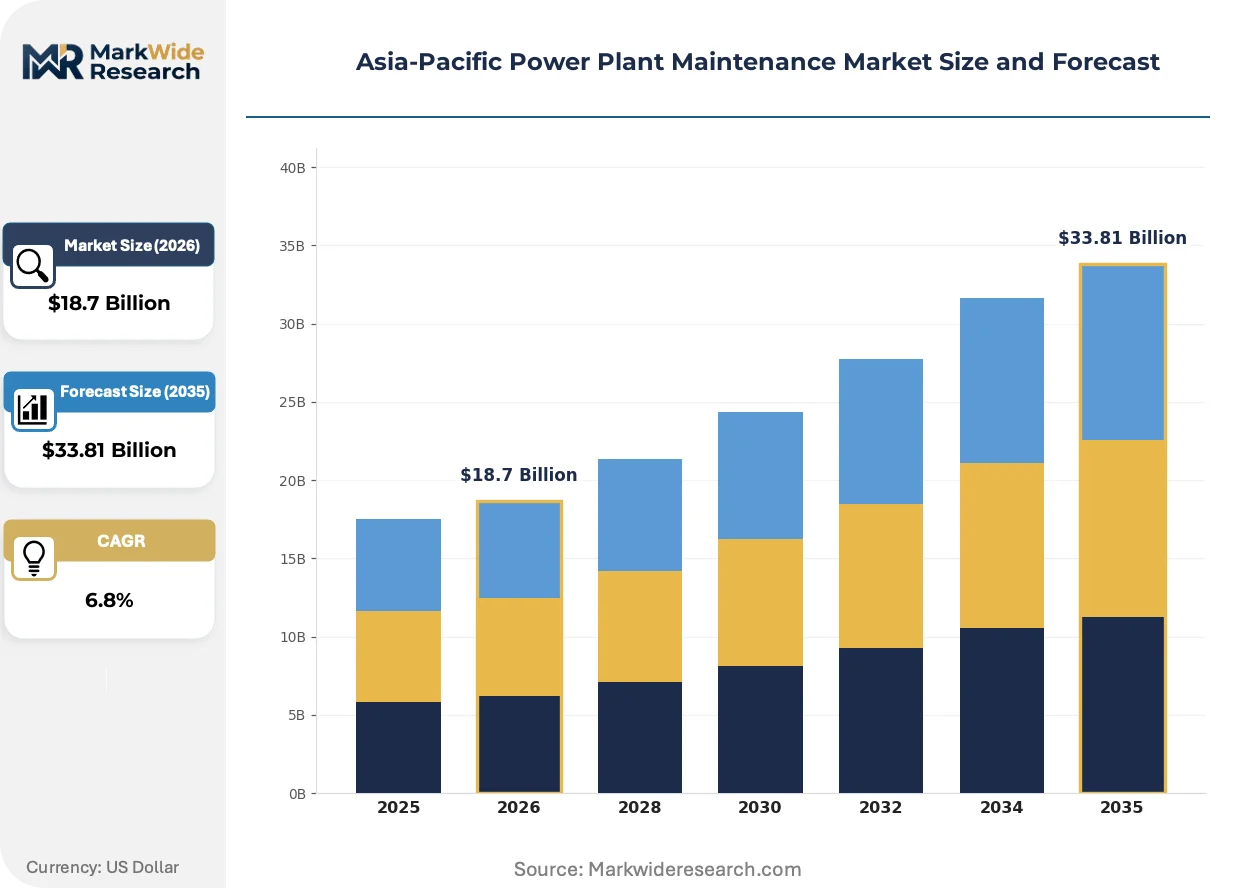
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corrective Maintenance, Preventive Maintenance, Predictive Maintenance, Overhauls Technology: Digital Twins, Condition Monitoring, Automated Maintenance, Drones End User: Utilities, Independent Power Producers, Manufacturing, Government Deployment: Onsite Services, Remote Services, Mobile Solutions, Cloud Solutions |
| Companies Covered | Siemens Energy AG, ABB Ltd., Doosan Enerbility Co. Ltd., KEPCO KPS, Voith Group, Mitsubishi Hitachi Power Systems Ltd., General Electric Company, Renom Energy Services, Toshiba Energy Systems & Solutions Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Power Plant Maintenance Market Evolving Landscape
Digital twin technology is collapsing traditional maintenance planning cycles. Utilities now simulate asset degradation trajectories before physical intervention, compressing decision timelines and reallocating capital toward predictive platforms.
Digital twins integrate real-time sensor feeds with physics-based degradation models to forecast boiler tube failures and turbine blade creep. PLN and Korean utilities deploy these systems across combined-cycle fleets, reducing unplanned outage frequency. This capability is collapsing the historical separation between engineering analysis and field execution, forcing maintenance contractors to embed simulation specialists within outage teams.
India's Central Electricity Authority mandates stricter equipment certification standards through statutory outage reporting requirements. Domestic power producers must now document root-cause failure analysis and corrective action verification. Thermal plant operators in Maharashtra and Gujarat have responded by pre-qualifying fewer, larger contractors capable of integrated inspection-repair-documentation workflows.
Long-term asset management contracts displace transactional repair orders across Southeast Asian procurement desks. State utilities in Indonesia and Vietnam now bundle 10-15 year service agreements with original equipment suppliers, compressing third-party access to turbine and generator overhaul revenue. This concentration is most visible in PLN's procurement restructuring, where comprehensive service agreements now cover over half the national thermal fleet.
Asia-Pacific Power Plant Maintenance Market Segmentation
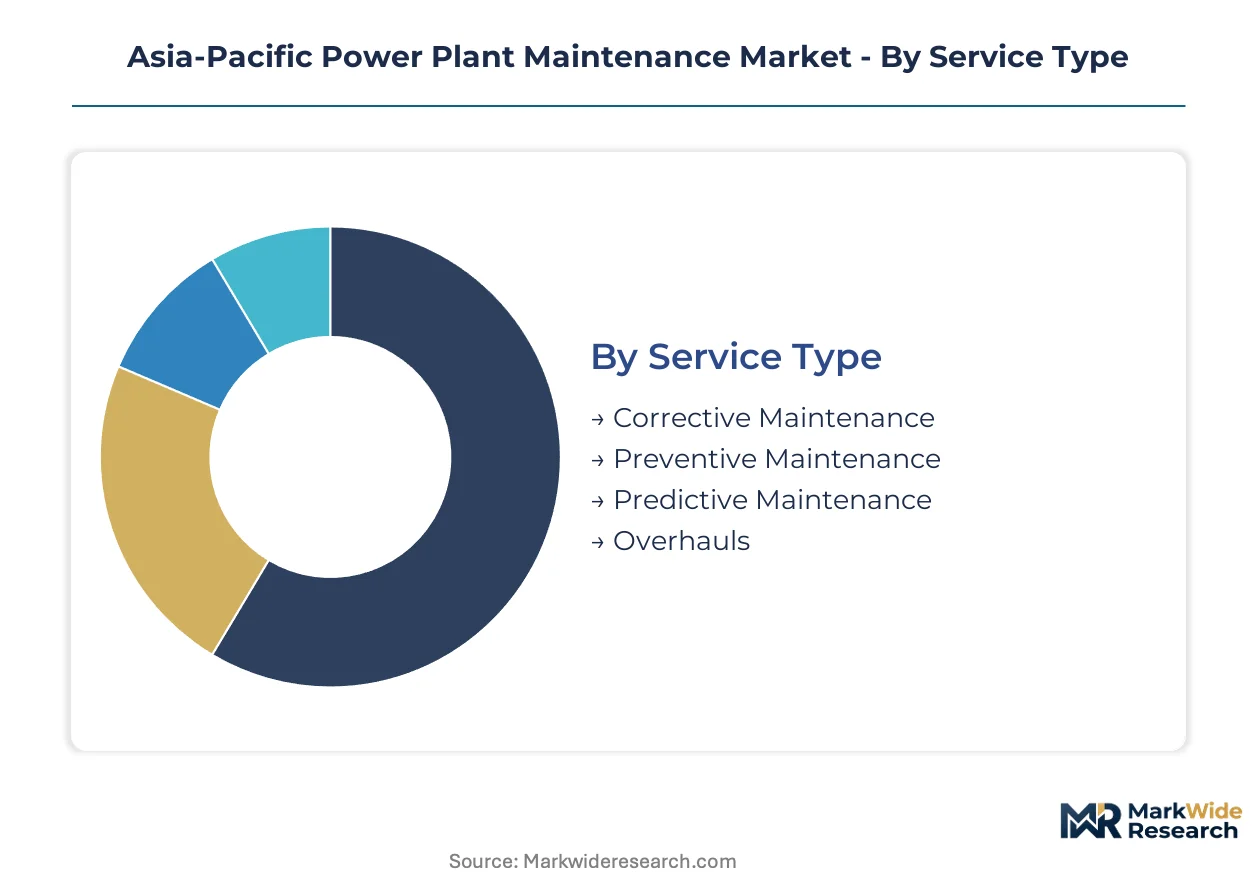
Service differentiation across the Asia-Pacific power plant maintenance market determines contractor qualification tiers and procurement contract structures. Utilities segment maintenance portfolios by outage criticality, technology integration depth, and regulatory compliance burden.
Service Type:
Mature corrective protocols dominate revenue pools while predictive platforms emerge as the capability differentiator among tier-one contractors.
- Corrective Maintenance:Reactive repair services address unplanned equipment failures through boiler tube replacement, turbine blade restoration, and generator rewinding. Indian power producers under CEA mandates concentrate demand here, as statutory outage reporting requirements force rapid response capabilities and documentation rigor.
- Predictive Maintenance:Condition-based intervention schedules leverage vibration analysis, thermal imaging, and oil analysis to forecast failures before operational impact. Southeast Asian utilities deploy these systems across aging coal fleets to compress unplanned downtime and extend asset life beyond original design specifications.
- Preventive Maintenance:Calendar-driven inspection and component replacement protocols sustain baseline reliability across regulated utility fleets.
- Overhauls:Comprehensive unit shutdown services encompassing major component replacement, system recalibration, and performance testing to restore rated output.
Corrective maintenance handles the majority of throughput; predictive maintenance is expanding most quickly on share.
Technology:
Deployment cost tiers separate enterprise-grade digital infrastructure from point-solution hardware across contractor service offerings.
- Digital Twins:Physics-based simulation platforms integrate real-time sensor data with degradation models to forecast asset failure trajectories. PLN and Korean utilities deploy these systems across combined-cycle fleets, collapsing traditional planning cycles and forcing contractors to embed simulation specialists within outage teams.
- Condition Monitoring:Continuous sensor networks track vibration, temperature, and pressure signatures to enable failure-mode-driven maintenance scheduling. Indonesian and Vietnamese utilities concentrate procurement here as they modernize thermal plant control systems.
- Automated Maintenance:Robotics and automated welding systems execute precision repairs in hazardous environments with reduced technician exposure.
- Drones:Aerial inspection platforms capture thermal and visual data from cooling towers, transmission lines, and elevated boiler structures.
Condition monitoring commands the largest installed base; digital twins are climbing the fastest on new deployment.
End User:
Customer type determines contract duration, technical specification complexity, and regulatory documentation requirements.
- Utilities:State-owned and regulated power producers operate under mandatory reliability obligations and statutory reporting requirements. India's Central Electricity Authority shapes procurement through granular outage documentation mandates, while Australia's national electricity market regulator imposes transmission-connected plant upkeep standards.
- Independent Power Producers:Merchant generators prioritize availability guarantees and rapid turnaround to maximize dispatch revenue in competitive wholesale markets.
- Manufacturing:Captive power plants serving industrial facilities require maintenance protocols synchronized with production schedules.
- Government:Public infrastructure and defense installations demand specialized security clearance and classified facility access protocols.
Utilities anchor contract volume; independent power producers are gaining share fastest as merchant capacity expands.
Deployment:
Geographic reach and labor mobility constraints shape service delivery architecture across archipelagic and continental markets.
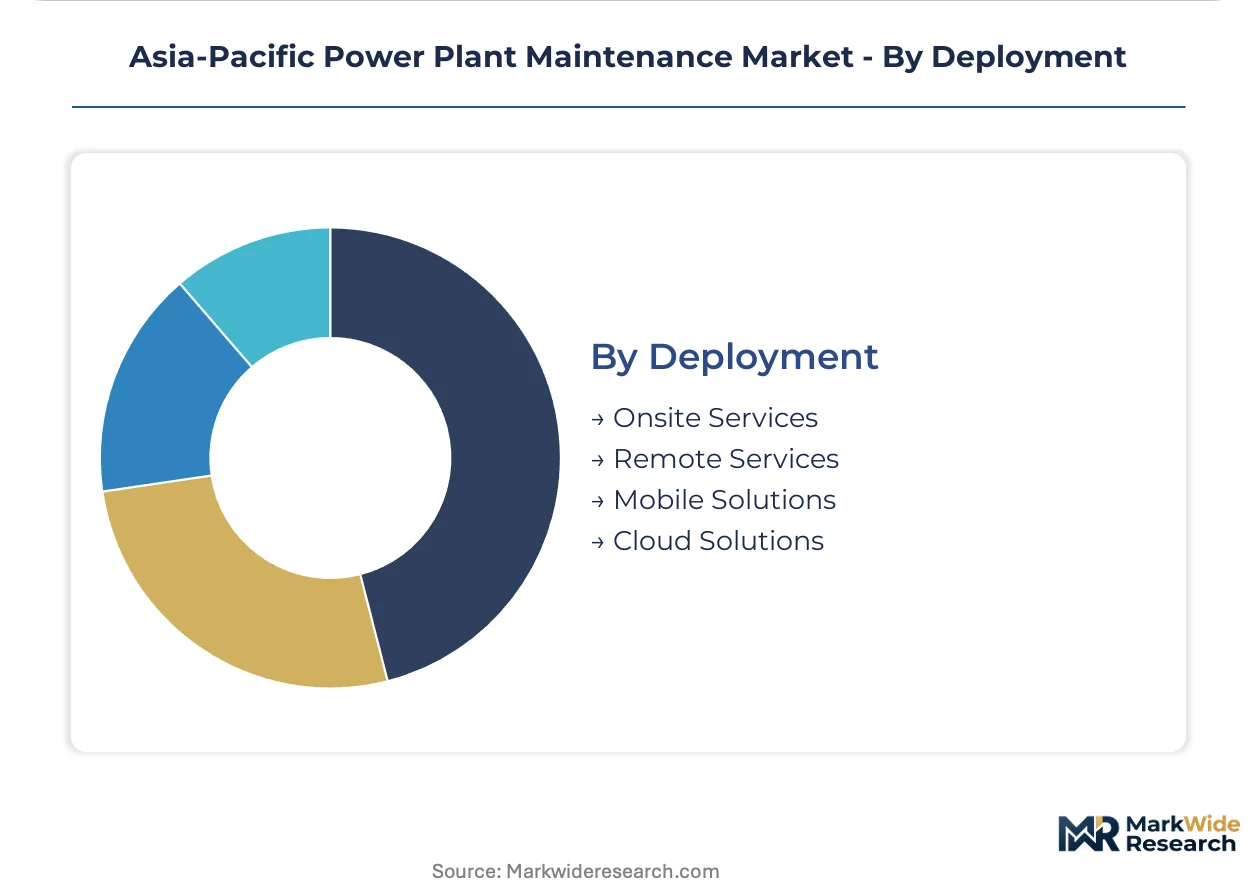
- Onsite Services:Technician-deployed inspection, repair, and overhaul execution at plant locations. Indonesia's PLN concentrates procurement here given the archipelagic dispersion of over 60 GW of thermal capacity requiring continuous rehabilitation.
- Remote Services:Centralized monitoring and diagnostic support delivered through secure network connections to plant control systems.
- Mobile Solutions:Transportable equipment and rapid-response technician teams for emergency outage support across dispersed asset bases.
- Cloud Solutions:Fleet-wide data aggregation platforms enabling benchmarking, predictive analytics, and centralized maintenance planning.
Onsite services handle the majority of revenue; cloud solutions are expanding most rapidly on infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korea and Australia where specialized nuclear and reliability-mandated services command premium rates, while Indonesian and Vietnamese markets compete on localization and volume throughput. This asymmetry shapes contractor qualification tiers and procurement contract structures across the region.
Indonesia
State-owned PLN manages over 60 GW of thermal capacity requiring continuous rehabilitation across an archipelagic dispersion that favors onsite service deployment. The national utility's procurement restructuring now bundles 10-15 year comprehensive service agreements, compressing third-party access to turbine overhaul revenue. Java-Bali corridor plants concentrate demand for boiler tube replacement and generator rewinding as aging coal fleets seek life extension.
India
The Central Electricity Authority mandates granular failure reporting and equipment certification standards that force domestic power producers to expand contracted maintenance scope. Maharashtra and Gujarat thermal plant operators pre-qualify fewer, larger contractors capable of integrated inspection-repair-documentation workflows. Western India clusters anchor corrective maintenance demand as statutory requirements accelerate procurement cycles.
South Korea
KEPCO KPS dominates nuclear and thermal maintenance within the regulated utility structure, leveraging specialized technician pipelines and heavy-component repair capabilities. The country's nuclear restart protocols under METI-influenced standards create high barriers to service provider entry. Busan-Ulsan industrial corridor hosts concentrated turbine blade restoration and precision alignment service capacity.
Vietnam
New coal and gas capacity additions create greenfield maintenance contract opportunities for providers establishing localized heavy-component repair capabilities. State utilities bundle long-term asset management contracts with original equipment suppliers, mirroring Indonesian procurement concentration. Northern coal clusters around Quang Ninh and southern gas-fired installations near Ho Chi Minh City anchor emerging service demand.
Australia
The national electricity market regulator imposes reliability obligations that sustain consistent investment in transmission-connected plant upkeep. High-availability maintenance services command premium pricing as merchant generators prioritize availability guarantees to maximize dispatch revenue. Queensland and New South Wales coal fleets concentrate predictive maintenance deployment as utilities shift from calendar-based to failure-mode-driven intervention schedules.
Asia-Pacific Power Plant Maintenance Market Competitive Landscape
Original equipment manufacturers and specialized service providers split the market between comprehensive long-term contracts and transactional repair orders. Market structure tilts toward consolidation as state utilities concentrate procurement with fewer qualified contractors capable of integrated compliance-documentation workflows. Three archetypes dominate: turbine OEMs anchoring asset management agreements, national champions leveraging localized heavy-component capabilities, and emerging specialists in predictive analytics platforms. Competitive dynamics center on geographic expansion through localized repair facilities and technology licensing for digital twin deployment.
Within the OEM-anchored tier, Siemens Energy AG and Mitsubishi Hitachi Power Systems exemplify comprehensive service agreement strategies built on installed base leverage. Doosan Enerbility Co. Ltd. occupies a position among Korean fabricators emphasizing localized heavy-component repair capabilities. KEPCO KPS represents the national champion archetype within South Korea's regulated utility structure. These three patterns—OEM comprehensive service, localized fabrication scale, and captive utility service—structure competitive positioning across Southeast Asian procurement desks.
| Leading Market Players |
|---|
| Siemens Energy AG |
| ABB Ltd. |
| Doosan Enerbility Co. Ltd. |
| KEPCO KPS |
| Voith Group |
| Mitsubishi Hitachi Power Systems Ltd. |
| General Electric Company |
| Renom Energy Services |
| Toshiba Energy Systems & Solutions Corporation |
| Others |
Value Network & Pricing Analysis
Busan-Ulsan industrial corridor's concentrated turbine blade restoration capacity anchors premium pricing power for heavy-component overhauls across Northeast Asian markets. Indonesian and Vietnamese procurement desks respond with volume-driven localization strategies that compress margins for standardized maintenance services.
Pricing Analysis
Configured-to-order pricing for specialized welding and precision alignment commands substantial premiums over standardized inspection packages. Three-tier pricing structure across premium, standard, and economy levels separates OEM-anchored comprehensive service agreements from transactional third-party repair orders. Cost compression in standard-tier boiler tube replacement is intensifying because Indonesian state utility procurement concentration forces competitive bidding on commodity maintenance scopes. Independent power producers in Australia's national electricity market exhibit lowest price sensitivity due to availability guarantee premiums, while Indian domestic producers under CEA mandates face highest sensitivity as regulatory compliance costs absorb maintenance budgets.
Supply Chain Analysis
Doosan Enerbility and KEPCO KPS hold dominant contract-manufacturing capacity for heavy-component repair across South Korea and Vietnam. Supply draws from Japan for precision instrumentation, Germany for specialized welding alloys, and China for sensor hardware and control system components. Nickel-based superalloy feedstock faces single-source vulnerability tied to Indonesian and Philippine ore deposit concentration. Distribution runs through state utility procurement desks in Indonesia and India, with long-term asset management contracts displacing spot maintenance orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin deployment across Southeast Asian combined-cycle fleets constitutes a high-growth disruption, with India's CEA outage mandates accelerating technology substitution timelines.
For Market Incumbents: Entrench comprehensive service agreement positions by embedding simulation specialists within outage teams before digital twin capabilities commoditize. Acquire localized heavy-component repair facilities in Vietnam's Quang Ninh and Ho Chi Minh City clusters to defend against Korean fabricator expansion. Certification investment in ASME weld inspection qualifications creates technician pipeline control that delays competitor outage completion. For New Entrants and Emerging Players: Vietnam's northern coal clusters around Quang Ninh represent underpenetrated greenfield opportunity as new capacity additions outpace established service provider localization. Battery energy storage thermal management protocols offer white-space entry outside traditional generation maintenance, with solar-hybrid installations requiring novel inverter service competencies. Partner with Australian merchant generators on outcome-based availability guarantees to bypass OEM-anchored procurement concentration in Southeast Asian state utilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors predictive analytics platform specialists with proven physics-based degradation modeling capabilities. Long-term viability rests on contractor qualification tier consolidation as Indian and Indonesian procurement desks pre-qualify fewer integrated inspection-repair-documentation providers. Monitor CEA equipment certification mandate enforcement intensity as regulatory escalation signal for compliance-documentation workflow acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | PLN and Korean utilities reduce unplanned outage frequency through physics-based simulation integration. |
| Localized Heavy-Component Repair Facility | Vietnamese state utilities bundle long-term contracts with providers establishing Quang Ninh and Ho Chi Minh City presence. |
| ASME Weld Inspection Certification Pipeline | Indian power producers under CEA mandates pre-qualify fewer contractors capable of integrated compliance workflows. |
| Battery Energy Storage Service Protocol Development | Solar-hybrid installations in Australia and Southeast Asia require novel thermal management and inverter maintenance capabilities. |
| Comprehensive Service Agreement Restructuring | Indonesian PLN procurement now covers over half the national thermal fleet through 10-15 year OEM-anchored bundles. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads. Secondary validation drew from EIA data, IEA reports, FERC filings, and project development databases. Bottom-up service revenue estimates triangulated against top-down generation capacity maintenance spend ratios.
Calibration against historical outage frequency and contract award patterns shaped analytical framework deployment across the analysis window. Segmentation dimensions modeled encompass service type, technology deployment tier, fuel source, generation capacity scale, and regulatory framework cluster. CAGRs derived from asset life-extension demand curves and digital twin adoption trajectories. Forecast inputs incorporated CEA mandate enforcement timelines and METI nuclear restart protocol progression.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by Korean national champions or accelerated digital twin licensing by software specialists would shift outcomes. Supply chain disruption from nickel superalloy price volatility or technician certification pipeline collapse represents primary revision risk. Quarterly review of CEA equipment certification standard updates and PLN procurement restructuring announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
Russian Federation Power EPC Market
Power Equipment
Process Air Heater Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
Power Analyzers Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
India Power EPC Market
Power Equipment
Nigeria Power EPC Market
Power Equipment
Vietnam Power EPC Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Europe Power Rental Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Magnetic Bearing Market
Power Equipment
South America Nuclear Power Plant Equipment Market