
 Power Engineering, Procurement, and Construction (EPC) Market | 2026-2036
Power Engineering, Procurement, and Construction (EPC) Market Size, Share, and Industry Trends Forecast 2026-2036
Power Engineering, Procurement, and Construction (EPC) Market Insights
Capital-intensity divergence between integrated turbine suppliers and pure construction contractors is reorganizing contract award patterns across the sector. Bechtel Corporation leverages its self-perform construction capability to capture mega-project risk premiums. Fluor Corporation anchors its competitive position through modular fabrication yards that reduce field labor exposure. Larsen & Toubro dominates South Asian thermal and nuclear EPC through captive forging and heavy engineering capacity.
Power engineering, procurement, and construction denotes a bundled delivery model where a single contractor assumes responsibility for front-end engineering design, equipment sourcing, and turnkey construction, typically governed by lump-sum or cost-reimbursable contracts with performance guarantees and liquidated damages clauses. The primary industrial purpose is to transfer completion risk from asset owners to contractors while compressing project schedules through concurrent rather than sequential activity. Design-Build and Project Management service types command premium margins due to their interface-risk concentration and scarce systems-integration talent. Mega Projects within the Project Size dimension absorb disproportionate capital but face execution risk that limits contractor appetite. Wind and Solar technology segments are expanding fastest, though Gas Turbines retains residual demand for grid-firming applications.
The US EPA and FERC shape environmental permitting and interconnection queue management, directly influencing project timelines and EPC contract structuring. India's CEA renewable purchase obligation framework and the EU Green Deal's carbon border adjustment mechanism are tightening emissions accountability across contractor supply chains. Stakeholders must monitor how evolving domestic content requirements across multiple jurisdictions alter equipment sourcing strategies and subcontractor selection criteria.
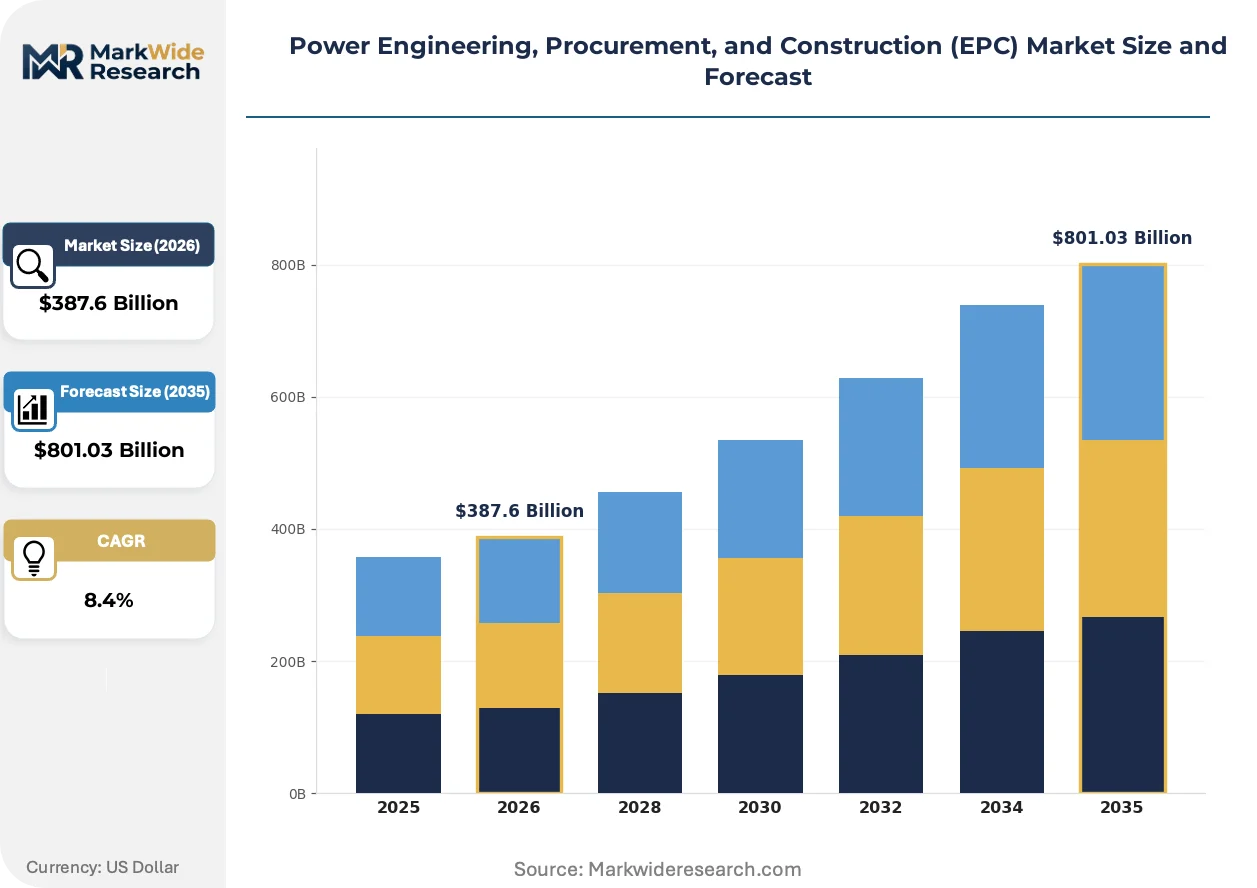
Market Dynamics
Capital allocation toward bundled EPC contracts is compressing traditional multi-vendor procurement cycles as asset owners seek single-point accountability for grid-scale renewable integration.
Growth Catalysts
- India's Renewable Purchase Obligations:State-level mandates under CEA directives compel discoms to contract integrated solar-wind-hybrid EPC services, pulling engineering capacity toward utility-scale execution.
- US Inflation Reduction Act Production Tax Credits:Domestic content bonuses are redirecting developer capital toward EPC bundling that captures both construction and equipment manufacturing incentives.
- Green Hydrogen Electrolyzer Deployment:India's National Hydrogen Mission mandates require captive renewable generation paired with electrolyzer installation, creating demand for multi-technology EPC integration.
Market Restraints
- Steel and Copper Price Volatility:Input cost swings for conductors and structural steel compress lump-sum contract margins before contingency reserves activate.
- Turbine Forging Capacity Concentration:Heavy component supply concentrates in South Korean and Chinese forging yards, creating single-source exposure for combined-cycle gas turbine projects.
- Interconnection Queue Backlogs:FERC Order 2023 implementation delays extend project COD timelines, inflating carrying costs and eroding EPC contractor risk appetite.
Strategic Opportunities
- Vietnam and Indonesia Grid Expansion:State utility procurement of distributed solar EPC remains underpenetrated relative to installed renewable potential, opening greenfield contractor entry.
- EU Carbon Border Adjustment Mechanism:CBAD phase-in creates compliance service demand for EPC firms that can document embodied carbon in steel and cement supply chains.
- Modular Fabrication-Field Assembly Convergence:Standardized skidded substation designs reduce site labor hours and enable factory quality control at port-proximate yards.
Industry Challenges
- Scarce Systems Integration Engineering Talent:Project managers capable of coordinating electrical, civil, and process disciplines across multi-hundred-megawatt sites command premium compensation that inflates overhead recovery rates.
- Liquidated Damages Exposure on Lump-Sum Contracts:Performance guarantee structures transfer completion risk to contractors without commensurate risk-adjusted pricing in competitive bidding environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Engineering, Procurement, and Construction (EPC) Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $801.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design-Build, Project Management, Construction, Maintenance End User: Utilities, Industrial Facilities, Renewable Energy Providers, Government Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Technology: Wind, Solar, Hydro, Gas Turbines |
| Companies Covered | Bechtel Corporation, Fluor Corporation, Larsen & Toubro, PowerChina, Siemens Energy, Hyundai Engineering and Construction, Mitsubishi Heavy Industries, Kiewit Corporation, McDermott International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Engineering, Procurement, and Construction (EPC) Market Trends and Innovations
Digitization of front-end engineering design is compressing project definition phases while modular construction methods are relocating value creation from field labor to controlled manufacturing environments.
Digital twin platforms for power plant commissioning are decomposing traditional sequential startup procedures into parallel virtual testing streams. EPC contractors deploying these tools reduce mechanical completion-to-COD intervals by identifying interface conflicts before physical construction. Asset owners in India's ultra-mega solar parks now mandate digital handover protocols that compress warranty negotiation cycles.
The EU Green Deal's carbon border adjustment mechanism is tightening emissions accountability across contractor supply chains. EPC firms must now document embodied carbon in structural steel and cement to avoid tariff exposure on exported power equipment. European offshore wind developers are responding by specifying low-carbon concrete mixes and regionally sourced steel in tender documents.
Asset owners are consolidating vendor relationships around integrated EPC-plus-O&M service providers capable of spanning construction through operational phases. Traditional equipment-only suppliers face displacement unless they develop captive construction capabilities or form exclusive subcontractor alliances. This pattern is most visible in US utility-scale solar procurement, where developers favor turnkey contractors over split EPC arrangements.
Power Engineering, Procurement, and Construction (EPC) Market Segmentation
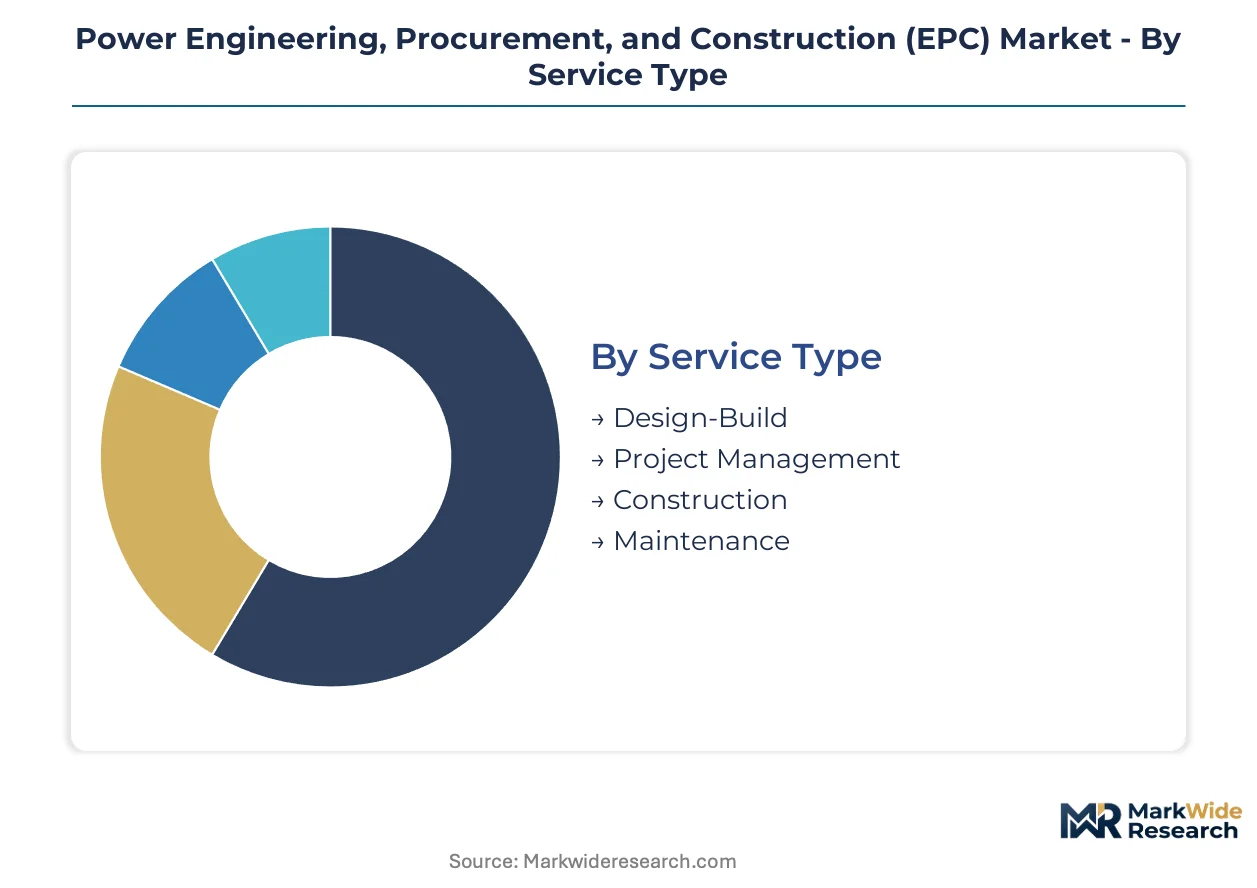
EPC contract structures vary sharply across service bundling, asset ownership, project scale, and generation technology. Each dimension reshapes risk allocation, margin profiles, and contractor capability requirements in distinct ways.
Service Type:
Domestic markets favor localized construction and maintenance contracts, while Design-Build and Project Management services increasingly cross borders as developers seek integrated accountability.
- Design-Build:Combines front-end engineering with turnkey construction under single-point accountability. India's ultra-mega solar parks and US utility-scale wind farms are concentrating procurement here as developers compress interface risk and accelerate COD timelines.
- Project Management:Delivers owner-engineer oversight without direct construction execution. Demand clusters in Southeast Asian grid expansion and Middle Eastern nuclear builds where local content requirements mandate domestic construction labor but foreign technical supervision.
- Construction:Field execution of civil, mechanical, and electrical works. Self-perform capability distinguishes tier-one contractors from subcontractor-dependent peers in lump-sum bidding environments.
- Maintenance:Post-COD operations support and asset management. Growing attach rates to original EPC contracts as owners consolidate vendor relationships across project lifecycles.
Design-Build commands the established base. The steepest expansion runs through Project Management.
End User:
Cost tier segmentation separates capital-rich utilities from price-sensitive industrial offtakers and subsidy-dependent renewable developers.
- Utilities:Vertically integrated grid operators procuring generation and transmission infrastructure under regulated cost-recovery frameworks. India's state discoms and US investor-owned utilities dominate contract volume through renewable purchase obligations and IRA-driven repowering programs.
- Industrial Facilities:Captive power for manufacturing, mining, and data center loads. Procurement emphasizes levelized cost over technology type, with gas turbines retaining share where grid reliability is uncertain.
- Renewable Energy Providers:Independent power developers and yieldcos financing greenfield solar, wind, and green hydrogen assets. IRA production tax credits and India's National Hydrogen Mission are accelerating integrated EPC-plus-equipment bundling.
- Government:Public-sector nuclear, hydro, and strategic reserve capacity. Projects carry extended timelines and complex permitting but offer counterparty security absent in merchant markets.
Utilities anchor the revenue base. Renewable Energy Providers are climbing the fastest.
Project Size:
Volume concentration sits with repeatable mid-scale execution, while margin premiums attach to scarce mega-project capability.
- Small Scale:Distributed solar, battery storage, and industrial cogeneration under 50 MW. Standardized designs enable regional contractor participation and compressed development cycles.
- Medium Scale:Utility-scale renewable and gas peaker projects from 50-200 MW. This band absorbs the majority of EPC contract awards in India and Vietnam as grid integration capacity expands.
- Large Scale:Combined-cycle gas turbines and offshore wind clusters from 200-500 MW. Requires integrated electrical and civil engineering coordination that filters out pure construction contractors.
- Mega Projects:Nuclear, pumped hydro, and ultra-mega solar parks exceeding 500 MW. Bechtel, Fluor, and Larsen & Toubro dominate through captive heavy engineering and risk capital capacity that smaller competitors cannot replicate.
Medium Scale absorbs the contract volume. Mega Projects concentrate the margin premium.
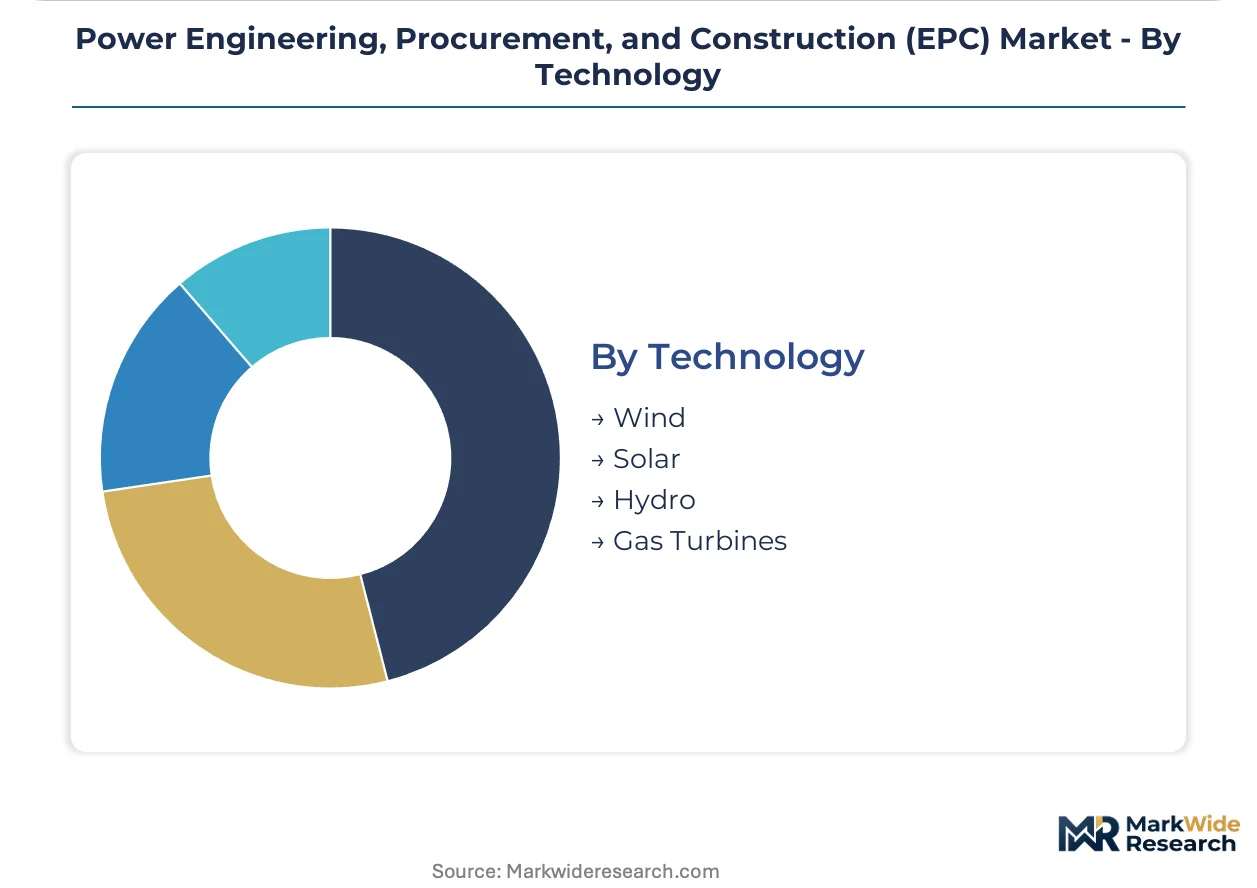
Technology:
Maturity gradients separate established thermal execution from emerging renewable integration challenges.
- Wind:Onshore and offshore turbine installation with electrical interconnection. India's Gujarat and Tamil Nadu coastal zones plus US Great Plains developments are pulling nacelle and tower EPC specialization.
- Solar:Photovoltaic and concentrated solar power with inverter and tracking integration. IRA domestic content bonuses and India's PLI scheme are reshoring module supply and bundling construction with manufacturing.
- Hydro:Run-of-river and pumped storage civil works. Permitting complexity and geological risk limit contractor appetite outside established geographies like the Himalayas and Nordic regions.
- Gas Turbines:Combined-cycle and simple-cycle peaking capacity. Residual demand concentrates in grid-firming applications where renewable intermittency requires dispatchable backup, particularly in US ERCOT and Indian states with renewable curtailment risk.
Gas Turbines retains the installed base. Solar records the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian developers exhibit acute price sensitivity on lump-sum EPC bids, while US utilities absorbing IRA tax credits tolerate premium pricing for domestic content compliance. Southeast Asian markets sit between these poles, with Vietnam and Indonesia prioritizing speed-to-execution over lowest-cost sourcing.
United States
IRA production tax credits with domestic content bonuses are redirecting developer capital toward bundled EPC contracts that capture manufacturing incentives alongside construction. FERC Order 2023 implementation delays continue inflating interconnection queue backlogs, extending project COD timelines. Texas ERCOT zone and California ISO territory concentrate renewable-plus-storage procurement as grid-firming demand intensifies.
India
State-level renewable purchase obligations under CEA directives compel discoms to contract integrated solar-wind-hybrid EPC services at scale. The National Hydrogen Mission mandates captive renewable generation paired with electrolyzer installation, creating multi-technology integration demand. Gujarat and Tamil Nadu coastal zones anchor offshore wind and ultra-mega solar park development, pulling engineering capacity toward utility-scale execution.
China
Dual carbon goals and provincial renewable installation targets sustain domestic EPC contract volume despite grid curtailment challenges in northwest regions. MIIT industrial policy supports turbine and electrolyzer manufacturing scale-up, enabling integrated equipment-construction bundling. Xinjiang and Inner Mongolia concentrate wind-solar hybrid bases, while coastal provinces prioritize offshore wind cluster development.
Germany
EU Green Deal carbon border adjustment mechanism tightens emissions accountability across imported steel and cement supply chains, forcing EPC documentation compliance. Offshore wind tender specifications now mandate low-carbon concrete mixes and regionally sourced structural components. North Sea ports and Baltic Sea development zones concentrate fabrication yard investment for turbine installation logistics.
Vietnam
State utility EVN procurement of distributed solar EPC remains underpenetrated relative to installed renewable potential, opening greenfield contractor entry. Feed-in tariff transitions toward competitive auction mechanisms are compressing developer margins and demanding construction cost discipline. Southern provinces including Ninh Thuan and Binh Thuan concentrate solar irradiation advantage and transmission expansion projects.
Power Engineering, Procurement, and Construction (EPC) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital intensity and risk capacity determining contract access. Tier-one contractors deploy self-perform construction capability and captive heavy engineering capacity to capture mega-project premiums. Mid-scale specialists compete on regional relationships and modular fabrication efficiency. Dominant competitive moves include strategic partnerships for technology licensing and geographic expansion through local joint ventures.
Within the integrated leader tier, Bechtel Corporation and Fluor Corporation exemplify self-perform construction archetypes with modular fabrication yard networks. Larsen & Toubro occupies a distinctive position combining South Asian market dominance with captive forging and heavy engineering capacity. These three anchors demonstrate how risk capital scale and integrated capability determine access to nuclear, pumped hydro, and ultra-mega solar park contracts exceeding 500 MW.
| Leading Market Players |
|---|
| Bechtel Corporation |
| Fluor Corporation |
| Larsen & Toubro |
| PowerChina |
| Siemens Energy |
| Hyundai Engineering and Construction |
| Mitsubishi Heavy Industries |
| Kiewit Corporation |
| McDermott International |
| Others |
Pricing and Supply Chain Analysis
CEA renewable purchase obligation compliance gates both contractor qualification and price differentiation in India's utility-scale procurement, compressing margins for non-integrated bidders while rewarding bundled EPC-plus-equipment providers with premium risk-adjusted pricing.
Pricing Analysis
Post-COD O&M service contracts and extended warranty bundles drive lifetime value capture for integrated EPC providers. Project-based lump-sum contracting dominates utility-scale awards, with price differentiation anchored in self-perform construction capability and domestic content certification under IRA bonuses. Cost compression in mid-scale solar EPC is intensifying as standardized designs proliferate. Industrial offtakers exhibit acute price sensitivity, while regulated utilities absorb premium pricing for single-point accountability.
Supply Chain Analysis
Strait of Malacca transit routes and Korean-Japanese forging yard concentration anchor heavy component logistics for gas turbine and nuclear projects. Structural steel and copper conductor supply draws from China, South Korea, and domestic Indian mills. Single-source vulnerability concentrates in forged rotors and pressure vessels from South Korean heavy engineering shops. Distribution runs through port-proximate modular fabrication yards with direct field assembly dispatch.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across technology-specialist tiers creates entry niches as green hydrogen and offshore wind integration demands outpace integrated contractor capacity.
For Market Incumbents: Secure captive forging partnerships or joint venture arrangements to lock heavy component supply for mega-project bidding. Anchor risk capital deployment in modular fabrication yard expansion to reduce field labor exposure and defend margin position against emerging regional specialists. For New Entrants and Emerging Players: ISO 14001 environmental management fast-track certification opens EU carbon border adjustment mechanism compliance service demand. Target Vietnam and Indonesia distributed solar EPC where state utility procurement remains underpenetrated. Pursue exclusive subcontractor alliances with established turbine suppliers lacking captive construction capability. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across green hydrogen electrolyzer integration and offshore wind foundation installation sub-segments. Long-term viability favors contractors with documented embodied carbon tracking and multi-technology project management platforms. Signal to monitor: FERC Order 2023 implementation pace and interconnection queue clearance rates as project COD risk indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Yard Expansion | Relocates value creation from field labor to controlled manufacturing environments near port infrastructure. |
| Domestic Content Certification Program | Captures IRA production tax credit bonuses and qualifies contractors for US utility-scale renewable procurement. |
| Electrolyzer Integration Partnership | Positions contractors for India's National Hydrogen Mission captive renewable-plus-electrolyzer mandates. |
| Digital Twin Platform Deployment | Compresses mechanical completion-to-COD intervals through parallel virtual testing at Indian ultra-mega solar parks. |
| Regional Joint Venture Formation | Enables market entry in Vietnam and Indonesia where local content requirements favor domestic construction labor. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA project databases, FERC interconnection filings, IEA renewable investment trackers, and CEA directive circulars. Utility planning officers, IPP project developers, EPC contract managers, and grid operators provided structured input across India, the United States, Vietnam, and Germany. Bottom-up project pipeline aggregation triangulates against top-down regulatory mandate analysis.
Segmentation dimensions modeled span service type bundling, generation technology, project capacity tier, end-user regulatory framework, and regional grid integration complexity. CAGRs derive from project award velocity tracking and capital deployment pattern analysis across the projection horizon. Forecast inputs incorporate electrolyzer deployment schedules, offshore wind tender pipelines, and domestic content bonus qualification rates.
Decision-makers should treat outputs as directional under base assumptions of continued renewable purchase obligation enforcement and IRA credit stability; material deviation in interconnection queue management or steel tariff regimes would warrant model refresh. Practitioners should keep alternative scenarios live as FERC Order 2023 implementation timelines and EU carbon border adjustment mechanism phase-in schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Thailand Power Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Digital Power Conversion Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
US Power EPC Market
Power Equipment
Wind Turbine Bolts Market
Power Equipment
Turbine Control Systems Market
Power Equipment
Portable Power Station Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Air Preheater Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
SCR Power Controller Market
Power Equipment
Turbine Governor Market