
 Asia-Pacific Gas Turbine MRO Market | 2026-2036
Asia-Pacific Gas Turbine MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Gas Turbine MRO Market Outlook
Japan's Top Runner program for thermal power efficiency is decoupling MRO procurement from simple replacement cycles across the Asia-Pacific. GE Vernova leverages its regional parts depots in Singapore and Thailand to sustain rapid turnaround commitments for utility clients. Mitsubishi Heavy Industries anchors the heavy-duty segment through captive servicing networks tied to its domestic turbine installed base. Siemens Energy competes on aeroderivative expertise, particularly for offshore platform operators requiring modular overhaul solutions.
Asia-Pacific gas turbine MRO encompasses inspection, component refurbishment, combustion system restoration, and performance enhancement services for axial-flow turbines operating above 1,000 degrees Celsius firing temperatures. These activities restore thermal efficiency, extend operational life, and ensure compliance with emissions limits for power generation and mechanical drive applications. The maintenance category commands the largest revenue share due to recurring inspection intervals mandated by OEM warranties and insurer requirements. Overhaul and repair services for combined-cycle units represent the fastest-growing technology segment as operators seek to defer capital expenditure on new capacity. Upgrades for heavy-duty installations concentrate margin pools where hot gas path component replacements integrate advanced coatings and cooling geometries.
Japan's METI enforces turbine efficiency benchmarks that directly shape upgrade specifications and parts substitution protocols for domestic operators. Australia's TGA-equivalent energy safety frameworks and South Korea's MFDS-aligned industrial equipment standards create differentiated compliance pathways that filter market access for foreign service providers. India's CEA grid reliability directives and the country's PLI scheme for domestic manufacturing are tightening localization requirements for spare parts sourcing. Stakeholders must monitor how divergent national efficiency mandates reshape the economics of cross-border MRO contracting versus in-country capability buildout.
Market Dynamics
Japan's METI efficiency mandates are decoupling MRO procurement from simple replacement cycles, forcing operators to justify every overhaul through measurable thermal performance gains rather than calendar-based scheduling.
Growth Catalysts
- Aging Combined-Cycle Fleets:Southeast Asian power utilities face mounting overhaul backlogs as first-generation gas turbines installed during the 1990s capacity expansion reach critical maintenance intervals.
- Performance Upgrade Mandates:Japan's Top Runner program for thermal power efficiency accelerates demand for hot gas path component replacements integrating advanced coatings and cooling geometries.
- Insurer Warranty Requirements:Recurring inspection intervals mandated by OEM warranties and insurer requirements lock in recurring revenue streams for maintenance category providers.
Market Restraints
- Specialized Alloy Supply Concentration:Superalloy forgings for hot section components concentrate among a limited supplier base in Japan and Germany, creating input cost volatility and extended lead times.
- Localization Requirements:India's PLI scheme for domestic manufacturing and CEA grid reliability directives tighten spare parts sourcing rules, fragmenting cross-border contracting economics.
- Technical Limitation of Legacy Units:Distributed gas turbine installations across Indonesia's archipelago geography limit economies of scale for mobile overhaul equipment deployment.
Strategic Opportunities
- Offshore Platform Modular Solutions:Aeroderivative expertise for offshore platform operators in Australia's Bass Strait and Southeast Asian waters creates demand for containerized overhaul systems.
- Dual-Use Technology Convergence:Additive manufacturing for blade repair is expanding into remanufacturing applications previously requiring complete component replacement.
- Thailand's Eastern Economic Corridor:State-led industrial zone development concentrates gas-fired cogeneration demand, anchoring regional MRO hub investment.
Industry Challenges
- Specialized Welding Technician Scarcity:Precision joining of directionally solidified superalloys requires certification levels that outpace regional vocational training pipeline output.
- Cross-Border Certification Timelines:Australia's TGA-equivalent energy safety frameworks and South Korea's MFDS-aligned industrial equipment standards create divergent compliance pathways that extend market access timelines for foreign service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Gas Turbine MRO Market |
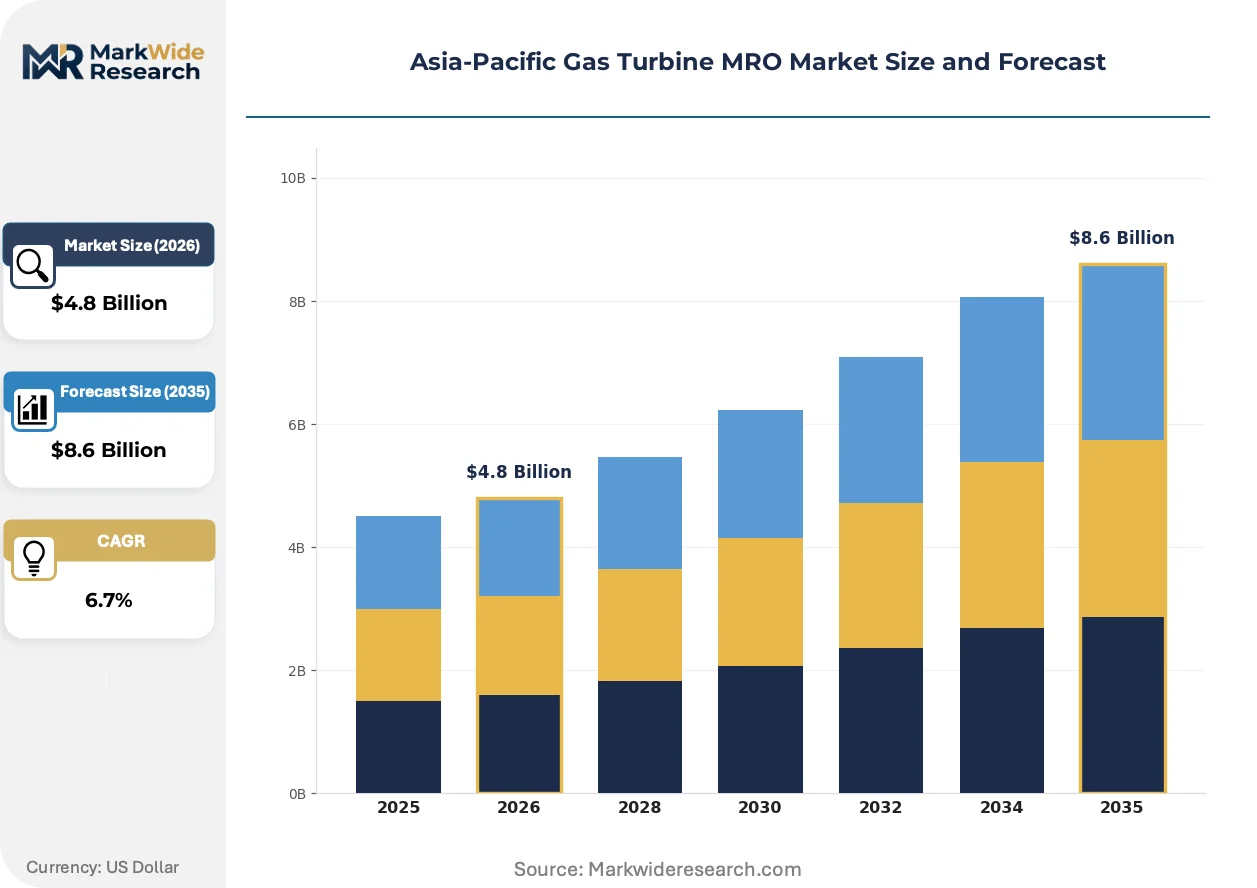
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Overhaul, Repair, Upgrades End User: Energy Sector, Aviation Industry, Marine Operators, Industrial Facilities Technology: Open Cycle, Combined Cycle, Aeroderivative, Heavy Duty Deployment: Onshore, Offshore, Hybrid, Stationary |
| Companies Covered | Rolls-Royce, EthosEnergy, GE Vernova, Ansaldo Energia, Sulzer, Mitsubishi Heavy Industries, John Wood Group, Doosan Enerbility, Siemens Energy, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Gas Turbine MRO Market Strategic Shifts
Digital inspection technologies and advanced coating systems are compressing overhaul cycles while extending component life, fundamentally altering the economics of maintenance versus replacement decisions across the region.
Thermal barrier coating systems incorporating ceramic matrix composites are expanding into heavy-duty gas turbine hot sections previously limited to metallic superalloys. Japanese power utilities operating under METI efficiency mandates are adopting these systems at accelerated replacement intervals. The technology is expanding into performance guarantee contracts where coating durability directly determines service provider liability exposure.
Japan's METI enforces turbine efficiency benchmarks that directly shape upgrade specifications and parts substitution protocols for domestic operators. The industrial consequence is mandatory pre-approval of any component modification affecting heat rate performance. Combined-cycle installations above 100MW capacity face the most stringent documentation requirements, driving consolidation of upgrade engineering among certified service providers.
Power utilities are unbundling after-sales service contracts from original equipment procurement, separating long-term maintenance agreements from turbine supply deals. Independent service providers in Singapore and Thailand are capturing these disaggregated contracts through rapid turnaround commitments backed by regional parts depots. This pattern is most visible in Indonesia, where state-owned generators face procurement flexibility constraints that favor modular service contracting over bundled OEM agreements.
Asia-Pacific Gas Turbine MRO Market Segmentation
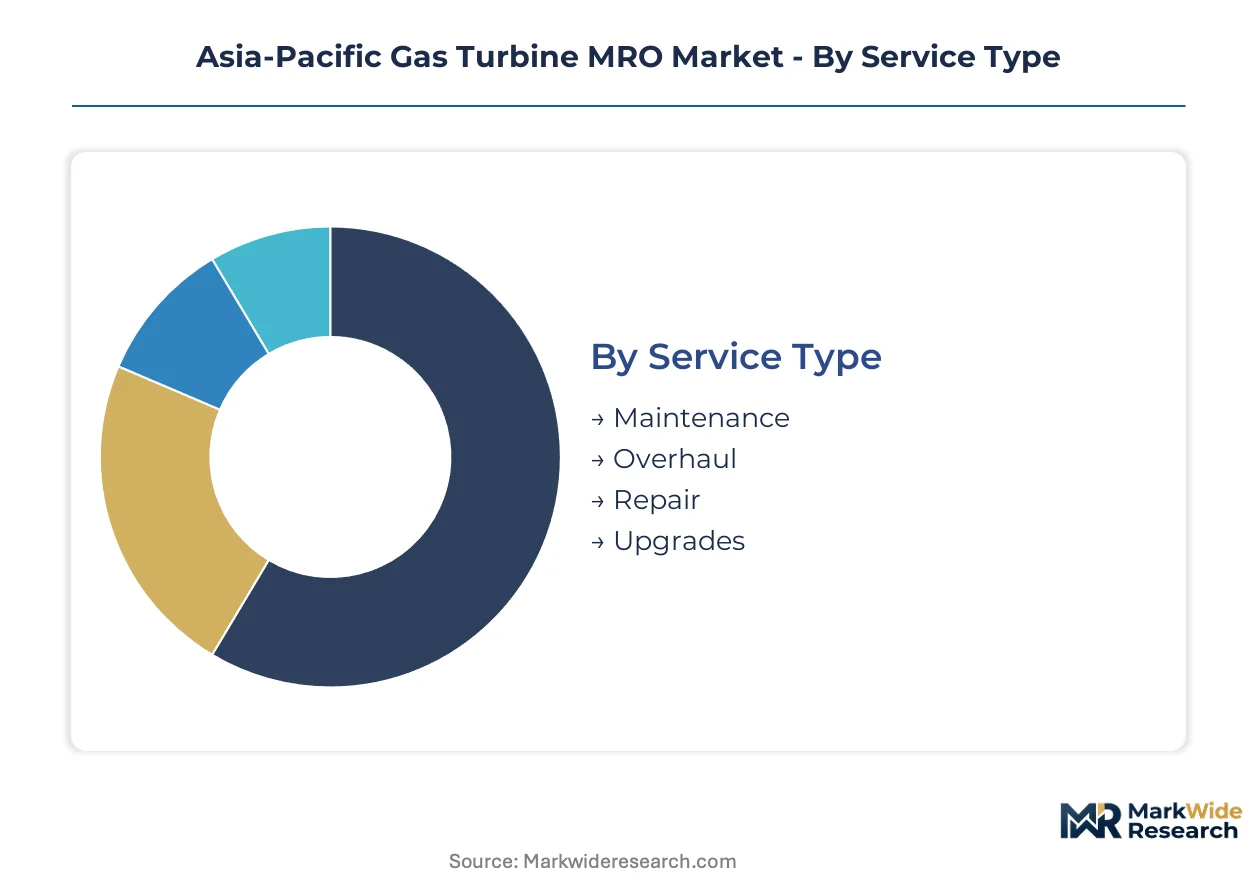
Segmentation in the Asia-Pacific Gas Turbine MRO Market reveals how upgrade cycles, deployment constraints, and end-user procurement flexibility reshape contract structures across service tiers and technology platforms. Understanding these divides exposes where margin pools concentrate and where volume expansion accelerates.
Service Type:
Upgrade intensity and component replacement cycles determine how service contracts bundle or separate across the maintenance-to-overhaul spectrum.
- Maintenance:Recurring inspection intervals mandated by OEM warranties and insurer requirements lock in predictable revenue streams. Indonesian state-owned generators concentrate demand here due to procurement flexibility constraints that favor modular service contracting over bundled agreements.
- Overhaul:Hot gas path component replacements integrate advanced coatings and cooling geometries as operators seek to defer capital expenditure on new capacity. Southeast Asian utilities face mounting backlogs as first-generation combined-cycle units installed during the 1990s capacity expansion reach critical intervals.
- Repair:Precision joining of directionally solidified superalloys requires certification levels that outpace regional vocational training pipeline output.
- Upgrades:Japan's METI efficiency mandates force operators to justify every overhaul through measurable thermal performance gains rather than calendar-based scheduling.
Maintenance sits at the top of the volume ranking, with Overhaul climbing the fastest as aging fleets force capital deferral strategies.
End User:
Procurement sophistication and regulatory exposure create divergent service requirements across customer categories.
- Energy Sector:Power utilities unbundle after-sales service contracts from original equipment procurement, separating long-term maintenance agreements from turbine supply deals. Thailand's Eastern Economic Corridor state-led industrial zone development concentrates gas-fired cogeneration demand.
- Aviation Industry:Aeroderivative expertise for offshore platform operators creates demand for containerized overhaul systems. Australia's Bass Strait operators require rapid turnaround commitments backed by regional parts depots.
- Marine Operators:Modular service contracting dominates as vessel downtime costs exceed premium paid for rapid mobilization.
- Industrial Facilities:Cogeneration operators balance thermal efficiency mandates against capital constraints through performance guarantee contracts.
Energy Sector commands the largest contract value, with Aviation Industry expanding most quickly on aeroderivative platform growth.
Technology:
Thermal efficiency thresholds and firing temperature regimes segment engineering capabilities and parts substitution protocols.
- Combined Cycle:Hot gas path component replacements integrate advanced coatings and cooling geometries as operators seek measurable thermal performance gains. Japan's METI enforces turbine efficiency benchmarks that directly shape upgrade specifications for installations above 100MW capacity.
- Heavy Duty:Axial-flow turbines operating above 1,000 degrees Celsius firing temperatures require specialized alloy forgings that concentrate among limited supplier bases in Japan and Germany. Mitsubishi Heavy Industries anchors this segment through captive servicing networks.
- Aeroderivative:Modular overhaul solutions serve offshore platform operators requiring containerized systems.
- Open Cycle:Peaking units face compressed maintenance windows that favor rapid turnaround commitments.
Heavy Duty leads installed base volume, with Combined Cycle gaining share fastest on efficiency upgrade mandates.
Deployment:
Geographic accessibility and mobilization economics determine service delivery architecture and contract pricing structures.
- Onshore:Regional parts depots in Singapore and Thailand sustain rapid turnaround commitments for utility clients. Indonesia's state-owned generators favor modular service contracting here due to procurement flexibility constraints.
- Offshore:Containerized overhaul systems address Australia's Bass Strait and Southeast Asian waters where platform downtime costs dominate economics. Siemens Energy competes on aeroderivative expertise in this segment.
- Hybrid:Dual-mode installations require flexible service windows accommodating operational switching.
- Stationary:Fixed-base units enable predictive maintenance integration with digital inspection technologies.
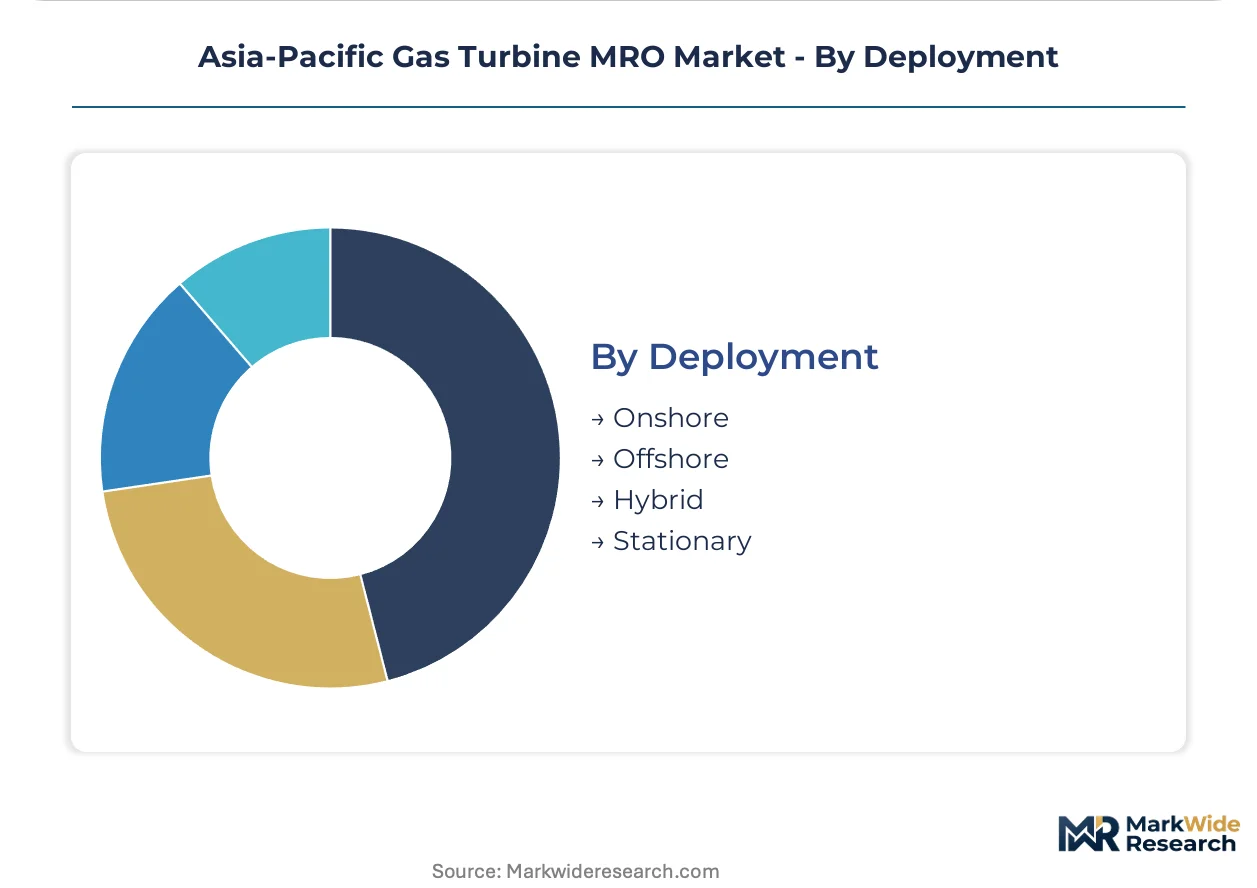
Onshore dominates contract frequency, with Offshore showing the steepest expansion trajectory on platform development activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gas turbine MRO operations across Asia-Pacific trace their modern scale to Japan's post-war industrialization and the subsequent 1990s capacity buildouts in Southeast Asia. Regional service networks now span from Japanese precision engineering hubs to Indonesian archipelago maintenance bases.
Japan
Japan's METI Top Runner program mandates measurable thermal efficiency gains from every overhaul cycle, forcing operators to abandon calendar-based scheduling. The regulator's pre-approval requirements for component modifications above 100MW capacity drive consolidation among certified service providers. Tokyo-Osaka corridor hosts the densest concentration of captive servicing networks tied to domestic turbine installed bases.
Indonesia
State-owned generators face mounting overhaul backlogs across distributed gas turbine installations spanning the archipelago geography. Procurement flexibility constraints favor modular service contracting over bundled OEM agreements. Java-Bali grid concentration anchors the largest maintenance contract volumes despite mobilization challenges to outer island units.
South Korea
MFDS-aligned industrial equipment standards create differentiated compliance pathways that extend market access timelines for foreign service providers. Domestic heavy industry clusters generate steady demand for heavy-duty turbine overhaul. Ulsan-Busan industrial corridor concentrates gas-fired cogeneration assets requiring specialized alloy refurbishment capabilities.
Australia
TGA-equivalent energy safety frameworks govern offshore platform operations in the Bass Strait where vessel downtime costs dominate service economics. Aeroderivative expertise commands premium positioning for containerized overhaul systems. Perth-based service hubs coordinate rapid mobilization to remote northwest shelf installations.
Thailand
State-led Eastern Economic Corridor development concentrates gas-fired cogeneration demand from automotive and electronics manufacturing clusters. Regional parts depots in Bangkok-Rayong sustain rapid turnaround commitments for utility clients. Board of Investment incentives anchor foreign MRO hub investment against Singapore competition.
Asia-Pacific Gas Turbine MRO Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology specialization and certification depth. The vendor base segments into OEM-captive networks, independent service providers with regional depot infrastructure, and specialized component repair shops. Three archetypes dominate: integrated turbine manufacturers with legacy installed base lock-in, depot-based independents capturing unbundled maintenance contracts, and precision coating specialists serving hot gas path refurbishment. Competitive moves concentrate on strategic partnerships for alloy supply security and geographic expansion through mobile overhaul system deployment.
Among integrated manufacturers, Mitsubishi Heavy Industries anchors the heavy-duty segment through domestic servicing networks, while GE Vernova leverages Singapore and Thailand parts depots for rapid turnaround commitments. Siemens Energy occupies a distinct position on aeroderivative expertise for offshore platform operators. These three exemplify how OEM-captive structures compete against unbundling pressure from independent providers in Indonesia and Thailand.
| Leading Market Players |
|---|
| Rolls-Royce |
| EthosEnergy |
| GE Vernova |
| Ansaldo Energia |
| Sulzer |
| Mitsubishi Heavy Industries |
| John Wood Group |
| Doosan Enerbility |
| Siemens Energy |
| Others |
Value Chain & Pricing Dynamics
Specialized alloy forgings for hot section components travel from Japanese and German superalloy mills through tiered service pricing structures, with procurement officers at Indonesian state-owned generators absorbing premium markups for expedited delivery against overhaul backlogs.
Pricing Analysis
Performance-guarantee contracting dominates premium tiers, where coating durability directly determines service provider liability exposure and pricing stratifies across OEM-captive, certified independent, and non-certified repair tiers. Certification grade under METI pre-approval requirements and geographic delivery cost to Indonesia's outer islands drive price differentiation. Cost compression in standard maintenance tiers is intensifying as Singapore-based independents capture unbundled contracts through rapid turnaround commitments. State-owned utilities exhibit highest price sensitivity due to procurement flexibility constraints, while offshore platform operators in Australia's Bass Strait show lowest sensitivity given vessel downtime economics.
Supply Chain Analysis
Single-source vulnerability sits with directionally solidified superalloy forging capacity concentrated in Japan and Germany, where precision casting for hot gas path components draws from nickel-cobalt-chromium feedstocks and ceramic matrix composite precursors. Tariff exposure on alloy imports fragments cross-border contracting economics under India's PLI localization mandates. Distribution runs through regional parts depots in Singapore and Thailand sustaining rapid turnaround commitments, with Bangkok-Rayong and Jakarta-Surabaya corridors anchoring downstream logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through additive manufacturing adoption for blade remanufacturing, converting complete component replacement into premium repair services while reducing alloy input exposure.
For Market Incumbents: To counter unbundling pressure from Singapore-based independents, deepen captive servicing network density across Japan's Tokyo-Osaka corridor and invest in METI certification for component modification pre-approval. Secure long-term alloy supply agreements with Japanese superalloy mills to hedge input cost volatility. For New Entrants and Emerging Players: Launch via containerized overhaul systems targeting Indonesia's outer island distributed installations, where procurement flexibility constraints favor modular service contracting over bundled OEM agreements. Penetrate aeroderivative offshore platform segments in Southeast Asian waters through rapid mobilization capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where precision welding technician scarcity outpaces regional vocational training pipeline output, favoring acquisition of certified repair shops with established superalloy joining capabilities. Target depot-based independents with regional parts infrastructure. Monitor METI efficiency mandate tightening as inflection signal for upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Alloy Supply Security Partnership | Long-term agreements with Japanese superalloy mills reduce hot section component lead time volatility for overhaul providers. |
| Mobile Overhaul System Deployment | Containerized repair units capture Indonesia's archipelago maintenance demand unreachable by fixed-base infrastructure. |
| Certified Welding Training Pipeline | Joint vocational programs with Japanese technical institutes address directionally solidified superalloy technician scarcity. |
| Digital Inspection Platform Integration | Remote monitoring systems compress overhaul cycles for METI-mandated efficiency verification documentation. |
| Regional Parts Depot Expansion | Bangkok-Rayong hub investment anchors rapid turnaround commitments against Singapore competition. |
Study Parameters
Direct dialogue with maintenance directors at Indonesian state-owned generators, OEM aftermarket service heads, superalloy procurement managers, and precision welding technicians combined with secondary validation from METI efficiency mandate filings, CEA grid reliability directives, customs trade data on superalloy imports, and EPC contractor project databases. Bottom-up contract value aggregation triangulates against top-down market sizing from regional turbine installed base estimates.
Installed base age profiles and overhaul interval modeling produced segment-level projections across the analysis window, with service type, end user category, and technology platform dimensions informing volume allocation. CAGRs derived from maintenance contract renewal rates and upgrade penetration curves under METI efficiency mandates, incorporating fuel price sensitivity and capital deferral propensity among Southeast Asian utilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt METI mandate tightening or sudden alloy supply disruption from Japanese forging capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Wind Turbine Bolts Market
Power Equipment
India Power EPC Market
Power Equipment
Deaerators Market
Power Equipment
Turbine Control Systems Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
AC Power Sources Market
Power Equipment
United Arab Emirates Power Market
Power Equipment
Power Analyzers Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Global Power Supply Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
Thailand Power EPC Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Ecuador Power EPC Market