
 Australia Power EPC Market | 2026-2036
Australia Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Power EPC Market Outlook
Modular construction and prefabricated substation assemblies is narrowing the execution gap between engineering design and field commissioning in Australian power infrastructure. CIMIC Group leverages its civil-engineering heritage to dominate complex remote-site logistics. AGL Energy Limited anchors its EPC positioning through integrated development-to-operation workflows across gas-peaking and grid-battery hybrids. Origin Energy Ltd competes on distributed energy resource contracting, bundling commercial solar with behind-the-meter storage.
Australia Power EPC encompasses the full-scope engineering, procurement, and construction of electricity generation, transmission, and distribution assets, typically governed by AS/NZS 3000 wiring rules and NEM grid connection standards requiring harmonic distortion limits below 5% THD at point of interconnect. The primary purpose is delivering capital-intensive energy infrastructure on fixed-price, schedule-certain contracts that transfer completion risk from asset owners to contractors. Commissioning services command premium margin pools due to the scarcity of certified grid-code specialists capable of negotiating AEMO registration protocols. Renewable Energy end users are driving fastest growth, with solar and wind technology segments pulling disproportionate procurement volume as developers race to capture firmed offtake agreements.
The Australian Energy Market Operator enforces generator performance standards that dictate inverter settings, frequency response curves, and voltage ride-through parameters for every new connecting asset. The Clean Energy Regulator administers Large-scale Generation Certificate creation, directly influencing project revenue stacking and EPC contract structuring around qualification deadlines. State-based renewable energy targets in Queensland, Victoria, and New South Wales layer additional planning approval pathways that extend pre-construction timelines. Stakeholders must monitor the trajectory of integrated system plan transmission investments to align EPC capacity buildout with corridor commissioning sequences.
Market Dynamics
The convergence of grid-scale battery storage deployment with National Electricity Market reform is compressing traditional EPC project timelines while elevating technical performance requirements for contractors.
Growth Catalysts
- Clean Energy Finance Corporation funding mechanisms:These capital structures redirect institutional investment toward firming capacity projects, reducing weighted average cost of capital for hybrid renewable developments.
- Queensland renewable energy zones:Concentrated transmission corridor planning is aggregating project pipelines that reward EPCs with multi-site execution capabilities and standardized design templates.
- Grid-scale battery chemistry evolution:Lithium iron phosphate and emerging sodium-ion configurations are expanding the addressable project size range for utility-scale storage EPCs.
Market Restraints
- Certified grid-code specialist scarcity:AEMO registration protocol negotiation requires specialized commissioning engineers whose limited supply extends project handover timelines.
- Copper and rare earth magnet input volatility:Transformer windings and permanent magnet generators face raw material price swings that erode fixed-price contract margins.
- Substation equipment lead time extension:High-voltage switchgear and power transformer manufacturing concentration in East Asian supply chains creates delivery uncertainty for Australian project schedules.
Strategic Opportunities
- New South Wales renewable energy zone offtake aggregation:Central-West Orana and Hunter-Central Coast corridors present bundled EPC contracting opportunities across co-located wind, solar, and storage assets.
- Behind-the-meter commercial solar plus storage bundling:Distributed energy resource integration is opening recurring revenue streams through long-term asset performance contracts.
- Integrated System Plan transmission investment sequencing:Early alignment with AEMO corridor commissioning schedules positions EPCs for preferred contractor status on priority projects.
Industry Challenges
- AS/NZS 3000 wiring rules harmonization with NEM grid connection standards:Dual compliance pathways create documentation complexity that extends pre-construction engineering phases.
- Harmonic distortion mitigation at point of interconnect:Sub-5% THD requirements demand specialized power quality engineering that strains mid-tier EPC technical capabilities.
- Large-scale Generation Certificate qualification deadline management:Clean Energy Regulator administration timelines compress construction windows and penalize schedule overruns with revenue loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Power EPC Market |
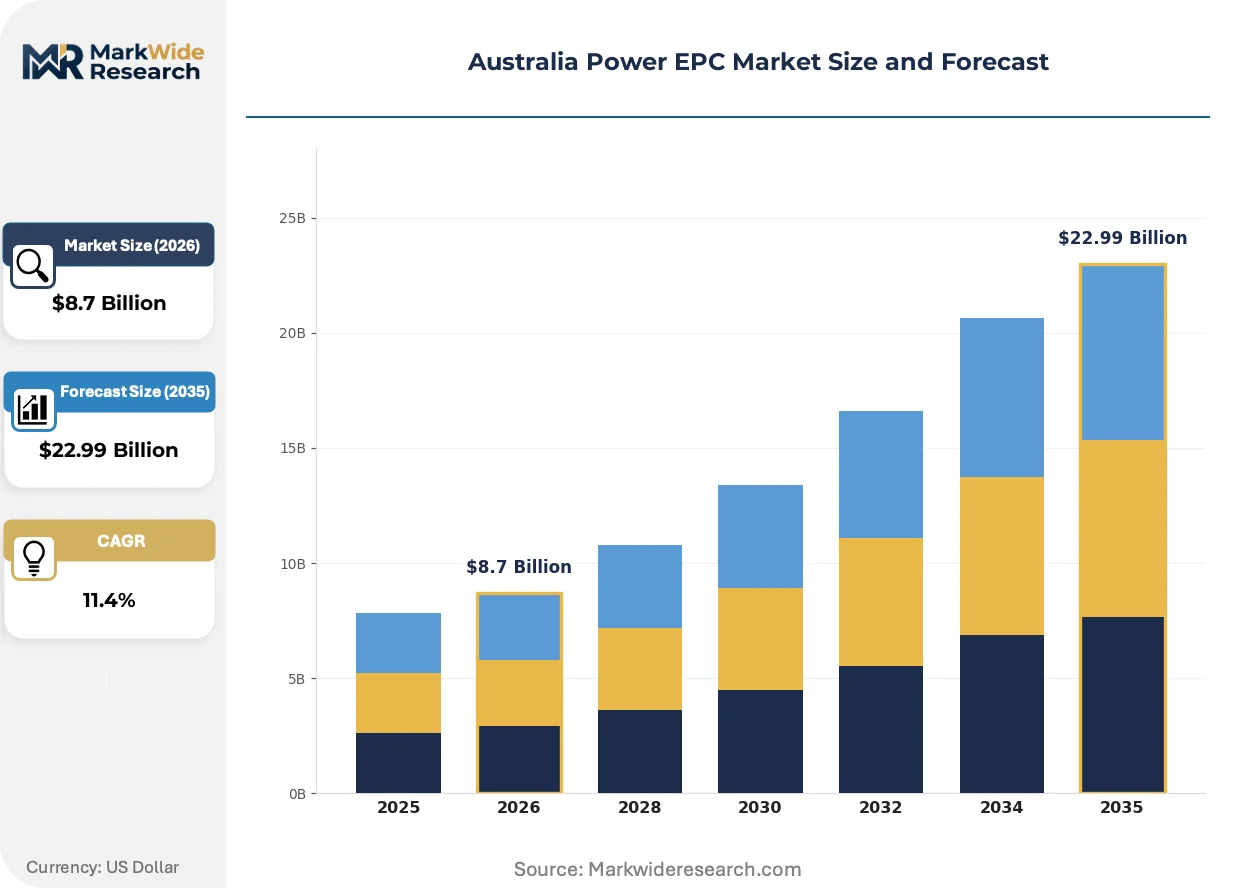
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Construction, Procurement, Commissioning, Maintenance End User: Utilities, Industrial, Commercial, Renewable Energy Technology: Solar, Wind, Gas, Biomass Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Stanwell Corporation Limited, Sumitomo Corporation, AGL Energy Limited, NRG Energy Inc, InterGen Services Inc, EnergyAustralia Holdings Ltd, Rio Tinto Limited, CIMIC Group, Origin Energy Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Power EPC Market Strategic Shifts
Digital twin technology and modular prefabrication are converging to compress field commissioning durations while elevating remote-site execution precision across Australian power infrastructure.
Digital substation automation platforms incorporating IEC 61850 protocol compliance are digitizing protection and control system integration. Major utilities including AEMO-registered generators are mandating these architectures for new interconnects. This digitizing of secondary systems engineering is collapsing traditional factory acceptance test and site acceptance test boundaries into unified virtual commissioning workflows.
The National Electricity Market reform agenda is tightening generator performance standards enforcement. AEMO now mandates granular inverter setting disclosure and frequency response curve verification prior to registration. Grid-scale battery and hybrid renewable developers face compressed compliance timelines that favor EPCs with established AEMO liaison capabilities and pre-approved control system templates.
Commercial and industrial offtakers are unbundling engineering and construction contracts from long-term asset management agreements. This procurement fragmentation is displacing single-source EPC-plus-O&M contracting across Queensland and New South Wales commercial solar markets. Developers now bid construction-only scopes while separate entities capture recurring revenue through performance-guaranteed operational contracts.
Australia Power EPC Market Segmentation
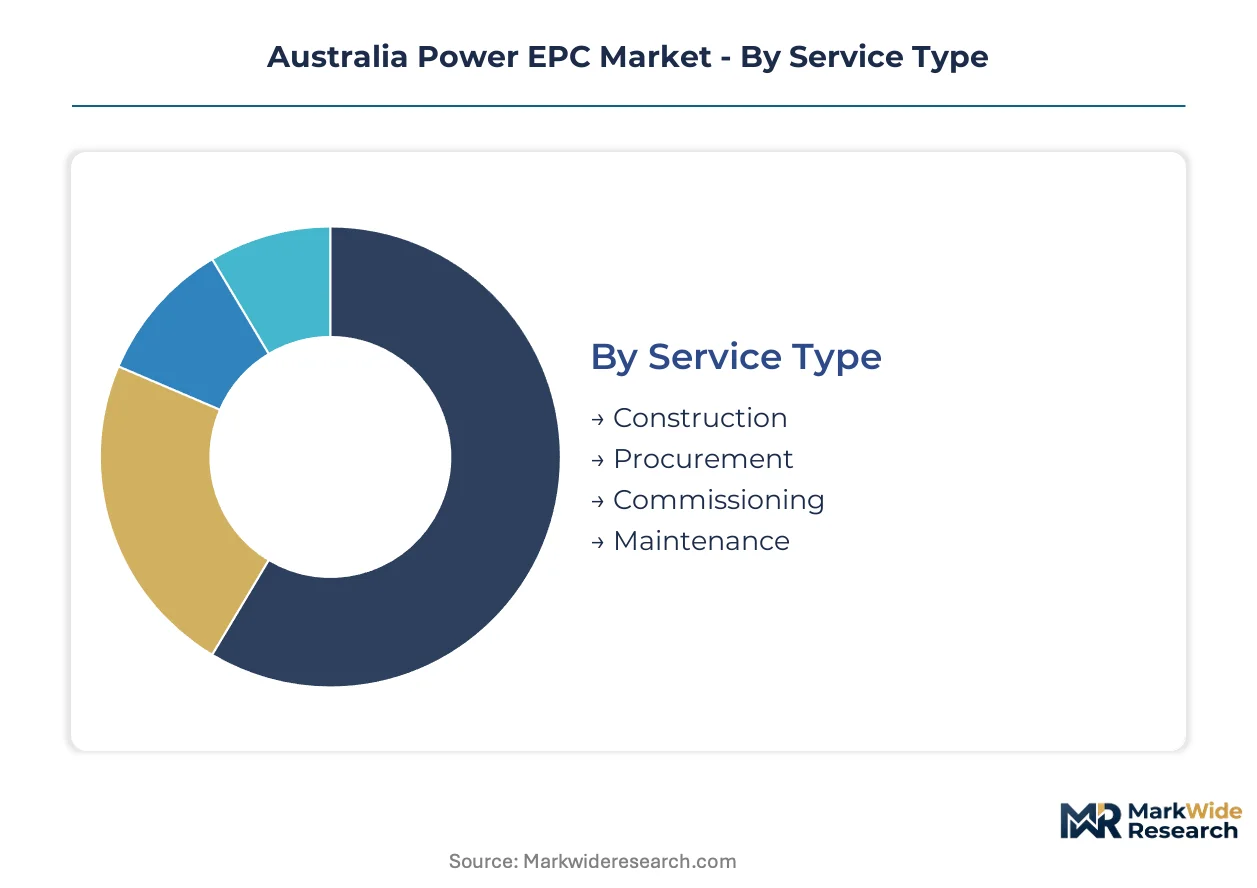
Power EPC contracting in Australia fragments across service delivery modes, end-use applications, generation technologies, and capital scale thresholds. Each segmentation dimension carries distinct margin profiles, technical capability requirements, and regulatory compliance pathways that reshape contractor positioning strategies.
Service Type:
Cost tier differentiation across the EPC value chain separates commodity construction labor from premium-margin technical services requiring certified specialist credentials.
- Construction:Civil works, structural assembly, and electrical installation form the volume base of Australian power EPC contracting. Queensland and New South Wales renewable energy zones concentrate demand for standardized balance-of-plant execution. Fixed-price risk transfer to contractors intensifies margin pressure as raw material volatility persists.
- Procurement:Equipment sourcing and supply chain orchestration spans high-voltage switchgear, power transformers, and inverter stations governed by AS/NZS 3000 wiring rules compliance. Extended lead times from East Asian manufacturing clusters create schedule uncertainty that EPCs must price into lump-sum contracts.
- Commissioning:Grid-code compliance and AEMO registration protocol negotiation command scarcity premiums due to limited certified specialist supply. Harmonic distortion verification below 5% THD at point of interconnect requires power quality engineering capabilities.
- Maintenance:Long-term asset performance contracts capture recurring revenue streams through availability guarantees and predictive service models. Commercial and industrial offtakers increasingly unbundle O&M from initial construction procurement.
Construction holds installed capacity. Commissioning is rotating up the share rankings.
End User:
Customer type segmentation reveals diverging procurement sophistication, contract structure preferences, and technical specification intensity across Australian electricity market participants.
- Utilities:Transmission network operators and generation portfolio managers drive grid-scale battery storage and hybrid renewable deployments. Clean Energy Finance Corporation funding mechanisms reduce weighted average cost of capital for firming capacity investments. National Electricity Market reform agendas compress project timelines while elevating generator performance standards enforcement.
- Industrial:Mining, manufacturing, and resource processing operations procure captive generation and behind-the-meter storage for power cost hedging and reliability assurance. Remote-site logistics complexity favors EPCs with civil-engineering heritage and modular construction capabilities.
- Commercial:Retail, logistics, and property sector offtakers bundle distributed solar with battery storage through power purchase agreement structures. Procurement fragmentation displaces single-source EPC-plus-O&M contracting across Queensland and New South Wales markets.
- Renewable Energy:Solar and wind developers race to capture firmed offtake agreements, pulling disproportionate procurement volume. Large-scale Generation Certificate qualification deadlines compress construction windows and penalize schedule overruns with revenue loss.
Utilities anchor current contract value. Renewable Energy is gaining share fastest.
Technology:
Application-specific engineering requirements and equipment supply chains differentiate generation technology segments within Australian power EPC markets.
- Solar:Photovoltaic module mounting, inverter integration, and DC-to-AC conversion systems dominate utility-scale and distributed deployment pipelines. Queensland and New South Wales renewable energy zones concentrate project aggregation opportunities.
- Wind:Turbine foundation engineering, nacelle installation, and grid connection compliance for variable renewable output require specialized logistics and commissioning expertise. Generator performance standards mandate granular inverter setting disclosure prior to AEMO registration.
- Gas:Peaking plant and combined-cycle configurations provide firming capacity as coal retirements accelerate. Integrated development-to-operation workflows reward EPCs with operational asset management capabilities.
- Biomass:Feedstock handling, combustion system integration, and emissions compliance add process engineering complexity to power generation contracting. Regional supply chain constraints limit deployment scale relative to other technologies.
Solar holds installed capacity. Wind is rotating up the share rankings.
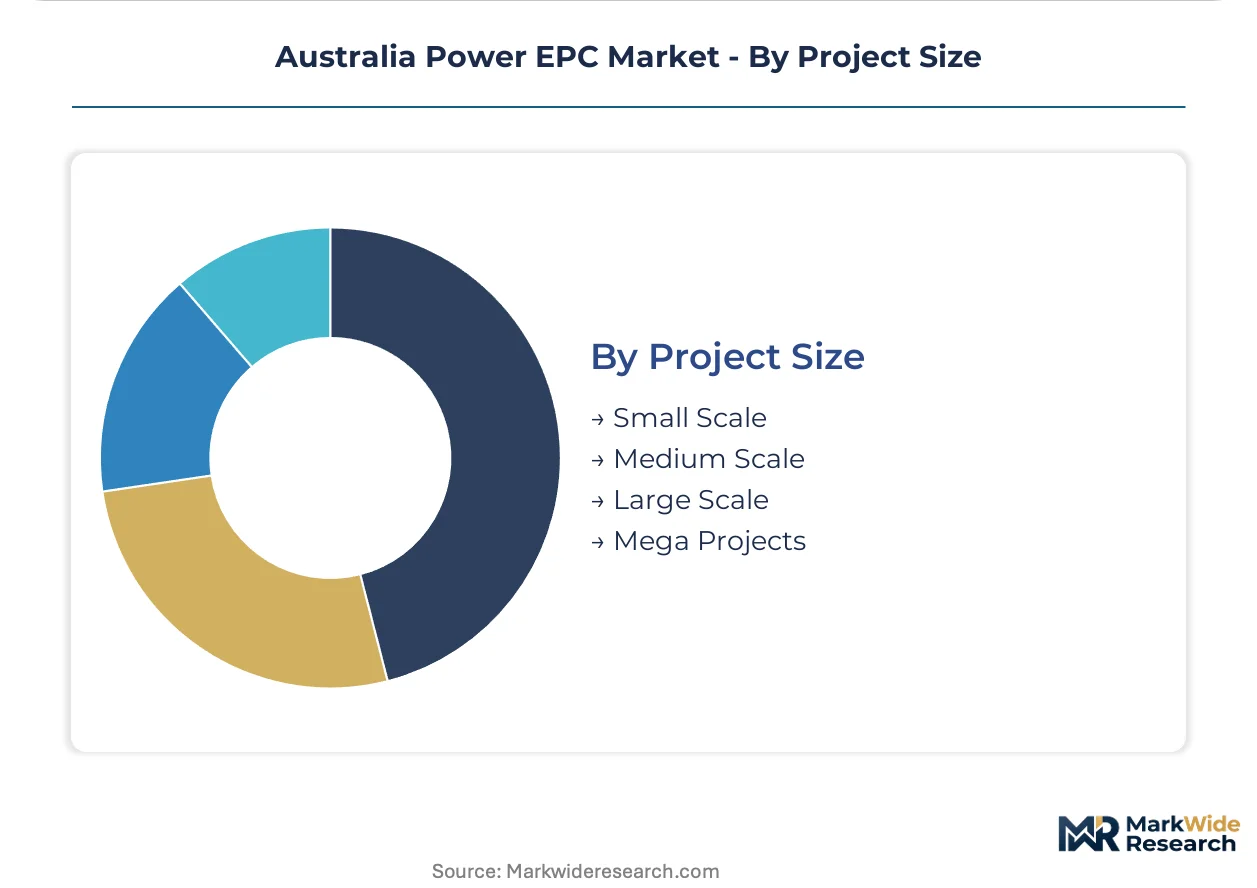
Project Size:
Capital scale thresholds determine risk allocation structures, financing complexity, and execution methodology standardization within Australian power EPC contracting.
- Small Scale:Distributed commercial solar and behind-the-meter storage installations below utility-scale thresholds. Standardized design templates and prefabricated substation assemblies compress field commissioning durations.
- Medium Scale:Industrial captive generation and grid-connected renewable developments requiring dedicated transmission infrastructure. Procurement bundling across engineering, construction, and initial O&M phases persists in this segment.
- Large Scale:Utility-scale solar, wind, and battery storage assets connecting to National Electricity Market transmission networks. AEMO corridor commissioning sequencing determines project handover timelines and revenue recognition schedules.
- Mega Projects:Multi-gigawatt renewable energy zone developments spanning co-located generation, storage, and transmission infrastructure. Multi-site execution capabilities and standardized design templates reward EPCs with portfolio-scale delivery experience.
Large Scale holds installed capacity. Mega Projects is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian equipment manufacturers supply high-voltage switchgear and power transformers to Australian renewable energy zones, with manufacturing concentration in China, Japan, and South Korea creating delivery dependencies for Queensland and New South Wales project schedules.
New South Wales
Central-West Orana and Hunter-Central Coast renewable energy corridors aggregate co-located wind, solar, and storage developments. The state's renewable energy zone framework mandates transmission-linked project pipelines that reward EPCs with multi-site execution capabilities. Sydney-based engineering consultancies coordinate grid connection compliance for AEMO registration protocols.
Queensland
Clean Energy Finance Corporation funding mechanisms reduce weighted average cost of capital for firming capacity investments across the state's northern and central zones. The Queensland renewable energy target drives planning approval pathways that extend pre-construction timelines. Townsville and Rockhampton industrial clusters concentrate civil engineering and modular construction expertise for remote-site logistics.
Victoria
Offshore wind development licensing and grid-scale battery storage procurement anchor EPC demand in the state's renewable energy transition. The Victorian renewable energy target administration compresses Large-scale Generation Certificate qualification deadlines. Melbourne engineering firms specialize in harmonic distortion mitigation below 5% THD for NEM grid connection standards.
South Australia
Grid-scale battery storage deployment and wind generation integration dominate project pipelines in the state's electricity market. AEMO generator performance standards enforcement mandates granular inverter setting disclosure prior to registration. Adelaide-based contractors leverage proximity to the Heywood interconnector for Victoria-linked transmission projects.
Western Australia
Mining sector captive generation and remote microgrid development drive isolated grid EPC contracting outside the National Electricity Market. The state's Wholesale Electricity Market operates under separate dispatch protocols from eastern seaboard jurisdictions. Perth engineering groups specialize in modular prefabrication for Pilbara and Goldfields region logistics constraints.
Australia Power EPC Market Competitive Environment
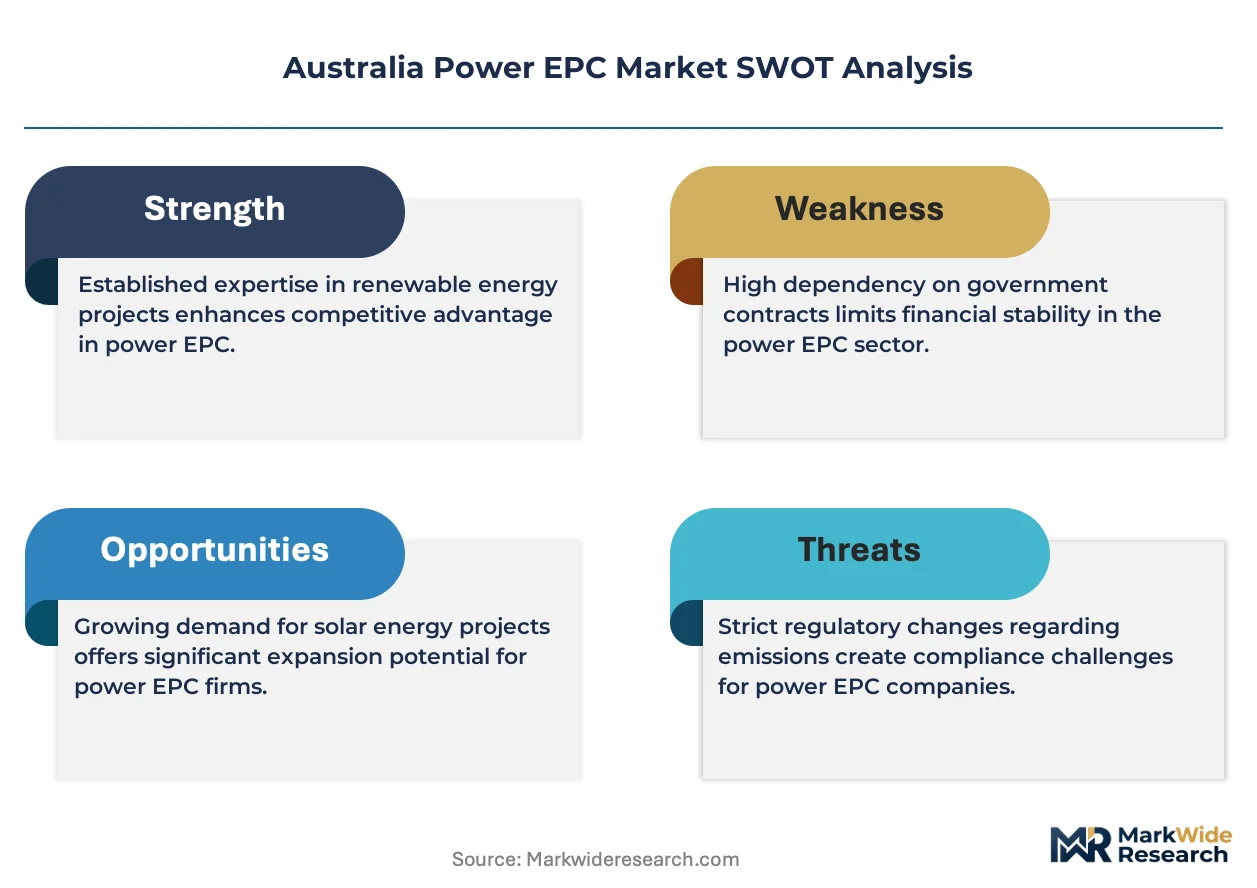
On the supply side, the industry is consolidating around integrated energy companies with captive development pipelines and diversified construction groups with civil-engineering heritage. Tier-one contractors capture utility-scale renewable energy zone contracts through multi-site execution capabilities. Mid-tier specialists compete on distributed commercial solar and behind-the-meter storage bundling. Dominant competitive moves include strategic partnerships with transmission network operators and portfolio diversification into long-term asset performance contracting.
Within the integrated energy company tier, AGL Energy Limited and Origin Energy Ltd represent development-to-operation workflow models that span gas-peaking and grid-battery hybrid configurations. CIMIC Group anchors the diversified construction archetype, leveraging civil-engineering capabilities for complex remote-site logistics across Queensland and New South Wales renewable energy zones. These three entities exemplify the strategic segmentation between energy-integrated EPC positioning and construction-centric execution models.
| Leading Market Players |
|---|
| Stanwell Corporation Limited |
| Sumitomo Corporation |
| AGL Energy Limited |
| NRG Energy Inc |
| InterGen Services Inc |
| EnergyAustralia Holdings Ltd |
| Rio Tinto Limited |
| CIMIC Group |
| Origin Energy Ltd |
| Others |
Value Chain & Pricing Dynamics
East Asian shipping lanes connecting Shanghai, Busan, and Yokohama to Australian ports transmit transformer and switchgear freight costs that compound with manufacturing concentration to stratify EPC contractor margins across project tiers. Port congestion premiums and bunker fuel volatility feed directly into lump-sum contract pricing, while downstream buyers face tiered cost structures tied to grid-code certification complexity and remote-site logistics intensity.
Pricing Analysis
Gas-peaking plant pricing gaps separate established combined-cycle configurations from emerging grid-battery hybrids and next-generation hydrogen-ready turbines. Project-based fixed-price contracting dominates utility-scale developments, with price differentiation driven by AEMO registration certification tiers and volume scale across renewable energy zone portfolios. Pricing pressure stems from raw material volatility in copper windings and rare earth magnets, squeezing mid-tier EPC margins most acutely. Commercial and industrial offtakers exhibit highest price sensitivity, while utility procurement teams prioritize schedule certainty over unit cost optimization.
Supply Chain Analysis
Tariff exposure between China and Australia dominates procurement risk for high-voltage switchgear and power transformer imports. Manufacturing concentrates in China, South Korea, and Japan, with Australian EPCs drawing from East Asian production clusters for critical electrical equipment. Lithium iron phosphate cells, permanent magnet generators, and transformer core steel constitute primary raw material dependencies. Single-source vulnerability persists for 500kV+ switchgear assemblies. Distribution runs through project-specific direct procurement contracts rather than distributor networks, with long-term offtake agreements locking in equipment allocation priority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's power EPC sector faces high-growth disruption as grid-scale battery chemistry evolution and National Electricity Market reform compress traditional project timelines while elevating technical performance thresholds. The Clean Energy Finance Corporation's capital redirection mechanisms and renewable energy zone aggregation frameworks create structural openings for repositioned competitors.
For Market Incumbents: Pre-empt margin erosion in standardized construction scopes by deepening captive commissioning capabilities and securing certified grid-code specialist pipelines. CIMIC Group and AGL Energy Limited should anchor multi-site execution templates across Queensland and New South Wales renewable energy zones to defend against emerging modular construction specialists. Backward integration into prefabricated substation assembly reduces exposure to East Asian equipment lead time volatility. For New Entrants and Emerging Players: Pursue behind-the-meter commercial solar plus storage bundling across Sydney and Melbourne metropolitan corridors, where procurement fragmentation has displaced single-source EPC-plus-O&M contracting. Distributed energy resource integration presents the most penetrable segment, with recurring revenue streams through long-term asset performance contracts offering sustainable margin pools absent in construction-only competition. Target facility managers and property sector offtakers through power purchase agreement structuring expertise. For Investors and Strategic Acquirers: Grid-code compliance specialists with AEMO liaison capabilities and pre-approved control system templates represent the highest-value acquisition archetype for portfolio exposure to commissioning scarcity premiums. Long-term viability hinges on alignment with Integrated System Plan transmission investment sequencing across the analysis window. Monitor Large-scale Generation Certificate qualification deadline compression as the signal for construction capacity tightness and EPC pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Scale Battery Capacity Buildout | Captures Clean Energy Finance Corporation funding for firming capacity investments in Queensland zones. |
| Power Purchase Agreement Structuring | Locks in long-term offtake revenue streams for commercial and industrial behind-the-meter deployments. |
| Modular Prefabrication Technology Licensing | Compresses field commissioning durations while elevating remote-site execution precision. |
| Backward Integration into Switchgear Supply | Reduces exposure to East Asian manufacturing concentration and tariff volatility. |
| AEMO Grid-Code Certification Program | Secures scarcity premiums for commissioning services through certified specialist credentialing. |
Study Parameters
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from Australian Energy Market Operator registration databases, Clean Energy Regulator Large-scale Generation Certificate records, Clean Energy Finance Corporation funding disclosures, and state-based renewable energy zone planning documents. Bottom-up project pipeline enumeration and top-down capital flow analysis triangulated market sizing across the study period.
Scenario-bracketing framed the analytical approach, with segmentation dimensions spanning service type, end user category, generation technology, and project capital scale. CAGRs derived from installed capacity buildout trajectories, equipment procurement volumes, and contractor revenue recognition patterns across the projection horizon. Forecast inputs incorporated Integrated System Plan transmission corridor commissioning schedules and renewable energy target compliance deadlines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese equipment manufacturers or accelerated National Electricity Market reform implementation would shift outcomes. Macroeconomic deviation in commodity prices, regulatory acceleration of generator performance standards, or breakthrough sodium-ion battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Wind Turbine Components Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
AC Power Sources Market
Power Equipment
India Nuclear Power Plant Equipment Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Digital Power Conversion Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Air Preheater Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
Power Infrastructure Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Automatic Power Factor Controller Market