
 Gas Insulated Power Equipment Market | 2026-2036
Gas Insulated Power Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Insulated Power Equipment Market Analysis
Ultra-high-voltage 800 kV and above specification tiers is bifurcating the competitive landscape into premium engineering specialists and volume manufacturers. ABB leverages its installed base in European transmission networks to sustain service revenue streams. Siemens AG anchors its position through in-house GIS manufacturing and captive supply of cast resin components. Hitachi Energy differentiates via hybrid technology integration, combining gas insulation with digital monitoring systems.
Gas insulated power equipment comprises high-voltage apparatus—switchgear, circuit breakers, transformers, and bus systems—sealed within metal enclosures pressurized with sulfur hexafluoride or alternative insulating gases at densities of 400-600 kPa, designed to interrupt fault currents up to 63 kA while occupying 10% of the footprint of air-insulated equivalents. Gas insulated switchgear dominates product type revenue due to substation retrofit cycles and urban land constraints, while gas insulated transformers represent the fastest-expanding category as offshore wind and data center loads require fire-safe, compact solutions. Digital technology installations are displacing conventional relay-protected systems as utilities prioritize predictive maintenance and real-time thermal monitoring.
The EPA regulates SF6 emissions under greenhouse gas reporting mandates, while the EU F-Gas Regulation imposes phased reduction quotas on fluorinated gas use in electrical equipment. IEC 62271-203 and IEEE C37.122 define dielectric withstand and seismic performance benchmarks that determine market access for non-European suppliers. Stakeholders must monitor alternative gas qualification timelines and certification reciprocity between regional testing laboratories to avoid stranded engineering investments.
Market Dynamics
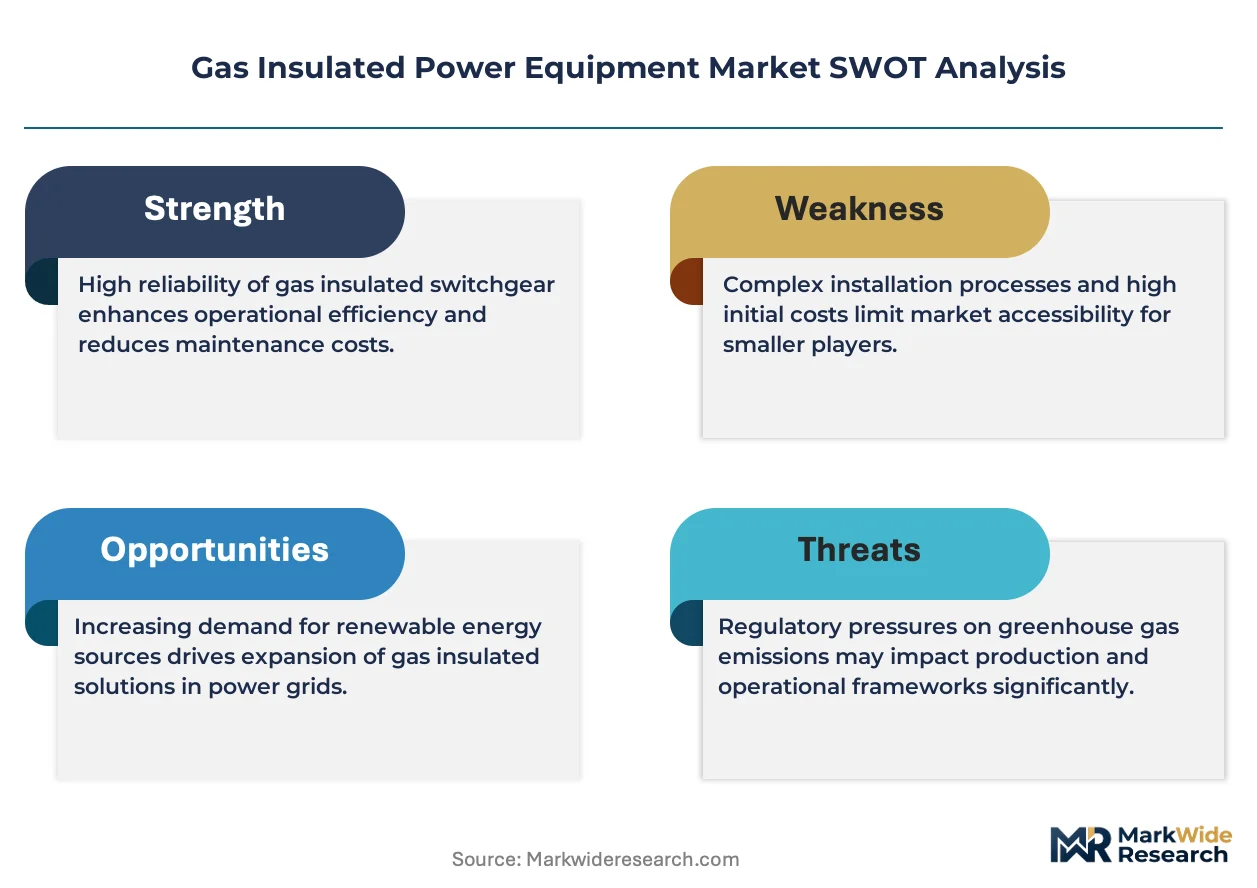
The EU F-Gas Regulation's phased SF6 reduction quotas are forcing manufacturers to requalify entire product portfolios under accelerated timelines, compressing engineering cycles and fragmenting certification reciprocity across regional testing laboratories.
Growth Catalysts
- Urban land scarcity:Metro substations in Tokyo, Shanghai, and Mumbai face footprint constraints that favor compact gas-insulated architectures over air-insulated alternatives.
- EU F-Gas Regulation:Phased fluorinated gas reduction mandates are pulling forward replacement demand as utilities accelerate retrofit timelines to avoid stranded assets.
- Offshore wind interconnection:Fire-safe gas-insulated transformers are capturing new buildouts in North Sea and East Asian cable landing stations where mineral oil insulation carries unacceptable fire risk.
Market Restraints
- Alternative gas supply concentration:Fluoronitrile production capacity concentrates among three European chemical suppliers, creating input vulnerability for switchgear manufacturers.
- Technical limitation:Vacuum interruption technology faces dielectric withstand gaps above 145 kV that delay full SF6 substitution in ultra-high-voltage tiers.
- Regulatory friction:Divergent IEC 62271-203 and IEEE C37.122 testing protocols force dual certification investments for suppliers serving both European and North American utilities.
Strategic Opportunities
- Data center load growth:Hyperscale facilities in Northern Virginia and Frankfurt require fire-safe, compact substations that gas-insulated transformers uniquely satisfy.
- India grid modernization:The country's Central Electricity Authority mandates urban substation densification that favors GIS deployments in Kolkata, Bangalore, and Hyderabad.
- Digital twin convergence:Integration of gas insulation with IoT thermal monitoring and predictive analytics creates service revenue streams beyond equipment sales.
Industry Challenges
- SF6 handling certification gaps:Field technician training programs lag equipment deployment rates, creating service backlogs and warranty exposure for installed base maintenance.
- Legacy asset integration complexity:Hybrid retrofits combining new gas-insulated bays with decades-old air-insulated buswork require custom engineering that stretches project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Insulated Power Equipment Market |
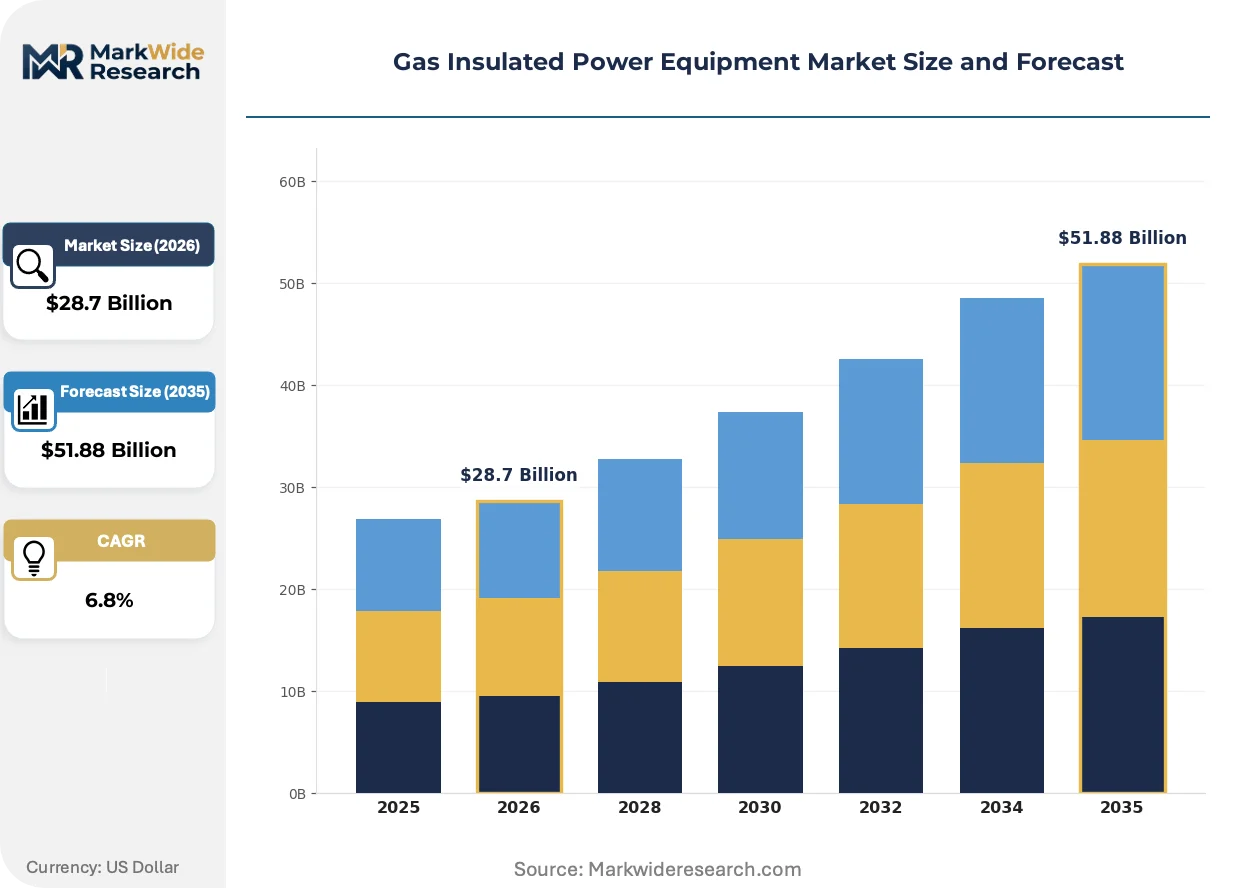
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Insulated Switchgear, Gas Insulated Bus, Gas Insulated Transformer, Gas Insulated Circuit Breaker End User: Utilities, Industrial, Commercial, Power Generation Installation: Indoor, Outdoor, Substation, Renewable Integration Technology: Hybrid Technology, Digital Technology, Conventional Technology, Others |
| Companies Covered | Schneider Electric, Mitsubishi Electric Corporation, ABB, Fuji Electric Co., Ltd., Eaton Corporation, Siemens AG, Hitachi Energy, CHINT Group Co., Ltd., General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Insulated Power Equipment Market Emerging Trajectories
Equipment architectures are fragmenting along voltage-tier lines as alternative insulation technologies mature at uneven rates, creating divergent competitive arenas rather than uniform substitution.
Fluoronitrile-based gas mixtures are decomposing the traditional SF6 monopoly in medium-voltage switchgear. European utilities under F-Gas compliance pressure are piloting these blends in 72.5 kV and 145 kV installations. The technology is decomposing established supplier relationships as chemical companies enter equipment partnerships that bypass conventional gas supply chains.
REACH authorization requirements for fluorinated gases are tightening substance tracking obligations across the value chain. Manufacturers must now document gas provenance through equipment lifecycle, adding compliance overhead that favors integrated producers over assembly specialists. The regulation most impacts medium-voltage GIS producers serving German and French distribution utilities.
Utility procurement departments are unbundling equipment supply from long-term service contracts that previously locked in incumbent suppliers. Competitive tendering now separates initial capital expenditure from predictive maintenance subscriptions, opening installed base access to third-party service providers. This pattern concentrates in UK and Scandinavian markets where distribution network operators face explicit cost-efficiency mandates.
Gas Insulated Power Equipment Market Segmentation
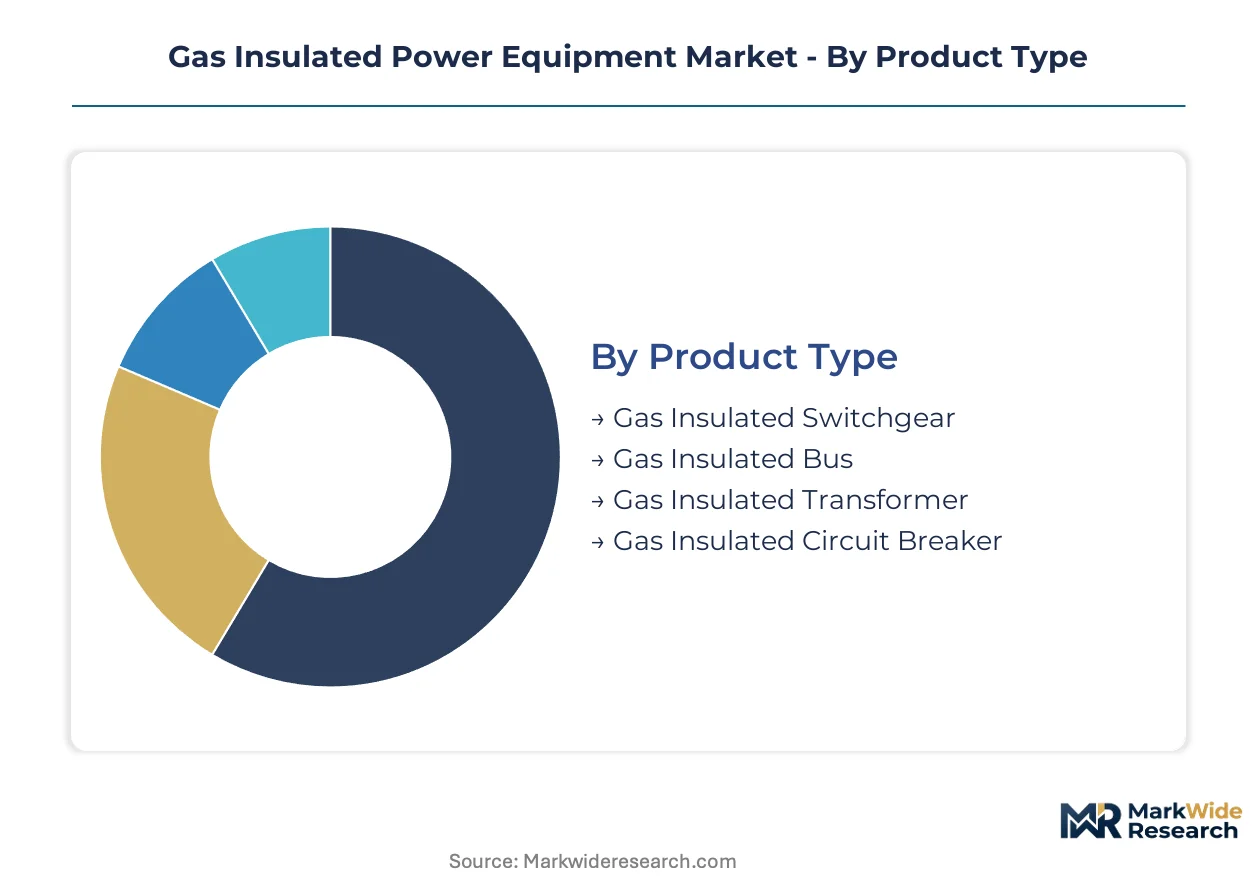
Voltage tier and application context determine substitution vulnerability across gas insulated equipment categories. Segmentation reveals which product lines face accelerated technology transitions versus stable incumbent positions.
Product Type:
Switchgear faces the steepest substitution pressure as F-Gas reduction deadlines force chemistry transitions across medium-voltage portfolios.
- Gas Insulated Switchgear:Metal-enclosed assemblies integrating circuit breakers, disconnectors, and earth switches within SF6 or fluoronitrile-filled chambers rated 72.5 kV to 800 kV. Demand concentrates in Chinese and Indian metro substations where land scarcity in Shanghai, Mumbai, and Delhi mandates 90% footprint reduction versus air-insulated alternatives.
- Gas Insulated Transformer:Cast-resin or gas-immersed windings eliminating mineral oil fire risk for indoor installations and offshore platforms. North Sea wind cable landing stations and Northern Virginia hyperscale data centers drive specification pull for fire-safe compact solutions.
- Gas Insulated Bus:High-current conductor assemblies for substation interconnection and generator lead-out applications.
- Gas Insulated Circuit Breaker:Individual interrupting units deployed in hybrid substation retrofits and specialized industrial feeds.
Gas insulated switchgear retains volume leadership; gas insulated transformer holds the steepest expansion curve.
End User:
Procurement scale and regulatory exposure separate segments with captive engineering resources from those dependent on third-party specification.
- Utilities:Transmission and distribution operators with direct F-Gas compliance obligations and accelerated retrofit timelines. European TSOs under EU reduction quotas and Japanese utilities facing METI efficiency mandates anchor replacement demand.
- Industrial:Heavy manufacturing, petrochemical, and mining operations requiring reliable medium-voltage distribution with minimal maintenance intervals. Gulf Coast US refineries and German chemical clusters specify GIS for process-critical uptime.
- Commercial:Urban real estate developments, hospitals, and transportation hubs prioritizing fire safety and space constraints.
- Power Generation:Conventional and renewable plant switchyards connecting generation assets to transmission networks.
Utilities command the largest procurement volumes; industrial users generate the highest margin premiums through specification customization.
Installation:
Environmental exposure and integration complexity create divergent certification and service requirements across deployment contexts.
- Indoor:Building-integrated substations in dense urban cores where fire safety and footprint dominate specification. Tokyo Metro, London Underground, and Singapore CBD installations require zero oil-content designs.
- Outdoor:Conventional open-air substations with weatherproof enclosures for transmission grid applications.
- Substation:Purpose-built switchyard complexes combining multiple gas insulated product categories.
- Renewable Integration:Offshore wind platforms and solar farm collector stations demanding corrosion-resistant compact architectures.
Indoor installations command the highest unit economics; renewable integration posts the most rapid capacity additions.
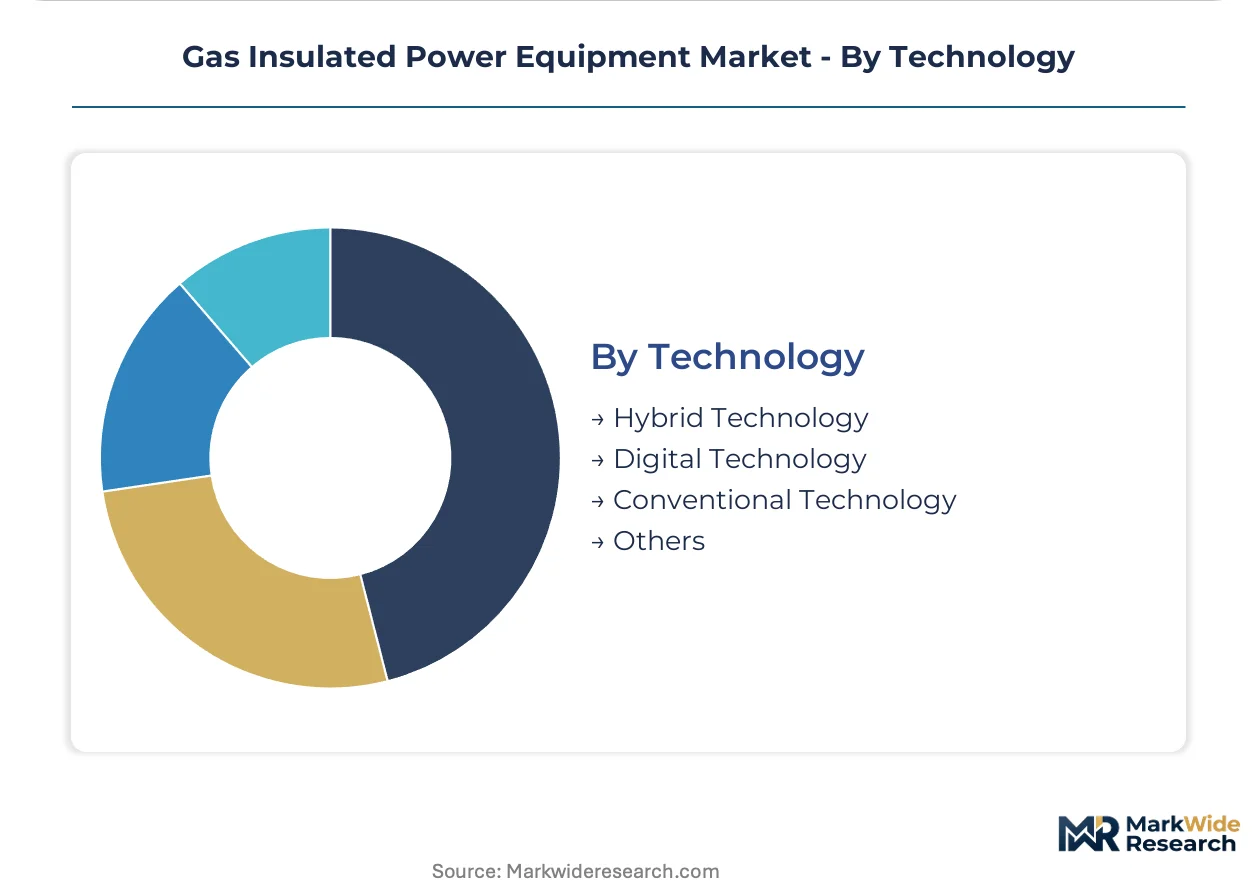
Technology:
Digital capability maturity is fragmenting competitive positioning between legacy relay-protected systems and predictive maintenance-enabled architectures.
- Hybrid Technology:Combinations of gas insulation with solid-state or vacuum interruption elements enabling staged SF6 phase-down. European pilot programs at 145 kV and below validate fluoronitrile blends for medium-voltage tiers.
- Digital Technology:IoT-embedded thermal monitoring, partial discharge detection, and cloud-connected analytics enabling condition-based maintenance. UK and Scandinavian DNOs unbundle predictive service contracts from equipment supply, opening installed base access.
- Conventional Technology:Relay-protected SF6 systems with established maintenance protocols and technician training infrastructure.
- Others:Emerging pure vacuum and solid insulation approaches under development for ultra-high-voltage qualification.
Conventional technology maintains the installed base majority; digital technology captures the fastest share gains in new procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for gas insulated power equipment clusters in Germany, Japan, China, and Switzerland, with European chemical suppliers controlling fluoronitrile feedstock for alternative gas formulations. Regulatory divergence between EU F-Gas mandates and EPA reporting requirements fragments certification pathways for equipment exporters.
China
State Grid Corporation drives ultra-high-voltage substation deployments across Shanghai, Beijing, and Guangzhou where land scarcity mandates compact GIS architectures. MIIT efficiency standards accelerate 800 kV and above equipment localization. Yangtze River Delta manufacturing clusters in Suzhou and Nantong supply cast resin components for domestic and export markets.
Germany
E.ON and TenneT TSOs face binding EU F-Gas reduction quotas that compress retrofit timelines for existing SF6 switchgear installations. REACH authorization requirements tighten gas provenance documentation across equipment lifecycles. Industrial demand concentrates in North Rhine-Westphalia chemical clusters and Bavarian automotive manufacturing corridors requiring fire-safe medium-voltage distribution.
Japan
Tokyo Electric Power and Chubu Electric accelerate urban substation densification under METI grid modernization mandates. Fire safety regulations prohibit mineral oil transformers in Tokyo Metro and Osaka underground installations. Kansai region manufacturers supply hybrid GIS technology integrating digital monitoring for predictive maintenance contracts.
United States
Duke Energy and Southern California Edison expand GIS procurement for data center load growth in Northern Virginia and Silicon Valley substations. EPA greenhouse gas reporting mandates track SF6 emissions from transmission equipment above 17,820 pounds annual capacity. Gulf Coast petrochemical clusters in Texas and Louisiana specify GIS for process-critical uptime requirements.
India
Power Grid Corporation and state DISCOMs deploy GIS under Central Electricity Authority urban densification mandates in Delhi, Mumbai, and Bangalore. BIS certification requirements for 72.5 kV and above equipment create entry barriers for non-domestic suppliers. Gujarat and Maharashtra industrial corridors drive medium-voltage demand from chemical and textile manufacturing operations.
Gas Insulated Power Equipment Market Vendor Landscape
Concentration sits with diversified electrical equipment conglomerates and specialized high-voltage engineering houses. The competitive structure splits between premium-tier engineering specialists serving 800 kV transmission networks and volume manufacturers capturing medium-voltage distribution utility procurement. Three archetypes dominate: integrated gas technology developers with captive chemical partnerships, digital-physical hybrid system integrators, and regional fabrication specialists leveraging cost-positioned manufacturing. Dominant competitive moves include strategic partnerships with fluoronitrile chemical suppliers and technology licensing agreements for alternative gas qualification.
Among European-headquartered engineering conglomerates, ABB and Siemens AG exemplify integrated technology developers with in-house manufacturing of cast resin components and established service revenue streams from installed base maintenance. Hitachi Energy occupies a position within the digital-physical hybrid tier, representing the convergence of gas insulation architectures with IoT-enabled monitoring systems. These three companies anchor the premium engineering segment where qualification timelines and certification reciprocity determine competitive access.
| Leading Market Players |
|---|
| Schneider Electric |
| Mitsubishi Electric Corporation |
| ABB |
| Fuji Electric Co., Ltd. |
| Eaton Corporation |
| Siemens AG |
| Hitachi Energy |
| CHINT Group Co., Ltd. |
| General Electric |
| Others |
Supply Flow & Price Mechanics
Cast resin component manufacturing scale in Suzhou and Nantong determines competitive cost floors across medium-voltage tiers, concentrating supply-side leverage among integrated producers while compressing margins for assembly-dependent specialists serving price-sensitive Indian distribution utilities.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European procurement, separating premium-qualified fluoronitrile-compatible equipment from standard SF6-based systems still permitted under phase-down timelines. Certification reciprocity gaps between IEC and IEEE testing protocols force dual-investment pricing for suppliers serving both German TSOs and US utilities, with industrial buyers in Gulf Coast petrochemical clusters showing lowest price sensitivity due to uptime-critical specifications.
Supply Chain Analysis
Germany, Japan, and Switzerland anchor high-voltage GIS manufacturing, while China concentrates medium-voltage volume production and cast resin component supply. Fluoronitrile feedstock draws from three European chemical suppliers, creating single-source vulnerability for switchgear manufacturers transitioning from SF6. Distribution runs through utility-direct procurement and EPC contractor channels, with logistics chokepoints at specialized high-voltage testing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gas insulated power equipment functions as a platform economy where digital monitoring integration creates interoperability lock-in, with predictive maintenance subscriptions displacing transactional equipment sales across UK and Scandinavian distribution networks.
For Market Incumbents: Shield installed base revenue by accelerating digital twin deployment and securing captive fluoronitrile supply agreements before chemical producer partnerships solidify. Prioritize certification investment in hybrid technology at 145 kV and below to defend against pure vacuum interruption challengers.
For New Entrants and Emerging Players: Predictive maintenance service gaps in India's urban densification projects offer white-space entry, with Kolkata and Bangalore DISCOMs unbundling long-term service contracts from capital equipment. Target third-party thermal monitoring and partial discharge analytics as the go-to-market angle, bypassing capital-intensive manufacturing barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital-physical hybrid system integrators with IoT-enabled monitoring platforms, positioning these archetypes for sustained cash flow quality across the medium-term horizon. Acquisition focus should center on specialists with IEC 62271-203 qualification and established utility service contracts. Monitor F-Gas reduction quota acceleration as the primary inflection signal for substitution technology winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluoronitrile Supply Partnership | Secures feedstock access for EU F-Gas compliance timelines and blocks competitor chemistry transitions. |
| Digital Twin Platform Launch | Creates predictive maintenance subscription revenue streams beyond equipment sales for UK DNOs. |
| Hybrid Technology Certification | Enables 145 kV SF6 substitution pilots with European utilities under accelerated reduction mandates. |
| India Manufacturing Scale-Up | Captures Central Electricity Authority urban densification procurement in Delhi and Mumbai corridors. |
| Service Contract Unbundling | Opens installed base access for third-party predictive maintenance providers in Scandinavian markets. |
Methodological Framework
Initial hypotheses were tested against primary input from utility planning officers, GIS maintenance directors, EPC contractors, and fluoronitrile chemical supply specialists, and refined through secondary validation against IEC standard revision documentation, EPA greenhouse gas reporting filings, EU F-Gas Regulation implementation guidance, and customs trade data for cast resin component flows. Bottom-up equipment deployment tracking and top-down grid investment forecasts were triangulated to reconcile volume estimates.
Variance decomposition across the projection horizon isolates technology substitution effects from pure capacity expansion drivers. Segmentation dimensions modeled include voltage tier, installation environment, end-user procurement scale, and digital capability maturity. CAGRs were derived from equipment replacement cycle analysis and regulatory deadline impact assessment, with forecast inputs incorporating F-Gas reduction quota trajectories and urban land scarcity indices for metro substation deployment.
Underlying assumptions cover fluoronitrile production scale-up timelines and certification reciprocity harmonization, with deviation risk concentrated in alternative gas dielectric performance validation and regional regulatory acceleration. Recalibration cycles align with material shifts in EU F-Gas quota enforcement and IEEE-IEC testing protocol convergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Turbine Governor Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Wind Power Fastener Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Portable Power Station Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
US Power EPC Market
Power Equipment
China Power EPC Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Thailand Power EPC Market