
 Power Plant Maintenance Market | 2026-2036
Power Plant Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Power Plant Maintenance Market Analytics
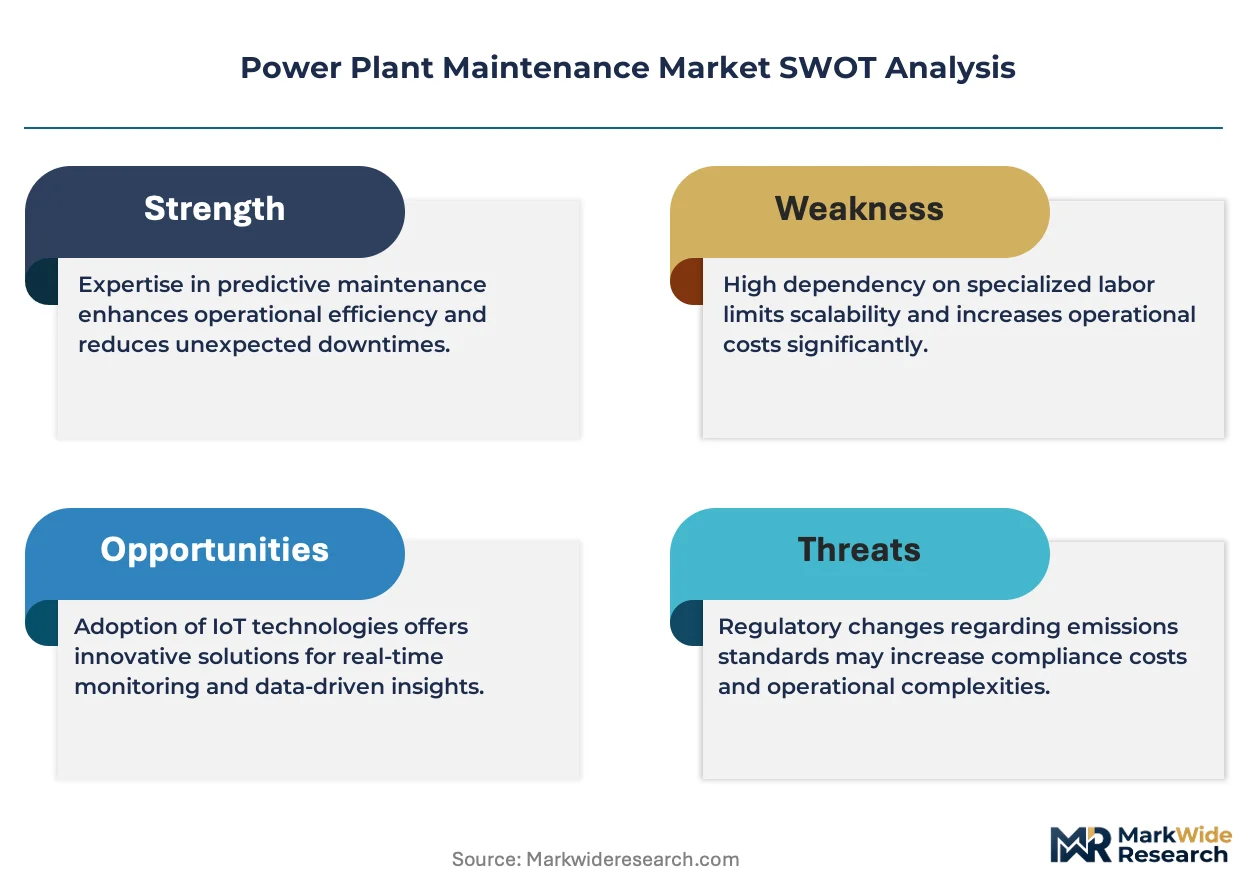
Aging specialist technician cohorts across OECD power markets is redrawing competitive dynamics for maintenance providers. General Electric Company leverages its deep installed base of gas turbine fleets to sustain long-term service agreements across North American utilities. Siemens Energy AG anchors its position through proprietary diagnostic platforms that dominate the European aftermarket for combined-cycle plants. Wärtsilä Corporation specializes in flexible engine maintenance cycles that compete directly with grid-balancing battery alternatives.
Power plant maintenance encompasses inspection, repair, overhaul, and component replacement activities performed on thermal, nuclear, and renewable generation assets to sustain rated output, heat rate efficiency, and operational availability above 85 percent annual capacity factor. Preventive maintenance commands the largest revenue share among service types due to mandatory OEM warranty compliance and insurer requirements for scheduled outage intervals. Predictive maintenance is expanding fastest as utilities deploy condition monitoring sensors and AI analytics to shift from calendar-based to failure-mode-driven intervention schedules.
EPA rules under the Clean Air Act and the EU F-Gas Regulation mandate leak detection protocols and refrigerant management that directly shape maintenance scope and contractor certification requirements for thermal plant operators. NRC inspection protocols and ASME boiler code standards further define the technical competencies that vendors must demonstrate to access the US nuclear and fossil fleet services market. Stakeholders must decide whether to build captive predictive analytics capabilities or outsource to OEM-linked platforms as plant digitalization redefines margin capture across the maintenance value chain.
Market Dynamics
The transition from calendar-based to condition-based maintenance protocols is restructuring vendor relationships and margin capture across thermal and renewable generation fleets. Digital instrumentation penetration is forcing incumbent service providers to reconfigure technical workforces and pricing architectures.
Growth Catalysts
- EPA Clean Air Act enforcement:Leak detection mandates and emissions compliance protocols expand mandatory inspection scopes for coal and gas turbine operators, sustaining preventive maintenance contract volumes.
- Flexible generation assets:Cycling duty patterns on combined-cycle plants accelerate wear on hot gas path components, shortening maintenance intervals and increasing parts replacement frequency.
- India's state genco restructuring:NTPC and regional utilities are outsourcing life-extension services for aging subcritical units, creating dedicated maintenance demand outside OEM channels.
Market Restraints
- Specialized alloy supply concentration:Superalloy forgings for gas turbine blades concentrate among a limited supplier base in Germany and Japan, creating procurement bottlenecks during outage seasons.
- EU F-Gas refrigerant phase-down:Restricted hydrofluorocarbon availability raises costs for cooling system maintenance and forces premature equipment replacement timelines.
- Grid-scale battery substitution:Lithium-ion storage systems displace peaking turbine maintenance demand as utilities retire simple-cycle units in favor of battery balancing assets.
Strategic Opportunities
- Southeast Asian outsourcing expansion:Vietnamese and Indonesian utilities are privatizing maintenance functions for first-generation CCGT fleets, opening non-OEM service windows.
- AI-augmented diagnostics:Machine learning platforms trained on vibration and thermal imaging data enable failure-mode prediction that extends component life beyond OEM recommended intervals.
- India PLI scheme for manufacturing:Domestic production incentives for power equipment reduce import dependency for replacement parts and shorten maintenance lead times.
Industry Challenges
- Welding and NDT technician scarcity:ASME-certified boiler inspectors and specialized radiographic testing personnel are retiring faster than training programs replenish qualified candidates.
- NRC inspection protocol complexity:Nuclear plant maintenance contractors face extended qualification timelines for safety-related work, compressing available labor pools during refueling outages.
- Legacy DCS integration:Digital predictive maintenance platforms require protocol translation layers to interface with aging distributed control systems, raising implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Plant Maintenance Market |
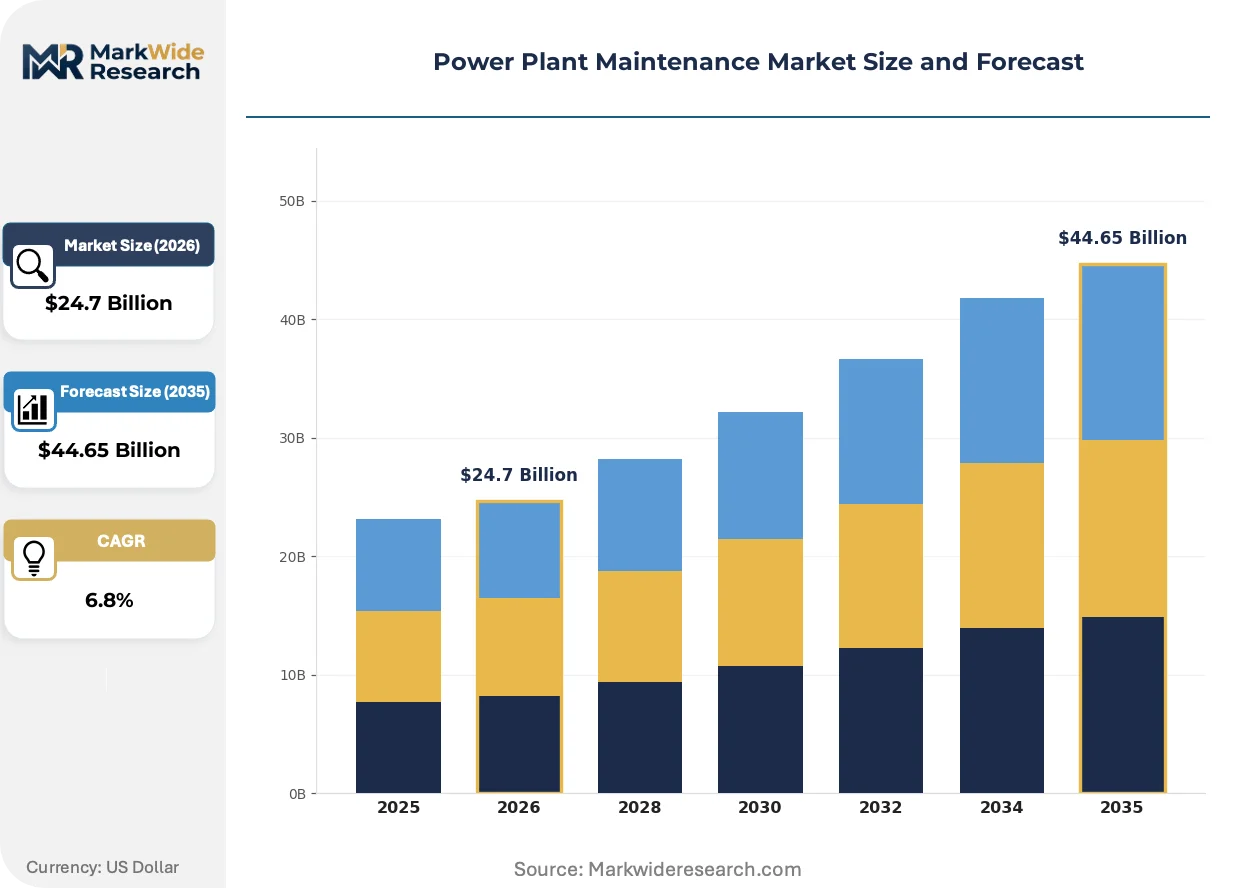
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Maintenance, Predictive Maintenance, Corrective Maintenance, Reliability-Centered Maintenance End User: Utilities, Independent Power Producers, Industrial Operators, EPC Contractors Technology: Condition Monitoring, Drones, AI Analytics, Remote Monitoring Maintenance Strategy: Time-Based, Condition-Based, Risk-Based, Performance-Based |
| Companies Covered | ENGIE SA, Wärtsilä Corporation, General Electric Company, John Wood Group PLC, Larsen & Toubro Limited, Siemens Energy AG, Doosan Enerbility Co., Ltd., NAES Corporation, Mitsubishi Hitachi Power Systems, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Plant Maintenance Market Evolving Landscape
Digital instrumentation and remote monitoring capabilities are collapsing the information asymmetry between plant operators and maintenance vendors. This transparency shift is redistributing pricing power and forcing contractual innovation across service relationships.
Digital twin simulations of gas turbine performance are decomposing traditional time-based overhaul cycles into component-specific interventions. Siemens Energy and GE deploy these models across North American utility fleets, enabling hot section replacements without full unit disassembly. The technology is compressing outage durations and challenging flat-rate service agreement structures.
The EU F-Gas Regulation mandates refrigerant leak detection protocols and phased hydrofluorocarbon reductions that reshape cooling system maintenance scope. Thermal plant operators in Germany and France must now certify contractors under updated refrigerant handling standards. Combined-cycle facilities face accelerated chiller replacement timelines that expand equipment sales at the expense of repair services.
Utility procurement departments are unbundling long-term service agreements into discrete inspection, repair, and parts supply contracts. This fragmentation enables competitive bidding for individual work scopes and pressures OEM-linked providers on price transparency. The pattern is most pronounced among municipal utilities in Texas and California seeking rate-case defensibility through demonstrated cost competition.
Power Plant Maintenance Market Segmentation
Segmentation in power plant maintenance reveals how service delivery, technology adoption, and contracting models diverge across asset ownership structures and regulatory environments. Understanding these divides exposes where margin concentrates and which technology investments reshape competitive positioning.
Service Type:
Geographic demand patterns split sharply between domestic-regulated utilities and export-exposed independent generators, with each segment prioritizing different risk-mitigation approaches.
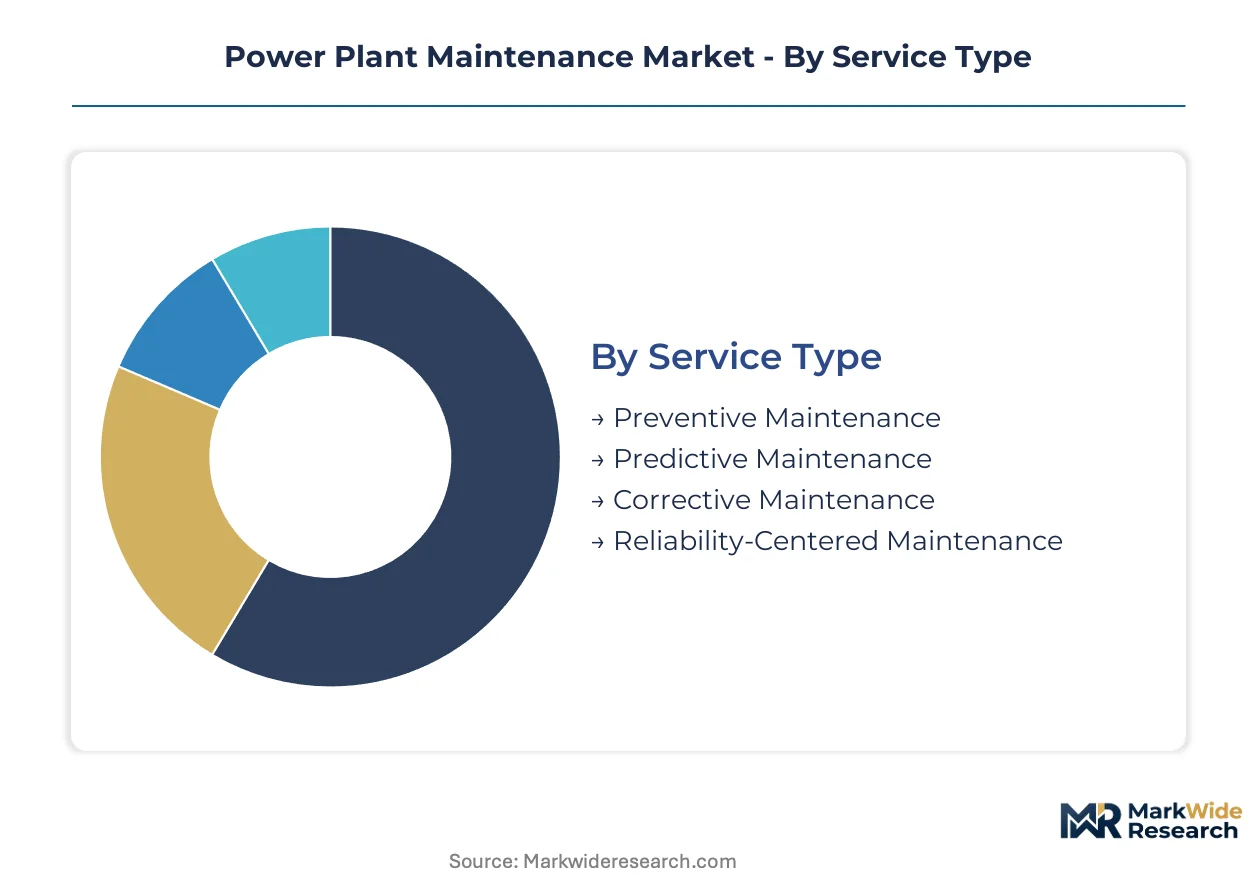
- Preventive Maintenance:Scheduled inspections, component replacements, and lubrication protocols executed at fixed calendar intervals to satisfy OEM warranty terms and insurer mandates. US utilities under EPA Clean Air Act enforcement sustain the densest contract volumes for emissions-related inspection scopes. This segment holds the largest share.
- Predictive Maintenance:Sensor-driven condition monitoring combined with failure-mode analytics to intervene only when degradation signals emerge. Indian state gencos including NTPC are deploying vibration and thermal imaging systems to extend outage intervals beyond OEM recommendations. Momentum sits with predictive approaches.
- Corrective Maintenance:Reactive repair and component replacement following unplanned failures or forced outages. Industrial captive plants in Germany face compressed timelines due to EU F-Gas refrigerant leak repair mandates.
- Reliability-Centered Maintenance:Risk-prioritized intervention schedules optimized for critical system availability rather than component longevity. Nuclear operators under NRC protocols apply this to safety-related systems exclusively.
Preventive maintenance commands the largest revenue base; predictive maintenance is climbing the fastest as digital instrumentation penetrates aging fleets.
End User:
Customer type determines contract structure, with regulated utilities favoring long-term service agreements and industrial operators driving unbundled competitive bidding.
- Utilities:Vertically integrated and municipal power providers managing rate-base assets under public utility commission oversight. Texas and California municipal utilities are fragmenting traditional LTSA contracts into discrete inspection, repair, and parts scopes for rate-case defensibility.
- Independent Power Producers:Merchant generators exposed to wholesale power price volatility and merchant offtake risk. IPPs in Vietnam and Indonesia are privatizing maintenance functions for first-generation CCGT fleets, opening non-OEM service windows.
- Industrial Operators:Captive generation assets serving manufacturing, refining, or mining operations. German chemical and steel producers face accelerated chiller replacement timelines under EU F-Gas phase-down schedules.
- EPC Contractors:Engineering-procurement-construction firms executing turnkey plant projects with embedded commissioning and initial warranty maintenance. Indian EPCs under PLI scheme incentives are localizing parts supply chains to compress maintenance lead times.
Utilities generate the densest contract flow; industrial operators are gaining share fastest through competitive unbundling.
Technology:
Technology deployment correlates with fleet digital maturity, creating a two-tier market between sensor-native new builds and retrofit-laden legacy assets.
- Condition Monitoring:Vibration, temperature, and pressure sensors deployed on rotating equipment and heat transfer surfaces. Siemens Energy and GE deploy these across North American utility fleets to enable hot section replacements without full unit disassembly.
- Drones:Unmanned aerial systems for cooling tower, stack, and boiler exterior inspection. Southeast Asian utilities are adopting drone-based thermography to reduce scaffolding costs during tropical outage seasons.
- AI Analytics:Machine learning platforms trained on historical failure data to predict component degradation trajectories. AI-augmented diagnostics enable failure-mode prediction that extends gas turbine blade life beyond OEM recommended intervals.
- Remote Monitoring:Cloud-connected sensor networks enabling centralized diagnostic centers to support distributed plant portfolios. Remote capabilities are collapsing information asymmetry between plant operators and maintenance vendors.
Condition monitoring dominates current deployment; AI analytics shows the steepest expansion trajectory as training datasets mature.
Maintenance Strategy:
Strategy selection reflects regulatory pressure intensity and asset criticality, with risk-based approaches concentrated in nuclear and high-reliability industrial settings.
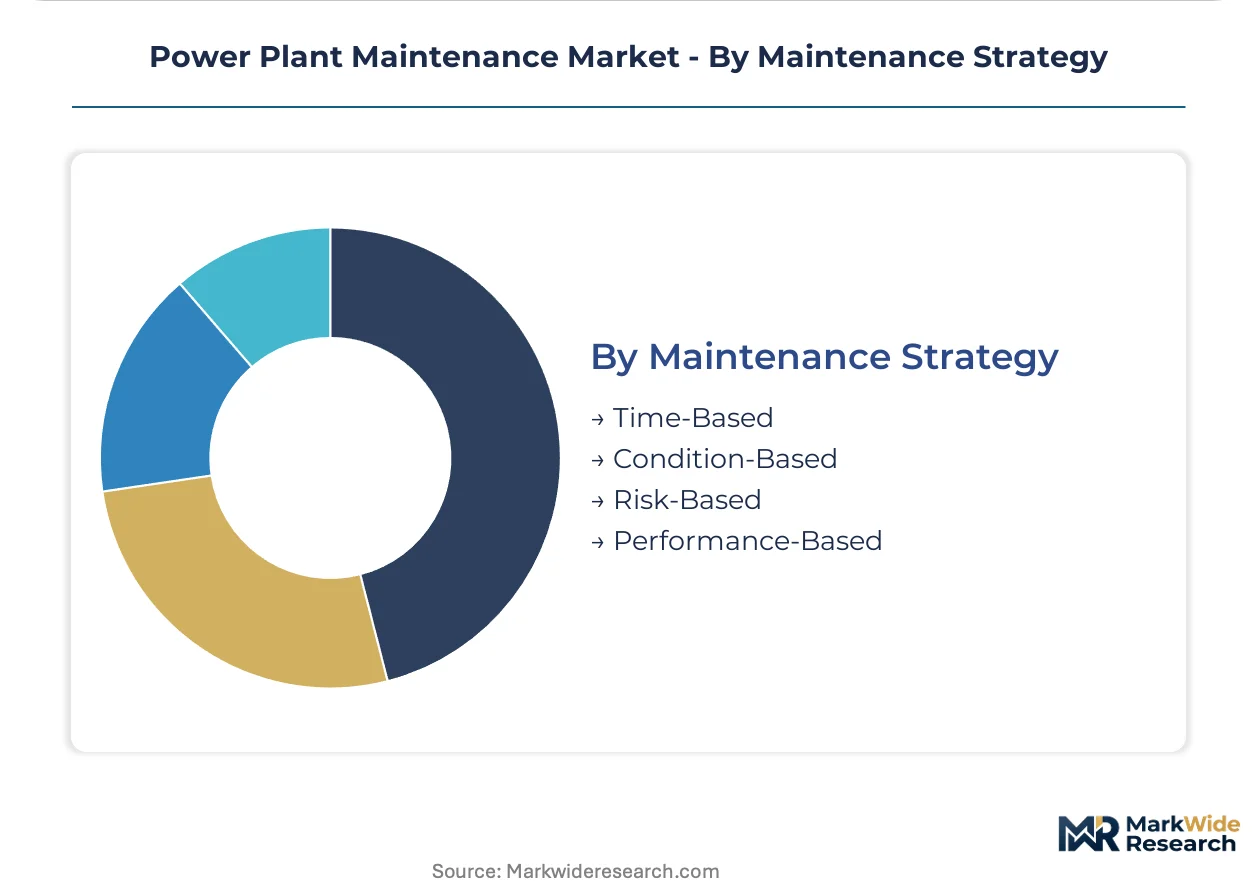
- Time-Based:Calendar-scheduled interventions at fixed intervals regardless of measured condition. EPA leak detection mandates and ASME boiler code standards sustain this approach for emissions and pressure-boundary compliance.
- Condition-Based:Intervention triggered by measured degradation exceeding threshold limits. Digital twin simulations of gas turbine performance are decomposing traditional time-based overhaul cycles into component-specific interventions.
- Risk-Based:Prioritization of maintenance resources based on failure probability and consequence severity. NRC inspection protocols require this for US nuclear safety-related systems.
- Performance-Based:Contractor compensation tied to achieved availability, heat rate, or output guarantees. Performance contracting is expanding among Southeast Asian utilities outsourcing first-generation CCGT maintenance.
Time-based strategies retain the largest installed base; condition-based approaches are gaining share fastest as sensor costs decline and analytics platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Japan where superalloy forging capabilities command outage-season premiums, while Indian utilities extract cost advantages through PLI-scheme localization and state genco restructuring programs.
United States
EPA Clean Air Act enforcement sustains dense preventive maintenance contract volumes for emissions-related inspection scopes. FERC rate-case oversight pressures municipal utilities in Texas and California to fragment long-term service agreements into competitively bid discrete contracts. The Southeast cluster around Atlanta and Charlotte hosts aging coal fleets requiring life-extension services.
Germany
EU F-Gas Regulation mandates accelerate chiller replacement timelines for combined-cycle facilities. ECHA refrigerant handling standards reshape contractor certification requirements for cooling system maintenance. The industrial Rhine-Ruhr corridor concentrates demand from chemical and steel producers facing compressed repair timelines.
India
NTPC and state gencos outsource structured maintenance programs to improve plant load factors on aging subcritical units. CEA oversight and PLI scheme incentives for domestic equipment production reduce import dependency for replacement parts. The western cluster of Gujarat and Maharashtra hosts the densest concentration of privatized maintenance functions.
Japan
METI efficiency standards and aging specialist technician cohorts tighten labor availability for ASME-certified inspection work. JIS standards and proprietary diagnostic platforms dominate the aftermarket for combined-cycle plants. The Chubu-Nagoya industrial zone anchors gas turbine maintenance demand from petrochemical complexes.
Vietnam
First-generation CCGT fleets from early-2010s capacity expansion cycles require privatized maintenance functions as state utilities unbundle service provision. Tropical outage seasons drive adoption of drone-based thermography to reduce scaffolding costs. The southern economic zone around Ho Chi Minh City concentrates IPP maintenance outsourcing.
Power Plant Maintenance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with OEM-linked providers commanding diagnostic platform premiums while independent service organizations compete on outage pricing and labor arbitrage. The market structure tiers between proprietary technology gatekeepers and scale-driven maintenance contractors. Three archetypes dominate: integrated OEM service arms with installed base leverage, independent turbine specialists with regional labor networks, and emerging AI-augmented diagnostics platforms. Competitive moves center on unbundling long-term service agreements and localizing parts supply chains through manufacturing incentives.
Within the OEM-anchored tier, General Electric Company and Siemens Energy AG occupy positions defined by deep installed base relationships and proprietary digital twin capabilities. Wärtsilä Corporation exemplifies the flexible-cycle specialist archetype competing against grid-balancing alternatives. Among Asia-Pacific scale contractors, Larsen & Toubro Limited and Doosan Enerbility Co., Ltd. represent the independent service organization model built on regional outage labor pools and state utility relationships.
| Leading Market Players |
|---|
| ENGIE SA |
| Wärtsilä Corporation |
| General Electric Company |
| John Wood Group PLC |
| Larsen & Toubro Limited |
| Siemens Energy AG |
| Doosan Enerbility Co., Ltd. |
| NAES Corporation |
| Mitsubishi Hitachi Power Systems, Ltd. |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for superalloy turbine blade forgings concentrate pricing power among German and Japanese specialty mills, while Indian PLI-scheme localization compresses replacement part costs for state genco buyers. This inventory-to-pricing linkage shapes how maintenance contractors structure outage contracts and where utilities source critical components.
Pricing Analysis
Configured-to-order pricing for OEM-linked digital twin platforms commands premiums of 40-60 percent above standard preventive maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and service bundling intensity. Cost compression in the standard tier is intensifying because independent service organizations in India and Vietnam compete aggressively on labor arbitrage. Municipal utilities in Texas and California exhibit the highest price sensitivity, driving competitive unbundling of long-term service agreements into discrete inspection and repair scopes.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for superalloy forgings and specialized welding consumables. Supply concentrates in Germany, Japan, and India for gas turbine hot section components, with Chinese production expanding for balance-of-plant equipment. Raw material dependencies center on nickel-based superalloys, cobalt-chromium welding wire, and refrigerant-grade hydrofluorocarbons. Single-source vulnerability persists for ASME-certified boiler inspection services where technician cohorts are aging faster than training programs replenish qualified candidates. Distribution runs through OEM-authorized service networks for warranty-compliant work, while independent contractors capture non-OEM aftermarket volume through regional labor pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities multiply as utility procurement departments unbundle traditional service relationships and Southeast Asian markets privatize first-generation fleet maintenance. Digital instrumentation penetration creates niches for AI-augmented diagnostic specialists outside OEM channels.
For Market Incumbents: Secure proprietary diagnostic platform lock-in through predictive analytics subscriptions that extend beyond OEM warranty periods. Deepen backward integration into superalloy component remanufacturing to defend margin position against Indian PLI-scheme localization. Channel control over certified technician training programs represents the priority defensive lever as ASME-qualified inspector scarcity intensifies. For New Entrants and Emerging Players: Differentiate on AI-augmented failure-mode prediction trained on Southeast Asian tropical outage datasets where drone-based thermography reduces scaffolding costs. Target Vietnamese and Indonesian first-generation CCGT fleets as the most penetrable geography, where state utility unbundling opens non-OEM service windows. A performance-based contracting go-to-market angle aligns with IPP merchant generator risk profiles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates spinning non-core power services divisions amid energy transition portfolio rebalancing. Long-term viability favors predictive maintenance platform specialists with demonstrated machine learning training datasets and utility reference contracts. The signal to watch as inflection indicator is accelerating battery storage substitution rates for simple-cycle peaking units, which compresses addressable turbine maintenance demand.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Diagnostic Platform Development | Machine learning platforms trained on vibration data extend component life beyond OEM intervals for NTPC and state gencos. |
| Backward Integration into Superalloy Remanufacturing | In-house blade repair capabilities reduce dependency on German and Japanese forging suppliers during outage seasons. |
| Performance-Based Contracting Expansion | Availability guarantees align contractor incentives with IPP merchant generator output requirements in Vietnam and Indonesia. |
| Drone-Based Thermography Service Launch | Unmanned aerial inspection reduces scaffolding costs and outage durations for Southeast Asian tropical maintenance windows. |
| PLI-Linked Domestic Parts Localization | Indian manufacturing incentives compress replacement part lead times for state genco restructuring programs. |
Research Methodology
The analysis maps preventive, predictive, corrective, and reliability-centered maintenance segments, each validated through utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads. Primary interviews with maintenance directors at NTPC, state gencos, and Southeast Asian utilities combined with secondary validation against EIA data, IEA reports, FERC filings, and CEA regulatory disclosures. Bottom-up service type segmentation triangulates against top-down regional demand aggregation.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework models service type, end user archetype, technology deployment, and maintenance strategy dimensions throughout the forecast period. CAGRs derive from segmented demand build-ups incorporating plant load factor improvement targets, EPA emissions enforcement timelines, and EU F-Gas phase-down schedules. Forecast inputs include aging fleet replacement cycles, digital instrumentation penetration curves, and outsourcing privatization patterns.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement, PLI scheme continuation, or technician training program expansion would require recalibration. Forecasts reflect documented assumptions regarding regulatory compliance intensity, superalloy supply availability, and battery storage substitution rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Asia-Pacific Power Plant Maintenance Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Power Equipment Testing Market
Power Equipment
France Power EPC Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Power Analyzers Market
Power Equipment
Ecuador Power EPC Market
Power Equipment
Process Air Heater Market
Power Equipment
AC Stabilized Power Supply Market
Power Equipment
Turbine Governor Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
Nigeria Power EPC Market