
 Industrial Demand Response Management Systems Market | 2026-2036
Industrial Demand Response Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Demand Response Management Systems Market Foresight
The gap between premium integrated platforms and commodity standalone controllers is rebalancing as large industrial buyers consolidate vendor relationships around full-stack solutions. Eaton leverages its electrical infrastructure heritage to anchor long-term service contracts with heavy manufacturing clients. Schneider Electric differentiates through deep integration between its building management and demand response software suites. Siemens competes on energy analytics depth, particularly in European utility partnerships.
Industrial demand response management systems coordinate electricity load reductions across factories, warehouses, and processing facilities using automated control signals, meter data, and pre-programmed curtailment protocols to stabilize grid frequency and reduce capacity charges. These systems typically interface with SCADA, EMS, or BAS architectures through open protocols such as OpenADR or proprietary utility APIs, executing load shifts in 4-second to 15-minute dispatch windows depending on grid operator requirements. Software platforms capture the dominant margin pool as recurring SaaS revenue displaces one-time licensing, while integration services face commoditization from standardized APIs. Automated control technology leads deployment volumes among manufacturing plants, though IoT-enabled edge devices represent the fastest-expanding segment as sensor costs decline and latency requirements tighten.
FERC Order 2222 in the United States enables aggregated distributed energy resources to participate in wholesale markets, directly expanding addressable revenue for industrial demand response providers. The EU Green Deal and national implementation frameworks such as Germany's EnWG amendments mandate demand-side flexibility as a core decarbonization lever, tightening product certification requirements through CE marking and harmonized grid codes. China's GB standards for industrial energy management and peak-shaving obligations under dual carbon goals shape market access for foreign platform vendors. Stakeholders must monitor evolving interconnection standards and carbon border adjustment mechanisms that will determine which solution architectures qualify for preferential procurement.
Market Dynamics
Automated load curtailment protocols are compressing dispatch windows from minutes to seconds, forcing industrial facilities to replace manual demand response with edge-computing architectures that synchronize SCADA triggers with wholesale market signals.
Growth Catalysts
- FERC Order 2222:The United States regulation enables aggregated distributed energy resources to bid into wholesale capacity markets, expanding revenue pools for industrial demand response aggregators serving manufacturing clusters in Texas and California.
- Steel and cement plants:Heavy process industries face escalating capacity charges from grid operators, driving automated curtailment system procurement to avoid peak pricing penalties during summer demand spikes.
- Cloud-native SaaS platforms:Subscription-based software architectures are displacing perpetual licensing, lowering upfront adoption barriers for mid-sized industrial facilities without dedicated energy management teams.
Market Restraints
- Copper and semiconductor input costs:IoT-enabled edge devices require specialized components whose price volatility squeezes hardware margins for system integrators deploying sensor networks across factory floors.
- German TSO certification bottlenecks:Prequalification testing for frequency containment reserves imposes 12-18 month approval timelines, delaying revenue recognition for platform vendors targeting EnWG-mandated flexibility markets.
- On-site generation substitutes:Behind-the-meter battery storage and combined heat and power systems compete for the same peak-shaving budget, fragmenting capital allocation in energy-intensive processing facilities.
Strategic Opportunities
- India's CEA mandate:The national regulator's peak-load obligation rules for designated consumers create first-mover advantage for OpenADR-certified platforms integrating with state load dispatch centers.
- Convergence of digital twins and demand response:Real-time process simulation combined with automated curtailment enables predictive load shaping in chemical processing plants without disrupting batch integrity.
- Utility direct-install programs:Channel partnerships with vertically integrated electricity retailers bypass capital constraints by financing control system deployment through tariff riders.
Industry Challenges
- SCADA protocol fragmentation:Industrial facilities operate heterogeneous automation stacks across Modbus, DNP3, and proprietary vendor implementations, complicating unified demand response command integration.
- Cybersecurity certification delays:IEC 62443 compliance timelines for industrial control systems extend project delivery by 6-9 months, straining implementation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Demand Response Management Systems Market |
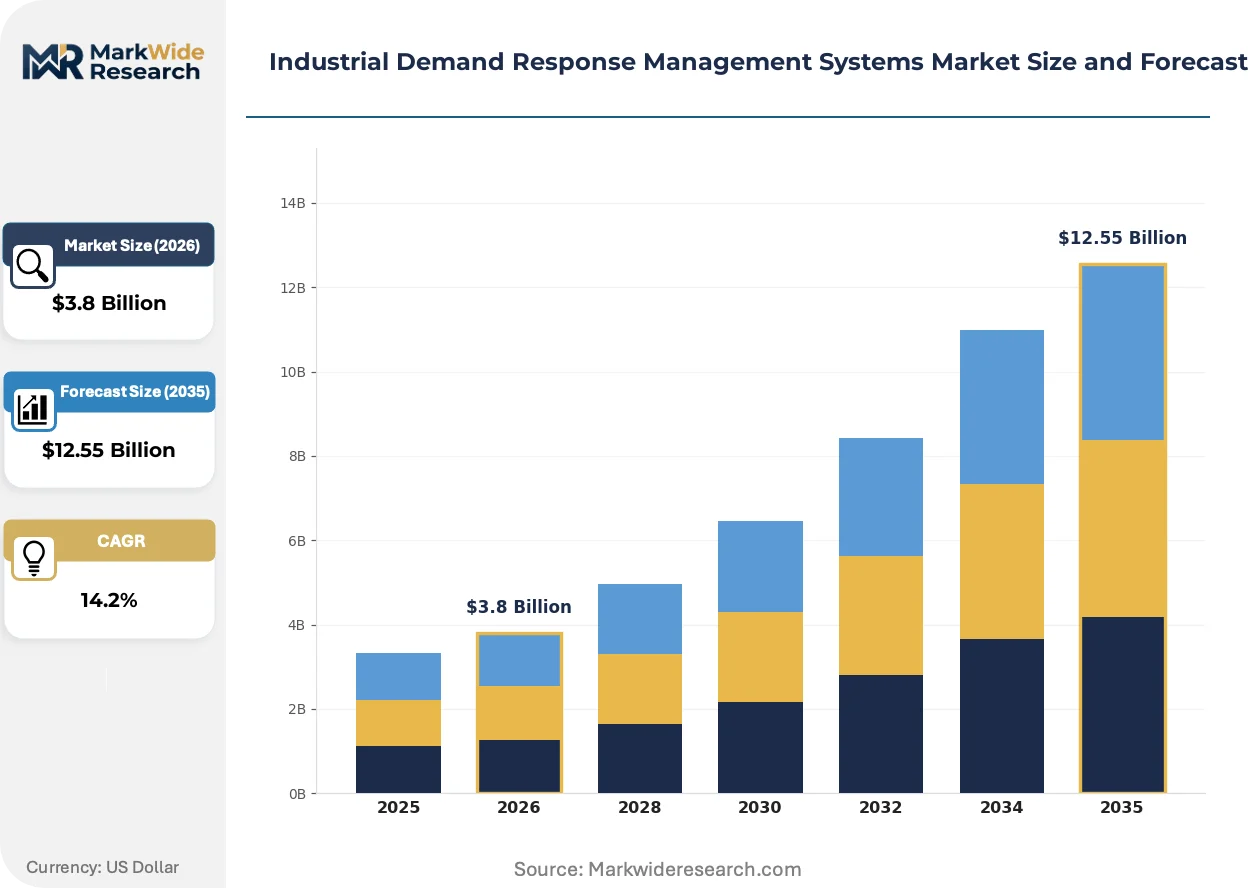
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Control, Smart Grid, IoT, Energy Storage Solution: Software Platforms, Consulting Services, Integration Services, Analytics Tools End User: Manufacturing Plants, Commercial Buildings, Utility Companies, Data Centers Installation: On-premises, Cloud-based, Hybrid, Remote Monitoring |
| Companies Covered | Eaton, Honeywell International, ABB, AutoGrid, Itron, Schneider Electric, General Electric, EnerNOC, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Demand Response Management Systems Market Shifts & Advancements
Edge-native control architectures are displacing centralized dispatch models, embedding decision logic directly at meter points to satisfy sub-second latency requirements from transmission system operators.
Artificial intelligence-driven load forecasting is expanding into predictive curtailment optimization, enabling cement and paper mills to pre-position production schedules before price spikes hit day-ahead markets. European heavy industry adopters in Germany and Poland are deploying these systems fastest, compressing the competitive advantage of early algorithmic adopters over rule-based competitors.
The EU Green Deal's demand-side flexibility mandate tightens product certification through harmonized grid codes and CE marking requirements for industrial energy management systems. National implementation frameworks in Germany, France, and Italy now require prequalified demand response assets for capacity market participation, forcing non-compliant legacy controllers into premature replacement cycles.
Energy-as-a-service contracting is restructuring procurement relationships, with industrial buyers transferring operational risk to platform vendors in exchange for guaranteed peak charge reductions. This model concentrates fastest among automotive assembly plants in the United States and Mexico, where volatile electricity tariffs make fixed-fee arrangements attractive to CFOs managing volatile operating margins.
Industrial Demand Response Management Systems Market Segmentation
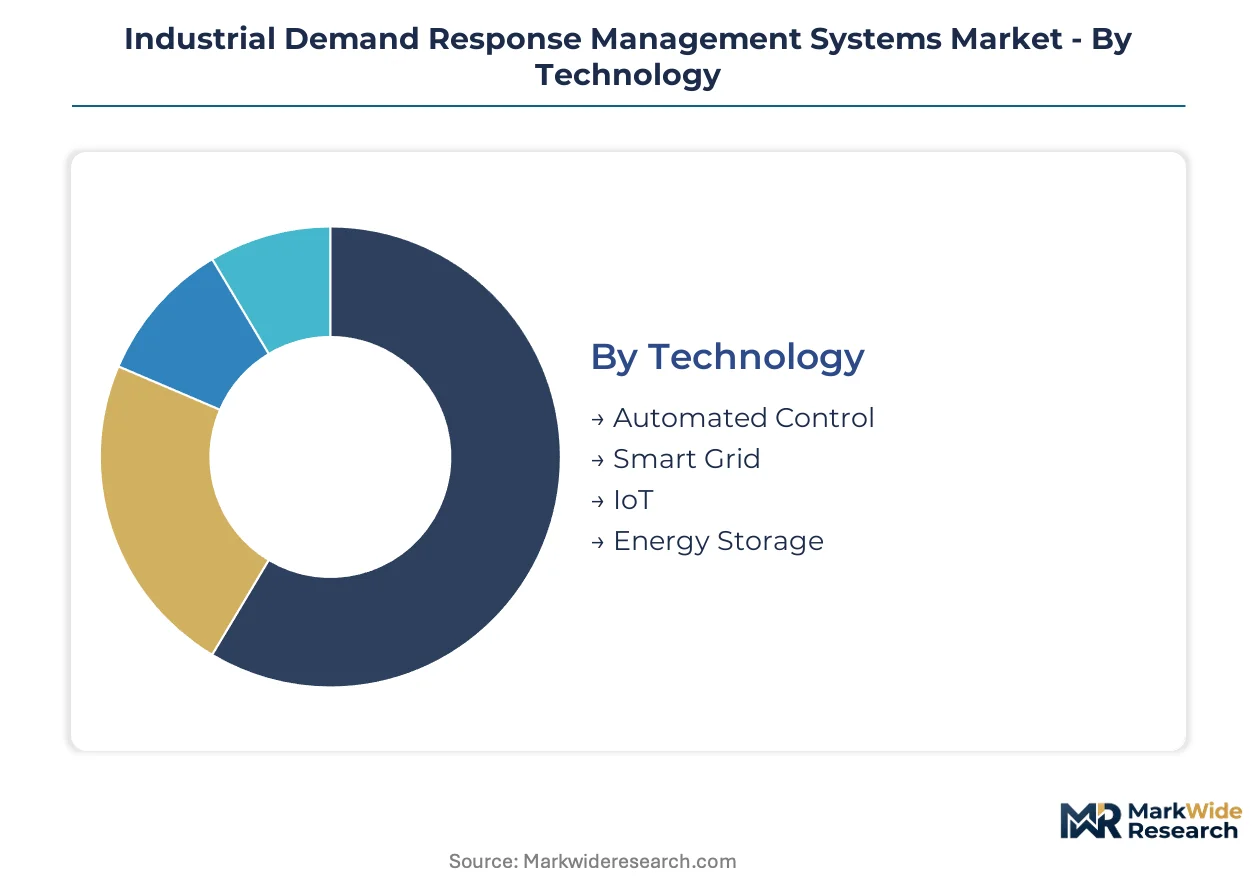
Industrial demand response management systems fragment across technology maturity, solution architecture, facility type, and deployment model. Each segmentation axis reveals distinct upgrade cycles and vendor positioning strategies.
Technology:
Replacement cycles vary sharply by technology vintage, with legacy systems facing obsolescence pressure from sub-second dispatch requirements.
- Automated Control:Programmable logic controllers and SCADA-integrated actuators execute load curtailment through pre-set protocols. Manufacturing plants in Germany and Texas deploy these most heavily to capture FERC Order 2222 wholesale market revenues without manual intervention.
- IoT:Wireless sensor networks and edge-computing nodes enable real-time telemetry from distributed industrial equipment. Deployment concentrates in automotive assembly plants seeking millisecond-latency response to grid frequency events as sensor costs decline.
- Smart Grid:Utility-facing communication infrastructure including OpenADR gateways and DNP3 protocol stacks. Demand clusters around European heavy industry participating in TSO-mandated flexibility markets.
- Energy Storage:Battery-backed demand response systems providing synthetic inertia and seamless load transition. Cement and steel plants in India adopt these to meet CEA peak-load obligations without production disruption.
Automated Control sits at the top of the volume ranking, with IoT climbing the fastest.
Solution:
Margin concentration follows recurring revenue intensity, with software architectures commanding premium valuations over project-based services.
- Software Platforms:Cloud-native SaaS architectures delivering curtailment optimization, market bidding, and compliance reporting through browser-based dashboards. Mid-sized industrial facilities without dedicated energy teams drive fastest expansion as subscription models displace perpetual licensing.
- Integration Services:SCADA protocol translation, API development, and legacy system retrofitting. These face commoditization from standardized OpenADR implementations and pre-certified hardware bundles.
- Consulting Services:Regulatory navigation, utility program enrollment, and curtailment strategy design. Demand concentrates in jurisdictions with complex prequalification requirements such as Germany's EnWG framework.
- Analytics Tools:Load forecasting algorithms and production-schedule optimization modules. Chemical processing plants deploy these to predict price spikes without disrupting batch integrity.
Software Platforms dominate revenue contribution, with Analytics Tools gaining share fastest.
End User:
Facility type determines dispatch flexibility, with continuous-process industries facing tighter operational constraints than batch operations.
- Manufacturing Plants:Automotive, electronics, and discrete assembly facilities with interruptible production lines. These generate the highest per-megawatt payments in Texas ERCOT and California CAISO markets due to rapid response capability.
- Data Centers:Hyperscale computing facilities with thermal load shifting and UPS-backed demand response. Water-cooled facilities in Northern Virginia and Frankfurt offer the deepest curtailment without IT workload migration.
- Commercial Buildings:Large-format retail and office complexes with HVAC-dominated load profiles. Utility direct-install programs target these for aggregated residential-scale participation under FERC Order 2222.
- Utility Companies:Vertically integrated electricity retailers deploying white-label demand response platforms for industrial customer bases. These prioritize vendor consolidation around full-stack solutions to reduce integration overhead.
Manufacturing Plants anchor volume leadership, with Data Centers expanding most quickly.
Installation:
Deployment architecture trade-offs center on cybersecurity certification timelines versus operational agility.
- Cloud-based:Fully managed SaaS delivery with automatic updates and centralized threat monitoring. Adoption accelerates among industrial buyers transferring operational risk to vendors through energy-as-a-service contracts.
- Hybrid:Split architectures with on-premises SCADA integration and cloud-based market bidding. These balance IEC 62443 compliance requirements with wholesale market access in European frequency containment reserve programs.
- On-premises:Air-gapped control systems meeting critical infrastructure cybersecurity mandates. Nuclear supply chain and defense-adjacent facilities in the United States require these despite higher capital intensity.
- Remote Monitoring:Vendor-managed operations centers overseeing distributed industrial portfolios. Steel and cement majors deploy these to centralize expertise across geographically dispersed production sites.
Cloud-based installations lead deployment counts, with Hybrid architectures gaining traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers specializing in grid automation and industrial control systems concentrate in Germany's Ruhr Valley, the United States' Texas Triangle, and China's Yangtze River Delta, anchoring demand response expertise in these manufacturing-heavy regions.
United States
Data centers in Northern Virginia and hyperscale computing facilities across Texas drive automated load curtailment procurement to manage volatile ERCOT pricing. FERC Order 2222 enables aggregated distributed energy resources to bid into wholesale capacity markets, expanding revenue pools for industrial aggregators. Manufacturing clusters in Houston and Dallas-Fort Worth deploy edge-computing architectures to capture sub-second dispatch payments.
Germany
Steel and cement plants in the Rhine-Ruhr industrial belt face escalating capacity charges from transmission system operators, accelerating automated curtailment system adoption. EnWG amendments mandate demand-side flexibility as a core decarbonization lever, tightening CE marking requirements through harmonized grid codes. Bavarian automotive assembly plants in Munich and Ingolstadt integrate cloud-native platforms with existing SCADA infrastructure to participate in frequency containment reserve markets.
China
Dual carbon goals and GB standards for industrial energy management shape market access for foreign platform vendors in the Yangtze River Delta. Peak-shaving obligations under national decarbonization targets drive procurement of battery-backed demand response systems. Heavy process industries in Shanghai and Suzhou deploy IoT-enabled edge devices to satisfy tightening latency requirements from grid operators.
India
The Central Electricity Authority's peak-load obligation rules for designated consumers create first-mover advantage for OpenADR-certified platforms. State load dispatch centers in Maharashtra and Gujarat require integrated demand response systems for large industrial consumers. Cement majors in Rajasthan and steel producers in Odisha adopt automated curtailment to avoid penalties during summer demand spikes.
Japan
METI's demand response programs for industrial consumers drive adoption of hybrid cloud-on-premises architectures in the Kanto region. Automotive and electronics manufacturers in Toyota City and Yokohama deploy predictive load forecasting to pre-position production schedules. Frequency regulation markets tighten latency requirements, favoring edge-native control systems over centralized dispatch models.
Industrial Demand Response Management Systems Market Competitive Landscape
Top-tier vendors anchor full-stack integrated platforms, while mid-tier specialists compete on vertical-specific customization and regional certification expertise. The vendor base stratifies across three tiers: electrical infrastructure conglomerates with long-term service contract capabilities, pure-play software platforms delivering SaaS-based optimization, and system integrators focused on legacy SCADA retrofitting. Dominant competitive moves include vendor consolidation around consolidated technology stacks and channel partnerships with vertically integrated electricity retailers.
Within the electrical infrastructure tier, Eaton and Schneider Electric exemplify full-stack positioning, while Siemens occupies a position emphasizing energy analytics depth. These three anchors represent contrasting approaches to industrial customer retention: Eaton leverages heritage in electrical infrastructure, Schneider Electric differentiates through building management integration, and Siemens competes on algorithmic sophistication in European utility partnerships. AutoGrid and EnerNOC exemplify the pure-play software archetype, representing cloud-native challengers unburdened by legacy hardware portfolios.
| Leading Market Players |
|---|
| Eaton |
| Honeywell International |
| ABB |
| AutoGrid |
| Itron |
| Schneider Electric |
| General Electric |
| EnerNOC |
| Siemens |
| Others |
Supply & Pricing Matrix
Copper futures volatility cascades through industrial demand response hardware tiers, compressing margins on IoT sensor assemblies while SaaS platforms capture pricing power through recurring revenue architectures insulated from commodity swings.
Pricing Analysis
Bundled energy-as-a-service contracts separate from unbundled software licensing across the competitive landscape. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with IEC 62443-compliant platforms commanding substantial premiums over uncertified alternatives. Price differentiation stems from after-sales service bundling and geographic delivery cost variations. Cost compression in hardware tiers is intensifying because semiconductor input volatility squeezes integrator margins, while mid-sized manufacturing plants exhibit highest price sensitivity due to capital constraint pressures.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement protocols for critical control components, with industrial buyers mandating multi-supplier qualification for programmable logic controllers and edge-computing nodes. Manufacturing concentrates in Germany, the United States, and China, drawing from specialized semiconductor foundries in Taiwan and South Korea. Raw material dependencies center on copper wiring, lithium-ion cells for battery-backed systems, and rare-earth magnets for actuator assemblies. Single-source vulnerability persists in advanced sensor modules. Distribution runs through system integrator channels and direct utility partnership programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software platforms where SaaS recurring revenue displaces project-based services, driven by sensor cost-down curves enabling broader addressable market penetration.
For Market Incumbents: Deepen vertical integration into edge-computing hardware to defend against pure-play software challengers unburdened by legacy manufacturing overhead. Expand IEC 62443 certification portfolios to maintain premium pricing power as cybersecurity mandates tighten procurement specifications. Anchor long-term service contracts through electrical infrastructure heritage advantages.
For New Entrants and Emerging Players: Launch via utility direct-install programs to bypass capital constraints among mid-sized industrial facilities lacking dedicated energy management teams. Target India's CEA-mandated peak-load obligation markets where OpenADR certification creates first-mover structural advantage. Prioritize cloud-native architectures over on-premises deployments to accelerate customer acquisition velocity.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented system integrators face commoditization from standardized APIs and pre-certified hardware bundles. Long-term viability favors platforms with demonstrated European TSO prequalification track records and established utility partnership channels. Monitor FERC Order 2222 implementation velocity across Texas and California as inflection indicator for wholesale market revenue expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| OpenADR Certification Investment | Unlocks participation in California CAISO and Texas ERCOT wholesale markets for aggregated resources. |
| Edge-Native Control Architecture Development | Satisfies sub-second latency requirements from German transmission system operators for frequency reserves. |
| Utility Direct-Install Partnership | Bypasses capital constraints by financing deployment through tariff riders in vertically integrated markets. |
| IEC 62443 Compliance Pathway | Accelerates project delivery timelines and qualifies platforms for critical infrastructure procurement. |
| Digital Twin Integration | Enables predictive load shaping in chemical processing without disrupting batch integrity protocols. |
Research Methodology
Coverage spans Germany, the United States, China, and India, with primary inputs from each market gathered through structured interviews with utility planning officers, industrial plant engineers, demand response aggregators, and grid operator dispatch coordinators. Secondary validation draws from FERC filings, EIA electricity market data, IEA demand-side flexibility reports, and EU Green Deal implementation tracking. Bottom-up facility-level deployment estimates triangulate against top-down market sizing from regulatory mandate quantification.
Rate-of-change decomposition separates volume expansion from value-per-unit evolution across the analysis window. Segmentation dimensions modeled include technology vintage, solution architecture, facility type, and deployment model, with additional granularity on latency requirement tiers and certification status. CAGRs derive from regression analysis against historical adoption curves and policy implementation schedules. Forecast inputs incorporate copper price trajectory assumptions and TSO prequalification timeline distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FERC Order 2222 implementation or extended German TSO certification bottlenecks. Deviation in semiconductor supply availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Smart Power Technologies Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Brazil Energy Sector Market
Energy Management
Power SCADA Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Electric Sub-Meter Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
Industrial Energy Management System Market
Energy Management
Europe Energy Management Systems Market
Energy Management
Energy Security Market
Energy Management
Germany Demand Response Management Systems Market
Energy Management
Global Utility Asset Management Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Middle-East and Africa Demand Response Management Systems Market
Energy Management
Energy Harvesting System Market