
 Submarine Power Cable Market | 2026-2036
Submarine Power Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Power Cable Market Analysis
Multi-source procurement for XLPE insulation compounds is realigning how tier-one cable contractors manage supply risk across project cycles. Prysmian Group leverages backward integration into compound manufacturing to protect margin stability on large-diameter contracts. Nexans sustains competitive position through specialized vessel fleets for deep-water installation. ZTT Group anchors Asia-Pacific project execution with integrated cable and accessory production.
Submarine power cables are insulated conductor assemblies engineered for direct current or alternating current transmission across marine environments, typically rated from 33 kV to 525 kV and armored with galvanized steel wire for mechanical protection during laying and operation. Their primary purpose is to transport bulk electrical power between offshore generation assets and onshore grids, or to link national transmission systems across seabed corridors. High voltage cables dominate capital allocation given their role in long-distance interconnectors and gigawatt-scale offshore wind export circuits. Offshore wind farms represent the fastest-expanding application segment as floating platform projects extend into deeper waters requiring dynamic cable solutions.
EU regulators enforce the F-Gas Regulation and CE marking requirements that constrain insulation gas choices and mandate third-party conformity assessment for subsea cable systems deployed in European waters. The International Electrotechnical Commission publishes IEC 62288 and related standards governing cable design testing that manufacturers must satisfy for project bankability and insurer acceptance. Stakeholders must monitor how emerging national content requirements and carbon border adjustments reshape sourcing geography for conductor metals and cable laying services.
Market Dynamics
Offshore wind farm developers are scaling individual project capacities past one gigawatt, forcing cable contractors to engineer 525 kV HVDC systems with single continuous lengths exceeding eighty kilometers without factory joints.
Growth Catalysts
- EU Green Deal offshore targets:The framework mandates 300 GW of offshore renewable capacity by 2050, requiring extensive subsea transmission corridors between North Sea generation clusters and continental load centers.
- Floating platform proliferation:Dynamic cable engineering for semi-submersible and tension-leg platforms unlocks deeper water sites previously inaccessible to fixed-bottom foundations.
- Cross-border interconnector pipelines:Germany, the United Kingdom, and the Netherlands are advancing multi-gigawatt transmission links that standardize procurement specifications for 320 kV and 525 kV cable systems.
Market Restraints
- Copper and aluminum price volatility:Conductor metals constitute forty to fifty percent of raw material costs, exposing project margins to London Metal Exchange fluctuations without effective hedging instruments at contract award.
- Installation vessel scarcity:Purpose-built cable lay vessels with dynamic positioning class three certification number fewer than fifteen units globally, creating queue congestion for deep-water projects.
- F-Gas Regulation insulation constraints:The EU framework phases down sulfur hexafluoride use in accessories, forcing redesign of gas-insulated terminations and joints with alternative dielectric media.
Strategic Opportunities
- Floating offshore wind in Portugal and France:Pre-commercial arrays in the Atlantic basin require dynamic cable solutions that incumbent suppliers have not yet standardized, creating entry paths for specialized engineering firms.
- HVDC-XLPE technology maturation:Extruded insulation systems for direct current are displacing mass-impregnated paper in voltage classes above 200 kV, enabling lighter cables and simplified jointing protocols.
- Carbon border adjustment mechanism:The EU's phased implementation rewards cable manufacturers with verified low-carbon smelting and compound production, penalizing imports from carbon-intensive supply bases.
Industry Challenges
- Subsea survey and route engineering talent:Geophysicists and marine spatial planners with experience in unexploded ordnance clearance and benthic habitat mapping command premium compensation and limited availability.
- IEC 62288 type-testing timelines:Pre-qualification protocols for 525 kV systems require eighteen to thirty-six months of accelerated aging and electrical load cycling, compressing project development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Power Cable Market |
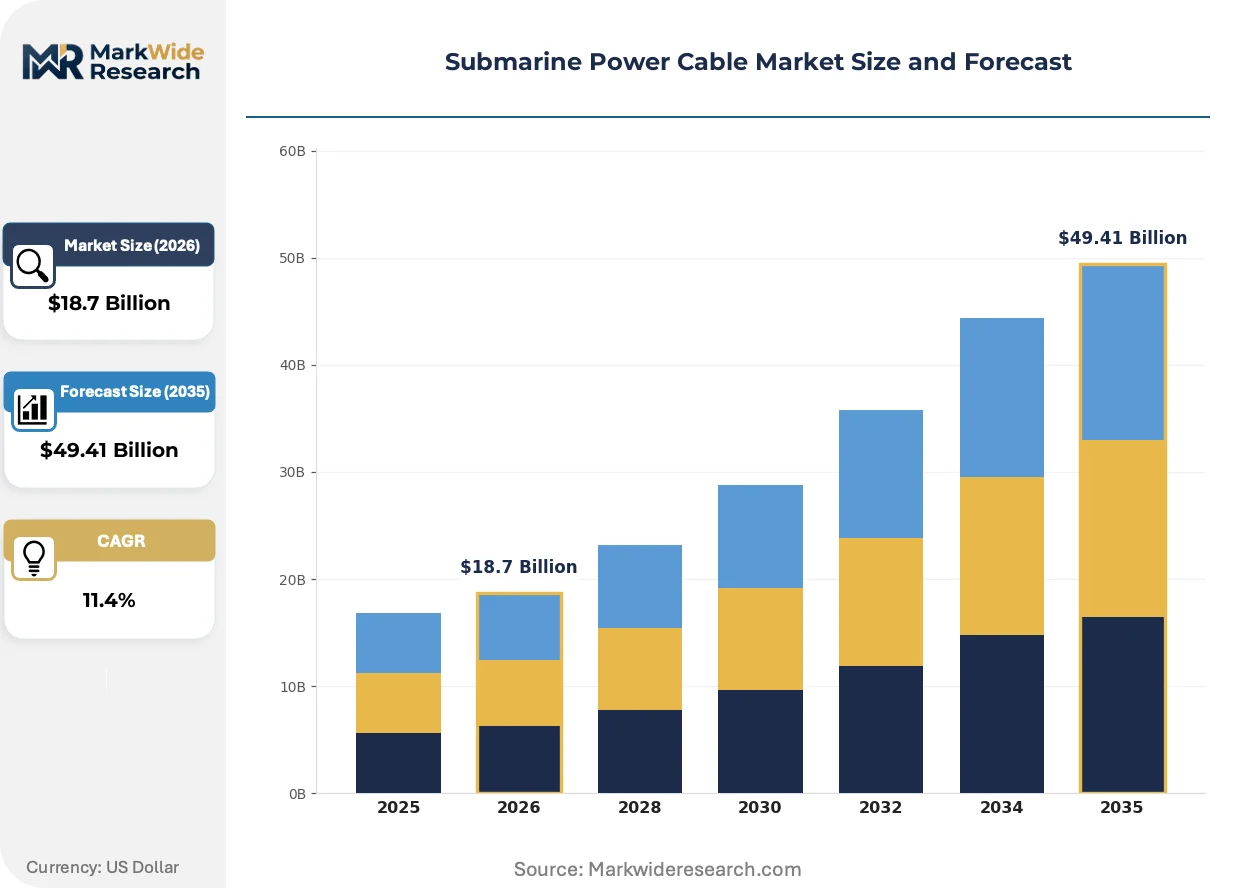
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Medium Voltage, Low Voltage, Fiber Optic Application: Offshore Wind Farms, Interconnectors, Subsea Oil & Gas, Utility Scale Installation Method: Trenching, Buried, Laid on Seabed, Plowed End User: Utilities, Oil & Gas Companies, Renewable Energy Providers, Governments |
| Companies Covered | Sumitomo Electric Industries, LS Cable & System, Prysmian Group, ZTT Group, Furukawa Electric, Nexans, Hengtong Group, ABB, NKT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Power Cable Market Emerging Trajectories
Materials science breakthroughs and regulatory pressure on embodied carbon are restructuring how cable systems are designed, manufactured, and validated for bankability.
High-temperature superconducting tapes are converging with conventional submarine cable architectures in demonstration projects. Transmission system operators in South Korea and Japan are piloting nitrogen-cooled systems for urban infeed applications. This convergence is compressing the technical gap between laboratory performance and commercial deployment timelines for bulk power transfer.
The EU F-Gas Regulation is accelerating substitution of sulfur hexafluoride in cable accessories with dry-type or vacuum-insulated alternatives. Manufacturers must requalify termination designs under revised IEC standards without grandfathering existing product lines. Offshore wind export cable packages for German and Danish projects are most affected, with developers now mandating SF6-free specifications in tender documentation.
Long-term service agreements are displacing traditional equipment-only procurement for interconnector projects. Transmission system operators in the United Kingdom and Norway are bundling twenty-five-year availability guarantees with initial cable supply. This shift concentrates risk with tier-one contractors and sidelines pure manufacturing plays without installation and maintenance capabilities.
Submarine Power Cable Market Segmentation
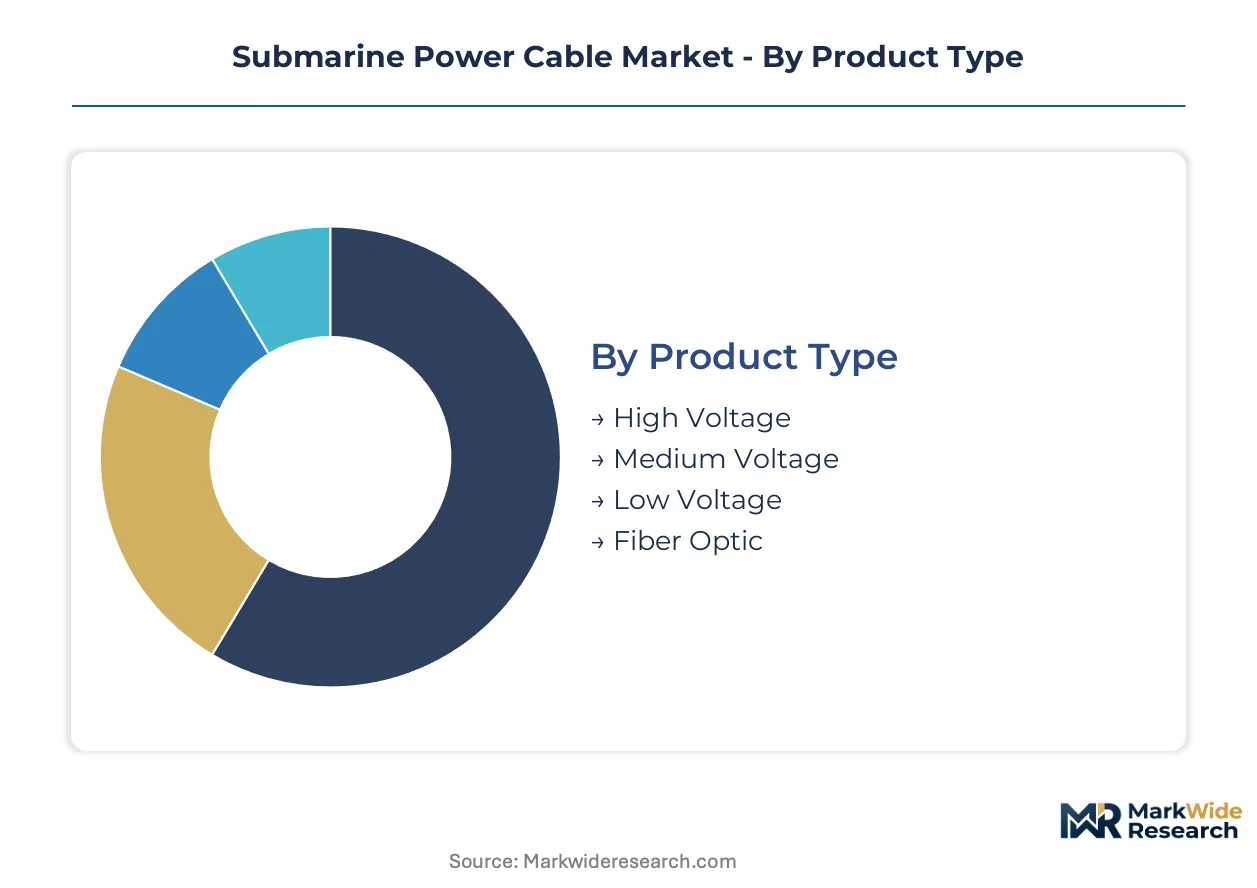
Submarine power cable procurement patterns diverge sharply across voltage classes and installation contexts. Understanding these divides clarifies where capital concentrates and which technical specifications command premium pricing.
Product Type:
High voltage cables absorb the majority of project capital, while medium and low voltage products serve niche distribution roles.
- High Voltage:Extruded XLPE or mass-impregnated paper insulation rated 200 kV to 525 kV, engineered for HVDC and HVAC bulk transmission. Demand concentrates in German and UK interconnector corridors where 525 kV systems transport gigawatt-scale power across North Sea routes without intermediate substations.
- Medium Voltage:33 kV to 150 kV class cables with polymeric insulation, common in offshore wind array cables and platform interlinks. Procurement volumes are climbing fastest in Chinese coastal provinces where provincial grid operators standardize 66 kV export circuits for near-shore wind clusters.
- Low Voltage:Subsea distribution cables below 33 kV for island interconnections and coastal industrial feeds.
- Fiber Optic:Composite power-communication cables with embedded optical elements for monitoring and control.
Today's leader: High Voltage. Tomorrow's challenger: Medium Voltage.
Application:
End-use demand splits between renewable export infrastructure and cross-border transmission assets.
- Offshore Wind Farms:Export cables connecting turbine arrays to onshore substations, with floating platform projects now requiring dynamic cable engineering. UK Round 4 and German auction rounds are driving procurement of 220 kV and 525 kV systems with route lengths exceeding sixty kilometers.
- Interconnectors:Subsea transmission links between national grids, demanding highest reliability specifications and long-term service agreements. The Norway-UK North Sea Link and planned Germany-Denmark corridors exemplify this segment's capital intensity and multi-year development timelines.
- Subsea Oil & Gas:Power cables for platform electrification and subsea processing equipment.
- Utility Scale:Coastal grid reinforcement and island supply projects.
Offshore wind export cables are expanding most quickly, while interconnectors retain the highest contract values per kilometer.
Installation Method:
Seabed conditions and regulatory requirements determine trenching depth and protection strategies.
- Trenching:Mechanical cutting of narrow seabed channels for cable burial in soft sediments, common in North Sea sand and clay zones where fishing activity necessitates deep protection.
- Buried:Post-lay burial using remotely operated vehicles with jetting swords, applied in rocky or coral substrates where pre-trenching is impractical.
- Laid on Seabed:Surface placement with rock dumping or mattress protection for hard seabed or pipeline crossings.
- Plowed:Simultaneous laying and burial using cable plows towed by lay vessels, efficient for long uninterrupted routes in compliant soils.
Jet trenching dominates soft sediment provinces, while mechanical plowing maintains cost advantage for long linear routes.
End User:
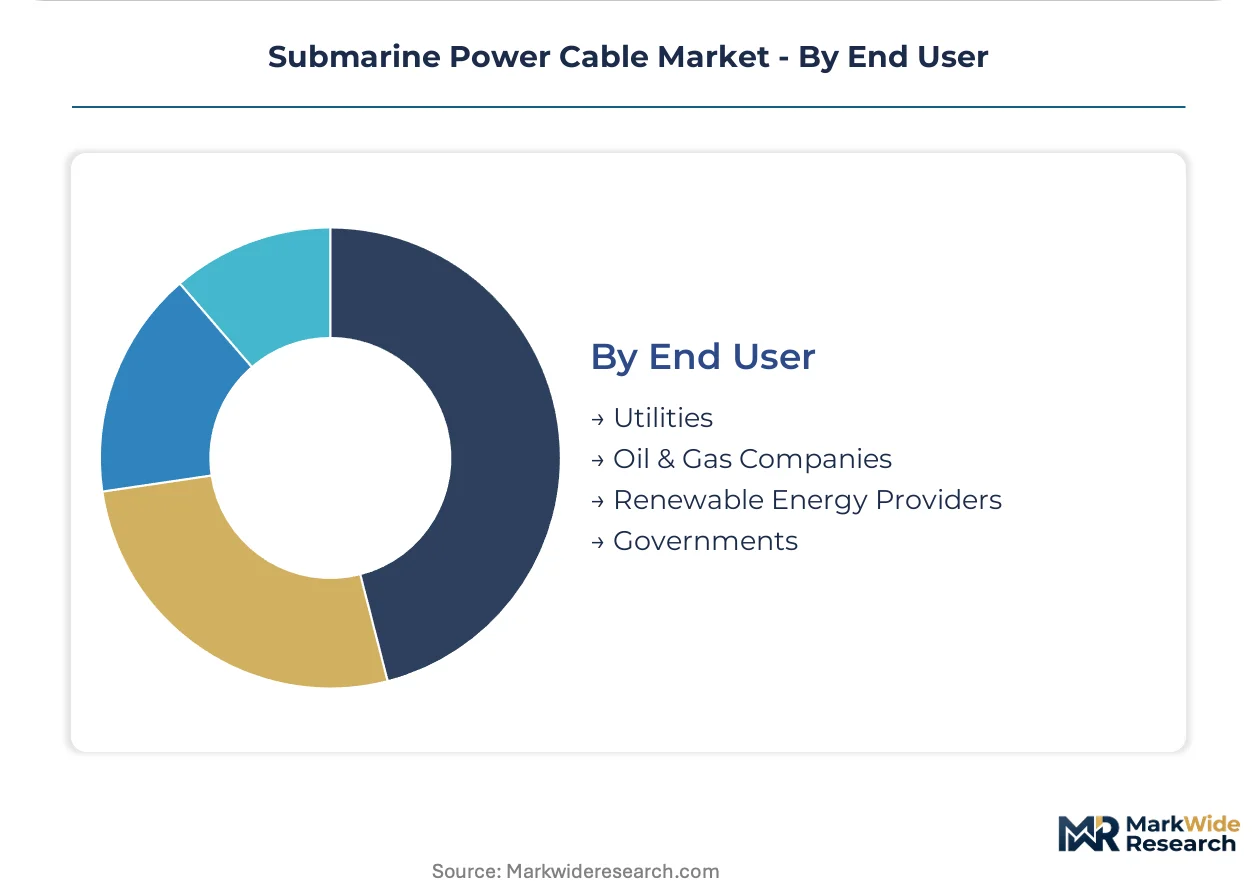
Procurement authority rests with entities bearing long-term asset risk and regulatory compliance obligations.
- Utilities:Transmission system operators in Germany, the UK, and the Netherlands owning interconnectors and grid reinforcement assets. TenneT, National Grid, and Energinet drive standardization of 525 kV HVDC specifications through bundled EPCI contracts.
- Renewable Energy Providers:Offshore wind developers including Ørsted, RWE, and Equinor procuring export cables as part of generation asset packages. These buyers increasingly mandate SF6-free accessories and carbon-verified materials in tender criteria.
- Oil & Gas Companies:Platform electrification and subsea power distribution purchasers.
- Governments:Direct procurement for strategic interconnector and island supply projects.
Utilities currently control the largest committed capital pipelines, though renewable developers are gaining procurement volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea corridor anchors submarine power cable demand through 2035, with Germany, the United Kingdom, and the Netherlands driving interconnector and offshore wind procurement. China and South Korea are scaling domestic manufacturing to serve Asia-Pacific project pipelines.
Germany
TenneT and 50Hertz are tendering 525 kV HVDC corridors linking North Sea wind clusters to Bavarian and Baden-Württemberg load centers. The EU Green Deal's offshore targets mandate 70 GW of German marine capacity by 2045, tightening F-Gas Regulation compliance for cable accessories. Cable laying contractors cluster in Bremen and Hamburg ports to serve the BorWin and DolWin converter platforms.
United Kingdom
National Grid and ScottishPower are advancing the Eastern Link and Shetland interconnector projects requiring 320 kV and 525 kV systems. The UK regulator Ofgem enforces price control mechanisms that favor long-term service agreements over equipment-only procurement. Manufacturing and installation engineering concentrates in Newcastle and Aberdeen, with port infrastructure scaling for Dogger Bank export cables.
China
State Grid and China Southern Power Grid are commissioning 500 kV HVAC and 535 kV HVDC submarine links across the Taiwan Strait and Bohai Bay. The National Development and Reform Commission prioritizes indigenous cable technology through the Made in China 2025 framework. Production and testing facilities cluster in Nantong and Yangzhou, with ZTT Group and Hengtong Group expanding extrusion capacity for 220 kV and above.
South Korea
KEPCO is deploying 345 kV and 400 kV submarine circuits for Jeju Island interconnection and offshore wind export. The Ministry of Trade, Industry and Energy enforces local content requirements under the Renewable Energy 3020 plan. Cable system integration and marine engineering concentrate in Busan and Ulsan, with LS Cable & System anchoring HVDC technology development for East Asian markets.
Netherlands
TenneT is procuring 525 kV HVDC systems for the IJmuiden Ver and Hollandse Kust offshore grid connections. The Dutch government implements EU taxonomy alignment for sustainable finance, favoring cable suppliers with verified low-carbon smelting. Engineering and project management functions cluster in Rotterdam and Eindhoven, with the Maasvlakte port serving as North Sea cable logistics hub.
Submarine Power Cable Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and installation capability, producing a tiered structure where integrated suppliers capture premium interconnector contracts. European and East Asian conglomerates anchor the top tier through captive vessel fleets and backward integration into compound production. Three archetypes dominate: full-service EPCI contractors, specialized cable manufacturers, and installation-focused engineering firms. Competitive moves concentrate on vessel fleet expansion and qualification of 525 kV HVDC-XLPE systems under revised IEC standards.
Within the integrated EPCI tier, Prysmian Group and Nexans exemplify European market positioning through bundled supply and installation contracts. ZTT Group anchors Chinese competitive dynamics with integrated cable and accessory production for Asia-Pacific projects. Sumitomo Electric Industries and LS Cable & System occupy positions bridging East Asian manufacturing scale with emerging HVDC technology deployment.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| LS Cable & System |
| Prysmian Group |
| ZTT Group |
| Furukawa Electric |
| Nexans |
| Hengtong Group |
| ABB |
| NKT |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed cable manufacturers in China and South Korea anchor supply-side discipline through state-financed capacity expansion, compressing margins for privately held European specialists while reinforcing long-term contracting power for utility buyers in Germany and the United Kingdom.
Pricing Analysis
Input-cost pass-through for copper and aluminum conductor metals dominates contract negotiations, with London Metal Exchange fluctuations absorbed through indexed pricing clauses in multi-year offtake agreements between TenneT and tier-one suppliers. Three-tier pricing structure across HVDC-XLPE premium systems, standard HVAC extruded cables, and economy-grade array cables separates procurement by voltage class and certification tier. Cost compression in medium-voltage segments is intensifying because Chinese producers are scaling 220 kV extrusion capacity for domestic wind farm export circuits. Renewable energy providers exhibit highest price sensitivity due to project finance leverage ratios, while transmission system operators prioritize availability guarantees over unit cost.
Supply Chain Analysis
Specialized marine engineers and geophysicists with unexploded ordnance clearance certification command premium compensation in Nantong, Bremen, and Newcastle manufacturing clusters, constraining production ramp rates for 525 kV systems. Geographic supply concentration centers on China for conductor drawing and XLPE compounding, Germany for HVDC converter platform integration, and Italy for specialized cable lay vessel outfitting. Raw material dependencies draw from Chilean copper cathode, Qatari aluminum smelting, and German specialty polymer production. Single-source vulnerability for dynamic positioning class three cable lay vessels creates queue congestion risk. Distribution runs through port-centric logistics hubs at Maasvlakte, Rotterdam, and Yangzhou with heavy-lift quayside infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The submarine power cable market reads as a late-cycle quality story, with procurement criteria hardening around IEC 62288 type-testing completion and SF6-free accessory specifications as offshore wind developers shift from cost-minimization to bankability-assurance.
For Market Incumbents: Lock in vessel fleet utilization through multi-project charter agreements with TenneT and National Grid before specialized installation assets face competition from Chinese shipyard newbuilds. Prioritize backward integration into low-carbon copper smelting to capture carbon border adjustment mechanism premiums in EU procurement tenders. The threat of HVDC-XLPE technology displacement by high-temperature superconducting pilots in South Korea demands accelerated R&D partnerships with transmission system operators. For New Entrants and Emerging Players: Digital-channel route optimization for subsea survey and route engineering software offers white-space entry without capital-intensive manufacturing. Target floating offshore wind dynamic cable engineering in Portugal and France where incumbent suppliers lack standardized product platforms. The most penetrable segment is pre-commercial Atlantic basin arrays requiring specialized mechanical fatigue modeling. A go-to-market angle anchored in digital twin simulation for cable-soil interaction modeling bypasses vessel ownership requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among installation-focused engineering firms without captive cable manufacturing, as bundled EPCI contracting concentrates margin capture with integrated suppliers. Long-term viability across the projection horizon rests on exposure to 525 kV HVDC qualification pipelines and converter platform integration capabilities. The acquisition target archetype is regional cable accessory specialists with SF6-free termination designs. The signal to watch is IEC standard revision timelines for extruded DC insulation above 320 kV.| Strategic Initiative | Industry Significance |
|---|---|
| Vessel Fleet Expansion | Secures installation queue position for TenneT's 525 kV HVDC corridor tenders. |
| Backward Integration into Compound Production | Protects margin stability against XLPE resin price volatility in long-diameter contracts. |
| SF6-Free Accessory Certification | Unlocks German and Danish offshore wind procurement under F-Gas Regulation compliance. |
| Dynamic Cable Engineering Partnerships | Captures floating platform proliferation in Portugal's pre-commercial Atlantic arrays. |
| Long-Term Service Agreement Bundling | Aligns with UK Ofgem price control mechanisms favoring availability guarantees. |
Methodological Framework
Multiple input streams — structured interviews with submarine cable project directors, vessel fleet managers, and utility procurement officers, alongside validation against IEC standard committee documentation and FERC interconnector filings — were reconciled through bottom-up project pipeline aggregation and top-down transmission system operator capex analysis.
Cross-referencing historical installation cost trajectories against expert panel assessments of HVDC-XLPE technology maturation shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include voltage class, insulation technology type, installation method, and end-user procurement authority. CAGRs were derived from project-level capacity commitment timelines and converter platform commissioning schedules. Industry-specific forecast inputs encompass cable lay vessel orderbook visibility and copper smelter carbon intensity benchmarking.
The model assumes a particular technology adoption path for extruded HVDC insulation displacing mass-impregnated paper; alternative pathways for gas-insulated line technology would alter the outlook for 525 kV system standardization. Forecasts reflect assumptions regarding EU Green Deal offshore target continuity and F-Gas Regulation enforcement stringency. Material deviation in vessel delivery schedules or unexploded ordnance clearance regulatory thresholds warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
AC Power Sources Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Europe Power Rental Market
Power Equipment
Levant Power Cable Market
Power Equipment
Induction Heating System Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Air Preheater Market
Power Equipment
Global Medium Voltage AC Drives Market
Power Equipment
China Power EPC Market
Power Equipment
United States Power Rental Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Power Generation Equipment MRO Market