
 Steam Turbine Control System Market | 2026-2036
Steam Turbine Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Turbine Control System Market Insights
The capability gap between full-stack automation providers and component specialists is rotating competitive capital allocation toward integrated platform investments. Siemens Energy leverages its turbine OEM heritage to bundle control systems with long-term service contracts. Honeywell International sustains aftermarket revenue through proprietary distributed control architectures that lock in upgrade cycles. ABB competes by extending its electrification portfolio into turbine-specific safety and governor modules.
A steam turbine control system governs speed, load, and protective shutdown functions through integrated sensors, actuators, and algorithmic governors, typically managing response times below 100 milliseconds to prevent overspeed events. These systems ensure synchronous grid connection, thermal stress mitigation, and emergency trip reliability in baseload and peaking power plants. Digital Control Systems now dominate new procurement as utilities replace analog relay logic with model-based predictive algorithms. Retrofit installations represent the fastest-growing installation category as operators seek to extend asset life without greenfield capital expenditure. Electromechanical governor segments remain entrenched in marine and remote oilfield applications where digital infrastructure proves cost-prohibitive.
IEC 61850 communication protocols and IEEE 1547 grid interconnection standards shape product development roadmaps for turbine control vendors seeking utility certification. The EPA's Mercury and Air Toxics Standards and corresponding emissions compliance timelines in Europe under the Industrial Emissions Directive force control system upgrades that optimize combustion efficiency and startup flexibility. Stakeholders must monitor how cybersecurity frameworks from NERC CIP and IEC 62443 constrain remote diagnostics architectures without degrading predictive maintenance value.
Market Dynamics
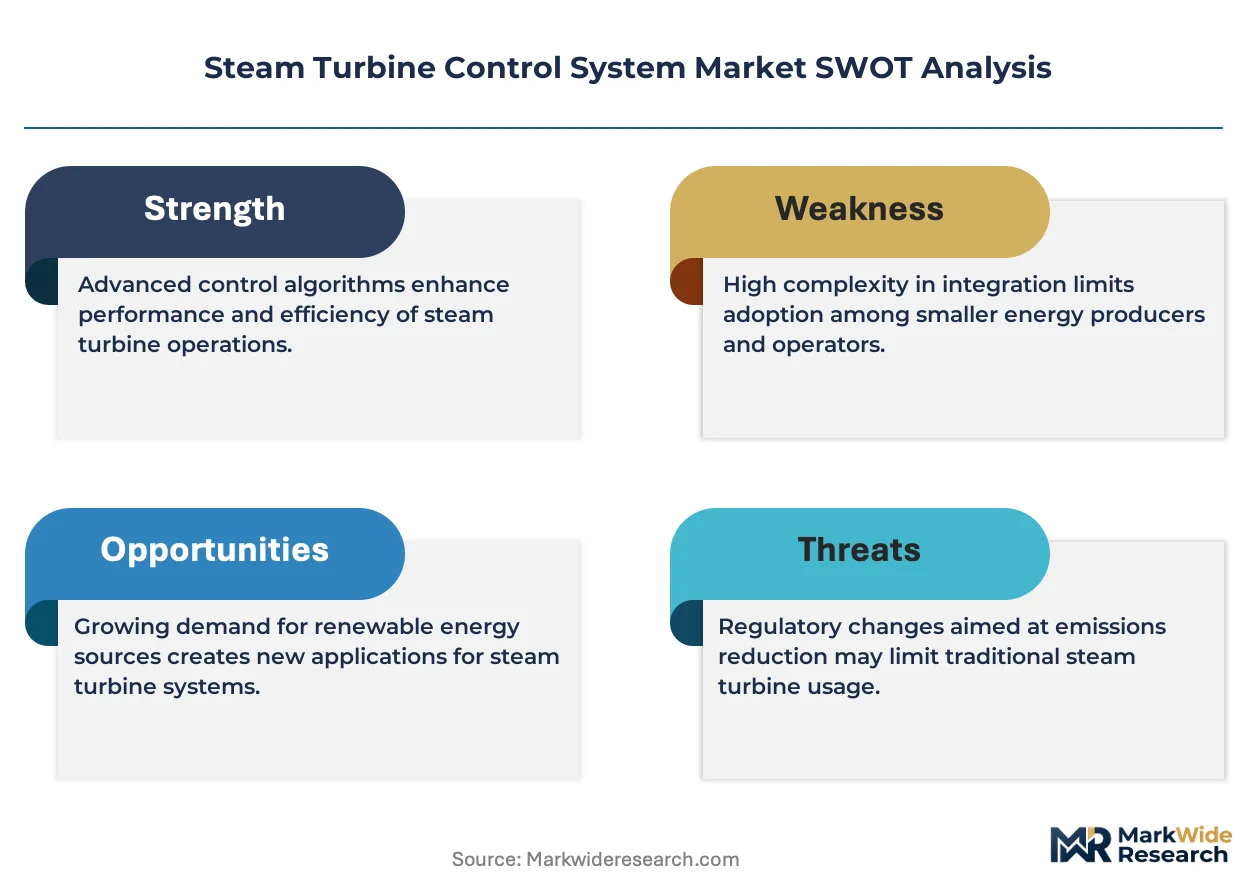
The migration from analog relay logic to model-based digital architectures is compressing upgrade cycles and redistributing vendor power toward full-stack automation providers with proprietary distributed control platforms.
Growth Catalysts
- IEC 61850 Interoperability Mandates:Grid stability requirements across Asia-Pacific utilities are forcing turbine fleet modernization, creating pull-through demand for communication-protocol-compliant control architectures.
- Predictive Maintenance Software:Power plant operators in China are bundling AI-driven diagnostics with control system retrofits to reduce unplanned outage frequency and extend asset life cycles.
- Emissions Compliance Timelines:The EPA's Mercury and Air Toxics Standards and Europe's Industrial Emissions Directive are accelerating control system replacements that optimize combustion efficiency and startup flexibility.
Market Restraints
- Semiconductor Component Volatility:Prolonged lead times for industrial-grade processors and FPGAs are extending project delivery schedules and inflating system integration costs.
- Electromechanical Lock-In:Marine and remote oilfield installations remain tethered to analog governor hardware where digital infrastructure deployment proves economically prohibitive.
- Cybersecurity Compliance Friction:NERC CIP and IEC 62443 framework requirements are constraining remote diagnostic architectures without degrading predictive maintenance value propositions.
Strategic Opportunities
- Nuclear Fleet Modernization:State-owned generators in China are executing large-scale retrofits of nuclear steam turbine assets, creating concentrated demand for safety-certified digital control platforms.
- Grid-Forming Inverter Convergence:Integration of turbine governor logic with battery energy storage dispatch algorithms is opening new revenue streams for hybrid power plant control vendors.
- Service Contract Unbundling:Independent service providers are penetrating aftermarket maintenance segments previously captured by OEM-locked proprietary architectures.
Industry Challenges
- Legacy System Integration Complexity:Retrofit installations must bridge 30-year-old analog sensor networks with modern digital buses without triggering protective relay misoperations during cutover.
- Functional Safety Certification Bottlenecks:SIL-rated turbine protection modules face extended validation timelines from notified bodies, delaying project commissioning and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Turbine Control System Market |
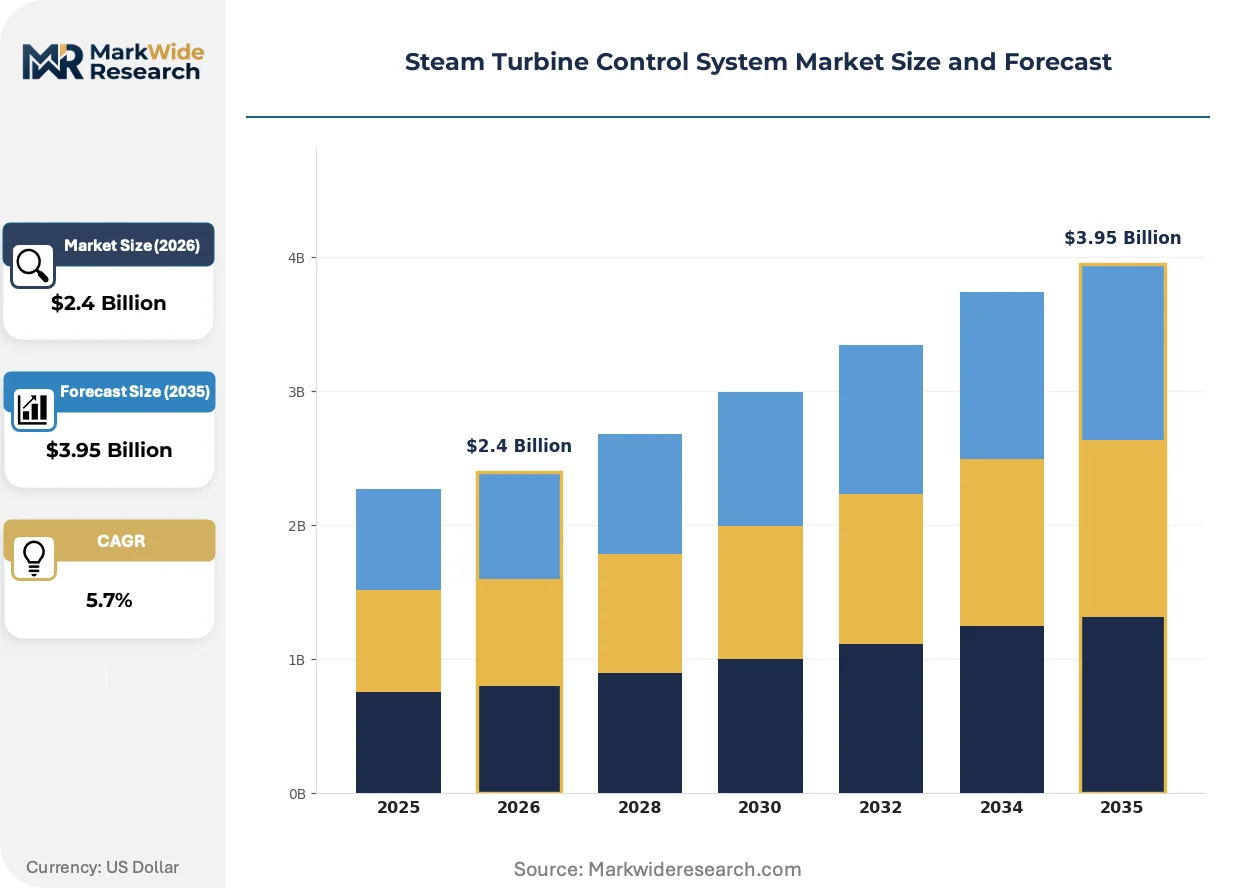
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Control Systems, Mechanical Control Systems, Hybrid Control Systems, PLC-Based Control Systems End User: Power Generation, Oil & Gas, Manufacturing, Marine Technology: Electromechanical, Programmable Logic Controllers, Distributed Control Systems, Supervisory Control and Data Acquisition Installation: Onshore, Offshore, Retrofits, New Installations |
| Companies Covered | Mitsubishi Heavy Industries, Honeywell International, Siemens Energy, Rockwell Automation, Eaton, General Electric, Emerson Electric, Yokogawa Electric Corporation, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Turbine Control System Market Trends and Innovations
Digital control architectures are actively displacing electromechanical heritage across baseload and peaking power applications, compressing the viable lifespan of analog relay logic and redistributing competitive advantage toward software-integrated platform vendors.
Model-based predictive control algorithms are supplanting traditional PID governor tuning in combined-cycle and nuclear applications. Siemens Energy and Honeywell International are embedding physics-informed digital twins directly into turbine protection loops, enabling sub-50-millisecond overspeed response. This capability compression is marginalizing standalone governor specialists who lack real-time simulation expertise.
The EU's Cyber Resilience Act and corresponding NIS2 Directive implementation timelines are forcing control system vendors to embed secure-by-design architectures from silicon layer upward. Vendors seeking utility certification must now demonstrate SBOM traceability and runtime attestation across the full sensor-to-actuator chain. European OEMs are responding fastest, leveraging existing IEC 62443-4-2 development pipelines to preempt compliance deadlines.
Power plant procurement committees are consolidating vendor selection authority from site engineering teams to centralized fleet technology offices. This buyer concentration is compressing evaluation cycles and privileging long-term service agreements over discrete hardware transactions. The shift is most visible in China's state-owned generation sector, where provincial grid companies now mandate unified control platforms across coal, nuclear, and gas turbine assets.
Steam Turbine Control System Market Segmentation
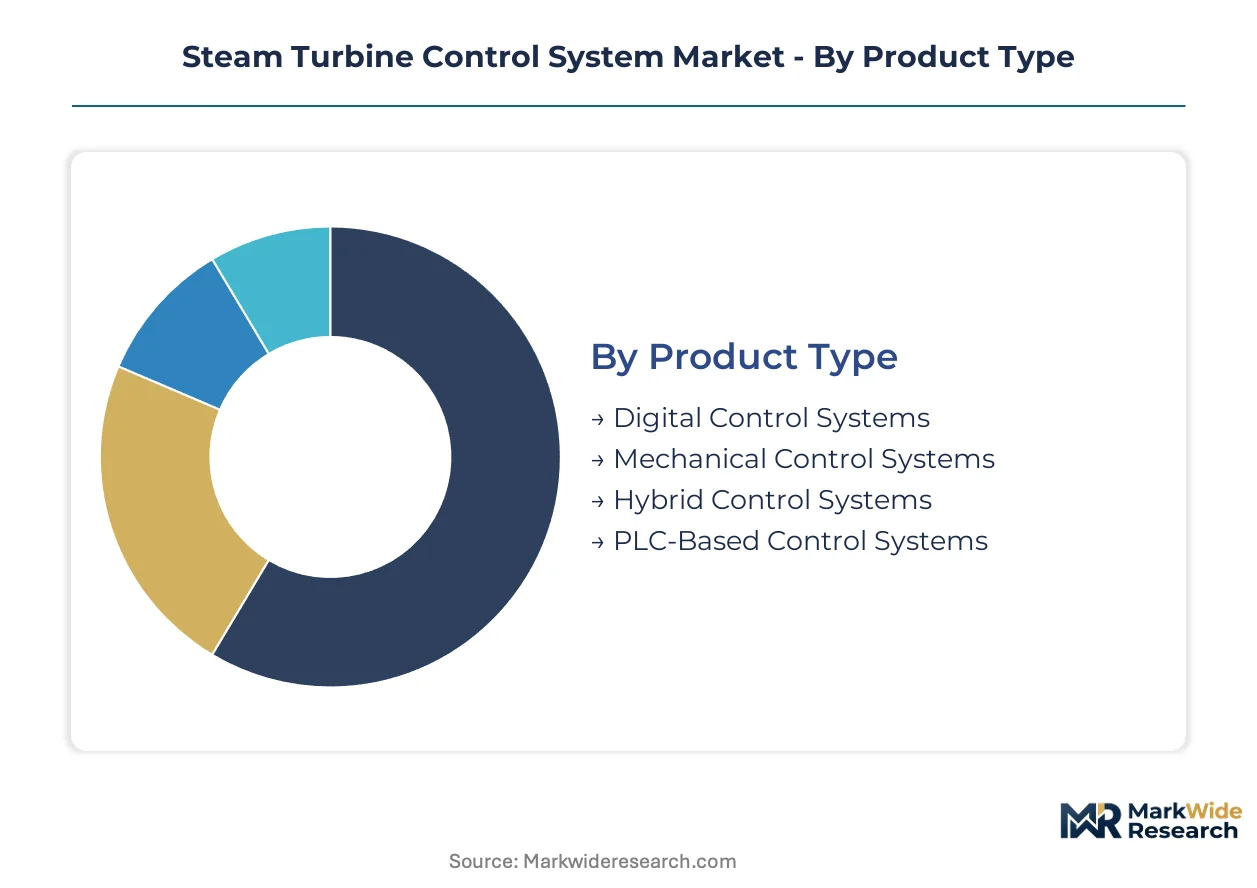
Control system procurement patterns diverge sharply across turbine vintages and operational environments. Segment boundaries reflect competing pressures between digital modernization imperatives and electromechanical lock-in economics.
Product Type:
Digital architectures face substitution pressure from hybrid configurations in capital-constrained retrofit scenarios where full-stack replacement proves uneconomical.
- Digital Control Systems:These architectures integrate model-based predictive algorithms with sub-100-millisecond governor response capabilities. Demand concentrates in Chinese state-owned power generators executing nuclear and coal fleet retrofits to comply with IEC 61850 grid stability mandates.
- Mechanical Control Systems:Analog relay logic and electromechanical governors persist in installations where digital infrastructure deployment costs exceed operational savings. Marine propulsion systems and remote oilfield turbines remain tethered to these heritage configurations.
- Hybrid Control Systems:Bridge configurations combining digital supervisory layers with retained electromechanical actuators. These systems appeal to operators seeking partial modernization without protective relay recertification.
- PLC-Based Control Systems:Programmable logic controllers adapted from general industrial automation for turbine-specific governor and protection functions. These systems compete on integration speed rather than performance margins.
Digital Control Systems anchor the volume base while Hybrid Control Systems gain share at the steepest rate.
End User:
Cost tier stratification separates mission-critical baseload applications from intermittent-duty installations where control system redundancy specifications relax.
- Power Generation:Utilities demand SIL-rated protection modules with predictive maintenance integration. Chinese provincial grid companies mandate unified platforms across coal, nuclear, and gas turbine assets.
- Oil & Gas:Remote extraction sites prioritize ruggedized electromechanical governors over digital architectures where satellite connectivity proves unreliable.
- Manufacturing:Cogeneration and combined heat-and-power installations drive demand for compact PLC-based systems with simplified operator interfaces.
- Marine:Classification society rules and salt-air corrosion constraints favor sealed mechanical governor enclosures over electronic alternatives.
Power Generation commands the revenue concentration while Marine represents the most price-sensitive procurement tier.
Technology:
Application maturity curves separate established electromechanical installations from emerging distributed architectures requiring cybersecurity certification.
- Electromechanical:Centrifugal governors and hydraulic actuators with decades of field-proven reliability. These systems dominate marine and remote oilfield applications where digital infrastructure costs prove prohibitive.
- Programmable Logic Controllers:Industrial automation platforms adapted for turbine speed and load control through specialized I/O modules. Manufacturing cogeneration plants favor these systems for rapid commissioning.
- Distributed Control Systems:Full-stack architectures integrating turbine protection with plant-wide process control. Honeywell and Siemens Energy leverage proprietary DCS platforms to lock in long-term service contracts.
- Supervisory Control and Data Acquisition:SCADA layers enable centralized fleet monitoring but face NERC CIP and IEC 62443 compliance friction for remote diagnostic architectures.
Distributed Control Systems capture the premium value pool while Programmable Logic Controllers expand most quickly in mid-scale applications.
Installation:
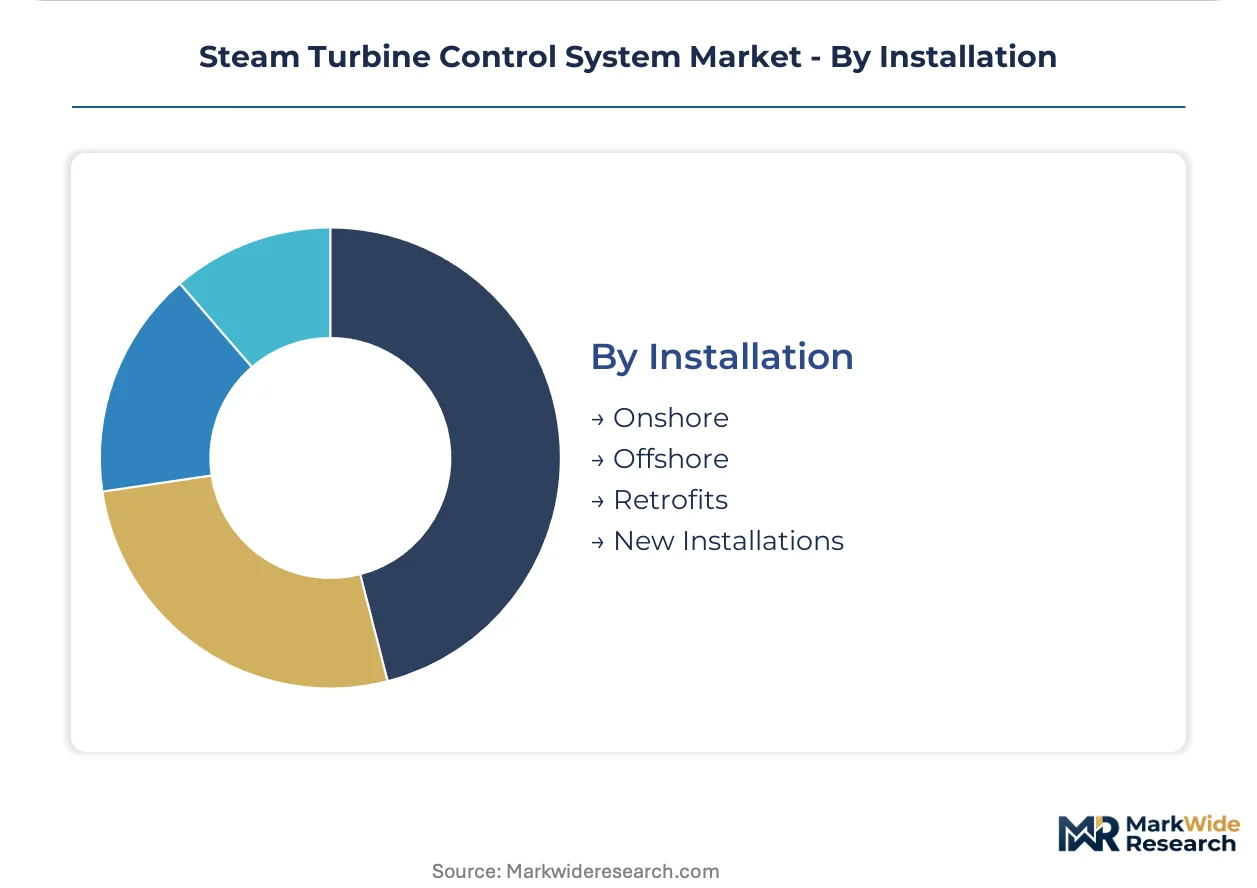
Volume concentration tilts toward brownfield retrofits as operators seek asset life extension without greenfield capital expenditure authorization.
- Onshore:Ground-based power plants with established digital bus infrastructure. These installations favor comprehensive DCS replacements over partial upgrades.
- Offshore:Platform-based turbines where space constraints and salt-air corrosion drive demand for compact, sealed control enclosures.
- Retrofits:Bridge installations connecting 30-year-old analog sensor networks to modern digital architectures. Chinese nuclear fleet modernization represents the largest concentrated retrofit demand.
- New Installations:Greenfield projects specifying integrated turbine-generator-control packages from single OEM sources. These procurements consolidate vendor selection authority at fleet technology offices.
Retrofits dominate current procurement volume while New Installations show the steepest expansion trajectory in nuclear and combined-cycle segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in steam turbine control systems tilt toward net importing positions in emerging economies while established manufacturing bases in Germany, Japan, and the United States supply digital governor platforms to utility retrofit programs across Asia-Pacific and the Middle East.
China
State-owned generators in China are executing concentrated retrofits of nuclear and coal steam turbine fleets to comply with IEC 61850 grid stability mandates issued by the National Energy Administration. Provincial grid companies now mandate unified control platforms across generation assets. The Yangtze River Delta cluster around Shanghai hosts the largest concentration of system integration activity for these modernization programs.
United States
US power utilities face accelerated control system replacement timelines under EPA Mercury and Air Toxics Standards compliance deadlines. FERC grid reliability directives are forcing turbine governor upgrades at aging baseload plants. The Gulf Coast petrochemical corridor drives demand for ruggedized control architectures in combined-cycle applications.
Germany
German utilities are retrofitting lignite and gas turbine assets to meet EU Industrial Emissions Directive requirements and coal phase-out schedules. The EU Cyber Resilience Act is forcing secure-by-design control architectures with SBOM traceability. The Rhine-Ruhr industrial region concentrates engineering expertise for these safety-certified digital migrations.
Japan
Japanese utilities are modernizing nuclear turbine control systems following METI safety reviews post-Fukushima. Grid interconnection standards under IEEE 1547 adaptations are reshaping procurement for thermal assets. The Chubu region around Nagoya hosts specialized vendors supplying governor protection modules for these precision-critical installations.
India
Indian state electricity boards are importing digital control platforms to retrofit aging coal turbines under CEA grid code compliance pressures. The country's national power regulator is mandating frequency response capabilities that analog governors cannot deliver. Gujarat and Maharashtra industrial clusters are concentrating demand for PLC-based systems in captive cogeneration plants.
Steam Turbine Control System Market Competitive Landscape
Concentration sits with full-stack automation providers who bundle turbine control systems with long-term service contracts. The vendor base stratifies into three tiers: proprietary distributed control system platforms, electromechanical heritage specialists, and industrial automation generalists. Strategic moves center on backward integration into safety-certified silicon and predictive maintenance software acquisitions.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries, Siemens Energy, and General Electric occupy positions that span turbine original equipment manufacture through integrated control system supply. These players exemplify the full-stack archetype where turbine heritage anchors control platform specification authority. Honeywell International and Emerson Electric represent the automation-native tier, competing through proprietary DCS architectures that lock in aftermarket upgrade cycles.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Honeywell International |
| Siemens Energy |
| Rockwell Automation |
| Eaton |
| General Electric |
| Emerson Electric |
| Yokogawa Electric Corporation |
| ABB |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month lead times for industrial-grade FPGAs and safety-certified processors are compressing vendor margins while amplifying pricing power for distributors holding buffer inventory. This supply scarcity tilts procurement toward long-term framework agreements that lock in component allocation before spot-market premiums materialize.
Pricing Analysis
Configured-to-order digital control platforms command 40-60 percent premiums over standard PLC-based configurations due to SIL certification requirements and custom governor algorithm development. Project-based pricing dominates, with final cost hinging on integration complexity and legacy system bridging requirements. Cost compression in the PLC-based tier is intensifying because industrial automation generalists are flooding mid-scale cogeneration applications with commoditized offerings. Marine and remote oilfield operators exhibit the highest price sensitivity, accepting performance trade-offs to avoid digital infrastructure capital outlays.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability crunches at Shanghai and Rotterdam are inflating inbound logistics costs for European and North American system integrators. Manufacturing concentrates in Germany, Japan, and the United States for precision governor modules, while China dominates PLC controller and sensor assembly. Supply chains draw from Taiwanese semiconductor foundries, German precision machining clusters, and Japanese industrial automation component suppliers. Single-source vulnerability around safety-certified processors creates exposure to export control restrictions. Distribution runs through OEM-direct channels for utility-scale projects and specialized industrial distributors for mid-tier manufacturing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Control system procurement authority is fragmenting from centralized fleet offices toward site-level engineering teams seeking niche solutions, creating entry points for specialized vendors outside full-stack automation hierarchies.
For Market Incumbents: Fortify proprietary DCS architectures through backward integration into safety-certified silicon supply, preempting component shortages that independent service providers exploit. Lock in provincial grid company relationships in China through unified platform mandates spanning coal, nuclear, and gas turbine assets. Prioritize IEC 62443-4-2 certification pipelines to preempt EU Cyber Resilience Act compliance deadlines before European competitors consolidate secure-by-design positioning.
For New Entrants and Emerging Players: Anchor in hybrid control system configurations that bridge 30-year-old analog sensor networks with digital supervisory layers, targeting capital-constrained retrofit operators avoiding full-stack replacement. Penetrate India's state electricity board procurement through PLC-based frequency response solutions that analog governors cannot deliver. Pursue independent service provider positioning to unbundle aftermarket maintenance from OEM-locked proprietary architectures.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because buyer concentration at fleet technology offices is compressing vendor counts toward integrated platform providers with predictive maintenance software capabilities. Target acquisition candidates with physics-informed digital twin expertise and existing IEC 61850 certification authority. Watch for inflection when Chinese nuclear fleet modernization programs shift from retrofit to new installation procurement, signaling margin expansion for safety-certified platform vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Safety-Certified Silicon | Captive processor supply insulates margins from 18-month lead time volatility affecting competitors. |
| Unified Platform Mandate Pursuit | Provincial grid company consolidation in China privileges vendors spanning coal, nuclear, and gas turbine assets. |
| Predictive Maintenance Software Acquisition | AI-driven diagnostics bundling extends asset life cycles and locks in long-term service contract renewals. |
| IEC 62443-4-2 Certification Pipeline | Secure-by-design architectures preempt EU Cyber Resilience Act deadlines before compliance becomes table stakes. |
| Independent Service Provider Positioning | Unbundling aftermarket maintenance penetrates segments previously captured by OEM-locked proprietary DCS architectures. |
Research Methodology
The analysis maps digital control architectures, electromechanical heritage systems, hybrid bridge configurations, and PLC-based platforms, each validated through utility planning officers, EPC contractors, aftermarket service heads, and OEM procurement teams. Primary intelligence combines structured interviews with plant engineers and maintenance directors at baseload and peaking power facilities across China, the United States, Germany, and India. Secondary validation draws from FERC filings, EIA power plant databases, IEC standard committee documentation, and CEA grid code notifications. Bottom-up unit economics triangulate against top-down market sizing from trade flow analysis and announced retrofit program scopes.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models technology substitution curves, installation type splits, and end-user concentration patterns. Segmentation dimensions include control system architecture, turbine vintage, operational environment, and regional regulatory framework. CAGRs derive from vintage-specific replacement cycles and announced fleet modernization program timelines. Forecast inputs incorporate announced nuclear retrofit commitments in China, EPA compliance deadlines in the United States, and EU Industrial Emissions Directive phase-out schedules.
Material uncertainties — semiconductor lead time normalization, cybersecurity framework enforcement intensity, and grid stability mandate implementation pacing — sit outside the modeled envelope. Forecasts reflect assumptions about continued IEC 61850 adoption and sustained state-owned generator capital allocation toward retrofit programs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
France Power EPC Market
Power Equipment
Global Power Supply Market
Power Equipment
Thailand Power Market
Power Equipment
Air Preheater Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Submarine Power Cable Market
Power Equipment
Digital Power Conversion Market
Power Equipment
Wind Turbine Components Market
Power Equipment
China Power EPC Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Japan Power EPC Market
Power Equipment
Turbine Control Systems Market