
 Wind Turbine Control System Market | 2026-2036
Wind Turbine Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Control System Market Analysis
IEC 61400-25 certification compliance is collapsing the supplier base for grid-connected turbine controls, forcing vendors to demonstrate interoperability across SCADA and power electronics layers. Siemens Gamesa Renewable Energy leverages its turbine OEM heritage to sustain integrated control-to-blade architectures. ABB Ltd. anchors high-voltage converter and grid integration modules across European and Asian wind portfolios. Emerson Electric Co. competes through specialized condition monitoring platforms that extend asset life for independent power producers.
A wind turbine control system comprises hardware and software modules that regulate blade pitch, generator torque, yaw orientation, and grid synchronization, typically operating within temperature ranges of minus forty to plus seventy degrees Celsius and processing sensor inputs at millisecond cycle times to maximize energy capture and structural safety. The system serves to optimize aerodynamic efficiency, prevent mechanical overload, and ensure compliance with electrical grid interconnection standards. Programmable Logic Controller architectures dominate onshore retrofits where cost sensitivity pressures hardware selection, while Supervisory Control and Data Acquisition platforms capture expanding margin pools in offshore arrays requiring centralized fleet management. Sensor Technology segments lead technology-level investment as lidar-based wind preview and blade load sensing displace legacy anemometer configurations.
FERC Order 2023 in the United States and the EU Grid Code Requirements issued by ENTSO-E are mandating enhanced frequency response and synthetic inertia capabilities, directly shaping control system firmware roadmaps and validation protocols. China's GB/T 25385 standard and NMPA-equivalent grid access rules enforce distinct testing regimes that fragment certification pathways for multinational suppliers. Stakeholders must monitor evolving grid code harmonization efforts across jurisdictions to determine whether centralized platform development or region-specific product variants offer superior capital efficiency.
Market Dynamics
Offshore wind farm developers are demanding integrated control architectures that unify blade pitch, generator torque, and grid synchronization under single software stacks, compressing procurement cycles and elevating firmware interoperability above hardware cost in vendor selection criteria.
Growth Catalysts
- GB/T 25385 grid access rules:China's national standard mandates enhanced fault-ride-through capabilities, forcing turbine OEMs to upgrade legacy control firmware and creating replacement demand across installed base.
- Lidar-based wind preview:Sensor technology investments accelerate as nacelle-mounted lidar systems enable predictive pitch adjustment, boosting annual energy production for independent power producers.
- Offshore array scale-up:Supervisory Control and Data Acquisition platforms capture expanding deployment as centralized fleet management becomes essential for multi-hundred-turbine complexes.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet generator architectures depend on neodymium processing concentrated in China, exposing control system manufacturers to input cost volatility and geopolitical sourcing risk.
- IEC 61400-25 certification complexity:Interoperability testing across SCADA and power electronics layers extends product validation timelines, collapsing the supplier base and elevating compliance costs for smaller vendors.
- Silicon carbide converter pricing:Wide-bandgap semiconductor adoption in grid integration modules faces cost barriers against established IGBT configurations, slowing high-voltage converter upgrades.
Strategic Opportunities
- India coastal wind zones:Underpenetrated offshore licensing rounds create first-mover positioning for turbine control suppliers willing to localize firmware for CEA grid codes and tropical cyclone resilience.
- FERC Order 2023 synthetic inertia mandates:Frequency response requirements open firmware upgrade revenue streams from existing US onshore fleets previously exempt from advanced grid services.
- Digital twin convergence:Physics-based modeling fused with operational sensor streams enables predictive maintenance contracts, shifting vendor revenue from hardware sales to recurring software subscriptions.
Industry Challenges
- Embedded systems firmware expertise:Millisecond-cycle control algorithm development requires specialized talent scarce outside aerospace and automotive sectors, constraining R&D velocity for mid-tier suppliers.
- Multi-jurisdiction certification parallelism:Divergent testing regimes across ENTSO-E, GB/T, and FERC standards fragment validation resources, delaying product launches and inflating quality assurance headcount.
- Legacy PLC architecture integration:Cost-sensitive onshore retrofits demand backward compatibility with decades-old Programmable Logic Controller installations, complicating feature rollouts and security patching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Control System Market |
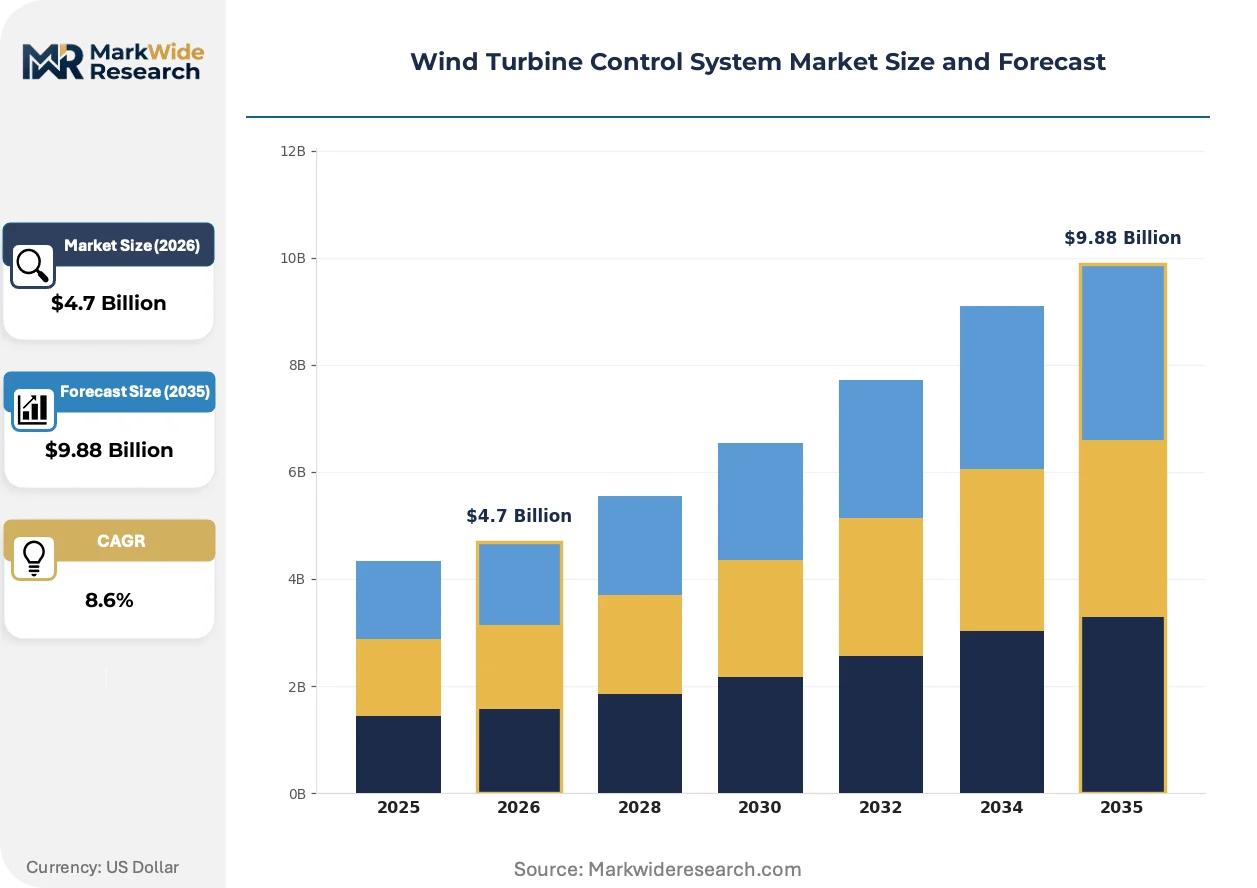
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distributed Control System, Programmable Logic Controller, Supervisory Control and Data Acquisition, Drive Control System Technology: Sensor Technology, Power Electronics, Communication Protocols, Monitoring Systems End User: OEMs, Independent Power Producers, Utilities, Service Providers Application: Load Control, Condition Monitoring, Performance Optimization, Grid Integration |
| Companies Covered | Woodward Inc., Siemens Gamesa Renewable Energy, ABB Ltd., Rockwell Automation Inc., Honeywell International Inc., Emerson Electric Co., Vestas Wind Systems A/S, Compressor Controls Corp., General Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Control System Market Emerging Trajectories
Control system architectures are converging around edge-computing nodes that process sensor data locally, reducing latency for blade load response while enabling centralized fleet analytics through standardized data protocols.
Model predictive control algorithms are supplanting classical proportional-integral-derivative loops in offshore turbine installations. Siemens Gamesa Renewable Energy and Vestas deploy these architectures across North Sea arrays, compressing pitch actuation response times and enabling sustained operation through transient wind shear events that previously triggered emergency shutdowns.
ENTSO-E's EU Grid Code Requirements now mandate synthetic inertia provision from all new wind farms above 50 MW capacity. This policy compresses firmware development cycles as OEMs must validate frequency-watt control curves across multiple grid operator jurisdictions, with German TSOs imposing the most stringent droop response testing protocols.
Independent power producers are unbundling condition monitoring contracts from original turbine supply agreements. Asset owners in Texas and Oklahoma now procure blade load sensing and gearbox vibration analytics separately, favoring specialized vendors over integrated OEM service packages and compressing aftermarket margin pools for traditional suppliers.
Wind Turbine Control System Market Segmentation
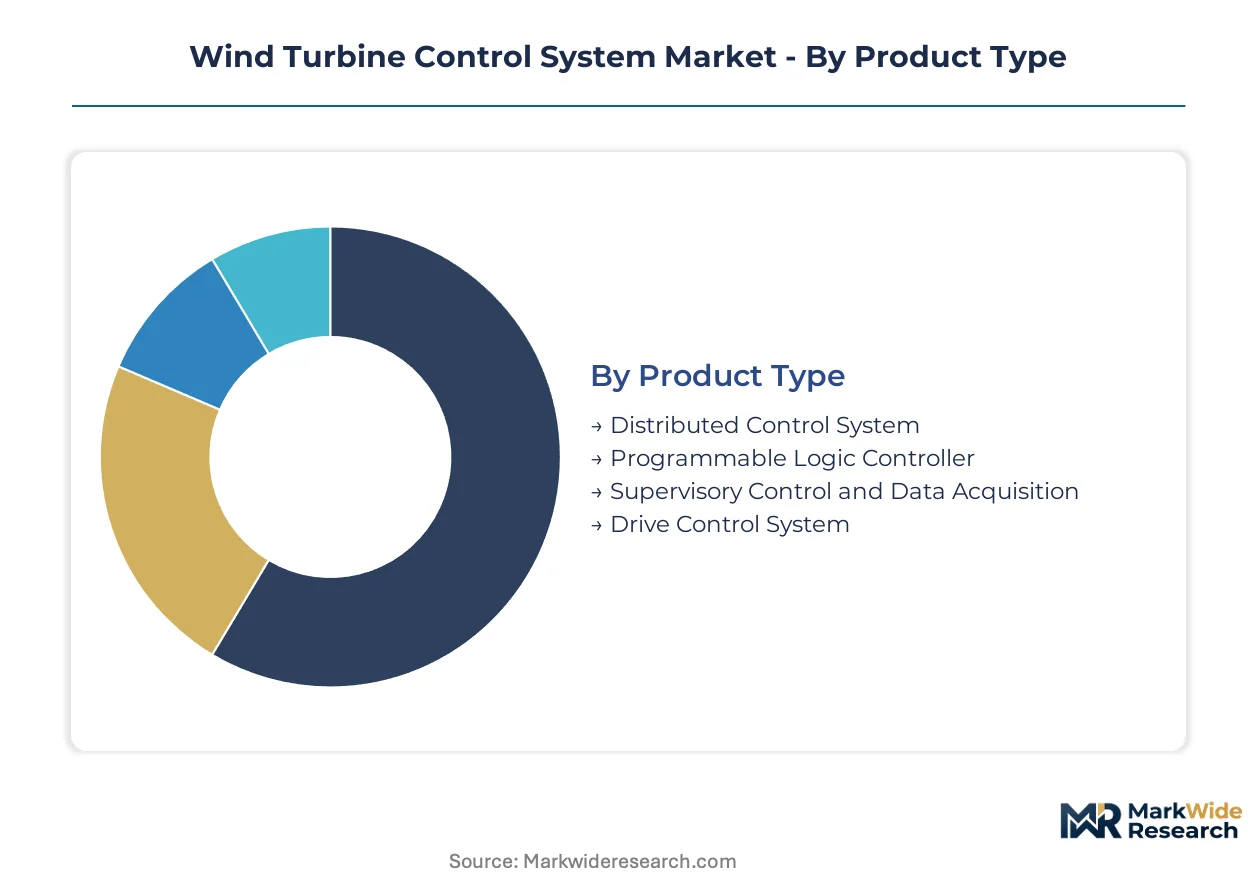
Wind turbine control system procurement varies sharply across installation contexts. Regulatory frameworks in Germany, China, and the United States enforce distinct certification requirements that reshape hardware selection and firmware validation priorities for each segment.
Product Type:
FERC Order 2023 and ENTSO-E grid codes differentiate control system procurement by mandating specific response capabilities that favor certain architectures over others.
- Supervisory Control and Data Acquisition:Centralized platforms aggregate telemetry from hundreds of turbines across offshore arrays, processing nacelle sensor streams through fiber-optic backbones. Chinese developers of multi-hundred-turbine coastal complexes in Jiangsu and Guangdong provinces specify SCADA architectures to satisfy GB/T 25385 fleet-level visibility requirements.
- Programmable Logic Controller:Ruggedized industrial controllers execute millisecond-cycle pitch and torque algorithms in temperature ranges from minus forty to plus seventy degrees Celsius. Cost-sensitive onshore retrofits in Texas and Oklahoma favor PLC configurations for backward compatibility with legacy turbine fleets.
- Distributed Control System:Modular architectures partition control functions across redundant nodes for fault tolerance in large-scale installations.
- Drive Control System:Integrated converter-generator coordination modules manage variable-speed operation across permanent magnet and doubly-fed induction generator topologies.
Supervisory Control and Data Acquisition handles the majority of throughput; Programmable Logic Controller is the fastest mover on share.
Technology:
Margin concentration follows sensor density and data processing intensity rather than raw hardware tonnage.
- Sensor Technology:Nacelle-mounted lidar systems and blade load strain gauges displace legacy anemometer configurations, enabling predictive pitch adjustment before wind shear reaches rotor planes. Offshore installations in the German North Sea and Danish waters mandate redundant sensor arrays to satisfy TSO availability guarantees.
- Power Electronics:Silicon carbide and IGBT converter modules regulate generator torque and grid synchronization, with wide-bandgap semiconductors penetrating high-voltage applications despite cost premiums. Chinese turbine OEMs source neodymium-dependent permanent magnet generators, exposing control system integrators to magnet supply volatility.
- Communication Protocols:IEC 61400-25 standardization drives interoperability investment across SCADA-to-turbine data links.
- Monitoring Systems:Vibration analytics and thermal imaging platforms extend asset life for independent power producers unbundling service contracts from OEM supply agreements.
Sensor Technology commands the steepest expansion trajectory; Monitoring Systems is gaining share fastest among aftermarket procurement.
End User:
Procurement authority fragmentation between turbine builders and asset owners reshapes vendor go-to-market strategies.
- Independent Power Producers:Asset owners in competitive electricity markets prioritize condition monitoring unbundled from OEM service packages, procuring blade load sensing and gearbox analytics separately to compress lifecycle costs. Texas and Oklahoma wind farms lead this procurement pattern.
- OEMs:Turbine manufacturers specify integrated control-to-blade architectures that compress commissioning timelines and warranty exposure. Siemens Gamesa Renewable Energy and Vestas maintain captive control system development to sustain differentiation in offshore tenders.
- Utilities:Vertically integrated power companies favor standardized control platforms across mixed-vintage fleets to simplify operator training and spare parts logistics.
- Service Providers:Third-party maintenance contractors retrofit legacy turbines with upgraded control firmware to capture FERC Order 2023 synthetic inertia upgrade revenue.
Independent Power Producers dominate aftermarket volume; Service Providers is climbing the fastest on share expansion.
Application:
Grid code evolution is redirecting R&D investment from mechanical load management toward electrical grid services.
- Grid Integration:Frequency-watt control curves and synthetic inertia provision now dominate firmware development cycles as ENTSO-E mandates droop response from installations above fifty megawatts. German TSOs impose the most stringent validation protocols, compressing product launch timelines.
- Condition Monitoring:Physics-based digital twins fused with operational sensor streams enable predictive maintenance contracts, shifting vendor revenue toward recurring software subscriptions. Asset owners in competitive markets favor this application to reduce unplanned outage penalties.
- Load Control:Pitch and torque coordination prevents mechanical overload during transient wind events.
- Performance Optimization:Model predictive control algorithms maximize energy capture while respecting structural fatigue limits.
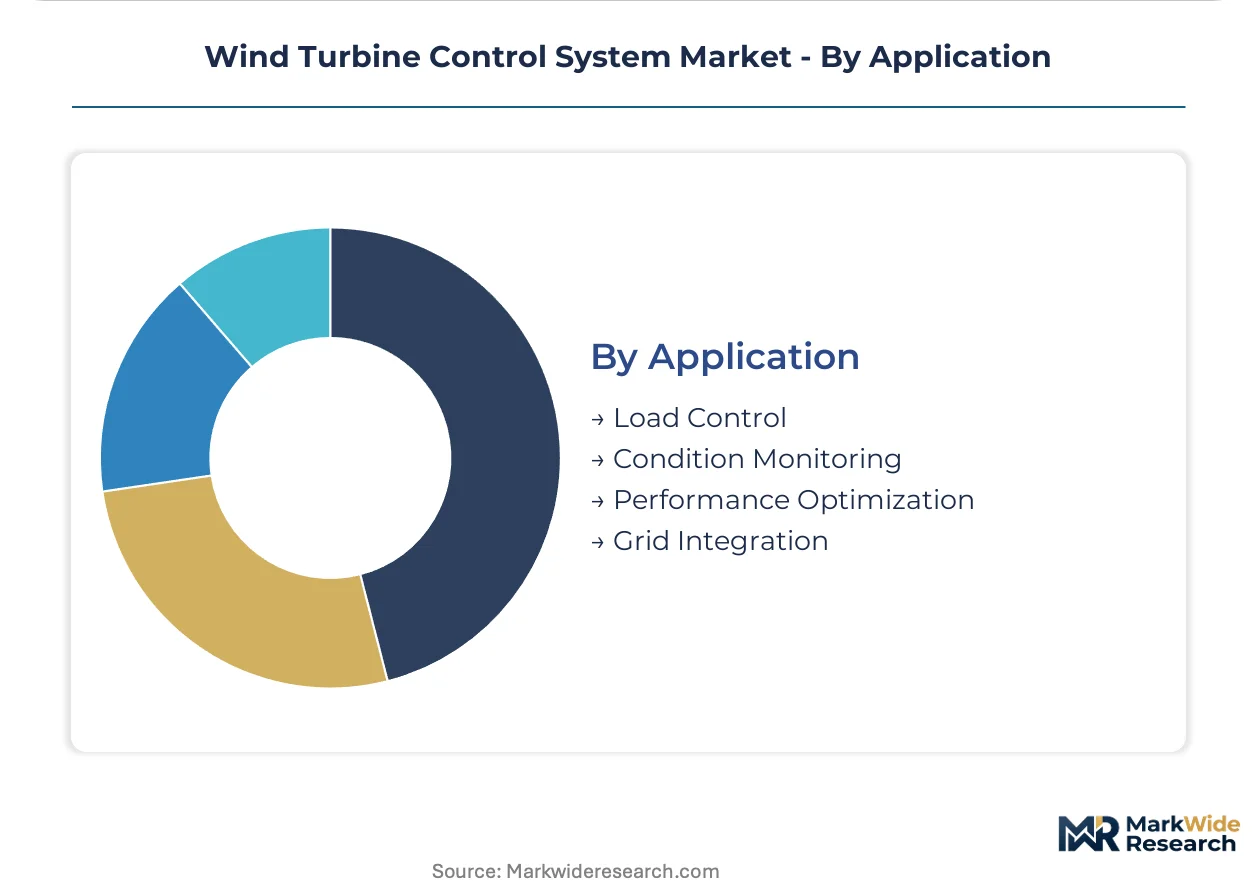
Grid Integration absorbs the majority of current R&D expenditure; Condition Monitoring is expanding most quickly on commercial deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 2023 synthetic inertia mandates and China's GB/T 25385 grid access rules are redirecting procurement toward control architectures capable of sub-second frequency response. National regulatory divergence is fragmenting certification pathways and elevating region-specific firmware development.
United States
Texas and Oklahoma independent power producers are unbundling condition monitoring from OEM service agreements. FERC Order 2023 mandates frequency-watt control curves for new interconnects above 50 MW. The Southwest Power Pool corridor is absorbing the majority of PLC retrofit volume for legacy onshore fleets.
Germany
North Sea offshore arrays are specifying SCADA architectures with redundant sensor arrays to satisfy TSO availability guarantees. ENTSO-E grid code requirements impose the most stringent droop response testing protocols in Europe. The Hamburg and Bremerhaven industrial clusters host converter validation facilities serving Baltic and North Sea developments.
China
Jiangsu and Guangdong coastal provinces are deploying multi-hundred-turbine complexes requiring fleet-level visibility under GB/T 25385. The national standard mandates enhanced fault-ride-through capabilities that force firmware upgrades across the installed base. Yangtze River Delta manufacturing corridors concentrate neodymium-dependent permanent magnet generator supply.
India
Gujarat and Tamil Nadu coastal wind zones are opening underpenetrated offshore licensing rounds. The Central Electricity Authority grid codes require localized firmware for tropical cyclone resilience. The Kutch and Mannar Gulf regions are attracting first-mover turbine control suppliers establishing regional validation partnerships.
United Kingdom
Scottish and North Sea lease rounds are compressing procurement cycles for integrated control-to-blade architectures. The Grid Code Issue 5 revisions align with ENTSO-E synthetic inertia timelines. Aberdeen and Hull port clusters are consolidating offshore control system commissioning and logistics functions.
Wind Turbine Control System Market Vendor Landscape
Player mix skews toward integrated turbine OEMs and specialized industrial automation suppliers with captive power electronics capabilities. Siemens Gamesa Renewable Energy and Vestas Wind Systems anchor the integrated tier through captive control-to-blade development. ABB Ltd. and Emerson Electric Co. occupy the modular supplier tier focused on grid integration and condition monitoring. Competitive moves concentrate on firmware interoperability certification and strategic partnerships with rare earth magnet processors.
Within the integrated OEM tier, Siemens Gamesa Renewable Energy exemplifies architectures that compress commissioning timelines through unified software stacks. Among industrial automation specialists, ABB Ltd. anchors high-voltage converter and grid integration modules across European and Asian portfolios. Emerson Electric Co. sits within the condition monitoring specialization, representing vendors that extend asset life for independent power producers through unbundled service contracts. Rockwell Automation Inc. and Honeywell International Inc. occupy positions in the PLC retrofit segment serving cost-sensitive onshore markets.
| Leading Market Players |
|---|
| Woodward Inc. |
| Siemens Gamesa Renewable Energy |
| ABB Ltd. |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Vestas Wind Systems A/S |
| Compressor Controls Corp. |
| General Electric Co. |
| Others |
Supply Flow & Price Mechanics
Multi-hundred-turbine offshore complexes in Jiangsu and Guangdong provinces achieve steep unit-cost declines through centralized SCADA procurement, compressing supplier margins while elevating firmware interoperability premiums above hardware commoditization floors. This scale concentration permits Chinese developers to extract pricing concessions from control system vendors, even as IEC 61400-25 certification complexity collapses the competitive field and sustains margin pools for compliant incumbents.
Pricing Analysis
Certification level (IEC 61400-25/GB/T 25385/ENTSO-E-grade) creates the primary spread between premium integrated architectures and cost-optimized PLC retrofits. Project-based licensing with recurring firmware maintenance subscriptions dominates offshore arrays, while transactional hardware sales persist in onshore retrofit markets. Price differentiation hinges on grid-code validation breadth and synthetic inertia capability depth, with margins tightening in the PLC segment due to backward-compatibility engineering burdens. Independent power producers in Texas and Oklahoma exhibit highest price sensitivity, whereas German North Sea developers prioritize availability guarantees over unit cost.
Supply Chain Analysis
China and Germany anchor permanent magnet generator and high-voltage converter manufacturing respectively, with Taiwan and Japan supplying silicon carbide wafer substrates for next-generation power electronics. Neodymium magnet processing draws from Chinese Yangtze River Delta corridors, while IGBT and wide-bandgap semiconductor assembly rests on European and East Asian fabrication networks. Single-source vulnerability concentrates in rare earth magnet supply, exposing control system integrators to geopolitical sourcing disruption. Distribution runs through turbine OEM captive channels for new installations, with aftermarket spares flowing via independent service providers and regional validation partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wind turbine control systems are approaching a platform-economics inflection as IEC 61400-25 standardization forces interoperability convergence across SCADA-to-power-electronics stacks, rewarding vendors who capture firmware layer network effects before hardware commoditization accelerates.
For Market Incumbents: Consolidate certification investment across multi-jurisdiction grid codes to defend against modular specialists fragmenting the aftermarket. Deepen captive converter development in Hamburg and Bremerhaven industrial clusters to secure German North Sea availability-guarantee contracts. Acquire lidar sensor technology capabilities to offset unbundling pressure from independent power producers procuring condition monitoring separately from OEM service packages. For New Entrants and Emerging Players: Firmware localization gaps for tropical cyclone resilience in Indian coastal zones present first-mover positioning opportunities before CEA grid code standardization hardens. Target predictive maintenance software subscriptions for Texas and Oklahoma independent power producers seeking to compress lifecycle costs outside integrated OEM agreements. Pursue strategic partnerships with rare earth magnet processors to mitigate supply concentration risk and differentiate grid-integration module offerings. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors condition monitoring specialists with physics-based digital twin capabilities that shift revenue toward recurring software streams. Long-term viability hinges on synthetic inertia firmware roadmaps aligned with FERC Order 2023 and ENTSO-E mandate timelines. Acquisition target archetypes include edge-computing node developers and blade load sensing analytics platforms. Watch for GB/T 25385 harmonization signals with international standards as inflection indicator for centralized versus region-specific product strategy winners.| Strategic Initiative | Industry Significance |
|---|---|
| Grid Code Certification Expansion | Multi-jurisdiction IEC 61400-25 validation opens German, Chinese, and US procurement channels simultaneously. |
| Edge Computing Node Development | Localized sensor processing reduces blade load response latency while enabling centralized fleet analytics. |
| Predictive Maintenance Platform Launch | Physics-based digital twins shift vendor revenue from hardware sales to recurring software subscriptions. |
| Rare Earth Magnet Supply Partnership | Upstream magnet processing agreements mitigate neodymium concentration risk in permanent generator architectures. |
| Condition Monitoring Service Unbundling | Independent blade load and gearbox analytics contracts capture aftermarket volume from traditional OEM service packages. |
Methodological Framework
The analysis maps Supervisory Control and Data Acquisition platforms, Programmable Logic Controller architectures, sensor technology modules, and power electronics components, each validated through control systems engineers, offshore project developers, grid operators, and independent power producer asset managers. Primary fieldwork combined structured interviews with firmware development leads at turbine OEMs and procurement officers at European and Asian wind farm operators. Secondary validation drew from FERC filings, ENTSO-E grid code documentation, GB/T standard registries, and IEC certification databases. Bottom-up installation forecasts triangulated against top-down market sizing across technology and end-user segments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, technology intensity, end-user procurement authority, and application function dimensions throughout the forecast period. CAGRs derived from segmented growth trajectory analysis incorporating regulatory mandate timelines, turbine installation pipelines, and grid code evolution patterns. Forecast inputs included fault-ride-through requirement phase-ins, synthetic inertia capability deployment curves, and lidar sensor penetration rates by installation context.
Material uncertainties — regulatory harmonization failures, rare earth supply disruptions, and wide-bandgap semiconductor cost barriers — sit outside the modeled envelope. Forecasts reflect assumptions regarding grid code implementation schedules and technology substitution elasticities. Recalibration cycles align with material shifts in national renewable energy targets and offshore leasing round announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Small Wind Turbine Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
United States Wind Energy Market
Wind Energy Systems
India Wind Energy Market
Wind Energy Systems
Ireland Wind Energy Market
Wind Energy Systems
Europe Wind Power Market