
 Wind Tunnel Fans Market | 2026-2036
Wind Tunnel Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Tunnel Fans Market Insights
REACH compliance is hardening material and coating specifications for wind tunnel fan blades across European supply chains. Chicago Blower leverages its foundry integration to control casting quality for large-diameter impellers. New York Blower sustains competitive positioning through dedicated aerospace testing channel relationships. Greenheck Fan anchors its portfolio with heavy-gauge industrial fan architectures that transfer into high-load wind tunnel configurations.
Wind tunnel fans are precision-engineered turbomachines designed to generate controlled, uniform airflow at calibrated velocities ranging from subsonic to transonic conditions for aerodynamic validation. Axial fans dominate aerospace testing installations where straight-through airflow and high volume throughput matter most, while centrifugal fans occupy architectural and environmental simulation segments requiring pressure head against duct resistance. Belt drive technology retains substantial installed base in legacy facilities, though brushless DC and variable frequency drive architectures are capturing replacement cycles where energy recovery and speed modulation justify capital outlay.
The FAA's airworthiness certification standards and EASA's CS-25 requirements directly shape wind tunnel fidelity specifications that fan systems must support. China's GB standards for aerodynamic test equipment and the MIIT's equipment localization directives are redirecting procurement toward domestic-qualified suppliers. Stakeholders must weigh retrofit timing against emerging synchronous motor and direct drive platforms that promise operating cost reductions but demand upfront validation investment.
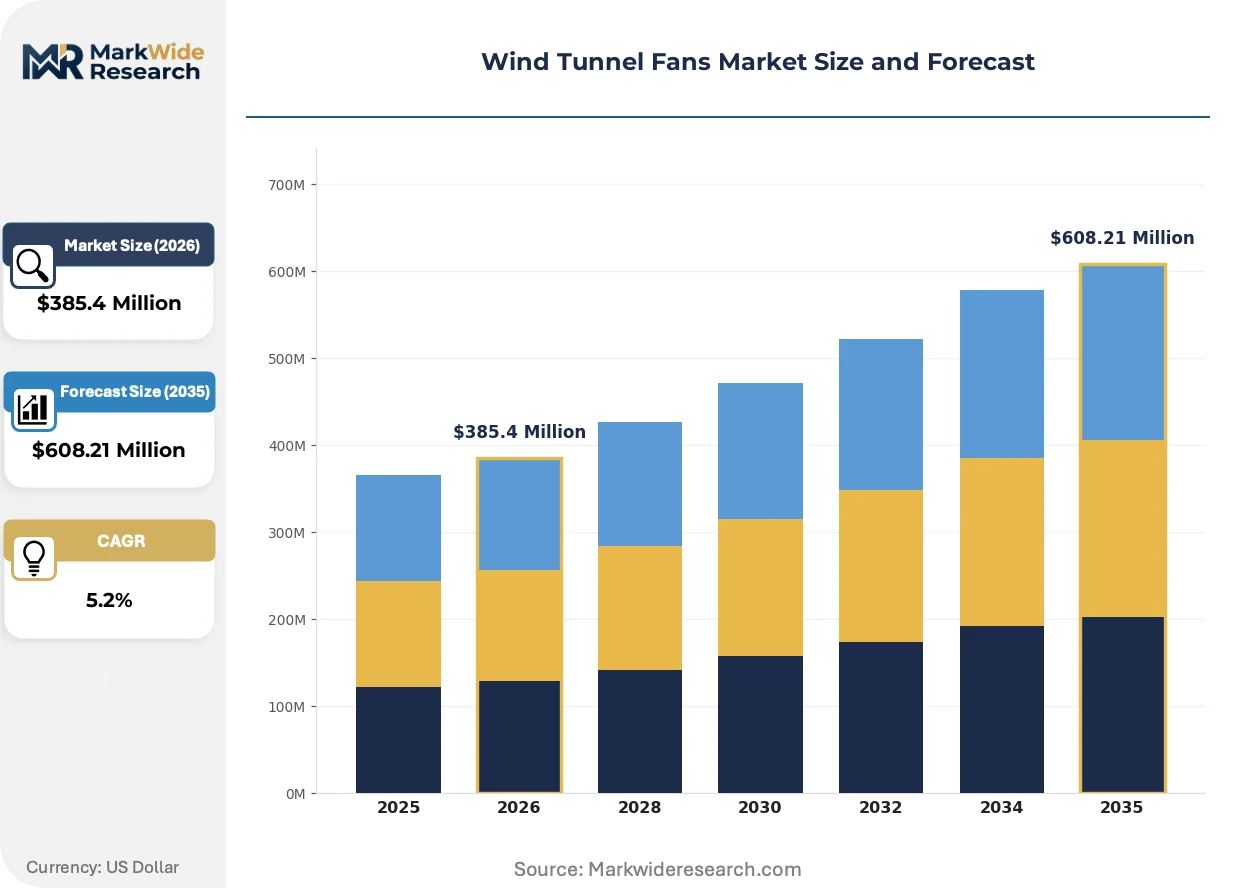
Market Dynamics
Variable frequency drive architectures are compressing replacement cycles across legacy wind tunnel installations as energy recovery economics justify capital redeployment. Aerospace testing facilities face simultaneous pressure from FAA airworthiness mandates and EASA CS-25 fidelity requirements that demand higher-precision airflow control.
Growth Catalysts
- FAA Certification Standards:Tightened airworthiness requirements for next-generation aircraft validation are mandating higher-fidelity test equipment across US aerospace facilities.
- China Civil Aviation Programs:Expansion of national wind tunnel networks for military and commercial aircraft development is concentrating procurement demand in domestic-qualified supplier channels.
- Brushless DC Motor Adoption:Speed modulation capabilities and energy recovery performance are displacing belt drive architectures in facility retrofit programs.
Market Restraints
- Specialized Alloy Input Costs:Nickel-based superalloy price volatility constrains large-diameter impeller casting economics for European foundries.
- MIIT Localization Directives:China's equipment procurement rules are redirecting demand toward domestic suppliers, creating access friction for foreign manufacturers.
- Centrifugal Fan Substitution:Architectural and environmental simulation segments increasingly favor pressure-head configurations over axial architectures for ducted applications.
Strategic Opportunities
- India Aerospace Testing Infrastructure:Underdeveloped wind tunnel capacity for indigenous aircraft programs presents white space for equipment suppliers meeting CEA electrical standards.
- Synchronous Motor Convergence:Integration of permanent magnet synchronous motors with direct drive platforms enables operating cost reductions in high-duty-cycle installations.
- EU Green Deal Incentives:Energy efficiency refurbishment grants for industrial equipment are accelerating replacement demand in German and French testing facilities.
Industry Challenges
- Aerodynamicist Talent Scarcity:Specialized computational fluid dynamics expertise required for fan blade design outpaces university pipeline output in Western Europe.
- Validation Timeline Compression:Extended certification cycles for new drive architectures delay revenue recognition against facility upgrade schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Tunnel Fans Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Mixed Flow Fans, Crossflow Fans, Vortex Fans Technology: Variable Frequency Drive, Direct Drive, Belt Drive, Brushless DC, Synchronous Motor Application: Aerospace Testing, Automotive Aerodynamics, Architectural Design, Sports Engineering, Environmental Simulation End User: Research Laboratories, Vehicle Manufacturers, Civil Engineering Firms, Sports Test Centers, Government Agencies |
| Companies Covered | System Fan Works, Chicago Blower, New York Blower, Roberts-Gordon, AirPro Fan, Twin City Fan, Greenheck Fan, Cincinnati Fan, Howden, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Tunnel Fans Market Trends and Innovations
Active magnetic bearing technology is reshaping large-diameter fan architectures by eliminating mechanical contact losses. Three distinct vectors are redirecting capital deployment and supplier positioning across the sector.
Permanent magnet synchronous motor systems are expanding into transonic wind tunnel applications where precise speed control and reduced maintenance intervals justify premium positioning. Major aerospace testing facilities in Germany and the United States are retrofitting legacy belt drive installations with these architectures. The technology is expanding into configurations previously reserved for mechanical bearing systems, compressing total cost of ownership calculations for facility operators.
REACH compliance protocols are hardening coating specifications for fan blade surfaces exposed to high-velocity particulate erosion. European supply chains must now validate chromium-free alternatives for corrosion protection. Aerospace testing segments in France and the Netherlands are absorbing qualification costs fastest, with coating suppliers accelerating R&D timelines to maintain specification compliance.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into component-level subscription arrangements. Wind tunnel operators in China and the United States are separating predictive analytics, spare parts logistics, and field service into discrete procurement decisions. This pattern is most visible among commercial aircraft manufacturers operating captive testing facilities, where internal maintenance capabilities reduce reliance on OEM service packages.
Wind Tunnel Fans Market Segmentation
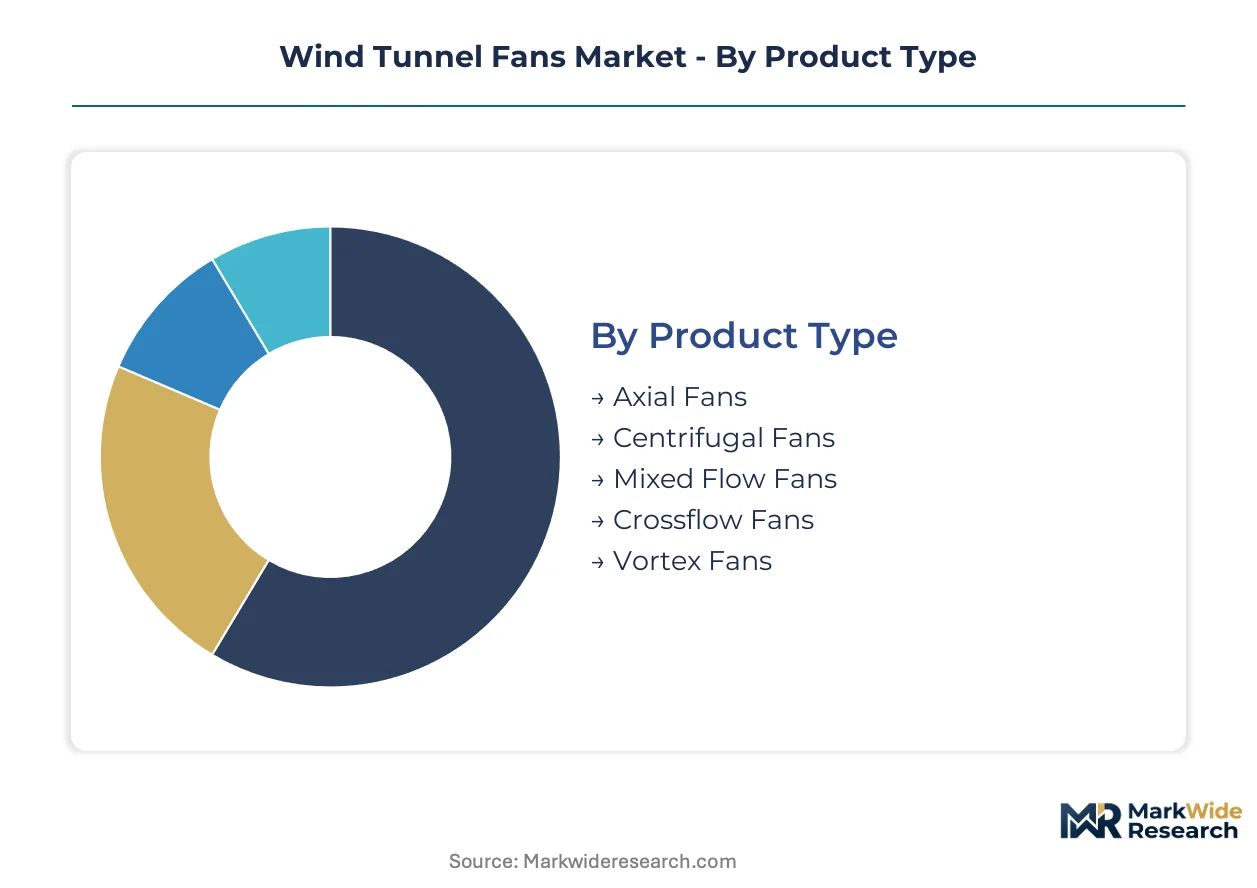
Wind tunnel fan procurement patterns diverge sharply between high-volume aerospace installations and specialized architectural or environmental applications. Understanding these segment boundaries clarifies where technology investments concentrate and which customer types drive specification upgrades.
Product Type:
Axial fans dominate volume installations where straight-through airflow and maximum throughput justify the premium, while centrifugal configurations capture pressure-critical niches.
- Axial Fans:These turbomachines generate airflow parallel to the impeller axis, optimized for subsonic through transonic velocity ranges with minimal duct resistance. Demand concentrates in aerospace testing facilities across the United States, Germany, and China where FAA and EASA certification mandates require high-fidelity velocity control.
- Centrifugal Fans:Radial blade configurations deliver pressure head against significant system resistance, making them essential for ducted architectural and environmental simulation installations. European REACH compliance protocols are hardening material specifications for blade alloys and coatings in these pressure-intensive designs.
- Mixed Flow Fans:Hybrid architectures combining axial throughput with centrifugal pressure characteristics serve medium-duty automotive aerodynamics installations.
- Crossflow Fans:Tangential flow designs provide uniform velocity profiles for compact architectural wind load testing.
- Vortex Fans:Specialized swirling flow generators occupy niche sports engineering applications requiring controlled turbulence injection.
Today's leader: Axial Fans. Tomorrow's challenger: Centrifugal Fans.
Technology:
Drive architecture selection determines energy recovery potential and maintenance burden across facility lifecycle economics.
- Variable Frequency Drive:Electronic speed control enables precise airflow modulation across test regimes while capturing regenerative braking energy. German and French testing facilities are retrofitting legacy installations with VFD architectures under EU Green Deal refurbishment incentives.
- Brushless DC:Permanent magnet motor systems eliminate commutator maintenance and deliver superior speed control precision for transonic applications. China's MIIT localization directives are accelerating domestic supplier qualification for these high-efficiency drive platforms.
- Direct Drive:Coupled motor-impeller configurations reduce mechanical losses and bearing maintenance in continuous-duty aerospace installations.
- Synchronous Motor:Precision speed holding and power factor correction benefits are displacing induction alternatives in high-fidelity test cells.
- Belt Drive:Mechanical speed reduction retains substantial installed base in legacy facilities where capital constraints delay full drive replacement.
Brushless DC is climbing the fastest as efficiency mandates tighten. Belt Drive retains the largest installed base awaiting replacement cycles.
Application:
End-use requirements span from military-grade certification fidelity to commercial building code compliance.
- Aerospace Testing:Military and commercial aircraft validation demands calibrated velocity uniformity within strict tolerances for FAA airworthiness certification. China's expanding national wind tunnel network for civil and military aviation programs concentrates procurement in this segment.
- Automotive Aerodynamics:Drag coefficient optimization and thermal management testing for electric vehicle platforms are expanding capacity requirements in Germany and the United States.
- Architectural Design:Wind load and pedestrian comfort studies for high-rise construction utilize scaled environmental simulation tunnels.
- Sports Engineering:Cycling, skiing, and equipment aerodynamics testing serves professional and Olympic training facilities.
- Environmental Simulation:Pollutant dispersion and urban microclimate studies employ specialized boundary layer wind tunnels.
Aerospace Testing commands the premium tier. Automotive Aerodynamics is expanding most quickly on electrification investment.
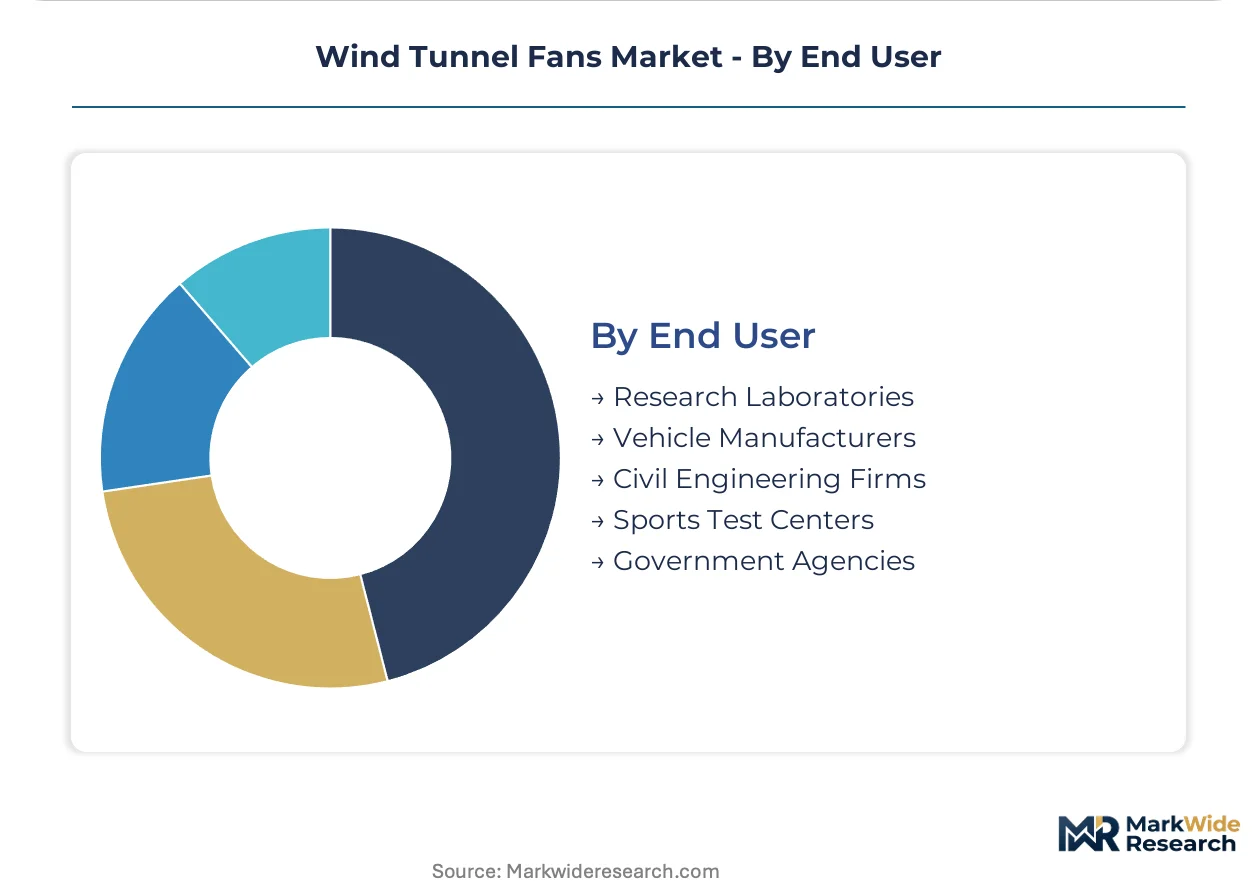
End User:
Customer type determines procurement sophistication, from integrated captive facilities to outsourced testing services.
- Research Laboratories:University and national laboratory installations prioritize measurement precision and multi-decade operational lifecycles over first cost. Facilities in the Netherlands and France are absorbing REACH compliance qualification costs for advanced coating specifications fastest.
- Vehicle Manufacturers:Captive aerospace and automotive testing centers at Boeing, Airbus, and major automakers drive specification-setting for the broader market.
- Civil Engineering Firms:Architectural wind consulting practices purchase simulation capacity for structural design validation.
- Sports Test Centers:Specialized facilities serving professional athletes and equipment manufacturers occupy a fragmented service layer.
- Government Agencies:Military and civil aviation authorities operate certification tunnels with procurement directed by national security and industrial policy considerations.
Research Laboratories anchor technology adoption. Vehicle Manufacturers control volume procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized aerodynamicist talent pools anchor wind tunnel fan demand in Germany, the United States, and China, where aerospace testing infrastructure concentrates around university research corridors and national laboratory networks.
United States
FAA airworthiness certification mandates and next-generation aircraft validation programs drive facility expansion across NASA centers and commercial aerospace campuses. The FAA's tightened CS-25 alignment requirements pressure testing centers toward higher-fidelity equipment upgrades. Boeing's captive facilities in Washington State and Airbus engineering centers in Alabama concentrate procurement decisions for axial fan architectures.
Germany
Automotive electrification and thermal management testing for electric vehicle platforms expand capacity requirements at OEM research campuses. EU Green Deal refurbishment incentives accelerate VFD retrofit cycles in legacy facilities. The Cologne-Düsseldorf corridor hosts concentrated aerospace testing infrastructure serving both commercial certification and motorsport aerodynamics segments.
China
Civil and military aviation program expansion concentrates procurement through MIIT localization directives redirecting demand toward domestic-qualified suppliers. GB standards for aerodynamic test equipment harden specification requirements. The national wind tunnel network expansion centers on Beijing and Xi'an research clusters supporting COMAC and military aircraft development.
France
REACH compliance protocols harden coating specifications for fan blade surfaces exposed to high-velocity particulate erosion. EASA CS-25 fidelity requirements shape testing center equipment decisions. The Toulouse aerospace cluster absorbs qualification costs fastest, with coating suppliers accelerating R&D timelines for chromium-free corrosion protection alternatives.
United Kingdom
Research laboratory installations at Cranfield and Imperial College prioritize measurement precision and multi-decade operational lifecycles over first cost. Defense procurement through the Ministry of Defence sustains military testing tunnel operations. The Oxford-Cambridge arc concentrates aerodynamicist talent pipelines for fan blade design expertise.
Wind Tunnel Fans Market Competitive Landscape
The competitive structure tilts toward diversified industrial fan manufacturers with aerospace channel relationships. Mid-scale specialists and diversified industrial conglomerates occupy distinct tiers, with technology licensing and strategic partnerships dominating competitive moves rather than capacity expansion.
Among North American fabricators, Chicago Blower, New York Blower, and Greenheck Fan occupy positions across the industrial-to-aerospace spectrum. Chicago Blower represents foundry-integrated casting quality control for large-diameter impellers. New York Blower exemplifies dedicated aerospace testing channel relationships. Greenheck Fan anchors heavy-gauge industrial architectures that transfer into high-load wind tunnel configurations.
| Leading Market Players |
|---|
| System Fan Works |
| Chicago Blower |
| New York Blower |
| Roberts-Gordon |
| AirPro Fan |
| Twin City Fan |
| Greenheck Fan |
| Cincinnati Fan |
| Howden |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor adoption is simultaneously compressing maintenance cost structures and concentrating procurement leverage among aerospace testing facilities with capital for full drive replacement. This technology transition reshapes supplier economics as legacy belt drive manufacturers face margin pressure from synchronous motor platforms that command premium positioning through energy recovery performance.
Pricing Analysis
The bundled-vs-unbundled service split is fragmenting traditional maintenance contracts into discrete procurement decisions. Three-tier pricing structure across premium, standard, and economy levels separates active magnetic bearing configurations from conventional mechanical systems and legacy belt drive retrofits. Pricing pressure stems from REACH compliance qualification costs for chromium-free blade coatings. Research laboratories exhibit lowest price sensitivity due to multi-decade lifecycle planning, while civil engineering firms face acute budget constraints on architectural simulation equipment.
Supply Chain Analysis
Single-source vulnerability sits with nickel-based superalloy foundries in Germany and the United States that control large-diameter impeller casting capacity. Raw material dependencies center on cobalt-chromium alloys, rare-earth permanent magnets, and specialized epoxy coating systems. Supply chain risk concentrates in tariff exposure on Chinese-sourced permanent magnet materials. Distribution runs through direct OEM relationships with aerospace testing facilities and national laboratory procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wind Tunnel Fans Market reads as a late-cycle quality story where FAA and EASA fidelity mandates are concentrating procurement toward premium axial fan architectures with active magnetic bearing technology.
For Market Incumbents: To counter domestic supplier qualification under China's MIIT localization directives, anchor market position through foundry-integrated casting control for superalloy impellers and accelerate REACH-compliant coating R&D partnerships with European aerospace clusters. Channel control through dedicated aftermarket service subscriptions preserves pricing power against unbundling pressures. For New Entrants and Emerging Players: Aerospace testing channel partners in India present the most penetrable white space, where CEA electrical standard compliance and underdeveloped wind tunnel infrastructure create first-mover advantages. Target automotive electrification testing facilities in Germany with permanent magnet synchronous motor platforms optimized for thermal management validation. A certification-first go-to-market angle accelerates trust-building with research laboratories. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale specialists with foundry integration and established EASA channel relationships. Long-term viability over the next decade hinges on synchronous motor platform adoption rates and energy efficiency refurbishment grant capture in EU markets. Watch for inflection when India's CEA publishes finalized aerodynamic test equipment electrical standards.| Strategic Initiative | Industry Significance |
|---|---|
| Active Magnetic Bearing Platform Launch | Eliminates mechanical contact losses for transonic testing facilities in Germany and the United States. |
| REACH-Compliant Coating R&D Partnership | Accelerates chromium-free qualification timelines for French and Dutch aerospace testing segments. |
| India Market Entry with CEA Certification | Captures white space in indigenous aircraft program infrastructure before domestic supplier consolidation. |
| Aftermarket Service Unbundling | Fragments bundled maintenance into predictive analytics and spare parts subscription tiers for captive OEM facilities. |
| Permanent Magnet Supply Agreement | Secures rare-earth material access against tariff exposure and MIIT localization procurement rules. |
Research Methodology
Direct dialogue with wind tunnel facility directors, aerospace procurement managers, foundry operations heads, and aftermarket service directors grounded qualitative findings. Secondary validation drew from FAA airworthiness certification databases, EASA CS-25 technical documentation, Chinese MIIT equipment localization directives, and EU Green Deal refurbishment incentive records. Bottom-up and top-down triangulation cross-checked installation counts against capital expenditure disclosures from NASA centers and COMAC research clusters.
Bottom-up modeling segmented demand across axial, centrifugal, and mixed flow architectures by drive technology type and end-user category. The projection horizon incorporated aerospace testing, automotive aerodynamics, and architectural simulation applications with permanent magnet motor adoption curves and energy efficiency retrofit cycles as primary forecast inputs. CAGRs emerged from facility expansion timelines and replacement cycle compression analysis.
Revisions become necessary when nickel-based superalloy price volatility exceeds historical bands, when India's CEA finalizes aerodynamic test equipment standards, or when China's MIIT expands localization directives to additional component categories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
Turbomachinery Control Systems, Retrofitting, and Ancillary Services Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
SCR Power Controller Market
Power Equipment
Process Plants Gas Turbine Market
Power Equipment
Global Power System Simulator Market
Power Equipment
Wind Power Fastener Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Power Recovery Winches Market
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
Germany Power EPC Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Deaerators Market
Power Equipment
Power Generation Equipment MRO Market