
 Pipeline Pigging Valves Market | 2026-2036
Pipeline Pigging Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Pigging Valves Market Analytics
Multi-source procurement for critical pipeline isolation equipment is hardening as operators reduce dependency on single OEM relationships. Jag Valves leverages its specialization in severe-service ball valve configurations for sour gas environments. Hartmann Valves GmbH anchors its position through German-engineered metal-seated designs that sustain high-cycle pigging operations. Tiger Valve Company competes on rapid custom engineering turnaround for midstream infrastructure projects.
Pipeline pigging valves are mechanical isolation devices engineered to full-bore or reduced-bore specifications, typically rated for ANSI Class 150 through 2500 pressure boundaries, designed to launch, receive, or bypass pipeline inspection and cleaning pigs without flow interruption. Their primary purpose is to enable inline maintenance, corrosion monitoring, and debris removal while maintaining system pressure containment. Ball valve configurations dominate capital procurement for crude oil and natural gas transmission lines due to bidirectional sealing reliability and piggable bore consistency. Stainless steel material grades command premium positioning in corrosive service applications, particularly offshore and chemical processing environments where chloride-induced pitting resistance determines asset life. The energy sector end-user category absorbs the largest share of replacement demand as aging North American pipeline networks require systematic valve upgrade cycles.
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration enforces valve integrity standards through 49 CFR Part 195, mandating periodic proof testing and material traceability for hazardous liquid lines. API 6D and ISO 14313 specifications define design validation protocols that gate market access for manufacturers serving international oil company procurement frameworks. Stakeholders must monitor evolving methane emission regulations and digital valve positioner integration requirements as pipeline operators recalibrate maintenance strategies toward predictive rather than calendar-based intervention models.
Market Dynamics
Pipeline pigging valve procurement is hardening around multi-source supplier strategies as operators reduce single-OEM dependency risks for critical isolation equipment. API 6D and ISO 14313 certification tightening is compressing qualification timelines for new entrants while elevating compliance costs for established manufacturers.
Growth Catalysts
- Integrity Management Mandates:PHMSA enforcement of 49 CFR Part 195 proof testing requirements is accelerating replacement cycles across aging North American hazardous liquid networks.
- Sour Gas Development:Hydrogen sulfide-resistant metal-seated configurations see heightened specification for Middle Eastern and Caspian Basin production infrastructure.
- Offshore Expansion:Brazil and West Africa subsea trunk line construction is driving demand for super-duplex stainless steel valve specifications rated to 2500 ANSI Class.
Market Restraints
- Alloy Cost Volatility:Nickel and molybdenum price swings directly compress margin structures for super-austenitic and duplex stainless steel casting producers.
- Foundry Concentration:Specialized large-bore valve body forging capacity concentrates in Germany, Italy, and Japan, creating geographic supply vulnerability.
- Technical Sealing Limits:Metal-to-metal seat designs face cycle-life constraints above 10,000 operations in abrasive crude service, limiting full substitution of resilient-seated alternatives.
Strategic Opportunities
- Digital Positioner Integration:Predictive maintenance architectures using valve-mounted sensors create aftermarket service attachment opportunities.
- Hydrogen Infrastructure:Repurposed natural gas pipelines for hydrogen transport require revised material compatibility standards and sealing technology qualification.
- India Midstream Buildout:Reliance Industries and GAIL trunk line expansion programs specify API 6D pigging valves for cross-country crude and product distribution networks.
Industry Challenges
- Welding Inspector Scarcity:ASME Section IX-qualified welders for high-pressure valve fabrication face acute shortage across North American and European supply bases.
- Legacy System Integration:Retrofitting digital positioners onto mechanical valve assemblies in brownfield installations demands custom engineering and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Pigging Valves Market |
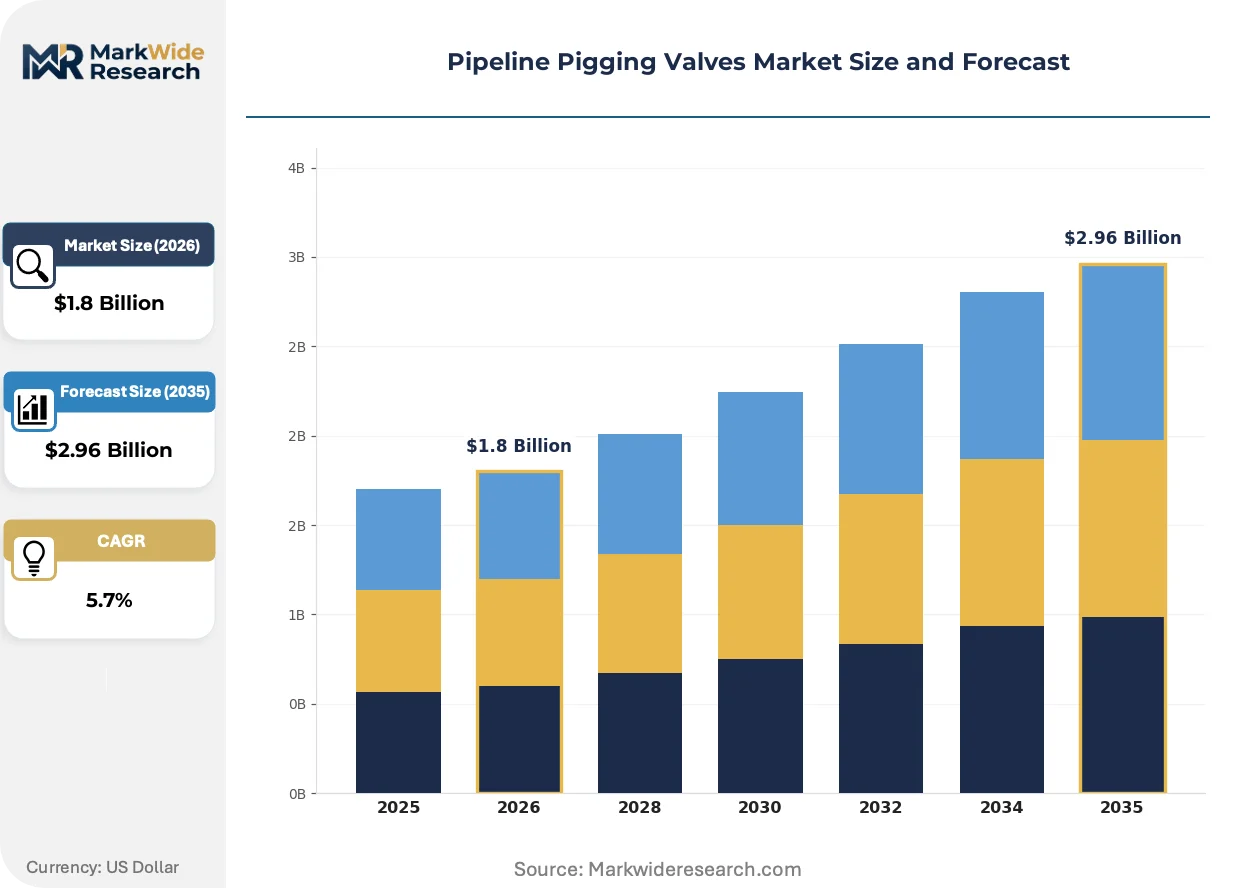
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Valve Type: Ball Valve, Gate Valve, Check Valve, Butterfly Valve Material: Steel, Plastic, Brass, Stainless Steel Application: Oil & Gas, Water Treatment, Chemical Processing, HVAC End User: Energy Sector, Manufacturing, Utilities, Municipalities |
| Companies Covered | Jag Valves, Hartmann Valves GmbH, Tiger Valve Company, Master Flo Valve Inc., Argus Machine Co. Ltd., Frontier Valve International, Sofis Valve Operation, CGIS, PBM Valve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Pigging Valves Market Evolving Landscape
Electrification of valve actuation and control architectures is compressing maintenance intervals while enabling remote pipeline isolation capabilities. Material science advances in hard-facing alloys and additive manufacturing are reshaping component sourcing strategies.
Electro-hydraulic actuation for pigging valve automation is electrifying field operations by eliminating pneumatic supply infrastructure and enabling precise stroke control. Offshore platform operators in the Gulf of Mexico and North Sea are specifying all-electric valve packages for subsea tieback projects. This architecture is electrifying competitive positioning by favoring suppliers with integrated electrical engineering capabilities over pure mechanical valve manufacturers.
The EU Methane Regulation's 2024 implementation timeline mandates leak detection and repair protocols for oil and gas transmission infrastructure. Valve packing emissions monitoring becomes a compliance checkpoint, driving specification of low-emission stem seal designs. European transmission system operators are accelerating procurement of ISO 15848-1 certified fugitive emission valves ahead of enforcement deadlines.
Integrated valve-and-automation packages are displacing discrete component sourcing as midstream operators consolidate vendor accountability. Engineering-procurement-construction firms now specify turnkey pigging valve skids with pre-commissioned positioners and control logic. This bundling pattern is most pronounced in Permian Basin gathering system projects where speed-to-production dictates simplified supply chain interfaces.
Pipeline Pigging Valves Market Segmentation
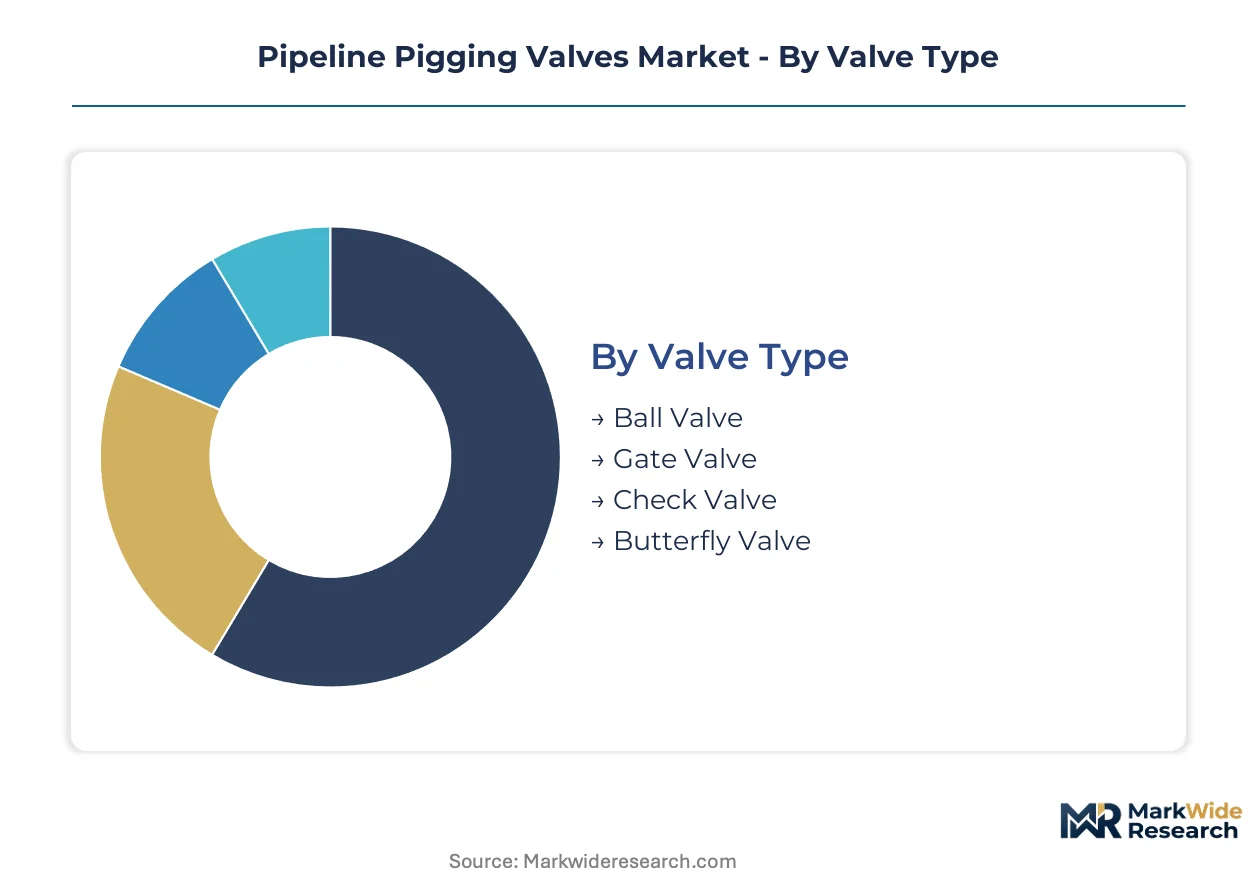
Pipeline pigging valve segmentation reveals how specification choices cascade through procurement decisions. Material selection and valve configuration determine pressure rating compatibility, maintenance intervals, and total lifecycle cost across transmission infrastructure.
Valve Type:
Pressure containment geometry and sealing mechanism architecture differentiate procurement specifications across transmission networks.
- Ball Valve:Full-bore spherical closure elements deliver bidirectional sealing with consistent piggable internal diameter. Crude oil trunk lines in the Permian Basin and Saudi Arabia's Master Gas System specify API 6D ball valves for high-cycle pigging operations where flow interruption is economically prohibitive.
- Gate Valve:Linear-motion wedge or slab gate designs provide straight-through flow with minimal pressure drop when fully open. Water treatment facilities and municipal distribution networks favor gate valves for isolation service where pigging frequency remains low and cost sensitivity dominates specification.
- Check Valve:Automatic backflow prevention through swing, piston, or dual-plate configurations protects pump stations and compressor facilities. Midstream operators deploy check valves in pig launcher and receiver bypass loops to prevent reverse flow during isolation sequences.
- Butterfly Valve:Quarter-turn disc operation enables compact axial installation with reduced weight compared to flanged alternatives. HVAC and secondary chemical processing circuits specify resilient-seated butterfly valves for moderate-pressure pigging where space constraints override sealing performance priorities.
Ball valves lead on scale across hydrocarbon transmission; check valves gain momentum in automated safety system integration.
Material:
Corrosion resistance and mechanical strength requirements drive foundry selection and forging source decisions.
- Steel:Carbon and low-alloy castings dominate large-bore transmission valve bodies through cost-effective pressure containment. Standard crude oil gathering systems specify ASTM A216 WCC steel for ANSI Class 600 and below where hydrogen sulfide exposure remains minimal.
- Stainless Steel:Austenitic and duplex grades deliver chloride pitting resistance for offshore and sour gas environments. Super-duplex 2507 specifications anchor subsea pigging valve procurement for Brazil's pre-salt developments and West Africa trunk line tiebacks.
- Plastic:Thermoplastic and thermoset polymer constructions eliminate galvanic corrosion in chemical processing and demineralized water service. Polyvinylidene fluoride and reinforced epoxy valves serve low-pressure pigging loops where metallic contamination must be excluded.
- Brass:Copper-zinc alloy castings provide machinability and moderate corrosion resistance for instrumentation and small-bore utility pigging. Brass valve specifications concentrate in HVAC and potable water applications where lead-free compliance and soldering compatibility matter.
Steel leads on installed volume across onshore transmission; stainless steel climbs fastest on offshore project specifications.
Application:
Process fluid characteristics and regulatory exposure shape material qualification and certification requirements.
- Oil & Gas:Hydrocarbon transmission, gathering, and storage infrastructure demands API 6D and ISO 14313 certification with full material traceability. PHMSA 49 CFR Part 195 mandates drive replacement cycles across US hazardous liquid networks exceeding thirty years of service.
- Chemical Processing:Aggressive media compatibility requires alloy selection per NACE MR0175/ISO 15156 sour service limits. Chlor-alkali and sulfuric acid handling facilities specify tantalum-lined or Hastelloy valve trims for pigging operations in corrosive slurry service.
- Water Treatment:Potable and wastewater infrastructure prioritizes NSF/ANSI 61 certification and low-lead material compliance. Desalination plants specify super-austenitic stainless steel for seawater intake pigging valves exposed to continuous chloride attack.
- HVAC:Heating, ventilation, and air conditioning systems specify bronze or cast iron valves for chilled water and steam distribution pigging. Building automation integration drives demand for compact actuated packages with BACnet communication protocols.
Oil and gas leads on capital deployment; water treatment expands most quickly on infrastructure rehabilitation programs.
End User:
Asset ownership structure and maintenance capability determine procurement channel and service bundling preferences.
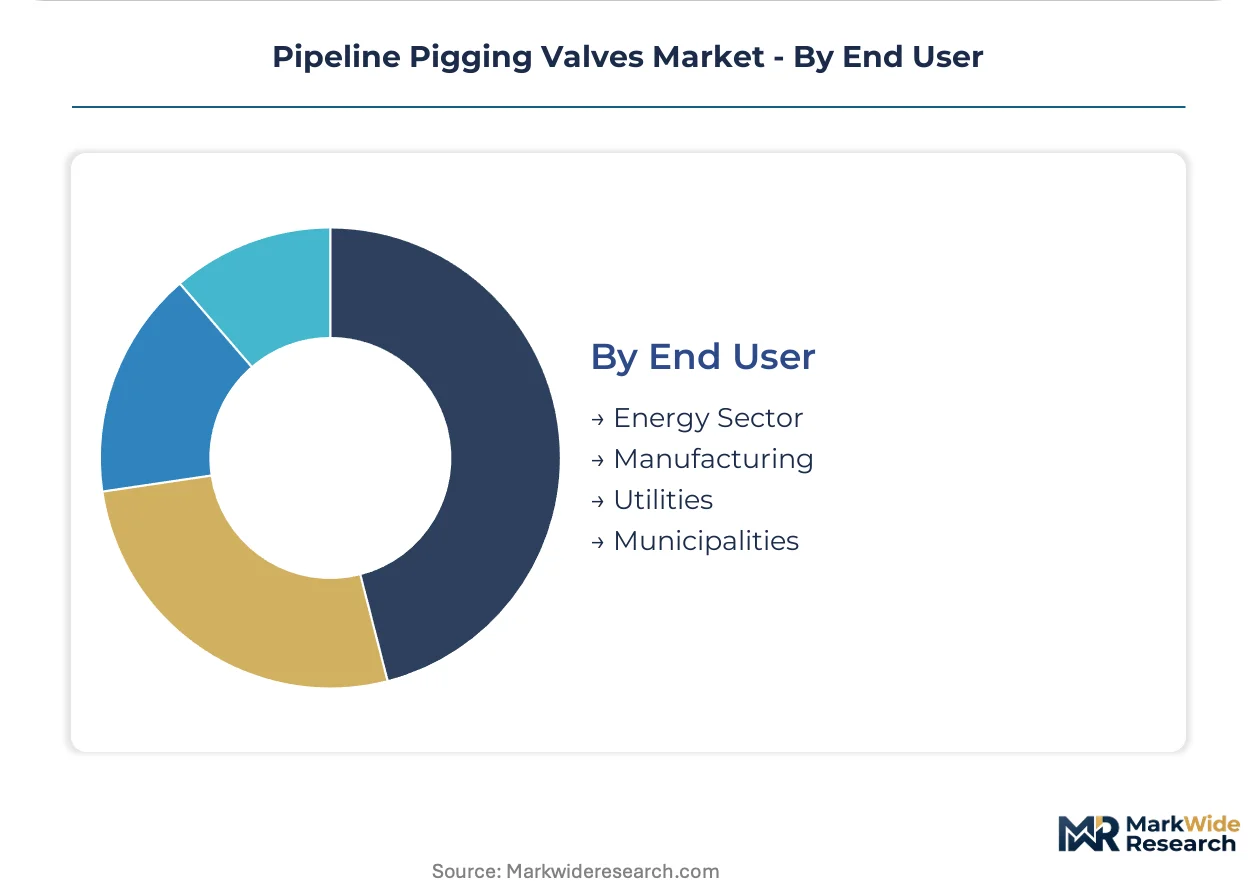
- Energy Sector:Integrated oil companies and independent midstream operators maintain specialized valve engineering groups with direct OEM relationships. Kinder Morgan and Energy Transfer specify turnkey pigging valve skids with pre-commissioned automation for Permian Basin gathering expansions.
- Utilities:Electric and gas distribution utilities consolidate procurement through master service agreements with approved manufacturer lists. Consolidated Edison and Southern California Gas specify standardized valve configurations to simplify inventory and technician training across geographic territories.
- Municipalities:City water departments and wastewater authorities rely on engineer-specified competitive bidding with emphasis on domestic content requirements. Chicago and Houston water utilities specify AWWA C500 gate valves with pigging adapters for transmission main maintenance.
- Manufacturing:Process industries including refining, petrochemicals, and food production specify application-engineered valves through EPC contractors. Dow Chemical and BASF procurement frameworks require ISO 15848-1 fugitive emission certification for valve packages in volatile organic compound service.
Energy sector leads on unit value; utilities gain share fastest on distribution network automation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin infrastructure operators anchor procurement volume for API 6D pigging valves through gathering system expansions and trunk line rehabilitation cycles. National regulators enforce diverging material traceability and emission control standards that reshape supplier qualification requirements. Industrial clusters in Saudi Arabia, China, and Germany concentrate specialized forging capacity and final assembly operations.
United States
PHMSA enforcement of 49 CFR Part 195 proof testing mandates accelerates replacement cycles across hazardous liquid networks exceeding thirty years of service. The Infrastructure Investment and Jobs Act channels federal funding toward pipeline modernization programs. Gulf Coast petrochemical corridors in Texas and Louisiana specify super-duplex stainless steel pigging valves for offshore tieback projects.
Saudi Arabia
Master Gas System expansion and unconventional gas development drive specification of hydrogen sulfide-resistant metal-seated configurations. The national oil company procurement frameworks require ISO 14313 certification with full material traceability for critical isolation equipment. Eastern Province industrial cities anchor fabrication partnerships between international valve OEMs and domestic engineering contractors.
China
West-East Gas Pipeline Phase III construction and shale gas trunk line buildouts absorb high-volume ball valve procurement. GB standards alignment with API 6D specifications gates market access for domestic manufacturers serving international joint ventures. Sichuan-Chongqing shale basins concentrate demand for sour service valve specifications in high-pressure drilling environments.
Germany
EU Methane Regulation implementation drives procurement of ISO 15848-1 certified fugitive emission valves ahead of enforcement deadlines. REACH compliance requirements constrain alloy selection for valve trim components in chemical processing applications. Ruhr industrial clusters maintain specialized large-bore forging capacity for high-pressure ANSI Class 2500 specifications.
Brazil
Pre-salt offshore trunk line construction specifies super-duplex 2507 pigging valves for subsea tieback projects. ANP regulatory frameworks mandate periodic valve integrity verification for deepwater production infrastructure. Rio de Janeiro engineering centers coordinate specification packages between international operators and domestic valve fabricators.
Pipeline Pigging Valves Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital integration and aftermarket service architectures. Market structure concentrates around three capability clusters: German-engineered metal-seated specialists, North American severe-service configurators, and Asian volume fabricators. Strategic archetypes include full-bore ball valve standard-setters, sour gas material specialists, and integrated automation packagers. Dominant competitive moves span capacity expansion into super-duplex forging and strategic partnerships for digital positioner integration.
Within the severe-service specialization tier, Jag Valves represents North American configurators for sour gas environments. Hartmann Valves GmbH exemplifies German-engineered metal-seated design heritage. Tiger Valve Company occupies a position among rapid-turnaround custom engineering providers for midstream infrastructure projects. These three anchors illustrate how geographic engineering traditions translate into differentiated procurement positioning across certification-intensive oil and gas supply chains.
| Leading Market Players |
|---|
| Jag Valves |
| Hartmann Valves GmbH |
| Tiger Valve Company |
| Master Flo Valve Inc. |
| Argus Machine Co. Ltd. |
| Frontier Valve International |
| Sofis Valve Operation |
| CGIS |
| PBM Valve |
| Others |
Value Network & Pricing Analysis
ASME Section IX-qualified welders for high-pressure valve fabrication concentrate in Houston and Edmonton, creating labor-cost differentials that widen pricing spreads between premium-certified and standard-grade pigging valve tiers. German and Italian forging specialists command 40-60 percent labor premiums over Asian competitors, compressing margins for super-duplex specifications while elevating entry barriers for mid-tier producers.
Pricing Analysis
Input-cost pass-through from nickel and molybdenum alloy markets directly shapes valve pricing structures, with super-austenitic grades absorbing commodity volatility through quarterly contract adjustments. Pricing stratifies across API 6D-certified premium tiers, ISO 14313-compliant standard configurations, and uncertified economy alternatives serving non-critical utility applications. Cost compression in the economy tier intensifies because Chinese volume fabricators are expanding forging capacity. Municipal water utilities exhibit highest price sensitivity, while offshore operators in Brazil and West Africa prioritize metallurgical grade over unit cost.
Supply Chain Analysis
Workforce availability for specialized large-bore forging concentrates in Germany, Italy, and Japan, constraining capacity expansion for ANSI Class 2500 specifications. Raw material dependencies draw from nickel mines in Indonesia, molybdenum concentrates in Chile, and chromium alloys in South Africa. Single-source vulnerability runs through Japanese forging houses controlling super-duplex heat-treatment expertise. Distribution runs through engineering-procurement-construction firms consolidating valve-and-automation packages for midstream gathering projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on foundry automation reducing super-duplex casting rework rates, while premium-tier demand shifts toward integrated digital positioner packages that capture aftermarket service attachment.
For Market Incumbents: Deploy backward integration into captive nickel alloy supply to offset commodity volatility squeezing super-austenitic margins. Expand ASME-qualified welding training partnerships in Houston and Calgary to defend against workforce scarcity threatening fabrication timelines. Counter emerging Asian volume fabricators by accelerating ISO 15848-1 certification for fugitive emission valve portfolios ahead of EU Methane Regulation enforcement. For New Entrants and Emerging Players: EU Methane Regulation implementation opens a window for ISO 15848-1-certified valve packagers to capture European transmission operator procurement. Target India's midstream buildout where Reliance Industries and GAIL specifications favor rapid custom engineering turnaround over established brand relationships. Penetrate through pre-commissioned skid packages bundling valves with automation, displacing discrete component sourcing in Permian Basin gathering expansions. For Investors and Strategic Acquirers: Integrated midstream operators are the most active acquirer in this space, consolidating valve engineering capabilities to secure supply chain control. Five-to-ten year viability favors targets with super-duplex forging expertise and digital positioner integration partnerships. Monitor hydrogen infrastructure material qualification standards as the inflection signal determining which sealing technologies survive pipeline repurposing cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Super-Duplex Forging Capacity Expansion | Secures supply position for Brazil pre-salt and West Africa subsea trunk line specifications. |
| Digital Positioner Integration Partnership | Captures predictive maintenance revenue streams from PHMSA-mandated integrity programs. |
| ISO 15848-1 Certification Acceleration | Gates European market access ahead of EU Methane Regulation enforcement deadlines. |
| Hydrogen Compatibility Qualification | Positions sealing technology for repurposed natural gas pipeline infrastructure conversion. |
| ASME Welder Training Consortium | Alleviates fabrication bottlenecks constraining North American supply response. |
Research Methodology
Bottom-up energy sector modeling reconciled against top-down forging capacity tracking forms the analytical core of this study. Primary interviews with pipeline integrity managers, EPC procurement leads, valve OEM engineering directors, and aftermarket service heads combine with secondary validation from PHMSA incident databases, API certification registries, SEC filings of publicly traded midstream operators, and customs trade data on nickel alloy imports. Triangulation between demand-side project pipelines and supply-side foundry utilization rates ensures coherence in volume estimates.
Historical trendline analysis of replacement cycles across North American hazardous liquid networks informs the projection framework. Segmentation dimensions span valve configuration, material grade, pressure class, end-user ownership structure, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to disclosed capital expenditure plans by Kinder Morgan, Energy Transfer, and comparable midstream operators. Forecast inputs incorporate integrity management mandate enforcement intensity and offshore project sanctioning timelines.
Revisions become necessary when nickel-molybdenum price volatility exceeds historical bands, ASME welding certification backlogs extend fabrication lead times, or hydrogen infrastructure material standards diverge from natural gas compatibility assumptions. Material deviation in these triggers warrants pause and re-evaluation of premium-tier demand assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Thermal Power Valve Market
Valves
Reciprocating Compressor Components Market
Valves
Europe Medium Voltage Switchgear Market
Valves
One-Way Valve Market
Valves
Gas Equipment Market
Valves
Steam Trap Valve Market
Valves
Asia Pacific Pipeline Maintenance Market
Valves
North America Valves Market
Valves
Electronic Expansion Valves Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Cathodic Protection Market
Valves
Industrial Vacuum Valves Market
Valves
Manual Control Valve Market
Valves
India Industrial Valves Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Rupture Discs Market