
 Industrial Power Transmission Drive Belts Market | 2026-2036
Industrial Power Transmission Drive Belts Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Power Transmission Drive Belts Market Foresight
Polyurethane is rebalancing cost-performance tradeoffs across the Industrial Power Transmission Drive Belts landscape as rubber faces volatile petrochemical input costs. Gates Corporation leverages captive polymer research to sustain margin stability in timing belt production. Continental AG anchors European supply through integrated rubber compounding and steel cord fabrication. Mitsuboshi Belting dominates Asian OEM channels with specialized heat-resistant V-belt formulations for heavy manufacturing.
Industrial power transmission drive belts are flexible looped power-transfer elements, typically reinforced with polyester cords or steel cables embedded in rubber or polyurethane matrices, engineered to transmit torque between rotating shafts at defined speed ratios with minimal slippage. These components operate under tension loads exceeding 3,000 N in heavy-duty configurations, serving as critical links in machinery drivetrains where gearboxes prove impractical or cost-prohibitive. Timing belts command premium positioning due to synchronous power transfer requirements in precision manufacturing, while V-belts retain volume leadership across general industrial maintenance. Flat belts occupy niche applications in high-speed textile and paper processing where wrap-angle efficiency determines performance.
OSHA machine-guarding standards and EPA emissions frameworks shape belt specification requirements in US industrial facilities, while REACH chemical restrictions in Europe constrain rubber additive formulations and accelerate polyurethane migration. China's GB standards and MIIT industrial efficiency mandates drive domestic procurement toward higher-grade synchronous belts in state-owned manufacturing enterprises. Stakeholders must weigh material-transition capital requirements against regulatory compliance timelines as regional standards diverge on chemical content and energy-efficiency testing protocols.
Market Dynamics
Polyurethane formulation advances are compressing replacement cycles as mining and heavy manufacturing operations demand belts capable of sustaining higher torque loads under elevated thermal stress. REACH chemical restrictions and EU F-Gas Regulation are accelerating material-transition investments while input cost volatility in synthetic rubber feedstocks destabilizes legacy supplier margins.
Growth Catalysts
- Australian mining throughput:Iron ore and copper extraction operations in Western Australia are extending belt-replacement intervals through heavy-duty synchronous belt adoption, creating pull for heat-resistant cord-reinforced constructions.
- REACH additive restrictions:European chemical compliance mandates are redirecting procurement toward polyurethane matrices with lower environmental footprints, compressing rubber formulation market share in EU industrial facilities.
- Shanghai-Yangtze manufacturing corridor:China's state-owned enterprise procurement under MIIT efficiency mandates is concentrating synchronous belt demand in precision machinery clusters around Jiangsu and Zhejiang provinces.
Market Restraints
- Petrochemical input volatility:Synthetic rubber compounding costs fluctuate with crude oil derivatives, compressing margin stability for manufacturers dependent on nitrile and chloroprene feedstocks.
- Steel cord supply concentration:High-tensile cord fabrication capacity clusters in East Asian metallurgical centers, creating vulnerability for European and North American belt producers without captive wire-drawing operations.
- Polyurethane cure-rate limitations:Extended mold-cycle times for large-diameter synchronous belts constrain throughput scaling versus rubber calendering processes.
Strategic Opportunities
- Chilean copper expansion:Antofagasta and Atacama mining districts are upgrading conveyor and power transmission systems, opening demand for abrasion-resistant V-belt configurations in high-dust environments.
- EU Green Deal industrial retrofit:Energy-efficiency refurbishment mandates in German and Italian manufacturing plants are creating replacement windows for synchronous belt retrofits in precision positioning equipment.
- IoT-enabled condition monitoring:Embedded tension and temperature sensors are converging with belt systems, enabling predictive maintenance contracts and service revenue streams for component suppliers.
Industry Challenges
- Polymer formulation expertise scarcity:Qualified compound chemists capable of optimizing polyurethane elastomer hardness and fatigue resistance command premium compensation, constraining R&D scaling for mid-tier manufacturers.
- Multi-standard certification complexity:Simultaneous compliance with OSHA machine-guarding, REACH chemical disclosure, and China's GB belt standards extends product qualification timelines for suppliers serving cross-border industrial accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Power Transmission Drive Belts Market |
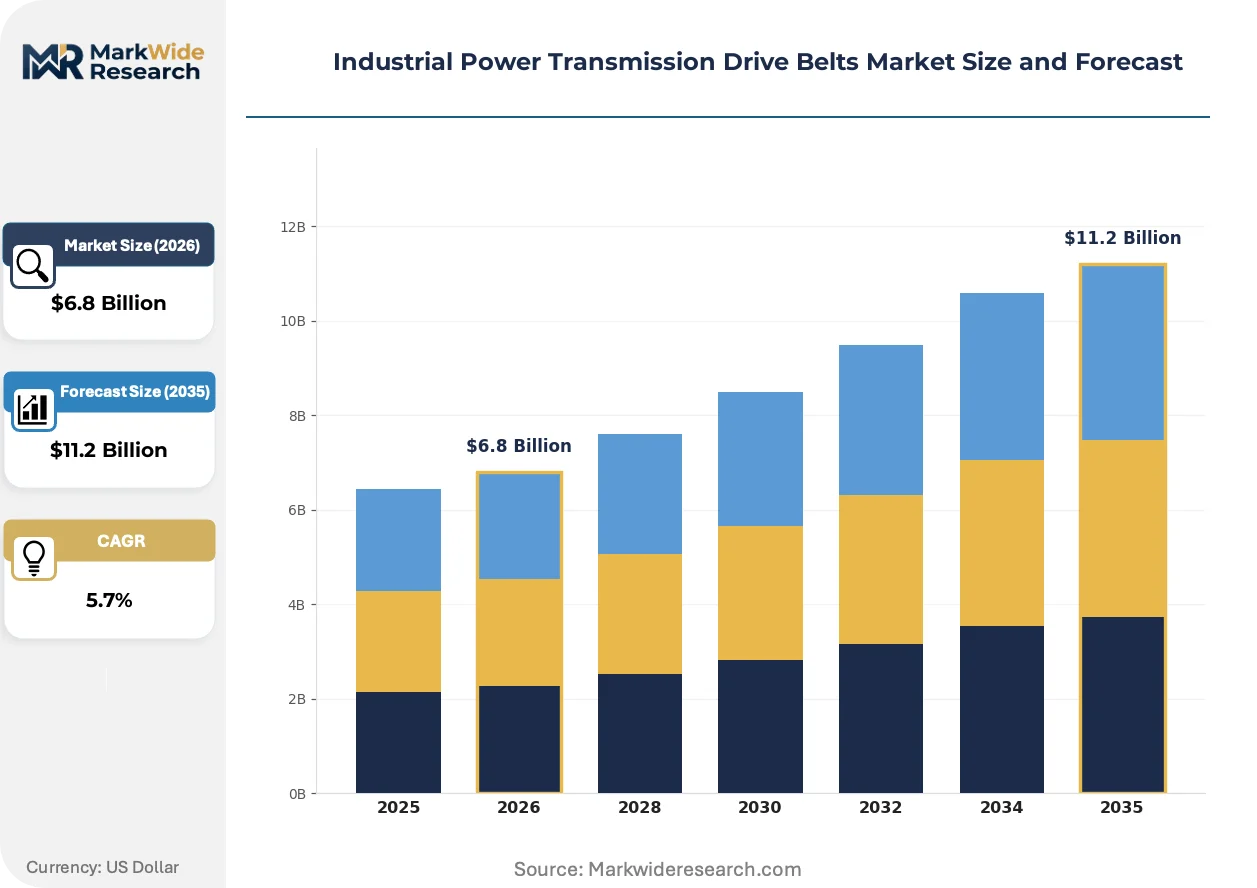
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: V-belts, Timing belts, Flat belts, Conveyor belts Material: Rubber, Polyurethane, Polyester, Steel Application: Manufacturing, Agriculture, Mining, Automotive End User: OEMs, Aftermarket Providers, Distributors, Maintenance Services |
| Companies Covered | Gates Corporation, Continental AG, Mitsuboshi Belting Ltd., Optibelt GmbH, AB SKF, Bando Group, Dayco Corporate, Megadyne, Schaeffler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Power Transmission Drive Belts Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry restrictions are converging to accelerate polyurethane displacement of conventional rubber constructions across precision power transmission applications. Three developments are restructuring competitive positioning in belt manufacturing and procurement.
Aramid fiber reinforcement is electrifying heavy-duty synchronous belt performance by replacing glass and polyester cords in mining and metal-processing drivetrains. Australian iron ore operators are specifying aramid-cord constructions for primary crusher drives, reducing elongation under shock loads. This fiber transition is electrifying supplier R&D priorities as aramid's tensile stability enables longer center distances without tensioning hardware.
EU F-Gas Regulation phase-down schedules are constraining fluorinated polymer availability for specialized belt coatings, forcing reformulation toward non-fluorinated surface treatments. Industrial consequence includes accelerated qualification of plasma-treated polyurethane surfaces for chemical resistance in process industries. German chemical processing OEMs are most affected, responding with accelerated supplier audits for F-Gas-free coating alternatives.
Buyer consolidation among multi-site manufacturing groups is compressing supplier rosters and shifting negotiation leverage toward volume-tiered pricing frameworks. Industrial maintenance procurement at Chinese state-owned enterprises is consolidating belt purchasing through centralized e-procurement platforms, displacing fragmented distributor relationships. This concentration is most visible in the Yangtze River Delta, where Shanghai-based manufacturing headquarters are mandating approved-supplier lists across subsidiary operations.
Industrial Power Transmission Drive Belts Market Segmentation
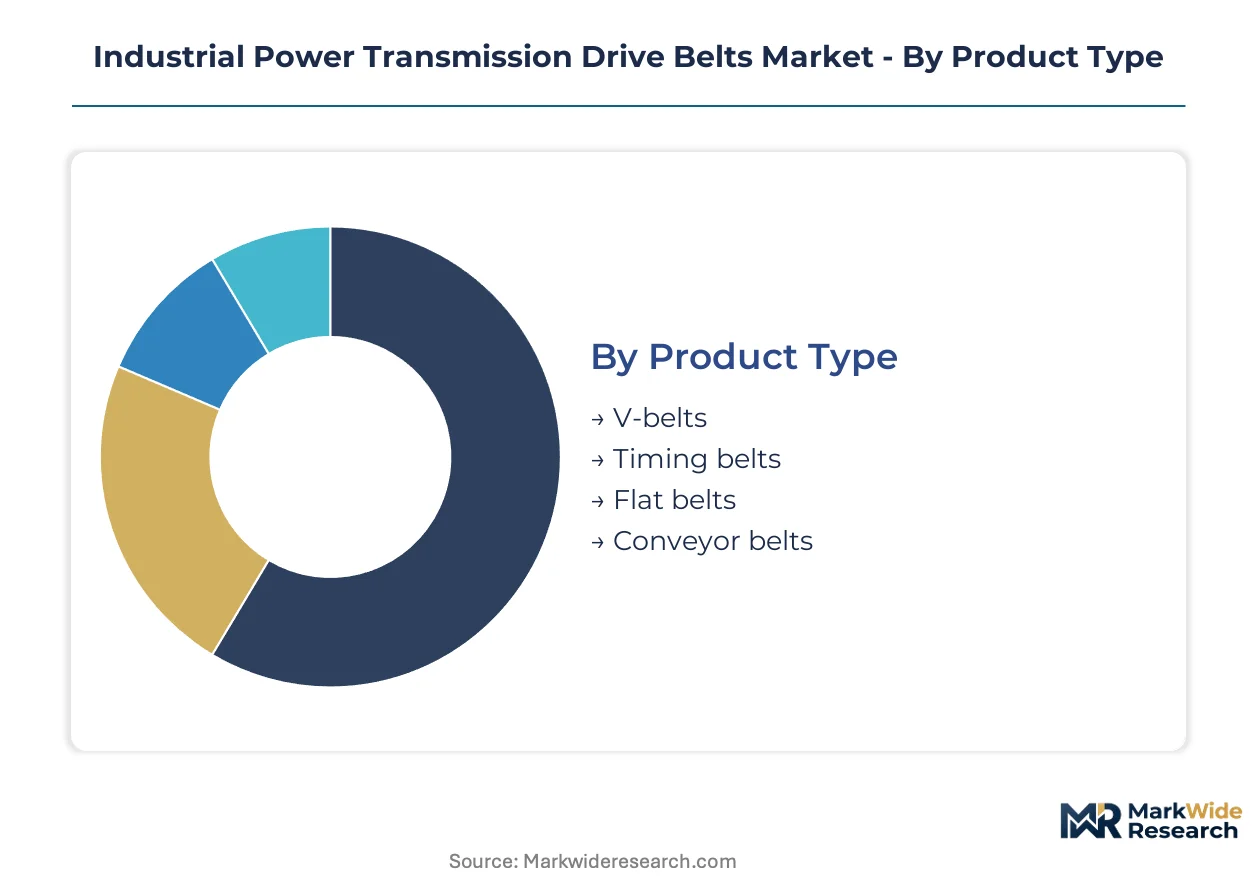
Industrial power transmission drive belts require precise specification matching across torque loads, thermal environments, and regulatory jurisdictions. Segmentation reveals how material chemistry and application intensity determine certification burdens and procurement priorities for facility engineers.
Product Type:
V-belts carry CE marking and OSHA machine-guarding compliance requirements for general industrial installations, while timing belts face additional synchronous precision certifications under ISO 9563 for power transmission accuracy.
- V-belts:Trapezoidal cross-section constructions reinforced with polyester cords or fabric jackets dominate general-purpose power transmission. Demand concentrates in Brazilian agricultural processing facilities and Indian textile mills where cost-sensitive maintenance procurement favors standardized profiles. REACH chemical disclosure requirements are compressing rubber additive options for EU-bound shipments.
- Timing belts:Tooth-profile synchronous constructions with glass fiber or steel cord reinforcement eliminate slip for precision positioning. German automotive component manufacturers and Japanese machine tool builders specify these for camshaft drives and servo positioning systems. ISO 9563 pitch accuracy certification extends qualification timelines for new supplier entry.
- Flat belts:Thin, wide constructions optimize high-speed wrap-angle efficiency in paper and textile processing. Lighter tensioning requirements suit older machinery retrofits in Eastern European manufacturing plants.
- Conveyor belts:Heavy-duty bulk material handling systems integrate with power transmission in integrated mining operations. Australian iron ore ports and Chilean copper concentrators specify flame-resistant constructions under site-specific safety protocols.
V-belts sit at the top of the volume ranking, with timing belts climbing the fastest.
Material:
Raw material selection determines environmental compliance pathways, with polyurethane formulations bypassing REACH-restricted rubber additives while rubber compounds face F-Gas Regulation constraints on fluorinated processing aids.
- Rubber:Nitrile, chloroprene, and natural rubber matrices with fabric or cord reinforcement retain installed-base dominance. Volatile petrochemical feedstock costs destabilize margin structures for manufacturers without backward integration into polymer supply. EPA emissions frameworks and REACH chemical restrictions constrain additive packages in transatlantic trade.
- Polyurethane:Thermoset elastomer constructions with superior abrasion resistance and chemical stability. German chemical processing OEMs and Chinese state-owned manufacturers under MIIT efficiency mandates are redirecting procurement toward these formulations. Lower environmental footprint accelerates qualification for EU Green Deal retrofit programs.
- Polyester:High-tenacity cord reinforcement embedded in rubber or polyurethane matrices controls elongation under load. Textile machinery manufacturers in Italy and South Korea specify these for precision tension maintenance.
- Steel:High-tensile cable reinforcement for heavy-duty synchronous and conveyor applications. Mining operators in Western Australia prioritize these for primary crusher drives where shock loads exceed 3,000 N.
Rubber maintains volume leadership, though polyurethane is expanding most quickly.
Application:
Application intensity dictates belt specification tiers, with mining and automotive demanding heavy-duty synchronous constructions while manufacturing and agriculture accommodate standardized V-belt profiles.
- Manufacturing:General machinery drivetrains in metalworking, plastics processing, and packaging equipment. Precision positioning segments in German and Italian machine tool production favor timing belt specifications.
- Agriculture:Combine harvesters, irrigation pumps, and grain handling equipment in Brazil, India, and US Midwest operations. Cost-driven maintenance cycles favor standardized V-belt replacement.
- Mining:Primary crushers, conveyors, and processing equipment in Australian iron ore and Chilean copper districts. Abrasion-resistant constructions with aramid or steel reinforcement withstand high-dust, shock-load environments.
- Automotive:Engine camshaft drives, accessory drives, and electric vehicle motor timing systems. Japanese and German OEMs specify molded rubber or polyurethane synchronous constructions with ISO-certified pitch accuracy.
Manufacturing commands the largest volume position, with mining gaining share fastest.
End User:
Procurement consolidation patterns diverge sharply, with OEMs demanding certified supplier partnerships and aftermarket channels fragmenting across distributor networks and direct e-procurement platforms.
- OEMs:Original equipment manufacturers specify belts during machinery design and assembly. Japanese automotive and German machine tool builders maintain approved-supplier lists with multi-year qualification protocols.
- Aftermarket Providers:Independent distributors and service organizations supplying replacement inventory. Chinese state-owned enterprise consolidation is compressing these channels into centralized e-procurement platforms.
- Distributors:Regional stocking intermediaries serving fragmented industrial maintenance demand. Margin pressure from manufacturer-direct sales is constraining inventory breadth.
- Maintenance Services:Contracted facility management and predictive maintenance providers. IoT-enabled condition monitoring integration is creating service revenue attachment opportunities.
OEMs anchor the volume ranking, with maintenance services climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing corridor anchors demand concentration for precision synchronous belt applications, with Shanghai-based procurement offices consolidating supplier rosters across Jiangsu and Zhejiang industrial clusters. Mining operations in Western Australia and Chilean copper districts drive heavy-duty replacement cycles, while EU chemical regulations accelerate material transitions in German processing equipment.
China
MIIT efficiency mandates redirect state-owned enterprise procurement toward high-grade synchronous belts in metalworking and plastics machinery. GB standards compliance requirements extend qualification timelines for polyurethane formulations entering domestic supply chains. The Jiangsu province precision machinery cluster around Suzhou and Wuxi concentrates OEM specification authority for timing belt retrofits.
Germany
EU Green Deal industrial retrofit programs create replacement windows for energy-efficient belt systems in automotive component and machine tool production. REACH chemical disclosure requirements constrain rubber additive packages, accelerating polyurethane migration in chemical processing OEM supply chains. The Baden-Württemberg automotive belt corridor sustains demand for ISO 9563-certified synchronous constructions.
United States
OSHA machine-guarding standards and EPA emissions frameworks shape belt specification requirements across metalworking and agricultural equipment sectors. The Midwest manufacturing belt spanning Illinois, Michigan, and Ohio maintains volume demand for standardized V-belt maintenance procurement. Texas petrochemical processing clusters specify chemical-resistant polyurethane formulations under site-specific safety protocols.
Australia
Western Australian iron ore extraction operations extend belt-replacement intervals through aramid-cord synchronous belt adoption in primary crusher drives. TGA-equivalent mining safety regulations mandate flame-resistant constructions for conveyor and power transmission integration. The Pilbara region concentrates heavy-duty procurement authority for abrasion-resistant configurations in high-dust environments.
Chile
Antofagasta and Atacama copper mining districts upgrade conveyor and power transmission systems, opening demand for steel-reinforced V-belt configurations. National mining regulator standards enforce abrasion resistance certification for surface and underground equipment. The Calama industrial service corridor anchors aftermarket distribution for maintenance-intensive extraction operations.
Industrial Power Transmission Drive Belts Market Competitive Landscape
Material-transition investments dominate the current landscape as polyurethane formulation R&D compresses rubber market share. The vendor base stratifies across three tiers: integrated polymer compounders with captive cord fabrication, specialized belt fabricators dependent on external metallurgical supply, and regional distributors serving fragmented maintenance demand. Two competitive vectors define positioning: backward integration into polymer research to stabilize margin structures, and IoT-enabled service revenue attachment to escape component commoditization.
Among integrated compounders, Gates Corporation and Continental AG exemplify archetypes of polymer-captive stability, while Mitsuboshi Belting occupies a position within Asia-Pacific OEM channel specialization. These three entities represent distinct strategic postures: American polymer research depth, European rubber-steel integration, and Japanese heat-resistant formulation expertise for heavy manufacturing environments.
| Leading Market Players |
|---|
| Gates Corporation |
| Continental AG |
| Mitsuboshi Belting Ltd. |
| Optibelt GmbH |
| AB SKF |
| Bando Group |
| Dayco Corporate |
| Megadyne |
| Schaeffler Group |
| Others |
Supply & Pricing Matrix
Chinese state-owned enterprise procurement consolidation through centralized e-procurement platforms anchors the dominant pricing model across the Industrial Power Transmission Drive Belts market. This buyer concentration compresses margin structures for manufacturers without captive polymer supply or approved-supplier status.
Pricing Analysis
Petrochemical feedstock volatility in nitrile and chloroprene rubber compounds passes through to contract pricing with 60-90 day lag structures. Three-tier pricing structure across premium ISO 9563-certified synchronous belts, standard V-belt maintenance grades, and economy textile-cord constructions differentiates procurement tiers. Pricing pressure stems from polyurethane formulation R&D investments required for REACH compliance. Aftermarket distributors serving fragmented maintenance demand exhibit highest price sensitivity, while German automotive OEMs prioritize certification over unit cost.
Supply Chain Analysis
High-tensile steel cord fabrication rests on East Asian metallurgical centers in China, Japan, and South Korea. Synthetic rubber compounding draws from German and Thai petrochemical complexes, while aramid fiber reinforcement sources from US and European specialty polymer producers. Single-source vulnerability concentrates in steel cord supply for heavy-duty mining applications. Distribution runs through regional stocking intermediaries serving industrial maintenance clusters, with manufacturer-direct sales compressing traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Industrial Power Transmission Drive Belts market functions as a geographic-arbitrage play between EU REACH compliance costs and Chinese MIIT efficiency-mandate procurement premiums. Polyurethane formulation investments required for European market access create 15-20 point margin spreads versus rubber-dependent competitors.
For Market Incumbents: Extend captive polymer research capabilities to stabilize margin structures against petrochemical input volatility. Gates Corporation and Continental AG exemplify this posture through backward integration into rubber compounding and steel cord fabrication. Consolidate approved-supplier status with Chinese state-owned enterprises before centralized e-procurement platforms harden entry barriers. For New Entrants and Emerging Players: Begin with aftermarket service integration in Chilean copper mining districts and Australian iron ore corridors, where abrasion-resistant V-belt demand outruns established distributor coverage. Target predictive maintenance contracts attaching IoT-enabled condition monitoring to belt supply agreements, bypassing capital-intensive polymer formulation requirements. For Investors and Strategic Acquirers: German chemical processing OEMs are the most active acquirer in this space, seeking polyurethane formulation capabilities for F-Gas-free coating alternatives. Long-term viability hinges on material-transition completion before REACH additive restrictions harden. Watch aramid-cord synchronous belt adoption rates in Western Australian mining operations as inflection signal for heavy-duty segment restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Gates Corporation's captive research stabilizes timing belt margins against rubber feedstock volatility. |
| EU Green Deal Retrofit Certification | German automotive OEMs mandate ISO 9563 pitch accuracy for energy-efficient synchronous belt replacements. |
| IoT-Enabled Condition Monitoring | Embedded tension sensors create predictive maintenance revenue streams beyond component commoditization. |
| Aramid Fiber Reinforcement Scale-Up | Australian iron ore operators specify aramid-cord constructions for primary crusher shock loads exceeding 3,000 N. |
| Centralized E-Procurement Platform Entry | Chinese state-owned enterprise consolidation compresses supplier rosters in Yangtze River Delta manufacturing clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged maintenance directors at Australian mining operations, plant engineers in German automotive component facilities, OEM procurement teams at Japanese machine tool builders, and aftermarket service heads in Chilean copper districts. Secondary validation drew from customs trade data, SEC 10-K filings of listed belt manufacturers, MIIT industrial efficiency mandate documentation, and REACH chemical disclosure registries. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Historical reference periods anchored volume and value projections across the modeling period. Segmentation dimensions included product type tier, material chemistry grade, application intensity level, and end-user procurement channel. CAGRs derived from regression analysis of replacement cycle compression, regulatory-driven material transition timelines, and mining throughput expansion rates. Industry-specific inputs incorporated ore extraction volume forecasts for Pilbara and Atacama districts and MIIT mandate implementation schedules for state-owned enterprise procurement.
Several conditions sit outside the modeled scope, including tariff rate shifts affecting steel cord cross-border flows, abrupt F-Gas Regulation phase-down accelerations, and unanticipated polyurethane cure-rate breakthroughs. Forecasts reflect documented assumptions about regulatory compliance timelines and mining capital expenditure continuity. A small set of named triggers warrants ongoing watch: REACH additive restriction scope expansions, Chinese e-procurement platform policy pivots, and aramid fiber supply capacity additions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Power Infrastructure Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Qatar Power EPC Market
Power Equipment
US Power EPC Market
Power Equipment
Global Power Supply Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Levant Power Cable Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Induction Heating System Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Europe Power Rental Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
Global Auxiliary Power Unit Market