
 United States Turbine Control Systems Market | 2026-2036
United States Turbine Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United States Turbine Control Systems Market Analytics
The capability gap between integrated hardware-software platforms and component-only suppliers is unwinding competitive dynamics across the sector. Siemens Energy AG leverages its captive gas turbine manufacturing base to bundle control systems with new unit sales. Woodward Inc. specializes in fuel metering and combustion management subsystems for retrofit installations. Emerson Electric Company sustains broad installed-base service contracts through its DeltaV distributed control platform.
United States turbine control systems encompass hardware and software architectures that regulate speed, load, temperature, and vibration across rotating turbomachinery, typically integrating programmable logic controllers with safety instrumented systems achieving SIL 3 certification for emergency shutdown sequences. Distributed control systems anchor the product mix, reflecting their entrenched position in utility-scale power generation facilities where operators prioritize redundant I/O architectures. Digital control technology leads growth trajectories as operators replace analog pneumatic loops with model-based predictive algorithms; hybrid control configurations persist in marine applications where vessel classification societies mandate physical backup channels.
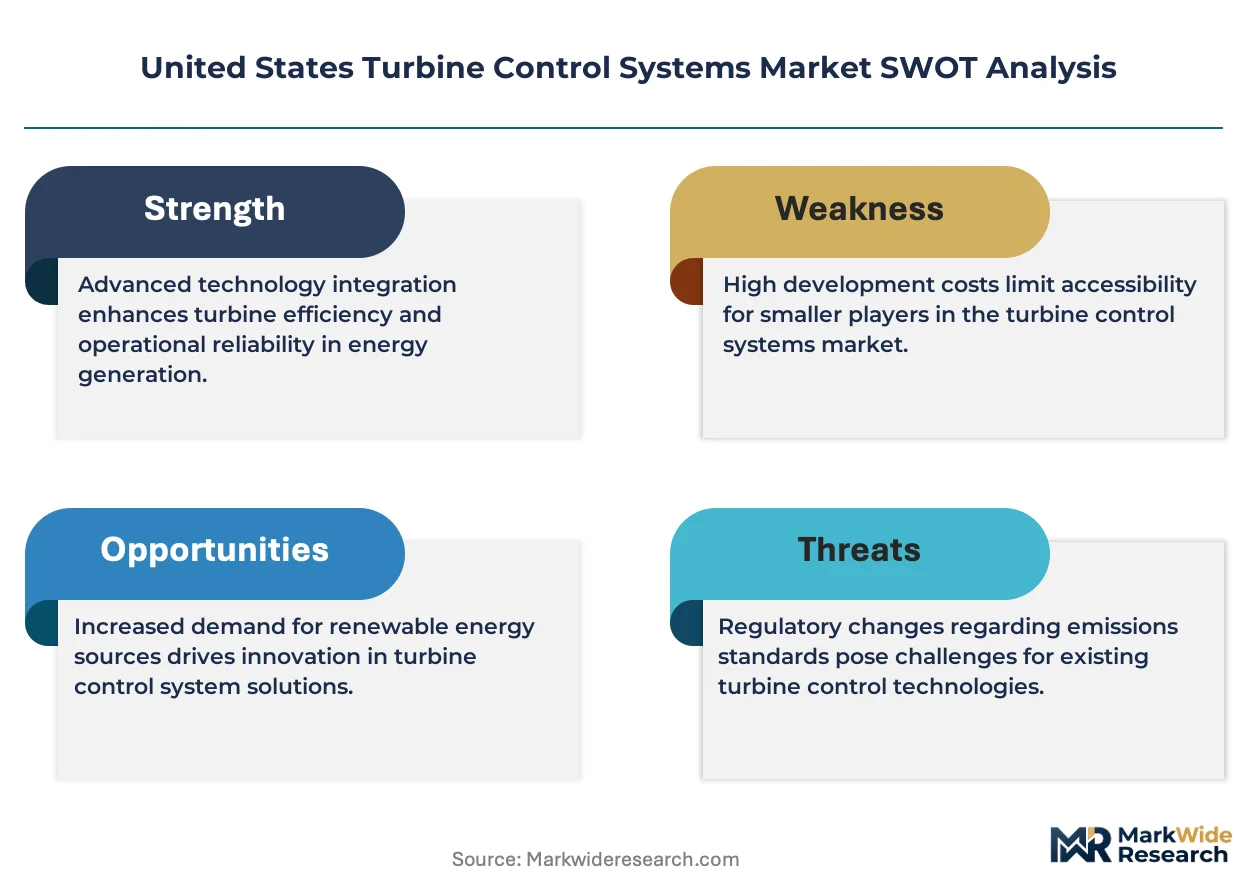
FERC Order 2222 enables aggregated distributed energy resources to participate in wholesale markets, expanding addressable demand for turbine control upgrades that enable rapid ramping and grid stabilization services. EPA greenhouse gas standards and NERC CIP cybersecurity mandates compel utilities to modernize legacy control architectures with authenticated network segmentation and emissions-optimized combustion tuning. Stakeholders must weigh the capital allocation trade-off between full control system replacement and incremental digital overlay deployments as plant operating horizons extend amid dispatch volatility.
Market Dynamics
Digital control retrofits across aging gas turbine fleets are compressing replacement cycles while EPA greenhouse gas standards force precision combustion upgrades. Utilities face capital allocation trade-offs between full system replacement and incremental digital overlays as dispatch volatility extends plant operating horizons.
Growth Catalysts
- EPA Performance Standards:Greenhouse gas regulations for power plants mandate emissions-optimized combustion tuning, driving demand for advanced fuel metering and control architectures.
- Texas CCGT Concentration:Independent power producers in Texas operate the nation's largest combined-cycle gas turbine fleet, creating concentrated demand for control system modernization.
- Model-Based Predictive Algorithms:Operators replace analog pneumatic loops with digital control technology that enables rapid ramping and grid stabilization services.
Market Restraints
- Specialized Component Supply:Precision sensors and actuators for high-temperature turbine environments concentrate among limited qualified suppliers, creating procurement bottlenecks.
- NERC CIP Compliance Burden:Cybersecurity mandates for critical infrastructure impose authenticated network segmentation requirements that extend upgrade timelines and engineering costs.
- Hybrid Configuration Persistence:Marine classification societies mandate physical backup channels that constrain full digital adoption in offshore and naval applications.
Strategic Opportunities
- FERC Order 2222 Aggregation:Wholesale market participation rules for distributed energy resources expand addressable demand for turbine controls enabling grid stabilization services.
- SIL 3 Safety Integration:Convergence of programmable logic controllers with safety instrumented systems creates bundled upgrade pathways for emergency shutdown sequences.
- Installed-Base Service Contracts:Long-term maintenance agreements for legacy distributed control platforms offer recurring revenue streams as operators defer capital replacement.
Industry Challenges
- Cybersecurity Engineering Talent:NERC CIP compliance requires specialized expertise in industrial control system security that utilities struggle to source and retain.
- Legacy System Integration:Digital overlay deployments must interface with decades-old analog architectures, creating commissioning complexity and extended outage windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Turbine Control Systems Market |
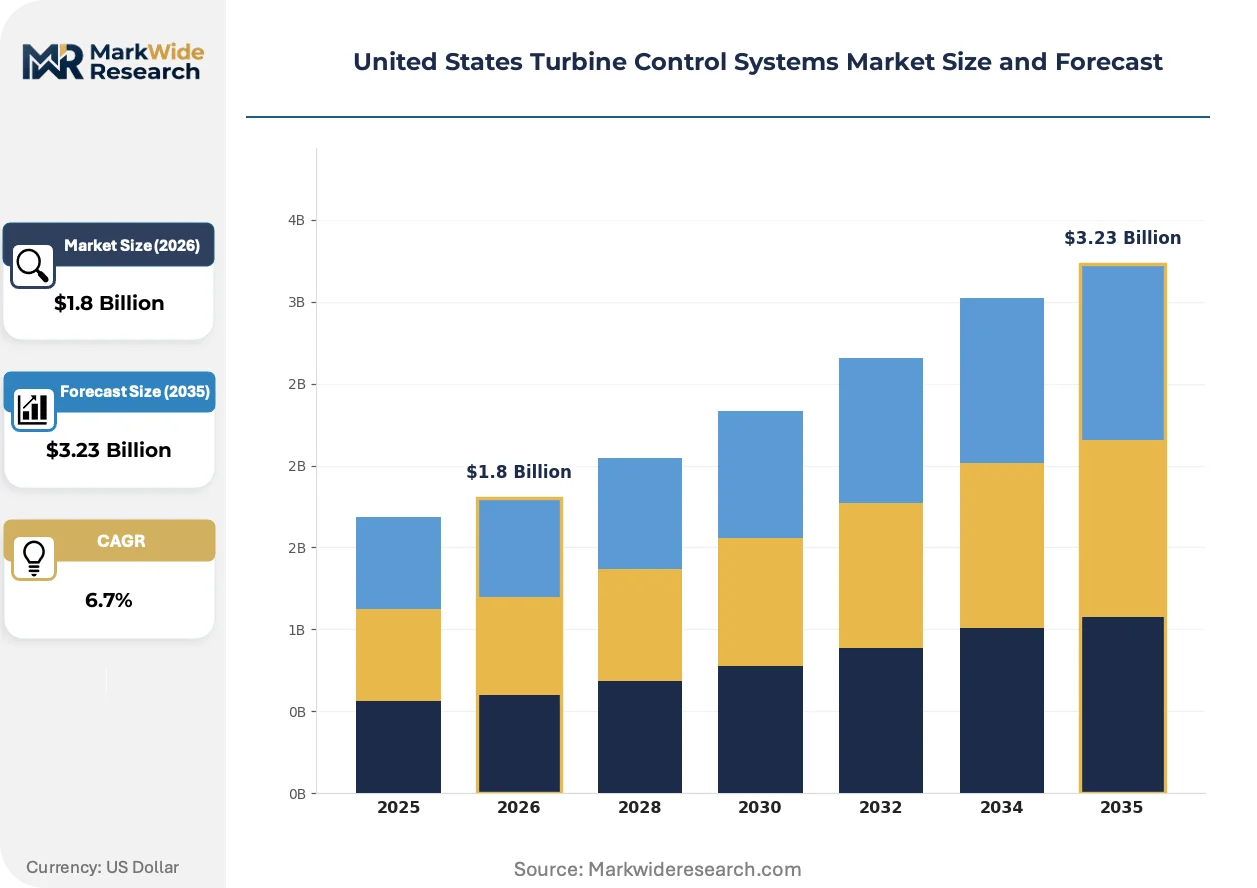
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distributed Control Systems, Programmable Logic Controllers, Safety Instrumented Systems, Human-Machine Interface Application: Power Generation, Oil & Gas, Marine, Industrial End User: Utilities, OEMs, Contractors, End Users Technology: Digital Control, Analog Control, Hybrid Control, Wireless Communication |
| Companies Covered | Siemens AG, Emerson Electric Company, General Electric Company, ABB Ltd, Rockwell Automation, Honeywell International Inc., Siemens Energy AG, Woodward Inc., Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Turbine Control Systems Market Evolving Landscape
Control system architectures are bifurcating between integrated hardware-software platforms and modular component suppliers, reshaping competitive positioning across the sector. Three forces are actively restructuring how turbine control solutions are specified, procured, and deployed.
Edge computing nodes deployed directly at turbine skids are fragmenting traditional centralized control room architectures. Combined-cycle operators in Texas and the Southeast are piloting distributed intelligence for millisecond-level combustion feedback. This topology is fragmenting the historic dominance of single-vendor distributed control systems by enabling multi-supplier interoperability.
EPA greenhouse gas performance standards are mandating continuous emissions monitoring integrated with fuel control loops. Power generators must retrofit existing units with automated combustion optimization or face dispatch penalties. Combined-cycle facilities in ERCOT and PJM interconnection zones are prioritizing controls vendors with certified emissions tuning algorithms.
After-sales service unbundling is separating hardware procurement from long-term maintenance agreements. Large independent power producers now negotiate control system upgrades through engineering-procurement-construction contractors rather than original equipment manufacturers. This pattern concentrates in merchant gas turbine fleets where operating cost transparency drives vendor selection.
United States Turbine Control Systems Market Segmentation
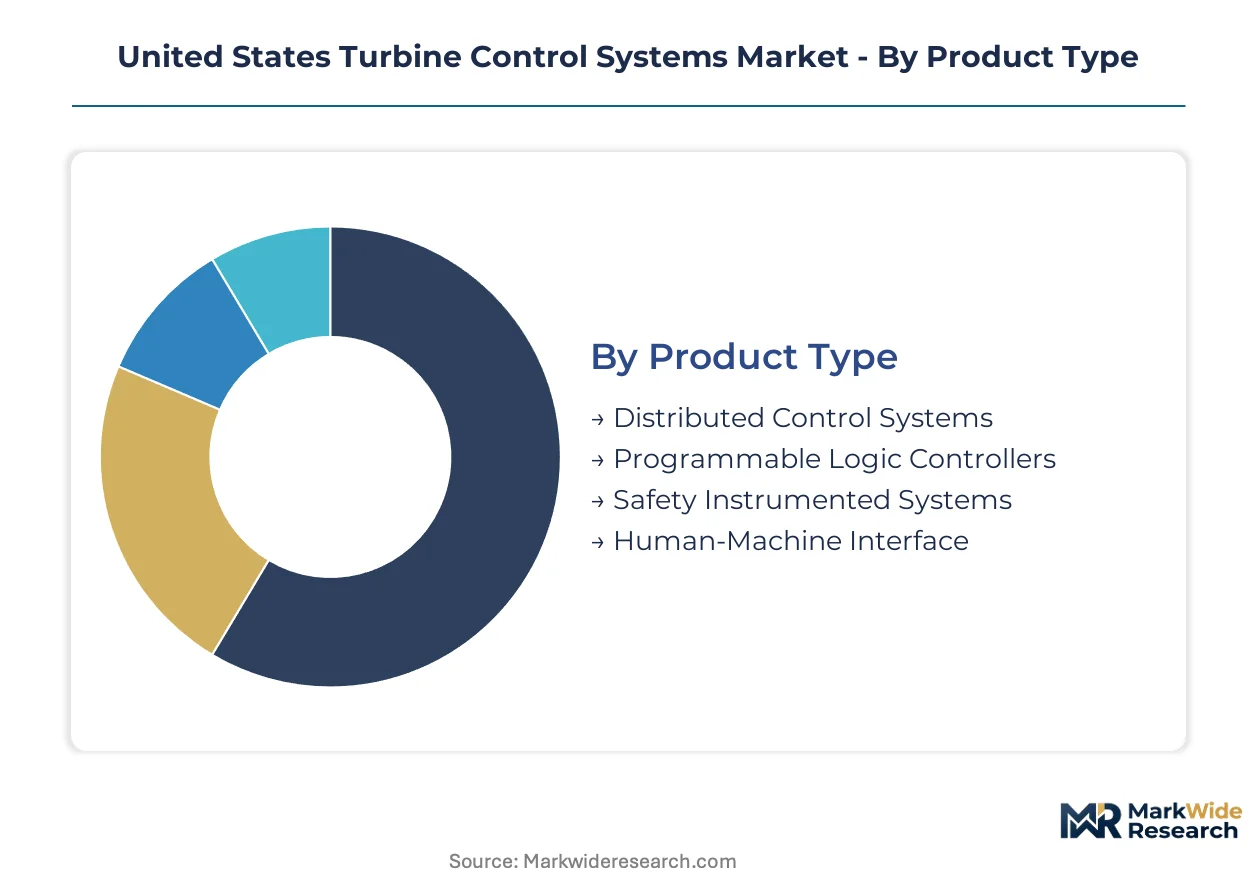
Turbine control procurement patterns diverge sharply across product architectures and end-use contexts. Utility operators prioritize redundant safety certifications while independent power producers optimize for rapid dispatch flexibility. Understanding these segment-level trade-offs clarifies where upgrade budgets concentrate versus where replacement cycles stretch.
Product Type:
Distributed Control Systems face intensifying substitution pressure from edge-computing architectures that fragment centralized command structures. Programmable Logic Controllers confront competition from integrated safety platforms that bundle control and emergency shutdown functions.
- Distributed Control Systems:Redundant I/O architectures dominate utility-scale generation facilities where operators demand fault-tolerant process management. Demand concentrates in Texas combined-cycle plants where ERCOT dispatch volatility requires millisecond-level load modulation. EPA emissions standards accelerate retrofits of legacy DCS platforms with integrated combustion optimization modules.
- Programmable Logic Controllers:Modular processing units execute discrete logic sequences for turbine sequencing and auxiliary system coordination. OEM turbine manufacturers in the Southeast specify PLCs for new unit commissioning where standardized programming reduces field engineering hours. NERC CIP cybersecurity mandates drive authentication layer upgrades across installed PLC bases.
- Safety Instrumented Systems:SIL 3-certified emergency shutdown architectures protect rotating machinery from overspeed and vibration excursions.
- Human-Machine Interface:Operator workstations consolidate alarm management and trend visualization for control room personnel.
Distributed Control Systems anchors the volume base while Programmable Logic Controllers gains share at the steepest rate.
Application:
Cost tier differentiation separates mission-critical power generation from price-sensitive industrial deployments. Marine applications command premium pricing for classification society compliance while oil and gas operators balance reliability against offshore maintenance logistics.
- Power Generation:Combined-cycle and simple-cycle gas turbines require precision speed, temperature, and emissions control across baseload and peaking duty cycles. ERCOT and PJM interconnection zones drive concentrated demand as merchant operators retrofit for FERC Order 2222 grid services participation. EPA greenhouse gas performance standards mandate continuous emissions monitoring integration with fuel control loops.
- Oil & Gas:Pipeline compression and offshore platform power demand ruggedized control architectures tolerant of sour gas environments and extreme ambient temperatures. Permian Basin producers specify explosion-proof enclosures and remote diagnostic capabilities to minimize helicopter-deployed maintenance crews.
- Marine:Naval and commercial vessel applications require physical backup channels under classification society rules that constrain full digital adoption.
- Industrial:Petrochemical and refining operations integrate turbine controls with broader plant-wide optimization systems.
Power Generation captures the majority of current procurement while Oil & Gas expands most quickly amid LNG export facility construction.
End User:
Customer type determines whether procurement flows through long-term service contracts or competitive engineering-procurement-construction tenders. Utility ownership structures create divergent capital allocation timelines compared to merchant generator financing models.
- Utilities:Investor-owned and municipal electric utilities operate under rate-base regulation that amortizes control system investments across decades of depreciation schedules. Southeast utilities prioritize vendor relationships that bundle hardware with multi-year maintenance agreements.
- OEMs:Original equipment manufacturers specify control architectures for new turbine unit deliveries where captive software platforms lock in aftermarket service revenue.
- Contractors:Engineering-procurement-construction firms negotiate control system packages on behalf of independent power producers seeking transparent operating cost structures.
- End Users:Industrial facility operators with captive power generation manage smaller-scale turbine installations with less specialized technical staff.
Utilities dominate current installed base ownership while Contractors capture expanding share as merchant generation assets change hands.
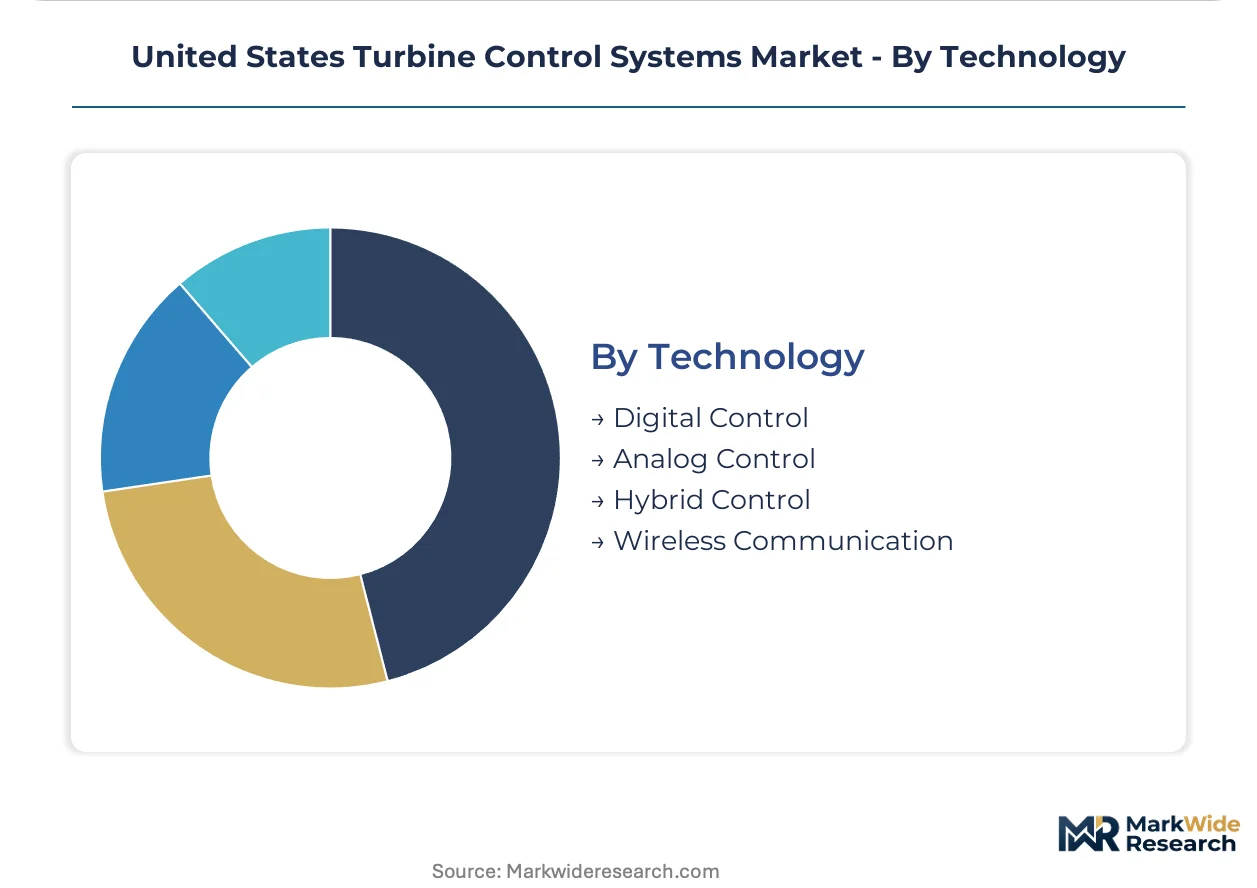
Technology:
Maturity gradients separate legacy analog installations from digitally native architectures. Wireless communication protocols introduce cybersecurity surface area that NERC CIP mandates must address through authenticated network segmentation.
- Digital Control:Model-based predictive algorithms replace pneumatic loops with software-defined combustion tuning and automated emissions optimization. Texas combined-cycle operators pilot edge computing nodes for distributed intelligence at turbine skids.
- Analog Control:Pneumatic and hardwired electronic systems persist in baseload plants with extended depreciation horizons and conservative engineering cultures.
- Hybrid Control:Physical backup channels satisfy marine classification society requirements and certain critical infrastructure redundancy mandates.
- Wireless Communication:Industrial wireless protocols reduce cabling costs in retrofit applications while introducing new cybersecurity engineering complexity.
Digital Control commands the dominant technology position while Wireless Communication climbs the fastest as retrofit projects seek installation cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant generators in Texas exhibit the lowest price elasticity as dispatch volatility forces rapid ramping investments, while municipal utilities in the Midwest stretch replacement cycles across depreciation schedules. Coastal utilities face intermediate sensitivity where EPA compliance deadlines override capital constraints.
Texas
Independent power producers operate the nation's largest combined-cycle gas turbine fleet concentrated along the ERCOT interconnection. EPA greenhouse gas performance standards mandate emissions-optimized combustion tuning across aging units. The Houston Ship Channel corridor hosts intensive retrofit activity as operators pilot edge computing nodes for millisecond-level load modulation.
California
Load-serving entities face accelerating turbine control procurement as renewable intermittency forces gas peaker cycling. The state's air resources board imposes stringent NOx limits that require automated combustion optimization. The Los Angeles Basin and Central Valley host concentrated demand for digital retrofits that enable rapid ramping services.
Southeast
Investor-owned utilities in Florida and Georgia prioritize vendor relationships bundling hardware with multi-year maintenance agreements. NERC CIP cybersecurity mandates drive authenticated network segmentation upgrades across legacy distributed control platforms. The Savannah River nuclear corridor and Gulf Coast petrochemical clusters anchor regional demand concentration.
Midwest
Municipal and cooperative utilities stretch capital replacement timelines across decades-long depreciation schedules. FERC Order 2222 aggregation rules expand addressable demand for turbine controls enabling distributed energy resource participation in wholesale markets. The Ohio River Valley and Upper Midwest manufacturing belt concentrate industrial cogeneration retrofit activity.
Northeast
Merchant generators and load-serving entities face compressed upgrade timelines as state decarbonization mandates intersect with reliability requirements. Regional greenhouse gas initiatives impose emissions caps that force precision fuel metering investments. The Boston-Washington corridor hosts concentrated demand for SIL 3 safety instrumented system integration.
United States Turbine Control Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United States turbine control systems market. Integrated hardware-software platforms command premium positioning through bundled safety certification and emissions optimization capabilities, while modular component suppliers compete on retrofit installation speed and interoperability. Three archetypes dominate: captive turbine OEMs with aftermarket lock-in, specialized combustion subsystem vendors, and broad distributed control platform providers with installed-base service contracts. Competitive moves concentrate on strategic partnerships with engineering-procurement-construction contractors and portfolio diversification into edge-computing architectures.
Among Germany-based industrial conglomerates, Siemens AG and Siemens Energy AG exemplify the integrated platform archetype through captive gas turbine manufacturing relationships. Woodward Inc. represents specialized component suppliers focused on fuel metering and combustion management subsystems. Emerson Electric Company anchors the broad platform provider tier through distributed control system installed-base penetration. These three occupy positions spanning the technology-cost spectrum without overlapping core value propositions.
| Leading Market Players |
|---|
| Siemens AG |
| Emerson Electric Company |
| General Electric Company |
| ABB Ltd |
| Rockwell Automation |
| Honeywell International Inc. |
| Siemens Energy AG |
| Woodward Inc. |
| Schneider Electric |
| Others |
Value Network & Pricing Analysis
Eighteen-month lead times for SIL 3-certified safety processors concentrate pricing power among qualified vendors while compressing margins for system integrators caught between component scarcity and fixed-price EPC contracts. Inventory buffers at Texas combined-cycle facilities now stretch to ninety days as operators hoard critical spares against supply disruptions, embedding working capital costs into lifecycle pricing models.
Pricing Analysis
After-sales service revenue from multi-year maintenance agreements drives lifetime value for distributed control system vendors, often exceeding original hardware margins by the third contract renewal. Project-based pricing dominates initial procurement, with differentiation anchored in EPA emissions certification tiers and NERC CIP cybersecurity compliance levels. Pricing pressure stems from independent power producers unbundling hardware from service contracts and negotiating through EPC intermediaries. Merchant generators in Texas exhibit the lowest price sensitivity as dispatch volatility forces rapid ramping investments, while municipal utilities in the Midwest stretch replacement cycles across depreciation schedules.
Supply Chain Analysis
Strait of Hormuz transit exposure for specialty high-temperature alloys concentrates supply risk for precision turbine sensors and actuators, forcing US operators to maintain strategic reserves. Manufacturing draws from Germany, Japan, and domestic US foundries for critical rotating machinery components. Raw material dependencies span nickel-based superalloys, ceramic thermal barrier coatings, and hardened electronic substrates. Single-source vulnerability persists for FPGA chips qualified to military-grade temperature specifications. Distribution runs through OEM captive channels, EPC contractor procurement desks, and direct utility maintenance agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as edge-computing architectures fragment the historic single-vendor DCS model and enable multi-supplier interoperability at turbine skids.
For Market Incumbents: Shield installed-base service contracts through cybersecurity certification bundling that locks out modular competitors lacking NERC CIP compliance depth. Deepen backward integration into FPGA supply chains to insulate against semiconductor allocation shocks. Counter edge-computing fragmentation by acquiring specialist combustion optimization software firms before they achieve ERCOT reference installations. For New Entrants and Emerging Players: Anchor in the marine hybrid control segment where classification society mandates for physical backup channels constrain incumbent digital platforms. Target Permian Basin oil and gas operators with explosion-proof edge nodes that reduce helicopter-deployed maintenance. Lead with wireless retrofit kits that slash installation outage windows versus hardwired alternatives. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates where turbine controls represent non-core revenue pools amid energy transition portfolio rebalancing. Five-to-ten year viability hinges on emissions optimization software recurring revenue rather than hardware shipment cyclicality. Watch for FERC Order 2222 aggregation pilots achieving wholesale market revenue certification as the inflection signal for grid-services monetization platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Architecture Deployment | Fragmented intelligence at turbine skids enables millisecond combustion feedback and multi-vendor interoperability. |
| Emissions Optimization Software Licensing | EPA greenhouse gas standards force automated combustion tuning retrofits across ERCOT and PJM zones. |
| SIL 3 Safety Platform Integration | Convergence of control and emergency shutdown functions creates bundled upgrade pathways for utilities. |
| Cybersecurity Certification Investment | NERC CIP mandates require authenticated network segmentation that extends engineering timelines and costs. |
| After-Sales Service Unbundling | Independent power producers now negotiate hardware and maintenance separately through EPC contractors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility control room engineers, EPC procurement managers, OEM aftermarket service directors, and FERC regulatory specialists. Secondary validation drew from EPA enforcement databases, FERC Order 2222 implementation filings, EIA power plant inventories, and NERC CIP compliance bulletins. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation by product architecture, application context, end-user procurement channel, and technology maturity gradient. CAGRs were derived from replacement cycle compression rates and EPA compliance deadline clustering. Forecast inputs included dispatch volatility patterns in ERCOT, LNG export facility construction timelines, and marine classification society rulemaking trajectories.
Material uncertainties — tariff exposure on German and Japanese components, NERC CIP enforcement intensity variations, and FERC Order 2222 aggregation adoption rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology substitution curves and regulatory implementation timelines. Practitioners should keep alternative scenarios live as EPA greenhouse gas standard litigation outcomes and edge-computing interoperability certification evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Germany Power EPC Market
Power Equipment
Europe Power Rental Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Turbine Control Systems Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Middle East Power Filter Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
Thailand Power EPC Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Global Power System Simulator Market
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
Kazakhstan Power EPC Market