
 Hydraulic Diaphragm Valve Market | 2026-2036
Hydraulic Diaphragm Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Diaphragm Valve Market Insights
The EU Green Deal's industrial emissions benchmarks is consolidating procurement standards across European process industries. GEMÜ Gebr. Müller Apparatebau GmbH & Co. KG leverages its Swabian manufacturing base to sustain precision-engineered diaphragm assemblies for pharmaceutical cleanrooms. The Weir Group plc anchors its competitive position through mining slurry expertise that extends into severe-service valve applications. Parker Hannifin Corporation dominates aerospace-derived sealing technologies that it positions for high-pressure hydraulic infrastructure.
A hydraulic diaphragm valve employs a flexible elastomer or PTFE membrane to separate the valve bonnet mechanism from the process fluid, enabling bubble-tight shutoff at pressures up to 300 bar with zero stem leakage. The device serves critical isolation and throttling duties in corrosive, abrasive, or sterile media where conventional packed-stem designs would fail. Pneumatic actuation variants command premium positioning in automated chemical processing skids where remote operation reduces operator exposure. Stainless steel construction leads material selection in power generation feedwater systems, while plastic bodies compete on cost in municipal water treatment chlorination loops.
The EPA enforces maximum contaminant level targets that force municipal utilities into accelerated valve replacement schedules, particularly for lead service line remediation. EMA and FDA sterilization-grade requirements in Europe and the United States mandate surface finish certifications that filter out non-specialist suppliers. China's MEE wastewater discharge rules are tightening allowable effluent concentrations, pushing chemical processors toward higher-reliability isolation equipment. Stakeholders must monitor how divergent regional certification regimes fragment supplier qualification costs and determine whether to pursue multi-jurisdiction approvals or concentrate on single-market dominance.
Market Dynamics
The hydraulic diaphragm valve market faces a structural pivot where zero-emission mandates and precision sterilization requirements are bifurcating demand between commodity municipal water applications and premium pharmaceutical-grade systems. This divergence is compressing mid-tier supplier margins while rewarding specialists with certified cleanroom capabilities.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Municipal utilities across the United States face mandatory replacement timelines for aging distribution infrastructure, accelerating procurement cycles for corrosion-resistant isolation valves in potable water systems.
- Stainless steel diaphragm assemblies:German water treatment utilities specify these components for chlorination skids, prioritizing material traceability and surface finish certifications that exclude lower-tier suppliers.
- MEE effluent standard enforcement:Chemical processors in China's industrial corridor cities must upgrade isolation equipment to meet stricter wastewater discharge limits, driving demand for bubble-tight shutoff capabilities in corrosive media handling.
Market Restraints
- Fluoropolymer membrane cost volatility:PTFE and PFA diaphragm materials face price pressure from semiconductor industry demand competing for limited high-purity resin supply, squeezing valve manufacturer margins.
- Swabian precision manufacturing concentration:Critical pharmaceutical-grade diaphragm assembly production clusters in southwestern Germany, creating geographic supply risk for cleanroom-certified components.
- Pneumatic actuator substitution:Electric actuation systems are displacing compressed-air alternatives in remote automation applications, threatening incumbent valve-actuator bundling strategies.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO sterilization-grade requirements for active pharmaceutical ingredient production create entry points for suppliers with validated surface finish protocols and material certification documentation.
- Hydrogen infrastructure isolation:High-pressure electrolyzer and fueling station applications demand metal-diaphragm valves rated for 700 bar hydrogen service, opening adjacent market development for severe-service specialists.
- EU Green Deal industrial emissions benchmarks:Process industry consolidation around unified procurement standards reduces fragmentation costs for suppliers achieving multi-jurisdiction certification coverage.
Industry Challenges
- Multi-jurisdiction qualification timelines:EMA, FDA, and NMPA sterilization-grade surface finish certifications require parallel validation studies, extending product commercialization cycles and consuming engineering resources.
- Legacy distributed control system integration:Automated valve skids must interface with decades-old SCADA architectures in municipal water facilities, complicating digital positioner deployment and remote diagnostics implementation.
- Specialized welding technician scarcity:Orbital welding certification for high-purity diaphragm valve assembly remains concentrated among aging European and North American workforces, constraining cleanroom production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Diaphragm Valve Market |
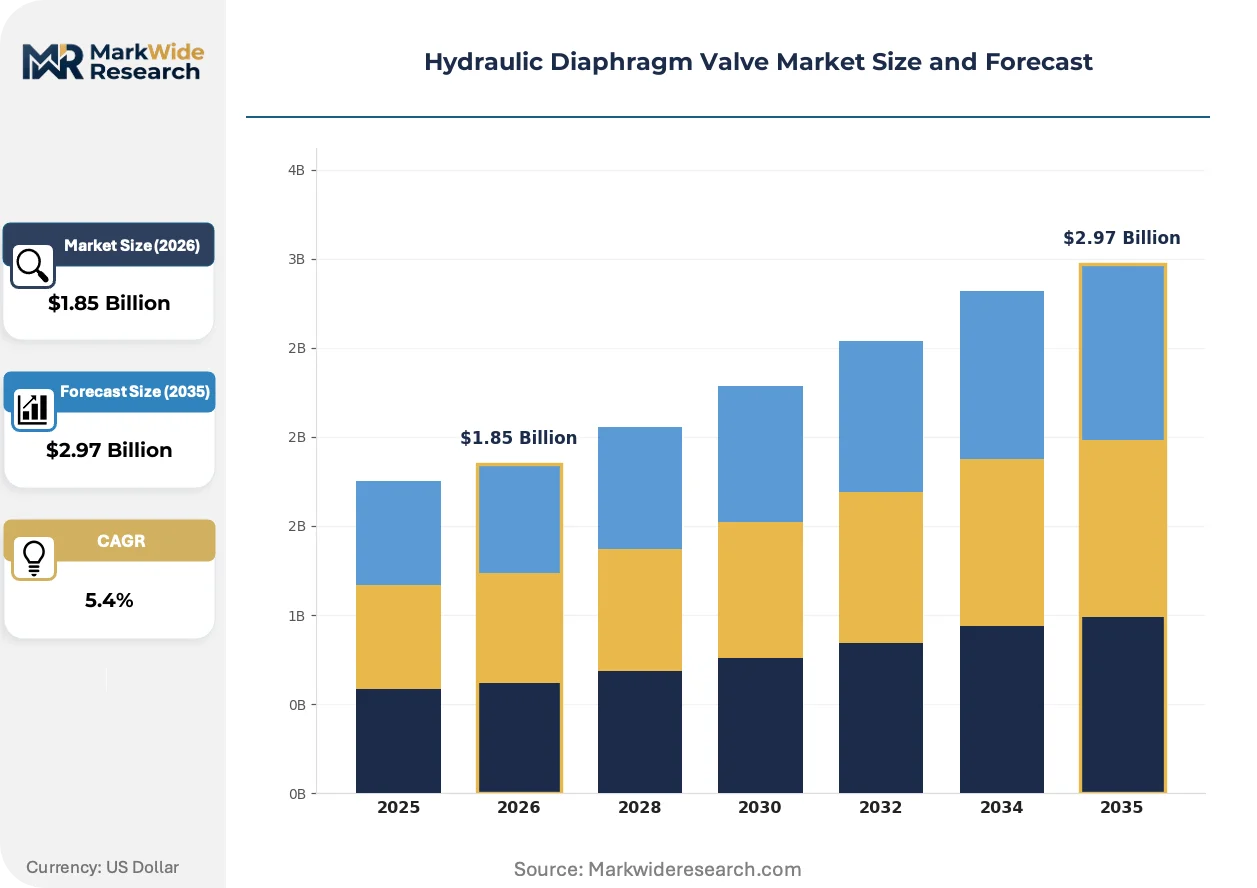
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Pneumatic, Actuated End User: Water Treatment, Oil & Gas, Chemical Processing, Power Generation Material: Plastic, Stainless Steel, Cast Iron, Bronze Application: Fluid Control, Flow Regulation, Pressure Management, Isolation |
| Companies Covered | CRANE ChemPharma & Energy, The Weir Group plc, GEMÜ Gebr. Müller Apparatebau GmbH & Co. KG, Parker Hannifin Corporation, Pentair PLC, ITT Inc., LIANKE, Georg Fischer AG, Nippon Daiya Valve Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Diaphragm Valve Market Trends and Innovations
Smart positioner integration and predictive maintenance architectures are redefining valve lifecycle economics, shifting buyer evaluation criteria from upfront capital cost toward total cost of ownership metrics across extended service intervals.
PTFE-composite diaphragm laminates with embedded fiber reinforcement are integrating into severe-service chemical processing applications. Refinery operators and chlor-alkali producers specify these materials for extended cycle life in abrasive slurry handling. This material transition is integrating predictive replacement scheduling based on diaphragm wear telemetry rather than fixed maintenance intervals.
The EU F-Gas Regulation phase-down is compressing availability of perfluorinated sealing compounds used in traditional diaphragm formulations. Valve manufacturers must qualify alternative elastomer compounds or engineered thermoplastics for equivalent chemical resistance profiles. Pharmaceutical cleanroom applications in Ireland and Switzerland face the tightest compliance timelines given their concentration of sterile API production.
Water utilities in the United States are unbundling valve supply from installation and commissioning services, separating equipment procurement from field integration. Municipal purchasing departments now direct-buy from certified manufacturers while contracting specialized integrators for site-specific adaptation. This disintermediation is most pronounced in California and Texas where utility consolidation has centralized procurement authority at state or regional district levels.
Hydraulic Diaphragm Valve Market Segmentation
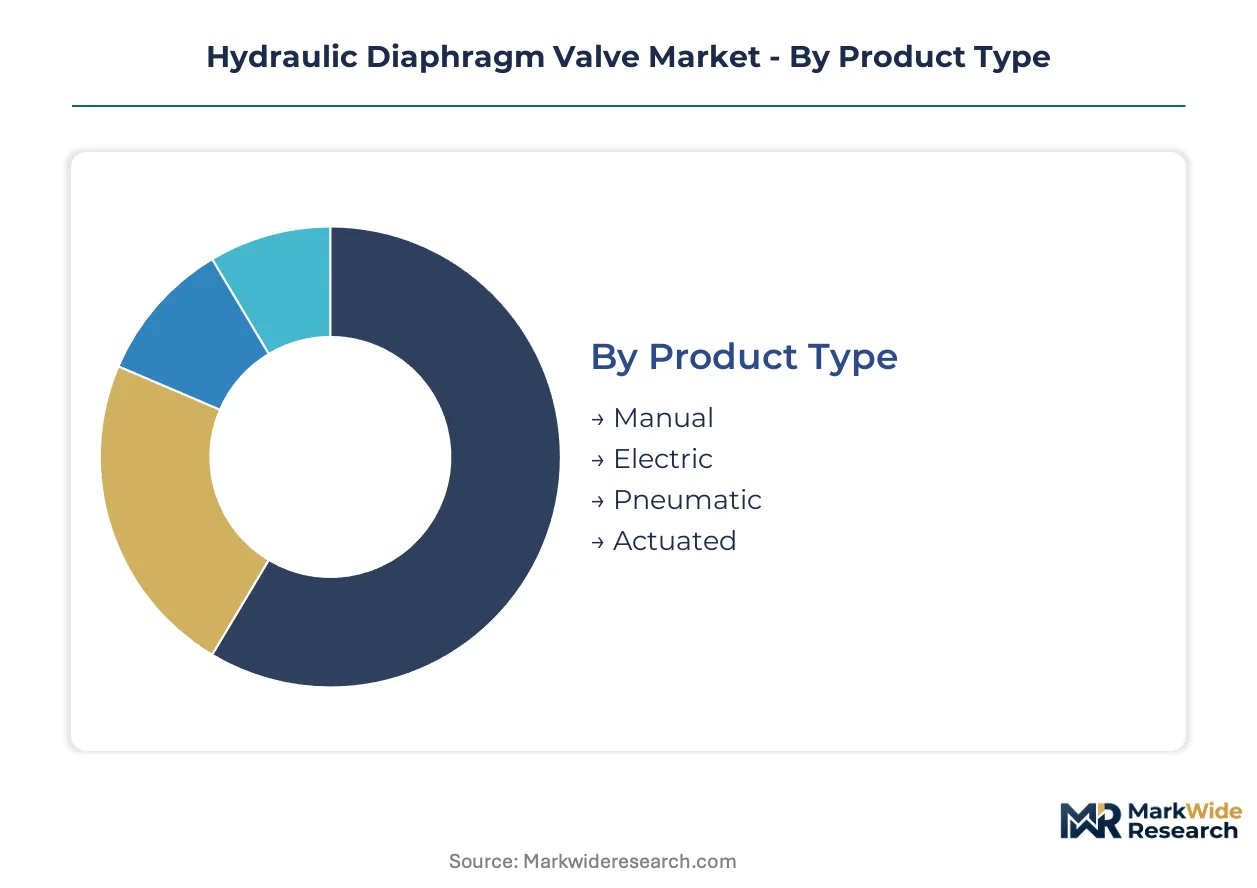
Segmentation in the hydraulic diaphragm valve market maps directly to certification burden and procurement authority concentration. Buyers with sterilization-grade requirements impose surface finish protocols that filter supplier pools, while municipal utilities prioritize material traceability over precision engineering.
Product Type:
Pneumatic and electric actuation variants carry divergent regulatory loads, with pneumatic systems dominating pharmaceutical cleanrooms under EMA sterilization protocols while electric actuators face FCC electromagnetic compliance for remote automation.
- Pneumatic:Compressed-air actuation achieves bubble-tight shutoff at pressures up to 300 bar with zero stem leakage, serving critical isolation in corrosive media. German pharmaceutical cleanrooms specify these variants under EMA surface finish certifications, prioritizing remote operation that reduces operator exposure to hazardous process fluids.
- Electric:Motor-driven actuation integrates digital positioners for predictive maintenance architectures, shifting lifecycle economics toward total cost of ownership metrics. Municipal water utilities in California and Texas specify electric variants for SCADA integration, though legacy distributed control system compatibility complicates deployment in aging infrastructure.
- Manual:Handwheel-operated designs compete on first cost in low-cycle municipal applications where automation premiums cannot be justified.
- Actuated:Pre-integrated valve-actuator skids reduce field commissioning complexity for chemical processing expansions in China's industrial corridor cities.
Pneumatic sits at the top of the volume ranking, with electric climbing the fastest.
End User:
End-user concentration determines margin structure, with pharmaceutical-grade water treatment commanding certification premiums while oil and gas applications prioritize severe-service durability.
- Water Treatment:Municipal utilities face EPA Lead and Copper Rule replacement timelines that accelerate procurement cycles for corrosion-resistant isolation valves. German chlorination systems specify stainless steel diaphragm assemblies with full material traceability, excluding lower-tier suppliers from specification.
- Chemical Processing:China's MEE effluent standards force upgrades to bubble-tight shutoff equipment in abrasive slurry handling, with PTFE-composite diaphragm laminates extending cycle life in chlor-alkali production.
- Oil & Gas:Severe-service applications demand metal-diaphragm construction for high-pressure hydrogen infrastructure and refinery isolation duties.
- Power Generation:Feedwater systems specify stainless steel construction under ASME pressure vessel codes, with surface finish requirements less stringent than pharmaceutical grades.
Water treatment captures the largest revenue share, with chemical processing expanding most quickly.
Material:
Material selection bifurcates between precision-engineered metal alloys for sterilization-grade applications and cost-optimized polymers for municipal infrastructure.
- Stainless Steel:Austenitic grades dominate pharmaceutical cleanrooms and power generation feedwater systems, with surface finish certifications under EMA and FDA protocols filtering out non-specialist suppliers. Full material traceability requirements concentrate procurement among Swabian precision manufacturers.
- Plastic:PVC and PTFE bodies compete on installed cost in municipal chlorination loops where chemical resistance outweighs pressure rating requirements.
- Cast Iron:Ductile iron construction serves low-pressure water distribution replacement cycles under EPA infrastructure mandates.
- Bronze:Naval brass alloys resist dezincification in seawater cooling applications for coastal power plants.
Stainless steel leads revenue contribution, with plastic gaining share fastest in municipal cost-constrained procurement.
Application:
Application scope determines actuator specification and diaphragm material qualification, with isolation duties imposing the strictest leak-tightness standards.
- Isolation:Zero-leakage requirements in sterile API production mandate PTFE or elastomer diaphragm separation between bonnet mechanism and process fluid, with EMA and FDA surface finish certifications extending commercialization timelines.
- Flow Regulation:Throttling applications in chemical processing require engineered diaphragm geometries that maintain linear flow characteristics across pressure differentials, with embedded fiber reinforcement extending service intervals.
- Fluid Control:General-purpose on-off service in water treatment prioritizes cycle life over precision, with pneumatic actuation variants bundling remote operation capability.
- Pressure Management:Surge suppression and relief functions in distribution networks specify rapid-response actuation with position feedback for SCADA integration.
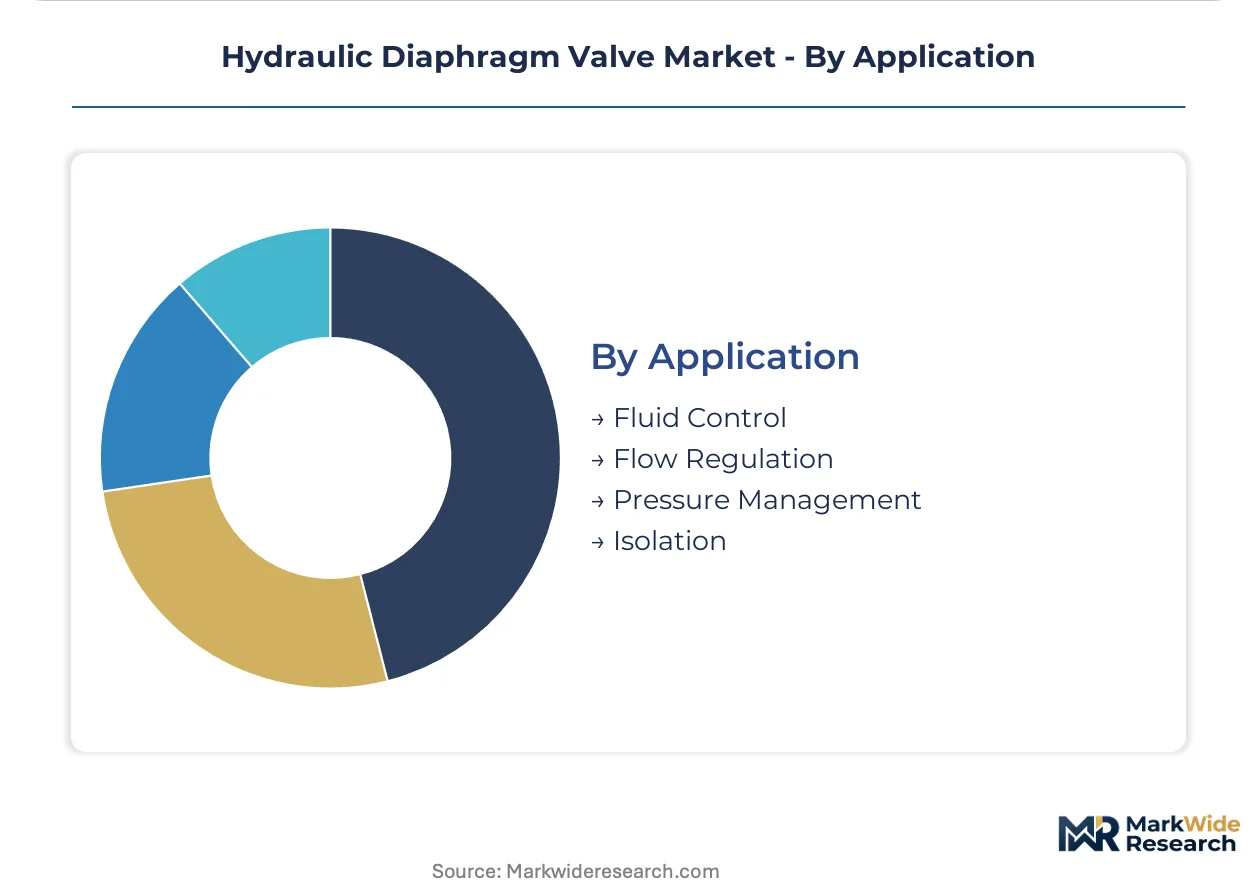
Isolation commands the highest unit margins, with flow regulation showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orbital welding technicians with cleanroom certifications concentrate in southwestern Germany and the Great Lakes region of the United States, anchoring precision diaphragm assembly production for sterilization-grade applications. Their geographic clustering shapes regional supply capabilities and qualification timelines for pharmaceutical-grade valve systems.
United States
Municipal utilities in California and Texas face EPA Lead and Copper Rule replacement mandates that accelerate procurement cycles for corrosion-resistant isolation valves. The EPA enforces maximum contaminant level targets that force accelerated valve replacement schedules across aging distribution networks. Water utilities in the Southwest are unbundling valve supply from installation services, centralizing procurement authority at regional district levels.
Germany
Swabian precision manufacturers in Baden-Württemberg sustain pharmaceutical-grade diaphragm assembly production with full material traceability protocols. The EU Green Deal's industrial emissions benchmarks consolidate procurement standards across European process industries. Municipal water treatment utilities in Bavaria and North Rhine-Westphalia are expanding procurement of stainless steel diaphragm valves for chlorination systems.
China
Chemical processors in the Yangtze River Delta industrial corridor must upgrade isolation equipment to meet stricter MEE wastewater discharge limits. The Ministry of Ecology and Environment enforces tightening allowable effluent concentrations that push processors toward higher-reliability isolation equipment. Capacity expansion in Shanghai and Jiangsu province is driving demand for bubble-tight shutoff capabilities in corrosive media handling.
Switzerland
Sterile API production facilities in Basel and Zurich face compressed compliance timelines under the EU F-Gas Regulation phase-down of perfluorinated sealing compounds. Swissmedic mandates sterilization-grade surface finish certifications that filter supplier pools to specialists with validated protocols. Pharmaceutical cleanroom applications in the Basel-Land region concentrate demand for PTFE-composite diaphragm laminates with embedded fiber reinforcement.
India
Active pharmaceutical ingredient manufacturers in Maharashtra and Gujarat confront CDSCO sterilization-grade requirements that create entry points for suppliers with validated surface finish protocols. The country's national pharmaceutical regulator imposes documentation standards that parallel EMA and FDA protocols. Production expansion in the Mumbai-Pune pharmaceutical belt is concentrating demand for diaphragm valves with material certification documentation.
Hydraulic Diaphragm Valve Market Competitive Landscape
Capital-heavy producers with captive foundry and precision machining capabilities compete with asset-light designers that outsource diaphragm assembly to certified contract manufacturers. The market structure bifurcates between integrated specialists commanding pharmaceutical-grade premiums and volume players serving municipal water replacement cycles. Three archetypes dominate: Swabian precision engineers with cleanroom certification heritage, diversified flow control conglomerates leveraging mining or aerospace adjacencies, and Asian fabricators competing on cost-optimized plastic-body designs. Competitive moves center on multi-jurisdiction qualification investments and predictive maintenance technology partnerships.
Among diversified industrial conglomerates, The Weir Group plc and Parker Hannifin Corporation occupy positions that exemplify adjacency-driven market participation. GEMÜ Gebr. Müller Apparatebau GmbH & Co. KG represents the Swabian precision engineering archetype, anchoring the specialist tier through its manufacturing base in southwestern Germany. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without requiring specific product or technology claims.
| Leading Market Players |
|---|
| CRANE ChemPharma & Energy |
| The Weir Group plc |
| GEMÜ Gebr. Müller Apparatebau GmbH & Co. KG |
| Parker Hannifin Corporation |
| Pentair PLC |
| ITT Inc. |
| LIANKE |
| Georg Fischer AG |
| Nippon Daiya Valve Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation phase-down gates both qualified supply and premium-tier pricing access, compressing availability of perfluorinated sealing compounds while elevating certification costs for pharmaceutical-grade diaphragm formulations. Buyers seeking EMA-validated surface finish protocols face extended qualification timelines that concentrate procurement power among Swabian precision manufacturers with captive cleanroom capabilities.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across municipal and industrial tiers. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cleanroom certifications from power generation feedwater specifications and cost-optimized plastic-body municipal designs. Price differentiation hinges on material traceability documentation and after-sales commissioning bundling. Cost compression in standard-tier electric actuation variants is intensifying because pneumatic-to-electric substitution threatens incumbent valve-actuator bundling strategies. Municipal water utilities in California and Texas exhibit highest price sensitivity, while German pharmaceutical cleanrooms absorb premium positioning for validated orbital welding protocols.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EMA sterilization-grade buyers mandate multi-supplier qualification, fragmenting procurement across Swabian precision manufacturers, diversified flow control conglomerates, and Asian fabricators. Geographic supply concentration centers on Germany, China, and the United States, with critical diaphragm assembly production anchored in Baden-Württemberg. Raw material dependencies draw from high-purity PTFE resin, austenitic stainless steel forgings, and specialized elastomer compounds. Single-source vulnerability concentrates in orbital welding technicians with cleanroom certifications, whose aging European and North American workforces constrain production scaling. Distribution runs through OEM direct sales for pharmaceutical-grade systems and regional distributor networks for municipal water replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier pharmaceutical certifications and predictive maintenance technology partnerships, with cost-down potential from diaphragm wear telemetry reducing fixed-interval replacement overhead.
For Market Incumbents: Cement defensive positioning through backward integration into high-purity PTFE-composite diaphragm laminate production and multi-jurisdiction certification investments spanning EMA, FDA, and NMPA protocols. Electric actuator substitution threatens pneumatic bundling strategies; counter via predictive maintenance architecture partnerships that shift buyer evaluation toward total cost of ownership metrics. For New Entrants and Emerging Players: Launch via certified contract manufacturing partnerships targeting India's CDSCO sterilization-grade requirements for active pharmaceutical ingredient production. White-space concentration appears in hydrogen infrastructure isolation rated for 700 bar service and municipal water utility consolidation in Texas and California where procurement authority centralization favors agile suppliers. For Investors and Strategic Acquirers: Roll-up economics work for asset-light designers with validated surface finish protocols because multi-jurisdiction qualification investments create barriers that concentrate value in certification heritage. Five-to-ten year viability favors acquisition of Swabian precision engineering specialists with captive cleanroom capabilities. Signal to monitor: CDSCO enforcement intensity in Maharashtra and Gujarat pharmaceutical corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Investment | EMA, FDA, and NMPA parallel validation reduces fragmentation costs for pharmaceutical-grade suppliers. |
| Predictive Maintenance Technology Partnership | Diaphragm wear telemetry integration shifts buyer criteria from capital cost toward lifecycle economics. |
| Backward Integration into Diaphragm Materials | Captive PTFE-composite laminate production insulates margins from semiconductor industry resin competition. |
| Hydrogen Infrastructure Product Development | 700 bar metal-diaphragm qualification opens adjacent severe-service applications in electrolyzer isolation. |
| Orbital Welding Technician Certification Programs | Workforce pipeline expansion addresses cleanroom production scaling constraints in pharmaceutical supply. |
Research Methodology
Coverage spans Germany, the United States, China, Switzerland, and India, with primary inputs from each market combined through structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and municipal water utility purchasing directors. Secondary validation draws from EPA enforcement databases, EMA sterilization-grade certification registries, MEE effluent standard filings, and customs trade data for valve component flows. Bottom-up demand modeling and top-down industry sizing triangulate volume and value outputs.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include actuation type, end-user industry, material grade, and application duty, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from fitted trend extrapolation adjusted for policy-driven replacement cycle acceleration. Industry-specific forecast inputs incorporate EPA Lead and Copper Rule replacement timelines and MEE wastewater discharge enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under fluoropolymer membrane cost volatility and orbital welding technician availability constraints. Deviation in EU F-Gas Regulation phase-down timelines or CDSCO enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Steel Cylinder Market
Valves
Total Containment Vessels Market
Valves
Motorized Valves Market
Valves
Blow - Off Valves Market
Valves
Portable Valve Actuator Market
Valves
Blasting Stemming Plugs Market
Valves
Dense Phase Vessels Market
Valves
Global Stainless Steel Control Valves Market
Valves
Explosion Vents Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Pipeline and Process Services Market
Valves
Emergency Shutdown Valves Market
Valves
Flare Stack Monitoring Systems Market
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Air Heated Vaporizer Market
Valves
Pneumatic Slide Gates Market