
 SCR Power Controller Market | 2026-2036
SCR Power Controller Market Size, Share, and Industry Trends Forecast 2026-2036
SCR Power Controller Market Analysis
Market Dynamics
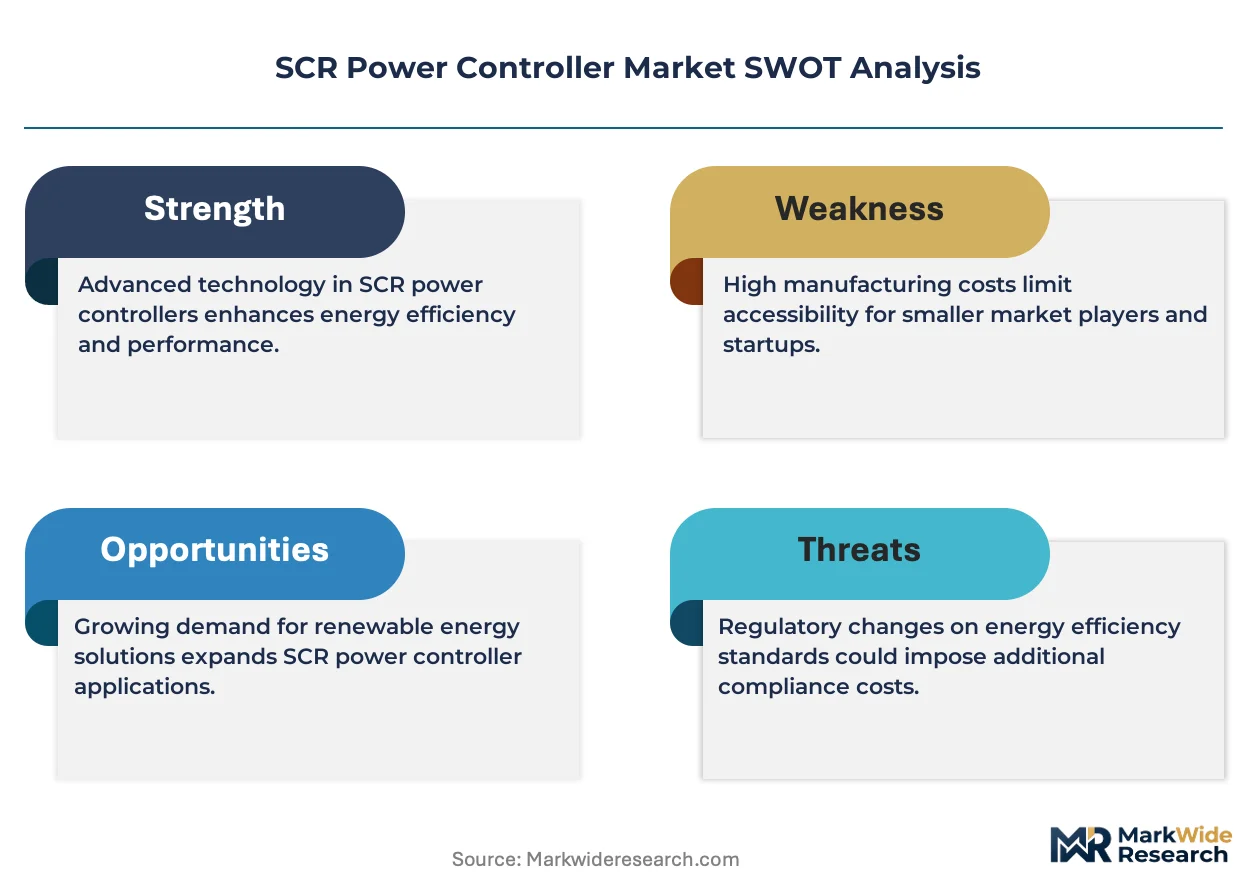
Silicon carbide (SiC) and gallium nitride (GaN) power semiconductor integration is fragmenting the traditional thyristor-dominated architecture into hybrid and full-SiC platforms. ABB Ltd. leverages its installed base in heavy industry to sustain retrofit demand across European steel and chemical plants. Mitsubishi Electric Corporation anchors Asian supply chains through captive silicon wafer capacity and localized controller production. Advanced Energy Industries, Inc. differentiates via precision power delivery systems for semiconductor fabrication equipment.
Technology and Segmentation
An SCR power controller modulates alternating current flow to resistive or inductive loads through phase-angle or burst-fire triggering of silicon-controlled rectifiers, typically handling voltages from 120V to 600V and currents exceeding 1,000A in industrial configurations. Three-phase controllers dominate heavy manufacturing applications where load balancing and harmonic reduction prove critical, while smart controllers with embedded diagnostics and IoT connectivity represent the fastest-expanding margin pool. Digital control technology is displacing analog architectures in HVAC and lighting applications where programmable setpoints and energy metering integrate with building management systems.
Regulatory Environment
The EU Ecodesign Directive and F-Gas Regulation compel controller manufacturers to certify efficiency tiers and refrigerant leak detection compatibility in climate equipment. In the United States, OSHA electrical safety standards and NHTSA automotive EMC requirements shape product validation protocols for industrial and transportation-adjacent deployments. China's GB standards and MIIT energy-efficiency labeling mandate local testing before market entry. Stakeholders must monitor how impending carbon border adjustments and semiconductor export controls recalibrate sourcing strategies for thyristor die and heat sink assemblies.
Market Dynamics
Silicon carbide and gallium nitride power semiconductors are fragmenting the traditional thyristor architecture, forcing incumbent suppliers to recalibrate their product portfolios and manufacturing footprints around hybrid and full-wide-bandgap platforms.
Growth Catalysts
- EU F-Gas Regulation:Mandates for refrigerant leak detection and energy-efficiency certification in climate equipment are accelerating replacement cycles across European HVAC installations.
- Industrial electrification:China's MIIT energy-efficiency labeling and domestic semiconductor capacity expansion are concentrating procurement of three-phase and microcontroller-based units in heavy manufacturing clusters.
- Smart controller architectures:Embedded diagnostics and IoT connectivity are expanding margin pools as building management systems demand programmable setpoints and real-time energy metering.
Market Restraints
- Thyristor die supply concentration:Captive silicon wafer capacity in Asia creates sourcing vulnerability for European and North American controller assemblers.
- Analog-to-digital transition costs:The capex required to retool production lines for digital control platforms strains mid-tier manufacturers with limited R&D budgets.
- Solid-state relay substitution:Lower-cost SSRs are capturing price-sensitive applications in lighting and small-motor control below 100A.
Strategic Opportunities
- Semiconductor fabrication equipment:Precision power delivery requirements in advanced node manufacturing create demand for ultra-stable phase-angle controllers.
- Retrofit demand in European steel:ABB's installed base in heavy industry sustains aftermarket revenue as plants modernize aging electromechanical systems.
- Carbon border adjustment mechanisms:Impending EU CBAM regulations will reward locally manufactured controllers with verified low-carbon heat sink assemblies.
Industry Challenges
- Wide-bandgap power electronics expertise:The scarcity of engineers proficient in SiC and GaN device characterization and thermal management is constraining product development timelines.
- Multi-standard certification complexity:Controllers must simultaneously satisfy OSHA electrical safety, NHTSA automotive EMC, and China's GB standards before cross-border deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SCR Power Controller Market |
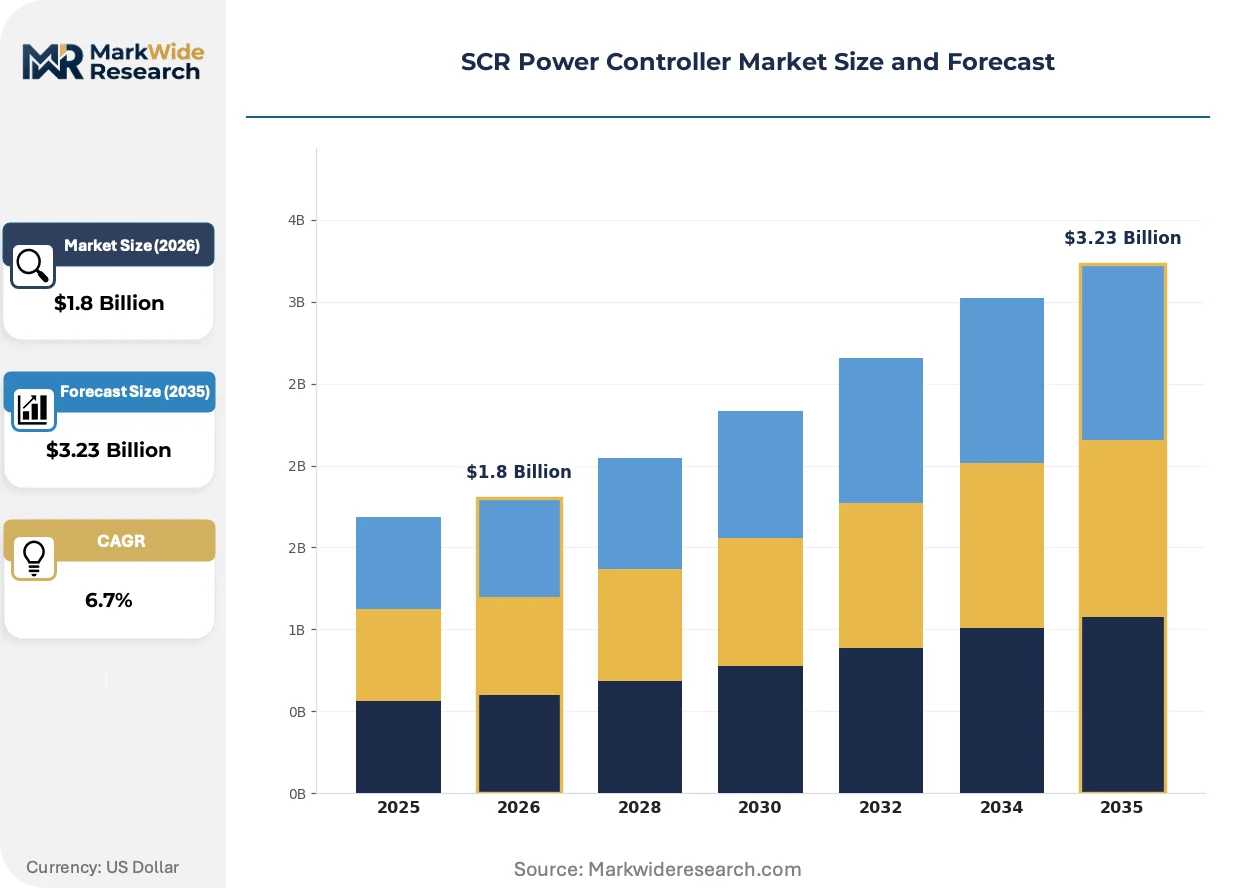
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase Controllers, Three-Phase Controllers, Smart Controllers, Modular Controllers Application: Industrial Automation, HVAC Systems, Home Appliances, Lighting Control End User: Manufacturing, Energy Sector, Residential, Commercial Technology: Analog Control, Digital Control, Microcontroller-Based, Wireless Control |
| Companies Covered | AMETEK, Mitsubishi Electric Corporation, ABB Ltd., Omron Corporation, Honeywell International Inc., Schneider Electric SE, Eaton Corporation plc, Advanced Energy Industries, Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SCR Power Controller Market Emerging Trajectories
Power semiconductor material transitions and digital control architectures are compressing product lifecycles while regulatory pressure on energy efficiency is redefining competitive differentiation across industrial, commercial, and transportation-adjacent applications.
Hybrid SiC-thyristor modules are rendering obsolete pure silicon phase-angle controllers in high-frequency heating applications above 10kHz. Induction furnace operators in Germany and Japan are adopting these platforms to reduce switching losses and shrink heat sink volumes. The technology is rendering obsolete traditional analog gate drivers that cannot support the faster switching speeds and tighter protection windows.
REACH substance restrictions and RoHS recast directives are compelling controller manufacturers to eliminate leaded solder and hexavalent chromium plating from heat sink assemblies. The industrial consequence is a supply chain scramble for compliant thermal interface materials and alternative surface finishes. HVAC and refrigeration OEMs in the European Union are responding by qualifying new supplier tiers and extending validation cycles.
Buyers are consolidating vendor relationships and demanding integrated power delivery systems rather than discrete controllers. System integrators in North American automotive battery manufacturing are displacing component distributors with direct manufacturer partnerships that bundle thermal design, EMI filtering, and commissioning support. This pattern is most visible in Michigan and South Carolina where gigafactory construction is concentrating procurement authority among a handful of plant engineering teams.
SCR Power Controller Market Segmentation
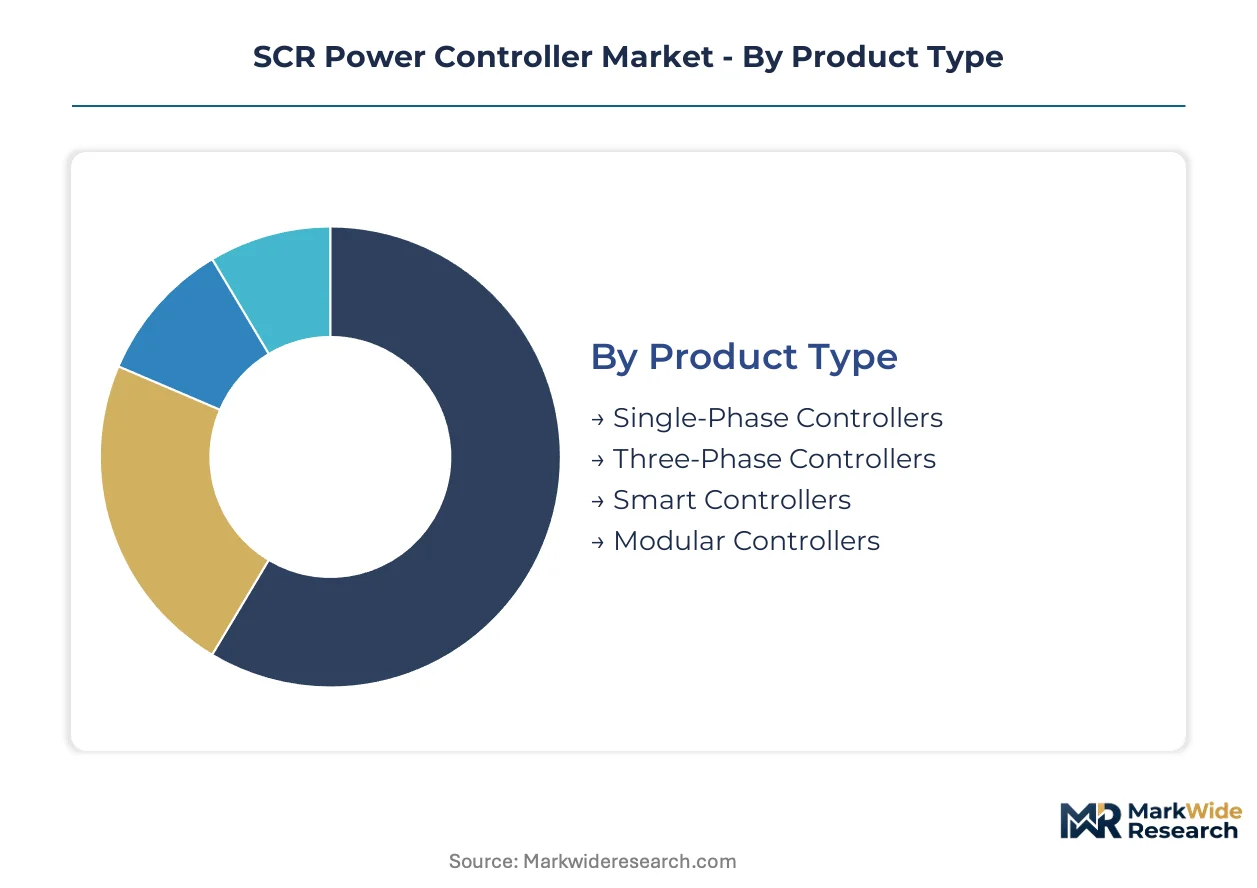
SCR power controller segmentation reveals how technical specifications, deployment environments, and control architectures determine procurement patterns. After-sales service intensity varies sharply across categories, with industrial three-phase units demanding field commissioning support while residential single-phase products rely on distributor networks.
Product Type:
After-sales service intensity climbs with unit complexity and downtime costs, creating divergent margin structures across the four product architectures.
- Three-Phase Controllers:These units handle currents exceeding 1,000A across 380V to 600V industrial feeds, employing six-thyristor bridge configurations with forced-air or liquid cooling. Demand concentrates in China's Yangtze River Delta manufacturing belt where MIIT energy-efficiency labeling drives replacement of electromechanical contactors in steel and chemical plants.
- Smart Controllers:Embedded diagnostics, IoT connectivity, and programmable setpoints define this architecture, enabling integration with building management systems and predictive maintenance platforms. European HVAC OEMs in Germany and Poland are specifying these units to satisfy EU F-Gas Regulation leak-detection mandates and real-time energy metering requirements.
- Single-Phase Controllers:Compact units for 120V to 240V residential and light commercial loads, typically rated below 100A with natural convection cooling.
- Modular Controllers:Scalable rack-mounted systems allowing field expansion of power stages through standardized thyristor modules.
Three-phase controllers hold the largest share; momentum sits with smart controllers.
Application:
Cost tier differentiation separates premium precision-heating installations from price-sensitive residential lighting deployments.
- Industrial Automation:Phase-angle and burst-fire triggering of resistive and inductive loads in packaging lines, extrusion equipment, and heat-treatment furnaces. German automotive suppliers in Bavaria and Baden-Württemberg are retrofitting aging electromechanical systems with digital controllers to reduce harmonic distortion and improve power factor.
- HVAC Systems:Compressor soft-start, fan speed modulation, and electric heat control in commercial and institutional buildings. US contractors in Texas and Florida are specifying digital architectures with BACnet integration to meet ASHRAE 90.1 efficiency standards and utility demand-response programs.
- Home Appliances:Cooktop power regulation, water heater control, and clothes dryer heating elements in consumer white goods.
- Lighting Control:Dimmer circuits for incandescent and LED loads in theatrical, architectural, and residential settings.
Industrial automation commands the premium tier; HVAC systems are expanding most quickly.
End User:
Customer type determines procurement authority, with energy utilities centralizing specifications while residential buyers delegate to contractor channels.
- Manufacturing:Heavy industry deployments requiring load balancing, harmonic reduction, and integration with SCADA systems. Japanese automotive and electronics producers are adopting hybrid SiC-thyristor modules to shrink heat sink volumes in high-frequency heating above 10kHz.
- Energy Sector:Grid-connected battery storage, solar inverter coupling, and electric vehicle charging infrastructure. US independent power producers in California and Texas are procuring three-phase units with IEEE 1547 compliance for distributed generation interconnection.
- Residential:Single-phase controllers for water heaters, HVAC equipment, and pool pumps through retail and contractor channels.
- Commercial:Office buildings, hospitals, and retail centers specifying digital controllers with energy metering for LEED certification and utility rebate programs.
Manufacturing absorbs the highest unit volumes; the energy sector shows the steepest expansion trajectory.
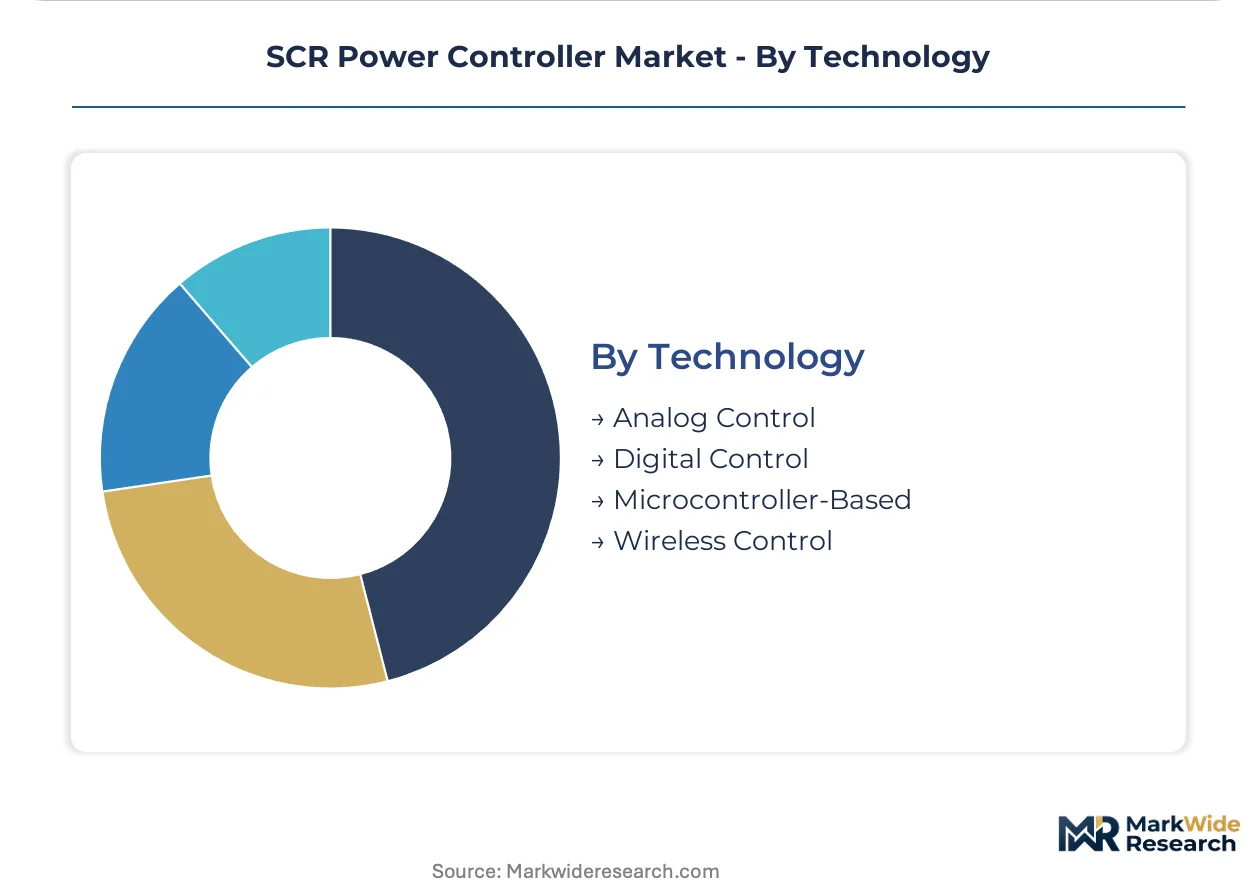
Technology:
Supply concentration in digital signal processors and wide-bandgap semiconductors is restructuring competitive positioning across control architectures.
- Digital Control:Microprocessor-based phase-angle computation with EEPROM-stored setpoints, serial communication, and adaptive firing algorithms. REACH substance restrictions and RoHS recast directives are forcing redesigns of analog gate driver assemblies in European-sourced equipment.
- Microcontroller-Based:ARM Cortex or proprietary MCU cores executing PID loops, fault protection, and communication protocols in a single device. Chinese controller assemblers are migrating to domestic MCU suppliers to mitigate semiconductor export control exposure.
- Analog Control:Discrete op-amp and comparator circuits with potentiometer adjustment, now relegated to cost-sensitive replacement markets.
- Wireless Control:Wi-Fi, Zigbee, or proprietary RF interfaces enabling smartphone and cloud-based setpoint adjustment.
Digital control dominates current procurement; microcontroller-based architectures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority concentrates with industrial automation integrators in Germany, heavy manufacturing clusters in China, and energy infrastructure developers in the United States. These buyer archetypes drive divergent product specifications across voltage classes and control architectures. Regulatory pressure on energy efficiency and carbon intensity is reshaping supplier qualification criteria in each market.
China
MIIT energy-efficiency labeling and domestic semiconductor capacity expansion are accelerating replacement of electromechanical contactors in steel and chemical plants. The Yangtze River Delta manufacturing belt concentrates demand for three-phase controllers exceeding 1,000A. Local controller assemblers are migrating to domestic MCU suppliers to mitigate semiconductor export control exposure.
Germany
Industrial electrification mandates and REACH substance restrictions are forcing redesigns of analog gate driver assemblies in European-sourced equipment. The EU F-Gas Regulation compels HVAC OEMs to specify smart controllers with leak-detection compatibility. Bavarian and Baden-Württemberg automotive suppliers are retrofitting aging systems with digital architectures to reduce harmonic distortion.
United States
OSHA electrical safety standards and IEEE 1547 compliance requirements shape validation protocols for grid-connected battery storage and solar inverter coupling. Independent power producers in California and Texas are procuring three-phase units for distributed generation interconnection. Michigan and South Carolina gigafactory construction is concentrating procurement authority among plant engineering teams demanding bundled power delivery systems.
Japan
METI industrial efficiency targets and JIS standards certification requirements are driving adoption of hybrid SiC-thyristor modules in high-frequency heating above 10kHz. Kanto and Kansai manufacturing corridors anchor demand from automotive and electronics producers seeking to shrink heat sink volumes. Domestic captive silicon wafer capacity insulates supply chains from thyristor die sourcing vulnerability.
India
CEA grid codes and state-level industrial electrification programs are expanding addressable demand for motor control and precision heating equipment. Gujarat and Maharashtra heavy manufacturing clusters are specifying three-phase controllers with forced-air cooling for load-balancing applications. BIS certification mandates are extending validation cycles for imported controller assemblies.
SCR Power Controller Market Vendor Landscape
Channel-controlling players compete with product-specialist players for specification authority in industrial automation and energy infrastructure verticals. The vendor base organizes around three strategic archetypes: diversified electrical conglomerates with captive silicon capacity, precision power delivery specialists serving semiconductor fabrication, and regional controller assemblers with cost-optimized analog platforms. Dominant competitive moves include backward integration into thyristor die sourcing and technology licensing partnerships for wide-bandgap power electronics.
Among diversified electrical conglomerates, ABB Ltd., Mitsubishi Electric Corporation, and Siemens AG exemplify the integrated-manufacturer archetype with established installed bases in heavy industry retrofit markets. These entities occupy positions where captive component supply and field service networks reinforce specification authority with plant engineering teams. Precision power delivery specialists such as Advanced Energy Industries, Inc. represent the technology-differentiated tier, anchoring demand from semiconductor fabrication equipment OEMs requiring ultra-stable phase-angle control. Regional assemblers and component distributors compete on cost-optimized platforms for price-sensitive applications below 100A.
| Leading Market Players |
|---|
| AMETEK |
| Mitsubishi Electric Corporation |
| ABB Ltd. |
| Omron Corporation |
| Honeywell International Inc. |
| Schneider Electric SE |
| Eaton Corporation plc |
| Advanced Energy Industries, Inc. |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor anchors cost dynamics for thyristor die and heat sink assemblies, where container rate volatility feeds directly into landed cost differentials between Asian captive-silicon suppliers and European controller assemblers seeking alternative sourcing. This logistics tension amplifies price spreads across premium certified tiers and economy-grade alternatives while forcing procurement teams to weight inventory carrying costs against single-source concentration risk.
Pricing Analysis
Cost-plus contracts with copper and silicon indexation dominate procurement of three-phase controllers above 1,000A, with pricing stratifying across IEC-certified premium tiers, CE-marked standard configurations, and uncertified economy units for replacement markets. Price differentiation hinges on thermal performance grade and after-sales commissioning bundling, with pressure intensifying in sub-100A segments where solid-state relays capture lighting and small-motor applications. Manufacturing buyers show lowest price sensitivity due to downtime costs, while residential contractors delegate decisions to distributor channels with tight margin expectations.
Supply Chain Analysis
Upstream silicon wafer feedstock concentrates in Japan, China, and South Korea, where captive thyristor die production creates sourcing asymmetry for European and North American controller manufacturers. The supply chain draws from high-purity silicon ingots, copper busbar extrusions, and ceramic substrate laminates, with single-source vulnerability concentrated in 300mm wafer processing for wide-bandgap semiconductors. Distribution runs through authorized industrial distributors for field-serviceable three-phase units and big-box retail channels for single-phase residential products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SCR power controller market sits in early-cycle expansion as industrial electrification programs and F-Gas Regulation compliance deadlines accelerate replacement of electromechanical contactors with digital architectures. Penetration headroom remains substantial in building management system integration and predictive maintenance platforms.
For Market Incumbents: Build switching-cost moats through embedded diagnostics and IoT connectivity that locks plant engineering teams into proprietary commissioning protocols. Defensive moves center on backward integration into silicon carbide wafer sourcing to secure hybrid module supply, plus certification pre-investment for impending EU carbon border adjustments. The threat of gallium nitride substitution in high-frequency heating demands R&D allocation to wide-bandgap gate driver expertise before capability scarcity hardens. For New Entrants and Emerging Players: Pursue white-space capture in semiconductor fabrication equipment power delivery, where precision phase-angle stability requirements create specification barriers too steep for diversified electrical conglomerates. Target North American automotive battery gigafactory construction clusters in Michigan and South Carolina, where bundled thermal design and EMI filtering contracts displace component distributors. A direct manufacturer partnership model with plant engineering teams offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core power electronics divisions with stranded analog controller portfolios. Long-term viability favors precision power delivery specialists with semiconductor fabrication equipment relationships over regional assemblers dependent on price-sensitive replacement markets. The signal to watch is qualification timelines for hybrid SiC-thyristor modules in induction furnace applications above 10kHz, as adoption velocity there indicates architecture transition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Wafer Sourcing | Captive supply of silicon carbide substrates insulates hybrid module production from export control exposure and thyristor die concentration. |
| Smart Controller Certification Investment | EU F-Gas Regulation leak-detection compatibility opens specification authority with German and Polish HVAC OEMs. |
| Precision Power Delivery Partnership | Direct relationships with semiconductor fabrication equipment OEMs in California and Texas secure ultra-stable phase-angle controller demand. |
| Carbon Border Adjustment Readiness | Verified low-carbon heat sink assemblies position European manufacturers for impending EU CBAM preference. |
| Domestic MCU Supplier Migration | Chinese controller assemblers reduce semiconductor export control risk by qualifying local ARM Cortex alternatives. |
Methodological Framework
Initial hypotheses were tested against primary input from plant engineering directors, HVAC OEM procurement leads, power semiconductor R&D heads, and industrial distributor account managers, then refined through secondary validation against SEC 10-K filings, MIIT energy-efficiency labeling databases, EU Ecodesign Directive compliance registries, and customs trade data for thyristor module imports. Bottom-up unit demand modeling and top-down market sizing triangulation converged on segment-level estimates across product architectures and control technologies.
Demand-supply balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product type, application vertical, end-user category, and technology architecture including analog, digital, microcontroller-based, and wireless control platforms. CAGRs derived from installed base replacement cycles, regulatory compliance deadlines, and penetration curves for smart controller connectivity. Industry-specific forecast inputs incorporated MIIT labeling enforcement timelines and EU F-Gas Regulation phase-out schedules.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, semiconductor equipment spending, or carbon border adjustment implementation pace would shift the trajectory. Forecasts reflect assumptions about technology transition speed and regulatory enforcement consistency. Cross-checking against IEA industrial electrification projections and national manufacturing investment announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Air Preheater Market
Power Equipment
India Nuclear Power Plant Equipment Market
Power Equipment
Levant Power Cable Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Turbine Governor Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Wind Turbine Bolts Market
Power Equipment
China Power EPC Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Process Air Heater Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Global Power System Simulator Market