
 Vietnam Power EPC Market | 2026-2036
Vietnam Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Power EPC Market Analytics
Project finance with limited-recourse structures is fragmenting the competitive landscape for Vietnam power EPC contracts. Samsung C&T leverages its balance sheet strength to anchor mega-project bids requiring multibillion-dollar capital commitments. Lilama Corporation sustains domestic market share through backward integration into civil works and localized equipment sourcing. Doosan Enerbility differentiates on thermal technology leadership while navigating the shift toward gas-to-power and combined-cycle configurations.
Vietnam Power EPC encompasses the integrated engineering, procurement, and construction of power generation and transmission infrastructure, typically involving turbine-generator sets rated from 50 MW to over 1,000 MW, high-voltage switchgear, and 220-500 kV substation integration. The primary purpose is delivering turnkey power assets that synchronize with Vietnam's national grid code and frequency stability requirements. Mega Projects command disproportionate margin pools due to complexity premiums and extended contract durations, while Renewable technology segments attract accelerated developer interest under feed-in tariff mechanisms. Procurement services face margin compression from standardized equipment sourcing, whereas Commissioning activities retain pricing power given scarcity of certified grid-integration specialists.
Vietnam's Ministry of Industry and Trade implements Power Development Plan VIII, which mandates technology localization ratios and environmental impact thresholds for new capacity. The country's national construction quality standards, administered by the Vietnam Register, govern structural safety and electrical installation protocols for thermal and renewable plants. CEA guidelines on grid interconnection shape equipment specification requirements and testing protocols. Stakeholders must monitor regulatory clarity on direct power purchase agreements and rooftop solar frameworks to anticipate shifts in contract structures and offtake risk allocation.
Market Dynamics
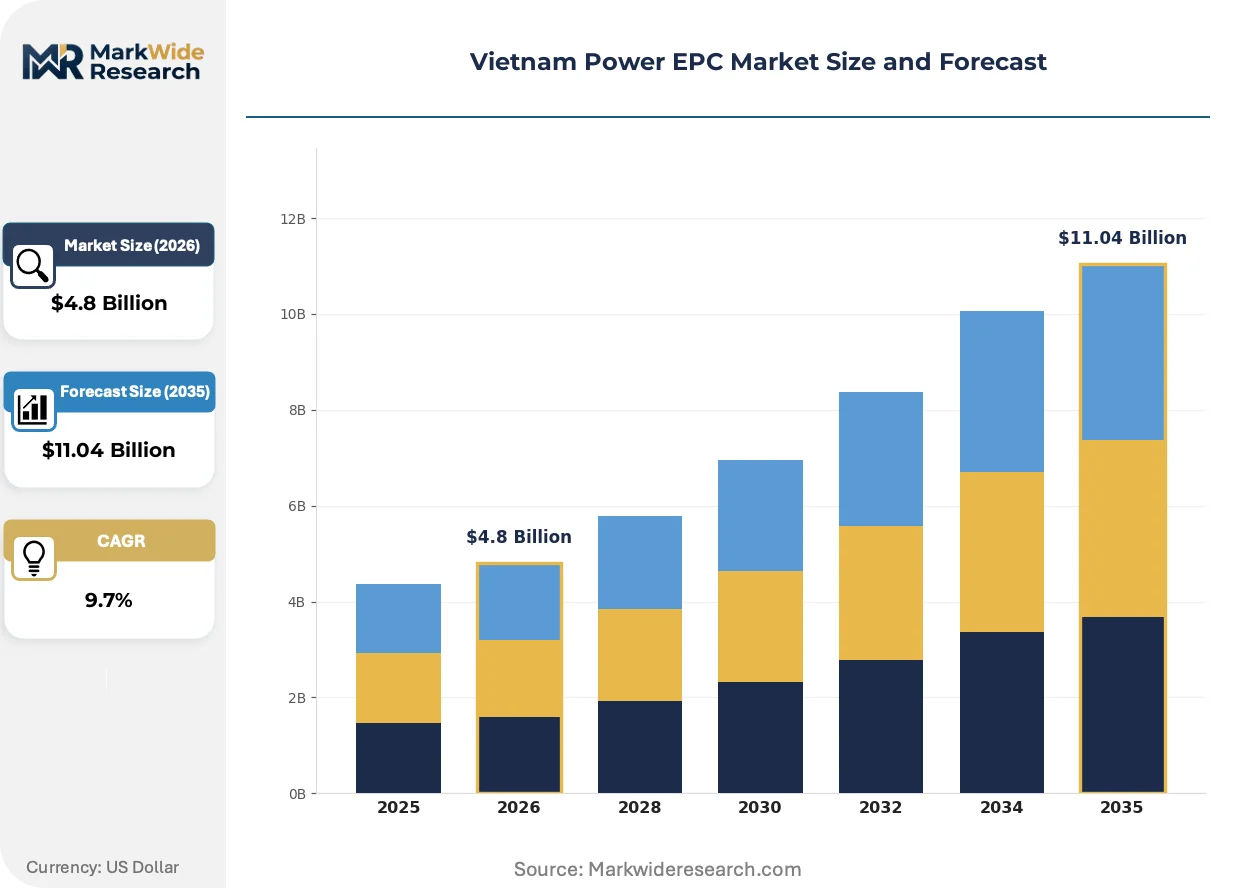
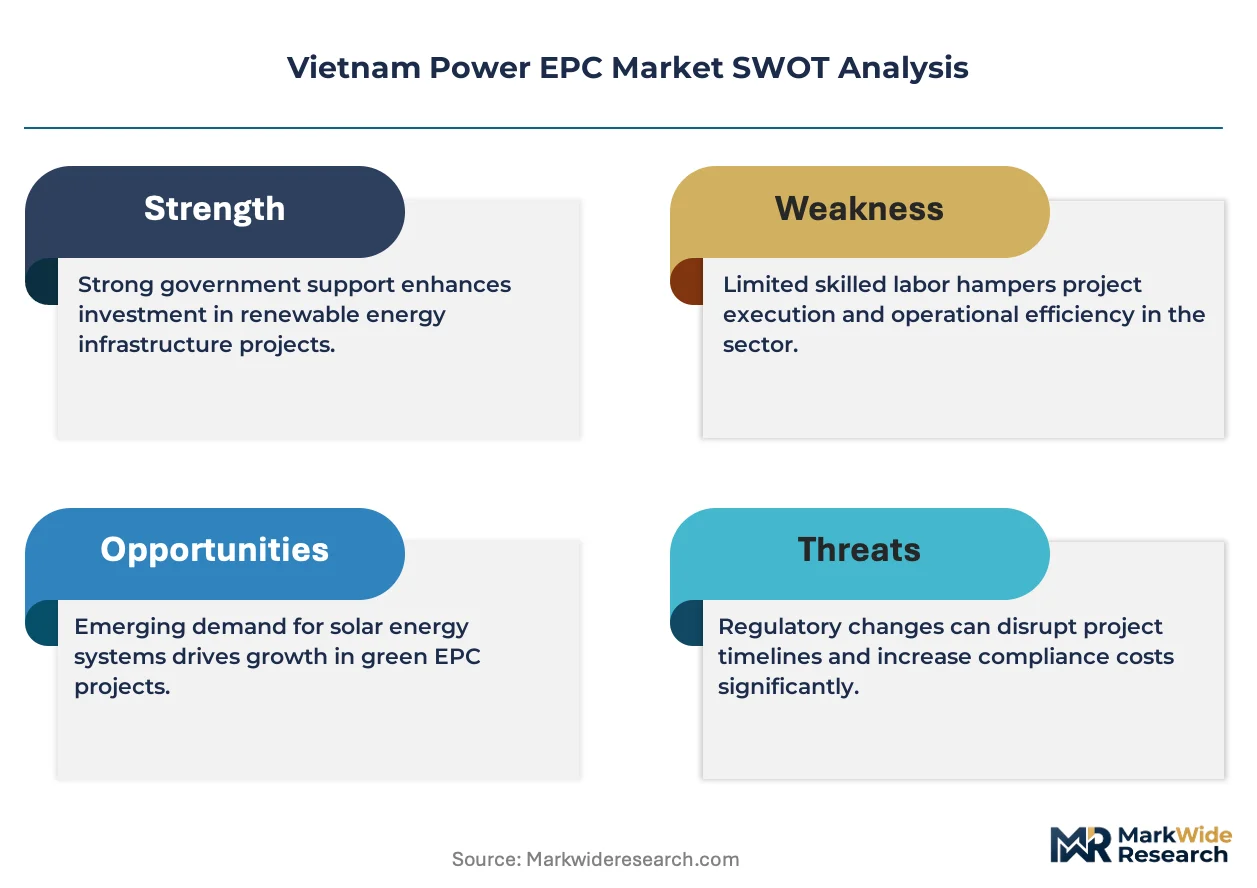
Power Development Plan VIII is compressing project timelines while mandating stricter localization ratios, forcing EPC contractors to restructure supplier networks and civil works capabilities simultaneously.
Growth Catalysts
- Feed-in tariff mechanisms:Vietnam's Ministry of Industry and Trade maintains preferential pricing frameworks for solar and wind installations, accelerating developer commitment to grid-scale renewable projects.
- Southern economic corridor load centers:Industrial zones spanning Ho Chi Minh City and Ba Ria-Vung Tau province concentrate manufacturing demand, requiring substantial transmission reinforcement and generation capacity.
- Gas-to-power transition:LNG import infrastructure expansion enables combined-cycle turbine deployment, replacing aging coal baseload with lower-emission thermal alternatives.
Market Restraints
- Steel and copper input volatility:Switchgear fabrication and transmission tower construction face margin erosion from commodity price swings, complicating fixed-price EPC bidding.
- Equipment import dependency:Turbine-generator sets and 500kV transformers rely on concentrated Northeast Asian supply bases, exposing projects to shipping bottlenecks and currency fluctuation.
- Grid interconnection queues:CEA technical standards create multi-month testing protocols, extending commissioning schedules and inflating working capital requirements.
Strategic Opportunities
- Direct power purchase agreement frameworks:Regulatory clarity on corporate renewable sourcing enables bilateral contracting models, diversifying offtake risk beyond state utility offtakers.
- Rooftop solar integration:Commercial and industrial facilities seek behind-the-meter generation paired with grid backup, opening distributed EPC service lines.
- Digital substation automation:IEC 61850 protocol adoption creates upgrade demand across existing 220kV infrastructure, blending hardware installation with software commissioning.
Industry Challenges
- Certified grid-integration specialist scarcity:Frequency synchronization and protection system testing require engineers with Vietnam Register accreditation, constraining project staffing.
- Legacy coal plant retrofit coordination:Existing thermal assets demand emissions control upgrades while maintaining operational continuity, complicating construction sequencing.
- Cross-border equipment specification disputes:Divergent standards between Korean, Japanese, and European turbine suppliers generate technical interface risks during multi-vendor procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Power EPC Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design, Construction, Procurement, Commissioning Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Technology: Renewable, Conventional, Hybrid, Advanced End User: Utilities, Industrial, Commercial, Government |
| Companies Covered | JGC Holdings Corporation, AES Corporation, IHI Infrastructure Systems, Samsung C&T, CTCI Corporation, Toshiba Corporation, Lilama Corporation, Song Da Corporation, Doosan Enerbility, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Power EPC Market Evolving Landscape
Technology convergence between renewable generation and grid stabilization equipment is redefining contractor capability requirements and procurement specifications across Vietnam's power infrastructure pipeline.
Floating solar photovoltaic systems are penetrating reservoirs and coastal lagoons previously excluded from land-based development. State-owned utilities pilot 500MW-class installations on hydropower dam surfaces, testing mooring engineering and corrosion-resistant cabling. This technology is hybridizing terrestrial EPC expertise with offshore construction methods, compressing the addressable market for pure-play solar installers.
Vietnam's Ministry of Industry and Trade enforces Power Development Plan VIII localization mandates requiring minimum domestic content ratios for wind tower fabrication and electrical assembly. Foreign EPC consortia must partner with Lilama Corporation or comparable domestic civil contractors to satisfy procurement rules. Thermal project developers respond by pre-qualifying Vietnamese steel fabricators and cable manufacturers during front-end engineering.
Industrial offtakers increasingly unbundle long-term service contracts from initial construction agreements, selecting specialized O&M providers independently of EPC selection. Manufacturing facilities in Dong Nai and Binh Duong provinces negotiate separate predictive maintenance subscriptions for turbine-generator assets. This pattern concentrates most visibly among semiconductor and electronics manufacturers with internal energy management capabilities.
Vietnam Power EPC Market Segmentation
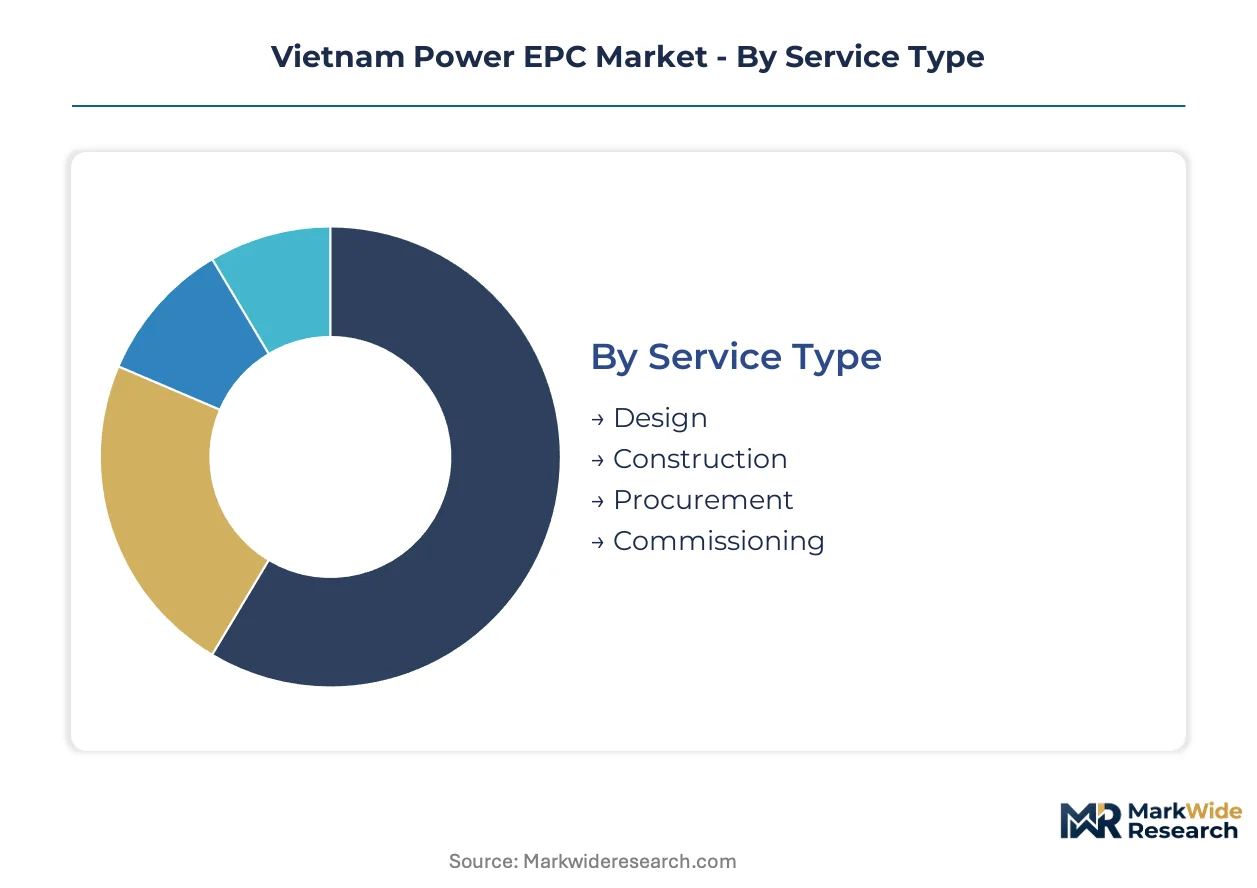
Segmentation reveals how contract structures, technology choices, and client risk appetites diverge across Vietnam's power infrastructure pipeline. EPC contractors must calibrate capability investments to capture margin pools that concentrate unevenly across service lines and project scales.
Service Type:
After-sales service intensity varies dramatically across the EPC value chain, with post-construction obligations driving long-term margin retention for specialized providers.
- Design:Front-end engineering packages specify turbine ratings, switchgear configurations, and grid synchronization protocols. Southern economic corridor developers prioritize firms with Vietnam Register accreditation for 500kV substation integration, where design errors cascade into commissioning delays.
- Construction:Civil works, structural erection, and mechanical installation absorb the largest labor deployment. Lilama Corporation leverages backward integration into steel fabrication and concrete batching to meet Power Development Plan VIII localization mandates while protecting margin.
- Procurement:Equipment sourcing spans turbine-generator sets from Northeast Asian suppliers and domestic cable manufacturers. Standardized switchgear procurement faces persistent margin compression from transparent international pricing benchmarks.
- Commissioning:Grid interconnection testing, frequency synchronization, and protection system validation require scarce certified specialists. CEA technical standards create multi-month protocol queues, extending working capital cycles and retaining pricing power for accredited engineers.
By volume, Construction leads. By growth pace, Commissioning is ahead.
Project Size:
Cost tier stratification determines bidder qualification thresholds and financing structure complexity, with capital scale dictating consortium composition and risk allocation mechanisms.
- Small Scale:Distributed generation below 50 MW and 220kV substation upgrades. Industrial zones in Dong Nai province drive demand for rapid-deployment gas turbines and behind-the-meter solar integration.
- Medium Scale:Single-unit thermal plants and 100-300 MW renewable clusters. Developers in Ba Ria-Vung Tau province favor fixed-price contracts with limited-recourse project finance structures.
- Large Scale:Multi-unit combined-cycle facilities and 500 MW-class wind farms. Samsung C&T deploys balance sheet capacity to anchor bids requiring multibillion-dollar capital commitments.
- Mega Projects:Integrated LNG-to-power complexes and 1,000 MW+ generation hubs. Complexity premiums and extended durations attract global EPC consortia seeking disproportionate margin pools.
Contract frequency peaks in Medium Scale. Mega Projects claim the steepest expansion trajectory as Power Development Plan VIII accelerates grid-scale procurement.
Technology:
Application-specific engineering requirements fragment contractor capabilities, with technology maturity determining localization feasibility and import dependency exposure.
- Renewable:Solar photovoltaic, onshore wind, and floating solar systems dominate capacity additions. State-owned utilities pilot 500 MW-class floating installations on hydropower reservoirs, hybridizing terrestrial EPC expertise with offshore mooring engineering.
- Conventional:Coal and gas-fired thermal plants with steam and combustion turbine configurations. Aging baseload assets require emissions control retrofits while maintaining operational continuity, complicating construction sequencing.
- Hybrid:Solar-plus-storage and wind-gas combinations addressing grid stability requirements. Battery integration demands power electronics specialization beyond traditional EPC scopes.
- Advanced:Hydrogen-ready turbines, carbon capture retrofits, and digital substation automation with IEC 61850 protocols. Early-stage deployment concentrates in demonstration projects with technology transfer obligations.
Renewable dominates current capacity awards. Advanced technology is gaining share fastest as feed-in tariff mechanisms mature and developers seek differentiation.
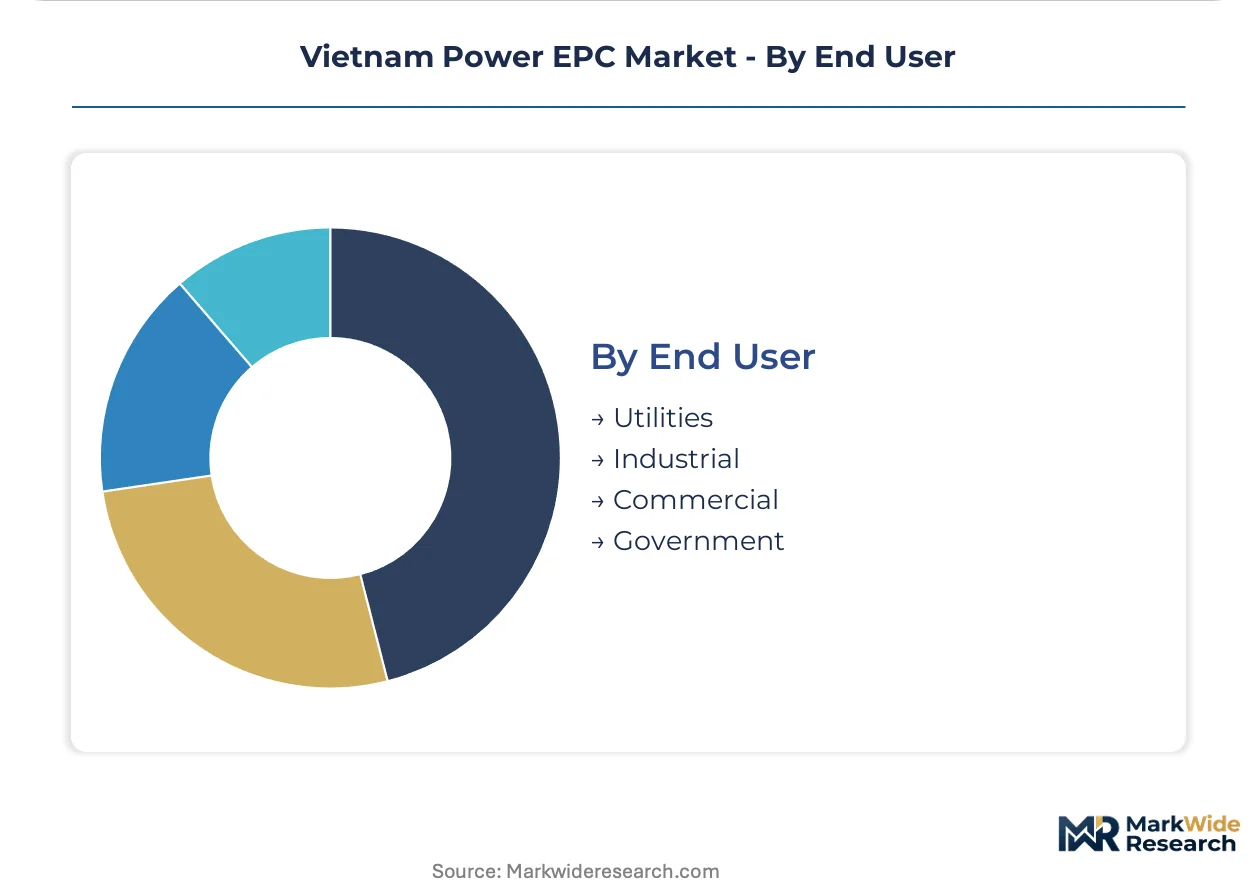
End User:
Customer type determines risk allocation preferences, contract duration tolerance, and in-house technical capabilities that shape EPC scope unbundling decisions.
- Utilities:State-owned generation companies and regional power corporations anchor procurement volume. Power Development Plan VIII mandates integrated EPC packages with strict localization ratios and environmental thresholds.
- Industrial:Semiconductor, electronics, and steel manufacturers in Binh Duong province. These offtakers increasingly unbundle O&M contracts from construction agreements, negotiating separate predictive maintenance subscriptions.
- Commercial:Data centers, logistics facilities, and retail complexes seeking rooftop solar with grid backup. Behind-the-meter generation opens distributed EPC service lines with shorter development cycles.
- Government:Military installations, public infrastructure, and rural electrification programs. Direct budget financing reduces project finance complexity while imposing rigid procurement timelines.
Utilities command the largest contract value. Industrial is climbing the fastest as direct power purchase agreement frameworks enable bilateral renewable sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's power infrastructure import dependency for turbine-generator sets and 500kV transformers creates persistent trade imbalances that shape regional procurement strategies. Equipment sourcing concentrates in Northeast Asian manufacturing bases, exposing projects to currency fluctuation and shipping bottlenecks.
Northern Delta Region
Hanoi and Hai Phong anchor grid-scale solar and combined-cycle gas projects under Power Development Plan VIII mandates. The Ministry of Industry and Trade enforces localization ratios requiring domestic content in wind tower fabrication. Bac Ninh province hosts manufacturing clusters where Samsung C&T anchors multibillion-dollar capital commitments for LNG-to-power complexes.
Central Highlands
Wind resource concentration in Gia Lai and Dak Lak provinces drives 100-300 MW renewable cluster development. Feed-in tariff mechanisms from the Ministry of Industry and Trade accelerate developer commitment despite grid interconnection queues. Quy Nhon port facilities handle turbine component imports facing multi-month CEA technical standard testing protocols.
Southern Economic Corridor
Ho Chi Minh City and Ba Ria-Vung Tau province concentrate industrial zone demand requiring transmission reinforcement and generation capacity. Direct power purchase agreement frameworks enable bilateral renewable sourcing for semiconductor and electronics manufacturers. Dong Nai province facilities negotiate separate predictive maintenance subscriptions unbundled from construction agreements.
Mekong Delta
Floating solar photovoltaic systems penetrate reservoirs previously excluded from land-based development. State-owned utilities pilot 500MW-class installations on hydropower dam surfaces, hybridizing terrestrial EPC expertise with offshore mooring engineering. Can Tho province serves as logistics hub for corrosion-resistant cabling deployment.
Vietnam Power EPC Market Competitive Landscape
On the supply side, the industry is bifurcated between balance-sheet-heavy conglomerates capable of anchoring mega-project finance and specialized domestic contractors leveraging localization mandates. Korean and Japanese industrial groups dominate thermal technology and high-voltage equipment integration. Vietnamese state-linked enterprises capture civil works and localized procurement through backward integration into steel fabrication. Competitive positioning hinges on multibillion-dollar capital deployment capacity and Vietnam Register accreditation for grid synchronization protocols.
Among Korean-Japanese industrial conglomerates, Samsung C&T and Doosan Enerbility occupy positions defined by thermal technology leadership and combined-cycle configuration expertise. Within the domestic contractor tier, Lilama Corporation exemplifies localization strategy through captive supply of civil works and equipment sourcing. Toshiba Corporation anchors the precision equipment integration segment where 500kV substation protocols demand scarce certified specialists.
| Leading Market Players |
|---|
| JGC Holdings Corporation |
| AES Corporation |
| IHI Infrastructure Systems |
| Samsung C&T |
| CTCI Corporation |
| Toshiba Corporation |
| Lilama Corporation |
| Song Da Corporation |
| Doosan Enerbility |
| Others |
Value Network & Pricing Analysis
Northeast Asian turbine-generator manufacturing concentration feeds directly into margin stratification across Vietnam's EPC contract tiers, with equipment import dependency compressing procurement service returns while commissioning premiums expand.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing differentiation across premium, standard, and economy service levels, with Vietnam Register accreditation for 500kV substation integration commanding certification premiums. Price differentiation hinges on localization ratio compliance and after-sales service bundling, with foreign consortia absorbing margin compression to meet Power Development Plan VIII domestic content mandates. Cost compression in standardized switchgear procurement is intensifying because transparent international pricing benchmarks eliminate information asymmetries. State-owned utilities demonstrate lowest price sensitivity given sovereign balance sheet backing, while commercial rooftop solar developers exhibit highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Export-control regimes on precision power electronics and high-voltage transformer technology limit flows from Japanese and Korean manufacturing bases into Vietnamese project sites. Geographic supply concentration centers on China, South Korea, and Japan for turbine-generator sets, 500kV transformers, and switchgear assemblies. Raw material dependencies span Vietnamese domestic steel for tower fabrication, copper from Chilean and Indonesian mining operations, and specialized insulation compounds from German chemical suppliers. Single-source vulnerability permeates 500kV transformer procurement given concentrated Northeast Asian manufacturing capacity. Distribution runs through Ho Chi Minh City port facilities and overland corridors to Bac Ninh and Ba Ria-Vung Tau project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's power infrastructure market is approaching a platform-economics inflection as IEC 61850 protocol standardization creates interoperability requirements that reshape contractor capability stacks and procurement specifications.
For Market Incumbents: Insulate margin position by deepening captive supply of civil works through backward integration into concrete batching and steel fabrication, mirroring Lilama Corporation's localization playbook. Acquire Vietnam Register accreditation for grid synchronization protocols to defend commissioning premium pools against emerging specialized engineering boutiques. Samsung C&T's balance sheet deployment for multibillion-dollar LNG-to-power complexes demonstrates how capital scale creates bid qualification barriers. For New Entrants and Emerging Players: Build out distributed EPC service lines targeting commercial and industrial rooftop solar integration in Dong Nai and Binh Duong provinces, where behind-the-meter generation demand outpaces established contractor coverage. Floating solar mooring engineering represents the most penetrable technology segment, hybridizing terrestrial construction expertise with offshore methods that pure-play solar installers cannot replicate. Pursue direct power purchase agreement frameworks as the primary go-to-market angle, enabling bilateral corporate renewable sourcing that bypasses state utility procurement queues. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Korean-Japanese industrial conglomerates seeking to monetize thermal technology portfolios amid Vietnam's gas-to-power transition. Long-term viability over the coming decade hinges on exposure to renewable capacity additions and grid modernization rather than legacy coal baseload. Target acquisition archetype: mid-scale EPC contractors with Vietnam Register accreditation and established relationships with domestic steel fabricators. Watch regulatory clarity on direct power purchase agreement implementation as the signal indicating accelerated unbundling of offtake risk from state utility balance sheets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Civil Works | Lilama Corporation demonstrates how captive steel fabrication protects margin against Power Development Plan VIII localization mandates. |
| Vietnam Register Accreditation Investment | Certified grid-integration specialists command pricing power given scarcity of engineers qualified for 500kV substation protocols. |
| Floating Solar Capability Buildout | State-owned utilities pilot 500MW-class reservoir installations that hybridize terrestrial EPC expertise with offshore mooring engineering. |
| Direct Power Purchase Agreement Positioning | Bilateral corporate renewable sourcing enables offtake risk diversification beyond state utility procurement for Ba Ria-Vung Tau manufacturers. |
| Digital Substation Automation Partnership | IEC 61850 protocol adoption across 220kV infrastructure blends hardware installation with software commissioning for recurring revenue streams. |
Research Methodology
Initial hypotheses were tested against primary input from EPC contract managers, utility planning officers, IPP project developers, and grid operators and refined through secondary validation against Power Development Plan VIII policy documents, CEA technical standards filings, Vietnam Register accreditation databases, and customs import records for turbine-generator sets. Bottom-up project pipeline aggregation was triangulated with top-down macroeconomic load growth assumptions.
Demand-supply balance dynamics across Vietnam's power infrastructure pipeline shaped the analytical framework, with segmentation modeled by service type, project scale tier, technology category, and end-user archetype across the projection horizon. CAGRs were derived from capacity addition schedules and contract award velocity. Forecast inputs incorporated feed-in tariff mechanism adjustments, LNG import infrastructure buildout timelines, and grid interconnection queue clearance rates.
Stress conditions across commodity price volatility, currency fluctuation, and regulatory clarity timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Power Development Plan VIII implementation pace and CEA technical standard evolution. Material shifts in direct power purchase agreement regulatory frameworks or floating solar technology cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Egypt Power EPC Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Power Generation Equipment MRO Market
Power Equipment
Digital Power Conversion Market
Power Equipment
SCR Power Controller Market
Power Equipment
China Power EPC Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Asia-Pacific SCR Power Controller Market
Power Equipment
Qatar Power EPC Market
Power Equipment
France Power EPC Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Portable Power Station Market
Power Equipment
Turbine Control Systems Market