
 Tumblers Market | 2026-2036
Tumblers Market Size, Share, and Industry Trends Forecast 2026-2036
Tumblers Market Intelligence
The base of buyers for premium tumblers is shifting from niche outdoor enthusiasts to a broader mainstream consumer audience. YETI leverages its strong brand identity to command premium pricing in this expanded market. Stanley capitalizes on its legacy status and viral social media trends to reach new demographics. Newell Brands competes across multiple price points through its diverse portfolio, including the Thermos brand.
Tumblers are insulated beverage containers, typically featuring double-wall vacuum construction to maintain liquid temperature for extended periods. Their primary function is providing portable, reusable drinkware for hot or cold beverages. Stainless steel remains the dominant material type due to its durability and thermal performance, though bamboo and recycled plastics gain traction on sustainability merits. While personal use and outdoor activities form the largest application base, corporate gifting represents the fastest-growing segment, demanding high customization.
Product safety standards are governed by food-contact material regulations, including those from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). Compliance with these frameworks, alongside China's GB standards for plastics and metals, is essential for market access and consumer trust. Future brand differentiation will depend on navigating material science innovations while adhering to evolving environmental marketing claims guidelines from bodies like the FTC.
Market Dynamics
The central dynamic shaping the tumblers market is the tension between its mainstream consumer adoption and the technical requirements of a performance product. This shift forces manufacturers to balance mass-market aesthetics and cost pressures against stringent food-contact safety regulations and durability expectations.
Growth Catalysts
- Corporate Gifting:The corporate gifting segment's expansion fuels demand for tumblers with extensive customization options, including co-branding and unique colorways.
- Wellness Culture:A focus on hydration and health encourages consumers to carry reusable beverage containers, directly benefiting the personal use application segment.
- Sustainability Focus:Consumer and regulatory pressure to reduce single-use plastic waste creates demand for durable alternatives like stainless steel and emerging bio-based materials.
Market Restraints
- Material Price Volatility:Fluctuations in the price of high-grade stainless steel, a primary raw material, create margin pressure and sourcing instability for manufacturers.
- Regulatory Fragmentation:Navigating disparate food-contact material standards, such as FDA rules in the US, EFSA in Europe, and GB standards in China, increases compliance costs.
- Counterfeit Goods:The proliferation of low-cost, non-compliant counterfeit products erodes brand value and poses safety risks, undermining consumer trust in the market.
Strategic Opportunities
- Smart Technology Integration:Incorporating features like temperature sensors, hydration tracking, or self-cleaning capabilities into tumblers opens a new premium product segment for tech-savvy consumers.
- Circular Economy Programs:Establishing take-back, refurbishment, or certified recycling programs for end-of-life tumblers can enhance brand loyalty and meet sustainability goals.
- New Application Niches:Developing specialized tumblers for specific uses, such as preparing infant formula or mixing nutritional supplements, can capture new, targeted customer segments.
Industry Challenges
- Supply Chain Verification:Ensuring the authenticity and grade of materials like recycled stainless steel or plastics is a complex challenge required to substantiate environmental claims.
- Marketing Claim Substantiation:Adhering to evolving guidelines from bodies like the FTC on environmental marketing requires significant investment in lifecycle analysis and data verification to avoid legal risks.
- Design Patent Enforcement:Protecting unique design elements and proprietary mechanisms from infringement in a crowded global market requires constant vigilance and significant legal resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumblers Market |
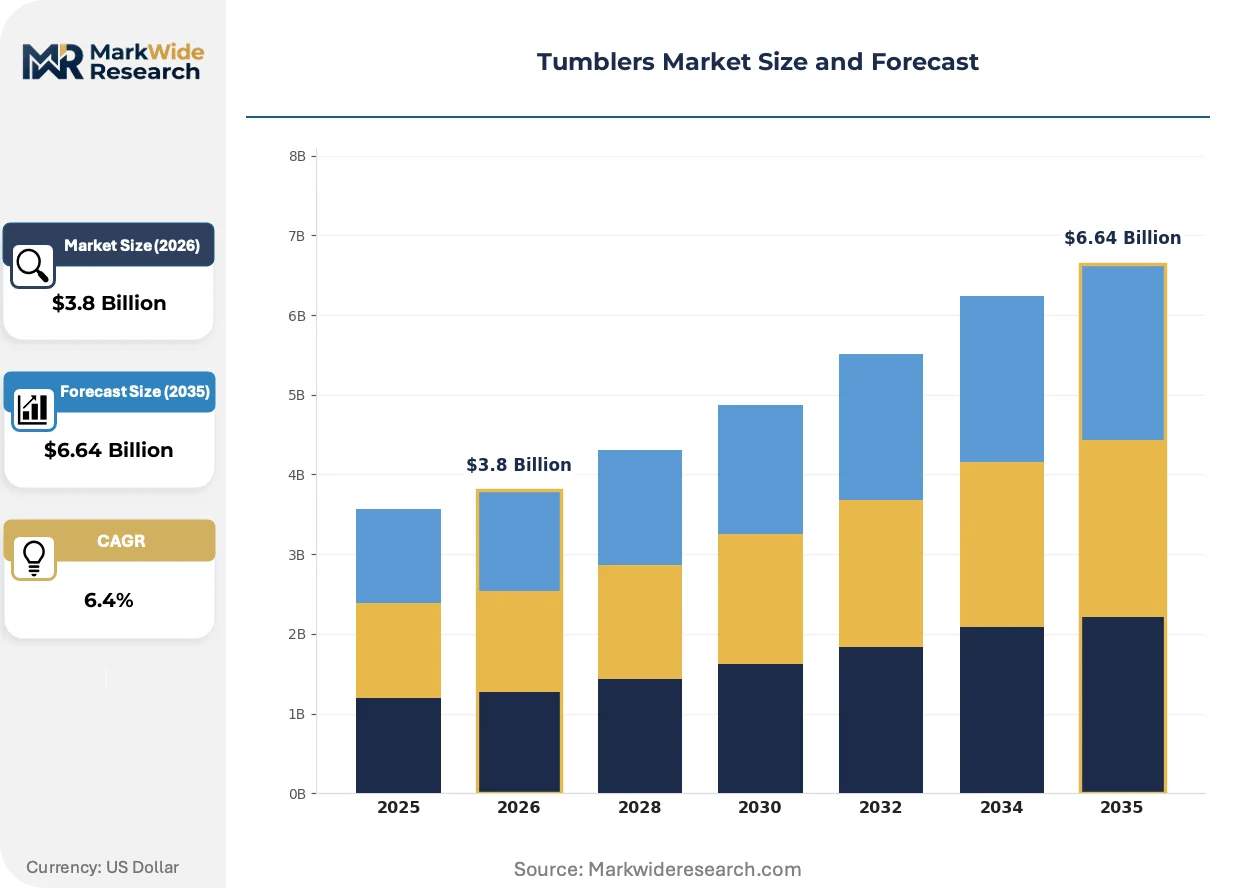
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Stainless Steel, Glass, Silicone, Plastic, Bamboo, Copper Capacity: 8 oz, 12 oz, 16 oz, 20 oz, 24 oz Application: Outdoor Activities, Corporate Gifting, Hospitality, Gift Shops, Personal Use Sales Channel: Online Retailers, Specialty Stores, Supermarkets, Department Stores |
| Companies Covered | Newell Brands, KingStar Industries, YETI, RTIC Outdoors, Zhejiang Haers Vacuum Containers, Stanley, Thermos, Everich Drinkware, Hydro Flask, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumblers Market Strategic Shifts & Innovations
Product evolution is accelerating as the tumbler transitions from a simple utility item to a highly visible lifestyle accessory. This change elevates the importance of material science, aesthetic customization, and brand storytelling in defining market leadership and consumer preference.
Smart lid technology integrates features like temperature displays or hydration tracking directly into the container. The wellness-focused consumer segment is an early adopter, seeking data-driven insights on their consumption habits. The traditional vacuum-insulated vessel is absorbing electronic components, creating a new, higher-margin product category defined by interactive functionality.
Heightened scrutiny over environmental marketing is a significant regulatory trend, exemplified by the FTC's Green Guides in the U.S. and EU directives on greenwashing. These rules require brands to substantiate claims like 'sustainable' or 'recyclable' with verifiable evidence. The premium segment, which often uses eco-credentials for differentiation, is most affected and must now invest heavily in material traceability.
A collector culture, amplified by viral social media campaigns, is altering purchasing patterns for tumblers. This behavior disrupts traditional product cycles, favoring limited-edition color releases and collaborations over static, seasonal catalogs. This phenomenon is most prominent within the United States consumer market, particularly influencing younger demographic cohorts.
Tumblers Market Segmentation
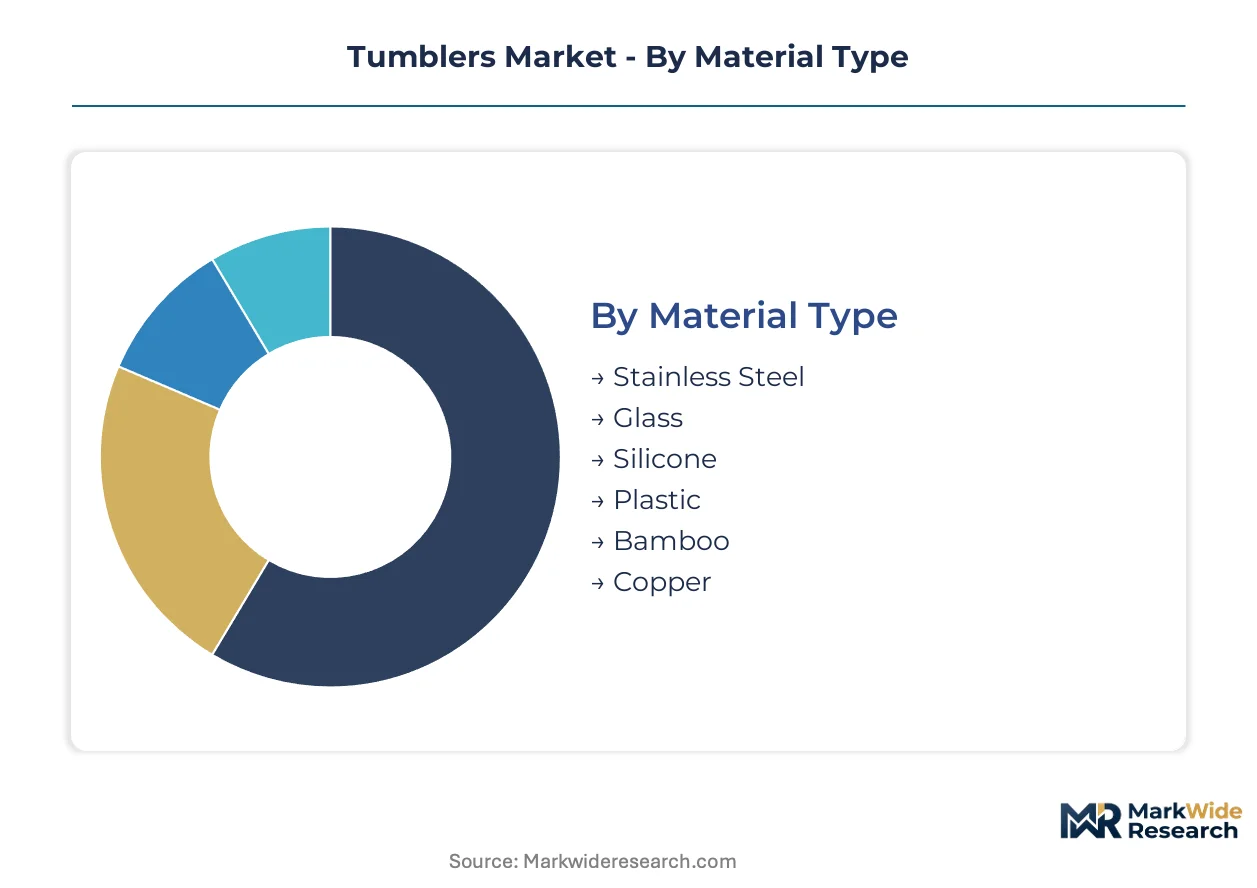
The tumblers market exhibits diverse segmentation, reflecting varied consumer needs and functional requirements across different end-use applications. Understanding these distinct segments allows manufacturers to tailor product development and marketing strategies effectively. This granular view reveals where demand concentrates and where new growth opportunities emerge.
Material Type:
Material selection for tumblers spans a spectrum from highly standardized, performance-driven options to those offering significant potential for customization and eco-friendly differentiation.
- Stainless Steel:This material dominates the market due to its exceptional durability, thermal insulation properties, and resistance to corrosion, making it ideal for performance-oriented tumblers. Demand concentrates in the United States, driven by outdoor recreational activities and a preference for long-lasting products.
- Bamboo:Representing a sustainable alternative, bamboo is often used for outer casings or accents, appealing to environmentally conscious consumers seeking natural aesthetics. This segment sees increasing demand in European markets, spurred by stricter environmental regulations and consumer pressure for bio-based materials.
- Glass:Glass tumblers offer chemical inertness and a premium feel, primarily appealing to consumers focused on taste purity and aesthetic transparency.
- Silicone:Known for its flexibility and shatter resistance, silicone is increasingly adopted for collapsible designs and protective sleeves in children's drinkware.
- Plastic:Lightweight and cost-effective, plastic tumblers serve budget-conscious segments, though demand for recycled plastic options is expanding due to sustainability efforts.
- Copper:Copper tumblers are valued for their traditional aesthetic and perceived health benefits, finding niche appeal in wellness-focused consumer groups.
Most installed capacity flows through Stainless Steel products. Expansion is steepest in Bamboo-based and recycled plastic alternatives.
Capacity:
Tumbler capacity segmentation directly correlates with user hydration needs and portability preferences, influencing product design for various daily activities and specialized uses.
- 20 oz:This capacity strikes a balance between portability and sufficient liquid volume, making it popular for daily commutes and fitness activities. Demand is strong among mainstream consumers in urban centers, who prioritize convenience and sustained hydration.
- 24 oz:Offering extended hydration, 24 oz tumblers cater to individuals with higher fluid intake requirements or those engaged in longer outdoor excursions. This size sees significant uptake in the United States, favored by outdoor enthusiasts and active lifestyle consumers.
- 8 oz:Smaller 8 oz tumblers are typically used for coffee, children's beverages, or specialized drink preparations, emphasizing compact design.
- 12 oz:The 12 oz capacity is a common choice for single servings of hot beverages, fitting well into standard cup holders and small bags.
- 16 oz:A versatile mid-range option, 16 oz tumblers are popular for everyday use, accommodating a standard beverage size for many consumers.
The largest volume sales are observed in the 20 oz and 24 oz capacities. The 12 oz segment also demonstrates consistent consumer preference for smaller, convenient options.
Application:
Application segmentation illustrates how tumblers serve distinct user purposes, ranging from individual daily hydration to large-scale promotional and commercial uses, each with specific product requirements.
- Personal Use:This segment encompasses tumblers purchased for individual daily hydration, commuting, and general beverage consumption, forming the largest base of buyers. Demand for personal use products is widespread across all demographics, driven by wellness culture and convenience.
- Corporate Gifting:Tumblers in this segment are customized with company branding, serving as promotional items or employee appreciation gifts, requiring extensive personalization options. This application represents the fastest-growing segment, fueled by companies seeking durable and visible brand ambassadors.
- Outdoor Activities:Tumblers for outdoor use prioritize rugged durability, superior insulation, and leak-proof designs, essential for camping, hiking, and sports enthusiasts.
- Hospitality:In the hospitality sector, tumblers are utilized by hotels, cafes, and restaurants for serving beverages, focusing on aesthetic appeal and ease of cleaning.
- Gift Shops:This channel offers tumblers as novelty items or souvenirs, often featuring unique designs or local themes, appealing to impulse buyers.
Personal Use accounts for the largest share of overall market consumption. Corporate Gifting continues to experience the most dynamic expansion, driven by customization needs.
Sales Channel:
Sales channel segmentation highlights the diverse routes through which tumblers reach consumers, each channel offering unique advantages in terms of reach, pricing, and customer interaction.
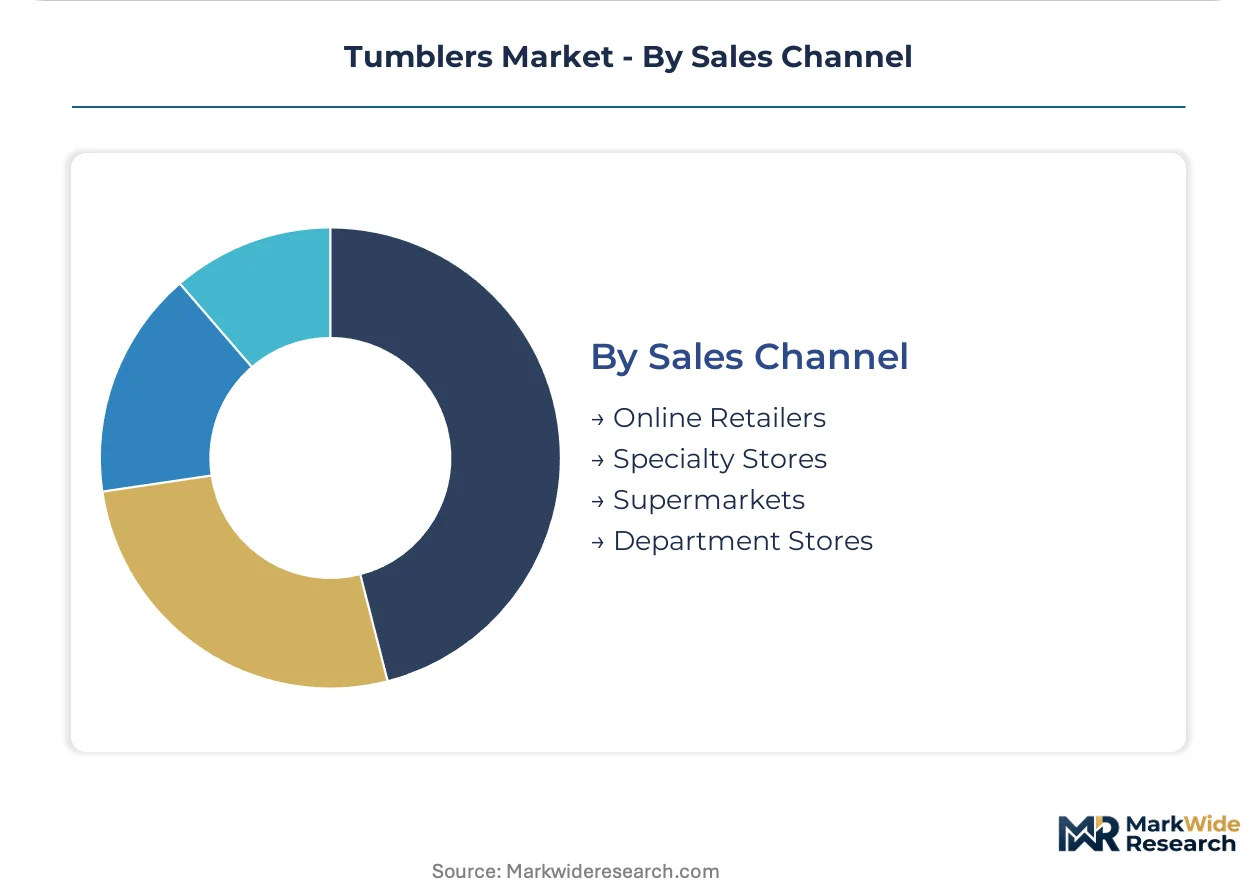
- Online Retailers:This channel includes e-commerce platforms and brand websites, offering broad product selections, competitive pricing, and direct-to-consumer convenience. Online sales are particularly strong for niche brands and limited-edition releases, capitalizing on digital marketing trends.
- Specialty Stores:These outlets, such as outdoor gear shops or gourmet kitchen stores, provide curated selections and expert advice, catering to consumers seeking premium or specialized tumblers. This channel thrives on brand loyalty and the tactile experience of product evaluation.
- Supermarkets:Supermarkets offer tumblers as part of a broader household goods selection, appealing to convenience-driven shoppers and mass-market pricing.
- Department Stores:These stores feature tumblers as part of their home goods or kitchenware sections, often showcasing mid-to-high-end brands with a focus on aesthetic appeal.
Online Retailers capture a significant and expanding portion of tumbler sales. Specialty Stores maintain importance for premium product discovery and brand engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A skilled manufacturing workforce anchoring key production hubs significantly influences the global tumblers market. Consumer preferences for convenience and performance drive demand across diverse geographies. Regulatory frameworks governing food-contact materials also shape regional market development and material adoption.
United States
Strong consumer demand for high-performance and customizable tumblers drives market expansion in the United States. The US Food and Drug Administration (FDA) enforces strict regulations on food-contact materials, influencing product design and material choices. Major outdoor recreational clusters in states like Colorado and California foster innovation in rugged, insulated drinkware.
Germany
German consumers prioritize product quality and sustainability, stimulating demand for durable stainless steel and bamboo tumblers. The European Food Safety Authority (EFSA) sets stringent standards for food-contact materials across the European Union, impacting market access for manufacturers. Bavaria and North Rhine-Westphalia, with their strong industrial bases, contribute to advanced material engineering for beverage containers.
China
China's vast manufacturing capabilities and a growing middle class fuel both domestic consumption and export of tumblers. China's GB standards for plastics and metals ensure product safety and quality for both local and international markets. Industrial clusters in Zhejiang and Guangdong provinces are centers for high-volume production and material innovation in tumblers.
Japan
Japanese consumers value aesthetic design and functional efficiency in their tumblers, driving demand for innovative features and compact sizes. The Ministry of Health, Labour and Welfare (MHLW) regulates food-contact materials to ensure consumer safety and product integrity. Urban centers like Tokyo and Osaka are key markets for premium, design-focused beverage accessories.
India
Rising disposable incomes and a growing health and wellness trend contribute to increased demand for reusable tumblers in India. The Bureau of Indian Standards (BIS) establishes quality and safety benchmarks for consumer goods, including drinkware. Metropolitan areas such as Mumbai and Delhi exhibit strong uptake for personal use and corporate gifting tumblers.
Tumblers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the tumblers market. This competitive structure features a mix of established brands leveraging legacy recognition and agile newcomers capitalizing on digital marketing. Strategic archetypes include premium lifestyle brands, value-oriented mass-market suppliers, and niche innovators. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach.
Premium lifestyle brands, such as YETI, command higher price points through strong brand identity and perceived performance. Stanley capitalizes on its heritage and viral social media trends to reach new demographics, exemplifying effective brand repositioning. Newell Brands, through its diverse portfolio including Thermos, occupies a position across multiple price points, serving a broad consumer base.
| Leading Market Players |
|---|
| Newell Brands |
| KingStar Industries |
| YETI |
| RTIC Outdoors |
| Zhejiang Haers Vacuum Containers |
| Stanley |
| Thermos |
| Everich Drinkware |
| Hydro Flask |
| Others |
Cost & Logistics Intelligence
FTC's Green Guides and EU directives on greenwashing significantly gate qualified supply and premium-tier pricing access in the tumblers market. These environmental mandates necessitate verifiable evidence for sustainability claims, impacting material sourcing and product development costs. Brands must invest in traceability to command higher prices.
Pricing Analysis
Bundled product sales versus unbundled customization options define pricing across the tumblers market. Per-unit transactional pricing dominates for standard products, while corporate gifting commands value-based pricing due to extensive personalization needs. Brand premium and certification level serve as key differentiation drivers, allowing premium brands like YETI to maintain higher price points. Pricing softness reflects intense competition from low-cost alternatives and counterfeit goods. Budget-conscious segments exhibit the highest price sensitivity, while consumers seeking specialized performance or brand status are less price-sensitive.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the downstream logistics for tumblers, optimizing delivery to diverse sales channels. Geographic supply concentration for manufacturing centers in China, with specialized material engineering contributions from Germany. The industry draws from stainless steel, recycled plastics, and bamboo as primary raw material dependencies. Regulatory fragmentation across FDA, EFSA, and GB standards presents a structural supply chain risk, increasing compliance costs for manufacturers. Distribution runs through online retailers, which capture significant sales, and specialty stores, crucial for premium product discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tumblers market represents a late-cycle quality story, driven by a demand-shift toward premium specifications and sophisticated product features. Consumers increasingly seek advanced functionality and aesthetic differentiation in their beverage containers.
For Market Incumbents:Cement brand loyalty through continuous material science innovation and stringent compliance with evolving food-contact regulations. Diversify product portfolios to cover multiple price points, leveraging established distribution networks to counter the threat of agile niche players. Invest in verifiable material traceability to substantiate environmental claims, differentiating premium offerings from mass-market alternatives. Control key manufacturing processes to mitigate supply chain volatility.
For New Entrants and Emerging Players:Begin with targeting underpenetrated application niches, such as specialized drinkware for infant formula or nutritional supplements, to establish a distinct market presence. Focus on smart technology integration, like temperature sensors or hydration tracking, to appeal to tech-savvy consumers in urban centers. A direct-to-consumer online go-to-market angle, amplified by viral social media campaigns, offers a cost-effective entry strategy. The wellness-focused consumer segment remains highly penetrable for innovative solutions.
For Investors and Strategic Acquirers:Roll-up economics work for mid-cap specialists because structural fragmentation exists across the vendor base and niche technology providers. The long-term viability of this market over a 5-10 year window hinges on material innovation and brand strength. Target acquisition profiles include agile innovators in smart technology or companies with proprietary sustainable material solutions. A signal to watch is the widespread adoption of circular economy programs by major brands, indicating a shift towards long-term asset value.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Innovation in Smart Lids | Introduces high-margin offerings, attracting tech-savvy consumers and expanding the premium segment. |
| Supply Chain Verification for Materials | Ensures compliance with evolving environmental regulations, building consumer trust and brand integrity. |
| Targeted Social Media Campaigns | Capitalizes on collector culture and viral trends, driving rapid demand among younger demographic cohorts. |
| Circular Economy Program Implementation | Enhances brand loyalty and meets sustainability goals, appealing to environmentally conscious consumers. |
| Niche Application Development | Captures new customer segments by addressing specific needs like infant formula preparation or supplement mixing. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming a robust mixed-methods approach. Primary insights came from manufacturing executives, brand managers, retail buyers, material scientists, and regulatory compliance specialists. Secondary validation drew from FDA regulations, EFSA guidelines, GB standards, customs data, and company annual reports, triangulating findings through bottom-up and top-down analyses.
Comparable historical reference periods anchored the forecast window, providing a stable basis for market projections across the analysis window. Segmentation dimensions modeled included material type, capacity, application, and sales channel, along with regional regulatory frameworks. Compound annual growth rates were derived through a comprehensive analytical framework, incorporating stainless steel price trends and consumer hydration trends as key industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events, abrupt shifts in global trade policies, or rapid emergence of disruptive substitute products. Forecasts reflect assumptions regarding raw material supply stability and consistent regulatory enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Combi Cans Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
Soft Drinks Packaging Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Water Bottle Racks Market