
 Collapsible Rigid Containers Market | 2026-2036
Collapsible Rigid Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Collapsible Rigid Containers Market Intelligence
The integration of RFID and IoT sensor technology directly into container molding processes is reshaping supply chain visibility and asset tracking. This shift enables real-time monitoring of goods from production to final delivery. Brambles Limited (CHEP) leverages its extensive global pooling network to deploy these smart containers at scale. Meanwhile, ORBIS Corporation specializes in custom solutions for the automotive and food sectors, embedding tracking capabilities to meet client specifications.
Collapsible rigid containers are reusable transit packaging systems designed to fold down when empty, significantly reducing return logistics costs. Constructed from materials like high-density polyethylene or polypropylene, they offer high strength-to-weight ratios and achieve collapse ratios of up to 5:1. Demand from pharmaceutical logistics is a primary growth engine due to stringent cold chain requirements. In terms of material composition, polypropylene-based containers lead the market due to their balance of durability, cost, and recyclability.
Material selection and design are heavily influenced by a multi-jurisdictional regulatory environment. In the United States, the FDA sets standards for food-contact materials, while in Europe, the ECHA's REACH regulation governs chemical substances used in plastics. Global ISO standards ensure dimensional compatibility for international shipping. Consequently, manufacturers must navigate these varied compliance requirements to ensure market access for their products across different end-user industries.
Market Dynamics
The central force shaping the market is the drive for circular economy principles in logistics, compelled by both sustainability mandates and the high cost of last-mile and reverse logistics. This pressure accelerates the integration of digital tracking technologies directly into durable, reusable packaging formats to optimize asset utilization.
Growth Catalysts
- Advanced Composites:The development of new polypropylene blends enhances impact resistance and reduces container weight, directly appealing to the air freight and automotive sectors where fuel efficiency is a primary cost driver.
- Pharmaceutical Cold Chain:Demand from pharmaceutical logistics for validated, temperature-controlled transit packaging to protect sensitive biologics and vaccines is a primary growth engine, especially with tightening global health regulations.
- Food Safety Regulation:Standards like the FDA's Food Safety Modernization Act in the United States and EFSA guidelines in Europe push agricultural exporters toward traceable, hygienic, and reusable containers for fresh produce.
Market Restraints
- High Initial Investment:The upfront capital cost to acquire a fleet of durable, smart-enabled containers and establish a supporting logistics pool is a significant barrier compared to low-cost, disposable packaging.
- Substitution from Single-Use Packaging:In market segments without stringent regulatory oversight or complex cold chains, lower-cost single-use options like cardboard or shrink wrap remain a persistent competitive threat.
- Cleaning and Maintenance Burden:The operational complexity and cost associated with cleaning, sanitizing, and repairing containers to meet food-grade or pharmaceutical standards can deter adoption for some end-users.
Strategic Opportunities
- Perishables Expansion:New applications are emerging in high-value perishables, including the global floriculture and live seafood trades, which require the same level of protection and temperature control as pharmaceuticals.
- Blockchain Integration:Combining IoT sensor data with blockchain ledgers offers an opportunity to create immutable records for high-value shipments, combating counterfeiting in pharmaceuticals and electronics.
- South American Agricultural Exports:Brazil and Chile represent underpenetrated markets where collapsible containers can significantly reduce logistics costs for high-volume fruit and vegetable exports to North America and Europe.
Industry Challenges
- Interoperability Standards:A lack of universal standards for container data protocols and API integrations between different pooling operators and logistics platforms creates friction and limits seamless supply chain visibility.
- Reverse Logistics Management:The operational challenge of efficiently managing the return, inspection, and repositioning of empty containers is a major hurdle to profitability and scalability for container pool operators.
- Asset Loss and Damage:Despite their durability, the loss, theft, or damage of high-value containers within complex, open-loop supply chains remains a significant operational and financial challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collapsible Rigid Containers Market |
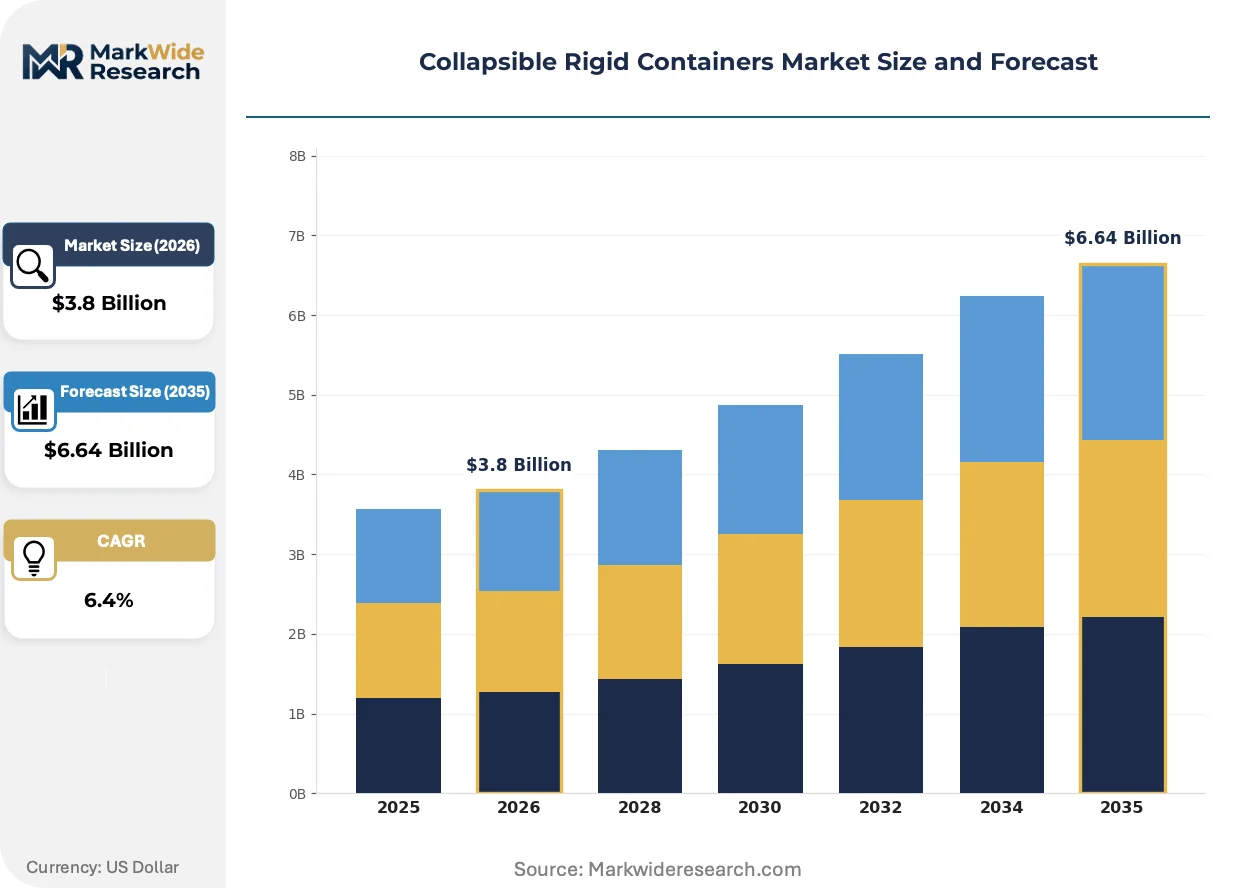
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Plastic, Metal, Composite, Hybrid Application: Food Storage, Chemical Transport, Pharmaceutical Logistics, Electronics Packaging, Agricultural Products End User: Manufacturers, Distributors, Retail Chains, Third-Party Logistics Providers, Warehousing Facilities Material Composition: Polypropylene, High-Density Polyethylene, Aluminum, Corrugated Fiberboard |
| Companies Covered | Brambles Limited (CHEP), Schoeller Allibert Services B.V., ORBIS Corporation, DS Smith plc, Rehrig Pacific Company, SSI Schäfer AG, Georg Utz Holding AG, Supreme Industries Limited, Craemer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collapsible Rigid Containers Market Strategic Shifts & Innovations
Material science and digital technology are converging, transforming containers from passive vessels into active, data-generating assets. This evolution enhances supply chain intelligence, enabling real-time monitoring of not just location but also the condition of goods in transit.
Active thermal management systems, which incorporate phase-change materials (PCMs) into container walls, provide passive temperature stability. The pharmaceutical and premium food sectors are adopting these systems to ensure cold chain integrity without reliance on powered refrigeration units. This technology is hybridizing the container's function, merging physical protection with active environmental management and reducing dependence on specialized refrigerated transport.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant policy driver, compelling companies to provide detailed disclosures on resource use and supply chain emissions. This regulatory pressure makes the quantifiable environmental benefits of reusable packaging a key factor in procurement decisions. Consequently, logistics managers in Europe's automotive and retail sectors are prioritizing collapsible rigid containers to meet ESG reporting mandates.
A transition toward packaging-as-a-service (PaaS) models is becoming more prevalent, allowing users to pay per trip rather than purchasing containers. This shifts the financial burden from a large capital expenditure to a predictable operational expense, lowering adoption barriers for small and medium-sized businesses. The trend is most pronounced in Germany's automotive parts supply chain and the US agricultural export hubs.
Collapsible Rigid Containers Market Segmentation
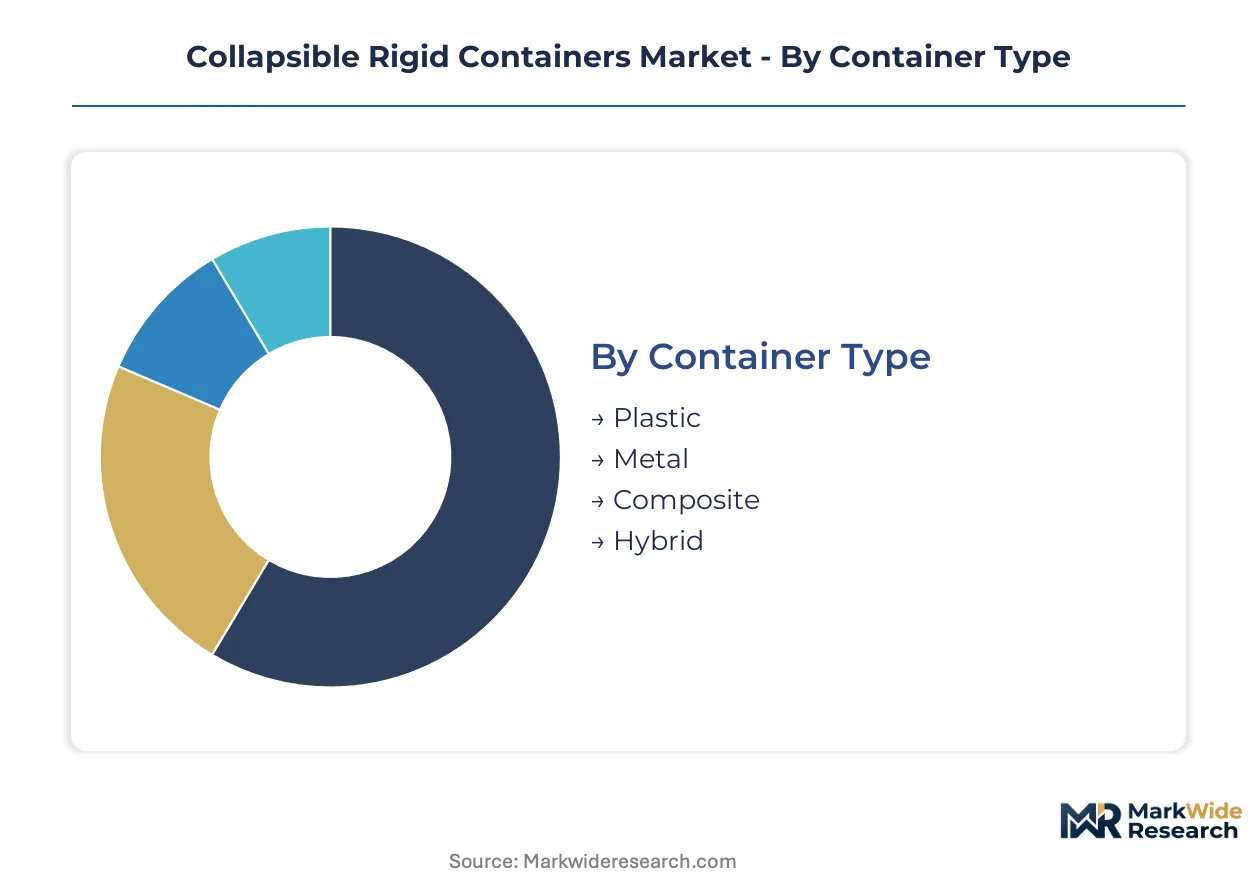
Collapsible rigid containers serve diverse industrial needs, necessitating segmentation to understand varied performance requirements and market dynamics. Analyzing these distinctions helps stakeholders tailor product offerings and optimize supply chain solutions. This detailed breakdown illuminates where specific container attributes deliver maximum value and operational efficiency.
Container Type:
The intensity of after-sales service requirements significantly differentiates container types, influencing their total cost of ownership and operational lifespan.
- Plastic:These containers are typically molded from high-density polyethylene (HDPE) or polypropylene, offering a balance of durability, chemical resistance, and lightweight properties. Demand is concentrating in pharmaceutical logistics due to stringent hygiene standards and the need for reusable, easily sanitizable packaging.
- Composite:Composite containers combine different materials, such as plastic panels with metal frames, to achieve enhanced strength, thermal insulation, or specialized barrier properties. Automotive parts supply chains in Germany utilize these for protecting sensitive components during transit.
- Metal:Metal containers, often steel or aluminum, provide superior strength and fire resistance, primarily used for heavy industrial components or hazardous materials transport.
- Hybrid:Hybrid containers integrate features from multiple types, such as collapsible plastic bodies with integrated IoT sensors, optimizing asset tracking in complex logistics networks.
Plastic containers hold the largest share; momentum sits with Composite containers.
Application:
Application-specific requirements drive material selection and structural design, directly impacting container functionality and compliance needs.
- Pharmaceutical Logistics:This application demands validated, temperature-controlled containers capable of protecting sensitive biologics and vaccines throughout complex cold chains. Tightening global health regulations, such as those from the FDA and EMA, are a primary growth engine.
- Agricultural Products:Containers for agricultural products prioritize hygiene, ventilation, and gentle handling to preserve freshness and prevent spoilage for items like fresh produce. Standards like the FDA's Food Safety Modernization Act push exporters towards traceable, reusable solutions.
- Food Storage:Food storage applications require containers meeting food-contact material regulations and offering hygienic, stackable designs for efficient warehousing.
- Chemical Transport:Chemical transport necessitates containers with robust chemical resistance and structural integrity to safely handle hazardous or corrosive substances.
- Electronics Packaging:Electronics packaging focuses on anti-static properties and cushioning to protect sensitive components from damage during transit and storage.
Pharmaceutical Logistics represents a significant revenue contributor, with Agricultural Products expanding most quickly.
End User:
The volume and frequency of container use by end-users dictate the economic viability of reusable systems versus single-use alternatives.
- Third-Party Logistics Providers:These entities manage extensive container pools, leveraging digital tracking technologies to optimize asset utilization and reverse logistics for multiple clients. Brambles Limited (CHEP) exemplifies this model with its global network.
- Manufacturers:Manufacturers integrate collapsible rigid containers into their internal and outbound supply chains for components and finished goods, often seeking custom solutions for specific production lines. ORBIS Corporation specializes in these tailored systems for automotive clients.
- Distributors:Distributors utilize these containers for efficient inventory management and streamlined transport between warehouses and retail points.
- Retail Chains:Retail chains adopt reusable containers for back-of-store logistics and direct-to-shelf delivery, reducing waste and improving operational flow.
- Warehousing Facilities:Warehousing facilities benefit from the collapsibility feature, maximizing storage density for empty containers and optimizing space.
Third-Party Logistics Providers issue the strongest demand signal, while Manufacturers drive innovation in custom container designs.
Material Composition:
Sustainability mandates and performance trade-offs heavily influence material composition choices for collapsible rigid containers.
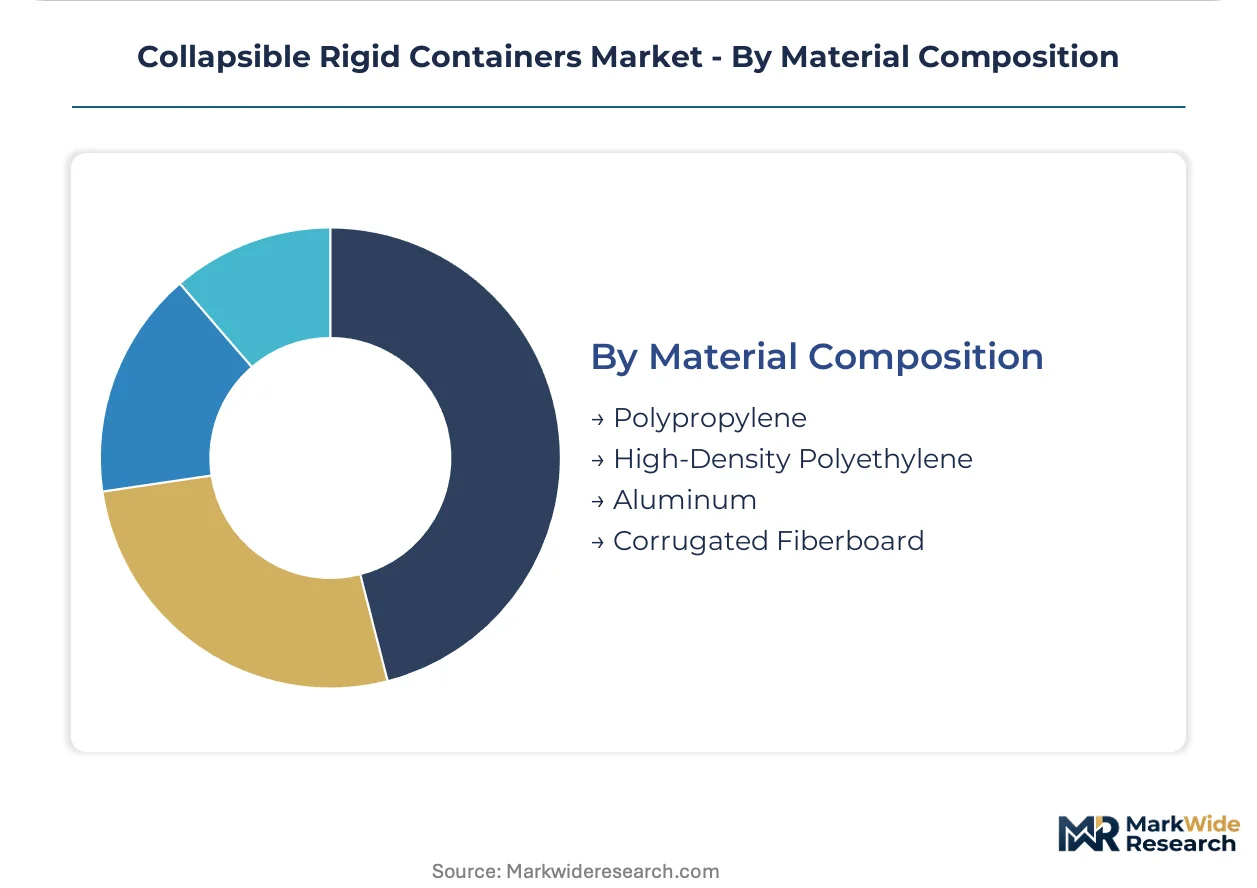
- Polypropylene:Polypropylene-based containers dominate the market due to their excellent balance of durability, lightweight properties, chemical resistance, and recyclability. Advanced blends enhance impact resistance for air freight applications.
- High-Density Polyethylene:HDPE containers offer high strength-to-weight ratios, chemical inertness, and good impact resistance, making them suitable for a wide range of industrial and food-grade applications. Demand is strong in agricultural export hubs in the United States.
- Aluminum:Aluminum provides superior strength and corrosion resistance, often selected for specialized applications requiring extreme durability or temperature control.
- Corrugated Fiberboard:Corrugated fiberboard, while less durable, offers a cost-effective and recyclable option for lighter-duty or less frequent reuse cycles.
Polypropylene remains the dominant material choice, with High-Density Polyethylene also demonstrating consistent adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global market for collapsible rigid containers exhibits a nuanced export-import balance, with advanced manufacturing hubs driving demand for specialized logistics solutions. Countries with significant agricultural and pharmaceutical export activities are particularly influential. This dynamic shapes regional investment in reusable packaging infrastructure.
United States
United States demand originates from its extensive agricultural export hubs, requiring hygienic and traceable packaging solutions. The FDA's Food Safety Modernization Act compels agricultural exporters toward reusable containers for fresh produce. Significant activity concentrates within the Midwest and California, optimizing logistics for high-volume fruit and vegetable shipments.
Germany
Germany's automotive parts supply chain drives demand for robust composite containers, ensuring precision component protection during transit. The EU's Corporate Sustainability Reporting Directive influences procurement decisions for sustainable logistics. Manufacturers in Bavaria and North Rhine-Westphalia prioritize reusable packaging to meet ESG reporting mandates.
Brazil
Brazil presents significant opportunities for collapsible containers, especially for its high-volume fruit and vegetable exports to North America and Europe. ANVISA regulations for food contact materials ensure product integrity and safety for international trade. The São Paulo and Minas Gerais regions are adopting these systems to reduce logistics costs for perishable goods.
India
India's expanding pharmaceutical logistics sector generates substantial demand for validated, temperature-controlled collapsible containers. The Central Drugs Standard Control Organization (CDSCO) mandates stringent packaging standards for sensitive biologics and vaccines. Major pharmaceutical manufacturing hubs in Gujarat and Telangana are integrating these reusable solutions into their supply chains.
Collapsible Rigid Containers Market Key Industry Players
On the supply side, the industry is moderately fragmented, featuring a blend of global pooling operators and specialized manufacturers. Strategic archetypes include large-scale service providers managing extensive container fleets, alongside niche players offering custom solutions for specific industrial applications. Dominant competitive moves center on geographic expansion into high-growth regions and the continuous technological integration of smart features into container designs to enhance supply chain visibility.
Global pooling network specialists, such as Brambles Limited (CHEP), leverage extensive infrastructure to deploy smart containers at scale, optimizing asset utilization for diverse clients. Meanwhile, ORBIS Corporation exemplifies manufacturers specializing in custom solutions for the automotive and food sectors, embedding tracking capabilities to meet client specifications. Schoeller Allibert Services B.V., a Netherlands-based provider, offers a broad portfolio of reusable transit packaging, serving various industrial and retail applications globally.
| Leading Market Players |
|---|
| Brambles Limited (CHEP) |
| Schoeller Allibert Services B.V. |
| ORBIS Corporation |
| DS Smith plc |
| Rehrig Pacific Company |
| SSI Schäfer AG |
| Georg Utz Holding AG |
| Supreme Industries Limited |
| Craemer GmbH |
Cost & Logistics Intelligence
Undercapacity in advanced composite container manufacturing drives both supplier behavior and pricing posture, especially for specialized solutions in pharmaceutical logistics. This concentration of advanced production capacity influences the negotiation power of key manufacturers for high-performance containers.
Pricing Analysis
The next-generation pricing gap between smart-enabled containers and traditional plastic units reflects embedded IoT sensor costs. Dominant pricing structures are shifting from per-unit transactional to packaging-as-a-service (PaaS) models. Price differentiation stems from customization levels for specific client needs and the certification level for cold chain compliance. Pricing softness impacts basic HDPE containers due to competition from single-use alternatives, while pharmaceutical logistics remains least price-sensitive.
Supply Chain Analysis
Single-source vulnerability for advanced polypropylene resins dominates the collapsible rigid container supply chain, primarily sourced from China and Germany. Key components include high-density polyethylene, polypropylene, and specialized RFID chips. Logistics chokepoints in international shipping lanes pose a structural risk. Distribution runs through a hybrid model combining direct sales to large manufacturers and pooling services via Third-Party Logistics Providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapsible rigid containers market is at a platform-economics inflection, driven by the interoperability shift towards integrated IoT and blockchain ecosystems for supply chain visibility.
For Market Incumbents: Entrench market leadership by expanding global pooling networks, particularly in emerging agricultural export hubs like Brazil. Invest in advanced material science R&D to counter the threat of cheaper, less durable substitutes. Control key intellectual property for smart container technologies, leveraging vertical integration into sensor manufacturing. Focus on achieving ISO standards for data protocols.
For New Entrants and Emerging Players: Underpenetrated cold chain logistics in India's burgeoning pharmaceutical sector represents the most penetrable entry point. Focus on specialized hybrid container solutions integrating active thermal management for high-value perishables. A go-to-market angle of 'validated cold chain-as-a-service' can attract smaller pharmaceutical manufacturers by reducing upfront capital expenditure barriers. Target specific compliance needs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among global pooling operators offering PaaS models. Long-term viability hinges on asset utilization rates and technological differentiation in smart packaging. Target vertically integrated manufacturers with strong R&D in composite materials and digital tracking. The signal to watch is the widespread adoption of interoperability standards for data protocols across logistics platforms, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Global Pooling Network | Increases asset utilization and reduces logistics costs for diverse clients across multiple regions. |
| Invest in Advanced Material R&D | Enhances container durability and reduces weight, directly appealing to high-value air freight applications. |
| Develop Active Thermal Management | Ensures cold chain integrity for sensitive goods, meeting stringent pharmaceutical and food safety regulations. |
| Integrate Blockchain for Tracking | Creates immutable records for high-value shipments, combating counterfeiting and enhancing traceability. |
| Offer Packaging-as-a-Service | Lowers adoption barriers for small and medium-sized businesses, shifting capital expenditure to operational expense. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and robust secondary validation. Primary data gathered from logistics managers, procurement heads at automotive OEMs, pharmaceutical supply chain directors, and material scientists. Secondary sources included trade association reports, regulatory filings (FDA, ECHA), and academic literature on packaging innovation. Bottom-up market sizing was triangulated with top-down economic indicators.
Forecast inputs considered macroeconomic trends, regulatory shifts, and technological advancements across the analysis window. Segmentation dimensions modeled included container type, application, end-user, material composition, and regional demand patterns. Compound annual growth rates were derived through a proprietary statistical model, integrating historical data with expert projections. Key industry-specific inputs included polypropylene resin prices and global cold chain investment trends.
Practitioners should monitor shifts in global trade policies and raw material supply stability for early signals impacting market forecasts. Forecasts reflect assumptions documented through iterative expert panel reviews. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Rigid Sleeve Boxes Market