
 Europe Beverage Packaging Market | 2026-2036
Europe Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Beverage Packaging Market Foresight
Single-serve and on-the-go formats is repositioning buyer choice across European beverage aisles. Ardagh Group dominates metal packaging supply through its extensive European can manufacturing footprint. Tetra Pak differentiates via aseptic carton technology leadership in ambient juice and dairy alternatives. CANPACK leverages integrated aluminum rolling and canmaking to control cost structures across Central European markets.
Europe Beverage Packaging encompasses containers, closures, and secondary materials engineered to preserve liquid product integrity, prevent contamination, and enable efficient distribution through supply chains; specifications include oxygen transmission rates below 0.1 cc per package per day for sensitive beverages, barrier coatings of ethylene vinyl alcohol or aluminum oxide, and forming processes spanning blow-molding, draw-and-wall-ironing, and liquid packaging board extrusion. Aluminum cans capture margin pools through premium positioning in craft beer and energy drinks, while paperboard formats accelerate in ambient juices as brands respond to plastic reduction commitments. Glass bottles sustain share in sparkling water and wine segments where premium perception and inert material properties anchor consumer preference.
The EU Packaging and Packaging Waste Regulation, REACH chemical compliance frameworks, and national extended producer responsibility schemes across France, Germany, and Italy collectively mandate recycled content thresholds and restrict certain additive chemistries. EFSA safety assessments and CE marking requirements shape material approval timelines and cross-border market access for novel barrier technologies. Stakeholders must monitor evolving delegated acts under the EU Green Deal that will set binding reuse targets and determine which formats qualify for circular economy labeling.
Market Dynamics
The EU Single-Use Plastics Directive is compressing format transitions across European beverage supply chains, forcing converters to requalify barrier chemistries and retool forming lines ahead of binding reuse targets scheduled under delegated acts of the EU Green Deal.
Growth Catalysts
- REACH compliance frameworks:Chemical safety assessments under ECHA are accelerating approval timelines for novel barrier coatings including aluminum oxide and ethylene vinyl alcohol laminates, enabling faster material transitions for sensitive beverages.
- Premium craft beer expansion:Aluminum can adoption is intensifying across Germany, France, and Italy as producers seek lightweight formats with superior oxygen barrier performance for hop-forward products.
- Extended producer responsibility schemes:National frameworks in France, Germany, and Italy are mandating recycled content thresholds that pull post-consumer aluminum and liquid packaging board back into virgin-equivalent specification loops.
Market Restraints
- Aluminum ingot cost volatility:Primary aluminum pricing fluctuations on the London Metal Exchange transmit directly into canmaking economics, compressing margin pools for non-integrated converters.
- Barrier coating technical limitations:Current ethylene vinyl oxygen transmission rates plateau near 0.1 cc per package per day, creating shelf-life ceilings for nitrogen-sensitive functional beverages.
- Glass supply concentration:Furnace capacity for premium sparkling water and wine bottles clusters in Italy and Germany, creating geographic vulnerability to energy price shocks.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Central European beverage production growth outpaces local converting capacity, creating white space for aseptic carton and can line investments.
- Aseptic technology convergence:Integration of hydrogen peroxide sterilization with paperboard forming is opening ambient distribution channels for oat milk and plant-based dairy alternatives previously limited to chilled supply chains.
- Digital watermarking integration:HolyGrail 2.0 sorting technology deployment across French and German material recovery facilities is improving post-consumer aluminum and fiber purity streams, qualifying more feedstock for food-contact recycling loops.
Industry Challenges
- Barrier chemistry certification timelines:EFSA safety assessments for novel coating chemistries extend eighteen to thirty-six months, delaying product launches for converters seeking oxygen transmission improvements.
- Retooling capex intensity:Converting blow-molding lines to handle recycled PET with degraded mechanical properties requires extruder screw redesigns and IV boosters, demanding capital commitments that mid-tier converters struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Beverage Packaging Market |
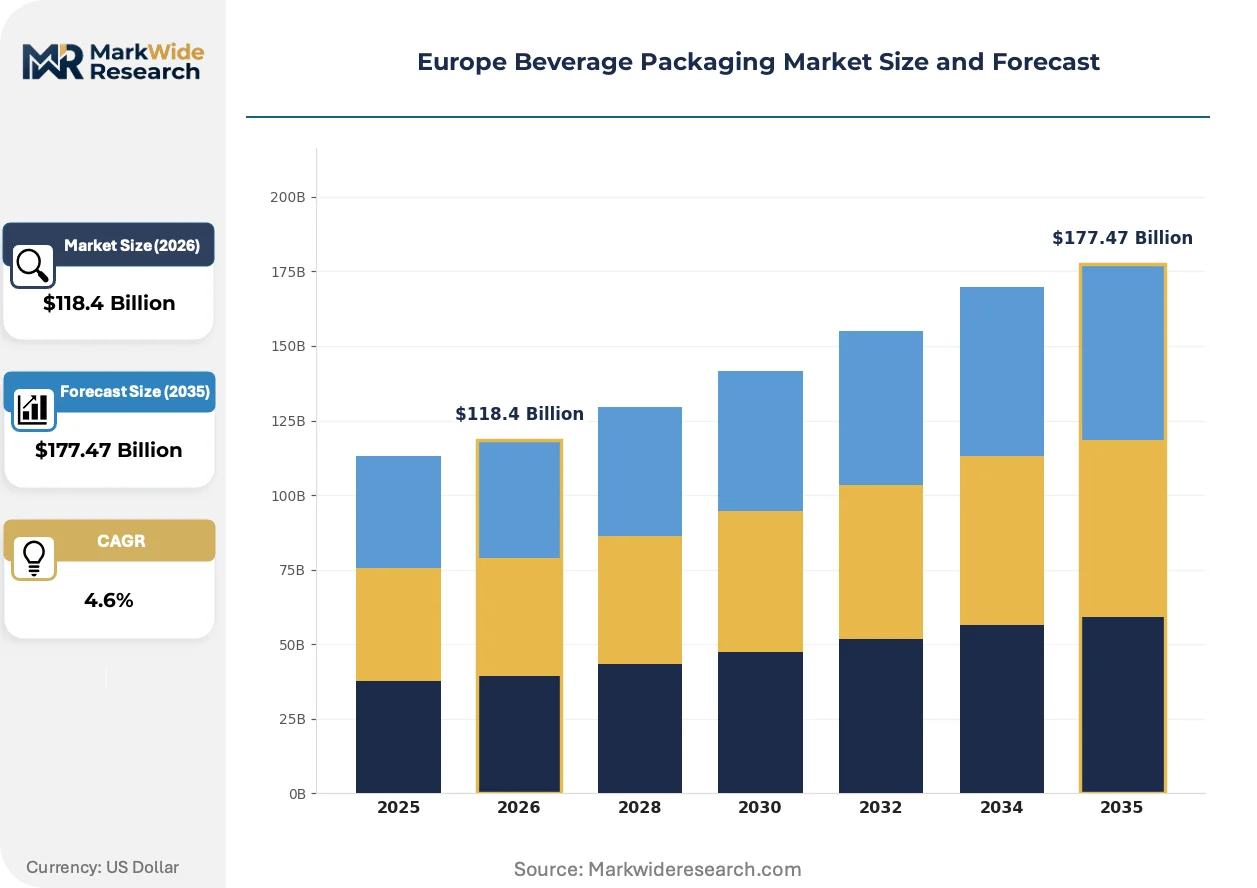
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $177.47 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Tetra Packs, Pouches Material: Plastic, Glass, Aluminum, Paperboard End User: Beverage Manufacturers, Distributors, Retailers, Private Label Brands Product Type: Soft Drinks, Alcoholic Beverages, Juices, Non-Alcoholic Drinks |
| Companies Covered | Ardagh Group, CANPACK, Amcor, Beatson Clark, Tetra Pak, Ball, Smurfit Kappa Group, Vidrala, Mondi Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Beverage Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory compliance automation are compressing development cycles for next-generation beverage formats. Three forces are actively restructuring competitive positioning across European converting.
Aluminum can lightweighting through draw-and-wall-ironing process refinements is electrifying format economics for energy drink and sparkling water producers. Ardagh Group and Ball Corporation are deploying 202-end diameter reductions and body wall thinning across Central European can lines. This metallurgical precision is enabling twelve-gram weight reductions per standard can, translating into freight cost compression and carbon intensity improvements that qualify products for circular economy labeling under draft EU Green Deal delegated acts.
The EU Packaging and Packaging Waste Regulation is mandating binding reuse targets and harmonized extended producer responsibility fee modulation across member states. This framework is forcing brand owners to pre-qualify refillable glass pool systems and deposit-return infrastructure before 2027 implementation deadlines. German mineral water producers are responding with returnable bottle share commitments exceeding eighty percent, while Italian wine exporters face complex cross-border compliance for single-use format exports.
Direct-to-retailer procurement consolidation is compressing converter sales cycles as beverage manufacturers centralize supply relationships with fewer domestic partners. German discount chains and French hypermarkets are unbundling technical service from volume contracts, awarding specification development to engineering teams separate from procurement functions. This organizational separation is most visible in the Nordics, where Arla Foods and Carlsberg have established captive packaging innovation centers that pre-qualify suppliers before tender participation.
Europe Beverage Packaging Market Segmentation
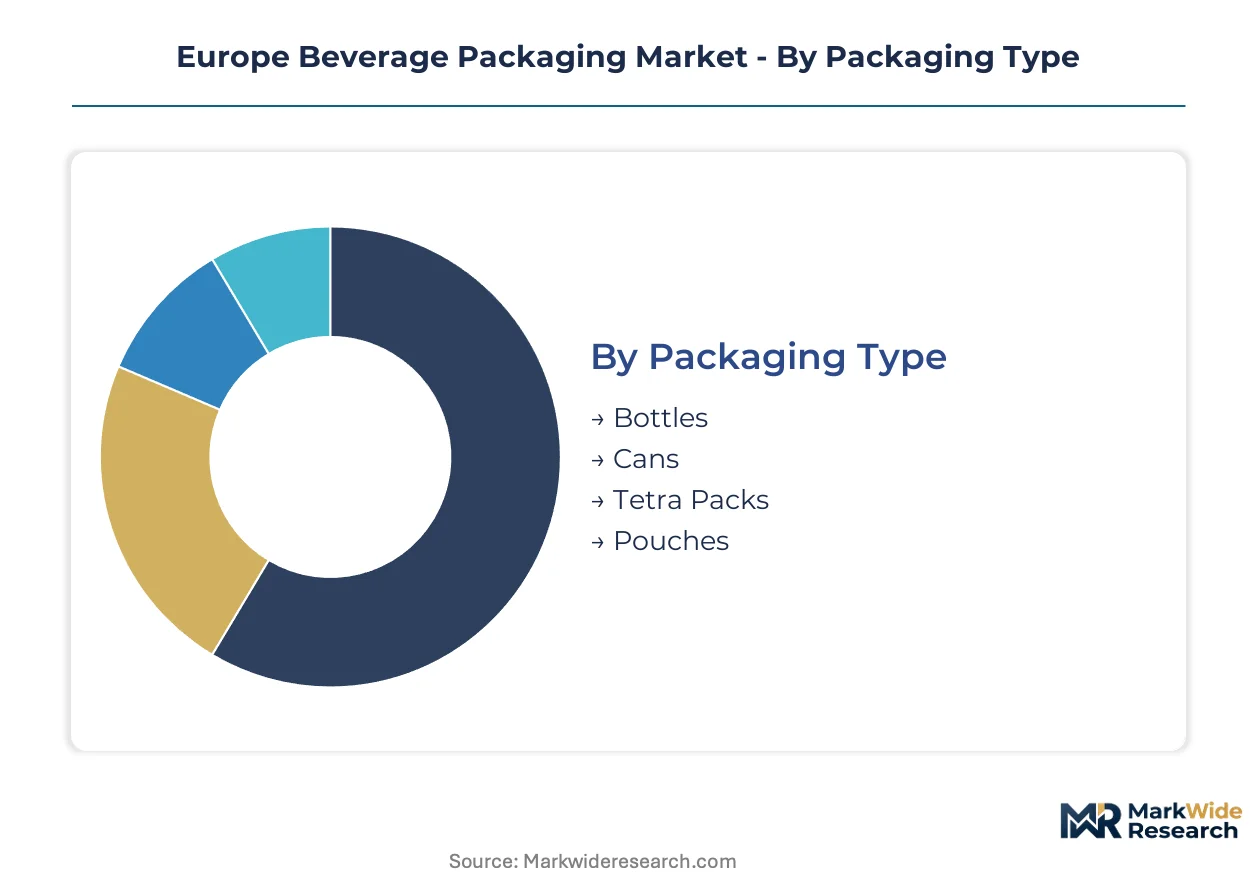
Packaging format decisions in Europe hinge on barrier performance, recycling infrastructure maturity, and regulatory compliance costs. Material specifications and end-user procurement consolidation are compressing supplier margins while rewarding integrated converters with scale advantages.
Packaging Type:
Beverage brand owners select formats based on shelf-life requirements, distribution distance, and deposit-return scheme compatibility across national markets.
- Bottles:Glass and PET variants dominate carbonated soft drinks and mineral water segments. German discount retailers and French hypermarkets drive standardization around returnable glass pools and lightweight PET designs. Deposit-return mandates in Germany and Scandinavia sustain refillable bottle share above eighty percent for domestic mineral water producers.
- Cans:Draw-and-wall-ironed aluminum formats capture craft beer and energy drink growth through superior oxygen barrier performance and freight efficiency. Ardagh Group and Ball Corporation deploy diameter reductions and wall thinning across Central European lines to qualify for circular economy labeling under draft EU Green Deal delegated acts.
- Tetra Packs:Aseptic carton technology from Tetra Pak enables ambient distribution for juices and plant-based dairy alternatives. Liquid packaging board with ethylene vinyl alcohol barrier layers meets EFSA safety assessments for sensitive beverages.
- Pouches:Flexible formats concentrate in single-serve juice and sports drink segments where lightweight logistics offset higher per-unit material costs. Stand-up pouch adoption remains constrained by limited European recycling infrastructure for multilayer films.
Bottles lead on scale; cans lead on momentum.
Material:
Raw material specifications are tightening under REACH compliance frameworks and recycled content mandates across France, Germany, and Italy.
- Plastic:Recycled PET and bio-based polymers face degraded mechanical properties requiring extruder screw redesigns and IV boosters. Mid-tier converters struggle to fund retooling capex for food-contact recycling loops.
- Glass:Inert material properties anchor premium perception in Italian wine and German sparkling water segments. Furnace capacity concentrates in Italy and Germany, creating geographic vulnerability to energy price shocks.
- Aluminum:Primary ingot cost volatility on the London Metal Exchange transmits directly into canmaking economics. Post-consumer aluminum streams qualify for food-contact loops through HolyGrail 2.0 digital watermarking deployment across French and German material recovery facilities.
- Paperboard:Liquid packaging board accelerates in ambient juices as brands respond to EU Single-Use Plastics Directive. EFSA safety assessments for novel barrier coatings extend eighteen to thirty-six months, delaying oxygen transmission improvements.
Plastic maintains volume dominance; aluminum climbs the fastest.
End User:
Procurement centralization is unbundling technical service from volume contracts, reshaping supplier relationships.
- Beverage Manufacturers:Carlsberg and Arla Foods operate captive packaging innovation centers in the Nordics that pre-qualify suppliers before tender participation. Direct-to-retailer consolidation compresses converter sales cycles.
- Distributors:Third-party logistics providers prioritize format standardization for pallet optimization and reverse logistics efficiency. Deposit-return infrastructure requirements vary across national boundaries.
- Retailers:German discount chains and French hypermarkets separate specification development from procurement functions. Private label sourcing concentrates with domestic converters to minimize compliance complexity.
- Private Label Brands:Discounter-owned beverage lines drive aggressive cost targets while demanding equivalent barrier performance to branded equivalents. Specification flexibility is limited by retailer quality assurance protocols.
Beverage manufacturers lead on scale; private label brands lead on momentum.
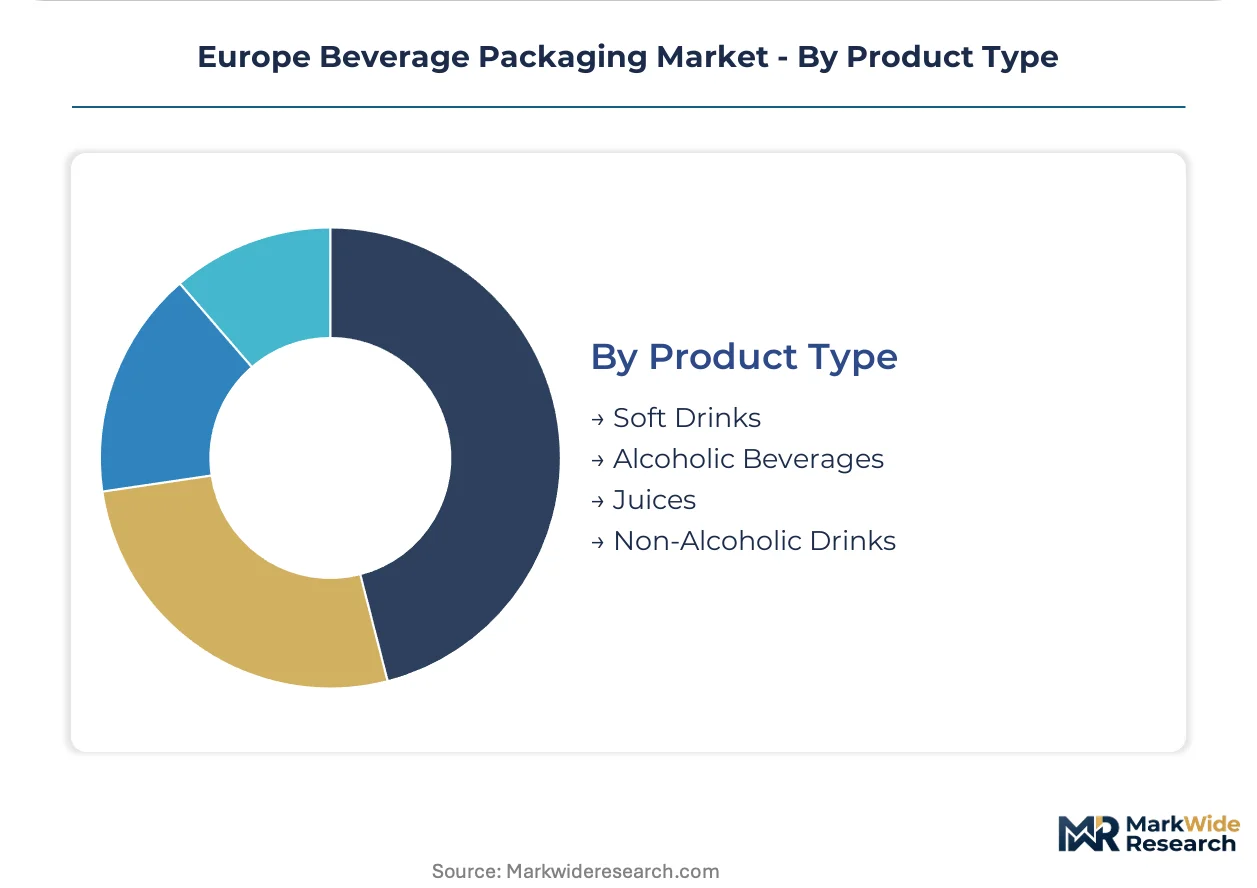
Product Type:
Category-specific shelf-life and premium positioning requirements dictate format selection and barrier investment.
- Soft Drinks:Carbonated formulations demand oxygen and carbon dioxide barrier precision. Aluminum cans and PET bottles split volume based on channel and consumption occasion.
- Alcoholic Beverages:Craft beer producers across Germany, France, and Italy expand aluminum can adoption for hop-forward products requiring superior oxygen barrier performance. Wine exporters face complex cross-border compliance for single-use format exports.
- Juices:Aseptic carton technology opens ambient distribution channels previously limited to chilled supply chains. Hydrogen peroxide sterilization integration with paperboard forming supports oat milk and plant-based dairy alternatives.
- Non-Alcoholic Drinks:Functional beverages with nitrogen-sensitive ingredients face shelf-life ceilings from current ethylene vinyl alcohol oxygen transmission rates near 0.1 cc per package per day.
Soft drinks lead on scale; alcoholic beverages lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German glassblowers pioneered modern beverage bottling in the 19th century Rhineland, establishing technical foundations that spread across Continental Europe. Today's converting landscape retains that industrial DNA while regulatory fragmentation now shapes investment geography.
Germany
Deposit-return mandates sustain refillable glass pools exceeding eighty percent for domestic mineral water producers. Extended producer responsibility schemes under the EU Packaging and Packaging Waste Regulation enforce recycled aluminum thresholds. The Rhine-Ruhr corridor concentrates furnace capacity for premium sparkling water bottles, though energy price volatility threatens operational economics.
France
Hypermarket procurement centralization unbundles technical service from volume contracts, compressing converter sales cycles. EFSA safety assessments for novel barrier coatings extend eighteen to thirty-six months, delaying oxygen transmission improvements. The Île-de-France region hosts captive packaging innovation centers where Arla Foods pre-qualifies suppliers before tender participation.
Italy
Wine exporters face complex cross-border compliance for single-use format exports under draft EU Green Deal delegated acts. Craft beer producers expand aluminum can adoption for hop-forward products requiring superior oxygen barrier performance. Furnace capacity for premium bottles clusters in the Veneto and Piedmont regions, creating geographic exposure to natural gas price shocks.
Poland
Central European beverage production growth outpaces local converting capacity, creating white space for aseptic carton and can line investments. HolyGrail 2.0 digital watermarking deployment across material recovery facilities improves post-consumer aluminum purity streams. The Silesian manufacturing belt attracts integrated converters seeking freight cost advantages into German and Czech markets.
United Kingdom
Post-Brexit regulatory divergence complicates cross-border material approvals for barrier technologies seeking CE marking equivalence. Private label sourcing concentrates with domestic converters to minimize compliance complexity. The Midlands packaging corridor hosts blow-molding lines retooling for recycled PET with degraded mechanical properties requiring extruder screw redesigns.
Europe Beverage Packaging Market Competitive Landscape
The competitive structure tilts toward integrated metal packaging specialists with captive aluminum supply. Three tiers operate: multinational converters controlling rolling and canmaking under one roof, regional glass specialists with furnace assets in Italy and Germany, and paperboard laminators serving ambient dairy alternatives. Dominant moves include diameter reduction programs for lightweighting qualification and strategic partnerships for aseptic technology licensing.
Among metal packaging specialists, Ardagh Group and Ball exemplify the integrated archetype with extensive European can manufacturing footprints. CANPACK occupies a position as a Central European cost leader through aluminum rolling and canmaking integration. Tetra Pak represents the aseptic technology tier, differentiating via barrier carton leadership in ambient juice segments.
| Leading Market Players |
|---|
| Ardagh Group |
| CANPACK |
| Amcor |
| Beatson Clark |
| Tetra Pak |
| Ball |
| Smurfit Kappa Group |
| Vidrala |
| Mondi Group |
| Others |
Supply & Pricing Matrix
Glassblower workforce concentration in the Italian Veneto and German Rhineland regions anchors labor-cost differentials that translate into pricing-tier spreads across premium sparkling water and standard mineral water segments. These craft-legacy clusters command wage premiums that feed into tiered converter quotations, while Central European automated can lines compress unit economics for economy-tier energy drinks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs converter quotations, with differentiation driven by barrier certification grade and volume scale commitments. Premium tiers absorb EFSA-validated oxygen transmission performance below 0.1 cc per package per day, while economy segments face cost compression from recycled PET mechanical degradation requiring IV booster investments. Private label brands at German discount chains exhibit highest price sensitivity; craft beer producers demonstrate lowest sensitivity due to format premiumization strategies.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor and northern Italian industrial districts operate hub-and-spoke patterns feeding French hypermarkets and Central European beverage plants. Supply concentrates in Germany, Italy, and Poland, with furnace capacity clustering in Veneto and Piedmont while canmaking assets spread across Silesia and the Czech Republic. Raw material dependencies center on primary aluminum ingots, liquid packaging board, and soda-lime glass batch chemicals. Single-source vulnerability to natural gas price shocks threatens Italian furnace economics. Distribution runs through pallet-optimized networks serving deposit-return infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in Europe beverage packaging rests on aluminum lightweighting programs and aseptic technology licensing fees that capture premium-tier shifts in plant-based dairy alternatives.
For Market Incumbents: Deploy diameter-reduction metallurgy to defend position against emerging Central European converters with integrated rolling capacity. Ardagh Group and Ball Corporation must accelerate 202-end lightweighting qualifications ahead of EU Green Deal circular economy labeling deadlines. Captive aluminum supply agreements with London Metal Exchange hedging programs anchor margin stability against ingot volatility.
For New Entrants and Emerging Players: Enter via aseptic carton white space in Poland and the Czech Republic, where beverage production growth outpaces local converting capacity. Target oat milk and plant-based dairy alternatives previously limited to chilled supply chains through hydrogen peroxide sterilization integration. License barrier coating technology from established laminators rather than pursuing eighteen-to-thirty-six-month EFSA certification timelines independently.
For Investors and Strategic Acquirers: Beverage manufacturers with captive packaging innovation centers are the most active acquirer in this space, seeking backward integration into canmaking and aseptic forming assets. Long-term viability favors converters with food-contact recycling loop qualifications under HolyGrail 2.0 digital watermarking deployment. Watch for inflection in EU Packaging and Packaging Waste Regulation delegated acts that mandate binding reuse targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Lightweighting Program | Twelve-gram per-can reductions qualify products for circular economy labeling under draft EU Green Deal acts. |
| Aseptic Technology Licensing | Hydrogen peroxide sterilization integration opens ambient distribution for oat milk and plant-based alternatives. |
| Backward Integration into Rolling | CANPACK's captive aluminum supply controls cost structures across Central European markets against LME volatility. |
| Digital Watermarking Deployment | HolyGrail 2.0 sorting technology improves post-consumer aluminum purity for food-contact recycling loops. |
| Refillable Glass Pool Expansion | German mineral water producers exceed eighty percent returnable bottle share under deposit-return mandates. |
Research Methodology
Coverage spans Western Europe, Central Europe, and the Nordic region, with primary inputs from each territory combined with secondary validation. Interviews with beverage procurement directors, converter plant managers, EFSA regulatory affairs specialists, and retail category buyers triangulate against customs records, SEC filings from listed packaging groups, EU regulatory databases, and trade association data from metal packaging federations. Bottom-up volume modeling and top-down value reconciliation ensure cross-verification.
Granularity extends to packaging format, material specification, end-user procurement archetype, and national regulatory cluster across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by aluminum ingot price scenarios and EPR fee modulation assumptions. Modeled inputs include oxygen transmission rate specifications, recycled content thresholds under national extended producer responsibility schemes, and aseptic line capacity expansion pipelines.
The model holds under stable EU regulatory implementation schedules; deviation in delegated act timing or REACH compliance acceleration would shift converter investment cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Soft Drinks Packaging Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Combi Cans Market
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Beverage Packaging Machine Market