
 Combi Cans Market | 2026-2036
Combi Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Combi Cans Market Analytics
Specialty chemical distributors is redrawing procurement patterns across the Combi Cans Market as just-in-time solvent blending replaces bulk tank deliveries. Mauser Packaging Solutions leverages its closed-loop reconditioning network to anchor long-term supply contracts with German industrial coatings plants. Silgan Holdings sustains margin density through dedicated metal combi can lines purpose-built for flammable liquid UN ratings. Greif competes by controlling captive steel drum and intermediate bulk container capacity that feeds combi can adjacencies.
Combi cans are dual-compartment or multi-chamber rigid containers, typically constructed from tinplate steel or high-density polyethylene with integrated pour spouts and venting mechanisms, engineered to store and dispense two-part systems or segregated contents within a single handling unit. Their primary commercial purpose centers on safe transport of reactive chemicals, two-component adhesives, and separated food ingredients where cross-contamination or premature mixing must be prevented. Metal combi cans retain dominant share in chemical storage applications where UN certification and solvent compatibility command premium positioning, while plastic combi cans represent the fastest-expanding category as polypropylene barrier technologies improve resistance to aggressive agrochemical formulations. Composite combi cans, layering polymer liners within steel shells, concentrate margin pools in specialty lubricants and marine coatings where extended shelf stability justifies unit cost premiums.
The EPA's hazardous waste container regulations and OSHA's flammable liquids storage standards shape material selection and venting specifications for US-manufactured combi cans, while REACH and the EU Packaging and Packaging Waste Directive mandate recyclability thresholds and substance restrictions across European supply chains. Germany's Federal Institute for Materials Research and Testing enforces additional mechanical performance benchmarks for dangerous goods transport that filter market access. Stakeholders must monitor evolving PFAS restrictions and recycled content mandates, as these frameworks will determine which substrate technologies retain commercial viability.
Market Dynamics
REACH compliance deadlines and UN-certified dangerous goods standards are compressing material substitution timelines across European supply chains, forcing specialty chemical producers to validate alternative substrates before legacy tinplate formulations lose regulatory clearance.
Growth Catalysts
- Automotive coatings clustering:Germany's industrial packaging corridor concentrates demand from solvent-based formulation plants serving OEM refinishing operations, creating density economies for combi can suppliers.
- REACH substance restrictions:The EU's phased bans on chromium VI in metal surface treatments are accelerating migration toward epoxy-phenolic linings that combi can architectures accommodate.
- Polypropylene barrier advancement:Improved resistance to aggressive agrochemical formulations is expanding plastic combi can penetration into crop protection chemical packaging previously reserved for steel.
Market Restraints
- Tinplate price volatility:Steel input cost swings compress margin predictability for metal combi can producers serving price-locked annual contracts.
- German testing institute concentration:BAM certification requirements filter market access, creating bottleneck dependency on a single national laboratory for UN dangerous goods validation.
- Intermediate bulk container substitution:Refillable IBC systems capture volume from bulk solvent distributors, constraining combi can demand in tank-to-tank transfer applications.
Strategic Opportunities
- Marine coatings shelf stability:Composite combi cans layering polymer liners within steel shells command premium positioning in specialty lubricants where extended storage justifies unit cost premiums.
- Agrochemical two-part systems:Segregated chamber designs for separated herbicide components remain underpenetrated in Brazil's crop protection distribution network.
- EU Packaging and Packaging Waste Directive:Recycled content mandates create first-mover advantage for suppliers with closed-loop reconditioning infrastructure.
Industry Challenges
- PFAS regulatory uncertainty:Evolving restrictions on fluorinated polymer barriers force simultaneous multi-substrate qualification programs without clear compliance endpoints.
- UN certification timeline compression:Dangerous goods testing queues at notified bodies extend new product introduction cycles beyond customer contract renewal windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combi Cans Market |
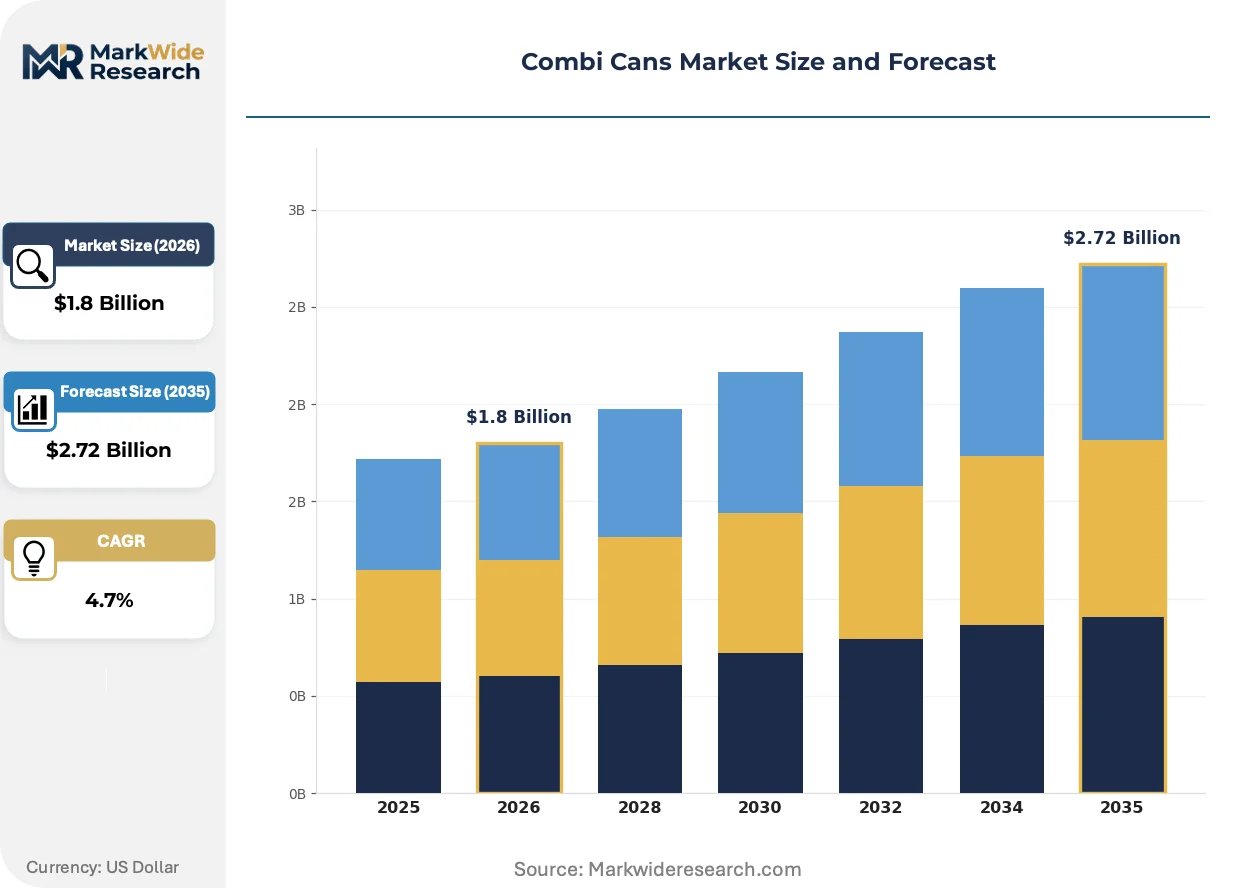
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Combi Cans, Metal Combi Cans, Composite Combi Cans, Glass Combi Cans Application: Food Storage, Beverage Packaging, Chemical Storage, Household Products End User: Manufacturers, Retailers, End Consumers, Distributors Capacity: 1L, 5L, 10L, 20L |
| Companies Covered | Mauser Packaging Solutions, Silgan Holdings, Berry Global, Greif, Schütz, DS Containers, CCL Container, Envases Group, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combi Cans Market Evolving Landscape
Material science convergence with regulatory chemistry is redefining combi can competitive advantage, as barrier performance becomes inseparable from hazardous substance compliance documentation.
Multi-layer coextruded polypropylene with ethylene vinyl alcohol interlayers is supplanting monolithic HDPE in agrochemical combi can production. German crop protection distributors are qualifying these structures for paraquat dichloride formulations previously restricted to steel. The shift is compressing metal substrate demand in volume agricultural segments while opening margin pools in barrier-engineered plastics.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing liner reformulation across European metal combi can supply chains. Manufacturers must validate epoxy-phenolic and polyester alternatives to fluoropolymer coatings before 2025 restriction deadlines. Specialty chemical segments with aggressive solvent profiles face the steepest qualification burden, with automotive coatings plants accelerating supplier audits.
Just-in-time solvent blending is displacing bulk tank farm deliveries at German industrial coatings facilities. Distributors are downsizing order quantities and compressing replenishment cycles, favoring combi can formats over drum-and-pump systems. The pattern concentrates in Bavaria's automotive supplier belt, where paint mixing rooms operate on 48-hour inventory turns.
Combi Cans Market Segmentation
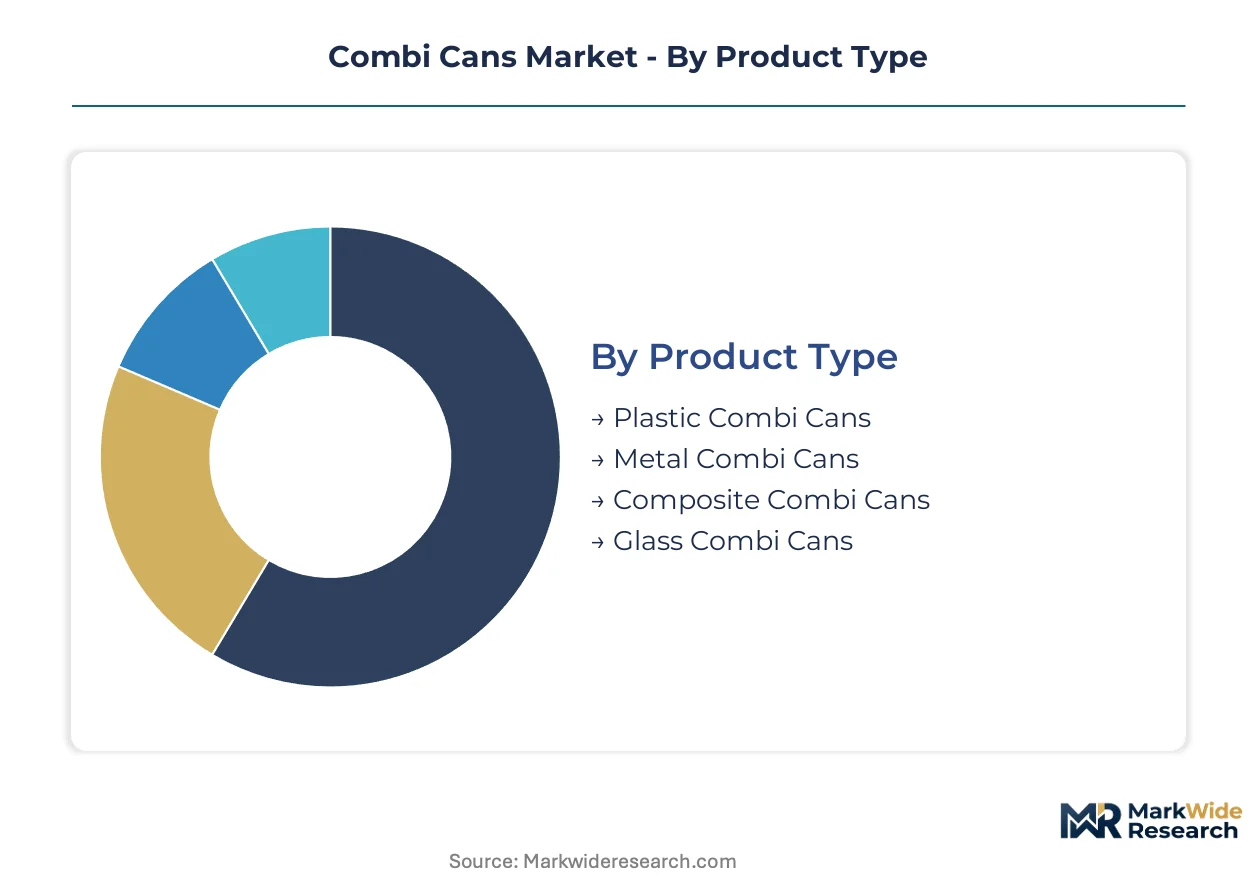
Combi can segmentation reveals divergent margin structures across substrate technologies and regulatory complexity tiers. Product type splits reflect fundamentally different certification burdens and end-use concentration patterns.
Product Type:
Margin pools concentrate in metal and composite architectures where UN dangerous goods certification creates pricing power and customer lock-in.
- Metal Combi Cans:Tinplate steel construction with epoxy-phenolic or fluoropolymer linings delivers solvent compatibility and UN-certified dangerous goods transport. REACH Annex XVII compliance timelines are forcing liner reformulation across German automotive coatings supply chains, compressing qualification windows for legacy chromium VI surface treatments.
- Composite Combi Cans:Polymer-lined steel shells command premium positioning in marine coatings and specialty lubricants where extended shelf stability justifies unit cost premiums. Bavaria's industrial packaging corridor concentrates demand from two-component adhesive formulators requiring oxygen and moisture barrier performance.
- Plastic Combi Cans:Multi-layer coextruded polypropylene with ethylene vinyl alcohol interlayers is displacing monolithic HDPE in agrochemical applications.
- Glass Combi Cans:Borosilicate dual-chamber designs serve laboratory reagent and high-purity chemical segments with visibility requirements.
Metal combi cans hold installed capacity. Composite combi cans are rotating up the share rankings.
Application:
Application segmentation tracks divergent regulatory exposure, with chemical storage commanding compliance premiums and food storage facing migration testing intensification.
- Chemical Storage:Solvent-based formulations, two-component adhesives, and reactive systems dominate volume. Germany's Federal Institute for Materials Research and Testing enforces mechanical performance benchmarks that filter market access for dangerous goods transport.
- Food Storage:Segregated ingredient systems for baking and confectionery require EU Regulation 10/2011 compliance on plastic materials in contact with food. Migration testing protocols are tightening for dual-chamber designs with polymer barriers.
- Beverage Packaging:Dual-compartment drink systems and separated flavor bases concentrate in premium beverage innovation pipelines.
- Household Products:Cleaning agent two-part systems and separated active ingredient formats serve DIY and professional maintenance segments.
Chemical storage anchors revenue density. Food storage is climbing the application hierarchy.
End User:
End user segmentation reflects procurement scale asymmetries, with manufacturers capturing volume discounts and distributors arbitraging specification complexity.
- Manufacturers:Specialty chemical producers and coatings formulators drive specification-setting through just-in-time solvent blending operations. German automotive OEM refinishing plants compress replenishment cycles to 48-hour inventory turns.
- Distributors:Agrochemical and industrial chemical distributors intermediate between producers and application sites, consolidating fragmented demand.
- Retailers:Home improvement and agricultural supply chains stock standard-capacity formats for consumer-facing segments.
- End Consumers:DIY enthusiasts and small-scale applicators purchase through retail channels with limited technical specification involvement.
Manufacturers dictate technical standards. Distributors are gaining procurement leverage.
Capacity:
Capacity segmentation maps to handling infrastructure and transport mode economics, with mid-range formats capturing density advantages in regional distribution.
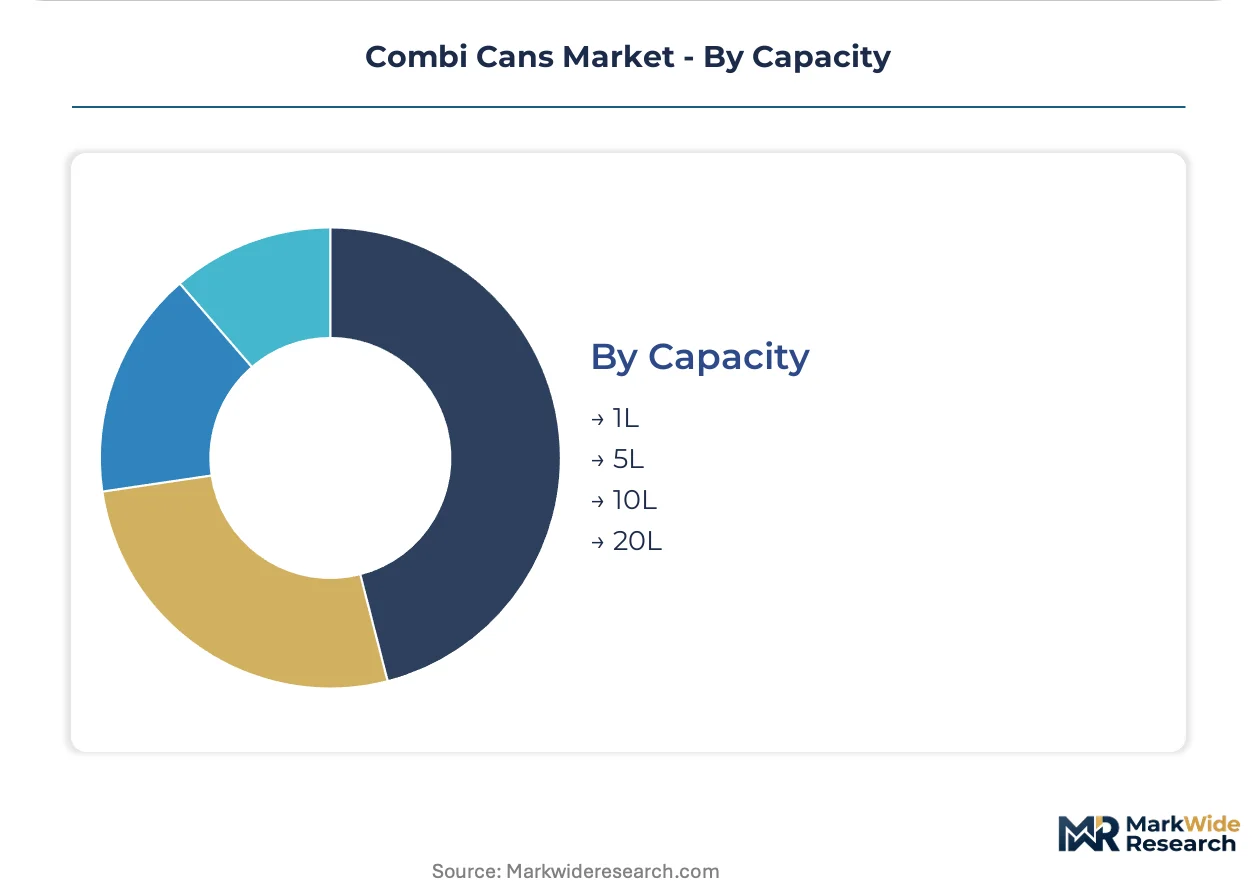
- 5L:Standard intermediate format balances manual handling ergonomics with transport efficiency. German industrial coatings facilities favor this capacity for just-in-time replenishment of mixing rooms.
- 10L:Extended-range format serves medium-batch chemical blending and agricultural spray tank filling operations.
- 1L:Compact format targets laboratory reagents, sample kits, and precision application systems.
- 20L:Bulk-capacity designs compete with drum formats in tank-to-tank transfer applications facing IBC substitution pressure.
5L formats hold production line dominance. 10L capacities are expanding share in agricultural distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel substrate supply chains concentrate in German industrial corridors, where automotive coatings demand and REACH compliance deadlines intersect. Regulatory validation bottlenecks at Germany's Federal Institute for Materials Research and Testing filter market access for dangerous goods certification.
Germany
Bavaria's automotive supplier belt drives solvent-based formulation demand through 48-hour inventory turn operations. REACH Annex XVII substance restrictions on chromium VI surface treatments accelerate epoxy-phenolic liner migration timelines. The Federal Institute for Materials Research and Testing in Berlin maintains exclusive UN dangerous goods validation authority, creating certification queues.
United States
EPA hazardous waste container regulations and OSHA flammable liquids storage standards shape venting specifications for chemical storage applications. Industrial coatings clusters in Michigan and Ohio source metal combi cans for OEM refinishing operations. Midwestern automotive paint mixing rooms favor 5L formats for just-in-time replenishment cycles.
China
GB standards for dangerous goods packaging and MIIT industrial material specifications govern domestic production. Yangtze River Delta chemical formulators adopt multi-layer polypropylene combi cans for agrochemical two-part systems. Shanghai-area coatings plants qualify barrier-engineered plastics for paraquat dichloride formulations previously restricted to steel.
Brazil
ANVISA pharmaceutical packaging regulations and agrochemical registration requirements influence import specifications. São Paulo-state crop protection distributors underpenetrate segregated chamber designs for separated herbicide components. Paraná's agricultural chemical blending facilities represent expansion targets for plastic combi can suppliers.
France
ANSM chemical product safety standards and EU Packaging and Packaging Waste Directive recyclability thresholds shape material selection. Auvergne-Rhône-Alpes specialty lubricant formulators command composite combi can premiums for extended shelf stability. Lyon-area marine coatings producers layer polymer liners within steel shells for oxygen barrier performance.
Combi Cans Market Competitive Landscape
Concentration sits with diversified industrial packaging conglomerates and metal substrate specialists. Tier-one suppliers control UN certification infrastructure and closed-loop reconditioning networks. Three archetypes dominate: steel drum and IBC incumbents extending into combi can adjacencies; dedicated metal packaging specialists with dangerous goods testing capabilities; and plastic barrier technology innovators capturing agrochemical share. Competitive moves center on captive reconditioning infrastructure deployment and multi-substrate qualification programs for PFAS-restricted liner formulations.
Within the diversified packaging tier, Mauser Packaging Solutions and Greif exemplify scale-driven positioning through integrated container service networks. Silgan Holdings occupies a specialist position in metal packaging architectures purpose-built for flammable liquid UN ratings. These three companies anchor competitive dynamics around certification authority and regional density economies rather than pure manufacturing scale.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Silgan Holdings |
| Berry Global |
| Greif |
| Schütz |
| DS Containers |
| CCL Container |
| Envases Group |
| Ball Corporation |
| Others |
Value Network & Pricing Analysis
Forty-eight-hour inventory turns at German automotive coatings plants compress lead-time tolerance to narrow windows, concentrating pricing power with suppliers who control UN-certified reconditioning networks and feedstock security across tinplate-dependent production corridors.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European combi can supply chains, separating premium-certified metal architectures from standard plastic alternatives and economy-grade unlined formats. Price differentiation hinges on UN dangerous goods certification grade and volume scale commitments, with automotive coatings manufacturers showing lowest sensitivity due to specification lock-in while agrochemical distributors face acute pressure from tinplate volatility. Cost compression in standard metal tiers is intensifying because REACH liner reformulation deadlines compress supplier qualification timelines.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes amplify inbound logistics costs for tinplate coil and epoxy-phenolic resin feedstocks. Manufacturing concentrates in Germany, China, and the United States, with raw material dependencies spanning Swedish steel slab, South Korean tin coating services, and Belgian phenolic resin production. Single-source vulnerability sits with Germany's Federal Institute for Materials Research and Testing as the exclusive UN validation authority. Distribution runs through closed-loop reconditioning networks anchored by industrial packaging conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combi can market expansion qualifies as high-growth disruption justified by REACH substance restrictions forcing simultaneous multi-substrate qualification programs across European chemical packaging supply chains.
For Market Incumbents: Consolidate captive reconditioning infrastructure in Germany's Bavarian industrial corridor to defend against plastic barrier technology substitution in agrochemical segments. Deepen backward integration into tinplate coil supply through long-term offtake agreements with Nordic steel producers, insulating margin structures from spot price volatility. For New Entrants and Emerging Players: Lead with multi-layer polypropylene barrier technology targeting Brazil's underpenetrated crop protection distribution network, specifically São Paulo-state herbicide formulators lacking segregated chamber designs. Establish technical partnerships with Yangtze River Delta chemical blenders to accelerate qualification timelines for paraquat dichloride compatibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across composite combi can manufacturing due to polymer-lined steel shell complexity and extended UN certification queues. Five-to-ten-year viability favors acquisition targets with existing BAM validation relationships and closed-loop reconditioning assets. Monitor PFAS regulatory clarity as the critical inflection signal for liner technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tinplate Supply | Captive steel coil access insulates margin structures from LME volatility in German production corridors. |
| Multi-Substrate Qualification Program | Parallel epoxy-phenolic and fluoropolymer liner validation hedges REACH Annex XVII compliance uncertainty. |
| Closed-Loop Reconditioning Network Expansion | EU Packaging and Packaging Waste Directive recycled content mandates reward first-mover infrastructure deployment. |
| Agrochemical Barrier Technology Partnership | Ethylene vinyl alcohol interlayer coextrusion opens Brazilian crop protection volume previously reserved for steel. |
| UN Certification Queue Management | Berlin testing institute relationship compression accelerates product introduction cycles ahead of contract renewals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from packaging conglomerates, Cefic chemical industry reports, and BAM certification records. Interviews with plant managers at German automotive coatings facilities, procurement leads at specialty chemical distributors, technical R&D directors at liner material suppliers, and channel partners in Brazilian agrochemical distribution validated substrate substitution timelines. Bottom-up capacity assessments across tinplate and polypropylene production lines triangulate against top-down demand modeling from end-use industry consumption patterns.
Segmentation dimensions modeled include substrate technology tier, application regulatory complexity, end-user procurement scale, and regional certification framework across the projection horizon. CAGRs derive from installed capacity utilization trajectories and replacement demand elasticities. Forecast inputs incorporate REACH compliance deadline phasing and UN dangerous goods testing queue durations at notified bodies.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or tinplate supply stability would require recalibration. Forecasts reflect documented assumptions regarding liner reformulation success rates and agrochemical distributor adoption curves for plastic barrier alternatives. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Bomber Bottles Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Heavy Wall Bottles Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Pouring Spout Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Bottle Shippers Market