
 Baritainer Jerry Can Market | 2026-2036
Baritainer Jerry Can Market Size, Share, and Industry Trends Forecast 2026-2036
Baritainer Jerry Can Market Outlook
Skilled polymer processing engineers familiar with fluorination and co-extrusion barrier technologies is redrawing competitive boundaries in container manufacturing. Mauser Packaging Solutions leverages integrated blow-molding operations across European plants to sustain cost leadership in multilayer HDPE jerry cans. Greif Inc. anchors North American supply through captive resin compounding and regional distribution hubs. Time Technoplast Ltd. specializes in narrow-mouth designs for Indian agrochemical clients, competing on localized mold customization and faster turnaround cycles.
A baritainer jerry can denotes a multilayer plastic container engineered with fluorinated or co-extruded barrier layers—typically EVOH or PA6 interlayers within HDPE walls—to prevent hydrocarbon permeation, odor migration, and chemical degradation during storage and transport. These containers serve industrial sectors requiring compliant, lightweight alternatives to metal drums for solvents, fuels, lubricants, and agricultural chemicals. Standard jerry cans dominate volume throughput in automotive and bulk chemical logistics, while flexible jerry cans represent the fastest-expanding format for field-deployed agrochemical and military applications where collapsibility reduces return freight. HDPE sustains the largest material share due to its chemical resistance and recyclability, though polypropylene gains ground in elevated-temperature food-grade and hot-fill industrial uses.
EPA regulations on volatile organic compound emissions and OSHA workplace chemical exposure limits directly shape fluorination depth requirements and permeation testing protocols for U.S.-sold barrier containers. REACH and the EU F-Gas Regulation in Europe mandate substitution documentation and recyclability disclosures that favor co-extruded barrier structures over post-mold fluorinated alternatives. India's BIS certification for plastic containers used in hazardous chemical transport adds compliance layers for exporters serving subcontinent chemical processors. Stakeholders must monitor evolving extended producer responsibility frameworks and per- and polyfluoroalkyl substance restrictions that could force material redesigns across multiple jurisdictions simultaneously.
Market Dynamics
Co-extruded EVOH barrier technology is displacing post-mold fluorination as REACH documentation requirements harden across European chemical logistics, forcing container manufacturers to requalify entire product lines.
Growth Catalysts
- REACH compliance mandates:Specialty chemical distributors in Germany and the Netherlands are expanding procurement of barrier-layer containers to meet hazardous substance transport documentation requirements.
- Agrochemical packaging substitution:Fluorination and co-extrusion advances in HDPE multilayer construction are replacing metal alternatives in agricultural chemical handling.
- Automotive fluid logistics:The German industrial corridor generates concentrated demand for odor-barrier and hydrocarbon-resistant containment solutions in precision chemical distribution.
Market Restraints
- Fluorinated polymer input volatility:Per- and polyfluoroalkyl substance feedstock costs fluctuate with regulatory scrutiny on persistent organic pollutants.
- Barrier technology concentration:Skilled polymer processing engineers familiar with fluorination and co-extrusion are concentrated in Western European manufacturing clusters.
- Metal drum residual substitution:Steel containers retain cost advantages in single-use, non-returnable chemical export applications.
Strategic Opportunities
- Indian agrochemical expansion:BIS certification requirements for hazardous chemical transport containers create compliance-driven demand for qualified barrier-layer suppliers.
- Flexible format penetration:Collapsible jerry can designs address military and field-deployed agrochemical applications where return freight reduction matters.
- Hot-fill industrial applications:Polypropylene barrier formulations capture elevated-temperature food-grade and industrial chemical segments beyond standard HDPE thermal limits.
Industry Challenges
- Fluorination depth calibration:EPA volatile organic compound emission limits and OSHA workplace exposure thresholds require precise permeation testing protocol alignment.
- Extended producer responsibility integration:Evolving recyclability disclosure mandates across multiple jurisdictions force simultaneous material redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baritainer Jerry Can Market |
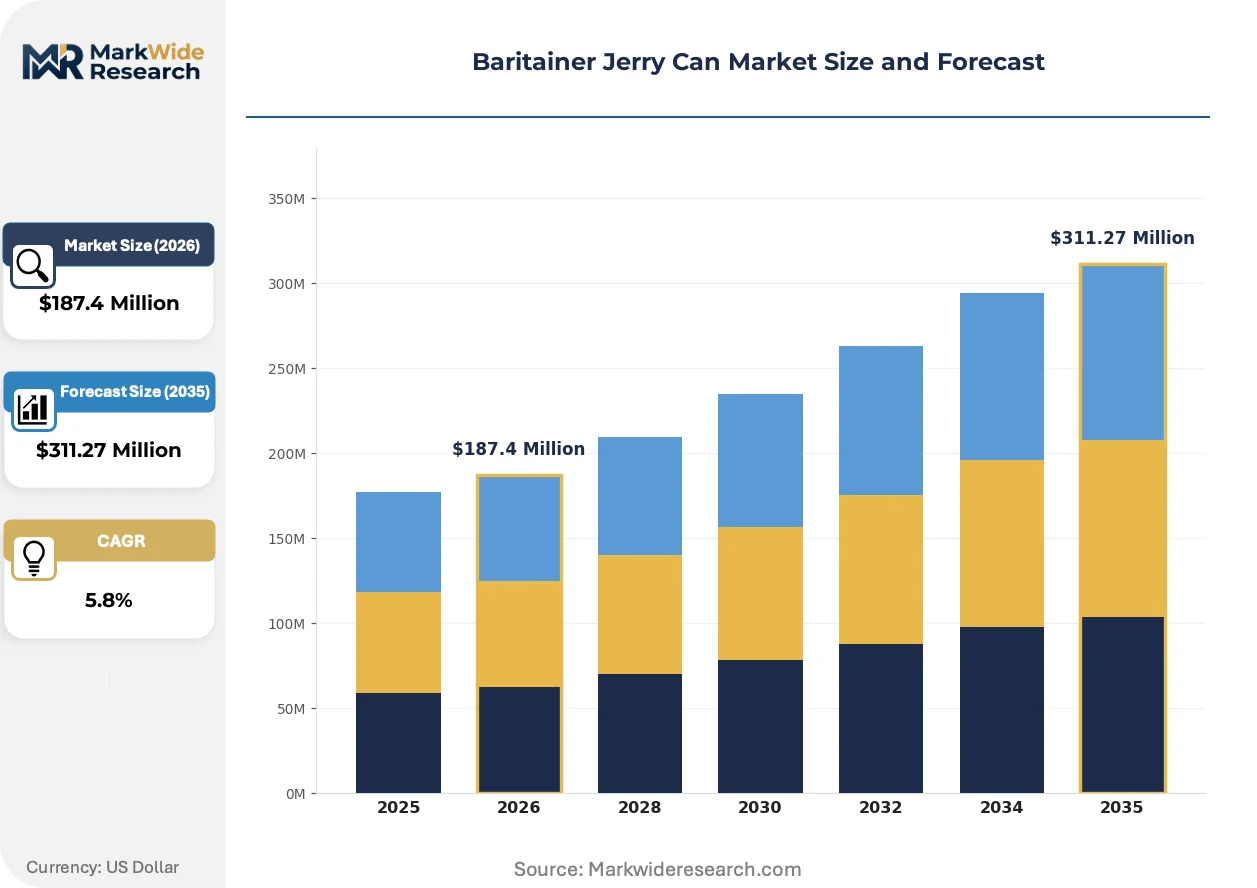
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Jerry Can, Narrow Mouth Jerry Can, Wide Mouth Jerry Can, Flexible Jerry Can Material: HDPE, Metal, Glass, Polypropylene Capacity: 5L, 10L, 20L, 25L End Use: Automotive, Chemical, Food & Beverage, Industrial |
| Companies Covered | Mauser Packaging Solutions, Greif Inc., Schuetz Container Systems, Time Technoplast Ltd., Berry Global Inc., Amcor Limited, Greiner Packaging International GmbH, RPC Group PLC, Nampak Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baritainer Jerry Can Market Strategic Shifts
Barrier-layer manufacturing is splitting into two technical camps as environmental compliance overtakes pure performance metrics in procurement decisions. This divergence is reshaping capital allocation across blow-molding operations.
Co-extruded multilayer HDPE construction incorporating EVOH or PA6 interlayers is bifurcating the container market into REACH-documented premium tiers and legacy fluorinated alternatives. Automotive fluid handlers and precision chemical distributors in Germany are adopting co-extruded formats at accelerated rates. This technical division is compressing margins for post-mold fluorination specialists while rewarding integrated barrier-layer producers with compliant product portfolios.
The EU F-Gas Regulation and REACH substitution documentation requirements are mandating recyclability disclosures that favor co-extruded structures. Container manufacturers must now maintain dual qualification pathways for European and export markets. Agrochemical packaging segments face the steepest compliance burden as they serve both regulated European buyers and less stringent export destinations.
Buying organizations are consolidating vendor relationships around certified barrier-layer suppliers capable of unified compliance documentation. Automotive OEMs and chemical distributors are replacing fragmented multi-source procurement with preferred supplier frameworks. This concentration is most visible in the German industrial corridor where REACH-aligned procurement departments demand single-point accountability for hazardous substance containment.
Baritainer Jerry Can Market Segmentation
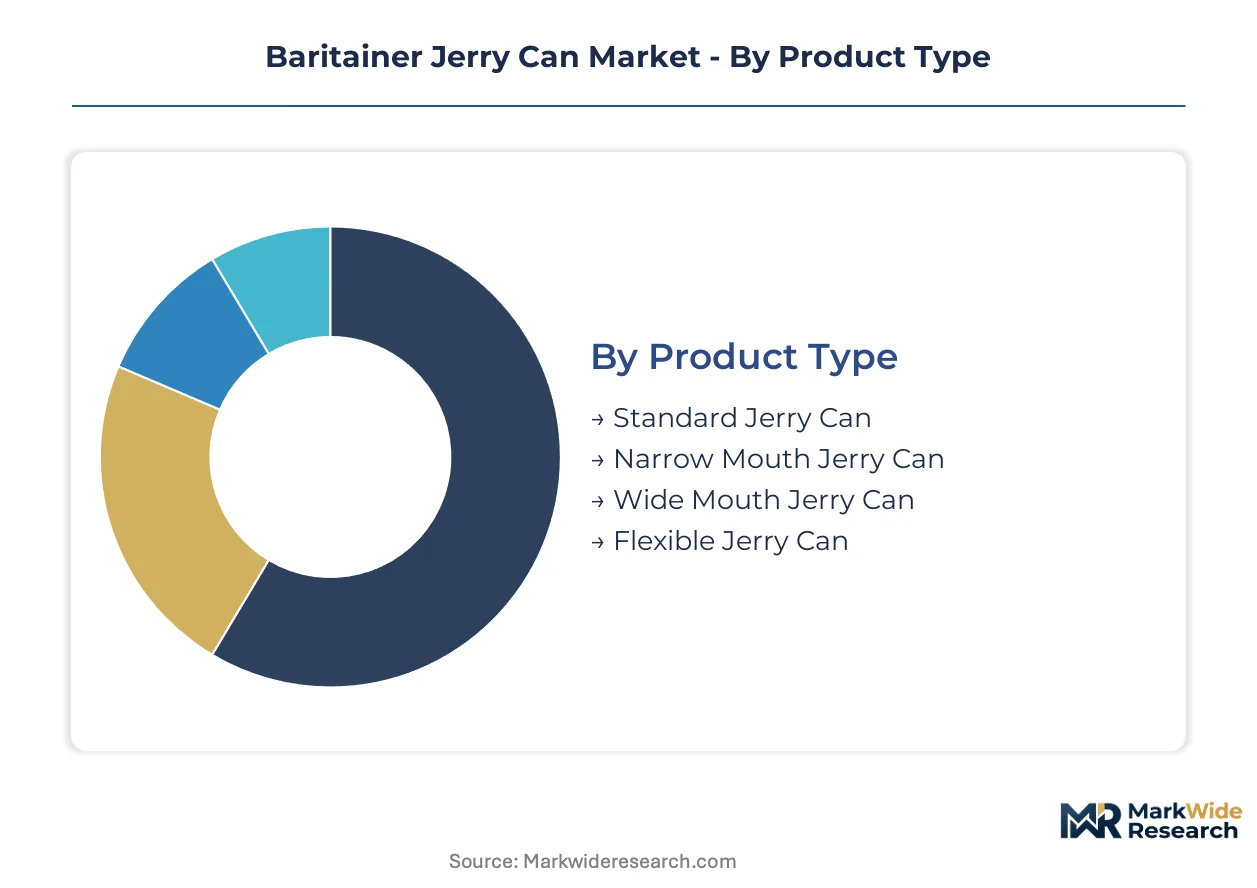
Baritainer jerry can procurement channels diverge sharply by segment, with industrial distributors favoring standard formats while specialty chemical handlers drive narrow-mouth and flexible variants. Channel mix decisions hinge on REACH documentation burdens, return logistics economics, and fluorination versus co-extrusion qualification requirements.
Product Type:
Industrial distributors and automotive fluid handlers channel standard formats through high-volume procurement frameworks, while agrochemical and military buyers route narrow-mouth and flexible designs through specialized packaging suppliers.
- Standard Jerry Can:Multilayer HDPE construction with EVOH or PA6 interlayers serves automotive OEMs and bulk chemical distributors across Germany's industrial corridor. Mauser Packaging Solutions and Greif Inc. dominate this channel through integrated blow-molding operations and captive resin compounding.
- Flexible Jerry Can:Collapsible barrier-layer designs reduce return freight costs for field-deployed agrochemical applications and military logistics. Indian agrochemical expansion and BIS certification requirements are accelerating procurement through specialized export channels.
- Narrow Mouth Jerry Can:Precision chemical handling formats with controlled pour characteristics serve laboratory and specialty chemical distributors in the Netherlands.
- Wide Mouth Jerry Can:Easy-access designs facilitate solids handling and viscous material transfer in food-grade and industrial chemical segments.
Standard jerry cans dominate installed base. Flexible formats are where expansion concentrates.
Material:
Cost tiers stratify sharply around barrier technology maturity, with fluorinated HDPE commanding premium positioning against emerging co-extruded alternatives.
- HDPE:Fluorinated and co-extruded multilayer constructions anchor volume throughput due to chemical resistance, recyclability, and REACH-compliant documentation pathways. German automotive fluid logistics and precision chemical distribution generate concentrated demand for hydrocarbon-resistant HDPE barrier layers.
- Polypropylene:Elevated-temperature formulations capture hot-fill industrial applications and food-grade segments beyond standard HDPE thermal limits. EU F-Gas Regulation and extended producer responsibility frameworks favor PP in temperature-critical supply chains.
- Metal:Steel containers retain cost advantages in single-use, non-returnable chemical export applications where barrier documentation is less stringent.
- Glass:Inert containment for ultra-high-purity chemicals and pharmaceutical intermediates where permeation tolerance approaches zero.
HDPE commands volume leadership. Polypropylene is climbing the fastest on temperature-performance differentiation.
Capacity:
Volume scale determines handling infrastructure requirements, with 20L formats aligning to pallet optimization and manual handling regulations.
- 20L:The logistical sweet spot for automotive fluid distribution and bulk chemical transport, matching standard pallet configurations and OSHA manual handling thresholds. German industrial corridor procurement concentrates heavily in this format.
- 10L:Mid-scale containers serve field-deployed agrochemical applications and specialty chemical sampling where portability outweighs unit economics.
- 5L:Compact formats for laboratory chemicals, pilot-scale production, and restricted-quantity hazardous substance transport under REACH documentation.
- 25L:Maximum manual handling capacity for industrial chemical bulk transfer and drum substitution programs.
20L formats dominate installed base. 10L capacities are gaining share fastest on field mobility requirements.
End Use:
Application-specific compliance burdens reshape customer type concentration, with automotive and chemical sectors driving barrier technology qualification.
- Chemical:REACH substitution documentation and EPA volatile organic compound emission limits force precise fluorination depth calibration and permeation testing protocol alignment. Specialty chemical distributors in Germany and the Netherlands are expanding barrier-layer procurement to meet hazardous substance transport requirements.
- Automotive:OEM fluid handling and precision chemical logistics demand odor-barrier and hydrocarbon-resistant containment solutions, with co-extruded EVOH formats displacing post-mold fluorination at accelerated rates.
- Industrial:Broad-spectrum chemical handling across manufacturing processes, with procurement consolidating around certified barrier-layer suppliers capable of unified compliance documentation.
- Food & Beverage:Hot-fill and elevated-temperature applications favoring polypropylene barrier formulations with BIS and FDA food-contact approvals.
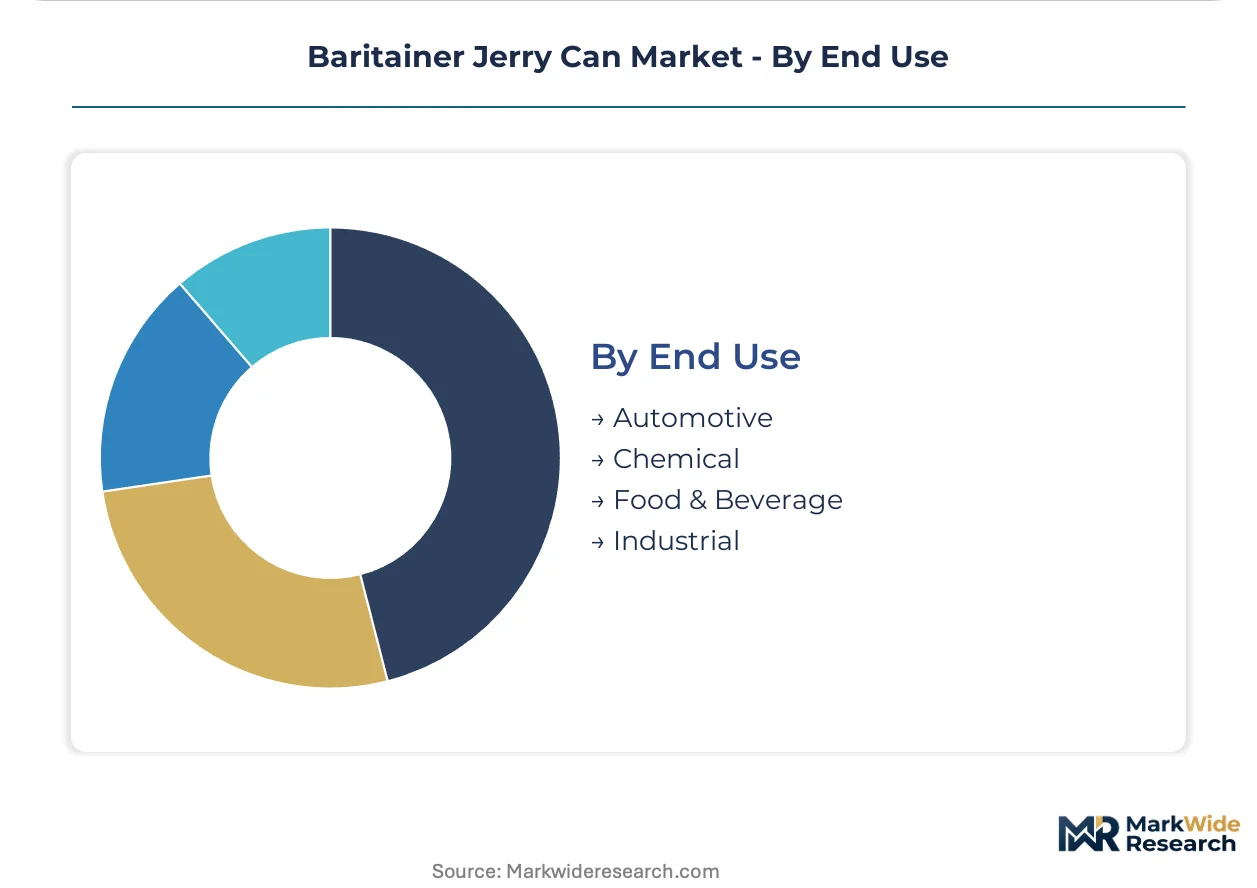
Chemical end use dominates installed base. Automotive applications are where expansion concentrates on co-extrusion technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial corridor while Indian suppliers compete on compliance-driven volume contracts. Container manufacturers in Western Europe command premiums through REACH documentation capabilities. Asian producers capture share through localized certification and faster mold customization cycles.
Germany
Automotive OEMs and precision chemical distributors drive concentrated demand for odor-barrier HDPE containers across the Rhine-Ruhr and Stuttgart manufacturing belts. REACH substitution documentation requirements under ECHA oversight favor co-extruded EVOH formats over legacy fluorinated alternatives. The Baden-Württemberg automotive cluster is accelerating procurement of barrier-layer containers for hydrocarbon-resistant fluid handling systems.
Netherlands
Specialty chemical distributors in Rotterdam-Antwerp port logistics corridors are expanding barrier-layer procurement to meet hazardous substance transport requirements. EU F-Gas Regulation mandates recyclability disclosures that disadvantage post-mold fluorination suppliers. The Eindhoven-Brabant chemical handling hub is consolidating vendor relationships around certified co-extrusion specialists capable of unified compliance documentation.
United States
EPA volatile organic compound emission limits and OSHA workplace exposure thresholds shape fluorination depth requirements for industrial chemical packaging. Automotive fluid logistics in the Midwest manufacturing belt generate steady demand for hydrocarbon-resistant containment. The Gulf Coast petrochemical corridor is witnessing procurement consolidation around suppliers with integrated permeation testing protocols.
India
BIS certification requirements for hazardous chemical transport containers create compliance-driven demand among agrochemical processors and specialty chemical exporters. Maharashtra and Gujarat industrial zones anchor domestic production capacity for barrier-layer HDPE formats. The Pune-Nashik agrochemical belt is accelerating adoption of narrow-mouth designs through localized mold customization capabilities.
China
MIIT industrial packaging standards and evolving environmental compliance frameworks reshape barrier technology qualification pathways for export-oriented chemical manufacturers. Yangtze River Delta chemical processors are evaluating co-extruded alternatives to fluorinated containers for European-bound shipments. The Shanghai-Ningbo port logistics cluster is driving procurement consolidation around suppliers with dual REACH and GB standards certification.
Baritainer Jerry Can Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the baritainer jerry can market. Integrated multilayer blow-molding specialists with captive resin compounding operations command premium positioning through REACH-aligned documentation capabilities. Regional fabricators with localized mold customization expertise compete on turnaround speed and certification agility. Dominant competitive moves include backward integration into barrier resin supply and geographic expansion through preferred supplier frameworks with automotive OEMs.
Among Western European integrated packaging groups, Mauser Packaging Solutions and Greif Inc. exemplify the scale-driven archetype with multiregional blow-molding footprints. Time Technoplast Ltd. represents the specialized regional fabricator model focused on compliance-driven emerging market penetration. These three anchors illustrate the market's structural division between documentation-heavy premium tiers and speed-oriented volume plays.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Greif Inc. |
| Schuetz Container Systems |
| Time Technoplast Ltd. |
| Berry Global Inc. |
| Amcor Limited |
| Greiner Packaging International GmbH |
| RPC Group PLC |
| Nampak Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between German automotive OEMs and integrated blow-molding specialists lock in multi-year supply access while anchoring price visibility for EVOH-barrier HDPE containers against fluorinated alternative volatility. These contracts insulate procurement departments from REACH-driven material substitution cycles while compressing spot-market liquidity for non-integrated suppliers.
Pricing Analysis
Configured-to-order pricing for narrow-mouth and flexible formats commands 15-25% premiums over standard 20L multilayer HDPE jerry cans. Price differentiation rests on fluorination depth certification and REACH substitution documentation tiers, with automotive fluid handlers showing lowest price sensitivity due to compliance liability exposure. Cost compression in post-mold fluorination tiers is intensifying because EVOH co-extrusion specialists are capturing German industrial corridor volume at contract rates. Agrochemical distributors in export markets exhibit highest price sensitivity, routing procurement toward Indian fabricators with BIS certification and faster mold customization cycles.
Supply Chain Analysis
Rotterdam-Antwerp port logistics throughput underwrites barrier-layer container distribution across the Rhine-Ruhr manufacturing belt and into Stuttgart automotive clusters. Manufacturing concentrates in Germany, the Netherlands, and India, with HDPE resin compounding and EVOH interlayer supply drawing from Belgian and Dutch petrochemical corridors. Single-source vulnerability sits with specialized fluorination equipment providers concentrated in Western European engineering clusters. Distribution runs through integrated packaging groups with captive blow-molding operations and regional distribution hubs serving REACH-compliant procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baritainer jerry can market is cycling through a compliance-driven recovery phase as REACH substitution documentation and EPA volatile organic compound limits force container requalification across automotive and chemical end uses. This regulatory wave is compressing legacy fluorination margins while rewarding integrated co-extrusion specialists with certified product portfolios.
For Market Incumbents: Compound defensive positioning through backward integration into EVOH barrier resin supply and capacity reservation agreements with German automotive OEMs facing REACH requalification deadlines. Threat from emerging Indian fabricators with BIS certification and localized mold customization capabilities demands accelerated documentation automation to maintain preferred supplier status in consolidated procurement frameworks. For New Entrants and Emerging Players: Anchor in flexible jerry can formats for Indian agrochemical expansion and military field-deployed applications where return freight economics drive procurement decisions. The most penetrable white space sits in 10L narrow-mouth designs for specialty chemical distributors in the Netherlands requiring controlled pour characteristics and faster turnaround than integrated multinationals provide. Go-to-market execution should emphasize BIS certification agility and mold customization speed against incumbent lead times. For Investors and Strategic Acquirers: Regional co-extrusion specialists with REACH-aligned documentation capabilities and captive automotive OEM relationships represent the highest-conviction acquisition archetype for this market. Long-term viability over the next decade rests on substitution documentation automation and extended producer responsibility compliance integration. The signal to watch is EU F-Gas Regulation tightening on post-mold fluorination, which would accelerate co-extruded format adoption and compress legacy specialist valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Resin Supply | Captive EVOH interlayer production secures margin control against petrochemical feedstock volatility. |
| REACH Documentation Automation Investment | Digital substitution documentation platforms accelerate German automotive OEM requalification cycles. |
| Flexible Format Manufacturing Scale-Up | Collapsible jerry can capacity captures Indian agrochemical and military logistics expansion. |
| BIS Certification-First Market Entry | Pre-qualified barrier-layer designs unlock Maharashtra and Gujarat agrochemical processor contracts. |
| Extended Producer Responsibility Integration | Recyclability disclosure capabilities align with EU Green Deal mandates across packaging value chains. |
Study Parameters
The analysis maps fluorinated HDPE, co-extruded EVOH/PA6 barrier, and polypropylene hot-fill sub-sectors, each validated through procurement directors at German automotive OEMs, specialty chemical distributors in Rotterdam-Antwerp corridors, and plant managers at Indian agrochemical processors. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from ECHA REACH registration databases, EPA VOC emission compliance filings, and BIS certification records. Bottom-up volume builds across product type, material, capacity, and end-use segments were triangulated against top-down chemical logistics trade flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled barrier technology format, end-use industry compliance burden, regional regulatory cluster, and container capacity tier as core segmentation dimensions. CAGRs were derived from installed base substitution rates and net new demand in automotive fluid logistics and agrochemical packaging. Key forecast inputs included REACH documentation timeline assumptions and fluorinated polymer feedstock cost trajectory scenarios.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity and continued automotive OEM procurement consolidation assumptions; material deviation in EU F-Gas Regulation stringency or Indian BIS certification enforcement would warrant model refresh. Practitioners should keep alternative scenarios live as per- and polyfluoroalkyl substance restriction timelines and extended producer responsibility framework implementations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Drink Hoses Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Biotainer Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Bomber Bottles Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Ice Transport Buckets Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market