
 Aluminium Cup Market | 2026-2036
Aluminium Cup Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Cup Market Outlook
ISO 22000 food safety certification is reorganizing competitive access in aluminium cup manufacturing, filtering out smaller metalformers lacking hazard-analysis documentation. Ball Corporation leverages captive aluminium supply from its aerospace-adjacent rolling operations to secure input cost stability. Trivium Packaging anchors European beverage packaging credibility through its Milan and Hamburg production campuses. Novelis competes on recycled-content guarantees, drawing on the world's largest aluminium recycling network to offer verified post-consumer feedstock.
Aluminium cups are cold-formed or deep-drawn vessels fabricated from 1000-series or 3000-series aluminium alloy sheet, typically 0.15–0.35mm thick, valued for thermal conductivity, crush resistance, and infinite recyclability without property degradation. Restaurants and catering services command the dominant demand share as front-of-house presentation standards rise alongside sustainability pledges. Reusable cups capture accelerating interest from event organizers seeking deposit-loop revenue and waste-diversion metrics, while insulated variants occupy a premium niche where temperature retention justifies unit cost multiples.
The US FDA governs direct food-contact aluminium surfaces through 21 CFR 177.1390 laminate specifications, while the EU F-Gas Regulation indirectly steels demand by restricting refrigerant choices that would otherwise preserve plastic alternatives. California's SB 54 producer-responsibility framework and Germany's Verpackungsgesetz amendment tighten compliance burdens that aluminium's established recycling infrastructure absorbs more readily than competing materials. Stakeholders must monitor how deposit-return scheme expansions in additional US states and EU member countries reshape channel economics between disposable and reusable cup formats.
Market Dynamics
Deposit-return scheme expansions across Germany, California, and emerging US states are restructuring channel economics between disposable and reusable aluminium cup formats, forcing manufacturers to retool for circular logistics.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates material substitution toward infinitely recyclable formats, accelerating venue procurement shifts in stadium concessions and outdoor event catering.
- Stadium concessions segment:Venues in Germany and California phase out single-use plastics under deposit-return compliance, normalizing metal drinkware at scale.
- Cold-forming process advancement:Deep-drawn 3000-series alloy fabrication achieves thinner gauges without sacrificing crush resistance, reducing unit material input.
Market Restraints
- Primary aluminium ingot volatility:London Metal Exchange price swings compress margin predictability for cup manufacturers lacking captive rolling supply.
- Concentrated rolling capacity:Aerospace-adjacent aluminium sheet production clusters in select North American and European facilities, creating input bottlenecks.
- Polymer laminate competition:Polypropylene cups retain cost advantage in non-regulated jurisdictions without deposit-return infrastructure.
Strategic Opportunities
- Festival culture penetration in Central Europe:Austria and Netherlands replicate Germany's reusable cup deposit loops at music and sporting events.
- Insulated variant development:Double-wall vacuum construction commands premium positioning where temperature retention justifies unit cost multiples.
- California SB 54 producer-responsibility framework:Expands compliance burdens that aluminium's established recycling infrastructure absorbs more readily than competing materials.
Industry Challenges
- ISO 22000 documentation burden:Hazard-analysis requirements filter smaller metalformers from food-contact certification, consolidating competitive access.
- Deposit-loop logistics integration:Event organizers face reverse-supply chain complexity when scaling reusable cup programs across multi-day festivals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Cup Market |
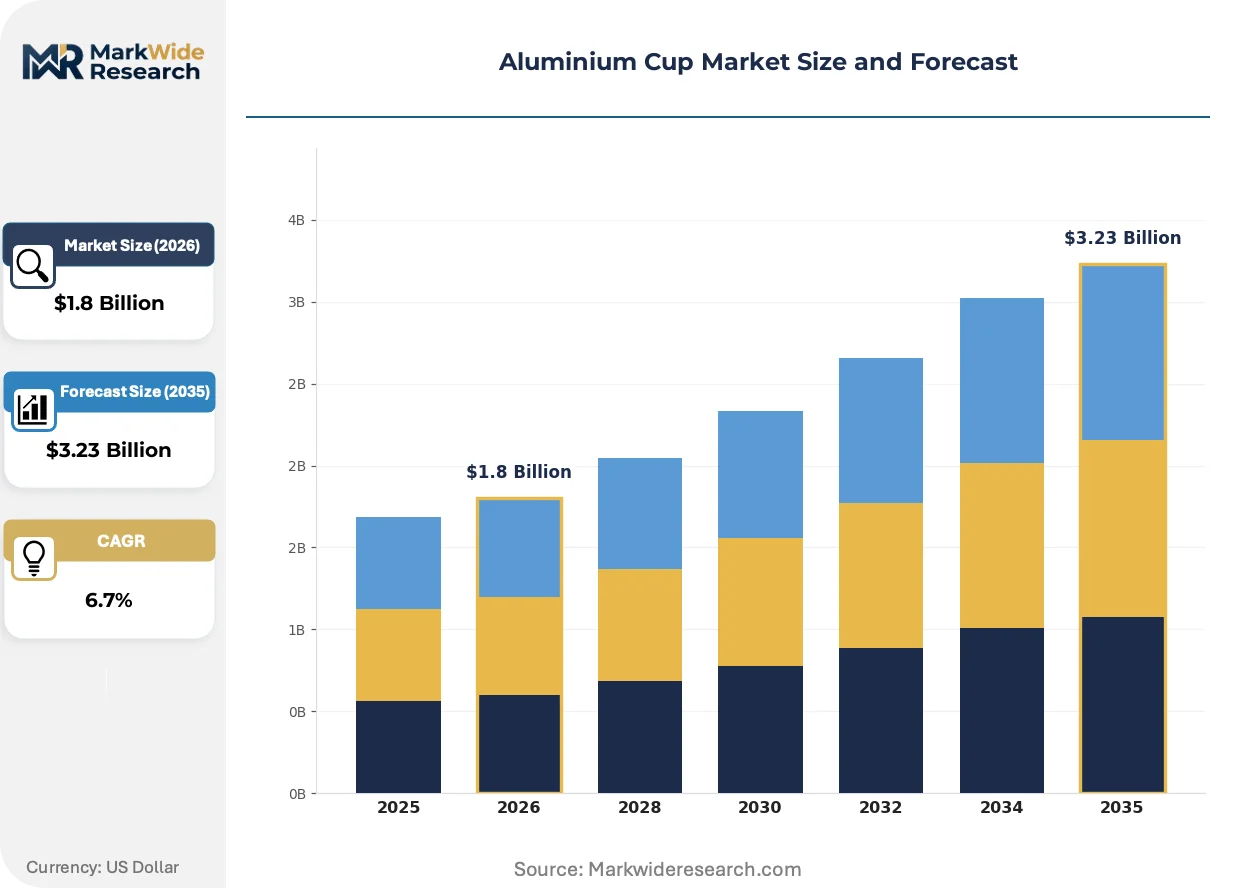
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Cups, Disposable Cups, Insulated Cups, Decorative Cups End User: Restaurants, Catering Services, Retail Outlets, Event Organizers Form: Sleek Design, Classic Design, Eco-Friendly Design, Novelty Design Capacity: 100ml, 250ml, 500ml, 1L |
| Companies Covered | Ball Corporation, Crown Holdings, Trivium Packaging, Ardagh Group, Novelis, Silgan Holdings, Alcoa, Norsk Hydro, Shining Aluminium Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Cup Market Strategic Shifts
Material science advances and regulatory tightening are converging to reposition aluminium cups from commodity drinkware to engineered sustainability solutions with embedded circularity credentials.
Digital printing direct-to-metal is displacing adhesive label applications in premium cup segments. Craft breweries and sports venues adopt UV-cured inkjet decoration for short-run customization at sub-10,000 unit scales. This technology is displacing traditional flexographic label converters from the value chain while compressing lead times from weeks to days.
The EU F-Gas Regulation restricts hydrofluorocarbon refrigerant choices that would otherwise preserve plastic cup alternatives in cold-chain beverage service. Industrial consequence flows through catering equipment procurement, where aluminium's thermal conductivity gains preference. Germany's beverage service sector responds fastest, integrating metal cup formats into mobile refrigeration systems ahead of 2025 compliance deadlines.
Event procurement teams now bundle cup supply with waste-diversion metric guarantees, unbundling traditional disposable packaging contracts. Stadium operators in California and Germany negotiate deposit-loop revenue sharing rather than per-unit purchase. This pattern concentrates most visibly at multi-day music festivals where waste-diversion targets determine vendor selection criteria.
Aluminium Cup Market Segmentation
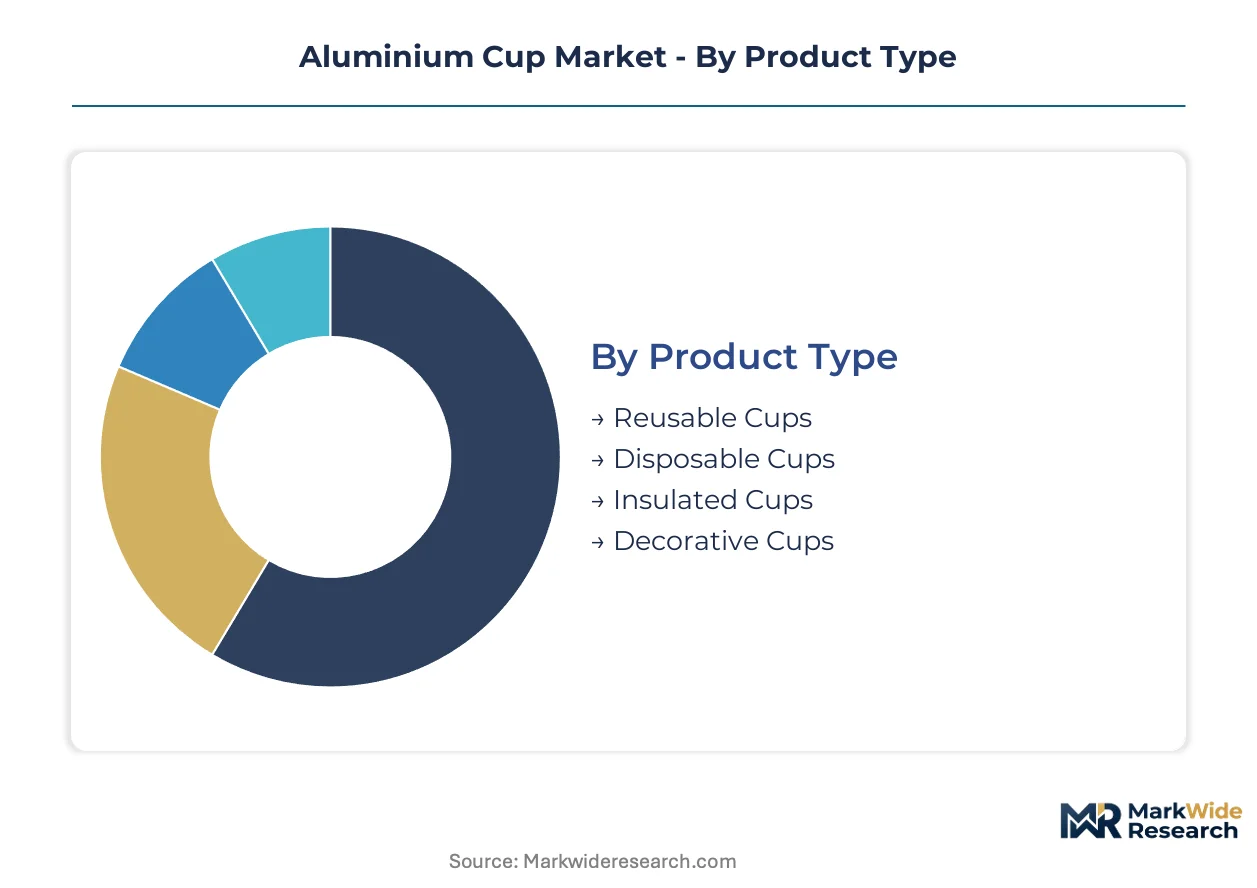
Segmentation in the aluminium cup market reveals how regulatory pressure and venue procurement standards split demand across durability tiers and service formats. Understanding these divides exposes where manufacturers must retool for circular logistics versus single-use throughput.
Product Type:
Margin pools concentrate in formats that capture deposit-loop revenue and command premium positioning through thermal performance differentiation.
- Reusable Cups:Cold-formed 3000-series aluminium vessels engineered for multi-use durability through reinforced rim structures. Germany's festival circuit and California stadium concessions drive procurement at scale as deposit-return compliance mandates displace single-use alternatives.
- Disposable Cups:Single-serve 1000-series aluminium formats with thinner gauge specifications for cost-competitive event service. Polypropylene retains price advantage in jurisdictions lacking producer-responsibility frameworks, constraining aluminium penetration outside regulated markets.
- Insulated Cups:Double-wall vacuum construction targeting temperature retention premiums in outdoor catering and mobile beverage service.
- Decorative Cups:UV-cured direct-to-metal printed variants for craft brewery limited releases and venue-branded merchandise programs.
The dominant share belongs to Reusable Cups, while Insulated Cups is closing the gap fastest.
End User:
Procurement authority clusters in operators facing visible sustainability compliance deadlines and waste-diversion metric disclosure requirements.
- Restaurants:Front-of-house presentation standards in Germany and California normalize metal drinkware for dine-in beverage service. ISO 22000 certification filters supplier access as hazard-analysis documentation becomes mandatory for food-contact approval.
- Catering Services:Mobile refrigeration integration drives thermal conductivity preference as EU F-Gas Regulation restricts hydrofluorocarbon refrigerant choices that would preserve plastic alternatives.
- Retail Outlets:Consumer-facing shelf presence for home entertaining and gift applications, with deposit-return infrastructure absent from purchase decision.
- Event Organizers:Multi-day festival operators in Austria and Netherlands replicate German deposit-loop models for waste-diversion target achievement.
Restaurants holds the largest procurement volume, though Event Organizers is expanding most quickly.
Form:
Aesthetic differentiation tracks venue brand identity requirements and consumer gift-market preferences rather than functional performance.
- Sleek Design:Tapered-wall contemporary profiles dominating California stadium concessions and premium restaurant table service. Digital printing direct-to-metal enables short-run customization at sub-10,000 unit scales, compressing lead times from weeks to days.
- Classic Design:Straight-walled traditional profiles with rolled rims for durability in high-frequency washing environments. Germany's reusable cup infrastructure standardizes around this format for deposit-loop interoperability across venue networks.
- Eco-Friendly Design:Minimal-material profiles with visible recycled-content markings for sustainability messaging in retail channels.
- Novelty Design:Shaped vessels for themed events and promotional applications with limited production runs.
Sleek Design commands the premium positioning, while Classic Design maintains the widest deployment base.
Capacity:
Volume specifications align with beverage category conventions and regional serving-size standards rather than manufacturing cost optimization.
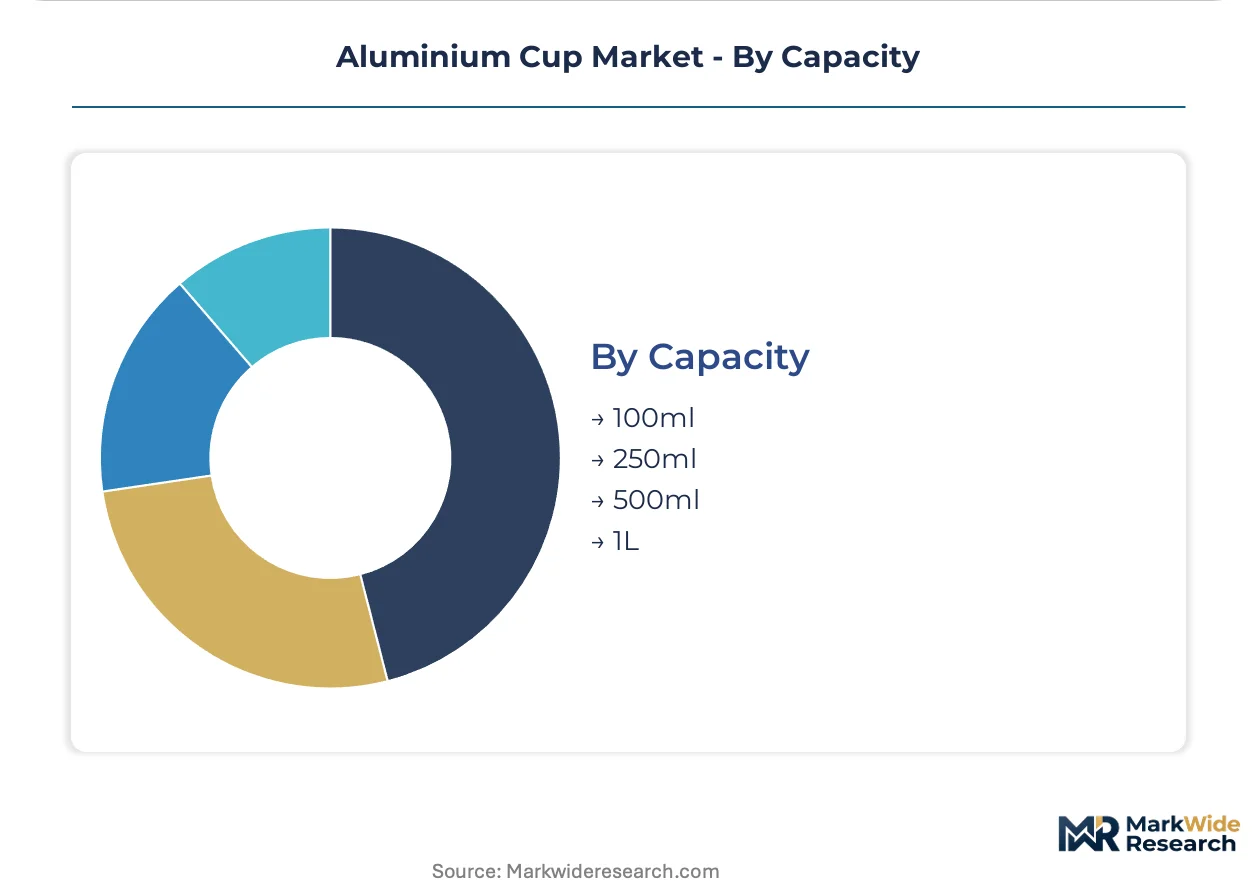
- 500ml:Standard beer and soft-drink serving format across German festival culture and California stadium operations. Deep-drawn fabrication achieves this capacity with optimal material efficiency, balancing crush resistance against aluminium input minimization.
- 250ml:Wine and spirits service format gaining traction in European outdoor catering as deposit-return schemes expand beyond beer-centric applications.
- 100ml:Tasting-sample and shot-service specifications for brewery tours and spirits sampling events.
- 1L:Large-format sharing vessels for group service at multi-day camping festivals and outdoor sporting events.
500ml generates the highest unit volume, with 250ml showing the steepest expansion trajectory in wine-service adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deposit-return legislation and producer-responsibility frameworks are redrawing procurement geography across beverage packaging markets. Regulatory momentum clusters in jurisdictions with established recycling infrastructure and visible venue sustainability mandates.
Germany
Festival culture and stadium concessions drive reusable aluminium cup procurement at scale. The Verpackungsgesetz amendment tightens compliance burdens that metal drinkware absorbs more readily than plastic alternatives. Hamburg and Berlin host the densest concentration of deposit-loop logistics providers serving multi-day music events.
United States
California stadium operators phase out single-use plastics under SB 54 producer-responsibility mandates. The FDA governs direct food-contact surfaces through 21 CFR 177.1390 laminate specifications. Los Angeles and San Francisco anchor venue procurement clusters where waste-diversion metrics determine vendor selection.
Netherlands
Event organizers replicate German deposit-loop models for outdoor catering and music festivals. The EU Packaging and Packaging Waste Regulation accelerates material substitution timelines. Amsterdam serves as the logistics hub for reusable cup reverse-supply chains serving Benelux festival circuits.
Austria
Mountain resort catering and alpine festival culture normalize metal drinkware for temperature-retention applications. The EU F-Gas Regulation restricts refrigerant choices that would otherwise preserve plastic alternatives. Tyrol and Salzburg concentrate procurement authority for reusable cup programs at ski-season events.
France
Stadium concessions in Paris and Lyon adopt aluminium formats under extended producer-responsibility pressure. ANSM food-contact material oversight aligns with EU-wide sustainability procurement standards. The Île-de-France region hosts the largest concentration of catering services integrating thermal-conductive metal vessels into mobile refrigeration systems.
Aluminium Cup Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and recycling network depth. The vendor base separates into three tiers: integrated aluminium producers with captive rolling supply, specialist metalformers with ISO 22000 certification, and regional fabricators serving deposit-loop logistics. Consolidation pressures concentrate among mid-scale metalformers lacking hazard-analysis documentation. Dominant competitive moves include backward integration into aluminium sheet supply and strategic partnerships with event organizers for circular logistics.
Within the integrated producer tier, Ball Corporation and Novelis exemplify archetypes of upstream control over material input. Trivium Packaging anchors European beverage packaging credibility through production campus positioning. These three entities represent distinct competitive positions: captive aerospace-adjacent rolling operations, recycled-content guarantee networks, and continental manufacturing footprint density respectively.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Trivium Packaging |
| Ardagh Group |
| Novelis |
| Silgan Holdings |
| Alcoa |
| Norsk Hydro |
| Shining Aluminium Packaging |
| Others |
Value Chain & Pricing Dynamics
Fourteen-day rolling inventory cycles at German festival logistics hubs concentrate pricing power among metalformers with Hamburg and Berlin production footprints, compressing margin capture for distant suppliers facing 3000-series alloy sheet transit lags. This inventory-service tension rewards backward integration into captive rolling supply while penalizing spot-market aluminium ingot exposure.
Pricing Analysis
Certification level creates the primary spread across the aluminium cup market, with ISO 22000-compliant metalformers commanding 15-25% premiums over uncertified regional fabricators. Three-tier pricing structure separates premium reusable cup formats with deposit-loop revenue sharing from standard disposable units and economy-grade unlaminated vessels. Pricing pressure stems from London Metal Exchange aluminium volatility, which squeezes margins for manufacturers lacking Novelis-style recycled-content networks. Event organizers exhibit the highest price sensitivity due to per-unit procurement volumes, while insulated cup buyers in Austrian alpine catering demonstrate the lowest sensitivity given temperature-retention performance requirements.
Supply Chain Analysis
Aerospace-adjacent rolling capacity clustering in Germany, the United States, and Norway creates input bottlenecks for 3000-series alloy sheet, constraining cup manufacturer throughput during peak festival season demand. Raw material dependencies center on primary aluminium ingot, post-consumer recycled feedstock, and food-grade polymer laminates for interior coating applications. Supply chain risk concentrates in single-source vulnerability for deep-drawn sheet supply, where Ball Corporation's captive aerospace rolling operations insulate against spot-market disruption. Distribution runs through deposit-loop logistics providers in Germany and California, with reverse-supply chain integration determining vendor selection at multi-day event contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminium cup market represents a high-growth disruption anchored by EU Packaging and Packaging Waste Regulation mandates that restructure beverage service procurement toward infinitely recyclable formats. This regulatory inflection compresses substitution timelines for plastic alternatives while amplifying returns on circular logistics infrastructure.
For Market Incumbents: Fortify competitive moats through captive 3000-series alloy sheet supply and ISO 22000 certification expansion, as hazard-analysis documentation requirements filter smaller metalformers from food-contact approval. Ball Corporation's aerospace-adjacent rolling model demonstrates how upstream control insulates margin predictability against London Metal Exchange volatility. Prioritize Hamburg and Milan production campus density to capture German festival circuit and California stadium concession procurement clusters. For New Entrants and Emerging Players: Differentiate on deposit-loop logistics integration rather than unit manufacturing cost, as Austrian and Dutch festival operators seek turnkey waste-diversion solutions. The Netherlands and Austria present the most penetrable geographies for reusable cup program replication outside German market saturation. Target event organizer procurement authority with bundled cup supply and reverse-supply chain metric guarantees rather than per-unit transactional positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-scale European metalformers lacking ISO 22000 documentation but holding established relationships with German festival logistics networks. Five-to-ten-year viability hinges on regulatory momentum for deposit-return scheme expansion across additional US states and EU member countries. Watch California SB 54 enforcement intensity and EU F-Gas Regulation compliance deadlines as inflection signals for aluminium thermal conductivity preference acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Sheet Supply | Captive 3000-series rolling capacity insulates margin predictability against LME price volatility. |
| ISO 22000 Certification Investment | Food-contact hazard documentation filters competitors from German and California venue procurement. |
| Deposit-Loop Logistics Partnership | Reverse-supply chain integration determines vendor selection at multi-day Austrian and Dutch festivals. |
| Insulated Variant R&D Expansion | Double-wall vacuum construction commands premium positioning in Austrian alpine temperature-retention applications. |
| Recycled-Content Guarantee Network | Novelis-style post-consumer feedstock verification meets EU Packaging Regulation sustainability procurement criteria. |
Study Parameters
Operator-level perspectives from festival logistics coordinators, stadium procurement directors, metalformer plant managers, and EU regulatory affairs specialists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through German Verpackungsgesetz amendment filings, California SB 54 implementation guidance, London Metal Exchange aluminium price series, and EU F-Gas Regulation compliance documentation. Bottom-up segment sizing across reusable, disposable, insulated, and decorative cup formats triangulated against top-down market value reconstruction.
Sensitivity analysis across primary aluminium ingot price scenarios, deposit-return scheme adoption rates, and ISO 22000 certification penetration thresholds shaped the analytical framework. Segmentation dimensions modeled include product durability tier, end-use procurement authority, thermal performance specification, and regional regulatory compliance cluster. CAGRs derived from volume trajectory analysis incorporating cold-forming process yield improvements and festival culture penetration rates across Central Europe.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation implementation and California SB 54 producer-responsibility enforcement; material policy shifts would require re-modeling. Revision becomes warranted when primary aluminium price volatility exceeds historical bands or when deposit-return scheme adoption accelerates beyond baseline state-level expansion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Bamboo Cups Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Soft Drinks Packaging Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Disposable Tea Flask Market