
 Disposable Water Bottle Market | 2026-2036
Disposable Water Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Water Bottle Market Analysis
ISO 22000 food safety management certification is bifurcating the competitive landscape between multinational suppliers and regional converters. Amcor leverages integrated resin-to-bottle manufacturing across multiple continents to sustain cost leadership in high-volume PET contracts. PepsiCo anchors North American retail shelf presence through direct-store-delivery infrastructure that controls replenishment velocity. Nestlé Waters differentiates via mineral-source provenance claims and premium positioning in European markets.
A disposable water bottle constitutes a single-serve sealed container, typically blow-molded from polyethylene terephthalate or extruded from aluminum, designed for immediate consumption without return logistics. The 500 ml plastic segment dominates unit economics through optimized resin-to-volume ratios and compatibility with existing filling lines. Online retail channels represent the fastest-growing distribution vector, though convenience stores still capture the highest impulse-purchase margin pools. Biodegradable material alternatives remain structurally constrained by limited industrial composting infrastructure and higher per-unit conversion costs.
The FDA governs food-contact substance safety through 21 CFR regulations, while the EU F-Gas Regulation and REACH framework restrict certain polymer additives and mandate recycled content thresholds. These standards elevate compliance costs for imported products and redirect R&D spending toward post-consumer recycled feedstock qualification. Stakeholders must monitor evolving extended producer responsibility schemes and deposit-return system expansions to anticipate margin compression or channel disruption.
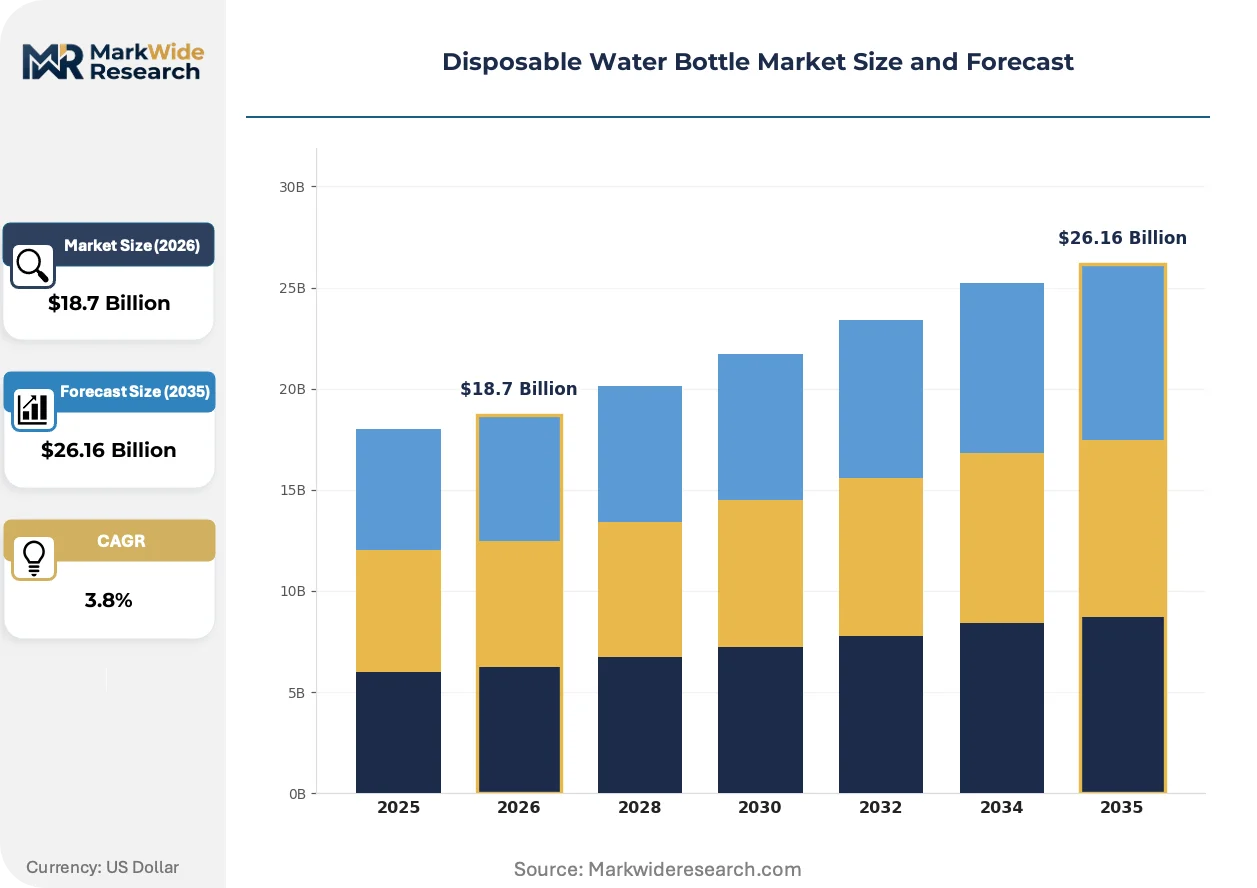
Market Dynamics
Recycled PET qualification timelines and EU Single-Use Plastics Directive compliance deadlines are compressing converter margins while accelerating material substitution investments across blow-molding supply chains.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content thresholds are pulling forward converter investment in post-consumer flake processing capacity across Germany, France, and Italy.
- Outdoor recreation demand:Trail running, ultramarathon, and backcountry hiking participation rates are sustaining single-serve volume in specialty retail channels.
- rPET resin technology:Advanced decontamination processes now achieve food-grade purity at commercial scale, unlocking closed-loop supply contracts with major beverage brands.
Market Restraints
- Feedstock cost volatility:Virgin PET resin prices track paraxylene and ethylene glycol spot markets, exposing converters to petrochemical commodity swings without pass-through mechanisms.
- Industrial composting infrastructure gaps:PLA and PHA biodegradable alternatives require controlled-temperature facilities absent in most US municipal waste systems.
- Deposit-return system fragmentation:Inconsistent bottle-bill coverage across US state lines creates reverse-logistics complexity and cross-border arbitrage in scrap material flows.
Strategic Opportunities
- India packaged water penetration:Rising disposable incomes and urbanization in tier-2 cities are expanding addressable demand beyond traditional boiled-water consumption patterns.
- Direct-to-consumer subscription hydration:Home and office delivery platforms are capturing recurring revenue pools previously held by convenience store impulse purchases.
- Extended producer responsibility schemes:France's Citeo eco-modulation fees reward lightweighting and recycled content, creating margin advantages for compliant producers.
Industry Challenges
- ISO 22000 certification backlog:Third-party audit capacity constraints are delaying supplier qualification timelines for multinational food and beverage contracts.
- Legacy filling line retrofit costs:Biodegradable material alternatives often require blow-molding parameter adjustments and downstream handling equipment modifications incompatible with existing high-speed assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Water Bottle Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Aluminum, Biodegradable Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Vending Machines Capacity: 250 ml, 500 ml, 1 L, 2 L End User: Households, Offices, Events, Outdoor Activities |
| Companies Covered | Amcor, Ball Corporation, Crown Holdings, Ardagh Group, Berry Global, Nestlé Waters, Coca-Cola Company, PepsiCo, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Water Bottle Market Emerging Trajectories
Material science breakthroughs and regulatory stringency are converging to transform converter economics, with sustainability credentials now functioning as gatekeepers to shelf access rather than premium positioning alone.
Enzymatic PET depolymerization is displacing mechanical recycling as the preferred route to food-grade rPET for premium bottled water applications. Nestlé Waters and Danone are piloting Carbios-derived resin in European production lines. This biotechnology is compressing the cost differential between virgin and recycled feedstock while eliminating the yellowing and odor issues that constrained mechanical flake adoption.
REACH restrictions on intentional microplastic additives are forcing reformulation of colorants and slip agents across EU-sourced bottle production. The European Chemicals Agency's 2023 restriction proposal targets polymer processing aids with environmental persistence profiles. Converter operations in Poland and Spain are accelerating qualification of bio-based alternatives ahead of enforcement timelines.
Bulk dispensary and refill-station networks are capturing share from single-serve formats in German and Scandinavian grocery retail. Aldi Süd and REWE have expanded in-store hydration stations that charge by volume rather than unit. This consumption-pattern shift is most visible in urban centers with mature packaging-free store footprints and municipal tap-water quality trust indices above European median levels.
Disposable Water Bottle Market Segmentation
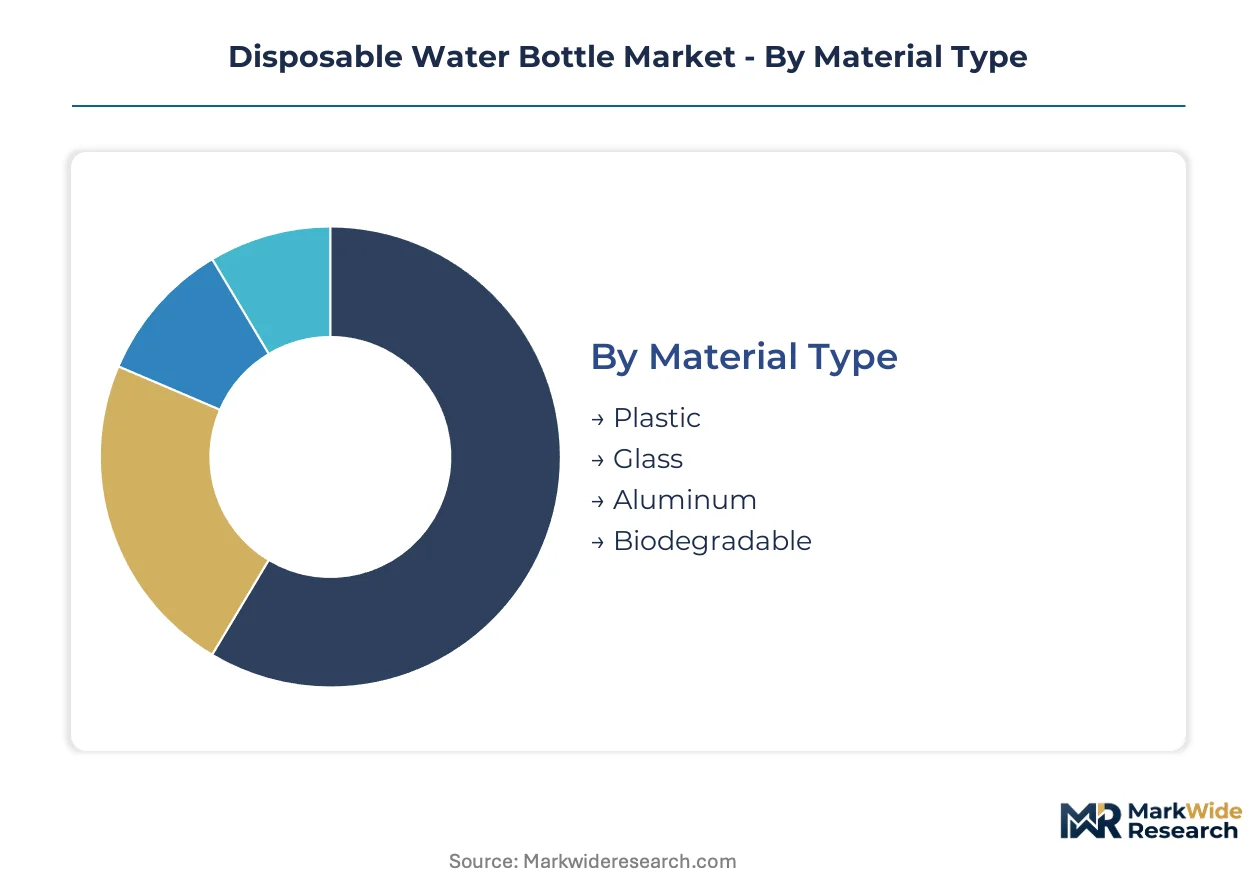
Material innovation and channel fragmentation are redrawing profit pool boundaries across converter operations. Segmentation clarity enables stakeholders to align capacity investments with evolving regulatory thresholds and consumption pattern shifts.
Material Type:
Margin pools concentrate in rPET-qualified supply chains where food-grade decontamination capabilities command premium pricing.
- Plastic:Polyethylene terephthalate blow-molding dominates unit economics through optimized resin-to-volume ratios and compatibility with existing high-speed filling infrastructure. Demand from outdoor activities and fitness applications sustains single-serve volume in the United States and Germany, though EU Single-Use Plastics Directive recycled content mandates are compressing converter margins.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate alternatives require controlled-temperature industrial composting facilities absent in most US municipal waste systems. Pilot deployments in France and Italy leverage Citeo eco-modulation fee structures to offset higher per-unit conversion costs, but infrastructure gaps limit addressable market penetration.
- Aluminum:Extruded and impact-extruded formats target premium positioning with infinite recyclability credentials.
- Glass:Returnable and single-use variants retain niche presence in mineral-source provenance segments.
Plastic holds installed capacity. Biodegradable is rotating up the share rankings.
Distribution Channel:
Impulse-purchase margin pools remain anchored in physical retail, though recurring revenue platforms are capturing lifetime value previously held by convenience transactions.
- Convenience Stores:Refrigerated shelf placement drives highest per-unit margins through immediate consumption triggers and limited price transparency. The United States convenience culture sustains replenishment velocity via direct-store-delivery infrastructure controlling stock rotation.
- Online Retail:Subscription hydration platforms and bulk delivery services are expanding addressable demand beyond traditional impulse purchase occasions. Home and office delivery networks in India and tier-2 Chinese cities capture recurring revenue pools through digital-first customer acquisition.
- Supermarkets:High-volume, low-margin throughput with private-label penetration pressure.
- Vending Machines:Automated distribution capturing transit and workplace micro-moments.
Convenience stores hold installed capacity. Online retail is rotating up the share rankings.
Capacity:
Volume-mix optimization determines resin efficiency and logistics cost structures across filling line configurations.
- 500 ml:The dominant format achieves optimal resin-to-volume ratios compatible with existing blow-molding and filling assets. Trail running, ultramarathon, and backcountry hiking participation in Germany and Australia sustain specialty retail channel placement.
- 250 ml:Compact formats target aviation, hospitality, and portion-controlled consumption occasions where waste minimization credentials support premium positioning.
- 1 L:Family and sharing occasions with lower per-liter packaging intensity.
- 2 L:Bulk household stocking with highest volume-to-resin efficiency but limited portability.
500 ml holds installed capacity. 250 ml is rotating up the share rankings.
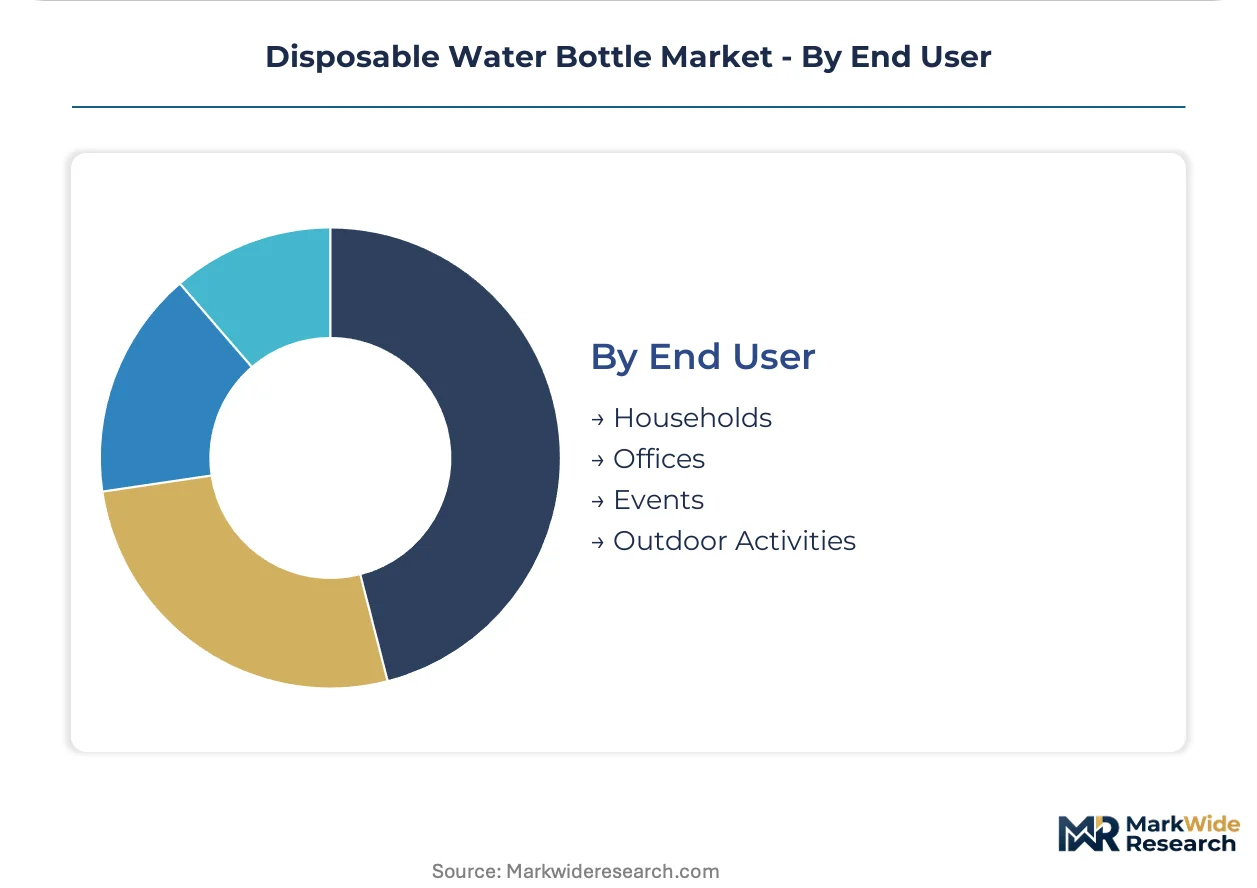
End User:
Application-specific requirements dictate certification tiers, handling protocols, and replenishment frequency.
- Outdoor Activities:Trail running, ultramarathon, and backcountry hiking participation rates sustain single-serve volume in specialty retail channels across the United States, Germany, and Australia. ISO 22000 certification requirements bifurcate supplier access to multinational brand contracts.
- Events:Stadium, festival, and conference consumption concentrates demand in seasonal patterns with deposit-return system complexity across fragmented US state-level bottle-bill coverage.
- Households:Stock-up purchasing with price sensitivity and private-label acceptance.
- Offices:B2B delivery platforms with cooler-service and recurring replenishment contracts.
Outdoor activities hold installed capacity. Events is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Convenience-driven buyers concentrate in North America and Western Europe, while emerging-market demand clusters around urban hydration infrastructure gaps in Asia-Pacific and Latin America.
United States
Direct-store-delivery networks and event-based consumption sustain per-capita volume leadership. FDA 21 CFR food-contact regulations govern resin safety standards for domestic blow-molding operations. The Southeast corridor from Atlanta to Florida hosts major converter capacity serving convenience store replenishment velocity.
Germany
Bulk refill stations and packaging-free retail formats are capturing share from single-serve formats in urban centers. EU Single-Use Plastics Directive recycled content mandates are compressing converter margins while accelerating rPET flake processing investments. The Rhine-Main industrial cluster around Frankfurt concentrates advanced decontamination technology deployment.
India
Rising disposable incomes in tier-2 cities are expanding packaged water penetration beyond traditional boiled-water consumption patterns. FSSAI food safety standards and BIS certification requirements are elevating compliance barriers for imported equipment. Maharashtra and Gujarat host the dominant blow-molding and filling line manufacturing corridors.
France
Mineral-source provenance claims and premium positioning sustain margin pools in European retail. Citeo eco-modulation fees reward lightweighting and recycled content, creating structural advantages for compliant producers. The Auvergne-Rhône-Alpes region anchors natural mineral water sourcing and enzymatic recycling pilot deployments.
Australia
Outdoor recreation culture and backcountry hiking participation sustain specialty retail channel placement for portable hydration. State-level container deposit schemes and federal plastics reduction targets are accelerating material substitution timelines. The Sydney-Melbourne corridor concentrates converter operations serving domestic and Asia-Pacific export demand.
Disposable Water Bottle Market Vendor Landscape
Player mix skews toward integrated resin-to-bottle manufacturers and multinational beverage brand captives. Consolidation around food-grade certification capabilities and direct-store-delivery infrastructure has created a tiered structure with scale advantages at the top. Strategic archetypes include backward-integrated resin producers, brand-captive filling operations, and regional converter specialists. Dominant competitive moves center on rPET flake processing capacity expansion and enzymatic recycling technology licensing.
Among integrated packaging specialists, Amcor and Berry Global represent the scale-driven archetype with multi-continent manufacturing footprints. Nestlé Waters and Danone occupy positions within the brand-captive tier, leveraging mineral-source provenance and sustainability credentials for premium positioning. PepsiCo anchors North American retail presence through infrastructure controlling replenishment velocity.
| Leading Market Players |
|---|
| Amcor |
| Ball Corporation |
| Crown Holdings |
| Ardagh Group |
| Berry Global |
| Nestlé Waters |
| Coca-Cola Company |
| PepsiCo |
| Danone |
| Others |
Supply Flow & Price Mechanics
Multi-continent blow-molding capacity utilization above 85 percent concentrates pricing power among resin-integrated converters while compressing margin buffers for regional specialists dependent on spot PET purchases. This scale asymmetry shapes both supply concentration in Germany, China, and the United States and price floors that exclude smaller players from multinational brand contracts.
Pricing Analysis
Cost-plus contracts with paraxylene and ethylene glycol indexation dominate converter-brand relationships, transmitting petrochemical commodity volatility directly to bottle economics. Three-tier pricing structure across premium mineral-source, standard purified, and economy private-label levels separates Nestlé Waters and Danone from PepsiCo and retail-label suppliers. Cost compression in standard-tier PET bottles is intensifying because EU recycled content mandates force parallel virgin and rPET feedstock qualification. Private-label buyers at Aldi Süd and REWE exhibit highest price sensitivity, while premium mineral-source positioning at French retailers shows lowest elasticity.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes and Red Sea routing disruptions have elevated inbound resin logistics costs for European converters sourcing Asian rPET flake. Geographic supply concentration centers on Germany, China, and the United States, with the Rhine-Main cluster hosting advanced decontamination technology and Guangdong province dominating virgin PET resin production. Raw material dependencies rest on paraxylene derivatives, post-consumer PET bales, and enzymatic recycling catalysts. Single-source vulnerability to Carbios technology licensing creates bottleneck risk for food-grade rPET qualification. Distribution runs through direct-store-delivery networks controlling convenience store replenishment velocity in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic PET depolymerization at commercial scale is disrupting mechanical recycling economics and rewriting converter qualification timelines across European supply chains. This technological inflection compresses the cost differential between virgin and recycled feedstock while eliminating quality penalties that previously constrained rPET adoption.
For Market Incumbents: Compound rPET flake processing capacity in Germany and France ahead of EU Single-Use Plastics Directive enforcement deadlines. Secure exclusive enzymatic recycling technology licenses from biotechnology suppliers to defend against Carbios-dependent competitors. Backward integration into post-consumer bale collection networks reduces feedstock cost volatility exposure.
For New Entrants and Emerging Players: Anchor in India's tier-2 city packaged water penetration, where FSSAI compliance barriers exclude unqualified imports but local blow-molding expertise remains scarce. Target direct-to-consumer subscription hydration platforms capturing recurring revenue pools from convenience store erosion. Pursue digital-first customer acquisition through home and office delivery networks in Maharashtra and Gujarat.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer hydration platforms with cooler-service contracts and automated replenishment algorithms. Long-term viability over the next decade hinges on rPET qualification capabilities and enzymatic recycling technology access rather than virgin resin scale. Acquisition targets should demonstrate Citeo eco-modulation fee optimization and lightweighting patents. The signal to watch is deposit-return system expansion across US state lines, which would reverse-logistics infrastructure requirements and reshape scrap material flow economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Recycling Technology Licensing | Carbios-derived resin pilots at Nestlé Waters and Danone eliminate mechanical recycling quality penalties. |
| rPET Flake Processing Capacity Expansion | Advanced decontamination investments in Germany and Italy secure EU Single-Use Plastics Directive compliance. |
| Direct-to-Consumer Subscription Platform Launch | Home and office delivery networks in India capture recurring revenue from convenience store impulse erosion. |
| Deposit-Return System Infrastructure Buildout | Reverse-logistics investments in Australia and Germany align with extended producer responsibility scheme expansions. |
| Bulk Refill Station Network Partnership | Aldi Süd and REWE hydration stations in urban Germany shift consumption patterns from single-serve formats. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blow-molding plant managers, beverage brand procurement directors, retail category buyers, rPET flake processors, and regulatory compliance officers. Secondary validation drew from FDA 21 CFR food-contact substance filings, EU ECHA REACH restriction proposals, FSSAI certification databases, customs trade flow records, and SEC 10-K disclosures from integrated packaging specialists. Bottom-up capacity and consumption estimates were triangulated against top-down macroeconomic drivers.
Across the analysis window, volume and value projections were constructed through segmented modeling of material type, distribution channel, capacity format, and end-use application dimensions. CAGRs were derived from historical trajectory analysis and regulatory inflection timing rather than extrapolation. Industry-specific forecast inputs included EU Single-Use Plastics Directive compliance deadlines, enzymatic recycling technology scale-up curves, and deposit-return system expansion probability weights.
Material uncertainties — paraxylene spot market volatility, industrial composting infrastructure buildout delays, and ISO 22000 audit capacity constraints — sit outside the modeled envelope and could compress or extend converter margin recovery timelines. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology licensing availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Drink Hoses Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Beverage Crates Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Slip Cover Cans Market
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
United States Aluminum Beverage Cans Market