
 Spout and Non-Spout Liquid Pouch Packaging Market | 2026-2036
Spout and Non-Spout Liquid Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spout and Non-Spout Liquid Pouch Packaging Market Analysis
Aftermarket recycling infrastructure is rewriting margin distribution across the value chain. Amcor leverages its global film extrusion network to control substrate supply for spouted pouch formats. Constantia Flexibles anchors European demand through pharmaceutical-grade barrier pouch production. Sonoco competes in North American food service channels with retort-capable stand-up designs.
Spout and non-spout liquid pouch packaging comprises flexible laminated structures with sealed edges, typically incorporating polyethylene, polyester, or aluminum oxide barrier layers, engineered to contain and dispense liquids through integrated closures or tear notches. These formats reduce material weight versus rigid alternatives while accommodating aseptic, hot-fill, and retort sterilization processes for shelf-stable goods. Stand-up pouches with spout closures capture premium positioning in toddler nutrition and adult beverage segments where resealability commands price premiums. Retort pouches sustain growth in ready-meal applications across Asia-Pacific markets where microwave convenience drives substitution of metal cans. Flat pouches with heat-seal closures dominate single-serve condiment and sample sachet production where unit economics favor minimal material usage.
The EU Packaging and Packaging Waste Regulation and FDA food contact substance notifications jointly determine material approval pathways for liquid-contact layers in export-bound pouches. REACH compliance costs for adhesive and ink formulations are shifting converter procurement toward pre-certified substrate suppliers. Stakeholders must monitor extended producer responsibility fee structures as these programs expand across North American and European jurisdictions.
Market Dynamics
Converters in Germany and India are accelerating conversion from rigid bottles to flexible pouches as EU Packaging and Packaging Waste Regulation recyclability mandates tighten material specifications across multilayer film supply chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates for multilayer films are forcing material redesigns that favor mono-material pouch structures compatible with existing European sorting infrastructure.
- Ready-to-drink beverage processors:Brand owners in Germany are substituting spouted pouches for PET bottles in adult beverage and toddler nutrition segments where resealability commands shelf price premiums.
- Yangtze River Delta cluster:Chinese converters supply both domestic food processors and export markets with retort-capable stand-up pouch capacity concentrated in this manufacturing hub.
Market Restraints
- Aluminum oxide barrier layer cost volatility:Thin-film deposition equipment and specialty substrate sourcing create fixed cost structures that resist short-run customization for mid-tier brand owners.
- Multilayer adhesive certification delays:REACH compliance costs for adhesive and ink formulations are extending procurement timelines for European converters sourcing from non-pre-certified substrate suppliers.
- Metal can substitution resistance:Ready-meal processors in mature Asian markets retain established retort can supply chains with amortized filling equipment and consumer familiarity.
Strategic Opportunities
- Indian liquid detergent segment:Rigid bottle replacement with flat pouch formats offers unit economics advantages where minimal material usage aligns with single-serve and bulk refill channel expansion.
- Extended producer responsibility fee structures:North American jurisdictions are piloting EPR programs that create first-mover advantages for converters with established recycling partnerships and certified recyclable mono-material designs.
- Aseptic spout integration:Convergence of ultrasonic welding and hydrogen peroxide sterilization technologies enables ambient-stable dairy and juice applications previously restricted to refrigerated supply chains.
Industry Challenges
- High-barrier metallization technician scarcity:Vacuum deposition and atomic layer deposition operations require specialized operators whose training pipelines lag capacity expansion timelines in emerging manufacturing regions.
- FDA food contact substance notification timelines:Liquid-contact layer approvals for export-bound pouches extend product development cycles by months when new coextrusion formulations trigger supplemental safety data requirements.
- Legacy filling line retrofit complexity:Brand owners with amortized rigid packaging equipment face integration friction when adapting form-fill-seal operations for spouted pouch formats with non-standard closure geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spout and Non-Spout Liquid Pouch Packaging Market |
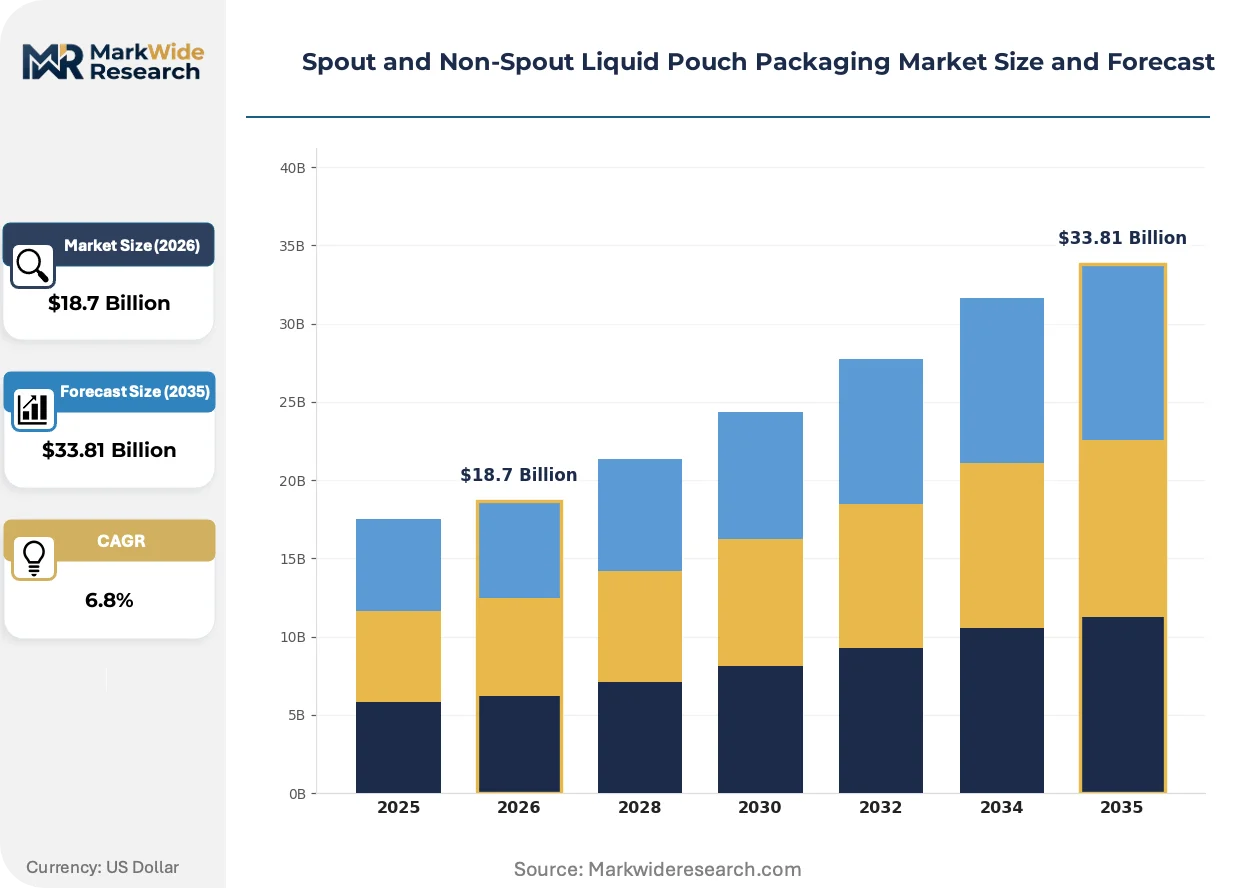
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Retort Pouches, Side Gusset Pouches Closure Type: Spout Closure, Easy Pour Closure, Zip Lock, Heat Seal Material: Plastic, Aluminum, Composites, Paper End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals |
| Companies Covered | Sonoco, Coveris, Amcor, Smurfit Kappa, Uflex, ProAmpac, Constantia Flexibles, Swiss Pac, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spout and Non-Spout Liquid Pouch Packaging Market Emerging Trajectories
Digital printing and virtualized barrier technologies are compressing minimum order quantities while regulatory pressure on recyclability is forcing substrate simplification across European and North American supply chains.
Digital inkjet printing with water-based formulations is virtualizing the traditional gravure cylinder pre-production step. Small-batch beverage brand owners in Germany and craft food processors in India are adopting short-run customized pouch designs with variable graphics. This technology is virtualizing the economics of SKU proliferation, enabling regional flavor variants and seasonal limited editions without cylinder engraving lead times or inventory risk.
REACH authorization requirements for adhesive chemistries are redirecting converter procurement toward pre-certified substrate suppliers with documented compliance dossiers. European flexible packaging converters face reformulation costs for legacy solvent-based laminating adhesives. Pharmaceutical-grade barrier pouch producers anchor demand through Constantia Flexibles' certified supply chain, while food service channels encounter extended qualification timelines for new material stacks.
Brand owner consolidation in German retail is compressing supplier qualification cycles and unbundling after-sales technical service from unit pricing. Large-format grocery chains now mandate direct converter relationships with transparent cost breakdowns and recycling partnership documentation. This pattern concentrates procurement leverage in the hands of buying cooperatives, squeezing margin for mid-tier converters without scale advantages or differentiated barrier performance credentials.
Spout and Non-Spout Liquid Pouch Packaging Market Segmentation
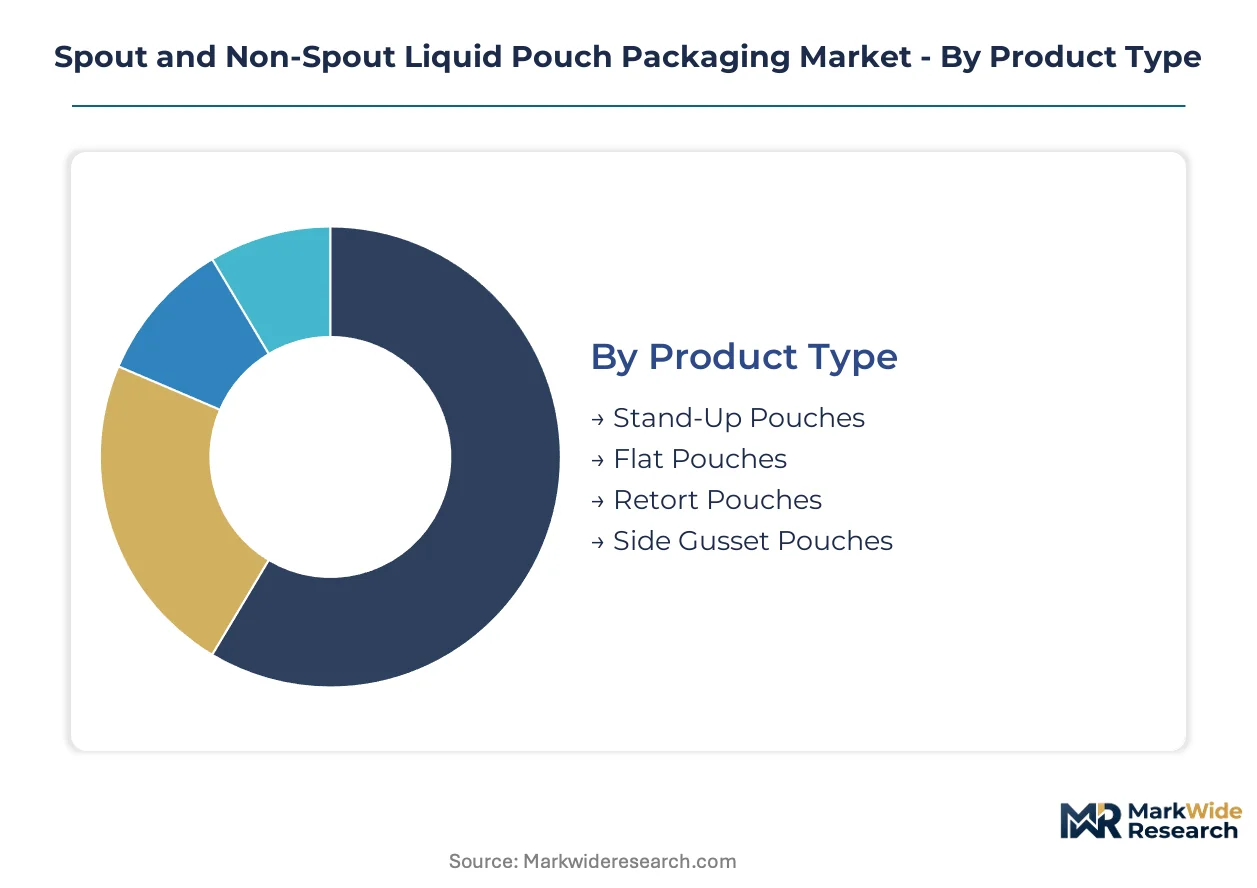
Segmentation in liquid pouch packaging reveals how substrate selection, closure geometry, and sterilization requirements create distinct margin pools across applications. Converters optimize line configurations for specific format families rather than attempting universal production flexibility.
Product Type:
Format families span the convenience-to-preservation spectrum, from ambient-stable shelf displays to single-serve portion control.
- Stand-Up Pouches:Laminated structures with bottom gusset geometry enable vertical shelf presentation and maximize retail facings per linear foot. German beverage brand owners specify these for adult drink and toddler nutrition lines where resealable spout closures support premium shelf positioning.
- Flat Pouches:Two-dimensional sealed-edge designs minimize material usage for single-serve condiments, sample sachets, and detergent refills. Indian household product processors favor these for liquid detergent conversion from rigid bottles, where unit economics and logistics cube efficiency drive format selection.
- Retort Pouches:High-barrier laminates withstand 121°C sterilization cycles for shelf-stable ready-meals and proteins.
- Side Gusset Pouches:Vertical formats with expandable side panels accommodate bulk dry goods and institutional liquid concentrates.
Established volume favors Stand-Up Pouches; emerging adoption favors Flat Pouches.
Closure Type:
Dispensing mechanism selection determines supply chain complexity, with welded-in spouts requiring specialized filling equipment versus simple heat-seal alternatives.
- Spout Closure:Injection-molded polyethylene or polypropylene fitments integrate through ultrasonic or thermal welding into pre-cut pouch apertures. China's Yangtze River Delta converters dominate capacity for these assemblies, supplying both domestic food processors and export markets with integrated spout-and-cap systems.
- Easy Pour Closure:Simple threaded or snap-fit designs reduce component count versus full spout assemblies.
- Zip Lock:Interlocking plastic profiles enable repeated reseal without separate cap inventory.
- Heat Seal:Direct thermal bonding of film layers provides tamper evidence at lowest unit cost.
Technology investment concentrates in Spout Closure; margin compression affects Heat Seal.
Material:
Substrate stacks balance barrier performance, recyclability compliance, and total applied cost across regulatory jurisdictions.
- Plastic:Mono-material polyethylene or polypropylene structures satisfy EU Packaging and Packaging Waste Regulation recyclability mandates, with European converters accelerating redesigns to eliminate incompatible multi-polymer laminations.
- Aluminum:Foil layers provide absolute oxygen and light barrier for retort applications and pharmaceutical stability requirements.
- Composites:Multi-layer combinations of plastic, aluminum oxide, and adhesives deliver tailored barrier properties.
- Paper:Fiber-based substrates with polymer barrier coatings address sustainability positioning in premium personal care segments.
Regulatory pressure favors Plastic; barrier-critical applications retain Aluminum.
End User:
Demand concentration varies sharply by sterilization requirements, regulatory scrutiny, and brand owner consolidation patterns.
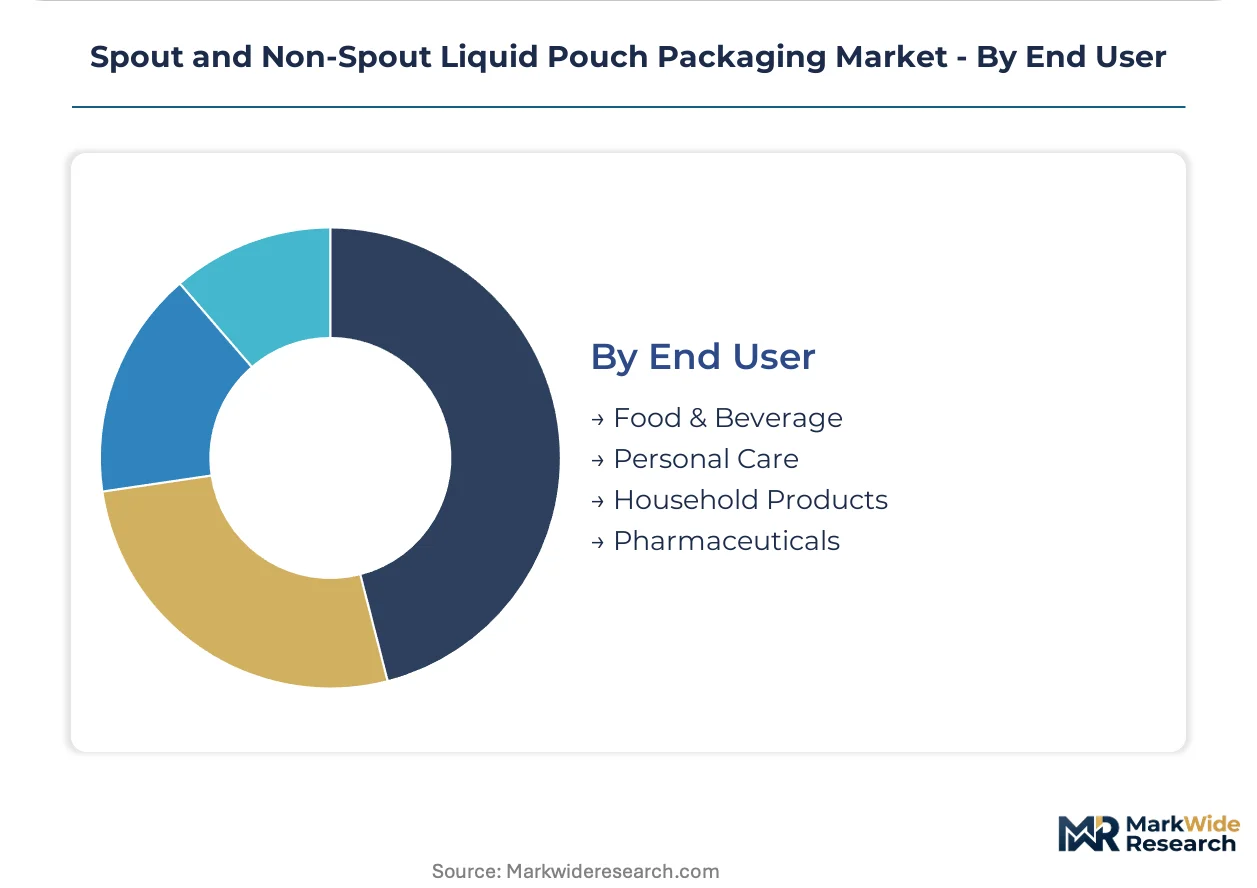
- Food & Beverage:Aseptic, hot-fill, and retort sterilization processes dominate this segment, with pouch formats displacing metal cans in ready-meal applications across Asia-Pacific markets where microwave convenience drives substitution.
- Personal Care:Premium positioning and sustainability messaging favor paper-based and recyclable mono-material pouches for lotions and shampoos.
- Household Products:Liquid detergents and cleaning concentrates convert rapidly from rigid bottles to flexible formats in India and Germany, driven by logistics efficiency and EPR fee avoidance.
- Pharmaceuticals:Barrier integrity and extractables testing requirements create qualification barriers that favor established suppliers with documented compliance dossiers.
Volume concentration sits with Food & Beverage; qualification intensity peaks in Pharmaceuticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes spouted pouches for ready-meals and dairy exports while Germany deploys them for premium adult beverages and toddler nutrition, revealing a consumption-mix split between convenience-driven emerging markets and premium-positioned mature economies.
China
Yangtze River Delta converters supply retort-capable stand-up pouches to domestic food processors and export markets, with Shanghai and Jiangsu province housing integrated spout-and-cap assembly capacity. SAMR food contact material standards and GB national standards govern liquid-contact layer approvals, creating compliance documentation requirements for multilayer laminates. Ningbo and Suzhou manufacturing clusters concentrate ultrasonic welding equipment for aseptic spout integration, enabling ambient-stable dairy applications.
Germany
Beverage brand owners in Bavaria and North Rhine-Westphalia substitute spouted pouches for PET bottles in adult beverage segments where resealability commands shelf price premiums. EU Packaging and Packaging Waste Regulation recyclability mandates force material redesigns toward mono-material polyethylene structures compatible with existing European sorting infrastructure. Hamburg and Düsseldorf serve as procurement hubs for large-format grocery chains mandating transparent cost breakdowns and recycling partnership documentation.
India
Liquid detergent processors in Maharashtra and Gujarat convert rapidly from rigid bottles to flat pouch formats, driven by logistics cube efficiency and unit economics advantages in single-serve and bulk refill channels. FSSAI food safety standards and BIS certification requirements extend qualification timelines for imported substrate suppliers. Ahmedabad and Mumbai converters optimize heat-seal closure production for household product segments where minimal material usage aligns with price-sensitive mass market demand.
United States
Food service channels in the Midwest and Southeast adopt retort-capable stand-up designs for institutional ready-meal applications, with Sonoco competing through established converter relationships. FDA food contact substance notification timelines extend product development cycles when new coextrusion formulations trigger supplemental safety data requirements. Chicago and Atlanta serve as distribution nodes for North American EPR pilot programs creating first-mover advantages for converters with certified recyclable mono-material designs.
Japan
Pharmaceutical-grade barrier pouch demand concentrates in the Kanto region around Tokyo, where extractables testing requirements and METI industrial standards create qualification barriers favoring established suppliers. PMDA pharmaceutical regulations govern liquid-contact layer approvals for medical and nutritional applications. Osaka-based converters specialize in aluminum oxide barrier deposition for oxygen-sensitive formulations, though technician scarcity in vacuum deposition operations constrains capacity expansion.
Spout and Non-Spout Liquid Pouch Packaging Market Vendor Landscape
Capability concentration sits with specialized barrier film producers; scale advantage sits with diversified packaging conglomerates with global extrusion networks. The market structures around three tiers: integrated multinationals controlling substrate supply, regional converters optimizing for specific sterilization processes, and niche specialists in pharmaceutical-grade barrier certification. Dominant competitive moves include backward integration into film extrusion to secure resin supply and strategic partnerships with recycling infrastructure operators to preempt EPR compliance costs.
Among diversified packaging conglomerates, Amcor and Sonoco exemplify scale-driven archetypes with global manufacturing footprints, while Constantia Flexibles occupies a position within the European specialist tier focused on certified pharmaceutical supply chains. Uflex represents the emerging-market converter archetype with integrated film production and spout assembly capacity concentrated in Indian manufacturing clusters. These three anchors illustrate how competitive positioning diverges between substrate control strategies and regulatory qualification depth.
| Leading Market Players |
|---|
| Sonoco |
| Coveris |
| Amcor |
| Smurfit Kappa |
| Uflex |
| ProAmpac |
| Constantia Flexibles |
| Swiss Pac |
| Huhtamaki Oyj |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Ningbo container corridor transmits resin cost volatility directly into European converter pricing, amplifying margin pressure for mid-tier players while rewarding integrated multinationals with captive polyethylene supply and certified mono-material designs that command shelf price premiums from German retail buyers.
Pricing Analysis
Long-term offtake contracts between Yangtze River Delta converters and Saudi Aramco affiliates anchor base resin supply for spout assembly production, though spot market exposure in aluminum oxide barrier layers creates margin compression for specialty pharmaceutical-grade orders. Three-tier pricing structure across premium, standard, and economy levels separates Constantia Flexibles' certified dossier holders from regional heat-seal specialists and Indian detergent pouch converters. Price differentiation hinges on REACH compliance documentation and ultrasonic welding certification. Cost compression in mid-tier retort pouch supply is intensifying because legacy solvent-based adhesive reformulation extends procurement timelines. Mass-market household product processors in India exhibit highest price sensitivity; German adult beverage brand owners show lowest sensitivity where resealability justifies shelf positioning.
Supply Chain Analysis
Contract manufacturing concentration rests with Amcor's global film extrusion network, Constantia Flexibles' European pharmaceutical lines, and Uflex's integrated Noida-Ahmedabad corridor for spout-and-cap assembly. Raw material flows draw from Saudi polyethylene feedstock, Chinese polyester film capacity, and Japanese vacuum deposition equipment for aluminum oxide barriers. Single-source vulnerability concentrates in ultrasonic welding machinery sourced from Osaka and Suzhou tooling specialists. Distribution runs through Hamburg and Düsseldorf procurement hubs for European grocery cooperatives, with Chicago and Atlanta serving North American food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across sterilization process requirements and EPR compliance maturity creates niche opportunities for specialists who anchor in single format families rather than competing for universal converter status.
For Market Incumbents: Build regulatory dossier moats by deepening REACH pre-certification partnerships with substrate suppliers and securing direct recycling infrastructure agreements ahead of North American EPR expansion. Defend against Indian flat pouch converters by adding aseptic spout integration capacity in the Yangtze River Delta cluster. Prioritize ultrasonic welding technician training pipelines to constrain emerging region capacity growth. For New Entrants and Emerging Players: Establish a beachhead in Indian liquid detergent flat pouch conversion where rigid bottle displacement accelerates and FSSAI qualification barriers remain lower than pharmaceutical-grade segments. Target Maharashtra and Gujarat processors seeking logistics cube efficiency in bulk refill channels. Lead with digital inkjet printing capabilities for regional flavor variants without cylinder engraving lead times. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates divesting non-core pharmaceutical barrier units amid brand owner consolidation in German retail. Long-term viability favors converters with backward integration into film extrusion and documented recycling partnerships. Watch for inflection when North American EPR fee structures trigger accelerated mono-material redesigns across mid-tier food service suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Amcor's captive polyethylene supply secures substrate allocation priority during resin shortage periods. |
| Aseptic Spout Integration Partnership | Ningbo ultrasonic welding specialists enable ambient-stable dairy applications for Yangtze River Delta converters. |
| Recycling Infrastructure Alliance | First-mover EPR compliance in Chicago and Atlanta creates procurement preference with North American retail buyers. |
| Digital Inkjet Printing Adoption | German craft beverage processors eliminate gravure cylinder costs for seasonal limited edition launches. |
| Pharmaceutical-Grade Barrier Certification | Constantia Flexibles' REACH dossiers anchor European demand through extractables testing documentation. |
Methodological Framework
Initial hypotheses were tested against primary input from flexible packaging plant managers, adhesive procurement leads at European converters, retail category buyers in Hamburg and Düsseldorf, and ultrasonic welding equipment specialists in Suzhou, then refined against secondary validation from EU Packaging and Packaging Waste Regulation implementation documents, SAMR food contact material standards, FSSAI certification databases, and SEC filings of diversified packaging conglomerates. Bottom-up capacity assessments across the Yangtze River Delta and top-down demand modeling from German beverage brand owner conversion rates were triangulated.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning pouch format family, closure geometry complexity, sterilization process requirement, barrier material stack, and end-use regulatory intensity. CAGRs were derived from installed capacity expansion timelines and brand owner format conversion elasticity. Industry-specific forecast inputs included EU EPR fee structure pilot progression and FDA food contact substance notification backlog estimates.
Macroeconomic conditions sit as an overlay; deviation in ocean freight rates, polyethylene resin pricing, and euro-dollar exchange would shift the trajectory for export-bound Chinese converter margins. Forecasts reflect assumptions about REACH authorization timelines and SAMR standards harmonization that regulatory implementation delays could revise. Cross-checking against ECHA pre-registration databases and EU recycling infrastructure investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Twin Pouch Packaging Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Clear Pouches Market
Pouch
Fin Seal Pouches Market
Pouch
Liquid Pouch Packaging Market
Pouch
Canada Pouch Packaging Market
Pouch
Slider Zipper Pouch Market
Pouch
Ziplock Products Market
Pouch
Colombia Pouch Packaging Market
Pouch
Anti-Static Foam Pouch Market
Pouch
Recyclable PE Pouch Market
Pouch
Aluminum Foil Zipper Pouch Market
Pouch
Wrap-Around Packers Market
Pouch
Foam Pouch Market
Pouch
GCC Retort Pouches Market
Pouch
Child Resistant Pouches Market