
 Cup Sleeves Market | 2026-2036
Cup Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Cup Sleeves Market Analysis
Digital printing integration is reconfiguring how cup sleeves transition from commodity blanks to brand communication surfaces. Smurfit Kappa Group leverages its European containerboard network to supply pre-printed sleeves at scale. Mondi Group anchors its position through kraft paper innovation and barrier coatings that eliminate plastic liners. Huhtamaki competes across emerging markets with localized converting plants that reduce logistics cost.
Cup sleeves are cylindrical wraps manufactured from corrugated cardboard, molded fiber, or extruded foam, typically 0.5–3 mm thick, designed to insulate hands from hot beverages while providing printable surface area for branding. Cardboard dominates material type due to recyclability alignment with corporate ESG targets and municipal composting infrastructure. Printed design segments command premium positioning as cafes and quick-service chains treat sleeves as mobile advertising inventory, while eco-friendly variants incorporating post-consumer fiber or water-based inks are capturing fastest growth in regulated European and North American urban markets.
The US EPA guides fiber sourcing standards for food-contact packaging, while the EU F-Gas Regulation and REACH constrain synthetic foam alternatives, indirectly channeling investment toward paper-based solutions. China's SAMR enforces GB standards for food-contact materials that foreign suppliers must navigate for market access. Stakeholders should monitor how extended producer responsibility schemes in California, Germany, and France alter cost allocation between sleeve converters and their beverage-chain customers.
Market Dynamics
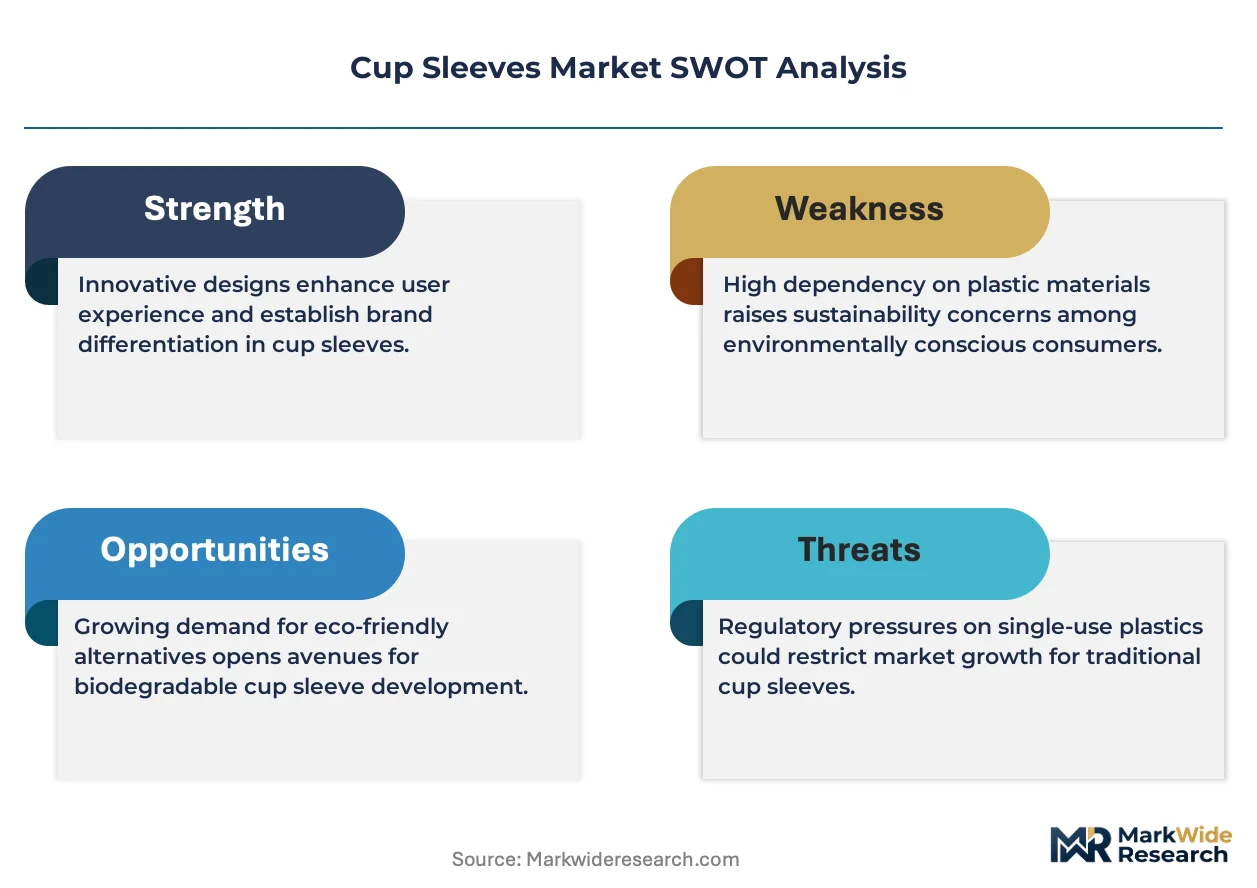
The EU Single-Use Plastics Directive is redirecting procurement budgets toward fiber-based cup sleeves while simultaneously compressing margins for converters still dependent on foam substrates.
Growth Catalysts
- Extended Producer Responsibility schemes:France, Germany, and California are mandating that beverage chains internalize end-of-life packaging costs. This regulatory pressure accelerates fiber-sleeve adoption as chains seek compliant supply contracts.
- Quick-service beverage expansion:Drive-thru coffee formats in the United States and drive-through tea chains in China are standardizing sleeve-inclusive packaging for temperature liability protection.
- Composting infrastructure maturation:Municipal facilities in the Netherlands, Austria, and Vermont now accept food-soiled cardboard sleeves, closing the loop for circular-economy claims.
Market Restraints
- Recycled pulp cost volatility:Post-consumer fiber prices fluctuate with municipal collection rates and export demand from Asian paper mills, squeezing converter margins unpredictably.
- Barrier coating technical limitation:Water-based and bio-based coatings still underperform polyethylene liners in high-humidity transport, restricting shelf-stable beverage applications.
- Substitution threat from double-walled cups:Integrated insulation designs eliminate sleeve necessity entirely, capturing premium positioning in specialty café segments.
Strategic Opportunities
- India café density growth:Metro expansion in Bangalore, Mumbai, and Delhi NCR is outpacing local sleeve converter capacity, creating import substitution openings.
- QR-embedded sleeve inventory:Near-field communication and scannable codes transform sleeves into loyalty-program touchpoints, unlocking recurring revenue streams for chains.
- EU Green Deal procurement mandates:Public-sector beverage concessions in Italy, Spain, and Poland now require demonstrably compostable packaging, favoring certified fiber suppliers.
Industry Challenges
- Food-contact certification timelines:GB standard compliance for China's SAMR requires 12-18 month validation cycles, delaying market entry for new substrate formulations.
- Legacy printing press incompatibility:Water-based ink adhesion on high-recycled-content board demands press retrofits that many mid-scale converters cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cup Sleeves Market |
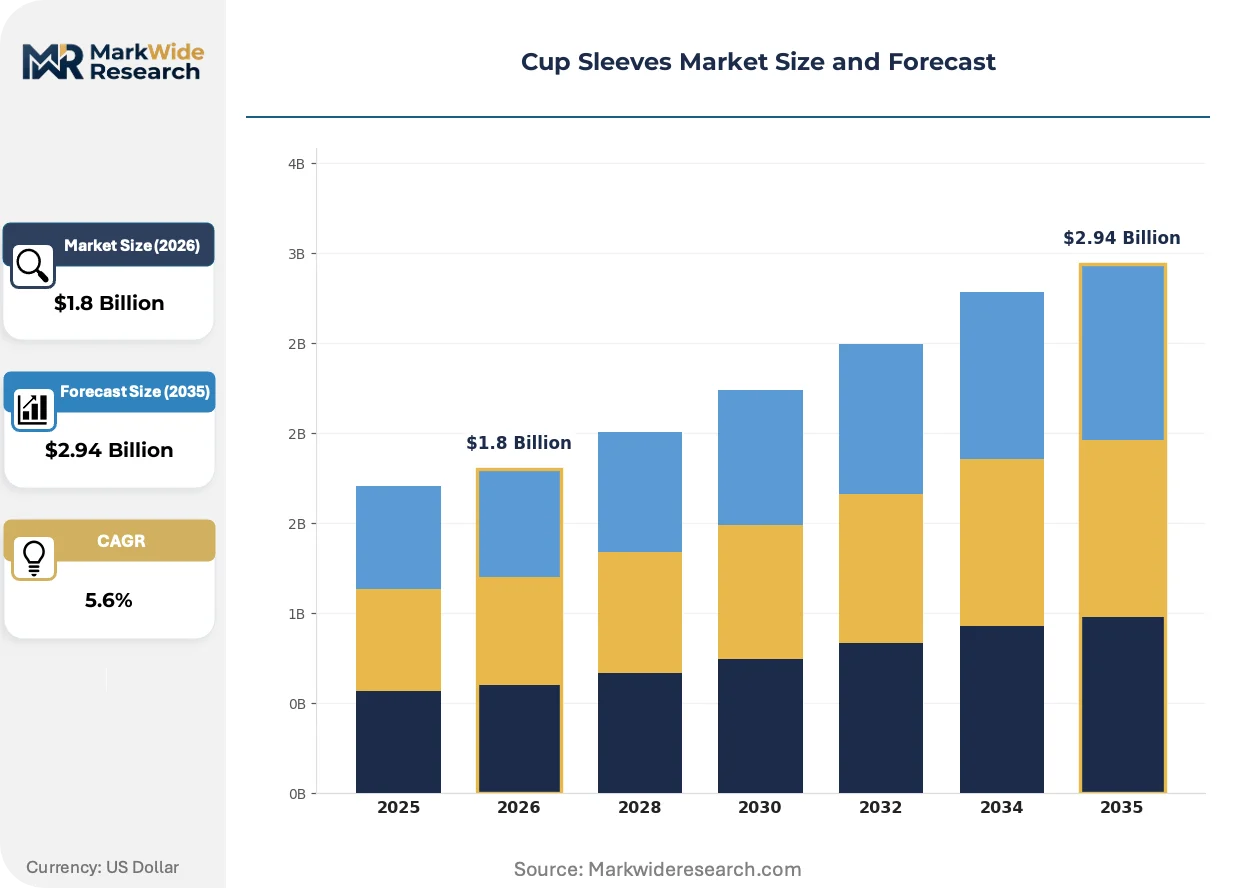
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Neoprene, Silicone, Plastic Size: Small, Medium, Large, Extra Large Application: Cafes, Restaurants, Events, Retail Design: Printed, Solid Color, Custom, Eco-Friendly |
| Companies Covered | Smurfit Kappa Group, Dart Container Corporation, Mondi Group, Novolex, Graphic Packaging International, Sonoco Products Company, WestRock Company, Genpak, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cup Sleeves Market Emerging Trajectories
Digital printing and smart packaging integration are transforming cup sleeves from passive insulation into active data-capture and brand-engagement surfaces. Three developments are restructuring competitive positioning.
Water-based barrier coatings are migrating from niche premium positioning toward mainstream quick-service adoption. Smaller café chains in Scandinavia and the Pacific Northwest are specifying these coatings for compostability claims. The technology is migrating from specialty roasters to volume beverage chains as coating durability improves and per-unit premiums compress below ten percent.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated grease barriers from food-contact paper across the European Union. Converter R&D budgets are redirecting toward polysaccharide and clay-based alternatives. Hot-beverage delivery applications in France and Germany are experiencing the most acute reformulation pressure, with Q3 2024 compliance deadlines accelerating supplier qualification.
Beverage chains are consolidating sleeve procurement under corporate sustainability officers rather than regional operations managers. This centralization compresses supplier rosters and extends contract durations in exchange for verified lifecycle data. The shift is most pronounced among US-based coffee chains with science-based targets, where procurement now demands Scope 3 emissions documentation from board-level vendors.
Cup Sleeves Market Segmentation
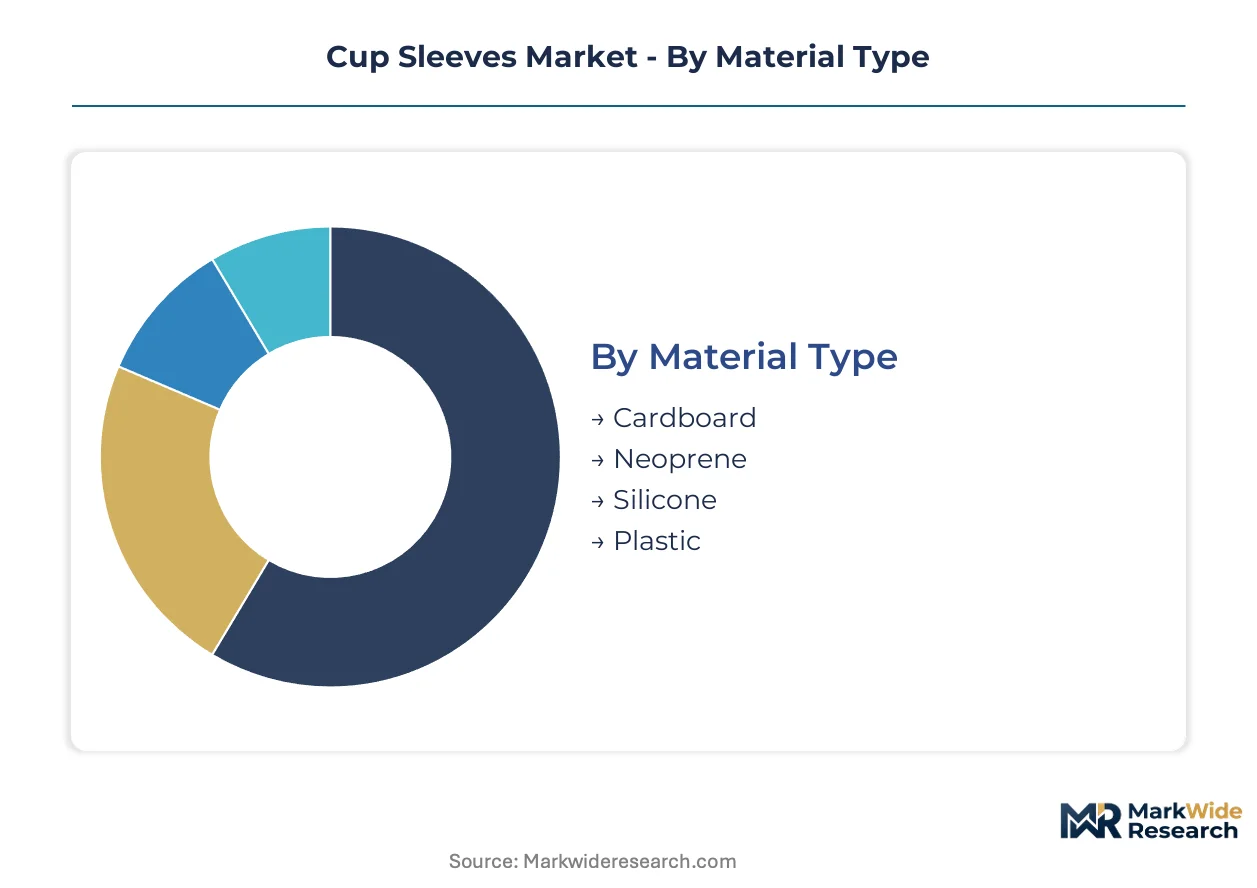
Material composition and design sophistication divide the cup sleeves market into distinct procurement tiers. Chains calibrate sleeve specifications against temperature performance, brand visibility requirements, and end-of-life compliance obligations.
Material Type:
Cardboard cycles through inventory fastest due to single-use economics, while silicone and neoprene sit at the opposite extreme with multi-year replacement intervals.
- Cardboard:Corrugated fiberboard or kraft paper substrates, typically 0.5–2 mm thickness with fluted insulation layers. Quick-service chains in the United States and Germany specify post-consumer recycled content to satisfy EPR schemes and municipal composting infrastructure. This segment captures the steepest expansion trajectory as EU Single-Use Plastics Directive enforcement accelerates fiber substitution.
- Neoprene:Synthetic rubber foam with closed-cell structure delivering superior thermal insulation and moisture resistance. Reusable cup sleeve programs at specialty cafés in Japan and Australia favor neoprene for durability claims and loyalty merchandise value.
- Silicone:Food-grade elastomer molded into collapsible or sleeve formats, washable and heat-resistant to 200°C. Premium roasters in Scandinavia specify silicone for subscription gift boxes and corporate branding.
- Plastic:Extruded polystyrene or polyethylene foam, legacy substrate now contracting under regulatory pressure. Remaining demand concentrates in price-sensitive institutional catering where composting infrastructure is absent.
Cardboard dominates installed base. Neoprene is where expansion concentrates among reusable-format innovators.
Size:
Volume concentration follows cup format standardization across major beverage chains, with medium and large formats capturing procurement scale.
- Small:Diameter 60–70 mm, espresso and cortado formats. Italian café culture and specialty third-wave roasters in Melbourne specify small sleeves for precision beverage service.
- Medium:Diameter 80–90 mm, the universal standard for 12–16 oz disposable cups. Starbucks, Costa Coffee, and Luckin Coffee procurement standardizes around medium sleeves, creating concentrated converter demand.
- Large:Diameter 90–100 mm, 20–24 oz formats dominant in US drive-thru culture. Dunkin' and Tim Hortons specifications drive large sleeve volume in North America.
- Extra Large:Diameter 100+ mm, 32 oz and novelty bucket formats. Limited to cinema concessions and stadium beverage service with seasonal demand spikes.
Medium sleeves anchor global procurement contracts. Large formats are climbing the fastest in US and Chinese drive-thru expansion.
Application:
Customer type determines order frequency and customization depth, with café and restaurant segments operating on opposing replenishment cycles.
- Cafes:Daily-turn inventory with branded sleeve requirements. Chains like Blue Bottle and Intelligentsia specify seasonal design rotations, compressing converter lead times.
- Restaurants:Lower-frequency, higher-volume orders aligned with menu cycles. Full-service chains in France and Spain bundle sleeves with disposable cup procurement under centralized purchasing.
- Events:Episodic demand from festivals, conferences, and sports venues. Sponsorship integration requires rapid-turn digital printing for logo placement.
- Retail:Packaged sleeve sets for home and office use. Amazon and Target private-label programs in the United States specify multipack formats with neutral or seasonal designs.
Cafes command the deepest customization requirements. Events represent the most volatile demand pattern with shortest planning windows.
Design:
Print sophistication and sustainability certification stratify pricing tiers, with eco-friendly variants capturing procurement priority in regulated markets.
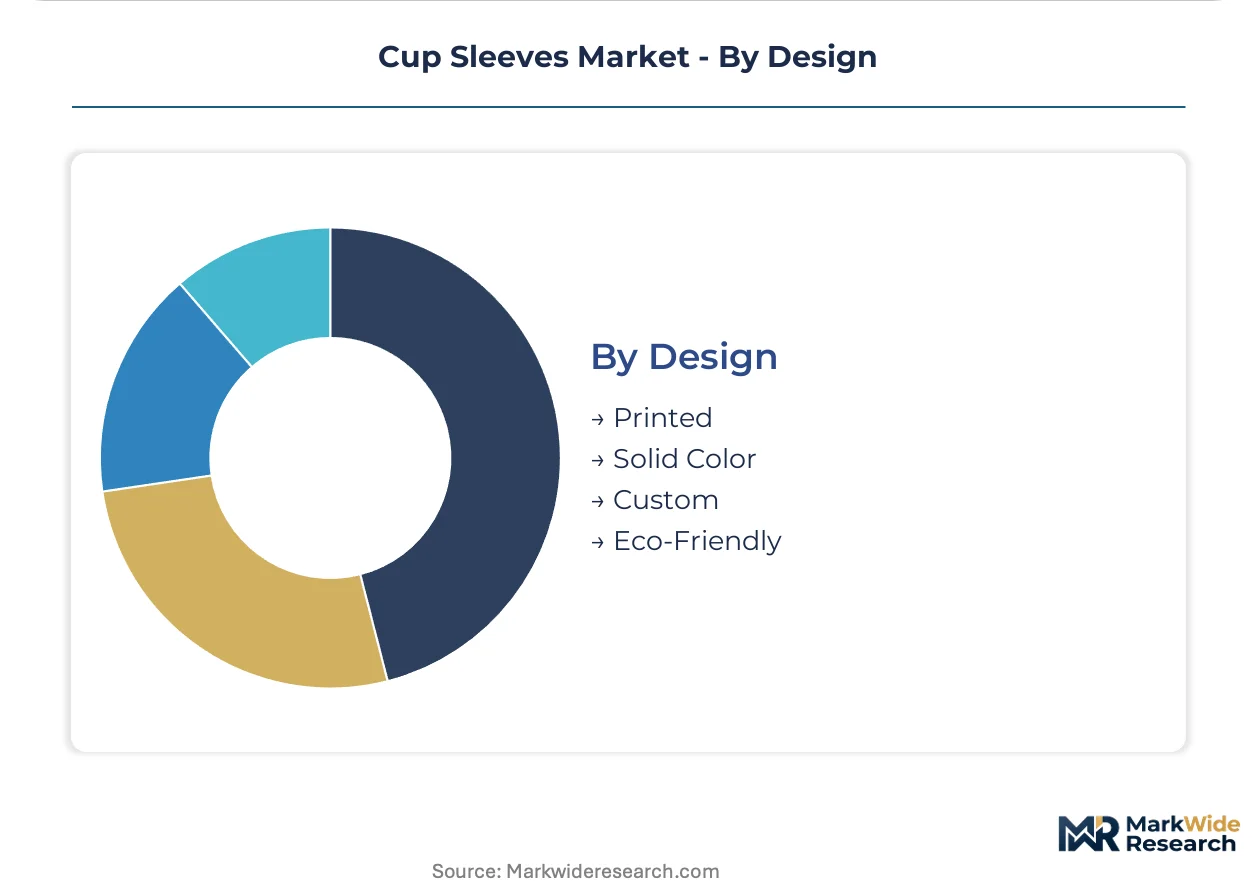
- Printed:Flexographic or digital surface graphics enabling brand messaging and promotional content. Quick-service chains treat printed sleeves as mobile advertising inventory with QR code integration for loyalty programs.
- Solid Color:Single-pigment kraft or bleached board without surface graphics. Institutional catering and budget café segments specify solid color for cost minimization.
- Custom:Bespoke die-cuts, embossing, or specialty substrates for limited editions. Specialty roasters in Portland and Copenhagen commission custom sleeves for harvest-season releases.
- Eco-Friendly:Post-consumer fiber content, water-based inks, and certified compostable substrates. EU Green Deal procurement mandates in Italy and Poland now require demonstrably compostable packaging, favoring certified fiber suppliers.
Printed designs anchor revenue concentration. Eco-friendly specifications are expanding most quickly under regulatory procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service beverage chains and specialty café operators drive procurement intensity across concentrated urban corridors. Extended producer responsibility schemes and municipal composting infrastructure determine supplier qualification thresholds.
United States
Drive-thru coffee formats in Texas, Florida, and California standardize sleeve-inclusive packaging for temperature liability protection. The EPA guides fiber sourcing standards for food-contact packaging while California's extended producer responsibility scheme mandates internalized end-of-life costs. Chicago and Atlanta clusters concentrate converter capacity serving national quick-service chains.
Germany
Municipal composting facilities in Bavaria and North Rhine-Westphalia accept food-soiled cardboard sleeves, validating circular-economy procurement claims. The EU F-Gas Regulation and REACH constrain synthetic foam alternatives, channeling investment toward paper-based solutions. Berlin-Brandenburg anchors converter R&D for water-based barrier coatings.
China
Drive-through tea chains and food delivery packaging upgrades intensify sleeve consumption in Shanghai, Beijing, and Shenzhen. SAMR enforces GB standards for food-contact materials that foreign suppliers navigate for market access. Yangtze River Delta manufacturing clusters supply domestic café expansion with localized converting capacity.
India
Metro café expansion in Bangalore, Mumbai, and Delhi NCR outpaces local sleeve converter capacity, creating import substitution openings. Central pollution control directives pressure fiber-based adoption though enforcement varies by state. Gujarat and Maharashtra industrial corridors attract packaging converters targeting food-service supply chains.
France
Public-sector beverage concessions in Paris, Lyon, and Marseille require demonstrably compostable packaging under EU Green Deal procurement mandates. Extended producer responsibility schemes alter cost allocation between sleeve converters and beverage-chain customers. Auvergne-Rhône-Alpes hosts specialty coating developers addressing REACH Annex XVII fluorinated barrier restrictions.
Cup Sleeves Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement hierarchies. Consolidated containerboard networks supply pre-printed sleeves at scale while regional converters capture quick-turn customization contracts. Three archetypes dominate: integrated paperboard conglomerates with European logistics networks, localized emerging-market converters with municipal composting certifications, and specialty coating innovators addressing regulatory barrier restrictions. Capacity expansion and strategic partnerships constitute the dominant competitive moves as procurement centralizes under corporate sustainability officers.
Among integrated paperboard suppliers, Smurfit Kappa Group and Mondi Group exemplify the scale-driven archetype with European containerboard network positions. Huhtamaki occupies a position within the emerging-market localization tier. These three entities represent distinct strategic postures: European network leverage, kraft paper innovation focus, and geographic proximity to high-growth café corridors respectively.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Dart Container Corporation |
| Mondi Group |
| Novolex |
| Graphic Packaging International |
| Sonoco Products Company |
| WestRock Company |
| Genpak |
| Huhtamaki |
| Others |
Supply Flow & Price Mechanics
Recycled pulp cost volatility determines both the spread between premium and economy sleeve tiers and the geographic distribution of converter capacity. Chains with science-based targets pay premiums for post-consumer fiber certification while budget operators absorb margin compression from spot-market OCC fluctuations.
Pricing Analysis
Cost-plus contracts with OCC indexation dominate procurement between quick-service chains and integrated paperboard suppliers. Pricing stratifies across certified compostable, standard recyclable, and economy virgin-fiber tiers. Cost compression in the economy tier is intensifying because Chinese import restrictions on recovered paper have tightened regional fiber availability. Institutional catering buyers exhibit highest price sensitivity, while specialty café chains with ESG mandates accept double-digit premiums for water-based barrier coatings.
Supply Chain Analysis
Contract manufacturing concentrates among European containerboard networks, Yangtze River Delta converting clusters, and Gujarat industrial corridor specialists. Virgin kraft pulp draws from Scandinavian and Brazilian forestry operations, while post-consumer fiber feeds from municipal collection systems in Germany and the Netherlands. Single-source vulnerability runs through water-based barrier coating formulations qualified under REACH Annex XVII. Distribution runs through beverage-chain regional distribution centers with just-in-time replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cup sleeve procurement fragmentation creates entry niches as sustainability officers consolidate supplier rosters around certified fiber specialists. Digital printing capabilities and municipal composting certifications now separate winning bids from commodity losers.
For Market Incumbents: Build certification moats around BPI and OK Compost HOME credentials before EU Green Deal procurement mandates harden qualification thresholds. Backward integration into post-consumer fiber collection networks in Germany and California secures supply continuity against OCC export competition from Asian paper mills. Capacity addition in Bangalore and São Paulo defends share against emerging-market localization by Huhtamaki-tier competitors. For New Entrants and Emerging Players: Quick-turn digital printing contracts for event sponsorship and seasonal café promotions represent the most penetrable entry point against legacy flexographic incumbents. India's metro café expansion outpaces local converter capacity, creating import substitution openings for European coating innovators. A go-to-market angle targeting municipal composting certification gaps in France and Poland unlocks public-sector concession procurement. For Investors and Strategic Acquirers: Regional converters with captive water-based barrier coating R&D and established SAMR compliance pathways offer asymmetric upside as China café density climbs. Long-term viability hinges on substrate diversification beyond cardboard toward molded fiber alternatives. Watch for consolidation signals when beverage-chain procurement centralization reduces qualified vendor pools below five per region.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Coating Scale-Up | REACH Annex XVII compliance unlocks EU quick-service procurement at premium tier. |
| Digital Printing Infrastructure Investment | Seasonal design rotations for Blue Bottle-tier chains compress converter lead times. |
| Post-Consumer Fiber Integration | EPR scheme alignment in California and Germany secures contract renewals. |
| Municipal Composting Certification | BPI and OK Compost HOME credentials qualify suppliers for EU Green Deal mandates. |
| Localized Converting Capacity Addition | Bangalore and São Paulo plants reduce logistics cost for café chain expansion. |
Methodological Framework
The analysis maps cardboard substrate tiers, reusable neoprene formats, and molded fiber alternatives, each validated through sustainability officers at beverage chains, procurement leads at quick-service operators, and technical directors at coating developers. Primary interviews with sleeve converters in Germany, India, and the United States combined with secondary validation from EPA fiber sourcing guidance, EU F-Gas Regulation filings, and SAMR GB standard documentation. Bottom-up volume estimates from café chain procurement data triangulated against top-down containerboard consumption figures from trade associations.
Assumptions held fixed include EU Single-Use Plastics Directive enforcement timelines and municipal composting infrastructure maturation in the Netherlands and Vermont. Variables tested across the analysis window include recycled pulp price trajectories and water-based coating durability improvements. Segmentation dimensions modeled cover material type, design sophistication, and application channel. CAGRs derived from historical procurement volume patterns and projected café outlet expansion. Forecast inputs incorporated drive-thru format penetration rates and food delivery packaging upgrade cycles.
Practitioners should monitor recycled pulp export demand from Asian paper mills and REACH Annex XVII amendment timelines for early signals of margin compression or regulatory displacement. Quarterly review of municipal composting facility acceptance rates and beverage-chain science-based target progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
US Soft Drinks Packaging Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Pouring Spout Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Self-Cleaning Bottle Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Drink Can Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Bottled Water Packaging Market