
 Plastic Tumblers Market | 2026-2036
Plastic Tumblers Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Tumblers Market Analytics
A shift from single-source Asian contract manufacturing to multi-source regional supply is pivoting procurement strategy across the plastic tumblers value chain. Tupperware Brands Corporation leverages direct-to-consumer channel infrastructure to sustain margin capture outside wholesale. CamelBak Products, LLC anchors its position through technical specialization in vacuum-insulated double-wall construction. Yeti Coolers, LLC differentiates via premium brand positioning and controlled distribution.
Plastic tumblers are injection-molded or thermoformed drinking vessels engineered from food-grade polymers, typically manufactured to withstand repeated dishwasher cycles and thermal stress from -20°C to 100°C beverage contents. The primary commercial purpose spans foodservice operations, consumer retail, and promotional corporate channels where portability and durability outweigh glass or ceramic alternatives. Reusable and insulated product types command disproportionate margin pools as hospitality buyers prioritize lifecycle cost over unit economics. Tritan and polypropylene material segments lead volume while insulated configurations represent the fastest-growing structural category as temperature retention becomes a baseline specification.
FDA food-contact substance regulations under 21 CFR 177, EFSA migration limits under EU Regulation 10/2011, and state-level extended producer responsibility frameworks in California and Maine constrain material selection and end-of-life obligations for manufacturers. These standards elevate compliance costs for imported goods while creating preferential market access for domestic producers with certified testing protocols. Stakeholders must monitor evolving patchwork legislation across North American jurisdictions to anticipate reformulation requirements and recycling infrastructure investments.
Market Dynamics
Single-use plastic bans across municipal jurisdictions are forcing foodservice operators to accelerate reusable tumbler procurement timelines, compressing supplier qualification cycles from 18 months to under 6 months.
Growth Catalysts
- FDA BPA-Free Mandates:Food-contact substance regulations under 21 CFR 177 are accelerating Tritan copolyester adoption across quick-service restaurant chains seeking compliance certainty.
- Extended Producer Responsibility:California and Maine EPR frameworks are creating preferential market access for domestic manufacturers with certified recycling protocols.
- Vacuum-Insulated Construction:Double-wall thermal retention technology is capturing premium positioning as hospitality buyers prioritize lifecycle cost over unit economics.
Market Restraints
- Petrochemical Input Volatility:Propylene and BPA feedstock price swings compress margin stability for injection-molded product lines.
- Asian Contract Manufacturing Concentration:Heavy reliance on single-source Asian suppliers creates tariff exposure and logistics vulnerability for North American distributors.
- Glass and Stainless Substitution:Premium consumer segments are migrating toward metal and ceramic alternatives in corporate gifting channels.
Strategic Opportunities
- Quick-Service Restaurant Reusable Programs:Major chains are deploying branded tumbler systems with deposit-return mechanics to preempt regulatory compliance costs.
- Direct-to-Consumer Channel Expansion:E-commerce subscription models for replacement lid and gasket components are unlocking recurring revenue streams.
- EU Green Deal Circular Economy:EFSA migration limits under EU Regulation 10/2011 are creating export opportunities for certified Tritan formulations.
Industry Challenges
- Multi-Jurisdictional Compliance Talent:Shortage of regulatory specialists capable of navigating patchwork state-level EPR and municipal single-use bans.
- Thermal Testing Certification Timelines:Dishwasher durability validation protocols require 12-18 month testing cycles before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Tumblers Market |
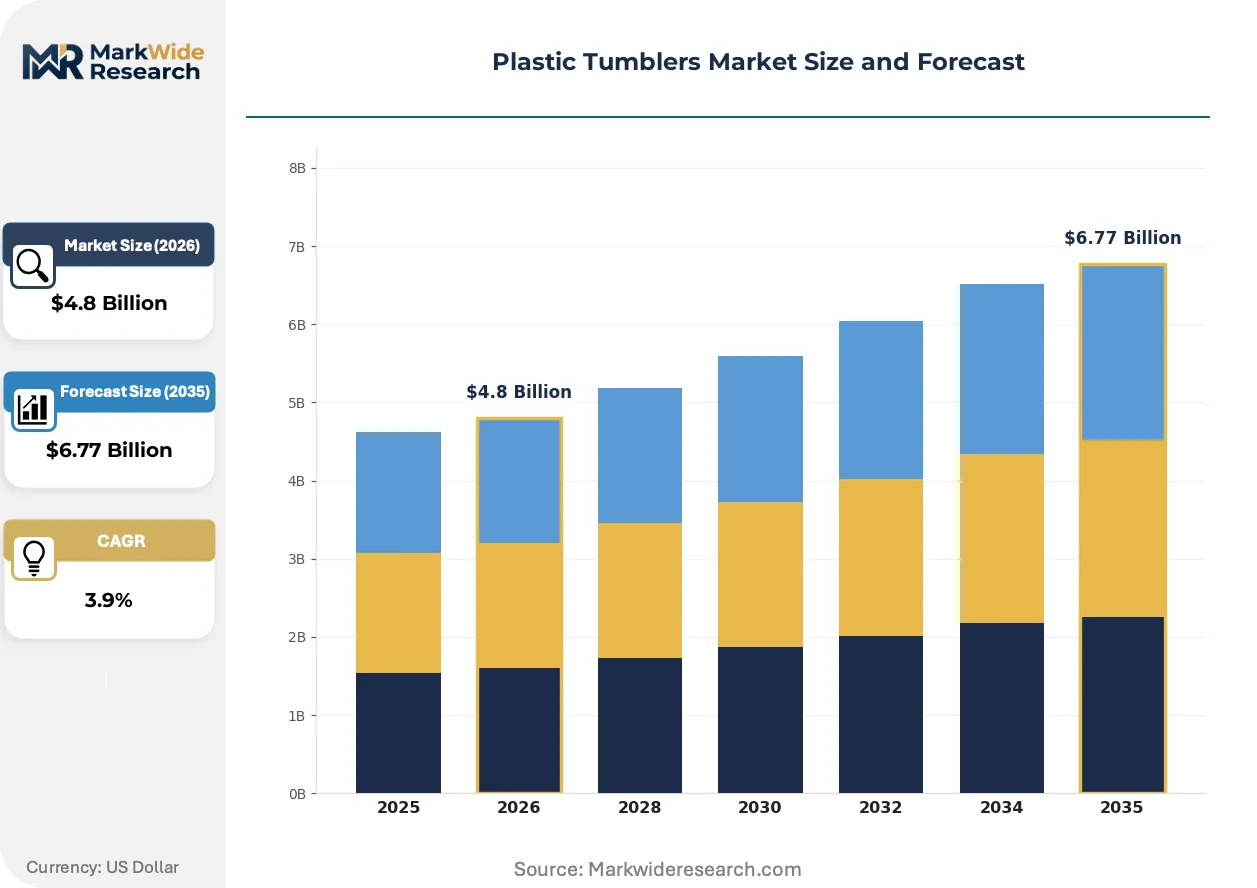
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable, Insulated, Reusable, Disposable Material: Polypropylene, Polyethylene, Tritan, PS Design: Cylindrical, Tapered, Textured, Customizable Capacity: 8 oz, 12 oz, 16 oz, 24 oz |
| Companies Covered | Tupperware Brands Corporation, CamelBak Products, LLC, Pelican Products, Inc., Hydro Flask, Yeti Coolers, LLC, Cool Gear International, LLC, Klean Kanteen, Inc., O2COOL, LLC, Bubba Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Tumblers Market Evolving Landscape
Material science advances and regulatory fragmentation are simultaneously compressing product development cycles and expanding compliance complexity across the plastic tumblers value chain.
Industrial-scale additive manufacturing is automating mold prototyping and short-run production for customized promotional tumblers. Corporate gifting buyers are compressing order lead times from 8 weeks to 10 days. This technology is automating the traditional tool-and-die bottleneck that previously constrained regional supplier responsiveness.
EFSA migration limits under EU Regulation 10/2011 are tightening permissible substance thresholds for food-contact polymers. European importers are demanding batch-level testing documentation that exceeds FDA 21 CFR 177 requirements. Premium Tritan formulations are capturing disproportionate share as buyers prioritize regulatory pre-certification over unit cost.
Foodservice procurement departments are consolidating vendor lists from 15-20 suppliers to 3-5 strategic partners with full compliance documentation. Regional distributors with in-house testing laboratories are displacing fragmented broker networks. This consolidation is most visible in United States quick-service restaurant chains where procurement directors now mandate single-source accountability for EPR obligations.
Plastic Tumblers Market Segmentation
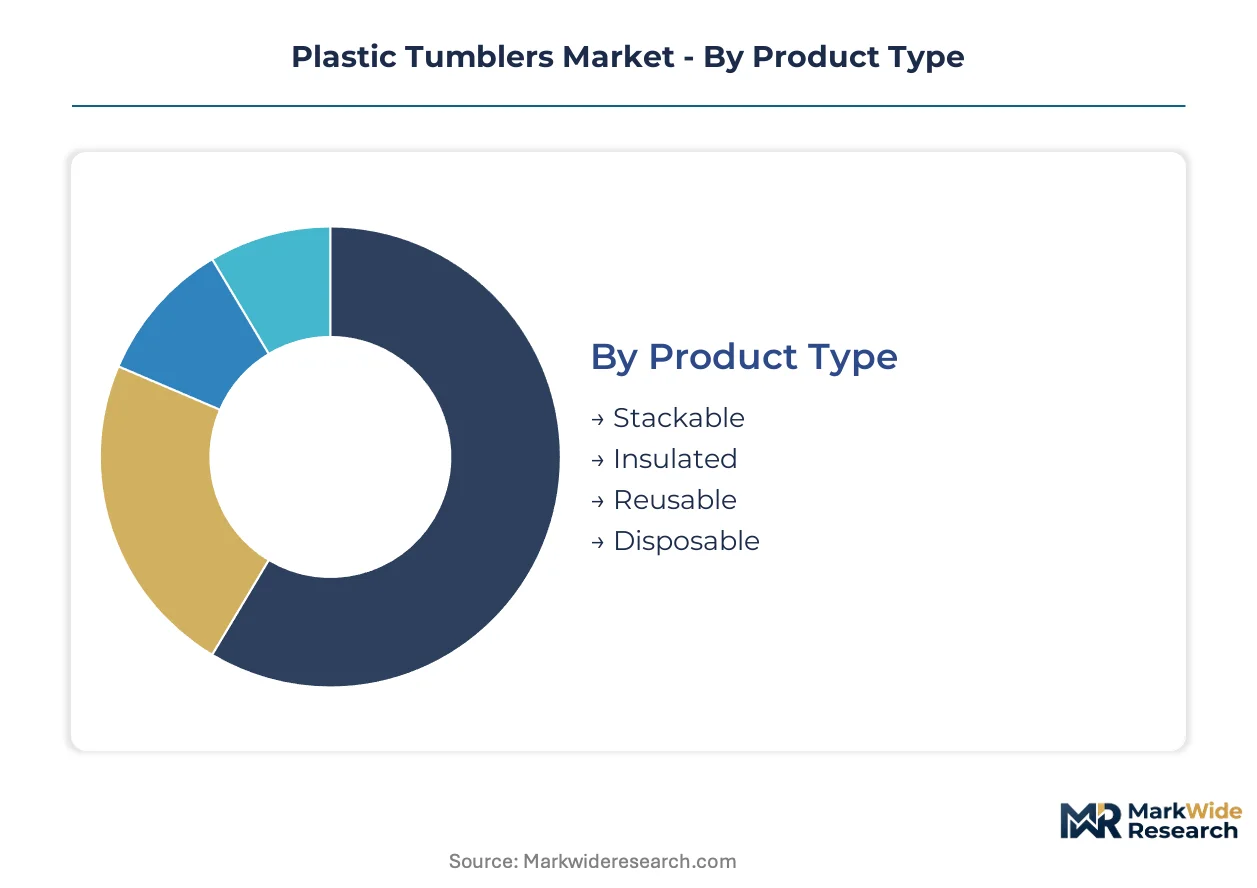
Plastic tumbler procurement patterns diverge sharply across functional specifications, with foodservice operators prioritizing stackability and thermal performance while retail channels emphasize material compliance and aesthetic differentiation. Segmentation clarity enables suppliers to align mold configurations and polymer formulations with channel-specific margin structures.
Product Type:
Stackable and insulated variants serve embedded foodservice systems requiring operational integration, while reusable and disposable formats operate as standalone purchase decisions for end consumers.
- Stackable:Injection-molded with interlocking rim geometries for commercial dish racks. Quick-service restaurant chains in the United States specify NSF-certified stackable designs to maximize storage density in back-of-house operations. FDA 21 CFR 177 compliance is non-negotiable for high-temperature sanitization cycles.
- Insulated:Double-wall vacuum or foam-core construction maintains beverage temperature across extended consumption windows. Hospitality buyers in California prioritize lifecycle cost calculations over unit economics when specifying insulated tumblers for outdoor dining programs. EPR frameworks in Maine and California create compliance barriers for imported insulated products lacking certified end-of-life protocols.
- Reusable:Engineered for 500+ dishwasher cycles with reinforced stress points. Municipal single-use bans in Montreal and Vancouver accelerate procurement timelines for branded reusable programs.
- Disposable:Thin-wall thermoformed construction for event catering and grab-and-go applications. Regulatory pressure compresses addressable market as EPR obligations expand.
Stackable configurations lead volumes today; insulated variants are gaining share fastest.
Material:
Polymer selection stratifies across cost tiers, with commodity resins dominating high-volume foodservice and engineered copolyesters capturing premium positioning.
- Polypropylene:Homopolymer and random copolymer grades offer chemical resistance and microwave stability. United States quick-service chains specify FDA-compliant polypropylene for hot beverage applications where thermal shock resistance exceeds Tritan performance. Feedstock volatility from propylene monomer swings compresses margin predictability.
- Tritan:Eastman Chemical's copolyester delivers glass-like clarity with BPA-free certification under FDA and EFSA guidance. European importers demand batch-level migration testing documentation exceeding domestic requirements. Premium pricing persists as buyers prioritize regulatory pre-certification.
- Polyethylene:LDPE and HDPE variants serve cold-beverage disposables and flexible lid components. Limited thermal resistance constrains foodservice adoption.
- PS:Polystyrene faces accelerating substitution as municipal bans proliferate; residual demand concentrates in low-cost event catering with limited reuse cycles.
Polypropylene dominates unit volumes; Tritan climbs the fastest on regulatory tailwinds.
Design:
Geometric complexity correlates with application specificity, with standardized cylindrical forms serving operational efficiency and customized surfaces enabling brand differentiation.
- Cylindrical:Uniform diameter enables automated filling lines and standardized lid compatibility. Foodservice procurement departments specify cylindrical designs to minimize SKU complexity across multi-location deployments.
- Tapered:Frustum profiles improve stack stability and ergonomic grip. Corporate gifting channels in the United States favor tapered silhouettes for premium unboxing experiences.
- Textured:Molded-in patterns enhance tactile grip and mask surface wear. Quick-service operators specify textured finishes for high-traffic outdoor dining environments.
- Customizable:Blank surfaces or molded recesses accommodate pad printing, heat transfer, and in-mold labeling. Promotional buyers compress lead times from 8 weeks to 10 days through additive manufacturing-enabled mold prototyping.
Cylindrical designs anchor procurement volumes; customizable formats expand most quickly on personalization demand.
Capacity:
Volume specifications map directly to beverage category conventions, with coffee and fountain drink standards driving procurement standardization.
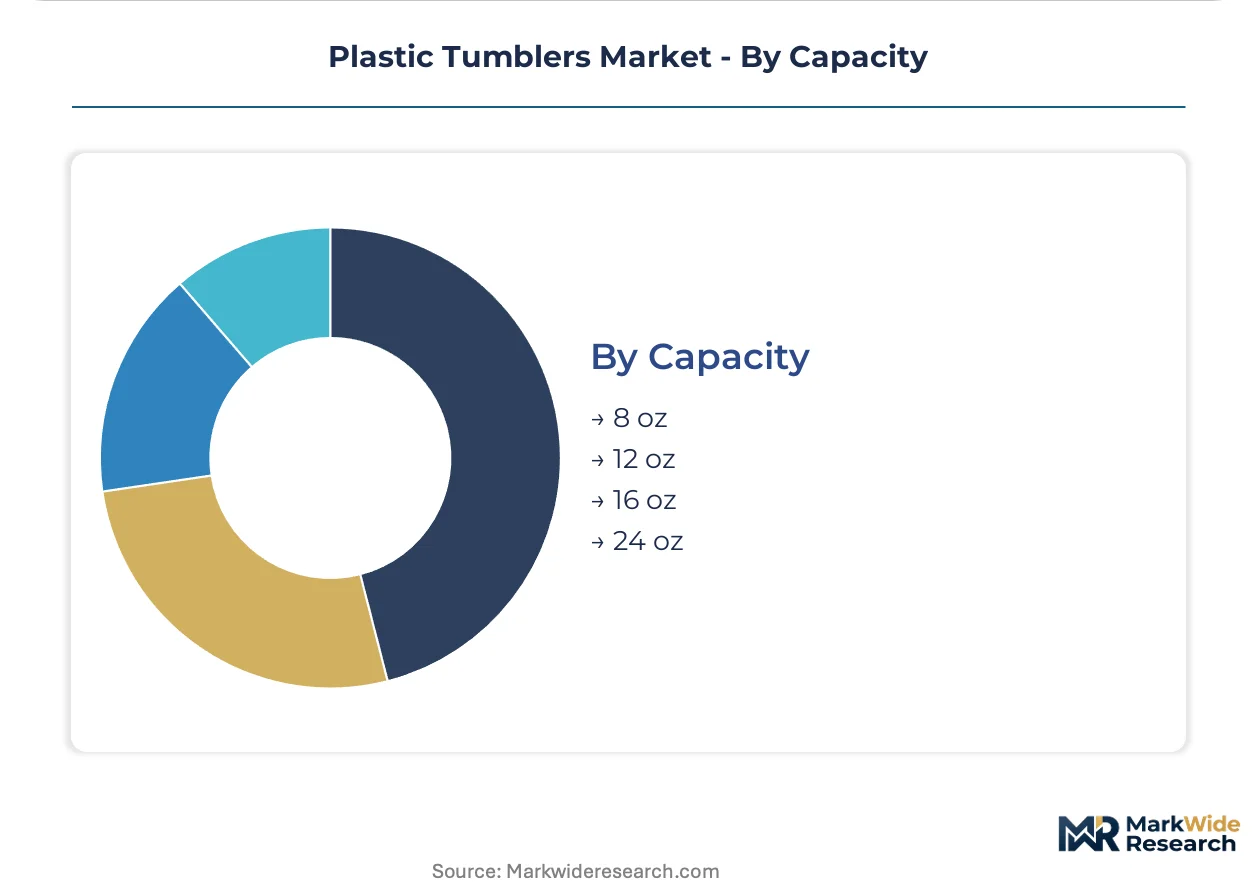
- 16 oz:The dominant specification for fountain beverages and iced coffee across United States quick-service chains. Stackable 16 oz configurations maximize operational efficiency in high-throughput environments.
- 12 oz:Standard hot coffee format with established lid ecosystem compatibility. Foodservice operators specify 12 oz as the baseline for breakfast daypart programs.
- 24 oz:Large-format option for specialty beverages and extended consumption occasions. Premium insulated 24 oz variants command disproportionate margin in hospitality channels.
- 8 oz:Concentrated in espresso-based applications and children's portions. Limited addressable market constrains supplier investment.
16 oz specifications lead procurement volumes; 24 oz formats show steepest expansion trajectory on premium beverage trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with streamlined compliance pathways as EFSA migration limits and FDA food-contact substance regulations diverge in stringency. This regulatory arbitrage concentrates molding capacity in countries offering pre-certified polymer formulations and accelerated testing timelines.
United States
Quick-service restaurant chains and corporate gifting channels drive procurement volumes across California, Texas, and the Southeast. FDA 21 CFR 177 compliance is mandatory for hot-beverage applications, with California's extended producer responsibility framework creating preferential access for domestic producers with certified recycling protocols. Injection-molding clusters in Ohio and Michigan serve foodservice operators consolidating vendor lists from 15-20 suppliers to 3-5 strategic partners.
Germany
Premium hospitality buyers prioritize lifecycle cost calculations over unit economics when specifying insulated tumblers for outdoor dining programs. EFSA migration limits under EU Regulation 10/2011 exceed FDA requirements, driving batch-level testing documentation demands. Industrial fabricators in Bavaria and North Rhine-Westphalia supply Tritan formulations to European importers seeking regulatory pre-certification.
China
Contract manufacturers face margin compression from propylene feedstock volatility and tariff exposure on exports to North American distributors. GB standards for food-contact materials are converging with international norms, though dual carbon goals from MEE are elevating energy costs for injection-molding operations. Production gravity in Guangdong and Zhejiang provinces is fragmenting as buyers pursue multi-source regional supply strategies.
Canada
Municipal single-use plastic bans in Montreal and Vancouver are accelerating procurement timelines for branded reusable programs from 18 months to under 6 months. Health Canada and PMRA guidance on BPA-free materials aligns with FDA mandates, simplifying cross-border compliance for Tritan copolyester formulations. Quebec and Ontario processors are capturing displaced demand from Asian contract manufacturers.
India
BIS certification requirements for food-contact polymers are tightening as FSSAI enforcement expands beyond metropolitan markets. PLI scheme incentives for domestic manufacturing are attracting mold fabrication investment in Gujarat and Maharashtra. Quick-service restaurant chains entering tier-2 cities are driving stackable tumbler specifications compatible with automated filling lines.
Plastic Tumblers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue vacuum-insulated specialization and direct-to-consumer channel expansion. The market exhibits tiered concentration with three to five strategic partners dominating foodservice procurement consolidation. Archetypes include diversified housewares conglomerates, technical outdoor specialists, and premium brand positioners. Competitive moves center on backward integration into polymer compounding and geographic diversification of molding capacity to preempt tariff exposure.
Within the diversified housewares tier, Tupperware Brands Corporation exemplifies direct-to-consumer infrastructure deployment. Technical outdoor specialists include CamelBak Products, LLC and Yeti Coolers, LLC, occupying positions anchored by vacuum-insulated construction expertise. These three companies represent distinct archetype strategies: channel control, engineering specialization, and premium brand positioning respectively.
| Leading Market Players |
|---|
| Tupperware Brands Corporation |
| CamelBak Products, LLC |
| Pelican Products, Inc. |
| Hydro Flask |
| Yeti Coolers, LLC |
| Cool Gear International, LLC |
| Klean Kanteen, Inc. |
| O2COOL, LLC |
| Bubba Brands, Inc. |
| Others |
Value Network & Pricing Analysis
Propylene feedstock price volatility cascades through injection-molded product lines, compressing margin stability and forcing buyers toward multi-year contract structures with indexed pricing clauses. Tritan copolyester formulations command premium positioning as FDA and EFSA compliance documentation elevates procurement qualification thresholds above commodity resin tiers.
Pricing Analysis
Input-cost pass-through mechanics dominate pricing negotiations as propylene monomer swings transmit directly to polypropylene tumbler quotations within 60-90 day lag windows. Three-tier pricing structure across premium, standard, and economy levels separates Tritan-certified hospitality specifications from NSF-grade foodservice stackables and thin-wall disposable formats. Cost compression in standard-grade polypropylene is intensifying because Asian contract manufacturers compete on volume throughput. Quick-service restaurant chains exhibit highest price sensitivity due to procurement consolidation, while corporate gifting channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification as procurement directors consolidate vendor lists from 15-20 suppliers to 3-5 strategic partners with full EPR accountability. Manufacturing capacity concentrates in China, the United States, and Germany, with mold fabrication clusters in Ohio, Michigan, Bavaria, and Guangdong feeding regional assembly operations. Raw material dependencies center on propylene monomer, BPA-free copolyester resins, and vacuum-insulation copper liners. Single-source vulnerability persists in specialized Tritan formulations where Eastman Chemical maintains formulation control. Distribution runs through foodservice redistribution networks, direct-to-consumer e-commerce platforms, and promotional product distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where municipal single-use plastic bans and EPR frameworks transform compliance capability into pricing power. FDA 21 CFR 177 and state-level extended producer responsibility mandates in California and Maine accelerate procurement timeline compression.
For Market Incumbents: Cement market position through backward integration into polymer compounding and captive mold fabrication capacity in Ohio or Michigan. Defend against glass and stainless substitution by accelerating vacuum-insulated product line expansion with certified end-of-life protocols. Channel control through direct-to-consumer infrastructure sustains margin capture outside consolidated foodservice procurement.
For New Entrants and Emerging Players: Launch via additive manufacturing-enabled rapid prototyping to serve corporate gifting channels with 10-day lead time compression. Target quick-service restaurant reusable program deployments in Canada where Montreal and Vancouver municipal bans compress supplier qualification cycles. White-space opportunity concentrates in certified Tritan formulations for European export markets demanding batch-level EFSA migration documentation.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional distributors possessing in-house testing laboratories and multi-jurisdictional compliance expertise. Long-term viability hinges on 5-10 year regulatory trajectory where EPR expansion and FDA guidance tightening favor domestic producers with certified recycling protocols. Signal to monitor: state-level EPR adoption velocity beyond California and Maine as inflection indicator for preferential market access dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captures margin pool from propylene volatility while securing FDA-compliant resin supply for Tritan formulations. |
| Direct-to-Consumer Channel Expansion | Unlocks recurring revenue through subscription models for replacement lid and gasket components outside wholesale compression. |
| Vacuum-Insulated Product Line Investment | Addresses hospitality buyer lifecycle cost priorities while preempting glass and stainless substitution in premium segments. |
| Multi-Jurisdictional Compliance Certification | Creates preferential market access under California and Maine EPR frameworks with single-source accountability. |
| Additive Manufacturing Prototyping Capability | Compresses promotional tumbler lead times from 8 weeks to 10 days for corporate gifting procurement departments. |
Research Methodology
Coverage spans the United States, Germany, China, Canada, and India, with primary inputs from each market informing cross-regional pattern identification. The approach combines structured interviews with procurement directors at quick-service restaurant chains, regulatory affairs specialists navigating FDA and EFSA frameworks, mold fabrication engineers in Ohio and Bavaria, and channel managers at foodservice redistribution networks. Secondary validation draws from FDA 21 CFR 177 guidance documents, EFSA migration limit specifications under EU Regulation 10/2011, state-level EPR legislative filings in California and Maine, and customs trade data on polymer resin imports. Bottom-up demand modeling and top-down supply capacity assessments triangulate volume and value outputs.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework models plastic tumbler demand across product type, material formulation, design geometry, and capacity specifications, with regional regulatory cluster as an additional segmentation dimension. CAGRs derive from weighted average of historical trajectory and forward scenario analysis. Industry-specific forecast inputs include propylene feedstock price futures curves and municipal single-use ban implementation timelines across North American jurisdictions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPR adoption or petrochemical supply disruption scenarios. Deviation in FDA guidance stringency or EFSA migration limit thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
United States Plastic Bottles Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
South Africa Plastic Packaging Films Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Australia Plastic Packaging Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Plastic Battery Containers Market
Plastic Packaging
PCR Films Market