
 Reusable Tumblers Market | 2026-2036
Reusable Tumblers Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Tumblers Market Analytics
Aftermarket customization revenue is fragmenting across engraving services, replacement lid programs, and co-branded corporate gifting. YETI anchors its position through premium thermal engineering and direct-to-consumer channel control. Hydro Flask differentiates via colorway innovation and outdoor retail partnerships. Klean Kanteen competes on certified food-grade stainless steel sourcing and B-Corp sustainability credentials.
Reusable tumblers are double-walled beverage vessels, typically fabricated from 18/8 stainless steel with vacuum insulation achieving 6–12 hour temperature retention, designed to displace single-use cups in commercial and consumer hydration. Stainless steel insulated designs dominate value pools due to durability premiums and corporate logo durability, while straw-included variants capture fastest household penetration among families with children. The hospitality end-user segment remains underdeveloped relative to office procurement, suggesting latent contract catering demand.
The EU Single-Use Plastics Directive, FDA food-contact substance regulations, and China's GB standards for stainless steel food containers collectively elevate material compliance costs while restricting low-grade imports. REACH and California Proposition 65 testing requirements further constrain pigment and coating chemistries available to manufacturers. Stakeholders must monitor evolving extended producer responsibility schemes and biopolymer substitution threats to stainless steel's cost position.
Market Dynamics
Corporate sustainability mandates are overriding cost optimization in procurement decisions, forcing stainless-steel vessel adoption across Fortune 500 food-service contracts despite 8-12x unit cost premiums over disposable alternatives.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework mandates phased elimination of disposable beverage containers across member states, compelling contract caterers to source compliant alternatives.
- 18/8 stainless steel vacuum insulation:This fabrication standard delivers 6–12 hour temperature retention that satisfies office and outdoor hydration requirements simultaneously.
- Urban coffee culture clusters:Dense metropolitan consumption in the United States, China, and Germany creates concentrated demand for portable, branded beverage vessels.
Market Restraints
- Nickel price volatility:18/8 stainless steel contains 8% nickel, exposing manufacturers to London Metal Exchange price swings that compress margin predictability.
- REACH compliance costs:ECHA registration requirements for pigment and coating chemistries elevate testing expenditure for EU market entry.
- Biopolymer substitution threat:PLA and PHA food-contact materials are achieving cost parity in single-use applications, pressuring reusable value propositions in price-sensitive segments.
Strategic Opportunities
- Hospitality contract catering:Hotels, airlines, and event venues remain underpenetrated relative to office procurement, representing latent volume for thermal vessel suppliers.
- Extended Producer Responsibility schemes:France and Germany are advancing deposit-return frameworks that incentivize durable container circulation over disposability.
- Replacement lid programs:Aftermarket component sales create recurring revenue streams independent of vessel replacement cycles.
Industry Challenges
- GB standard certification timelines:China's food-contact stainless steel testing protocols impose 4-6 month approval windows that delay product launches.
- Coating chemistry talent scarcity:Formulators with REACH-compliant food-grade powder coating expertise command premium compensation in constrained labor pools.
- California Proposition 65 litigation exposure:Warning label requirements for trace heavy metals create liability risk that demands specialized legal monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Tumblers Market |
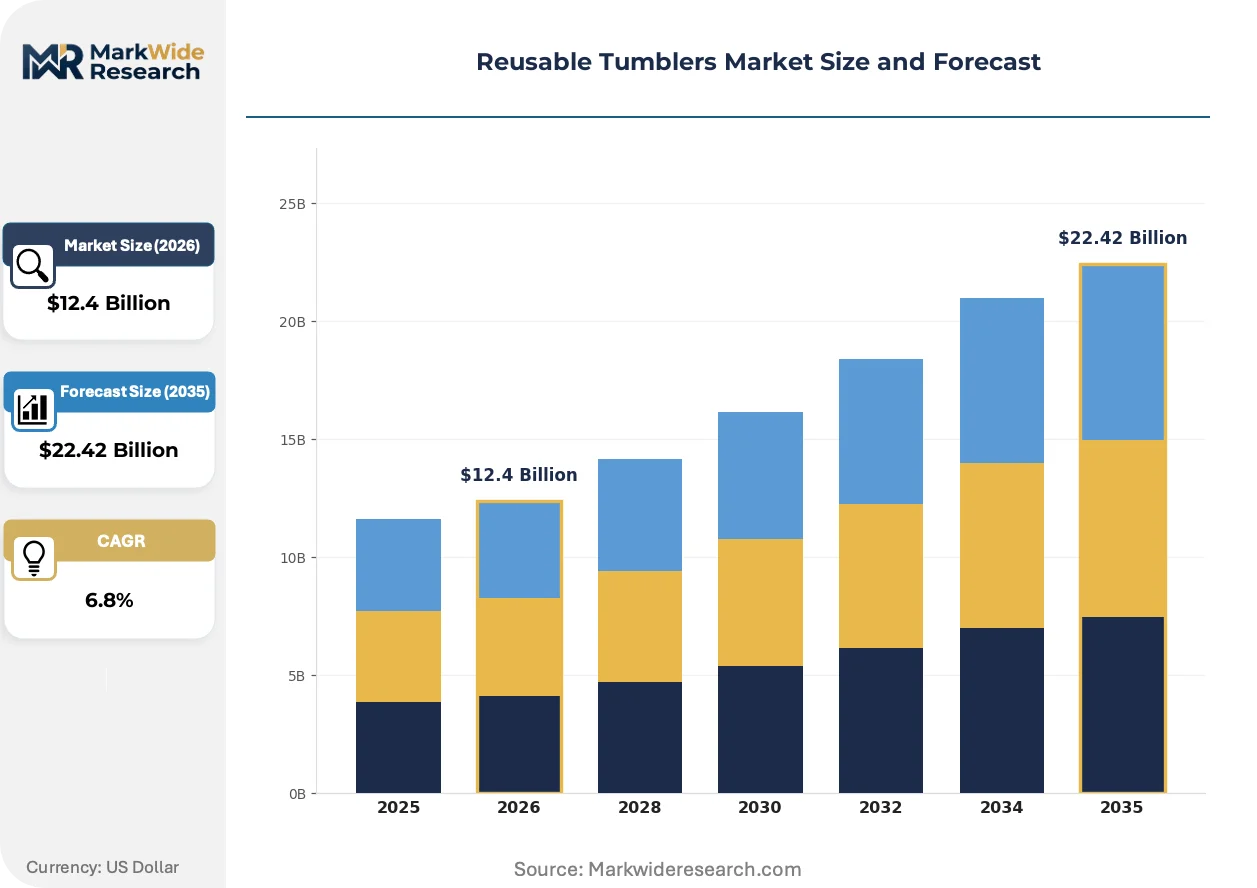
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Glass, Plastic, Silicone Design: Screw Top, Straw Included, Collapsible, Insulated End User: Household, Office, Hospitality, Sports Events Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | S'well, Thermos, YETI, Starbucks, CamelBak, Stanley, RTIC Outdoors, Klean Kanteen, Hydro Flask, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Tumblers Market Evolving Landscape
Material science advances and regulatory tightening are compressing product development cycles while fragmenting competitive differentiation across thermal performance, chemical compliance, and channel control dimensions.
Copper-lined vacuum insulation is collapsing the performance gap between mid-market and premium thermal retention claims. Corporate procurement teams at technology campuses are specifying copper-enhanced designs for executive gifting programs. The technology is collapsing price-tier boundaries that previously separated YETI-equivalent performance from private-label alternatives.
REACH SVHC candidate list expansion is forcing reformulation of color pigments across powder coating supply chains. ECHA's biannual updates are accelerating R&D expenditure for manufacturers serving EU food-service contracts. Stainless-steel tumblers with decorative finishes face disproportionate compliance burden relative to bare-metal designs.
Direct-to-consumer subscription models are displacing wholesale distribution for replacement component sales. Outdoor retail partnerships that built Hydro Flask's market presence are losing share to brand-owned digital channels. Germany and California exhibit the fastest channel rotation, where urban consumers prioritize customization over retail immediacy.
Reusable Tumblers Market Segmentation
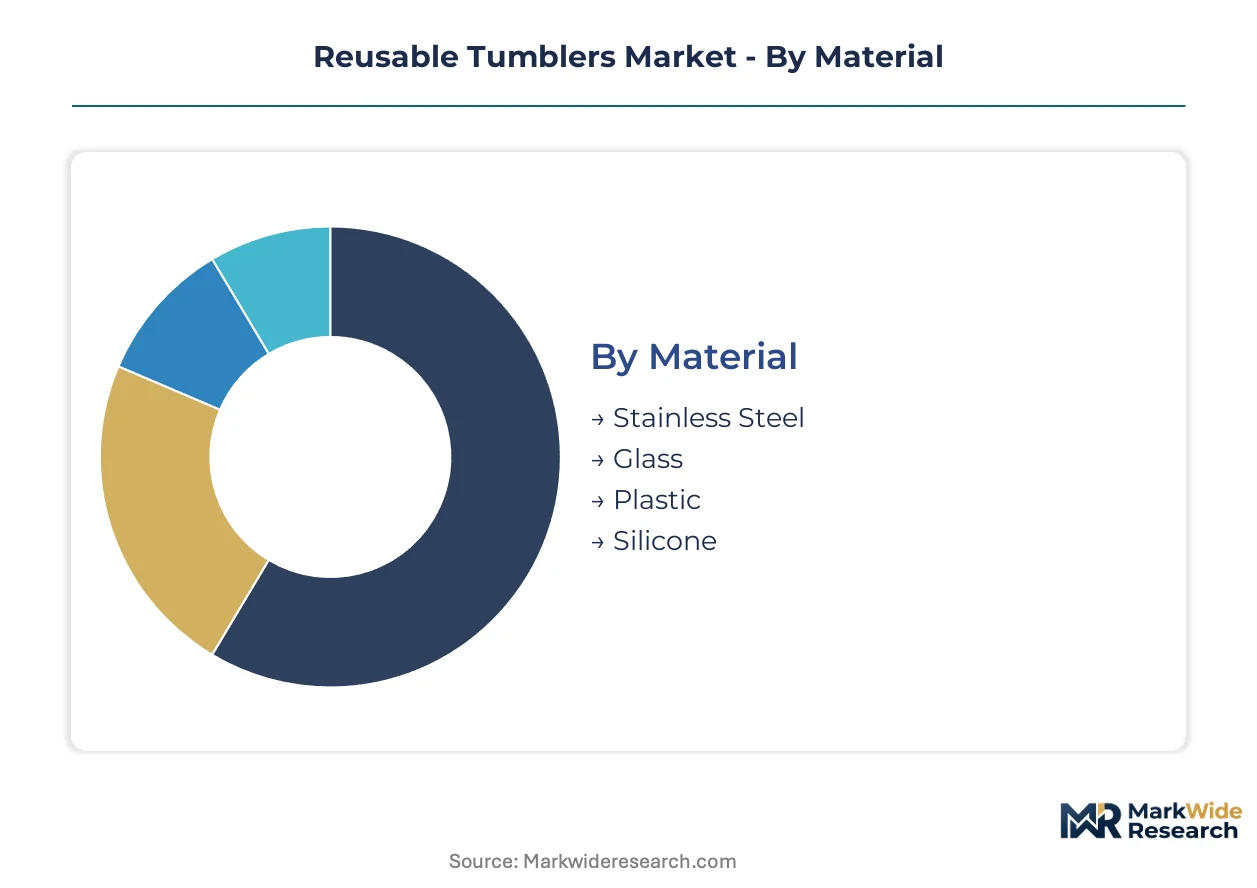
Segmentation in the Reusable Tumblers Market determines service intensity, replacement part economics, and channel investment priorities. Material selection drives thermal performance claims and regulatory compliance burdens, while design configuration shapes aftermarket revenue potential through lid replacement programs and component wear cycles.
Material:
Aftermarket service intensity varies sharply by material type, with stainless steel requiring minimal warranty intervention while glass and silicone generate higher replacement frequency and customer service touchpoints.
- Stainless Steel:18/8 grade vacuum-insulated fabrication delivers 6–12 hour temperature retention and satisfies corporate procurement durability specifications. Demand concentrates in United States and Germany office campuses where Fortune 500 sustainability mandates override unit cost premiums.
- Glass:Borosilicate construction offers chemical inertness and taste neutrality that appeals to specialty coffee consumers. European urban markets exhibit strongest adoption where ECHA REACH compliance on coatings displaces lower-grade alternatives.
- Plastic:Tritan copolyester and polypropylene variants serve price-sensitive household penetration with lower thermal performance thresholds. India and Southeast Asian markets show volume concentration for daily commuting applications.
- Silicone:Collapsible and sleeve-reinforced designs prioritize packability over insulation, capturing outdoor recreation and travel segments where space efficiency outweighs temperature retention requirements.
Stainless steel holds the largest share; momentum sits with silicone as travel and remote work patterns normalize.
Design:
Cost tier stratification separates premium thermal engineering from commodity convenience features, with screw-top and insulated variants commanding manufacturing complexity premiums over straw-included and collapsible alternatives.
- Screw Top:Threaded closure systems achieve leak resistance for bag transport and active commuting. Corporate gifting programs in China and United States specify engraved screw-top vessels for executive onboarding kits.
- Straw Included:Integrated or detachable straw configurations dominate household penetration among families with children, reducing spill risk and simplifying cleaning protocols.
- Collapsible:Silicone or hybrid folding designs compress to pocket size for intermittent use scenarios. Sports events and airline hospitality contracts represent underdeveloped volume opportunities.
- Insulated:Double-walled vacuum construction with copper lining now spans premium and mid-market tiers, collapsing historical performance boundaries between price segments.
Insulated designs command value concentration; straw-included variants are climbing the fastest as family-oriented demand expands.
End User:
Application context dictates volume scale, customization requirements, and contract renewal cycles, with office procurement exhibiting predictable replacement scheduling compared to episodic hospitality demand.
- Household:Individual and family consumption drives colorway diversity and seasonal purchasing patterns. Online retailers capture dominant share through subscription replacement lid programs.
- Office:Corporate sustainability mandates across technology and financial services campuses generate bulk procurement with logo durability specifications. United States and Germany lead contract value.
- Hospitality:Hotels, airlines, and event venues remain underpenetrated relative to office segments, with deposit-return frameworks in France and Germany creating structural incentives for durable vessel circulation.
- Sports Events:Stadium and arena concessions present latent volume for branded vessel programs, constrained by cleaning logistics and loss rates in high-turnover environments.
Office procurement holds the largest share; hospitality represents the steepest expansion trajectory as EPR schemes advance.
Distribution Channel:
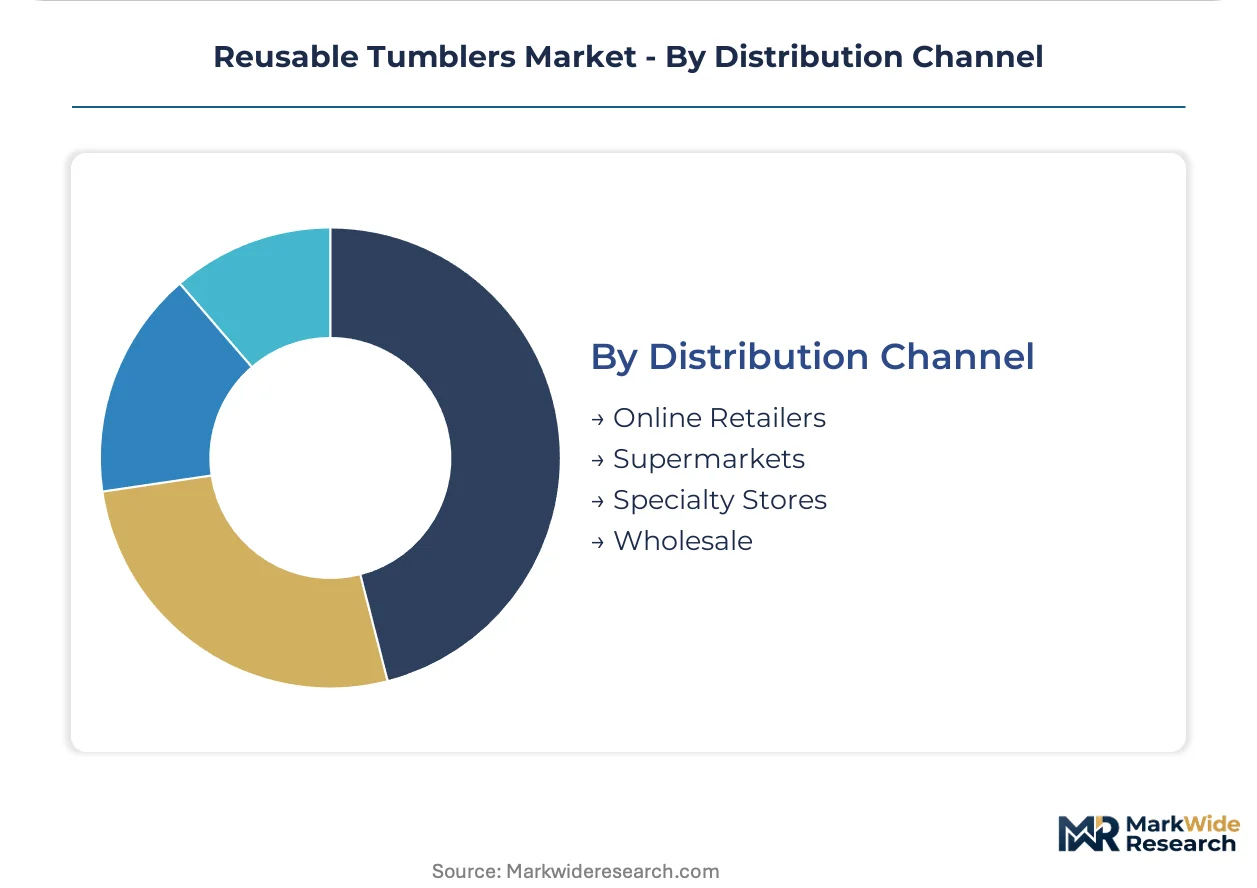
Customer type and purchase urgency shape channel preference, with urban professionals favoring digital customization while suburban households rely on retail immediacy for replacement and gift occasions.
- Online Retailers:Direct-to-consumer platforms enable engraving services, subscription lid replacement, and colorway exclusives. Germany and California exhibit fastest channel rotation toward brand-owned digital.
- Supermarkets:Mass retail placement captures impulse and gift purchases with lower price points and reduced thermal performance specifications. India and China urban markets show strongest supermarket velocity.
- Specialty Stores:Outdoor and coffee-focused retail built early brand presence through tactile evaluation and staff expertise. Hydro Flask partnerships exemplify this channel's historical importance.
- Wholesale:B2B procurement for corporate gifting and contract catering runs through specialized distributors with compliance documentation and volume pricing structures.
Online retailers hold the largest share; wholesale is gaining share fastest as corporate procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless-steel fabrication concentrates in China, Germany, and the United States, where vacuum-insulation manufacturing clusters serve corporate procurement contracts across three continents. Demand fragmentation follows urban coffee culture density and regulatory enforcement intensity.
United States
Fortune 500 technology and financial services campuses in Seattle, San Francisco, and New York Metro drive bulk procurement of engraved vessels for sustainability mandates. FDA food-contact substance regulations govern powder coating chemistries on stainless-steel interiors. Austin and Denver anchor outdoor retail distribution networks for premium thermal brands.
Germany
Extended Producer Responsibility frameworks in France and Germany incentivize deposit-return circulation models for hospitality contract catering. ECHA REACH SVHC candidate list expansions force reformulation of decorative pigment coatings. Munich and Hamburg concentrate corporate gifting procurement for automotive and engineering headquarters.
China
GB standards for stainless steel food containers impose 4-6 month certification timelines that delay product launches for export markets. Yangtze River Delta manufacturing clusters produce vacuum-insulated vessels for private-label and branded contract manufacturing. Shanghai and Shenzhen dominate e-commerce channel control for direct-to-consumer subscription models.
India
Daily commuting applications in Mumbai, Delhi-NCR, and Bangalore drive price-sensitive household penetration of plastic and lower-grade metal variants. FSSAI food-contact regulations and BIS certification requirements elevate import barriers for foreign manufacturers. Gujarat and Tamil Nadu industrial corridors host domestic fabrication capacity for regional brands.
United Kingdom
Specialty coffee culture in London and Edinburgh sustains demand for borosilicate glass and premium stainless-steel designs. UK implementation of EU Single-Use Plastics Directive phase-outs compels contract caterer compliance. Manchester and Birmingham office clusters exhibit accelerating corporate sustainability procurement velocity.
Reusable Tumblers Market Competitive Landscape
Premium thermal engineering specialists and outdoor retail heritage brands split the market into performance-tiered segments with divergent channel strategies. Consolidation pressure concentrates among mid-market private-label fabricators facing REACH compliance cost escalation. Three archetypes dominate: direct-to-consumer digital natives, outdoor retail partnership legacy players, and stainless-steel fabrication contract manufacturers. Capacity expansion in copper-lined vacuum insulation and backward integration into powder coating supply chains represent the dominant competitive moves.
Within the premium thermal tier, YETI and Hydro Flask exemplify divergent channel control strategies, while Klean Kanteen occupies a position emphasizing certified sourcing credentials. S'well and Thermos represent design-forward and heritage-insulation archetypes respectively. Stanley and CamelBak anchor multi-category hydration portfolios that span beverage vessels across outdoor and household applications.
| Leading Market Players |
|---|
| S'well |
| Thermos |
| YETI |
| Starbucks |
| CamelBak |
| Stanley |
| RTIC Outdoors |
| Klean Kanteen |
| Hydro Flask |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese vacuum-insulation manufacturing is compressing unit economics for mid-market fabricators while amplifying pricing power for REACH-certified European suppliers serving corporate procurement contracts. This utilization asymmetry rewards backward-integrated players with captive powder-coating capabilities and punishes pure-play assemblers exposed to nickel price volatility.
Pricing Analysis
Aftermarket lid replacement and engraving services now drive lifetime value capture, with subscription models displacing transactional vessel sales in Germany and California. Three-tier pricing structure across premium copper-lined, standard vacuum-insulated, and economy single-wall tiers separates thermal performance claims. Cost compression in bare-metal designs is intensifying because biopolymer substitutes are achieving functional parity in price-sensitive Indian and Southeast Asian households. Corporate procurement teams exhibit lowest price sensitivity, while daily commuters in emerging markets resist unit cost premiums exceeding disposable alternatives.
Supply Chain Analysis
Upstream nickel and chromium feedstock draws from Indonesian mining expansion and South African ferrochrome consolidation, with 18/8 stainless steel sheet production concentrating in China, Germany, and Japan. Vacuum-insulation manufacturing rests on copper lining adoption, automated welding equipment, and REACH-compliant powder coating chemistries. Single-source vulnerability sits with ECHA-registered pigment formulators in constrained European labor pools. Distribution runs through direct-to-consumer platforms for replacement components and specialized wholesale distributors for corporate gifting contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with REACH SVHC compliance expertise command compensation premiums that reshape competitive economics, creating asymmetric returns for employers who secured this capability early.
For Market Incumbents: Pre-empt biopolymer substitution threats by accelerating copper-lined vacuum insulation adoption across mid-market tiers, collapsing the performance boundary that previously protected premium positioning. Secure captive powder-coating capacity or long-term offtake agreements with ECHA-registered formulators before talent scarcity intensifies compliance cost escalation. For New Entrants and Emerging Players: Pursue hospitality contract catering in France and Germany where Extended Producer Responsibility deposit-return frameworks create structural demand for durable vessel circulation. Target airline and hotel procurement teams with collapsible silicone designs optimized for space-constrained service carts, leveraging direct-to-consumer subscription models for replacement lid revenue. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across copper-lined vacuum insulation fabrication as equipment automation and backward coating integration demands expand. Favor acquisition targets with established GB standard certification timelines and existing ECHA registration portfolios over greenfield entrants facing 4-6 month approval delays. Watch nickel price volatility on the London Metal Exchange as the signal indicating margin compression severity for non-integrated fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Coating | Captive REACH-compliant formulation capacity eliminates ECHA registration bottlenecks and margin leakage to scarce external suppliers. |
| Copper-Lined Vacuum Insulation Expansion | Collapsing thermal performance boundaries between premium and mid-market tiers defends against private-label displacement. |
| Direct-to-Consumer Subscription Launch | Germany and California channel rotation toward brand-owned digital displaces wholesale margin sharing with outdoor retail partners. |
| Hospitality Contract Catering Penetration | Underdeveloped hotels and airlines in France and Germany offer volume expansion as EPR deposit-return frameworks advance. |
| Replacement Lid Program Development | Recurring aftermarket revenue decouples growth from vessel replacement cycles and extends customer lifetime value. |
Research Methodology
The analysis maps material-grade tiers, design configurations, and end-user procurement patterns, each validated through procurement directors at Fortune 500 campuses, contract catering executives, and powder-coating formulation specialists. Primary interviews with sustainability officers, hospitality procurement managers, and vacuum-insulation equipment suppliers combined with secondary validation from EU ECHA SVHC candidate list updates, FDA food-contact substance registrations, and Chinese GB standard certification databases. Bottom-up vessel shipment estimates triangulated against top-down corporate sustainability spending disclosures.
Assumptions held fixed include EU Single-Use Plastics Directive enforcement timelines and nickel price bands within historical volatility ranges, while variables tested include biopolymer cost parity achievement and Extended Producer Responsibility scheme adoption rates across geographies. The projection framework models material type, design complexity, end-user application, and distribution channel dimensions across the analysis window. CAGRs derived from segment-level volume trajectories weighted by corporate procurement contract renewal cycles and hospitality EPR incentive diffusion curves.
Macroeconomic conditions sit as an overlay; deviation in nickel price spikes, REACH compliance cost escalation, or biopolymer substitution velocity would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Cross-checking against London Metal Exchange nickel futures and ECHA registration queue depth is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market