
 Water Bottle Racks Market | 2026-2036
Water Bottle Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Water Bottle Racks Market Analytics
Metal fabrication labor shortages across Gulf manufacturing zones is reorganizing supplier priorities for water bottle rack producers. Palletco Plastic Industries LLC leverages injection-molding scale to dominate Middle East plastic rack supply. Shandong Liyang Plastic Molding Co. Ltd. anchors East Asian export channels with cost-optimized medium-duty designs. Lista International specializes in premium metal configurations for European commercial kitchens.
Water bottle racks are structural storage systems engineered to hold standardized 5-gallon or 19-liter bottles, typically fabricated from powder-coated steel, high-density polyethylene, or laminated wood composites with load ratings between 75 and 200 kilograms. Their primary function spans warehouse staging, retail display, and point-of-use dispensing in offices and hospitality settings. Freestanding units occupy the largest volume share due to flexible placement in commercial backrooms and residential garages. Metal racks command premium positioning in industrial end-user segments where OSHA-compliant workplace storage mandates apply. Portable configurations represent the fastest-expanding category among outdoor recreation and event catering buyers.
Saudi Arabia's Saudi Standards, Metrology and Quality Organization (SASO) enforces product safety certification for imported metal and plastic storage goods, while EU REACH restricts hazardous substances in powder-coated finishes. The US Occupational Safety and Health Administration (OSHA) regulates rack load labeling and workplace placement to prevent bottle-tip hazards. Stakeholders must monitor evolving material compliance thresholds and workforce availability in fabrication hubs before committing capacity expansion.
Market Dynamics
Metal fabrication labor shortages across Gulf manufacturing zones are forcing water bottle rack producers to reorganize supplier priorities and accelerate automation investments in powder-coating and welding operations.
Growth Catalysts
- EU REACH compliance:Powder-coated steel racks meeting restricted substance thresholds command premium placement in European commercial kitchens and foodservice operations.
- Quick-service restaurant expansion:Bottled water storage infrastructure rollouts across Saudi Arabia and UAE catering facilities are pulling rack demand upward.
- High-density polyethylene injection molding:Cost-optimized plastic rack production is capturing residential and light-commercial segments previously served by laminated wood composites.
Market Restraints
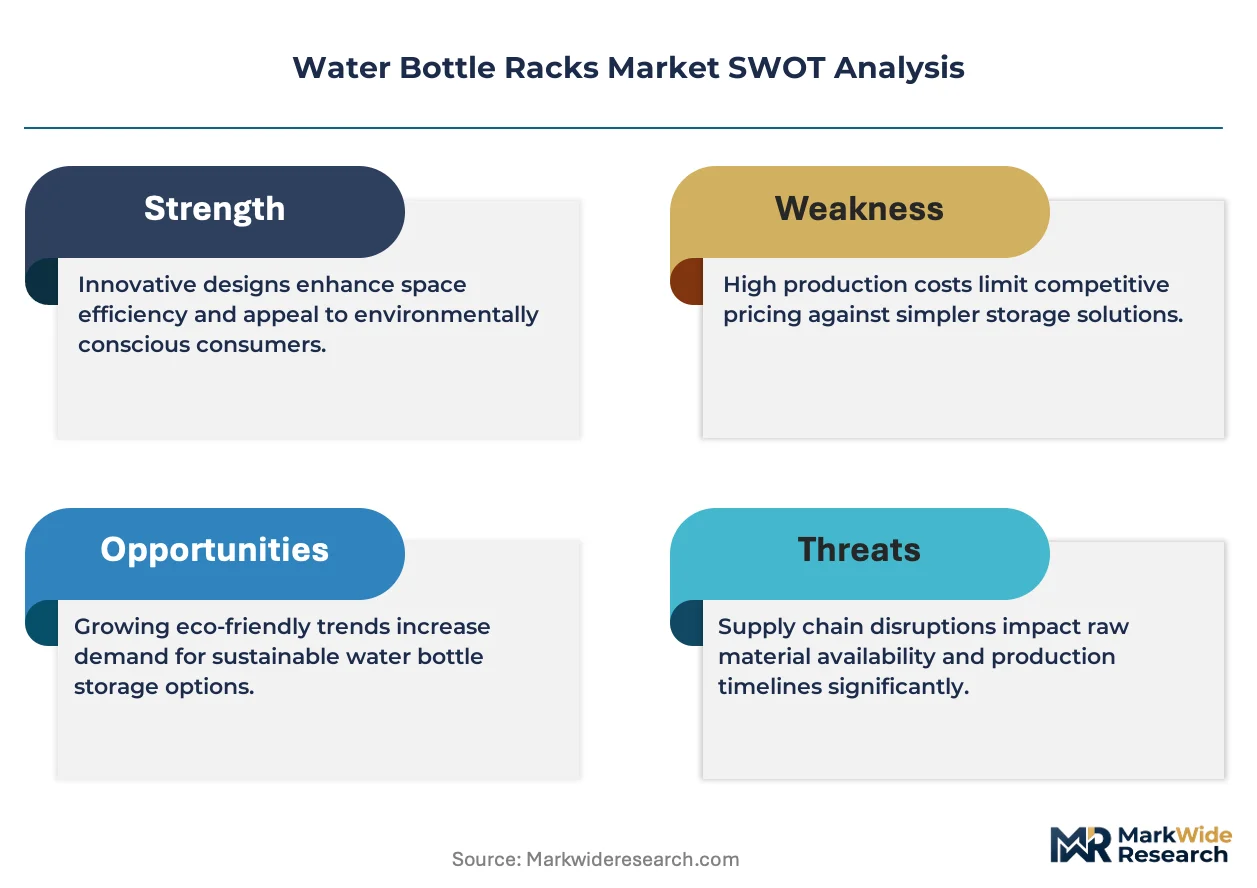
- Steel price volatility:Input cost swings for cold-rolled coil disrupt fabrication margins and destabilize long-term contracting with institutional buyers.
- Gulf supplier concentration:Heavy reliance on Saudi and UAE metalworking clusters creates vulnerability to workforce mobility restrictions and visa policy shifts.
- Substitute hydration systems:Point-of-use filtration and plumbed-in dispensers erode addressable demand for 5-gallon bottle storage in office settings.
Strategic Opportunities
- Outdoor recreation penetration:Portable collapsible rack designs for camping and event catering remain underdeveloped relative to fixed-installation products.
- US OSHA workplace mandates:Load-labeling and tip-prevention requirements for industrial storage are creating specification-driven upgrade cycles.
- Modular IoT integration:Weight-sensing racks connected to inventory management systems represent convergence of physical storage and digital supply chain visibility.
Industry Challenges
- Welding certification timelines:Gulf fabricators face extended approval periods for SASO-compliant metal rack production, delaying export readiness.
- Legacy warehouse integration:New rack specifications often conflict with existing pallet racking footprints in foodservice distribution centers, requiring custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Bottle Racks Market |
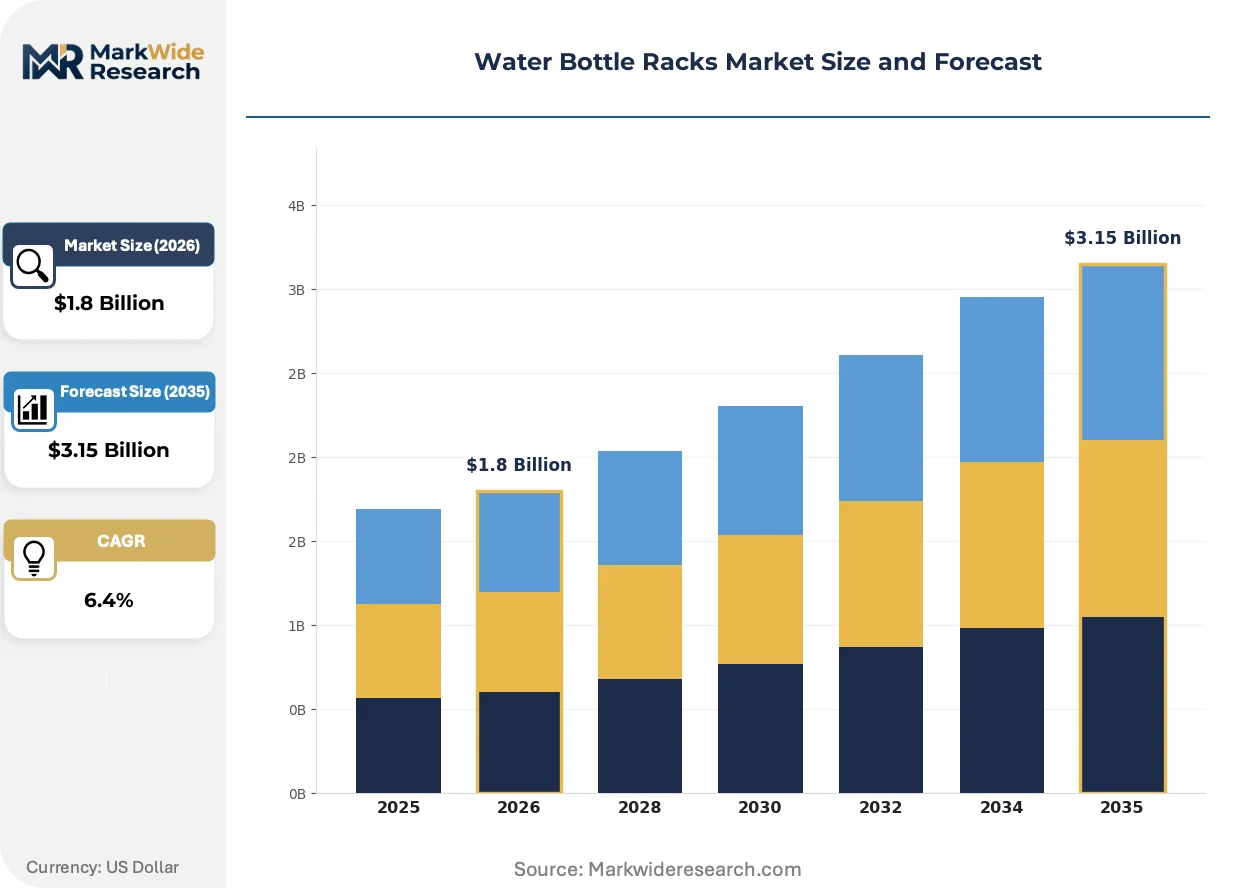
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Freestanding, Portable, Countertop Material: Metal, Plastic, Wood, Glass End User: Residential, Commercial, Outdoor, Industrial Size: Small, Medium, Large, Custom |
| Companies Covered | Coca-Cola Bottling Company of Saudi Arabia, Palletco Plastic Industries LLC, Lista International, Power Rack, Bahrain Water Bottling and Beverages Company S.P.C., ALSAMAANI Group, The Water Delivery Company, Shandong Liyang Plastic Molding Co. Ltd., Cixi Best Electrical Appliance Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Bottle Racks Market Evolving Landscape
Active transformation in water bottle rack production centers on material substitution, regulatory compliance automation, and buyer procurement recalibration across commercial and industrial segments.
Modular aluminum extrusion systems are decomposing traditional welded steel rack architectures in premium commercial installations. Boutique hotels and high-end catering operators across Germany and France are specifying these lightweight configurations for front-of-house visibility. The shift is compressing order-to-delivery timelines and reducing freight costs for export-oriented manufacturers.
EU REACH substance restrictions on hexavalent chromium in powder-coated finishes are compelling coating houses to migrate to trivalent chromium and ceramic-based alternatives. Industrial rack buyers in the Netherlands and Belgium now require third-party compliance documentation before contract execution. Metal fabricators with in-house electrocoating lines are capturing specification preference from outsourced coating dependent competitors.
Consolidated procurement by multinational foodservice operators is compressing supplier panels and demanding multi-year total-cost-of-ownership contracts rather than unit-price purchasing. Quick-service restaurant chains in Saudi Arabia are centralizing bottled water storage equipment buying through regional headquarters in Riyadh. This concentration is marginalizing smaller fabrication shops unable to meet bonded inventory and service-level agreement requirements.
Water Bottle Racks Market Segmentation
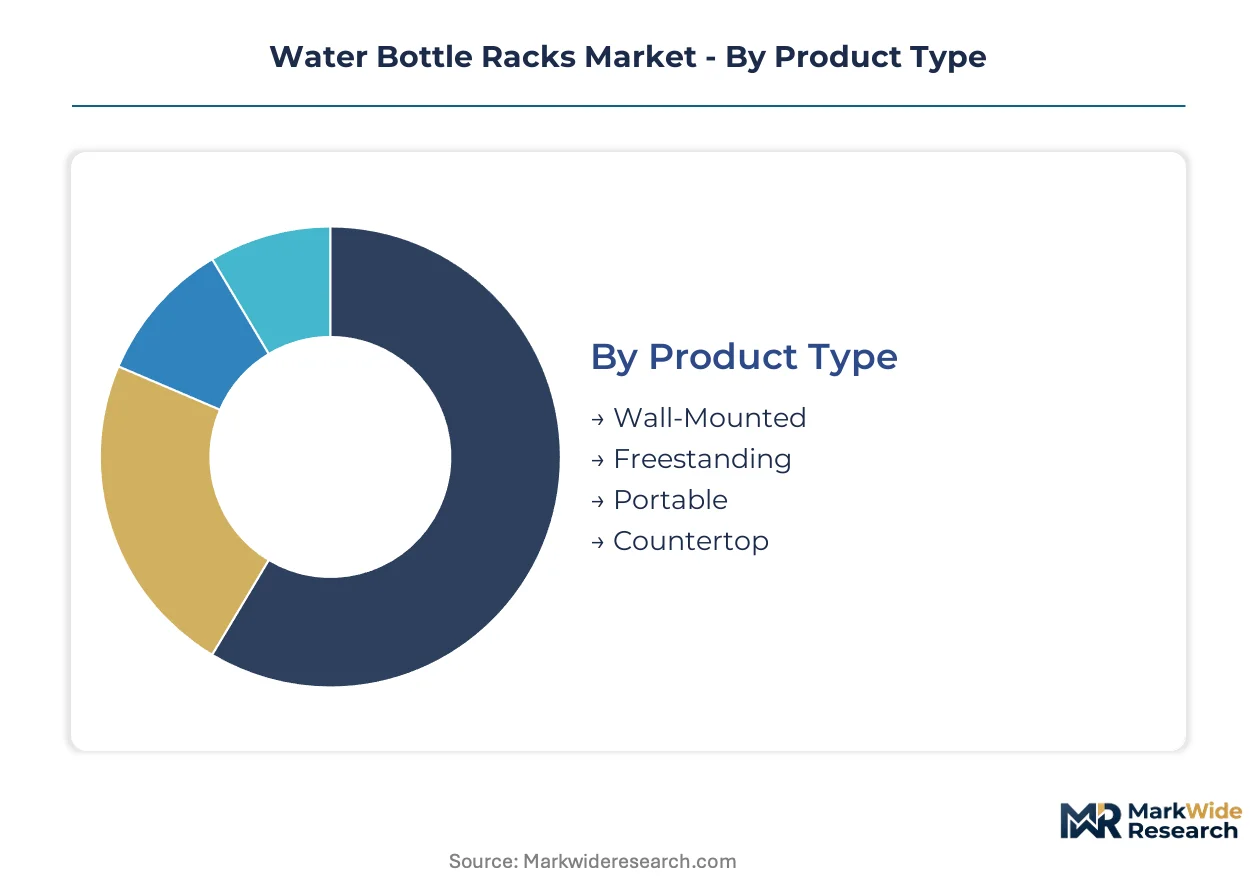
Water bottle rack procurement patterns diverge sharply across installation context, material specification, and operational intensity. Buyers select configurations based on load permanence, regulatory exposure, and total cost of ownership rather than unit price alone.
Product Type:
Margin pools concentrate in permanent-installation categories where engineering certification and workplace safety compliance justify premium positioning.
- Wall-Mounted:Steel bracket systems with reinforced anchor points dominate commercial kitchens and foodservice backrooms where floor space constraints apply. Demand clusters in Saudi Arabia's quick-service restaurant expansion, driven by SASO certification requirements for fixed-load storage.
- Freestanding:Four-post welded frames with adjustable shelving accommodate variable bottle counts across warehouse staging and retail environments. European commercial buyers specify these for EU REACH-compliant powder-coated finishes in high-visibility hospitality settings.
- Portable:Collapsible aluminum or polymer designs serve outdoor recreation and event catering segments with seasonal demand spikes. These configurations prioritize freight efficiency over load capacity.
- Countertop:Compact single or dual-bottle holders occupy residential and small-office point-of-use applications with minimal footprint requirements.
The dominant share belongs to Freestanding, while Portable is gaining share fastest among non-traditional buyer segments.
Material:
Cost tier stratification separates industrial-specification metals from consumer-grade alternatives, with fabrication labor availability reshaping competitive economics.
- Metal:Cold-rolled steel with electrocoated or powder-coated finishes commands industrial and commercial procurement where OSHA load-labeling mandates apply. Gulf fabricators face extended SASO welding certification timelines that constrain supply responsiveness.
- Plastic:High-density polyethylene injection-molding from Palletco Plastic Industries LLC and Shandong Liyang Plastic Molding Co. Ltd. captures residential and light-commercial volume with cost-optimized medium-duty designs.
- Wood:Laminated composites retain niche positioning in residential decorative applications where aesthetic integration outweighs durability specifications.
- Glass:Tempered shelf systems with metal framing appear in premium hospitality front-of-house installations across Germany and France.
Metal retains the largest revenue footprint, though Plastic is expanding most quickly into segments previously served by wood composites.
End User:
Application intensity determines specification grade, with industrial buyers driving standardization and residential buyers prioritizing configurability.
- Residential:Garage, pantry, and home-office installations favor modular plastic or wood-composite racks with tool-free assembly. Volume concentrates in cost-optimized channels with minimal regulatory exposure.
- Commercial:Quick-service restaurants, catering facilities, and hospitality operations across Saudi Arabia and UAE anchor demand for SASO-certified metal storage infrastructure. Centralized procurement through Riyadh headquarters is compressing supplier panels.
- Outdoor:Camping, festival, and mobile event applications pull portable collapsible designs with weather-resistant finishes. This segment remains underdeveloped relative to fixed-installation alternatives.
- Industrial:Warehouse staging and manufacturing facilities require OSHA-compliant load-rated systems with tip-prevention engineering. Third-party certification documentation is now mandatory for contract execution.
Commercial holds the dominant position, while Outdoor shows the steepest expansion trajectory as event catering infrastructure professionalizes.
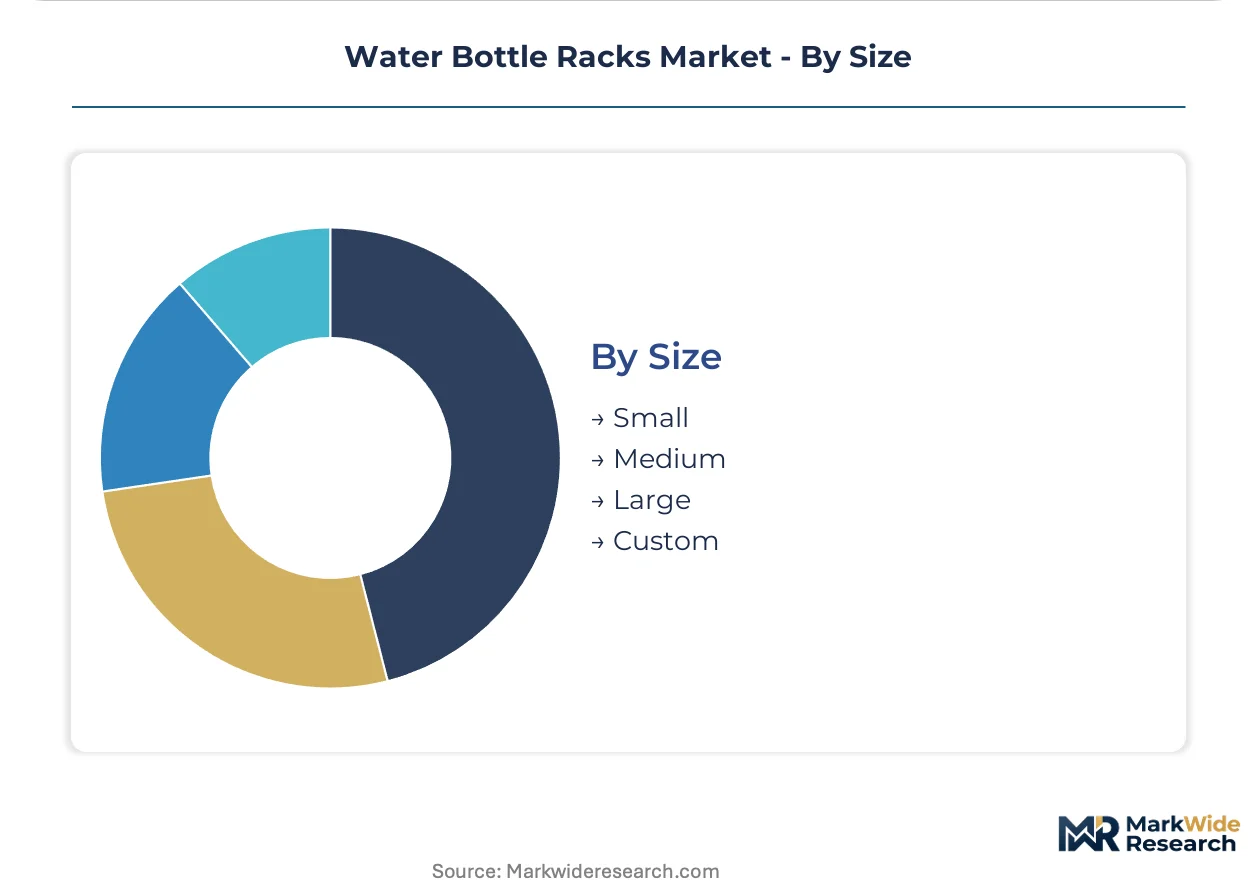
Size:
Volume scale aligns with buyer procurement sophistication, with large-format racks tied to multi-year service agreements and custom work requiring engineering engagement.
- Small:Single-tier countertop and under-sink configurations serve residential and micro-office deployments with minimal capital commitment.
- Medium:Three to six-bottle freestanding units balance footprint efficiency with replenishment cycle optimization across commercial backrooms.
- Large:High-capacity warehouse staging systems with pallet-compatible footprints serve distribution centers and bottling facilities with integrated inventory management requirements.
- Custom:Engineered-to-order configurations resolve legacy warehouse integration conflicts where new rack specifications conflict with existing pallet racking footprints.
Medium captures the greatest unit volume, while Custom commands the highest margin per installation due to engineering service attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO certification requirements in Saudi Arabia are establishing the regulatory baseline for metal and plastic storage goods across Gulf import markets. Fabrication clusters in the Eastern Province and Riyadh are scaling powder-coating capacity to meet European REACH-aligned substance thresholds for export-bound production.
United States
OSHA workplace safety mandates for load-rated storage systems are driving specification upgrades in warehouse and foodservice distribution networks. The agency's tip-prevention regulations for industrial bottle storage require third-party engineering documentation. Fabrication activity concentrates in Ohio and Pennsylvania steelworking corridors where cold-rolled coil processing feeds rack assembly lines.
Germany
EU REACH restrictions on hexavalent chromium in powder-coated finishes are compelling coating houses toward trivalent chromium and ceramic-based alternatives. ECHA substance database updates now require pre-contract compliance verification for commercial kitchen installations. Industrial metalworking clusters in North Rhine-Westphalia are integrating in-house electrocoating lines to capture specification preference from outsourced competitors.
Saudi Arabia
Quick-service restaurant expansion by Coca-Cola Bottling Company of Saudi Arabia and ALSAMAANI Group is pulling bottled water storage infrastructure demand upward. SASO welding certification timelines for metal rack production are extending export readiness periods for Gulf fabricators. Riyadh headquarters operations are centralizing procurement panels and compressing supplier relationships around bonded inventory capabilities.
China
Cost-optimized high-density polyethylene injection molding from Shandong-based producers is capturing residential and light-commercial segments previously served by laminated wood composites. GB standards for plastic storage goods are elevating material grade requirements for export-bound production. Manufacturing concentration in Shandong Province anchors East Asian export channels with medium-duty rack designs.
United Arab Emirates
Catering facility buildouts across Dubai and Abu Dhabi are generating demand for SASO-certified metal storage infrastructure aligned with Saudi import standards. MOHAP product safety guidelines for commercial foodservice equipment are converging with Gulf technical regulations. Fabrication activity in Jebel Ali industrial zones is scaling to serve regional distribution networks.
Water Bottle Racks Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in water bottle rack supply. The upper tier combines in-house metal fabrication with captive coating operations to meet REACH and OSHA documentation requirements. The specialist layer fragments across injection-molded plastic producers and regional metalworking shops. Two strategic archetypes dominate: scale-driven polymer molders serving cost-sensitive residential segments, and certification-focused metal fabricators capturing commercial and industrial procurement. Competitive moves center on automation investments in welding and powder-coating operations, plus geographic expansion through bonded inventory partnerships in Gulf distribution hubs.
Among Gulf-based metal fabricators, ALSAMAANI Group exemplifies the integrated certification-focused archetype. Palletco Plastic Industries LLC and Shandong Liyang Plastic Molding Co. Ltd. represent the scale-driven polymer molding tier, with the former leveraging UAE regional positioning and the latter anchoring East Asian export channels. Lista International occupies a position within the premium metal configuration segment for European commercial kitchen specifications. These three company structures illustrate the geographic and material bifurcation shaping supplier selection criteria across regulatory environments.
| Leading Market Players |
|---|
| Coca-Cola Bottling Company of Saudi Arabia |
| Palletco Plastic Industries LLC |
| Lista International |
| Power Rack |
| Bahrain Water Bottling and Beverages Company S.P.C. |
| ALSAMAANI Group |
| The Water Delivery Company |
| Shandong Liyang Plastic Molding Co. Ltd. |
| Cixi Best Electrical Appliance Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Multi-year total-cost-of-ownership contracts now dominate procurement between Gulf-based fabricators and Saudi quick-service restaurant chains, locking in bonded inventory commitments while insulating buyers from steel price volatility across the analysis window. This contract structure concentrates pricing power with integrated metalworking operations that can guarantee SASO-compliant welding certification and captive powder-coating capacity.
Pricing Analysis
Gulf-sourced metal racks command 15-25% premiums over Chinese polyethylene equivalents due to SASO certification overhead and REACH-aligned coating compliance. Three-tier pricing structure across premium certified-metal, standard commercial-grade, and economy plastic-residential levels stratifies buyer segments. Cost compression in economy tiers is intensifying because Shandong injection molders are scaling medium-duty production for residential export markets. Quick-service restaurant procurement through Riyadh headquarters shows lowest price sensitivity due to bonded inventory requirements, while residential garage buyers prioritize unit economics.
Supply Chain Analysis
Strategic stockpiling of cold-rolled coil and HDPE resin now prevails over just-in-timematerials management, as fabricators buffer against steel price swings and Gulf workforce mobility restrictions. Supply concentrates in Saudi Arabia's Eastern Province metalworking clusters, China's Shandong Province injection-molding corridors, and Germany's North Rhine-Westphalia electrocoating facilities. Production draws from cold-rolled steel coil, high-density polyethylene resin, and trivalent chromium coating chemistries. Single-source vulnerability in Gulf welding certification capacity creates export readiness bottlenecks. Distribution runs through bonded inventory partnerships anchored in Jebel Ali and Riyadh logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified welding labor and captive coating infrastructure constitute the binding constraints in this market, with Gulf fabricators facing 6-12 month SASO approval timelines that lock out smaller competitors from commercial procurement panels.
For Market Incumbents: Compound certification advantages by automating powder-coating lines and securing multi-year bonded inventory agreements with Riyadh-based quick-service restaurant headquarters. Vertical integration into trivalent chromium coating chemistry insulates margins from REACH compliance cost spikes. Defensive priority rests on welding certification throughput capacity as substitute hydration systems erode 5-gallon bottle storage demand in office segments. For New Entrants and Emerging Players: Anchor in portable collapsible rack designs for outdoor recreation and event catering, the most penetrable category where seasonal demand spikes and minimal regulatory exposure lower entry barriers. Target German boutique hotel specifications with modular aluminum extrusion systems that compress order-to-delivery timelines against welded steel competitors. Go-to-market angle: freight-efficient collapsible configurations for camping and festival infrastructure buyers. For Investors and Strategic Acquirers: Gulf-based integrated fabricators with captive electrocoating lines and established SASO welding certification represent the priority acquisition archetype for exposure to Saudi commercial foodservice expansion. Long-term viability hinges on automation capex cycles and regulatory compliance automation rather than commodity metalworking scale. Signal to watch: IoT-enabled weight-sensing rack adoption rates crossing 10% penetration in warehouse staging applications.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Investment in Welding Operations | SASO certification timelines compress from 12 months to 6 months for compliant Gulf fabricators. |
| Captive Electrocoating Line Installation | REACH-compliant trivalent chromium migration captures specification preference from outsourced coating competitors in Germany. |
| Modular IoT Integration Development | Weight-sensing racks connected to inventory management systems converge physical storage with digital supply chain visibility. |
| Bonded Inventory Partnership Expansion | Jebel Ali and Riyadh logistics hubs enable multi-year service agreements with centralized quick-service restaurant procurement. |
| Portable Collapsible Design Engineering | Aluminum extrusion systems reduce freight costs for outdoor recreation and event catering buyers across Germany and France. |
Research Methodology
Initial hypotheses were tested against primary input from metal fabrication plant managers, quick-service restaurant procurement directors, coating house technical leads, and commercial kitchen equipment distributors, then refined against SASO regulatory filings, EU ECHA substance database updates, US OSHA workplace safety guidance, customs trade data for steel and polyethylene imports, and SEC filings from diversified foodservice operators. Bottom-up unit economics from fabrication cost structures were triangulated against top-down market sizing from bottling facility capital expenditure disclosures.
Variance decomposition across product type, material specification, end-use intensity, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro drivers including quick-service restaurant expansion, outdoor recreation infrastructure investment, and workplace safety mandate adoption. Industry-specific forecast inputs incorporated welding certification capacity constraints and REACH substance restriction implementation timelines.
Decision-makers should treat outputs as directional under assumptions of stable Gulf workforce mobility policy and continued Saudi commercial foodservice expansion; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding steel price volatility bands and polyethylene resin supply continuity. Revision becomes warranted when substitute hydration system adoption in office settings crosses thresholds that materially compress 5-gallon bottle storage addressable demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Vending Cups Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Dual Chamber Bottles Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Ice Transport Buckets Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
US Beverage Packaging Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
US Soft Drinks Packaging Market