
 UAE Plastic Packaging Films Market | 2026-2036
UAE Plastic Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Plastic Packaging Films Market Insights
Food-grade specification upgrades is collapsing the gap between commodity polyethylene films and high-barrier alternatives. Taghleef Industries Group anchors the premium segment through biaxially oriented polypropylene capacity at its Dubai facility. UFlex Limited leverages backward integration into resin compounding to sustain margin control across stretch and shrink film lines. Amber Packaging Industries LLC dominates the industrial packaging channel through direct relationships with Jebel Ali logistics operators.
Plastic packaging films are thin, flexible polymer sheets engineered to thicknesses between 12 and 150 microns, manufactured via cast extrusion, blown film, or biaxial orientation processes to deliver moisture barriers, oxygen resistance, and mechanical protection for perishable and non-perishable goods. Barrier film commands the highest margin pool as pharmaceutical and fresh-protein applications demand multi-layer coextrusion with ethylene vinyl alcohol and polyamide cores. Stretch film leads volume throughput across Dubai's warehousing and e-commerce fulfillment infrastructure, while shrink film competes aggressively in beverage multipack collation. Polyethylene sustains raw-material cost advantages for high-volume industrial applications, though polypropylene gains ground in clarity-critical consumer goods segments.
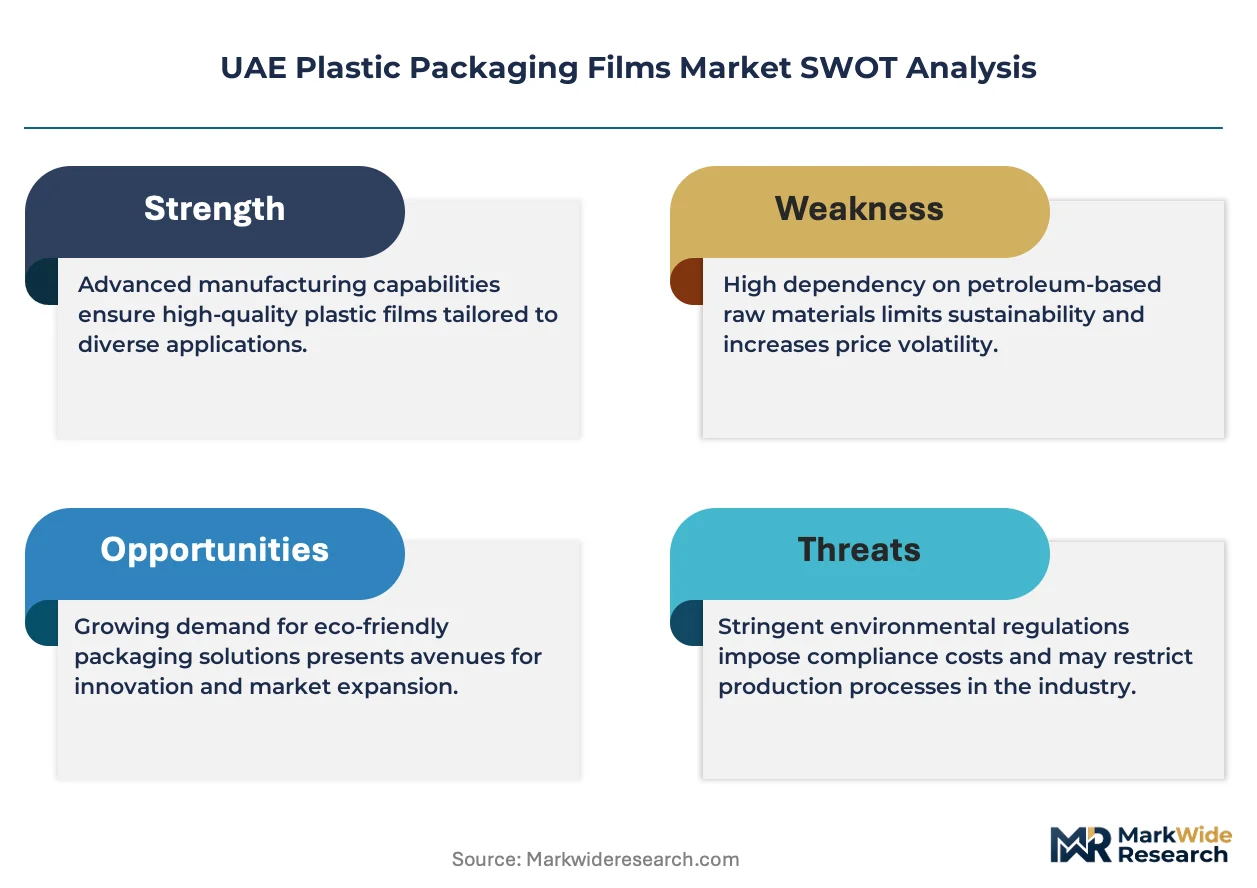
MOHAP enforces pharmaceutical packaging integrity standards that mandate track-and-trace-compatible barrier structures, while Emirates Authority for Standardization and Metrology governs food-contact compliance through migration limit testing aligned with Gulf Standardization Organization protocols. These frameworks elevate technical entry barriers for imported films and incentivize domestic conversion investment. Stakeholders must monitor Abu Dhabi's emerging restrictions on single-use plastics, as policy signals from the Environment Agency Abu Dhabi will determine whether mechanical recycling infrastructure or bio-based alternatives capture preferential regulatory treatment.
Market Dynamics
Food-grade specification upgrades are collapsing the gap between commodity polyethylene films and high-barrier alternatives, forcing conversion specialists to reengineer line configurations and resin sourcing strategies across Dubai's Jebel Ali industrial corridor.
Growth Catalysts
- MOHAP Pharmaceutical Serialization:Track-and-trace mandates for pharmaceutical packaging are accelerating demand for multi-layer barrier structures with ethylene vinyl alcohol cores.
- Gulf Retailer Private-Label Expansion:Food packaging applications are gaining momentum as regional retailers build captive-brand portfolios requiring customized film specifications.
- Free-Zone Conversion Incentives:Jebel Ali's tax and duty exemptions are attracting blown film and cast extrusion specialists to co-locate with logistics operators.
Market Restraints
- Resin Import Dependence:Polyethylene and polypropylene feedstock volatility ties margin stability to global petrochemical pricing cycles beyond local control.
- Barrier Film Technical Thresholds:Multi-layer coextrusion with polyamide cores demands capital-intensive metallization and orientation equipment that mid-scale converters cannot access.
- Single-Use Plastic Policy Uncertainty:Pending Environment Agency Abu Dhabi restrictions create investment hesitation around mechanical recycling versus bio-based alternative commitments.
Strategic Opportunities
- Abu Dhabi Circular Economy Infrastructure:Emerging recycling hubs in Khalifa Industrial Zone offer first-mover positioning for post-consumer film collection and reprocessing.
- Fresh-Protein Modified Atmosphere Packaging:Retail meat and seafood segments are adopting high-oxygen barrier structures that command premium positioning over standard polyethylene.
- E-Commerce Fulfillment Automation:Stretch film specifications for automated warehousing are shifting toward pre-stretched and machine-grade formulations.
Industry Challenges
- Coextrusion Technician Scarcity:Multi-layer line operation and die-gap optimization require specialized skills that regional technical institutes have not scaled to match demand.
- MOHAP Compliance Timeline Compression:Pharmaceutical barrier film certification cycles are compressing as serialization deadlines approach, straining converter quality assurance bandwidth.
- Legacy Equipment Retrofit Costs:Mono-layer blown film assets require substantial modification to achieve oxygen transmission rates demanded by fresh-protein applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Plastic Packaging Films Market |
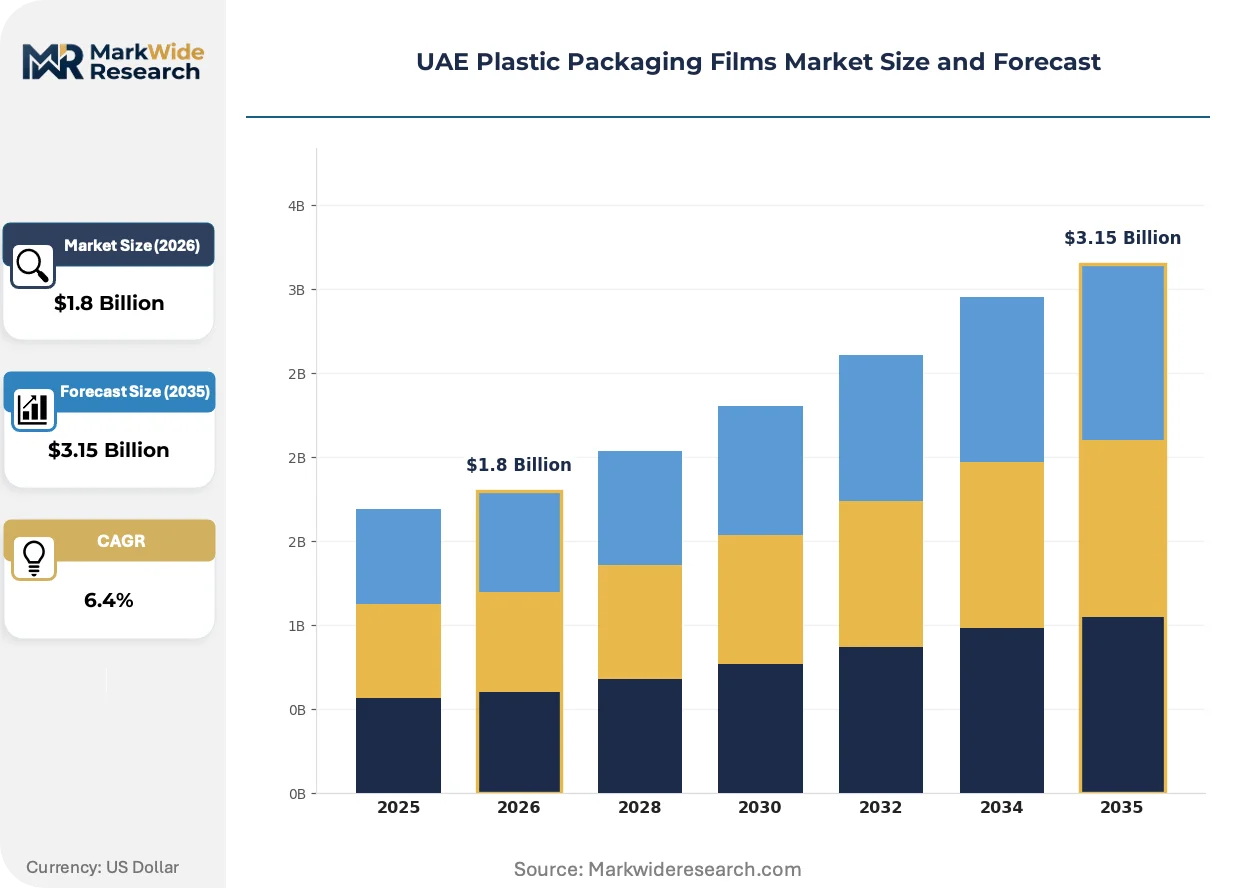
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Barrier Film, Rigid Film Application: Food Packaging, Pharmaceutical Packaging, Industrial Packaging, Consumer Goods Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others End User: Food & Beverage, Healthcare, Electronics, Personal Care |
| Companies Covered | Amber Packaging Industries LLC, Radiant Packaging Industry LLC, Taghleef Industries Group, UFlex Limited, Interplast, Aalmir Plastic Industries, ENPI Group, Falcon Pack, Emirates Printing Press LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Plastic Packaging Films Market Trends and Innovations
Barrier performance specifications are diverging sharply between pharmaceutical-grade multi-layer structures and industrial stretch films, creating technology investment forks that converters must navigate without overcommitting to either path.
Biaxially oriented polypropylene is supplanting cast polypropylene in clarity-critical consumer goods segments. Premium beverage and personal care brands are specifying BOPP for shelf appeal differentiation. This transition is compressing margins for commodity cast film converters who lack orientation capability.
MOHAP's tightening pharmaceutical packaging integrity standards are mandating track-and-trace-compatible barrier structures with embedded authentication features. Conversion specialists must integrate serialization-ready substrates into coextrusion lines. Fresh-protein and pharmaceutical end-uses are absorbing the steepest compliance cost increases.
Buyer concentration among Jebel Ali logistics operators is consolidating stretch film procurement under direct contract relationships with resin-integrated converters. Smaller distributors are losing shelf position to volume-backed suppliers with captive compounding operations. This pattern is most visible in Dubai's warehousing and cross-border fulfillment verticals.
UAE Plastic Packaging Films Market Segmentation
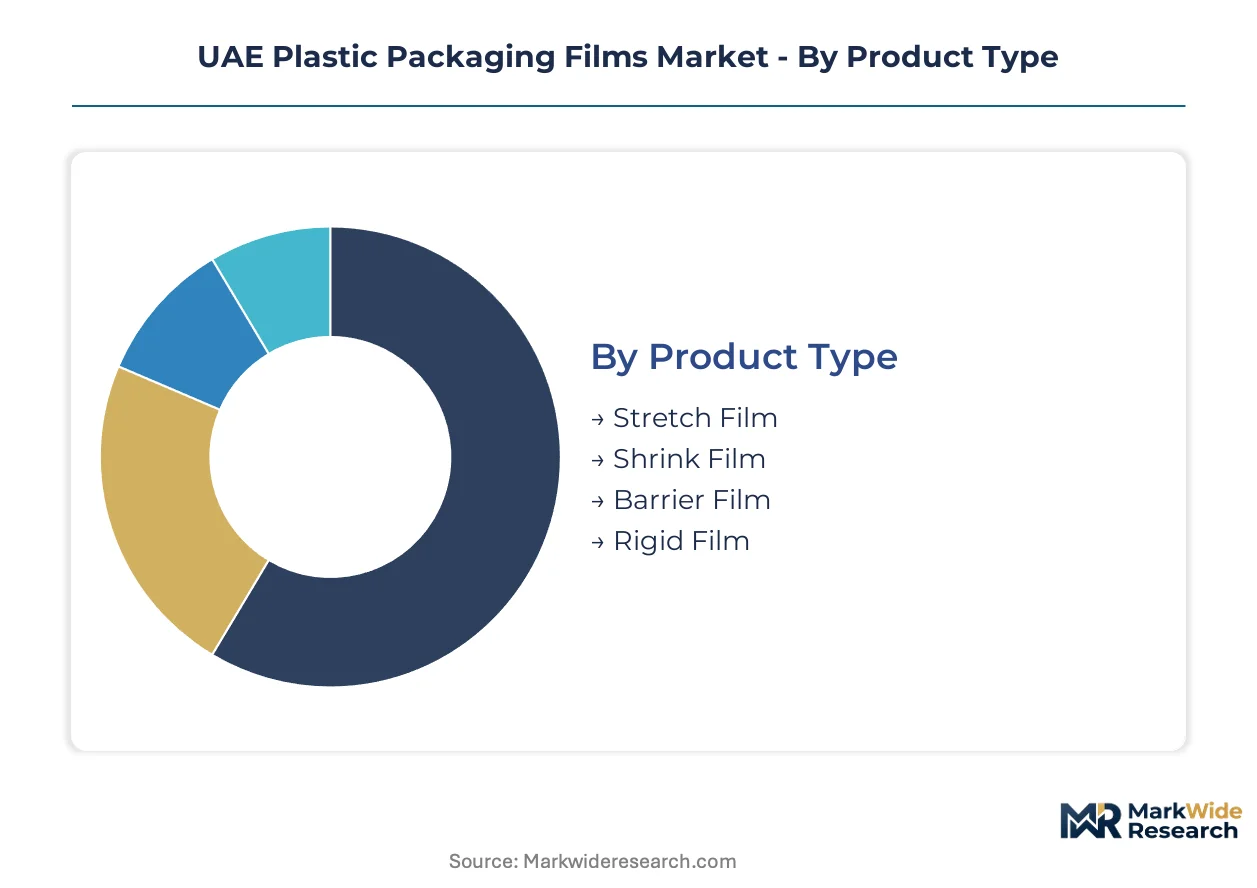
Segmentation in the UAE plastic packaging films market reveals how resin chemistry, barrier performance, and end-use compliance requirements create distinct competitive arenas. Each dimension carries different margin profiles and capital intensity thresholds that determine converter positioning.
Product Type:
Domestic demand concentrates in industrial films serving Jebel Ali logistics corridors, while barrier films increasingly serve GCC export pharmaceutical markets under MOHAP serialization mandates.
- Stretch Film:Linear low-density polyethylene formulations dominate Dubai's automated warehousing and cross-border fulfillment infrastructure. Machine-grade and pre-stretched variants are displacing hand-wrap specifications as e-commerce operators consolidate procurement under direct contracts with resin-integrated suppliers.
- Barrier Film:Multi-layer coextrusion structures with ethylene vinyl alcohol and polyamide cores command premium positioning. Pharmaceutical and fresh-protein applications in Abu Dhabi and Dubai are absorbing compliance cost increases from MOHAP track-and-trace mandates and extended shelf-life requirements.
- Shrink Film:Polyethylene-based formulations serve beverage multipack collation for regional bottlers.
- Rigid Film:Thermoformable polystyrene and PET structures target deli and dairy tray applications.
Stretch film holds the largest share; momentum sits with barrier film as pharmaceutical serialization deadlines compress certification cycles.
Application:
Cost tier stratification separates commodity food wraps from pharmaceutical-grade barrier structures requiring metallization and orientation capability.
- Food Packaging:Modified atmosphere packaging for fresh protein is shifting from standard polyethylene toward high-oxygen barrier structures. Retailers expanding private-label portfolios in Dubai and Sharjah are specifying customized film substrates that collapse the gap between commodity and premium grades.
- Pharmaceutical Packaging:MOHAP integrity standards mandate embedded authentication features and serialization-ready substrates. Multi-layer coextrusion lines in Dubai's free zones are retrofitting to achieve oxygen transmission rates below 0.1 cc/m²/day.
- Industrial Packaging:Pallet unitization and bulk goods protection dominate volume throughput.
- Consumer Goods:Clarity-critical segments are migrating from cast to biaxially oriented polypropylene.
Food packaging holds the largest share; pharmaceutical packaging is climbing the fastest as compliance deadlines reshape converter order books.
Material:
Volume concentration favors polyethylene for industrial applications, while polypropylene gains ground in clarity-critical consumer segments requiring biaxial orientation.
- Polyethylene:Linear low-density and metallocene grades sustain raw-material cost advantages for high-volume stretch and shrink applications. Jebel Ali converters leverage backward integration into resin compounding to control margin volatility from global petrochemical pricing cycles.
- Polypropylene:Biaxially oriented variants are supplanting cast film in premium beverage and personal care packaging. Taghleef Industries' Dubai orientation line anchors domestic supply for GCC export markets.
- Polyvinyl Chloride:Medical blister packs and pharmaceutical forming applications retain niche demand.
- Others:Bio-based alternatives and recycled content films await regulatory clarity from Environment Agency Abu Dhabi.
Polyethylene holds the largest share; polypropylene is gaining share fastest as brand owners specify clarity differentiation.
End User:
Customer type concentration among Jebel Ali logistics operators and Gulf retail chains is consolidating procurement under direct contract relationships.
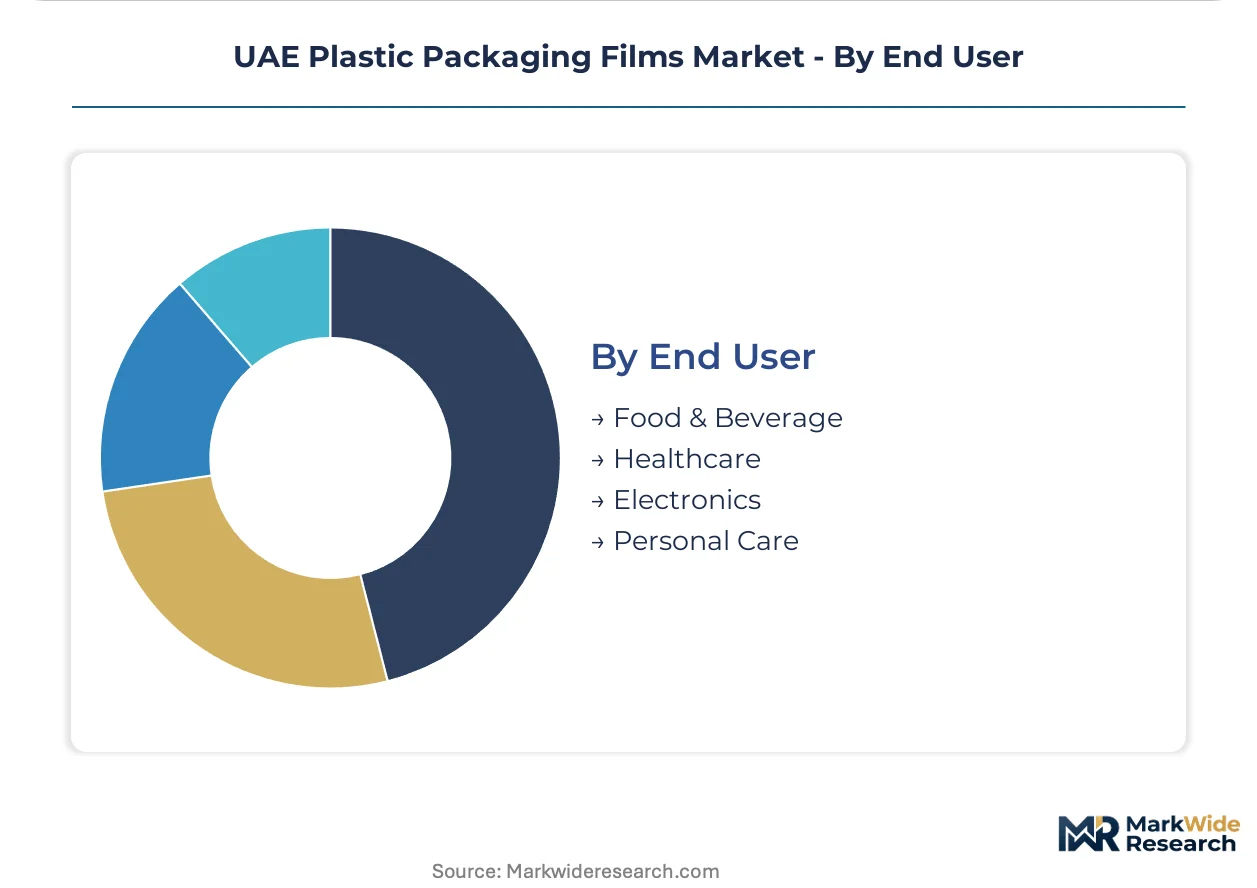
- Food & Beverage:Private-label expansion by regional retailers is accelerating specification upgrades. Fresh-protein segments in Abu Dhabi and Dubai are adopting high-barrier structures that command premium positioning over commodity polyethylene.
- Healthcare:MOHAP serialization mandates are reshaping barrier film procurement toward track-and-trace-compatible multi-layer structures. Domestic conversion investment is rising as imported films face elevated technical entry barriers.
- Electronics:Anti-static and moisture-barrier films serve semiconductor and component packaging.
- Personal Care:Clarity and printability requirements favor biaxially oriented polypropylene.
Food & Beverage holds the largest share; Healthcare is expanding most quickly as pharmaceutical compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE plastic packaging films market functions as a GCC export hub with substantial re-export flows to Saudi Arabia, Oman, and Kuwait. Domestic conversion capacity outpaces local consumption, positioning Jebel Ali operators as regional suppliers.
Dubai
Jebel Ali Free Zone concentrates blown film and cast extrusion capacity serving GCC logistics corridors. MOHAP pharmaceutical serialization mandates are accelerating multi-layer barrier line investment among free-zone converters. Taghleef Industries operates biaxial orientation capacity here, supplying premium BOPP for beverage and personal care export markets.
Abu Dhabi
Khalifa Industrial Zone is emerging as a circular economy hub with post-consumer film collection and reprocessing infrastructure under development. The Environment Agency Abu Dhabi is signaling single-use plastic restrictions that will determine mechanical recycling versus bio-based investment flows. Barrier film demand from pharmaceutical manufacturing in KEZAD is climbing as MOHAP deadlines approach.
Sharjah
Industrial packaging converters serve northern emirates logistics and construction material sectors. Stretch film procurement is consolidating under direct contracts with resin-integrated suppliers. Saja'a Industrial Area hosts mid-scale blown film operations supplying standard polyethylene grades for pallet unitization.
Northern Emirates
Ras Al Khaimah and Fujairah industrial zones attract commodity film conversion with lower operating costs than Dubai or Abu Dhabi. These facilities primarily serve domestic construction and agriculture packaging demand. Export orientation remains limited due to logistics connectivity gaps versus Jebel Ali port access.
UAE Plastic Packaging Films Market Competitive Landscape
Listed leaders compete with private specialists across resin integration and barrier technology tiers. The vendor base fragments across three capability levels: resin-integrated multinationals, regional conversion specialists with captive compounding, and commodity distributors dependent on spot resin purchases. Two strategic archetypes dominate: backward-integrated players controlling margin volatility through in-house resin production, and technology-focused operators metallizing and orienting films for pharmaceutical and premium food applications. Competitive moves center on free-zone capacity expansion and coextrusion line retrofit partnerships with European equipment suppliers.
Within the resin-integrated tier, UFlex Limited exemplifies backward integration into compounding that sustains margin control across high-volume stretch and shrink lines. Taghleef Industries Group anchors premium positioning through biaxial orientation capability. Amber Packaging Industries LLC occupies the industrial packaging channel through direct relationships with Jebel Ali logistics operators.
| Leading Market Players |
|---|
| Amber Packaging Industries LLC |
| Radiant Packaging Industry LLC |
| Taghleef Industries Group |
| UFlex Limited |
| Interplast |
| Aalmir Plastic Industries |
| ENPI Group |
| Falcon Pack |
| Emirates Printing Press LLC |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Jebel Ali converters and Gulf petrochemical suppliers lock in resin access and price visibility across 12-18 month windows, insulating domestic film producers from spot polyethylene volatility while tethering margin stability to regional feedstock pricing cycles.
Pricing Analysis
Industrial OEM buyers anchor volume-based contract structures that stratify across premium barrier grades, standard food-contact films, and economy industrial wraps. Price differentiation hinges on MOHAP certification tier and backward integration into captive compounding operations. Cost compression in commodity polyethylene tiers is intensifying as resin-integrated multinationals leverage scale advantages. Logistics operators in Dubai's free zones exhibit lowest price sensitivity due to operational criticality, while northern emirates construction distributors remain highly sensitive to per-kilogram fluctuations.
Supply Chain Analysis
Saudi Arabia and Qatar anchor regional polyethylene and polypropylene feedstock production, with specialty ethylene vinyl alcohol and polyamide resins drawing from South Korea and Germany. Raw material dependencies center on naphtha-derived ethylene, propylene monomer, and barrier-grade coextrusion adhesives. Single-source vulnerability concentrates in metallization equipment and multi-layer die systems sourced from European suppliers. Distribution runs through Jebel Ali port consolidation hubs serving GCC re-export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAE plastic packaging films represent an early-cycle expansion story as pharmaceutical serialization mandates and fresh-protein barrier upgrades drive specification migration from commodity polyethylene toward high-value coextrusion structures.
For Market Incumbents: Fortify barrier film certification pipelines ahead of MOHAP deadline compression, prioritizing multi-layer line retrofits in Jebel Ali free zones. Deepen upstream control over resin compounding to defend margin position against feedstock volatility. Channel control through direct logistics operator relationships remains critical as procurement consolidates under volume-backed suppliers. For New Entrants and Emerging Players: Differentiate on post-consumer recycled content capabilities as Environment Agency Abu Dhabi signals circular economy infrastructure support. Khalifa Industrial Zone recycling hubs offer white-space positioning for mechanical reprocessing specialists. Target fresh-protein modified atmosphere packaging segments where legacy equipment gaps create penetrable demand. For Investors and Strategic Acquirers: Capital is best deployed toward resin-integrated conversion specialists with pharmaceutical certification bandwidth and GCC export logistics access. Long-term viability over a 5-10 year horizon favors operators bridging barrier technology and circular economy compliance. Monitor MOHAP enforcement intensity as the inflection signal for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Coextrusion Line Retrofit | Enables MOHAP-compliant oxygen transmission rates below 0.1 cc/m²/day for pharmaceutical applications. |
| Backward Integration into Resin Compounding | Captive polyethylene production insulates margin volatility from Saudi Aramco pricing cycles. |
| Free-Zone Capacity Expansion | Jebel Ali tax exemptions attract blown film specialists co-locating with logistics operators. |
| Post-Consumer Recycling Infrastructure | Khalifa Industrial Zone hubs position first-movers for Environment Agency Abu Dhabi policy alignment. |
| Fresh-Protein Barrier Film Certification | High-oxygen structures command premium positioning over commodity grades in Dubai retail channels. |
Research Methodology
Desk research of customs trade databases, MOHAP regulatory filings, and Gulf petrochemical export statistics preceded structured interviews with blown film plant managers, pharmaceutical packaging procurement leads, Jebel Ali logistics operators, and technical R&D directors at conversion specialists. Primary fieldwork with industry stakeholders combined with secondary validation against Emirates Authority for Standardization and Metrology protocols. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile volume estimates.
Variance decomposition across product type, application tier, material chemistry, and end-user concentration shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include barrier performance grade, resin integration level, and free-zone versus mainland production location. CAGRs were derived from elasticity-adjusted demand curves incorporating pharmaceutical serialization compliance timelines and fresh-protein retail expansion patterns.
Material uncertainties — MOHAP deadline acceleration, Environment Agency Abu Dhabi single-use plastic restrictions, and global polyethylene feedstock shocks — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and petrochemical supply chain stability. Recalibration cycles align with material shifts in pharmaceutical compliance intensity and circular economy infrastructure deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Japan Plastic Packaging Film Market
Poly film
Foamed Polypropylene Films Market
Poly film
Australia and New Zealand Plastic Packaging Film Market
Poly film
Global Polyethylene Packaging Market
Poly film
Global Thermoplastic Films Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Silicone-Coated PET Films Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
India Plastic Packaging Film Market
Poly film
Cast Stretch Packaging Films Market
Poly film
North America Plastic Film Packaging Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
PET Lidding Films Market
Poly film
Italy Plastic Packaging Films Market