
 Soft Drinks Packaging Market | 2026-2036
Soft Drinks Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Drinks Packaging Market Outlook
Recycled PET is realigning cost structures across the soft drinks packaging value chain as virgin resin volatility persists. Amcor plc leverages global film extrusion networks to secure recycled feedstock at scale. Ball Corporation anchors North American aluminum can supply through dedicated beverage partnerships. Crown Holdings competes on decorated metal packaging technology for premium carbonated brands.
Soft drinks packaging encompasses primary and secondary containment systems engineered to preserve carbonation, prevent light-induced degradation, and enable automated filling at speeds exceeding 1,000 units per minute. Barrier-coated paperboard cartons with aluminum foil laminates dominate ambient-stable juice and nectar segments where shelf life extension matters. Plastic bottles remain the volume leader across cola and flavored water applications, though aluminum cans capture share in on-premise and convenience channels where chill-speed and recyclability signal value. Pouches represent the fastest-expanding format in single-serve children's beverages and functional drink trials, with margin pools concentrating in spouted fitment design and high-definition flexographic printing.
US FDA food contact substance notifications and EPA recycled content guidelines shape material approval timelines for domestic producers, while EU REACH restrictions on bisphenol-based coatings redirect R&D spending toward polyester and acrylic alternatives. Stakeholders must monitor evolving extended producer responsibility frameworks in California and New York, where deposit-return expansion and post-consumer content minimums will determine which material-platform investments generate acceptable returns through the forecast horizon.
Market Dynamics
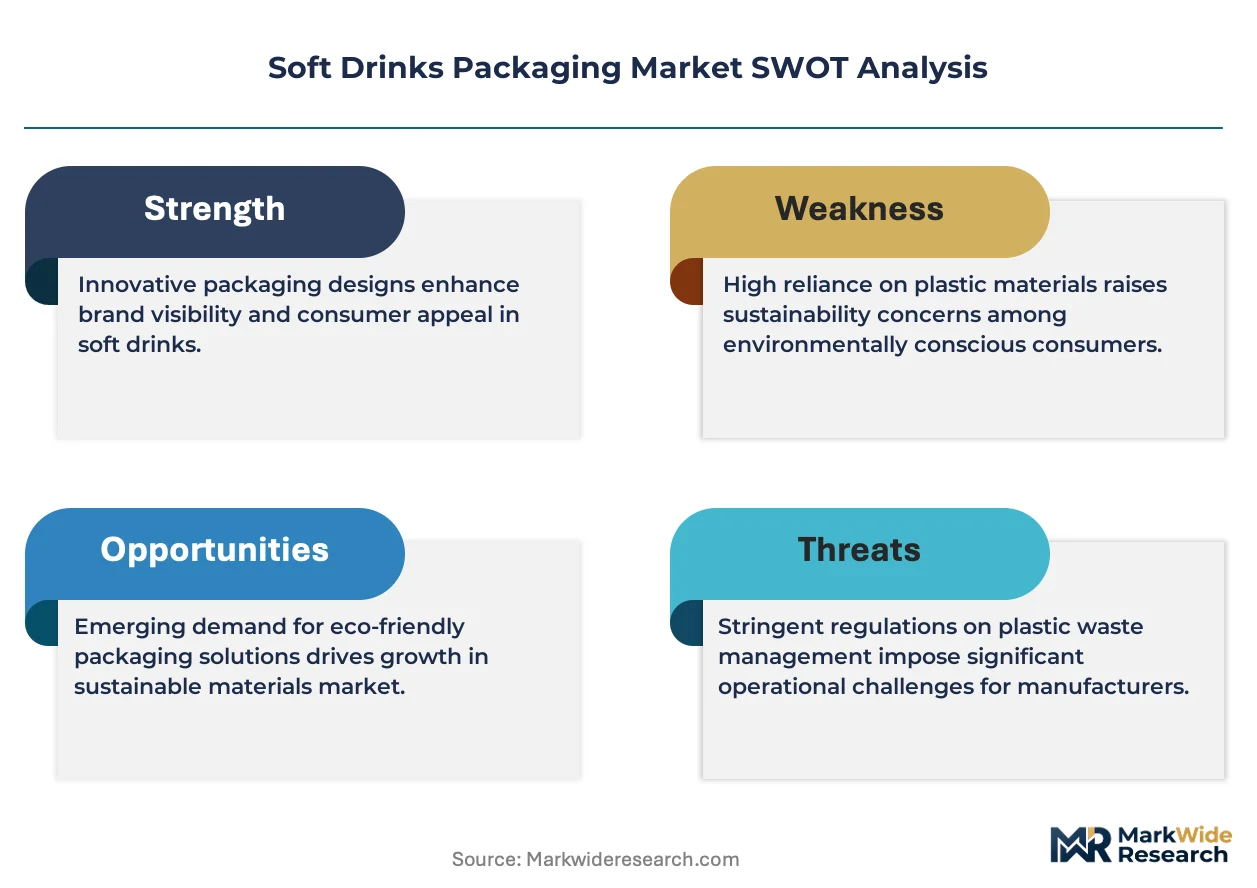
Recycled PET feedstock scarcity is compressing margin structures for carbonated beverage bottlers as EU Green Deal mandates tighten virgin plastic restrictions faster than collection infrastructure scales.
Growth Catalysts
- EU Green Deal packaging mandates:Binding recycled content minimums for PET bottles force format standardization that favors high-volume converters with secured rPET supply contracts.
- Aluminum can chill-speed performance:On-premise and convenience channels prioritize rapid cooling characteristics that metal formats deliver versus plastic alternatives in grab-and-go refrigeration.
- California deposit-return expansion:Post-consumer collection rate targets above 80 percent create localized feedstock pools that anchor West Coast rPET conversion investments.
Market Restraints
- rPET price volatility:Virgin resin fluctuations transmit directly to recycled feedstock premiums, squeezing converters without backward integration into collection or flake processing.
- Bisphenol coating phase-outs:EU REACH restrictions on epoxy-based internal linings force aluminum can makers into polyester and acrylic R&D cycles with unproven scale economics.
- Barrier-coated paperboard technical ceilings:Oxygen transmission rates in foil-laminated cartons limit shelf life extension for ambient-stable nectars beyond 12-month targets.
Strategic Opportunities
- Spouted pouch fitment innovation:Single-serve children's beverages and functional drink trials drive demand for high-definition flexographic printing and custom closure engineering.
- New York extended producer responsibility:Post-consumer content minimums and deposit-return expansion create first-mover advantages for converters with certified circular supply chains.
- Digital printing convergence with lightweighting:Direct-to-shape decoration eliminates label substrates while enabling SKU proliferation without plate-change downtime.
Industry Challenges
- High-speed filling line recalibration:PET bottle lightweighting below 8 grams threatens stability at speeds exceeding 1,000 units per minute, requiring gripper and conveyor reinvestment.
- Food contact substance notification timelines:US FDA approval cycles for novel barrier coatings extend 18-24 months, delaying commercialization of polyester-based can linings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Drinks Packaging Market |
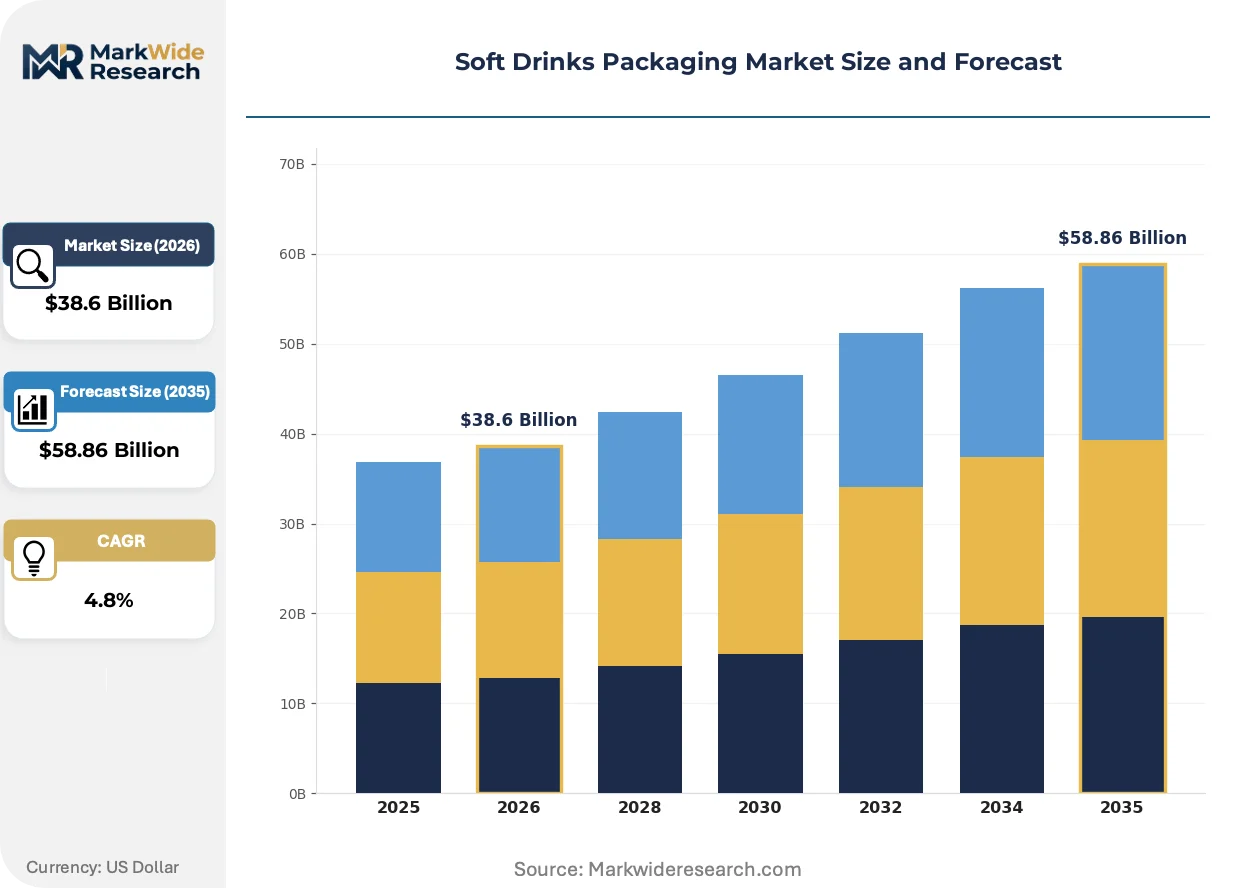
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Cans, Cartons, Pouches Material: Plastic, Glass, Aluminum, Paperboard Closure Type: Cap, Screw Cap, Snap-On Lid, Tetra Pak End User: Retail, Food Service, Vending, Online Sales |
| Companies Covered | Tetra Pak Group, Berry Global Group, Amcor plc, Toyo Seikan Group Holdings, Owens-Illinois, Ball Corporation, Ardagh Group, Silgan Holdings, Crown Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Drinks Packaging Market Strategic Shifts
Material-platform competition between aluminum, rPET, and fiber-based formats is forcing packaging engineers to optimize for carbon intensity metrics alongside unit economics and line efficiency.
Digital printing is overtaking conventional rotogravure for short-run promotional SKUs in flavored waters and energy drinks. Mid-sized bottlers in Germany and the Netherlands adopt direct-to-shape inkjet to support retailer-specific seasonal programs without minimum order constraints. This shift is overtaking the historical volume advantages of offset label production for runs below 50,000 units.
EU F-Gas Regulation phase-down schedules are accelerating hydrocarbon and CO2 propellant conversions in aerosolized beverage dispensers. Can makers face retrofit costs for crimping equipment compatibility while reformulating internal coatings for new pressure profiles. Carbonated soft drink brands with European manufacturing footprints absorb compliance costs fastest, while import-dependent bottlers delay capital commitments.
Retail channel consolidation in the United States concentrates procurement authority among three national grocery distributors. Bulk-format palletization and private-label co-packing contracts now dominate volume allocation discussions, displacing fragmented regional distributor networks. Beverage brand owners in the Southeast and Midwest restructure sales organizations to manage direct retailer relationships formerly handled by independent brokers.
Soft Drinks Packaging Market Segmentation
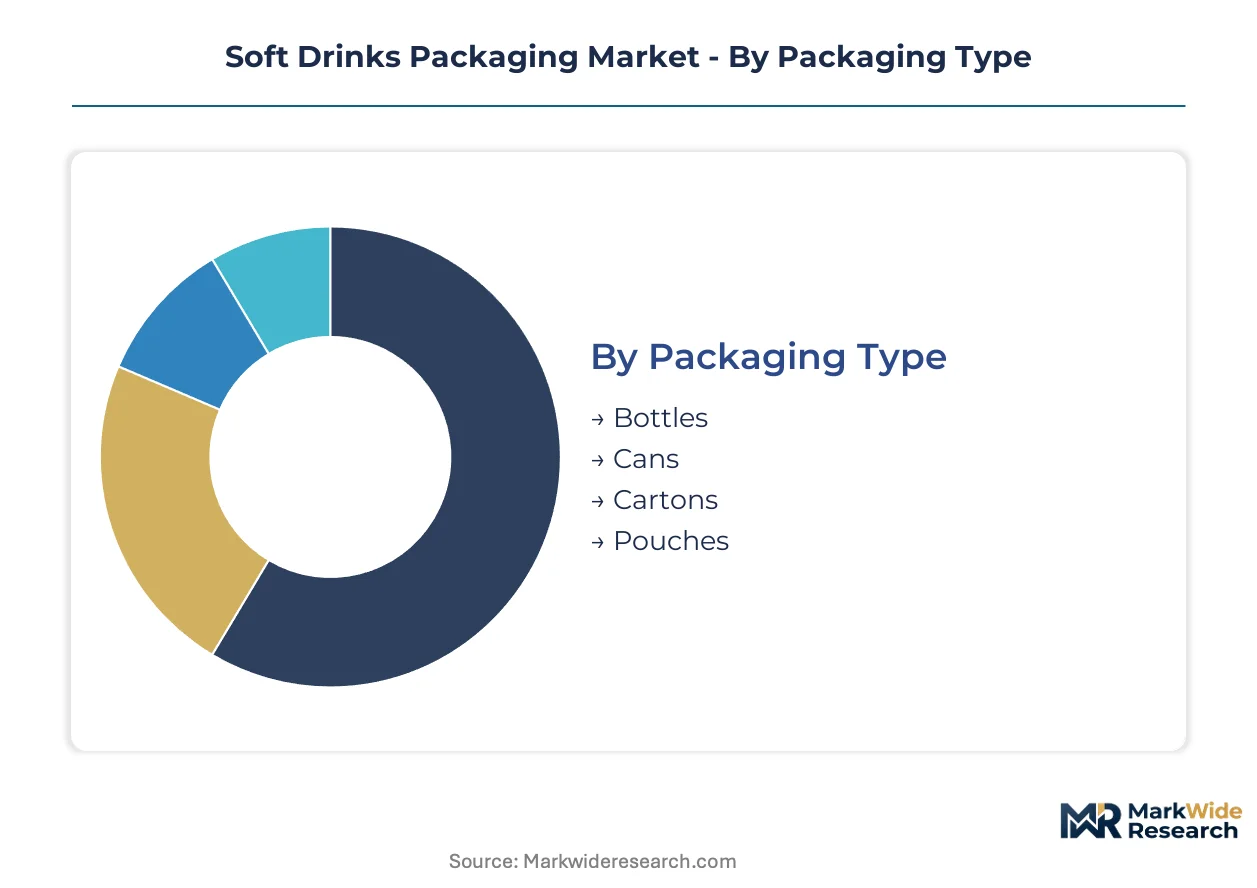
Packaging format selection determines filling line capital requirements, carbonation retention performance, and compliance pathways under divergent regulatory regimes. Material-platform choices lock in decade-long supply contracts and recycling infrastructure partnerships that resist rapid switching.
Packaging Type:
Capital intensity peaks with aluminum can lines requiring dedicated bodymakers and decorators, while pouch systems demand precision fitment welding equipment.
- Bottles:PET blow-molding dominates cola and flavored water volumes, with lightweighting below 8 grams requiring gripper reinvestment for stability at high-speed filling. Demand concentrates in the United States where retail consolidation drives bulk-format procurement and rPET integration timelines.
- Cans:Two-piece aluminum construction delivers superior chill-speed performance for on-premise and convenience channels. Ball Corporation anchors North American supply through dedicated beverage partnerships, though EU REACH bisphenol phase-outs force coating R&D cycles with unproven scale economics.
- Cartons:Barrier-coated paperboard with aluminum foil laminates serves ambient-stable juice segments where shelf life targets matter.
- Pouches:Spouted formats with high-definition flexographic printing dominate single-serve children's beverages and functional drink trials.
Most installed capacity flows through bottles. Expansion is steepest in pouches.
Material:
Feedstock security and regulatory approval timelines differentiate investment risk profiles across material platforms.
- Plastic:Virgin PET and recycled flake formats face EU Green Deal recycled content mandates tightening faster than collection infrastructure scales. Amcor plc leverages global film extrusion networks to secure rPET feedstock at scale.
- Glass:Returnable bottle systems retain share in premium mineral water and traditional cola markets where refill economics justify higher logistics costs.
- Aluminum:Primary and recycled sheet supply concentrates among integrated smelters with renewable energy offtake agreements.
- Paperboard:Foil-laminated carton oxygen transmission rates limit shelf life extension for ambient nectars beyond 12-month targets.
Plastic commands the largest installed base. Aluminum is climbing the fastest on recyclability positioning.
Closure Type:
Engineering complexity and tamper-evidence requirements drive tooling differentiation and line changeover economics.
- Cap:Standard 28mm PCO finishes dominate carbonated soft drinks with established capping head compatibility across filler platforms.
- Screw Cap:Precision thread engagement supports resealability for multi-serve juice and functional beverages.
- Snap-On Lid:Polypropylene fitments enable single-hand opening for on-the-go consumption formats.
- Tetra Pak:Proprietary aseptic closure systems integrate with laminated carton filling equipment for ambient distribution.
Cap closures carry the heaviest installed base. Screw cap formats are gaining share fastest in premium positioning.
End User:
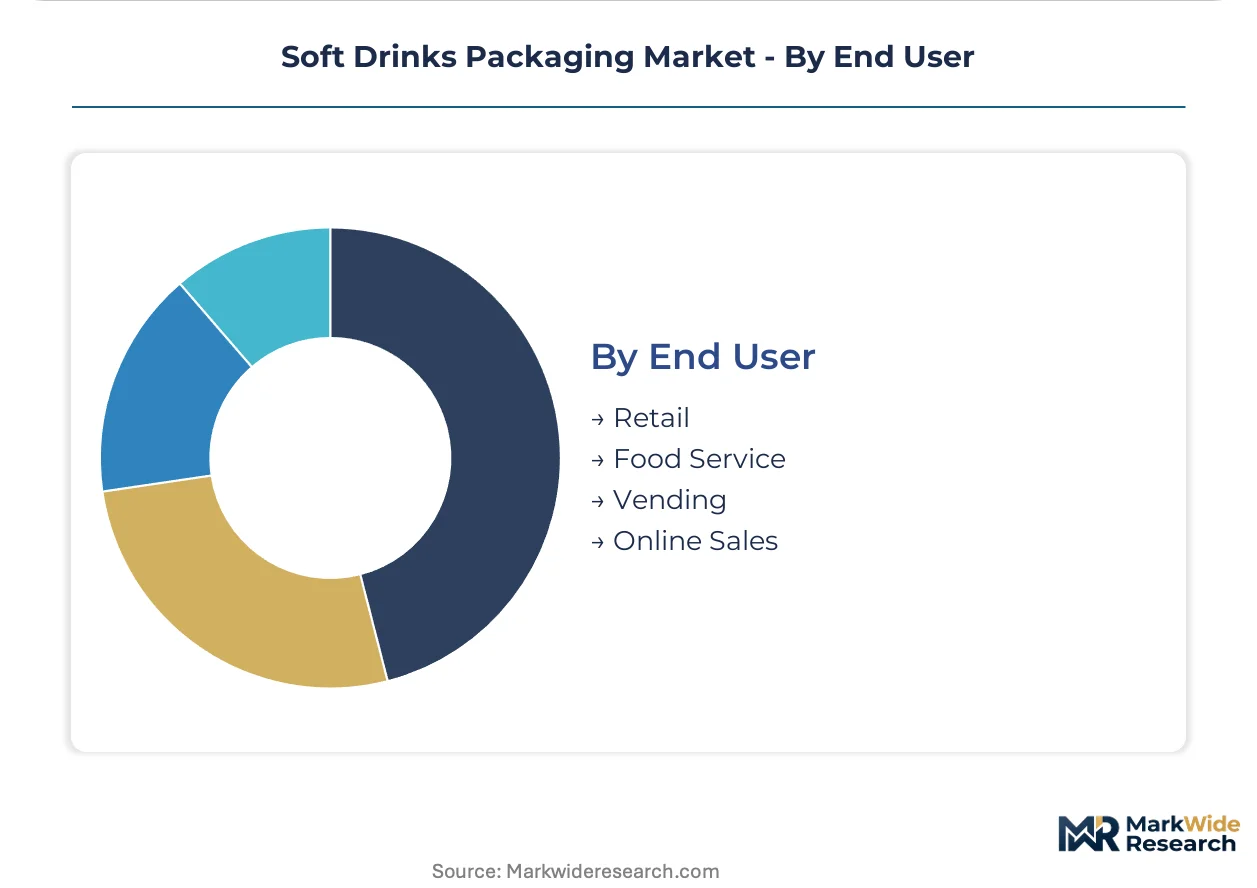
Channel-specific packaging requirements shape palletization standards, label decoration, and temperature-controlled logistics investment.
- Retail:Multi-pack bundling and shelf-ready display cases dominate procurement specifications for national grocery distributors. Three US grocery networks now concentrate volume allocation authority, displacing fragmented regional broker structures.
- Food Service:Fountain syrup systems and post-mix equipment reduce packaging per serving but require dedicated dispenser infrastructure.
- Vending:Drop-test durability and condensation management drive can preference over bottle formats in ambient machine placement.
- Online Sales:E-commerce-ready secondary packaging with damage-resistant dunnage addresses last-mile handling stress.
Retail absorbs most packaging volume. Online sales is expanding most quickly on direct-to-consumer trial formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European converter capacity for beverage packaging, with rPET flake processing clusters concentrated around Düsseldorf and Cologne responding to EU Green Deal mandates.
United States
Retail channel consolidation among three national grocery distributors drives bulk-format palletization standards and private-label co-packing contracts. EPA recycled content guidelines shape material approval timelines for domestic producers. Southeast and Midwest beverage brand owners restructure sales organizations to manage direct retailer relationships formerly handled by independent brokers.
Germany
Mid-sized bottlers adopt direct-to-shape inkjet printing for retailer-specific seasonal programs without minimum order constraints. EU F-Gas Regulation phase-down schedules accelerate hydrocarbon propellant conversions in aerosolized dispensers. Bavarian and Baden-Württemberg manufacturing footprints absorb compliance costs fastest due to integrated crimping equipment retrofit programs.
China
Dual carbon goals under MIIT directives push converters toward lightweight PET below 8 grams and aluminum sheet supply partnerships with renewable energy offtake agreements. Yangtze River Delta blow-molding clusters face gripper reinvestment requirements for stability at speeds exceeding 1,000 units per minute. Shanghai and Jiangsu province regulators enforce stricter post-consumer collection rate verification.
Brazil
Returnable glass systems retain share in premium mineral water markets where refill economics justify higher logistics costs in São Paulo and Minas Gerais distribution networks. ANVISA food contact substance notifications extend material approval cycles for novel barrier coatings. Southeastern industrial zones concentrate aseptic carton filling equipment for ambient-stable juice exports.
India
FSSAI packaging safety standards and BIS quality certifications drive formalization of previously fragmented converter networks. Maharashtra and Gujarat beverage bottlers invest in spouted pouch fitment welding equipment for single-serve children's beverage trials. Delhi-NCR and Bangalore urban clusters pilot deposit-return collection infrastructure ahead of national extended producer responsibility frameworks.
Soft Drinks Packaging Market Competitive Environment
Global majors compete with regional champions across material-platform specialization and rPET feedstock security. The vendor base stratifies into three tiers: integrated converters with captive flake processing, mid-scale decorators reliant on spot resin markets, and niche pouch specialists. Strategic archetypes include scale-driven rPET aggregators, premium metal packaging technologists, and flexible format innovation houses. Capacity expansion and backward integration into collection infrastructure represent the dominant competitive moves.
Among integrated packaging conglomerates, Amcor plc and Ball Corporation occupy positions exemplifying scale-driven material-platform dominance, while Crown Holdings anchors the decorated metal packaging tier for premium carbonated applications. Tetra Pak Group represents the aseptic carton technology archetype with proprietary closure system integration. These three entities collectively illustrate how feedstock security and regulatory compliance capabilities determine acceptable returns through the forecast horizon.
| Leading Market Players |
|---|
| Tetra Pak Group |
| Berry Global Group |
| Amcor plc |
| Toyo Seikan Group Holdings |
| Owens-Illinois |
| Ball Corporation |
| Ardagh Group |
| Silgan Holdings |
| Crown Holdings |
| Others |
Value Chain & Pricing Dynamics
ICIS PET virgin resin indices transmit volatility through converter contract tiers, with rPET premiums widening as EU Green Deal mandates outpace collection infrastructure scaling. Bottlers without backward integration into flake processing absorb margin compression while integrated converters capture pricing power through secured feedstock pools.
Pricing Analysis
Input-cost pass-through dominates converter-buyer negotiations, with rPET flake premiums indexed to virgin resin movements plus regulatory scarcity markups. Three-tier pricing structure across premium certified-circular, standard food-grade, and economy virgin-blend levels separates converters by feedstock security. Pricing pressure stems from California and New York deposit-return expansions concentrating regional feedstock demand. National grocery distributors wield volume leverage for bulk-format procurement, while niche functional drink brands accept premium positioning for decorated metal and spouted pouch formats.
Supply Chain Analysis
Direct-to-bottler channels handle hyperscale demand from consolidated US retail networks, while regional distributors serve mid-tier private-label co-packers. Raw material flows concentrate in Germany, China, and the United States, with rPET flake processing anchored around Düsseldorf, Cologne, and Shanghai clusters. Virgin PET resin, aluminum sheet, and barrier-coated paperboard represent the critical input trio. Single-source vulnerability in rPET feedstock exposes converters to collection rate shortfalls. Distribution runs through dedicated beverage partnerships with integrated converters holding palletization and logistics coordination roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soft drinks packaging market functions as a regulatory compounder, with EU Green Deal recycled content mandates forcing material-platform investments that reshape competitive returns.
For Market Incumbents: Hedge rPET exposure through collection infrastructure partnerships or flake processing acquisitions before California and New York deposit-return expansions tighten regional feedstock access. Anchor aluminum can supply through renewable energy-linked smelter offtakes as EU REACH bisphenol phase-outs accelerate coating R&D cycles. Prioritize digital printing convergence to defend SKU proliferation economics against mid-tier decorators. For New Entrants and Emerging Players: EU Green Deal mandates in Germany and the Netherlands open a window for certified-circular pouch specialists to capture functional drink trial formats. Target spouted fitment engineering and high-definition flexographic printing where margin pools concentrate. Penetrate through direct-to-shape inkjet service models for retailer-specific seasonal programs without minimum order constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with converters holding backward integration into rPET collection or captive flake processing capabilities. Five-to-ten year viability hinges on extended producer responsibility framework positioning across multiple state jurisdictions. Watch California and New York post-consumer content minimum implementation timelines as inflection signals for regional feedstock scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Collection Infrastructure Investment | EU Green Deal mandates force feedstock security as a prerequisite for volume retention. |
| Digital Printing Capability Expansion | Direct-to-shape inkjet enables SKU proliferation without plate-change downtime for seasonal programs. |
| Aluminum Can Coating R&D Partnership | EU REACH bisphenol restrictions demand polyester and acrylic alternatives with unproven scale economics. |
| Spouted Pouch Fitment Engineering | Single-serve children's beverages and functional drinks concentrate margin in closure design. |
| Deposit-Return System Participation | California and New York expansions create localized feedstock pools anchoring West Coast conversion. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with blow-molding plant managers, beverage brand procurement leads, retail category buyers, and rPET flake processors anchored demand-side and supply-side perspectives. Secondary sources include US EPA recycled content guidelines, EU ECHA REACH restriction updates, FDA food contact substance notification records, and customs trade data for resin and aluminum sheet flows. Bottom-up capacity modeling triangulates against top-down consumption estimates across packaging formats.
Granularity-level modeling disaggregates volume and value across packaging type, material platform, closure engineering, and end-user channel dimensions throughout the forecast period. CAGRs derive from segment-level demand elasticity analysis against regulatory milestone timelines. Industry-specific inputs include filling line speed requirements, rPET collection rate assumptions, and deposit-return expansion schedules.
Revisions become necessary when EU Green Deal implementation timelines accelerate, rPET collection infrastructure deployment lags mandates, or aluminum can coating approvals face extended FDA cycles. Forecasts reflect base-case assumptions about regulatory enforcement consistency and feedstock scaling trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Aluminium Cup Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Insulated Cup Sleeves Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Beverage Crates Market
Beverage Packaging
Zippered Bottle Suit Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Juice Packaging Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Global Beverage Container Market