
 Beverage Can Ends Market | 2026-2036
Beverage Can Ends Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Can Ends Market Analysis
Lightweighting of aluminum alloy formulations is tilting the manufacturing stack toward thinner-gauge, higher-strength can end designs. Ball Corporation leverages captive aluminum supply and integrated rolling capacity to control input costs across North American production networks. Crown Holdings anchors its position through deep specialization in beverage end conversion, sustaining technical leadership in easy-open tab geometries.
Beverage can ends are precision-stamped closures, typically fabricated from 3104-H19 or 5182-H48 aluminum alloy sheet between 0.008 and 0.011 inches thick, designed to seal cylindrical containers under internal carbonation pressure while enabling consumer access through scored fracture lines. Easy open ends now dominate volume across soft drink and beer applications, while specialty ends command disproportionate margin pools in premium energy and craft beverage segments. Aluminum as a material category leads on recyclability credentials, though steel retains structural roles in certain regional packaging specifications.
EPA recycling content guidelines, EU Packaging and Packaging Waste Regulation frameworks, and FDA food-contact substance notifications collectively shape alloy selection, surface coating chemistry, and regional market access conditions for can end suppliers. Ball Corporation, Crown Holdings, and Ardagh Group must navigate diverging compliance timelines across these jurisdictions. Stakeholders should monitor alloy price volatility and emerging deposit-return scheme expansions as decisive variables for capacity planning and geographic prioritization.
Market Dynamics
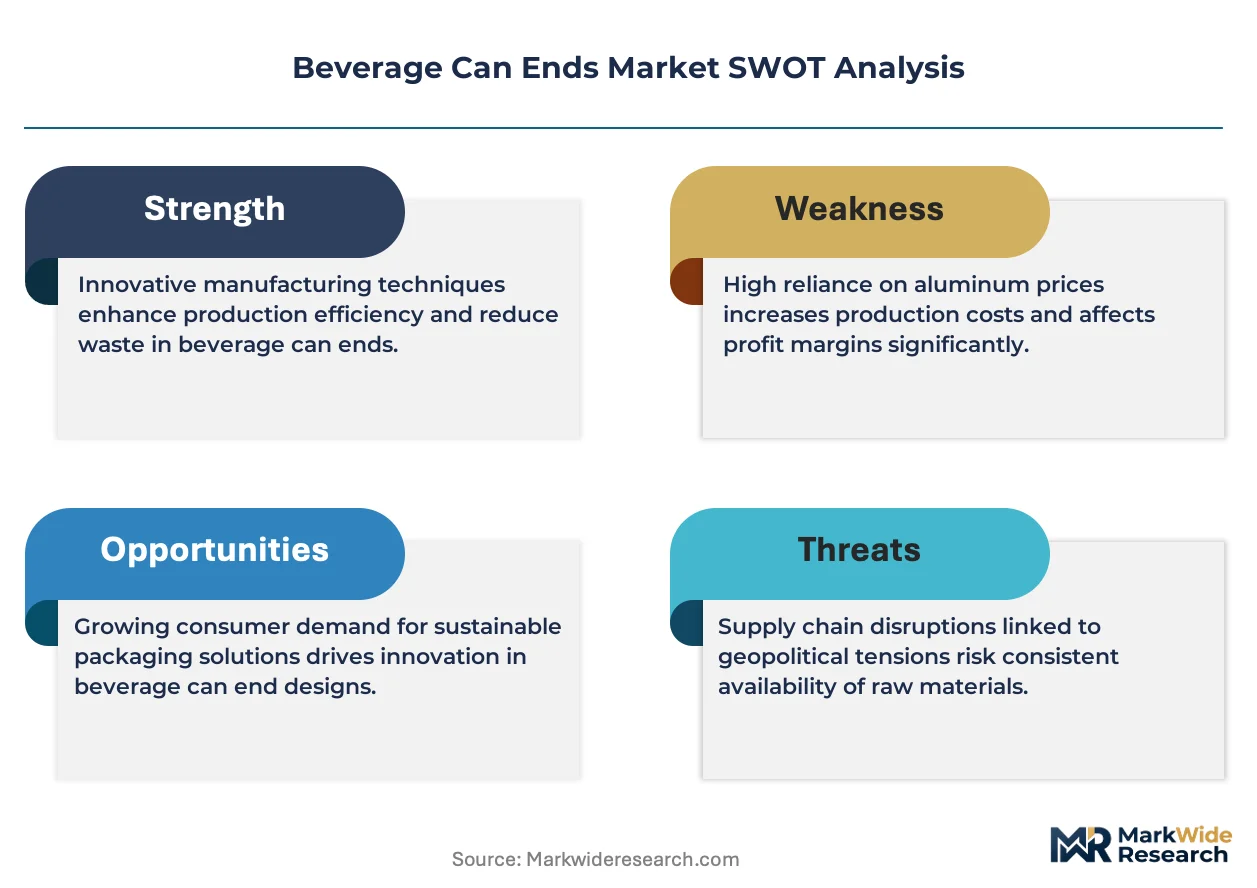
Aluminum alloy lightweighting is compressing gauge thickness specifications across beverage can end manufacturing, forcing capital retooling decisions throughout the supply base.
Growth Catalysts
- EPA Aluminum Recycling Standards:Tightened recycled content mandates in the United States are pulling virgin aluminum substitution toward post-consumer scrap streams, expanding end-of-life value capture for can fabricators.
- Energy Drink Volume Concentration:Premium energy brands are specifying higher-strength 5182-H48 alloys for carbonated formulations, creating specialized demand pools distinct from commodity beer and soft drink segments.
- Two-Piece Can End Adoption:Brazil, Germany, and Vietnam are concentrating equipment investment in drawn-and-ironed shell production, displacing three-piece legacy formats in regional packaging specifications.
Market Restraints
- Aluminum Price Volatility:London Metal Exchange ingot pricing swings directly transmit to sheet rolling margins, compressing conversion economics for independent end manufacturers without captive smelter access.
- Supply Concentration Risk:Primary aluminum smelting concentrates in Gulf Cooperation Council states and Quebec hydroelectric corridors, exposing logistics costs to geopolitical shipping lane disruptions.
- Technical Limitation:Thinner-gauge 3104-H19 formulations below 0.0085 inches face scored-tab fracture reliability constraints under elevated carbonation pressures, capping lightweighting progress in certain beverage categories.
Strategic Opportunities
- Vietnam Demand Expansion:Southeast Asian beverage packaging infrastructure is underpenetrated relative to per-capita consumption growth, creating greenfield site opportunities for integrated end-shell operations.
- Deposit-Return Scheme Tailwinds:Extended producer responsibility frameworks in Germany and adjacent EU markets are mandating closed-loop aluminum recovery, advantaging domestic recyclers with established collection networks.
- Digital Printing Convergence:Variable-data lid decoration technology is merging with high-speed conversion lines, enabling promotional versioning and regional customization without plate-change downtime.
Industry Challenges
- Tooling Engineer Scarcity:Precision die design expertise for scored fracture geometries is concentrating among aging specialists, constraining new line commissioning timelines.
- Surface Coating Certification Complexity:FDA food-contact substance notifications and EU REACH compliance for epoxy-phenolic interior coatings require parallel testing protocols, extending product qualification cycles.
- Capex Intensity:High-speed press installations exceeding 3,000 strokes per minute demand synchronized feeder and inspection systems, locking capital deployment into multi-year depreciation horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Can Ends Market |
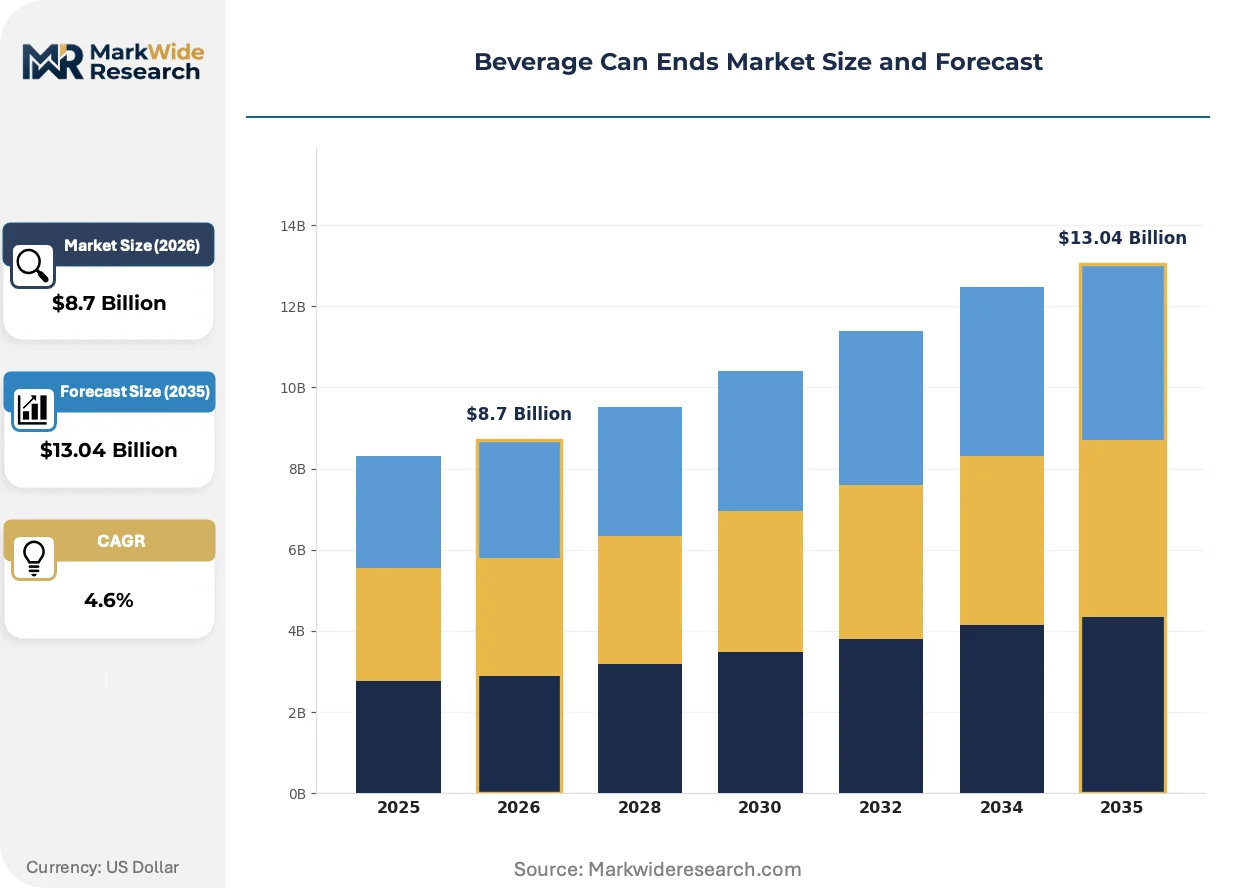
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Easy Open, Standard, Large Diameter, Specialty Material: Aluminum, Steel, Plastic, Composite Application: Soft Drinks, Beer, Juice, Energy Drinks Closure Mechanism: Pull Tab, Twist Off, Snap Off, Other |
| Companies Covered | Ball Corporation, Crown Holdings, Ardagh Group, Silgan Holdings, CANPACK, CPMC Holdings, Novelis, Orora Packaging, Envases Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Can Ends Market Emerging Trajectories
Digital simulation tools are compressing product development cycles for scored-tab geometries, while regulatory pressure on material chemistry is accelerating coating formulation turnover.
Finite element analysis software is virtualizing the traditional physical prototyping stage for easy-open end designs. Beverage brand technical teams are adopting these tools for rapid iteration on tab lift geometry and score residual thickness. This virtualization is compressing supplier qualification timelines from months to weeks.
EU Packaging and Packaging Waste Regulation frameworks are mandating extended producer responsibility for aluminum recovery across member states. Can end manufacturers must document recycled content percentages through certified mass-balance systems. German and French beverage packers are responding by specifying minimum post-consumer scrap thresholds in procurement contracts.
Direct-to-brewery technical service models are displacing distributor-mediated support relationships in craft beverage segments. Smaller regional brewers demand on-site press troubleshooting and alloy specification consulting. This pattern is most visible in Colorado, Oregon, and Bavaria craft brewing clusters where batch flexibility outweighs scale economies.
Beverage Can Ends Market Segmentation
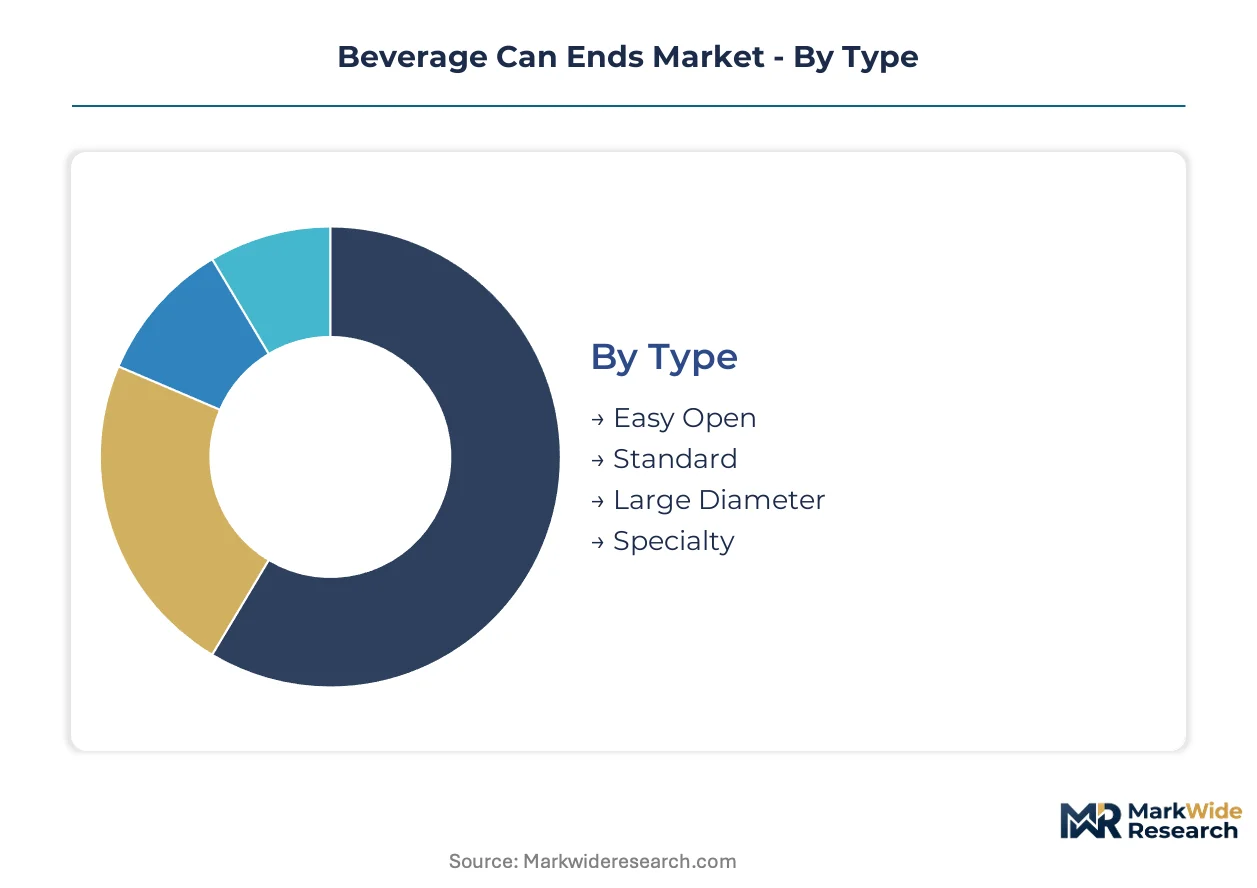
Beverage can end segmentation reveals divergent margin profiles across technical specifications and material categories. Procurement cycles vary dramatically by closure type, with easy-open formats commanding premium positioning against commodity standard ends.
Type:
Product lifecycles compress fastest in convenience-driven formats while industrial specifications retain decade-long equipment amortization horizons.
- Easy Open:Scored aluminum fracture geometries with integrated stay-on-tab designs dominate carbonated beverage sealing. Energy drink brands in Brazil and Germany specify reinforced 5182-H48 alloy variants to withstand elevated internal pressures during distribution.
- Standard:Conventional flat ends without consumer-opening features serve institutional and industrial container applications. Steel-retained specifications in certain regional packaging codes sustain residual demand despite aluminum recyclability advantages.
- Large Diameter:Expanded aperture designs accommodate viscous beverages and nitrogen-dosed coffee formulations. Craft brewing clusters in Colorado and Bavaria specify these for sensory-focused pouring experiences.
- Specialty:Custom aperture geometries and decorative embossing target premium spirits and limited-edition beverage releases. Variable-data lid decoration technology enables promotional versioning without plate-change downtime.
Easy Open dominates installed base. Specialty is where expansion concentrates.
Material:
Cost stratification separates virgin aluminum premiums from scrap-recycled alternatives, with steel and plastics occupying distinct regulatory niches.
- Aluminum:3104-H19 and 5182-H48 alloy sheets between 0.008 and 0.011 inches thick enable precision stamping under carbonation pressure. EPA aluminum recycling standards tighten virgin substitution toward post-consumer scrap streams.
- Steel:Structural retention in certain Eastern European and Middle Eastern packaging specifications persists despite recyclability disadvantages. Food-contact coating chemistry faces parallel FDA and EU REACH testing protocols.
- Plastic:Polymer-based closures serve niche non-carbonated and aseptic applications where metal corrosion resistance matters. Bisphenol-A regulatory pressure constrains interior coating formulation options.
- Composite:Multi-layer material stacks combine barrier properties with lightweighting targets in experimental formats. Extended producer responsibility frameworks complicate end-of-life sorting infrastructure requirements.
Aluminum commands volume leadership. Composite formats are climbing the fastest.
Application:
Carbonation intensity and thermal processing requirements segment alloy specification and coating chemistry across beverage categories.
- Soft Drinks:High-volume cola and flavored carbonated water applications standardize on 3104-H19 alloy at thinnest viable gauges. Thinner-gauge formulations below 0.0085 inches face scored-tab fracture reliability constraints under pressure.
- Beer:Pasteurization-compatible interior coatings and oxygen-scavenging layers protect flavor stability in extended distribution. German deposit-return schemes mandate closed-loop aluminum recovery with certified mass-balance documentation.
- Juice:Non-carbonated and low-acid formulations permit alternative closure geometries with reduced pressure ratings. Aseptic filling requirements drive specialized coating certification complexity.
- Energy Drinks:Premium carbonated formulations specify higher-strength 5182-H48 alloys for structural integrity. Vietnam and Southeast Asian markets concentrate greenfield demand growth for integrated end-shell operations.
Beer anchors legacy capacity. Energy Drinks is gaining share fastest.
Closure Mechanism:
Consumer ergonomics and line-speed compatibility determine mechanism selection across packaging formats.
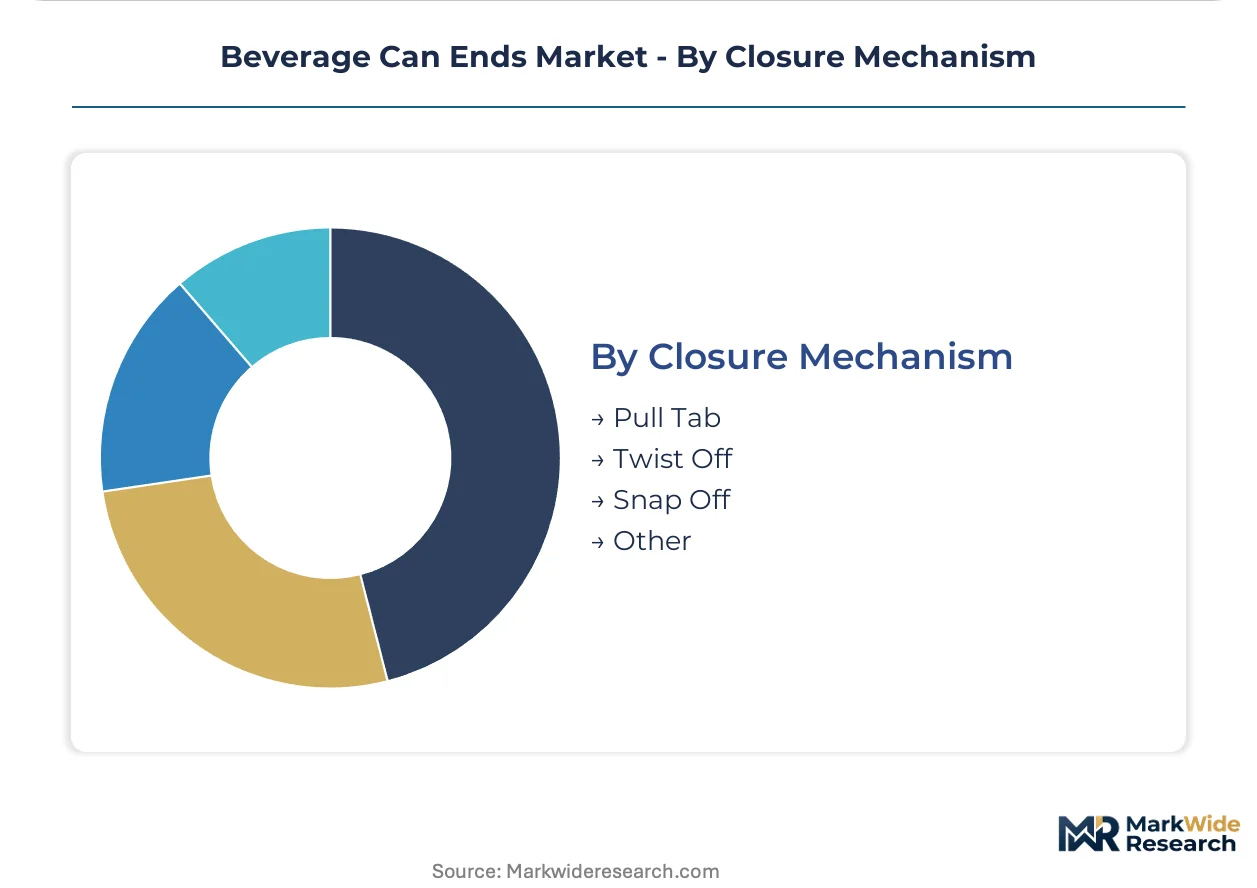
- Pull Tab:Stay-on-tab scored fracture designs dominate soft drink and beer volume through familiar consumer interaction patterns. Digital simulation tools compress product development cycles for tab lift geometry optimization.
- Twist Off:Threaded metal or composite closures serve resealable applications in larger-format beverage containers. Reusability claims face scrutiny under EU Packaging and Packaging Waste Regulation extended producer responsibility frameworks.
- Snap Off:Friction-fit mechanisms appear in single-serve juice and dairy-alternative formats with lower carbonation requirements. Child-resistance specifications constrain design freedom in certain regulatory jurisdictions.
- Other:Emerging peelable membrane and hybrid mechanisms target convenience and sustainability positioning. Direct-to-brewery technical service models support batch-flexible adoption in craft beverage segments.
Pull Tab holds installed base dominance. Other mechanisms show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational beverage brands and regional energy drink specialists concentrate procurement across manufacturing clusters in Brazil, Germany, Vietnam, and the United States. Each geography presents distinct regulatory frameworks and alloy specification demands that shape supplier qualification requirements.
Brazil
Energy drink volume expansion and two-piece can end migration drive equipment investment in São Paulo and Minas Gerais industrial corridors. ANVISA food-contact substance notifications govern interior coating chemistry for carbonated beverage sealing. Campinas hosts concentrated conversion line installations serving southeast Brazilian packaging demand.
Germany
Deposit-return scheme mandates and craft brewing cluster growth sustain premium end specification demand across Bavaria and North Rhine-Westphalia. EU Packaging and Packaging Waste Regulation frameworks enforce extended producer responsibility with certified mass-balance documentation. Munich-area technical service operations support direct-to-brewery consulting relationships.
Vietnam
Per-capita beverage consumption growth and greenfield packaging infrastructure investment concentrate demand in Ho Chi Minh City and Hanoi manufacturing zones. The country's national environmental regulator implements aluminum recovery targets aligned with regional circular economy commitments. Binh Duong province attracts integrated end-shell operation development.
United States
EPA aluminum recycling standards tighten virgin substitution requirements while energy drink brands expand 5182-H48 alloy sourcing. FDA food-contact substance notifications parallel state-level extended producer responsibility pilot programs. Colorado and Oregon craft brewing clusters specify large-diameter aperture designs for sensory-focused pouring.
Mexico
Nearshoring beverage production and USMCA trade integration support can end demand across Nuevo León and Jalisco industrial corridors. The country's national environmental regulator coordinates with EPA-aligned recycling content verification systems. Monterrey hosts captive aluminum supply integration for North American production networks.
Beverage Can Ends Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a consolidated structure where three integrated aluminum suppliers dominate volume. Ball Corporation, Crown Holdings, and Ardagh Group anchor the top tier through captive rolling capacity and technical leadership in scored-tab geometries. Mid-tier independent converters without smelter access face margin compression from London Metal Exchange price volatility. Competitive moves concentrate on backward integration into aluminum sheet rolling and geographic expansion into Southeast Asian greenfield markets.
Within the integrated-tier archetype, Ball Corporation exemplifies channel control through captive supply chain configuration, while Crown Holdings occupies a position emphasizing end conversion specialization. Among holding-company structures, Silgan Holdings and CANPACK represent diversified packaging portfolio approaches that span multiple closure categories. Novelis anchors the materials-tier position as a rolling specialist supplying independent fabricators.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Ardagh Group |
| Silgan Holdings |
| CANPACK |
| CPMC Holdings |
| Novelis |
| Orora Packaging |
| Envases Group |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange aluminum ingot volatility functions as the primary risk vector, compressing conversion margins for independent fabricators without captive smelter access while simultaneously widening pricing tier spreads between integrated suppliers and merchant converters. This commodity exposure determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of backward integration investments.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange primary aluminum pricing dominate procurement relationships between rolling mills and end converters. Price differentiation rests on alloy specification grade and volume scale commitments, with 5182-H48 high-strength formulations commanding premiums over commodity 3104-H19 gauges. Pricing pressure stems from thinner-gauge lightweighting investments that strain scored-tab reliability margins. Craft brewing clusters exhibit highest price sensitivity due to batch-flexibility requirements, while energy drink brands demonstrate lowest sensitivity given carbonation integrity specifications.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard instruments for managing working capital across aluminum sheet procurement cycles. Primary aluminum smelting concentrates in Gulf Cooperation Council states, Quebec hydroelectric corridors, and Australian bauxite-to-ingot operations. Raw material dependencies encompass bauxite ore, alumina refining capacity, and rolling mill sheet output. Tariff exposure on Chinese semi-fabricated aluminum creates structural vulnerability for North American converters. Distribution runs through beverage brand technical procurement teams with direct-to-brewery service models displacing traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beverage can ends market constitutes a defensive-moat structure anchored in regulatory entrenchment, where EPA aluminum recycling standards and EU Packaging and Packaging Waste Regulation frameworks create compliance barriers that favor incumbent integrated suppliers with established mass-balance documentation systems.
For Market Incumbents: Insulate conversion margin positions through captive aluminum supply integration and high-speed press capacity additions in Vietnam and Southeast Asian growth corridors. Threat substitution from composite and plastic closure formats demands accelerated 5182-H48 alloy qualification programs. Certification investment in FDA food-contact substance notifications and EU REACH compliance extends competitive distance from merchant converters lacking parallel testing infrastructure. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's greenfield packaging infrastructure zone, where per-capita beverage consumption growth outpaces domestic end-shell manufacturing capacity. Specialty energy drink segments with 5182-H48 alloy specifications offer the most penetrable white-space target given premium margin pools and technical service intensity that deters commodity-focused incumbents. Direct-to-brewery technical consulting models provide the essential go-to-market angle for securing initial qualification trials with craft brewing clusters. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated aluminum suppliers with backward control over sheet rolling capacity. Long-term viability across the five-to-ten year window hinges on deposit-return scheme expansion and closed-loop aluminum recovery infrastructure positioning. Acquisition target archetype: mid-tier independent converters with established brand relationships but lacking smelter access, where upstream integration unlocks margin expansion. The signal to watch as inflection indicator is state-level extended producer responsibility legislation adoption rates in the United States.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Captive 3104-H19 and 5182-H48 sheet supply insulates Ball Corporation from London Metal Exchange volatility. |
| Vietnam Greenfield Capacity Expansion | Binh Duong province integrated end-shell operations capture Southeast Asian beverage packaging demand concentration. |
| Digital Simulation Tool Deployment | Finite element analysis virtualization compresses Crown Holdings scored-tab geometry development cycles from months to weeks. |
| Deposit-Return Scheme Infrastructure Investment | German closed-loop aluminum recovery networks advantage Ardagh Group with certified mass-balance documentation. |
| Direct-to-Brewery Technical Service Model | On-site press troubleshooting in Colorado and Bavaria craft clusters builds switching costs against distributor-mediated competitors. |
Methodological Framework
Operator-level perspectives from beverage brand procurement directors, can end conversion line engineers, aluminum rolling mill technical sales managers, and craft brewery operations heads anchored the qualitative base. Primary interview findings were cross-validated against secondary sources including London Metal Exchange pricing data, EPA aluminum recycling standard filings, EU Packaging and Packaging Waste Regulation implementation documents, and FDA food-contact substance notification databases. Bottom-up capacity and demand modeling was reconciled with top-down macroeconomic consumption projections through iterative triangulation.
Scenario-bracketing around aluminum price volatility bands, regulatory compliance timeline variations, and deposit-return scheme adoption rates bounded the forecast uncertainty envelope. Segmentation dimensions encompassed closure type, alloy material specification, beverage application category, and regional manufacturing cluster. CAGRs were derived from installed base replacement cycles, greenfield capacity commissioning schedules, and per-capita consumption elasticity estimates. Industry-specific forecast inputs incorporated 5182-H48 alloy adoption curves in energy drink segments and two-piece can end migration rates in Brazil, Germany, and Vietnam.
Stress conditions across London Metal Exchange price spikes, EPA recycled content mandate acceleration, and Southeast Asian logistics disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding alloy substitution timelines and regulatory compliance cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Bottle Shippers Market
Beverage Packaging
Ice Transport Buckets Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Beverage Packaging Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
Cold Beverage Cups Market