
 Bowl Cans Market | 2026-2036
Bowl Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Bowl Cans Market Outlook
Southeast Asia is tilting toward bowl can capacity expansion as regional food exports climb. Crown Holdings leverages vertical integration across aluminum sourcing and coating technologies to sustain cost advantages. Ball Corporation anchors its position through beverage-to-food diversification, while Toyo Seikan Group specializes in high-barrier composite laminates for acidic food applications.
Bowl cans are cylindrical metal or hybrid containers with rolled rims and easy-open lids, typically constructed from 3004-H19 aluminum alloy or tinplate steel with internal epoxy-phenolic linings to prevent corrosion. They function as retortable packaging for ready meals, pet food, and nutritional products requiring thermal sterilization. Aluminum variants lead the product type category due to lightweighting benefits and recycling infrastructure maturity, whereas composite formats represent the fastest-growing segment as brands seek microwaveable and peelable solutions. The 400ml capacity band occupies the central margin pool, balancing portion flexibility with palletization efficiency across food industry and beverage industry end users.
The EPA governs volatile organic compound emissions from can coating operations in the United States, while REACH and the EU Packaging and Packaging Waste Directive shape material compliance obligations across Europe. Japan's METI enforces container recycling quotas that incentivize aluminum recovery rates above regional benchmarks. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between regional manufacturing scale or import-dependent flexibility before regulatory thresholds tighten.
Market Dynamics
Aluminum alloy substitution and coating chemistry reformulation dominate bowl can manufacturing decisions as REACH compliance deadlines and EU F-Gas phase-down schedules compress material specification windows across European supply chains.
Growth Catalysts
- Retortable ready-meal demand:Food processors in Germany and Thailand are expanding thermal sterilization capacity for shelf-stable proteins, driving procurement of 3004-H19 aluminum bowl cans with epoxy-phenolic linings.
- Extended producer responsibility frameworks:Japan's METI container recycling quotas incentivize aluminum recovery infrastructure investment, creating closed-loop supply incentives for converters.
- Barrier coating advances:High-barrier composite laminates enable acidic food applications previously restricted to glass, opening pet food and nutritional supplement segments to metal packaging.
Market Restraints
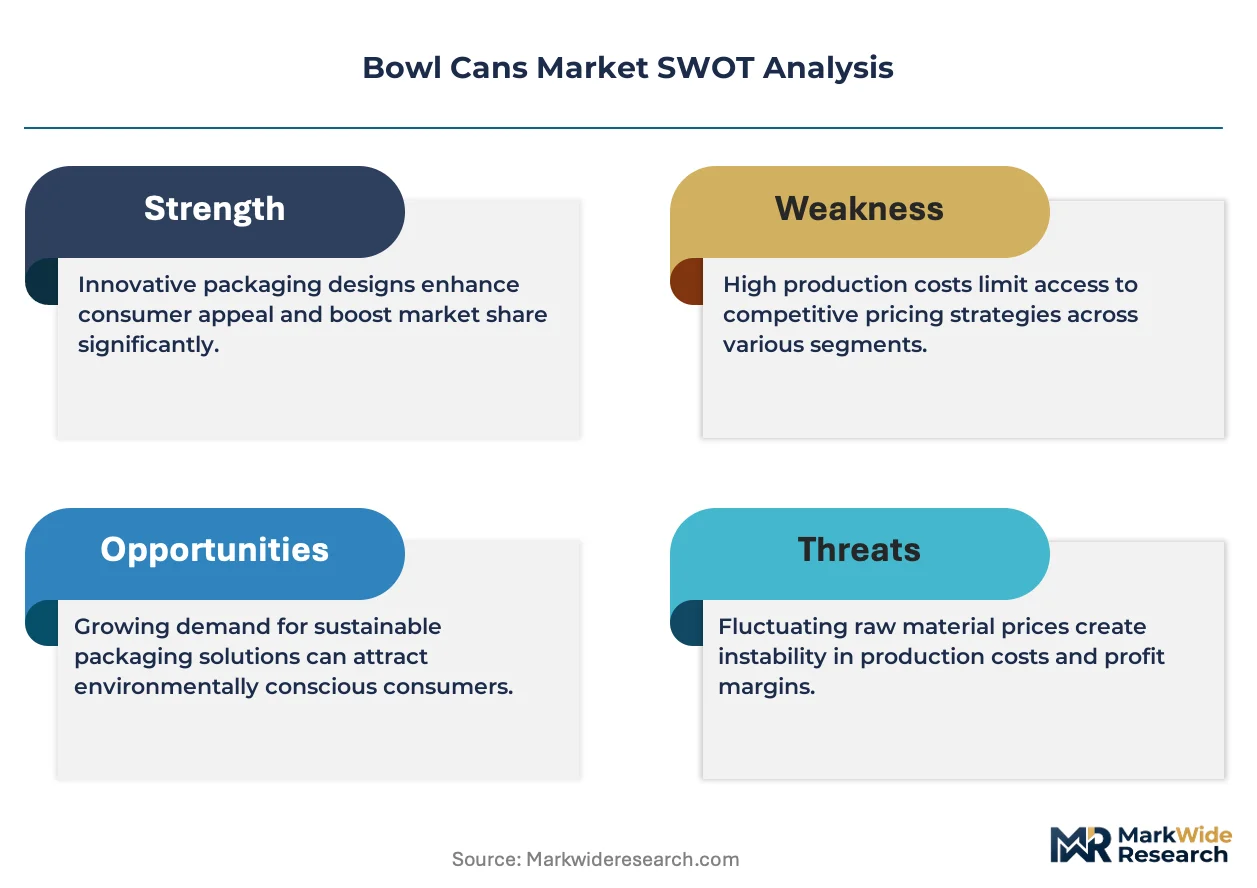
- Primary aluminum price volatility:LME aluminum contract swings directly compress converter margins on 400ml standard capacity bands, forcing index-linked pricing clauses.
- Coating chemical supply concentration:Epoxy-phenolic resin production clusters in Northeast Asia create single-source risk for European can makers during shipping disruptions.
- Steel substrate substitution:Tinplate remains cost-competitive for non-retort applications, constraining aluminum penetration in price-sensitive private-label segments.
Strategic Opportunities
- Microwaveable peelable formats:Composite bowl cans with modified atmosphere capabilities capture premium ready-meal positioning in Japanese convenience retail channels.
- Southeast Asian export processing zones:Vietnam and Indonesia food manufacturing clusters lack integrated can forming capacity, creating regional supply gaps for multinational processors.
- EU Green Deal carbon border adjustments:Lower-carbon aluminum grades certified under emerging EU methodologies command procurement preference from sustainability-mandated food brands.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for BPA-non-intent epoxy alternatives resides with a narrow cohort of specialists, extending R&D timelines.
- Retort qualification protocols:Thermal sterilization validation for new laminate structures requires 18-24 month food safety approvals, delaying commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bowl Cans Market |
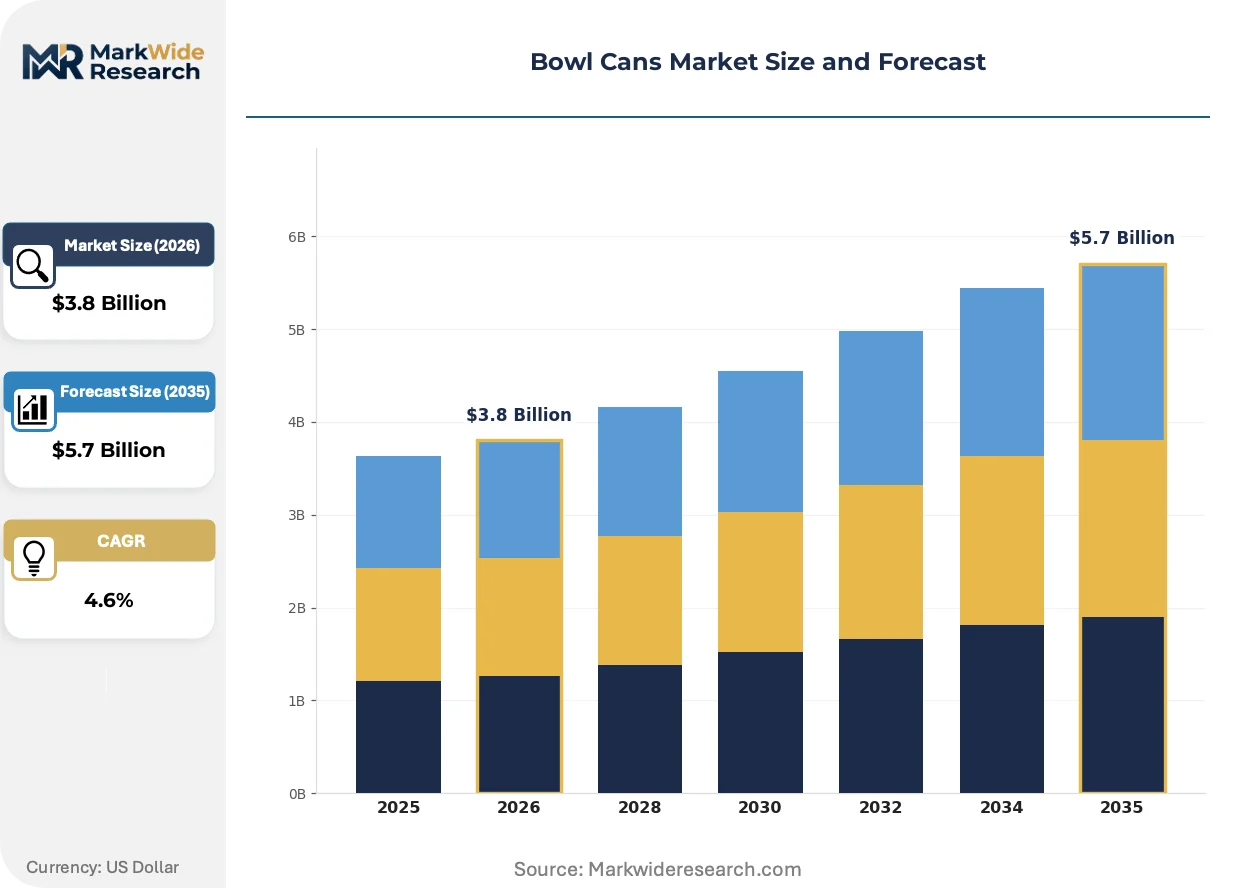
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Steel, Plastic, Composite Capacity: 200ml, 400ml, 600ml, 1000ml End User: Food Industry, Beverage Industry, Personal Care, Household Products Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Crown Holdings, Ball Corporation, Ardagh Group, Silgan Holdings, Can-Pack, Toyo Seikan Group, CPMC, Daiwa Can, Massilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bowl Cans Market Strategic Shifts
Digital process control and inline inspection systems are compressing defect rates and enabling lot-level traceability across high-speed bowl can forming lines, while regulatory chemistry restrictions force material stack redesigns.
Smart forming systems with machine vision and predictive maintenance algorithms are digitizing quality assurance workflows. Ready-meal contract manufacturers in Germany and Japan deploy these systems to eliminate rim defect escapes. The technology is digitizing supplier-customer data exchange, replacing batch certificate documentation with real-time coating thickness verification.
The EU F-Gas Regulation hydrofluorocarbon phase-down is restricting blowing agent options for internal insulation foams used in composite bowl can lids. Can makers reformulate polyurethane cores with hydrocarbon alternatives, extending curing cycles. Acidic food applications with high-barrier requirements face the tightest formulation windows under the new restrictions.
Direct sourcing from aluminum smelters is consolidating procurement relationships among large food brands, bypassing traditional converter-distributor channels. Nestlé and Unilever procurement teams in Switzerland and the Netherlands negotiate billet supply agreements directly with smelters certified to ASI standards. This pattern concentrates volume with integrated producers and fragments spot market liquidity.
Bowl Cans Market Segmentation
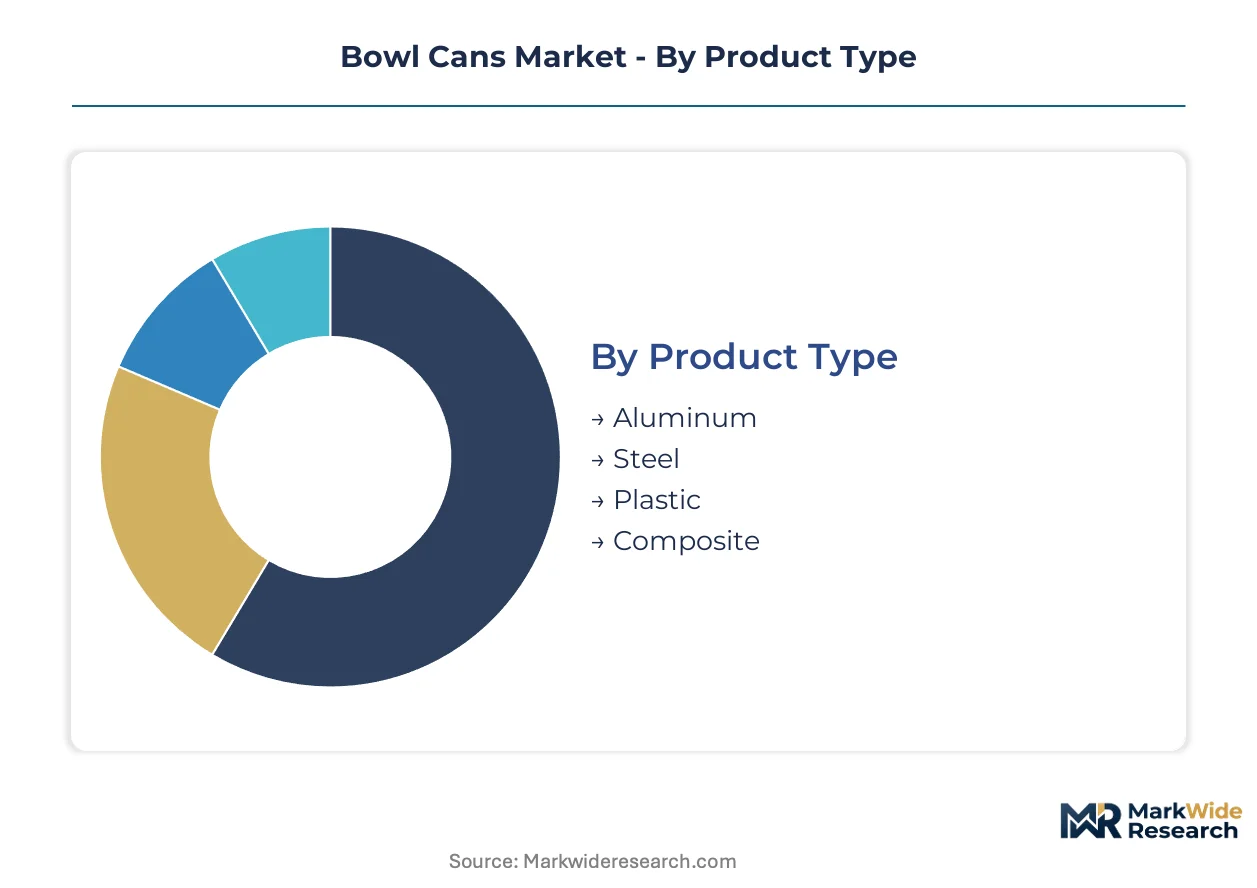
Bowl can procurement patterns diverge sharply across material grades and sterilization requirements. Food processors segment their supplier portfolios by retort compatibility, while beverage bottlers prioritize lightweighting economics. Understanding these technical fault lines clarifies where specification windows are tightening versus commoditizing.
Product Type:
Aluminum variants turn inventory fastest through established recycling loops, whereas composite laminates sit longer in qualification pipelines. Steel and plastic occupy intermediate velocity positions depending on regional coating chemistry availability.
- Aluminum:3004-H19 alloy construction with epoxy-phenolic internal linings delivers the lightweighting and thermal conductivity required for retort sterilization. German food processors anchor procurement volumes for shelf-stable proteins, though LME price volatility forces index-linked contract structures.
- Composite:Multi-layer structures combining aluminum foil, polypropylene, and paperboard enable microwaveable peelable formats with modified atmosphere capabilities. Japanese convenience retail channels concentrate demand as brands seek premium ready-meal differentiation against metal-only alternatives.
- Steel:Tinplate substrates with chromium passivation layers serve non-retort applications where cost sensitivity outweighs weight considerations. Private-label segments in price-conscious European markets sustain volume.
- Plastic:Polypropylene and polyethylene terephthalate variants target single-serve portions with snap-fit lids, bypassing metal forming capital intensity. Limited thermal tolerance restricts penetration in sterilized food categories.
Aluminum dominates installed base across retort applications. Composite formats are where expansion concentrates for microwaveable and peelable solutions.
Capacity:
Mid-range volumes generate the densest margin pools through palletization efficiency, while small formats sacrifice unit economics for portion control premiums. Large capacities face demand fragmentation across institutional and export segments.
- 400ml:The central specification band balances portion flexibility with cube utilization in intermodal shipping. Food industry procurement teams standardize around this capacity for ready meals and pet food, anchoring converter line utilization rates.
- 200ml:Single-serve nutritional supplements and infant formula portions command premium positioning. Japanese and German pharmaceutical-food crossover brands concentrate demand for high-barrier small-format solutions.
- 600ml:Family-size ready meals and bulk pet food applications occupy niche positioning. Limited converter tooling availability constrains supply elasticity.
- 1000ml:Institutional catering and food service export volumes drive intermittent demand. Pallet weight limits and manual handling constraints restrict adoption in retail channels.
400ml anchors converter capacity planning. 200ml is climbing the fastest as nutritional supplement brands downsize portion architecture.
End User:
Food sterilization requirements impose the longest qualification cycles, while personal care and household applications permit faster material substitutions. Beverage processors occupy intermediate timelines governed by carbonation compatibility testing.
- Food Industry:Thermal sterilization protocols for shelf-stable proteins, ready meals, and pet food mandate epoxy-phenolic lining integrity validation. Thailand and Germany anchor regional procurement clusters with expanding retort capacity.
- Beverage Industry:Carbonated and still drinks requiring pasteurization rather than full retort processing enable thinner gauge substrates. Southeast Asian export processing zones concentrate greenfield demand.
- Personal Care:Cosmetic creams and hair treatments prioritize aesthetic finish over barrier performance. Shorter qualification cycles permit faster material experimentation.
- Household Products:Cleaning agents and automotive chemicals drive corrosion-resistant specification demand. Limited overlap with food-grade converter capabilities fragments supply options.
Food Industry dominates specification complexity. Beverage Industry is gaining share fastest as bottlers diversify from cylindrical cans into bowl formats.
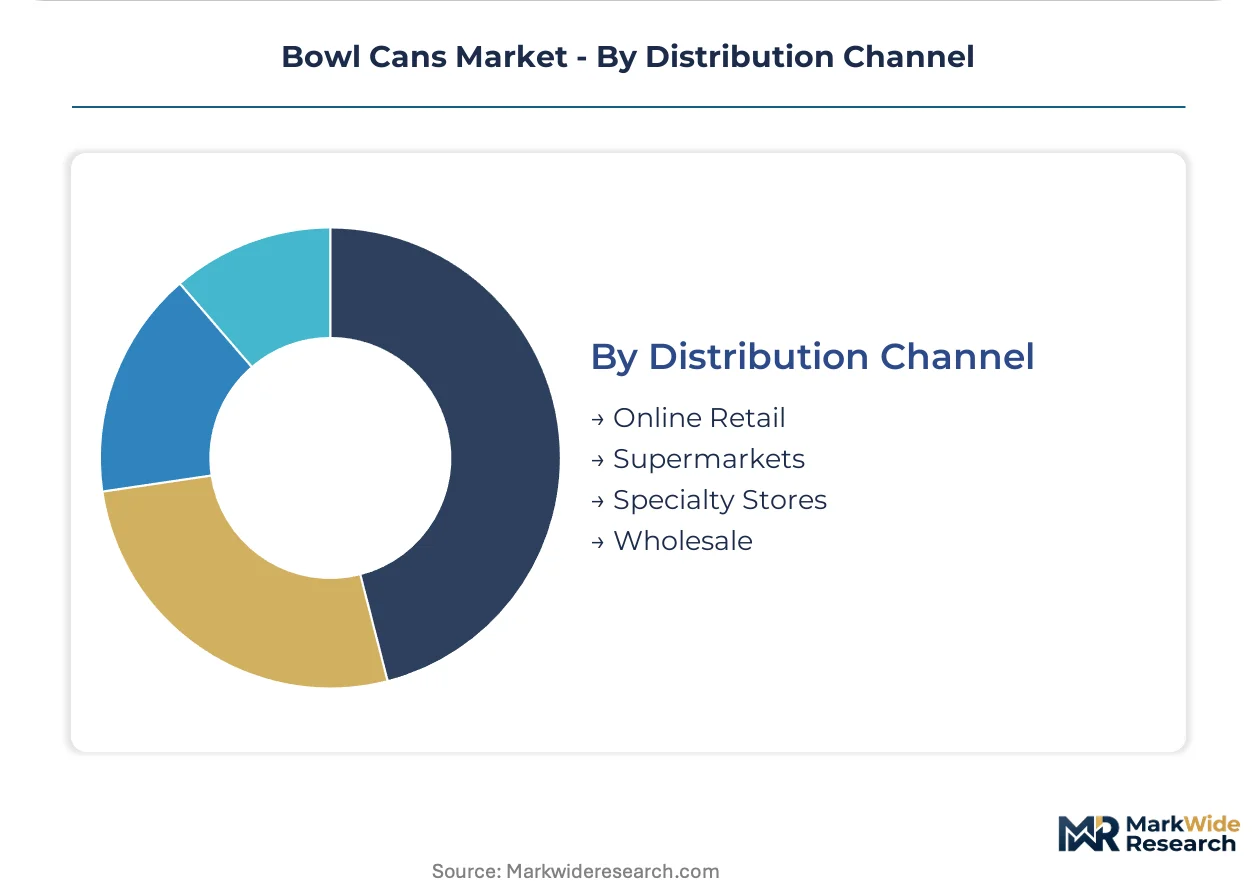
Distribution Channel:
Direct procurement relationships turn over slowly through multi-year framework agreements, while spot wholesale markets permit rapid volume reallocation. Digital channels occupy intermediate velocity with platform-dependent listing cycles.
- Wholesale:Converter-direct supply to multinational food processors and contract manufacturers locks in volume commitments across 12-36 month horizons. Nestlé and Unilever procurement teams negotiate billet-linked pricing directly with ASI-certified smelters.
- Supermarkets:Private-label specification power concentrates with Carrefour, Tesco, and Aeon category managers demanding cost-competitive tinplate alternatives for non-retort segments.
- Specialty Stores:Premium pet food and nutritional supplement boutiques sustain small-batch aluminum orders with customized lithography requirements.
- Online Retail:Direct-to-consumer subscription models for specialized nutrition products bypass traditional retail slotting constraints. Limited penetration in bulk food categories due to shipping cost thresholds.
Wholesale anchors volume concentration. Online Retail is expanding most quickly as subscription nutrition brands build direct fulfillment infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany, Japan, and Thailand where food processing density sustains dedicated bowl can lines. Regulatory chemistry restrictions in the EU and extended producer responsibility mandates in Asia-Pacific are forcing material specification divergence across regional supply chains.
Germany
Retort-ready meal processors in Baden-Württemberg and Bavaria anchor European procurement volumes for 3004-H19 aluminum bowl cans. The EU F-Gas Regulation and REACH compliance deadlines compress material specification windows for converters serving these clusters. Stuttgart-area forming facilities are upgrading epoxy-phenolic coating lines to meet emerging carbon border adjustment thresholds.
Japan
Microwaveable peelable formats for convenience retail channels drive composite laminate demand in the Kanto and Kansai regions. METI container recycling quotas incentivize aluminum recovery infrastructure investment above regional benchmarks. Nagoya-area converters specialize in high-barrier structures for acidic food applications previously restricted to glass packaging.
Thailand
Export-oriented food processors in the Eastern Economic Corridor expand thermal sterilization capacity for shelf-stable proteins. The country's Board of Investment incentives support can forming equipment imports for regional supply gaps. Bangkok-area procurement teams negotiate directly with ASI-certified aluminum smelters to bypass traditional converter-distributor channels.
United States
Beverage-to-food diversification among Midwest bottlers generates greenfield demand for bowl formats in Illinois and Ohio. EPA volatile organic compound emissions rules govern can coating operations across these industrial states. Chicago-area contract manufacturers deploy smart forming systems with machine vision to eliminate rim defect escapes in high-speed lines.
Vietnam
Food manufacturing clusters in the Red River Delta and Mekong Delta lack integrated can forming capacity for export processing zones. General import tariff structures on packaging machinery create capital barriers for local converter development. Ho Chi Minh City-based processors rely on regional supply from Thai and Chinese sources while assessing domestic forming investments.
Bowl Cans Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in coating chemistry and aluminum sourcing. The vendor base consolidates around three to five integrated producers with captive smelter relationships and in-house laminate R&D, while mid-scale converters compete on regional logistics and qualification speed. Two dominant competitive moves define current positioning: direct billet procurement agreements that bypass traditional distribution channels, and backward integration into aluminum sourcing to secure lower-carbon grade certification. Geographic expansion into Southeast Asian export processing zones and portfolio diversification from beverage into food sterilization applications complete the strategic map.
Among North American integrated producers, Crown Holdings and Ball Corporation exemplify the platform archetype with beverage-to-food diversification strategies. Toyo Seikan Group occupies a specialist position within the composite laminate tier, representing Japanese precision in high-barrier structures for acidic food applications. These three anchors illustrate how scale concentration at the top coexists with technical differentiation in material stack design, with each firm representing a distinct competitive vector rather than overlapping positioning.
| Leading Market Players |
|---|
| Crown Holdings |
| Ball Corporation |
| Ardagh Group |
| Silgan Holdings |
| Can-Pack |
| Toyo Seikan Group |
| CPMC |
| Daiwa Can |
| Massilly |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Rotterdam container freight corridors transmit cost volatility directly into bowl can converter margins, amplifying price differentiation between ASI-certified aluminum grades and standard commodity billets while compressing procurement flexibility for European food processors bound by REACH compliance timelines.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European bowl can procurement. Three-tier pricing structure across premium, standard, and economy levels separates ASI-certified low-carbon aluminum from commodity-grade billets and tinplate steel substitutes. Price differentiation rests on certification grade and volume scale, with Nestlé and Unilever procurement teams commanding preferential billet-linked terms through direct smelter agreements. Cost compression in the standard tier is intensifying because LME aluminum contract volatility forces index-linked clauses that erode converter margins. Private-label segments exhibit highest price sensitivity, while premium ready-meal brands in Japanese convenience channels absorb barrier coating premiums with minimal elasticity.
Supply Chain Analysis
Primary aluminum feedstock draws from smelter complexes in China, Russia, and the Middle East, with secondary recovery loops concentrating in Germany and Japan. Epoxy-phenolic resin production clusters in Northeast Asia, while 3004-H19 alloy rolling capacity localizes in the United States and Western Europe. Single-source vulnerability pervades coating chemistry supply, as European can makers depend on concentrated Northeast Asian resin producers vulnerable to shipping disruptions. Distribution runs through converter-direct wholesale channels locking 12-36 month framework agreements with multinational food processors, fragmenting spot market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bowl can demand cycles track food processing capital expenditure waves, with current retort capacity expansion in Thailand and Germany signaling an upswing phase. Procurement teams are consolidating supplier relationships ahead of anticipated raw material cost volatility.
For Market Incumbents: Entrench position through backward integration into ASI-certified aluminum sourcing and captive coating chemistry production. Crown Holdings and Ball Corporation already leverage direct billet agreements; mid-scale converters must secure similar smelter relationships or face margin compression from index-linked pricing volatility. Capacity addition in Vietnam and Indonesia addresses regional supply gaps before competitors establish local forming infrastructure. For New Entrants and Emerging Players: Pursue microwaveable peelable composite formats for Japanese convenience retail channels, where barrier coating expertise scarcity limits incumbent expansion speed. Vietnam's export processing zones present the most penetrable geography, with food manufacturing clusters lacking integrated can forming capacity. A joint venture with Thai or Chinese converters offers the fastest qualification pathway for retort sterilization protocols. For Investors and Strategic Acquirers: Regional converters with captive laminate R&D capabilities and established food safety approvals represent the highest-conviction acquisition archetype. Long-term viability hinges on positioning ahead of EU carbon border adjustment implementation and extended producer responsibility framework maturation. The signal to watch is ASI certification penetration rates among European food brand procurement mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Sourcing | Direct billet procurement from ASI-certified smelters bypasses distributor markups and secures carbon-grade preference. |
| High-Barrier Composite Laminate R&D | Toyo Seikan Group's acidic food expertise demonstrates premium positioning against metal-only alternatives in Japanese retail. |
| Southeast Asian Capacity Expansion | Vietnam and Indonesia food manufacturing clusters lack integrated forming infrastructure for export processing zone demand. |
| Smart Forming System Deployment | German contract manufacturers deploy machine vision to eliminate rim defect escapes and digitize coating verification. |
| Coating Chemistry Reformulation | Hydrocarbon blowing agent substitution addresses EU F-Gas Regulation phase-down constraints on polyurethane lid cores. |
Study Parameters
Initial hypotheses were tested against primary input from converter plant managers, food industry procurement leads, aluminum smelter sales directors, and epoxy-phenolic coating chemists, and refined through secondary validation against customs trade data, EU REACH substance restriction updates, SEC 10-K filings from Crown Holdings and Ball Corporation, and METI container recycling statistics. Bottom-up segment sizing triangulated against top-down aluminum billet consumption estimates across food packaging applications.
Demand-supply balance framing anchored the forecast framework across the analysis window. Segmentation dimensions modeled include material type, capacity band, end-use industry, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical retort capacity expansion patterns and food export volume trajectories. Industry-specific inputs incorporated LME aluminum price elasticity coefficients and coating chemistry qualification timeline distributions.
Macroeconomic conditions sit as an overlay; deviation in primary aluminum spot prices, container freight rates, or EU carbon border adjustment implementation schedules would shift the trajectory. Forecasts reflect documented assumptions about retort sterilization adoption rates and extended producer responsibility enforcement intensity. Cross-checking against ASI certification registry growth and food processing equipment import data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Water Bottle Racks Market
Beverage Packaging
Europe Soft Drinks Packaging Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Skep Bottle Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Beverage Cups Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Sugarcane Bottles Market