
 Juice Packaging Market | 2026-2036
Juice Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Juice Packaging Market Outlook
Premium aseptic specifications is bifurcating the competitive landscape as brands race to meet extended shelf-life claims without synthetic additives. Tetra Pak leverages its integrated filling-equipment ecosystem to lock in converter relationships across high-volume juice lines. Amcor anchors North American supply through blown PET capacity co-located with major beverage bottlers. SIG Combibloc differentiates via aluminum-free carton structures that resonate with European retailer sustainability scorecards.
Juice packaging encompasses primary containment systems engineered to preserve organoleptic integrity, block UV and oxygen ingress, and withstand pasteurization or high-pressure processing temperatures ranging from 85°C to 135°C. Aseptic cartons dominate value retention through multilayer barrier films combining polyethylene, aluminum foil, and paperboard substrates. Plastic bottles capture volume leadership in emerging retail channels where cost-per-unit and logistics flexibility outweigh premium positioning. Flexible pouches represent the fastest-expanding format among on-the-go consumption occasions and single-serve food service portions.
FDA food-contact substance notifications govern polymer and coating approvals for U.S. juice packaging, while EFSA migration limits under EU Regulation 10/2011 constrain additive chemistries across laminated structures. The EU Green Deal's packaging and packaging waste regulation is forcing measurable recycled content thresholds that reshape converter raw-material procurement. Stakeholders must monitor how diverging transatlantic compliance timelines for extended producer responsibility will redistribute manufacturing footprints and capital allocation across substrate technologies.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing converters to reengineer multilayer laminate structures while maintaining oxygen barrier performance. This regulatory compression is accelerating material substitution timelines and redistributing capital toward renewable substrate pilot lines.
Growth Catalysts
- Aseptic carton specifications:Health-conscious households in Germany and France are demanding extended shelf stability without synthetic preservatives, pulling premium multilayer formats into mainstream retail channels.
- EU Green Deal mandates:The packaging and packaging waste regulation is creating enforceable recycled content thresholds that reshape converter procurement strategies across laminated structures.
- Single-serve food service:Flexible pouches are capturing on-the-go consumption occasions in urban transit corridors and workplace catering installations.
Market Restraints
- Aluminum foil dependency:Barrier layer supply concentrates among a limited set of European rolling mills, exposing converters to input volatility and long lead times.
- Polyethylene cost structure:Fossil-derived sealant layers face price pressure from energy feedstock fluctuations and carbon border adjustment exposure.
- Recyclability technical limitation:Current mechanical separation processes cannot efficiently delaminate paperboard-polyethylene-aluminum composites at commercial scale.
Strategic Opportunities
- Aluminum-free carton structures:SIG Combibloc's polymer-only barrier technology opens positioning against European retailer sustainability scorecards demanding reduced metal content.
- High-pressure processing compatibility:Cold pasteurization at 600 MPa enables lighter-weight PET bottles without thermal degradation, suited to refrigerated juice segments.
- Indian organized retail expansion:Modern trade penetration in Mumbai and Delhi NCR creates first-mover advantage for aseptic brick formats in ambient juice categories.
Industry Challenges
- Migration testing timelines:EFSA compliance for novel barrier coatings under EU Regulation 10/2011 extends certification cycles to 18-24 months, delaying product launches.
- Legacy filling equipment retrofit:Converters face integration complexity when adapting existing Tetra Pak and SIG lines for thinner-gauge renewable substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Juice Packaging Market |
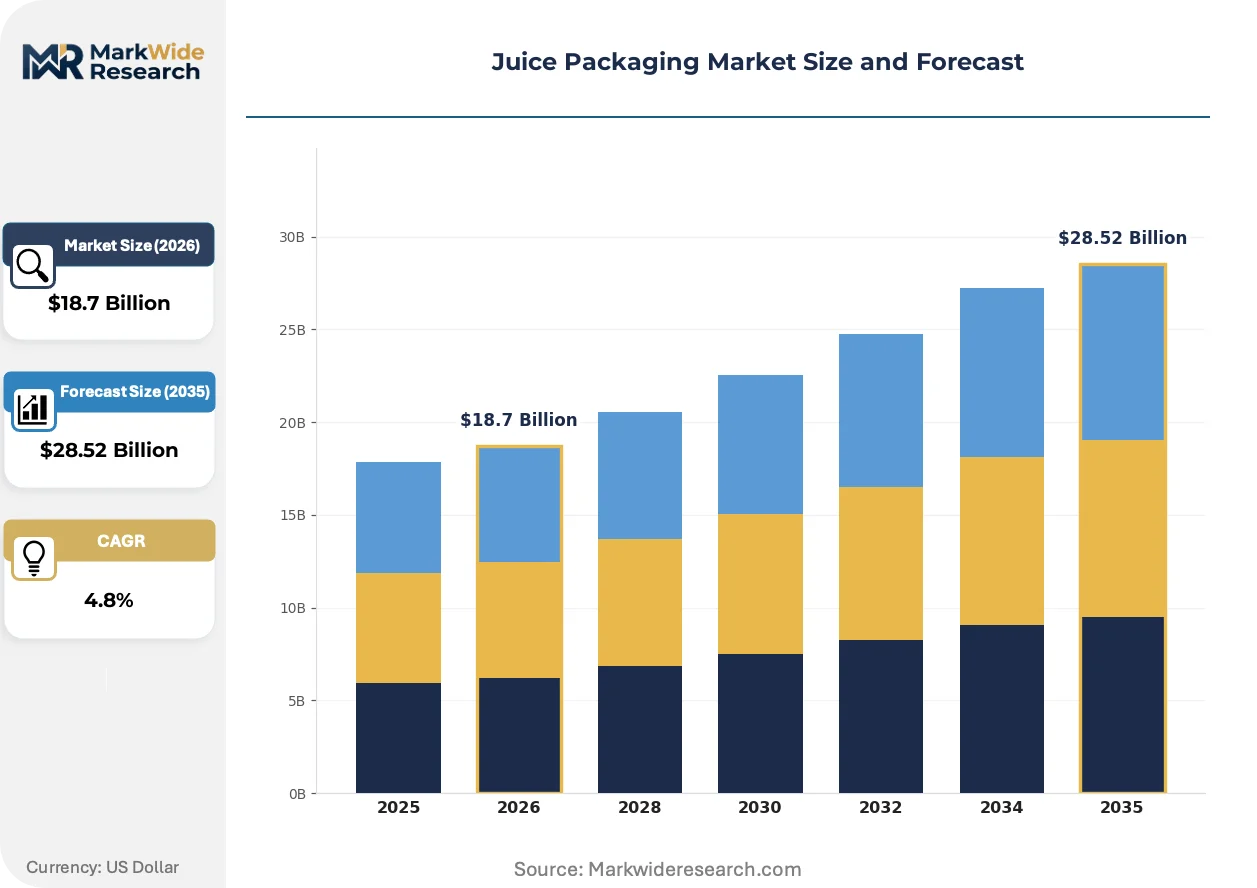
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Aseptic Cartons, Glass Bottles, Plastic Bottles, Flexible Pouches Closure Type: Screw Caps, Flip Tops, Spouts, Corks Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | Tetra Pak, Amcor, SIG Combibloc, Ball Corporation, Mondi Group, Elopak, Evergreen Packaging, Smurfit Kappa, Crown Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Juice Packaging Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine barrier performance standards. Converters must now engineer substrates that satisfy both shelf-life claims and end-of-life circularity requirements without trade-off penalties.
Polymer-metal hybrid barrier films are bifurcating the technical pathway for oxygen ingress protection. Premium juice brands in Nordic markets are adopting these structures for 12-month ambient shelf claims. The technology is bifurcating converter R&D allocation between aluminum-dependent legacy lines and metal-free pilot investments.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated greaseproof coatings from paperboard juice cartons. ECHA's 2023 PFAS restriction proposal forces immediate formulation pivots toward bio-based barrier alternatives. German private-label retailers are accelerating supplier audits to preempt compliance gaps.
Direct-to-food-service procurement is compressing traditional distributor layers in single-serve juice distribution. Workplace micro-market operators and university catering consortia now contract directly with regional bottlers for flexible pouch formats. This disintermediation is most visible in Netherlands and Belgium urban clusters where logistics density supports drop-ship economics.
Juice Packaging Market Segmentation
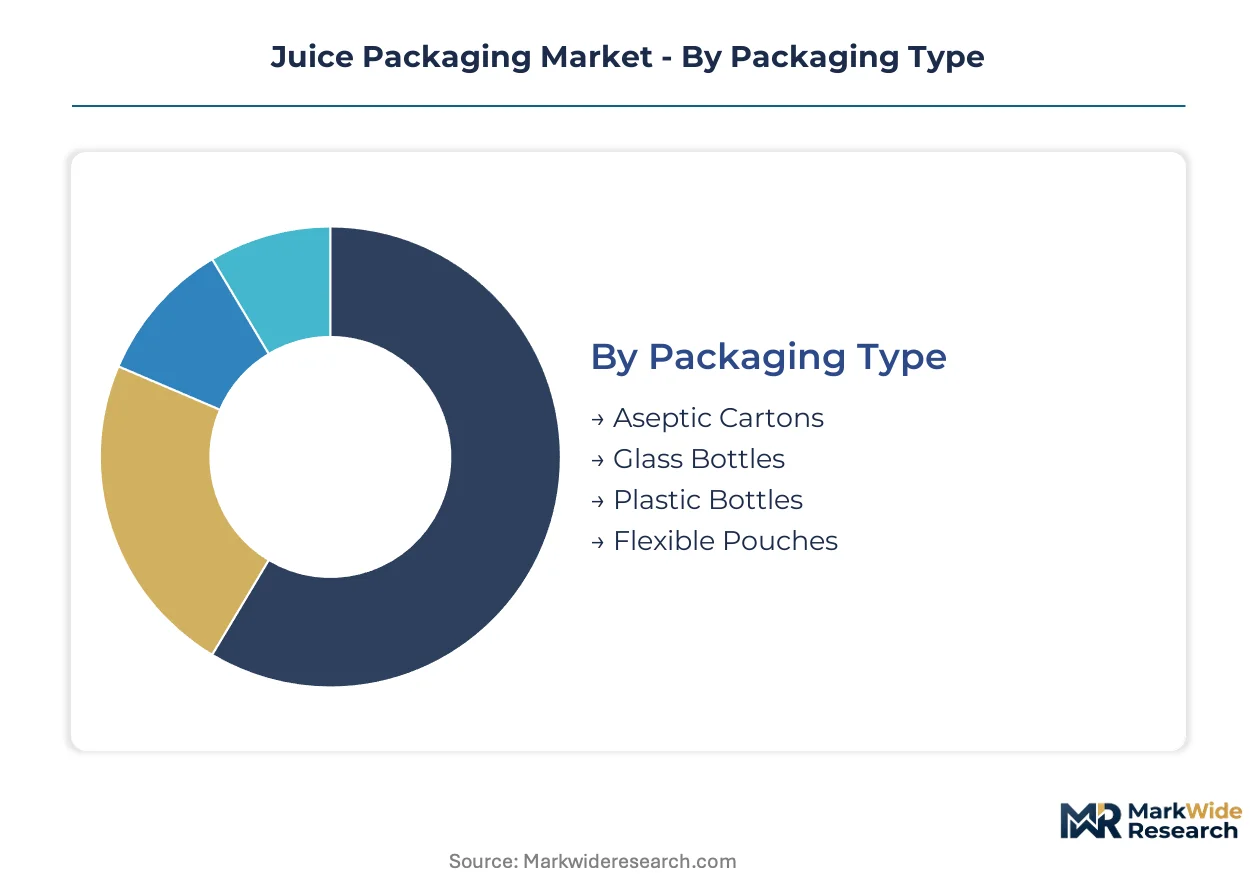
Juice packaging segments map directly to shelf-life requirements, pasteurization methods, and consumption occasions. Material selection and format geometry determine which channels and end-users each segment can serve.
Packaging Type:
Channel mix varies sharply by barrier performance and logistics economics. Aseptic cartons flow predominantly through supermarkets and ambient retail. Plastic bottles dominate convenience stores and online retail where weight and breakage risk matter. Flexible pouches concentrate in food service and on-premise channels.
- Aseptic Cartons:Multilayer laminates combine paperboard, polyethylene, and aluminum foil to achieve 12-month ambient shelf stability without refrigeration. Demand concentrates in German and French supermarkets where private-label juice volumes and EU Green Deal sustainability mandates converge. The format commands premium positioning for preservative-free claims.
- Flexible Pouches:Stand-up and spouted configurations with metallized or clear barrier films target single-serve consumption. Growth clusters in Mumbai and Delhi NCR food service channels where organized retail expansion creates first-mover advantage for ambient juice categories. Logistics flexibility and reduced shipping weight drive adoption.
- Plastic Bottles:PET and HDPE formats with oxygen scavenger additives serve refrigerated juice segments requiring high-pressure processing compatibility. Blown PET capacity co-located with major beverage bottlers anchors North American supply.
- Glass Bottles:Premium positioning for organic and cold-pressed juices with premium retail placement. Weight and breakage constraints limit channel penetration.
By volume, plastic bottles lead. By growth pace, flexible pouches are ahead.
Closure Type:
Cost tier structures closure selection across packaging formats. Premium juice lines specify engineered closures with tamper-evidence and reseal functions. Economy tiers accept basic screw configurations.
- Screw Caps:Standard threaded closures in HDPE or PP dominate high-volume juice lines. Injection-molded capacity scales efficiently across PET and HDPE bottle platforms.
- Spouts:Integrated drinking apertures with tethered lids target children's juice and on-the-go consumption. FDA food-contact substance notifications govern polymer approvals for U.S. applications.
- Flip Tops:Hinged reseal mechanisms balance convenience with material efficiency. Common in mid-tier supermarket juice offerings.
- Corks:Natural and synthetic stopper formats reserved for premium sparkling juices and celebratory positioning. Limited volume, highest margin tier.
Screw caps capture the largest unit volumes. Spouts show the steepest expansion trajectory.
Distribution Channel:
Customer type determines procurement patterns and format specifications. Household purchasers prioritize shelf stability and resealability. Food service operators value portion control and dispensing efficiency.
- Supermarkets:Multi-format shelf sets combining aseptic cartons, plastic bottles, and chilled glass for complete category representation. EFSA migration limits under EU Regulation 10/2011 constrain laminated structures across European retail.
- Food Service:Bulk bag-in-box and single-serve pouch formats for restaurant, cafe, and catering procurement. Direct contracting with regional bottlers compresses traditional distributor layers in Netherlands and Belgium urban clusters.
- Convenience Stores:Grab-and-go plastic bottles and small-format cartons for immediate consumption occasions. Refrigerated display constraints favor PET clarity and label visibility.
- Online Retail:Ship-ready packaging with drop-test certification and reduced dimensional weight. Flexible pouches and aseptic cartons outperform glass for e-commerce logistics.
Supermarkets retain the largest revenue share. Online retail is climbing the fastest.
End User:
Application requirements segment demand by consumption setting and volume scale. Households purchase for pantry stocking and daily consumption. Commercial operators need inventory efficiency and portion consistency.
- Households:Multi-serve aseptic cartons and refrigerated plastic bottles for at-home consumption across family and single-person units. Health-conscious segments in Germany pull premium multilayer formats into mainstream channels.
- Restaurants:Bag-in-box and bulk PET for fountain and back-of-house dispensing. Consistent pour quality and inventory turnover drive format selection.
- Catering Services:Single-serve pouches and portion cups for event and institutional feeding. Workplace micro-market operators contract directly with regional bottlers.
- Cafes:Premium glass and custom-labeled bottles for front-of-house merchandising. Brand differentiation through packaging aesthetics.
Households generate the highest absolute volume. Catering services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in juice packaging equipment and substrates tilt toward deficit in emerging consumption hubs and surplus in established manufacturing bases. Germany and the United States anchor export capacity for aseptic carton laminates and filling systems. Import dependency concentrates in markets where retail modernization outpaces domestic converter investment.
Germany
Private-label juice volumes and EU Green Deal sustainability mandates pull premium multilayer aseptic formats into mainstream supermarket channels. EFSA migration limits under EU Regulation 10/2011 constrain laminated structure chemistries and extend certification cycles. The Rhine-Main industrial corridor hosts concentrated converter pilot lines for aluminum-free carton substrates.
United States
FDA food-contact substance notifications govern polymer and coating approvals for high-volume juice lines. Blown PET capacity co-located with major beverage bottlers anchors North American supply for refrigerated segments. The Midwest manufacturing belt concentrates filling-equipment integration facilities serving retail and food service channels.
India
Organized retail expansion in Mumbai and Delhi NCR creates first-mover positioning for aseptic brick formats in ambient juice categories. FSSAI packaging regulations govern food-contact material safety and labeling requirements. The Maharashtra-Gujarat industrial corridor attracts converter investment targeting single-serve pouch demand from urban food service operators.
Netherlands
Workplace micro-market operators and university catering consortia contract directly with regional bottlers for flexible pouch formats. The EU Green Deal's packaging and packaging waste regulation forces measurable recycled content thresholds across converter procurement. The Randstad logistics cluster enables drop-ship economics for compressed distribution layers in single-serve juice.
China
Dual carbon goals and GB standards for food packaging materials reshape substrate selection toward renewable and recyclable alternatives. Yangtze River Delta manufacturing bases supply both domestic retail modernization and export demand for aseptic carton laminates. Shanghai-based converter networks pilot polymer-only barrier technologies for metal-free carton structures.
Juice Packaging Market Competitive Environment
Listed packaging conglomerates compete with private specialists across equipment integration and substrate supply. The vendor base concentrates among integrated system providers with captive filling-technology platforms and independent converters serving regional bottlers. Strategic archetypes span integrated carton-laminate-and-equipment providers, blown-film specialists co-located with beverage customers, and aluminum-free barrier technology pioneers. Competitive moves center on pilot-line investment for renewable substrates and direct contracting with food service operators to compress distributor layers.
Among integrated system providers, Tetra Pak and SIG Combibloc occupy positions as archetype anchors for equipment-locked converter relationships. Amcor exemplifies the blown-film specialist model with capacity positioned alongside major beverage bottlers. These three represent divergent technical pathways: multilayer aluminum-dependent laminates, aluminum-free polymer barriers, and high-volume PET oxygen-scavenger formulations.
| Leading Market Players |
|---|
| Tetra Pak |
| Amcor |
| SIG Combibloc |
| Ball Corporation |
| Mondi Group |
| Elopak |
| Evergreen Packaging |
| Smurfit Kappa |
| Crown Holdings |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal packaging waste directives gate supplier qualification while simultaneously forcing price differentiation across renewable substrate tiers. German and French retailers now audit converter compliance before contract award, embedding sustainability certification costs into premium multilayer carton pricing. This regulatory overlay compresses margins for aluminum-dependent legacy lines while rewarding aluminum-free pilot investments with shelf-space premiums.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across high-volume aseptic carton and PET bottle procurement. Pricing stratifies across premium, standard, and economy tiers based on barrier performance grade and EU Green Deal compliance certification. Cost compression in standard-tier polyethylene sealant layers is intensifying because fossil feedstock volatility and carbon border adjustment exposure. Food service operators exhibit highest price sensitivity due to direct contracting economics, while premium organic juice brands show lowest sensitivity to resealable closure premiums.
Supply Chain Analysis
Extended lead times for aluminum foil barrier layers expose converters to input volatility from European rolling mill concentration. Supply draws from Germany, China, and the United States for aseptic carton laminates, blown PET capacity, and filling equipment integration. Raw material dependencies center on polyethylene sealant resins, paperboard substrates, and oxygen scavenger additives. Single-source vulnerability concentrates in aluminum foil supply from limited European mills. Distribution runs through direct-to-food-service contracting that compresses traditional distributor layers in Netherlands and Belgium urban clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The juice packaging market tracks a cyclical recovery tied to organized retail modernization in emerging consumption hubs. Mumbai and Delhi NCR retail expansion creates demand pull for ambient-stable formats, repricing risk premiums for early converter positioning.
For Market Incumbents: Fortify equipment-locked relationships by retrofitting legacy Tetra Pak and SIG lines for thinner-gauge renewable substrates. SIG Combibloc's aluminum-free barrier technology threatens multilayer laminate incumbents with European retailer sustainability scorecard displacement. Backward integration into paperboard substrate supply secures input cost control against EU Green Deal recycled content mandates.
For New Entrants and Emerging Players: Differentiate on high-pressure processing compatibility for refrigerated juice segments requiring lighter-weight PET without thermal degradation. White-space concentrates in Indian organized retail expansion where aseptic brick formats lack established converter relationships. Direct contracting with workplace micro-market operators in Randstad logistics clusters offers food service channel entry without distributor layer investment.
For Investors and Strategic Acquirers: EU Green Deal enforceable recycled content thresholds reshape the acquisition landscape toward aluminum-free barrier technology platforms. Five-to-ten year viability favors converters with pilot-line investment in polymer-only laminates and renewable substrate qualification. Target acquisition archetype: mid-cap specialists with FSSAI or FDA food-contact substance notification pipelines. Signal to watch: EFSA certification cycle compression for novel barrier coatings under EU Regulation 10/2011.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum-Free Barrier Technology Deployment | SIG Combibloc's polymer-only structures unlock European retailer sustainability scorecard positioning against metal-dependent competitors. |
| High-Pressure Processing Compatibility Investment | Cold pasteurization at 600 MPa enables lighter-weight PET bottles for refrigerated juice segments without thermal degradation. |
| Direct-to-Food-Service Channel Expansion | Workplace micro-market operators in Netherlands urban clusters contract directly with regional bottlers, compressing distributor economics. |
| Renewable Substrate Pilot Line Scale-Up | Rhine-Main industrial corridor converter investments target EU Green Deal recycled content thresholds for laminated structures. |
| Indian Organized Retail First-Mover Positioning | Mumbai and Delhi NCR modern trade penetration creates aseptic brick format demand for ambient juice categories. |
Study Parameters
Desk research of FDA food-contact substance notifications, EFSA migration limit filings under EU Regulation 10/2011, and FSSAI packaging regulation disclosures preceded structured interviews with converter procurement directors, beverage bottler supply chain managers, and food service channel operators. Primary fieldwork triangulated with secondary validation from trade customs data, EU Green Deal regulatory impact assessments, and retail private-label volume audits. Bottom-up substrate demand modeling converged with top-down macroeconomic drivers across the analysis window.
Variance decomposition isolates segment-level growth contributions from packaging format adoption curves, regulatory compliance cost pass-through, and channel mix evolution. The analytical framework models demand across aseptic cartons, flexible pouches, plastic bottles, and glass formats by shelf-life requirement, pasteurization method, and distribution channel. CAGRs derive from segment-level volume trajectories weighted by value-per-unit differentials. Industry-specific forecast inputs include EFSA certification cycle timelines for novel barrier coatings and high-pressure processing equipment penetration rates in refrigerated juice segments.
Forecasts assume regulatory continuity in EU Green Deal packaging waste directives, FDA food-contact substance notification pathways, and FSSAI food packaging material standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Graduated Sample Bottle Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
Stackable Beaker Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Beveled Bottles Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Bowl Cans Market
Beverage Packaging
Bomber Bottles Market
Beverage Packaging
Beverage Crates Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market