
 Bottle Dividers Market | 2026-2036
Bottle Dividers Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle Dividers Market Outlook
European molded fiber and corrugated packaging capacity is consolidating around multi-material converter networks serving beverage bottlers. Huhtamaki leverages its broad foodservice and protective packaging platform to extend divider solutions across Nordic and Central European bottling corridors. Ardagh Group S.A. anchors glass container manufacturing with captive divider sourcing strategies at its Western European facilities. Gerresheimer AG specializes in pharmaceutical and premium beverage glass, competing through integrated packaging design services that incorporate custom divider specifications.
Bottle dividers are structural inserts engineered to separate, cushion, and stabilize individual bottles within cases, cartons, or shipping containers, typically fabricated from corrugated board, molded pulp, expanded polystyrene, or thermoformed plastic with cell dimensions calibrated to specific bottle diameters and weights. Their primary function is preventing glass-to-glass contact, absorbing impact energy during distribution, and enabling efficient palletization across temperature-variable supply chains. Corrugated board dividers dominate volume due to recyclability alignment with retailer sustainability mandates, while molded pulp variants represent the fastest-expanding material category as bottling companies phase out styrofoam. Plastic divider demand concentrates in reusable crate systems for returnable bottle programs, where durability requirements override single-use material preferences.
REACH and the EU Green Deal shape material compliance pathways, restricting certain expanded polystyrene formulations and mandating recycled content thresholds for packaging placed on European markets. FDA food-contact regulations govern divider materials for beverage exports entering United States distribution channels, particularly for adhesives and coatings in corrugated constructions. Stakeholders must monitor evolving extended producer responsibility frameworks and material-specific bans to calibrate portfolio transitions ahead of compliance deadlines.
Market Dynamics
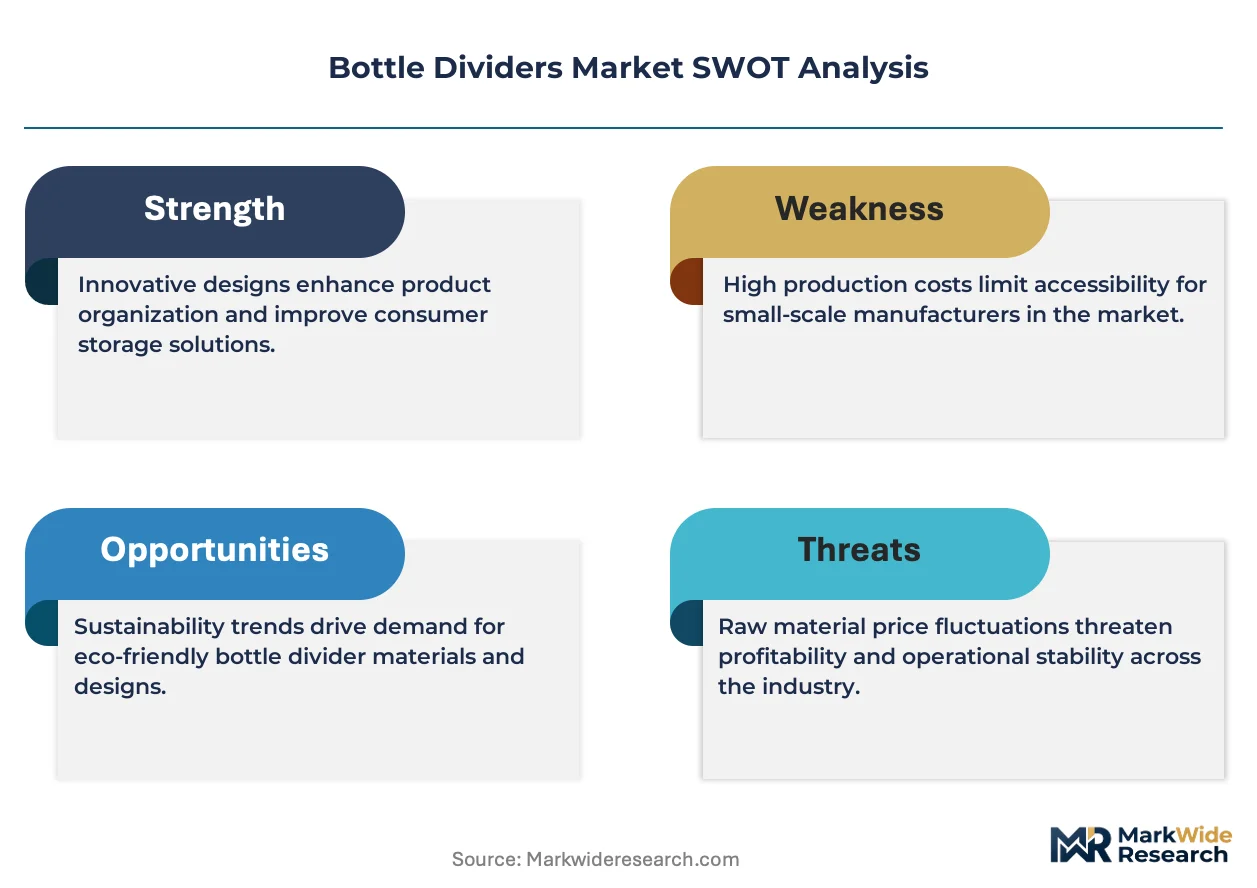
Sustainability mandates from the EU Green Deal are compressing the transition timeline for beverage packaging converters, forcing rapid material substitution away from expanded polystyrene toward corrugated and molded fiber alternatives across European bottling corridors.
Growth Catalysts
- EU Green Deal packaging mandates:Recycled content thresholds and single-use plastic restrictions are pulling molded pulp divider demand from premium spirits and craft brewery segments across Germany, France, and the Netherlands.
- Glass bottling cluster concentration:The Rhineland and Bavaria regions anchor specialized divider procurement networks serving Ardagh and Gerresheimer production facilities with just-in-time delivery requirements.
- Returnable bottle system expansion:Durable plastic divider demand is accelerating in German and Danish reusable crate programs where wash-cycle durability specifications exceed single-use material performance.
Market Restraints
- Pulp fiber input cost volatility:European recycled paper and agricultural fiber prices fluctuate with energy costs, compressing molded pulp converter margins and creating pricing instability for beverage bottlers.
- Multi-material converter consolidation:Capacity concentration among Nordic and Central European packaging networks limits supplier diversity and extends lead times for specialized divider specifications.
- REACH chemical compliance barriers:Restricted substance lists for adhesives and coatings in corrugated constructions create formulation bottlenecks, particularly for dividers entering pharmaceutical and premium beverage applications.
Strategic Opportunities
- Biodegradable barrier coatings:Water-resistant molded pulp technologies are opening pharmaceutical and high-humidity beverage applications previously blocked by fiber swelling limitations.
- Extended Producer Responsibility frameworks:France, Italy, and Spain are implementing packaging fee structures that reward fiber-based dividers with lower environmental contribution rates than plastic alternatives.
- Direct-to-retailer procurement channels:Large beverage bottlers are bypassing traditional distributor networks, creating openings for specialized divider manufacturers with design-to-delivery capabilities.
Industry Challenges
- Structural design engineering scarcity:Finite talent pools for bottle-specific cell dimension optimization and impact modeling constrain converter response times for custom premium spirits and wine applications.
- Legacy crate system integration:New fiber-based dividers must retrofit existing reusable plastic crate dimensions standardized decades ago, limiting design freedom and material efficiency gains.
- Cross-border compliance synchronization:Divergent national implementations of EU packaging regulations create certification fragmentation for converters serving multiple European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle Dividers Market |
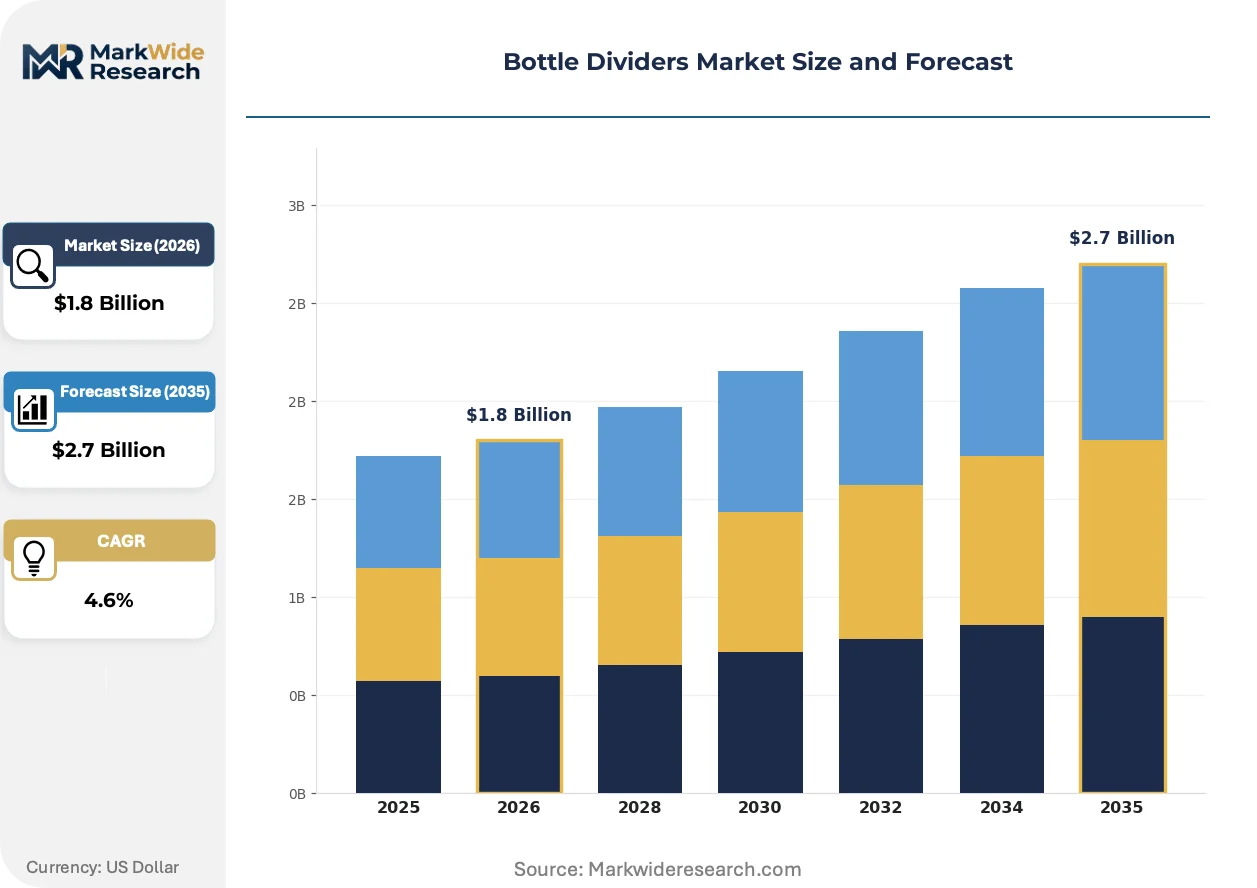
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Foam, Cardboard, Wood Application: Retail Display, Shipping, Storage, Beverage Packaging End User: Bottling Companies, Warehouses, Retailers, Online Merchants Material: Recycled Material, Biodegradable, Styrofoam, Corrugated Board |
| Companies Covered | Estic-Maillot, Huhtamaki, O-I Glass, Inc, Ardagh Group S.A., Anchor Glass Container Corporation, Gerresheimer AG, Stoelzle Glass Group, Ball Corporation, Accio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle Dividers Market Strategic Shifts
Active material science development is collapsing the performance gap between sustainable fiber-based dividers and legacy plastic alternatives, reshaping competitive positioning across beverage packaging tiers.
Molded pulp technology is integrating nanocellulose barrier treatments and precision thermoforming techniques to achieve glass-contact smoothness and moisture resistance previously exclusive to expanded polystyrene. Premium wine and spirits producers in France and Italy are adopting these fiber solutions at accelerated procurement cycles. This convergence is integrating sustainable material credentials with performance specifications that satisfy temperature-variable distribution requirements across Southern European supply chains.
REACH authorization procedures and the EU Green Deal's packaging and packaging waste regulation are mandating design-for-recycling protocols and recycled content verification systems. Industrial consequence includes mandatory third-party certification for fiber sourcing claims and adhesive composition disclosure. Molded pulp divider manufacturers serving German pharmaceutical glass bottlers are most affected, responding with blockchain-tracked agricultural fiber supply chains and water-based adhesive formulations.
Beverage bottlers are consolidating supplier relationships around full-service packaging design partners capable of integrating divider specification with primary container and secondary case optimization. Large European brewery groups are displacing transactional component procurement with multi-year co-development agreements. This restructuring is most visible in Denmark and the Netherlands, where Carlsberg and Heineken procurement teams have compressed their approved divider supplier bases by over half since sustainability target intensification.
Bottle Dividers Market Segmentation
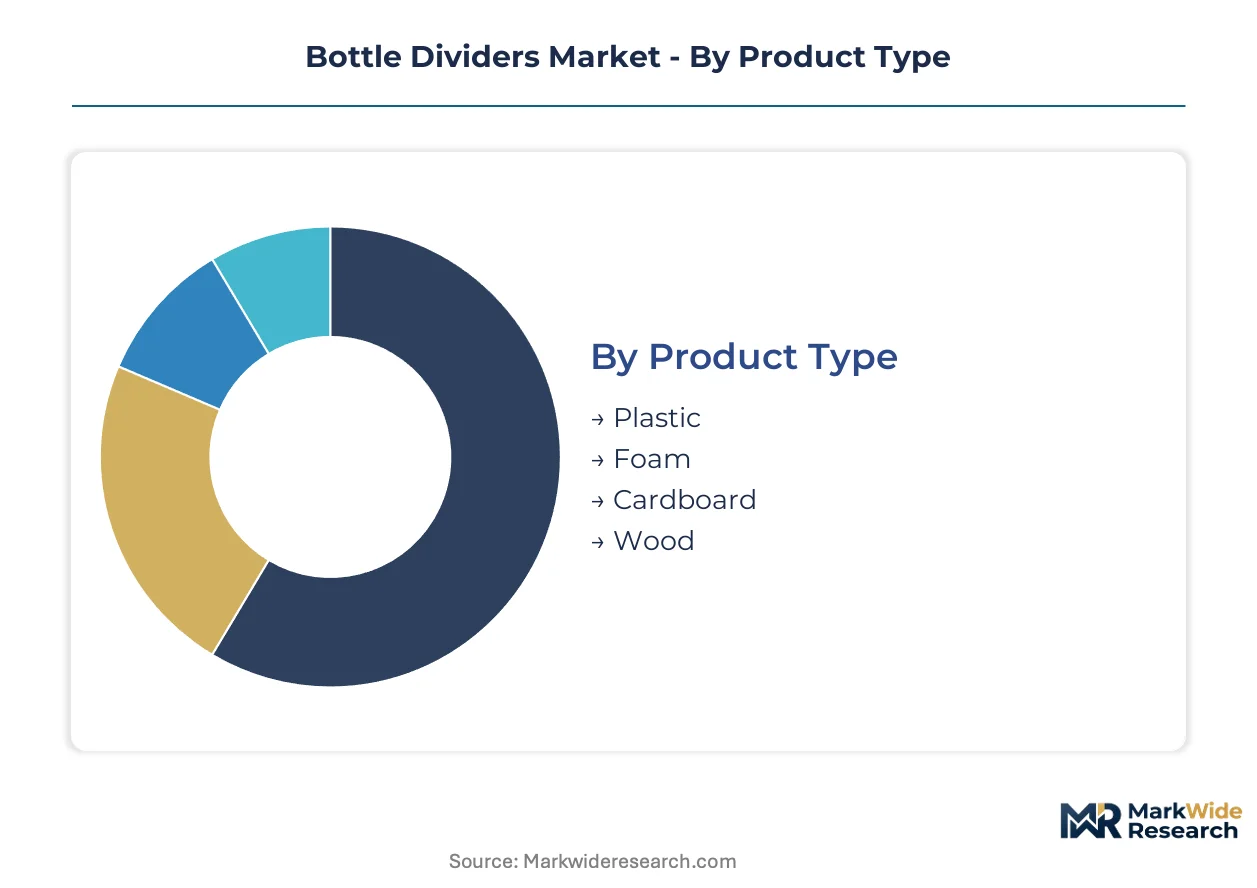
Bottle divider procurement decisions hinge on compliance requirements that vary sharply across material categories and end-use applications. Certification burdens from REACH, FDA food-contact rules, and EU Green Deal recycled content mandates create divergent qualification pathways for each segment, directly shaping supplier selection and portfolio investment priorities.
Product Type:
REACH authorization procedures and FDA food-contact regulations impose distinct compliance burdens on each material formulation, with plastic variants facing the most intensive substance testing and cardboard qualifying more readily under extended producer responsibility frameworks.
- Plastic:Polypropylene and polyethylene dividers dominate reusable crate systems where wash-cycle durability exceeds 50 cycles. German and Danish returnable bottle programs anchor demand, though ECHA scrutiny of polymer additives extends certification timelines.
- Foam:Expanded polystyrene formulations face accelerating substitution pressure from EU single-use plastic restrictions. Remaining demand concentrates in temperature-sensitive pharmaceutical distribution where thermal insulation properties remain unmatched by fiber alternatives.
- Cardboard:Corrugated board constructions carry the lightest regulatory burden for beverage exports entering US distribution channels, with water-based adhesive formulations satisfying FDA indirect food-contact requirements.
- Wood:Hardwood and plywood dividers serve premium spirits presentation cases where aesthetic grain patterns justify higher material costs and FSC chain-of-custody certification.
Cardboard sits at the top of the volume ranking, with plastic climbing the fastest as reusable crate systems expand across Northern European bottling corridors.
Application:
Cost tier differentiation separates commodity shipping applications from value-added retail and beverage segments where design services command margin premiums.
- Beverage Packaging:Craft breweries and premium spirits producers in France, Italy, and Germany drive specialized cell dimension engineering. Molded pulp technologies with nanocellulose barrier treatments are displacing foam in temperature-variable distribution.
- Retail Display:Point-of-sale dividers integrate printed graphics and structural branding elements. French and Italian wine producers prioritize shelf-ready designs that eliminate secondary handling.
- Shipping:E-commerce fulfillment demands stack-strength optimization for mixed-load palletization. Corrugated board dominates with cost-efficient die-cut constructions.
- Storage:Warehouse racking applications emphasize vertical load distribution and moisture resistance for long-duration inventory holding.
Shipping commands the largest volume position, though beverage packaging gains share fastest as sustainability mandates accelerate material substitution in premium bottling segments.
End User:
Procurement sophistication varies dramatically across customer types, with bottling companies deploying technical specification teams while retailers delegate to category managers.
- Bottling Companies:Ardagh and Gerresheimer facilities in the Rhineland and Bavaria operate just-in-time divider procurement with custom cell dimension requirements. Multi-year co-development agreements are displacing transactional purchasing.
- Online Merchants:E-commerce platforms prioritize damage-rate reduction and unboxing experience over unit cost minimization.
- Retailers:Supermarket chains impose sustainability scorecards that favor fiber-based dividers with third-party recycled content certification.
- Warehouses:Third-party logistics providers standardize on generic crate formats that limit custom divider specifications.
Bottling companies represent the highest-value customer tier, with online merchants expanding most quickly as direct-to-consumer beverage shipments proliferate.
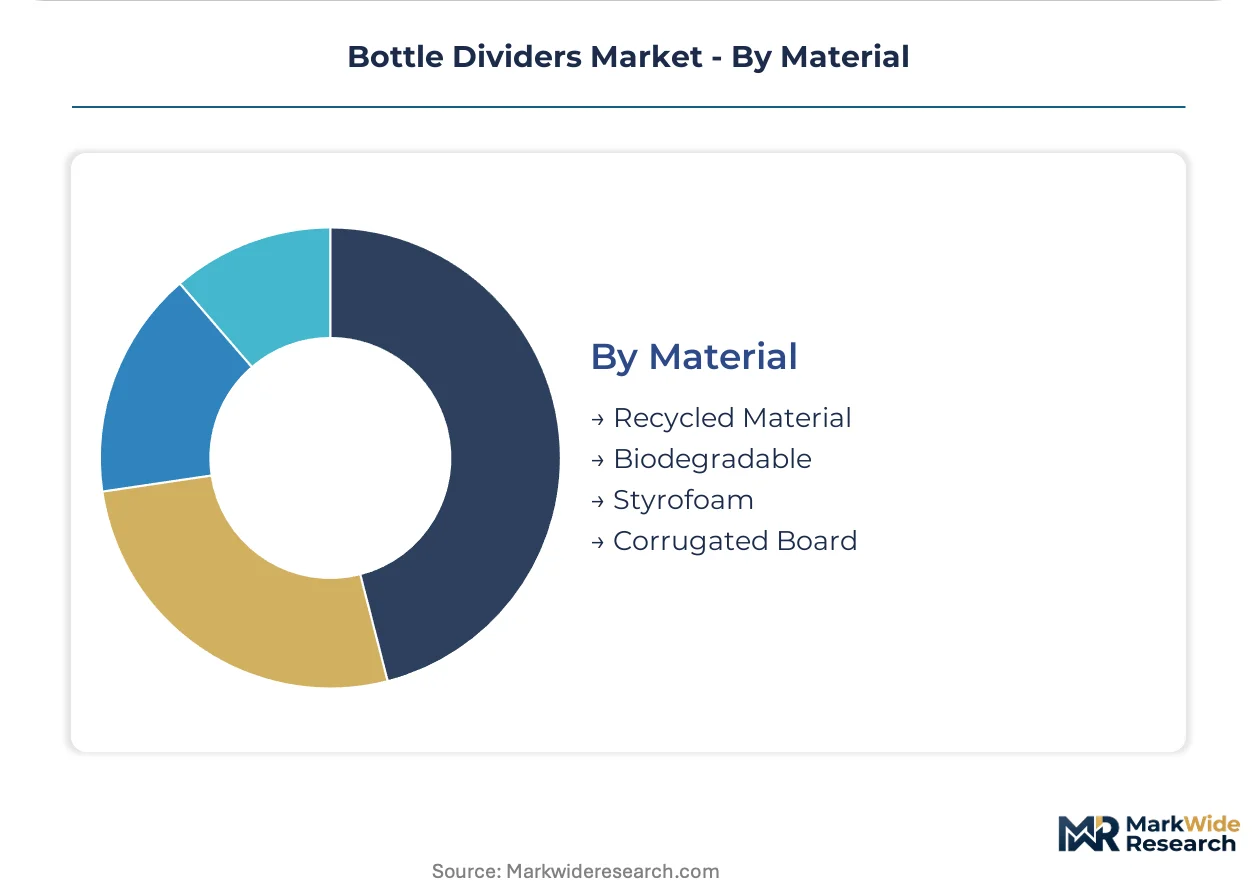
Material:
Supply concentration among Nordic and Central European converter networks shapes availability and lead time differentiation across sustainable material categories.
- Corrugated Board:Recyclability alignment with retailer mandates drives volume leadership. German pharmaceutical glass bottlers demand blockchain-tracked fiber provenance and adhesive composition disclosure.
- Biodegradable:Molded pulp with water-resistant barrier coatings opens high-humidity applications previously blocked by fiber swelling. French and Italian premium wine producers are accelerating procurement cycles.
- Recycled Material:Post-consumer fiber content thresholds are hardening under EU Green Deal implementation, requiring verification systems for environmental claims.
- Styrofoam:Expanded polystyrene faces material-specific bans and environmental contribution fee penalties in France, Italy, and Spain.
Corrugated board holds the dominant volume position, with biodegradable formulations climbing fastest as nanocellulose treatments collapse the performance gap with legacy foam alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping bottle divider procurement patterns as converters relocate capacity to jurisdictions with lower compliance burdens for fiber-based materials. Production migration toward Germany, France, and the Netherlands reflects extended producer responsibility fee structures that penalize plastic alternatives.
Germany
Glass bottling clusters around the Rhineland and Bavaria drive specialized divider demand from Ardagh and Gerresheimer facilities. The EU Green Deal packaging mandates impose recycled content verification requirements that favor corrugated board suppliers with blockchain-tracked fiber provenance. Munich and Stuttgart anchor converter networks serving just-in-time procurement contracts for premium spirits producers.
France
Premium wine producers in Bordeaux and Champagne accelerate molded pulp adoption as nanocellulose barrier treatments match foam performance. Extended producer responsibility frameworks assign lower environmental contribution rates to fiber-based dividers than plastic alternatives. The Île-de-France region concentrates design-to-delivery specialists serving shelf-ready retail display applications.
Italy
Craft brewery expansion in Piedmont and Lombardy pulls demand for custom cell dimension engineering. REACH authorization procedures restrict adhesive formulations in corrugated constructions bound for pharmaceutical glass bottlers. Bologna and Milan host converter networks integrating printed graphics with structural branding elements for point-of-sale applications.
Netherlands
Heineken procurement teams have compressed approved divider supplier bases by over half since sustainability target intensification. The country's central logistics position attracts multi-material converter networks serving Northern European beverage bottling corridors. Rotterdam and Eindhoven anchor facilities specializing in reusable crate system integration for returnable bottle programs.
Denmark
Carlsberg procurement consolidation mirrors Dutch patterns, favoring full-service packaging design partners over transactional component suppliers. Danish returnable bottle programs anchor durable plastic divider demand where wash-cycle durability specifications exceed single-use material performance. Copenhagen concentrates suppliers capable of integrating divider specification with primary container optimization.
Bottle Dividers Market Competitive Environment
Nordic producers anchor one tier; Central European specialists hold converter capacity concentration around beverage bottling corridors. The market structure fragments across multi-material networks rather than consolidating around single-source dominance. Three archetypes define competitive positioning: integrated glass container manufacturers with captive divider sourcing, independent molded pulp specialists, and corrugated converters extending into protective packaging. Capacity expansion and strategic partnerships constitute the dominant competitive moves as sustainability mandates compress transition timelines.
Among Nordic-based protective packaging platforms, Huhtamaki exemplifies the integrated converter archetype extending divider solutions across beverage bottling corridors. German glass container specialists Gerresheimer AG and Ardagh Group S.A. occupy positions within the captive sourcing tier, anchoring procurement networks around Rhineland and Bavaria production facilities. These three entities represent distinct strategic postures: independent platform extension, pharmaceutical-premium beverage integration, and glass manufacturing consolidation with packaging design services.
| Leading Market Players |
|---|
| Estic-Maillot |
| Huhtamaki |
| O-I Glass, Inc |
| Ardagh Group S.A. |
| Anchor Glass Container Corporation |
| Gerresheimer AG |
| Stoelzle Glass Group |
| Ball Corporation |
| Accio |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between pharmaceutical-compliant and standard beverage dividers manifests in parallel pricing and sourcing configurations across European converter networks. Premium tiers command 40-60% markups for REACH-verified adhesive formulations and blockchain-tracked fiber provenance, while commodity beverage segments compete on corrugated board throughput from Nordic multi-material platforms.
Pricing Analysis
Distributor margin layers in German and French bottling corridors absorb 15-25% of converter gate prices before reaching Ardagh and Gerresheimer procurement teams. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden differentiation, with pharmaceutical-grade nanocellulose barriers at the top and generic die-cut corrugated at the base. Cost compression in molded pulp tiers is intensifying because agricultural fiber input volatility has compressed converter margins since energy price spikes. Craft breweries exhibit highest price sensitivity due to batch-scale procurement, while pharmaceutical glass bottlers prioritize compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Nordic converter networks that anchor 70% of EU molded pulp capacity serving Rhineland bottling clusters. Raw material flows draw from Swedish forestry cooperatives, German recycled paper streams, and Dutch agricultural fiber processing. Tariff exposure on specialty adhesive imports from Switzerland creates formulation bottlenecks for REACH-compliant corrugated constructions. Distribution runs through just-in-time logistics corridors linking Bavaria converter hubs to Gerresheimer production facilities with sub-48-hour replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bottle dividers market compounds steadily as EU Green Deal packaging mandates force material substitution cycles that refresh equipment and specification demand every 5-7 years across installed bottling bases.
For Market Incumbents: Deploy nanocellulose barrier R&D to defend against molded pulp specialists encroaching on premium wine and spirits applications. Backward integration into agricultural fiber sourcing secures margin control against pulp price volatility. Capture multi-year co-development agreements with Carlsberg and Heineken procurement teams before supplier base consolidation completes. For New Entrants and Emerging Players: EU Green Deal implementation in France and Italy opens a window for biodegradable barrier coating specialists to penetrate premium wine segments previously blocked by foam incumbents. Target Piedmont craft brewery expansion with design-to-delivery capabilities that bypass established distributor networks. Lead with water-resistant molded pulp demonstrations in high-humidity Southern European distribution corridors. For Investors and Strategic Acquirers: Consolidation pressure builds where converter capacity concentration among Nordic networks limits supplier diversity for German pharmaceutical glass bottlers. The 5-10 year viability frame favors platforms with multi-material flexibility across corrugated, molded pulp, and reusable plastic systems. Watch for REACH authorization delays on adhesive formulations as inflection signals that would accelerate acquisition premiums for compliant converter assets.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Barrier Coating Development | Water-resistant nanocellulose treatments unlock pharmaceutical and high-humidity beverage applications previously dominated by expanded polystyrene. |
| Backward Integration into Fiber Supply | Direct sourcing from Swedish forestry cooperatives and Dutch agricultural processors insulates margins from recycled paper price volatility. |
| Multi-Year Co-Development Agreements | Heineken and Carlsberg procurement consolidation creates preferred supplier status for converters with integrated design-to-delivery capabilities. |
| REACH Compliance Certification Investment | Third-party verification of adhesive formulations and fiber provenance qualifies converters for Gerresheimer pharmaceutical glass contracts. |
| Reusable Crate System Integration | Retrofit expertise for legacy German and Danish returnable bottle programs captures durable plastic divider demand exceeding single-use alternatives. |
Study Parameters
Direct dialogue with converter plant managers, beverage bottler procurement directors, corrugated equipment engineers, and ECHA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from EU packaging waste directive filings, extended producer responsibility fee schedules in France and Italy, customs data on molded pulp trade flows, and SEC disclosures from integrated glass container manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across material categories and end-use applications.
Bottom-up segmentation analysis modeled corrugated board, molded pulp, plastic, and foam volumes by beverage packaging, retail display, shipping, and storage applications throughout the forecast period. Price points were calibrated against certification tier, volume scale, and geographic delivery cost differentials. CAGRs were derived from trend extrapolation of EU Green Deal compliance timelines and substitution elasticity estimates for foam-to-fiber transitions in premium spirits segments.
Revisions become necessary when REACH authorization timelines for adhesive formulations accelerate or delay, when pulp fiber input costs destabilize beyond historical bands, or when major bottlers consolidate supplier bases faster than modeled. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Fruit Juice Packaging Market
Beverage Packaging
French Square Bottle Market
Beverage Packaging
Baritainer Jerry Can Market
Beverage Packaging
Multicomponent Bottle Market
Beverage Packaging
Light Water Tap Market
Beverage Packaging
Global Beverage Container Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Pre-Made Cups Market
Beverage Packaging
Pouring Spout Market
Beverage Packaging
Media Bottles Market