
 Media Bottles Market | 2026-2036
Media Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Media Bottles Market Foresight
Asset-light leasing arrangements for pharmaceutical-grade glass molding equipment is reconfiguring competitive entry barriers across the media bottles landscape. Gerresheimer leverages captive borosilicate sourcing to sustain margin stability in European laboratory supply chains. Owens-Illinois Inc. anchors North American beverage-grade capacity while competing for crossover pharmaceutical contracts. Stoelzle Glass Group specializes in small-batch decorative and technical glass, occupying premium niche positions that larger volume players cannot replicate.
Media bottles are rigid containers engineered from borosilicate glass, soda-lime glass, or polymer resins such as HDPE and PET, typically manufactured via blow molding or tubular conversion processes to achieve precise neck finish tolerances and sterility assurance levels. These vessels store cell culture media, reagents, and liquid formulations where chemical inertness, thermal shock resistance, and barrier integrity determine experimental or production outcomes. Plastic and HDPE segments lead volume in single-use laboratory workflows where breakage risk and disposability outweigh optical clarity requirements. Glass dominates pharmaceutical applications where USP Type I certification and autoclave compatibility command price premiums and lock in supplier relationships through validation protocols.
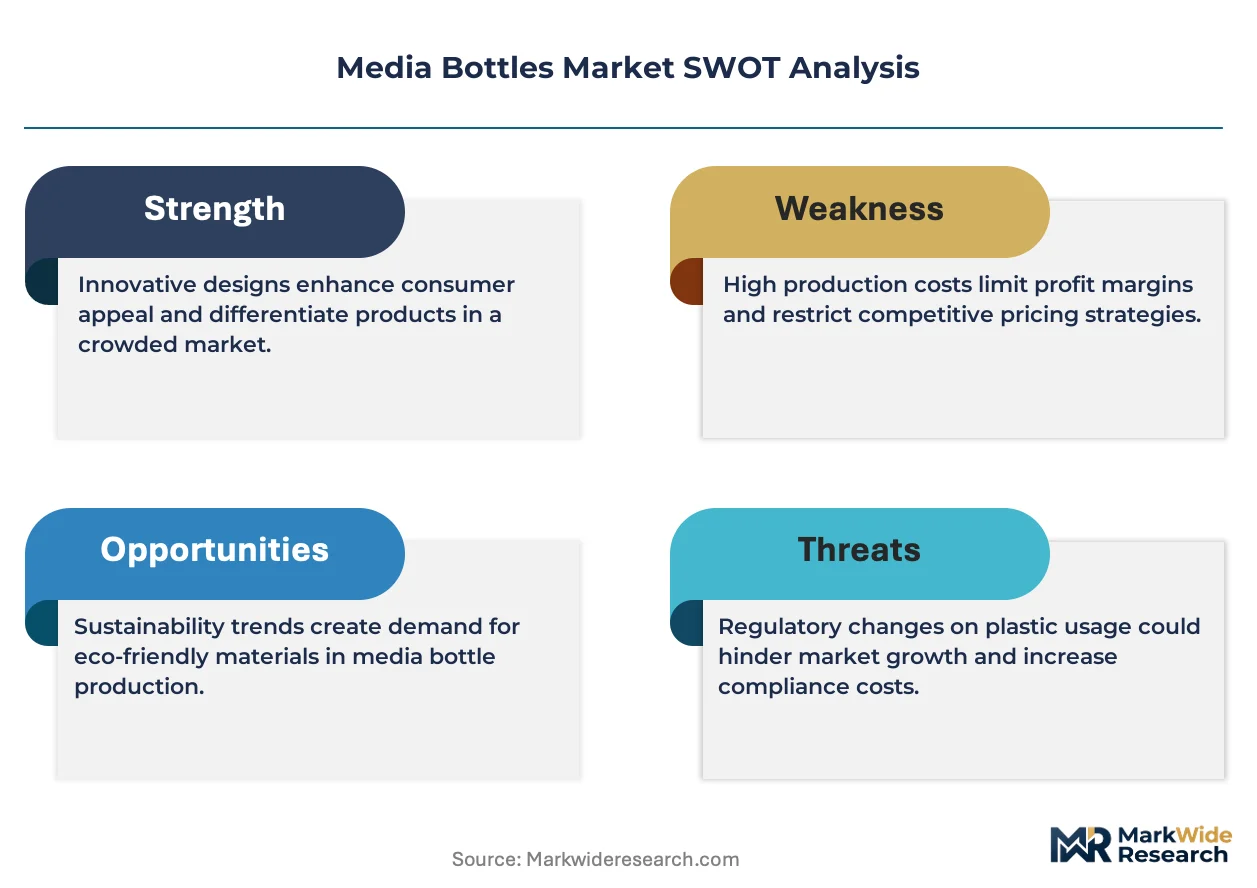
FDA 21 CFR Part 211 cGMP requirements and EMA Annex 1 sterile manufacturing guidelines shape material selection, cleaning validation, and documentation burdens for media bottle suppliers serving regulated end users. ISO 15378 primary packaging standards for medicinal products further constrain design flexibility while creating compliance moats for incumbent manufacturers with established quality management systems. Stakeholders must monitor evolving EU Green Deal packaging waste directives and state-level extended producer responsibility frameworks in California and New York, as recycled content mandates threaten to disrupt virgin glass and polymer cost structures without equivalent supply chain preparation.
Market Dynamics
EMA serialization mandates and FDA cGMP enforcement are compressing supplier qualification timelines while biologics manufacturers demand autoclave-compatible borosilicate formulations that lock in multi-year validation cycles.
Growth Catalysts
- Biologics manufacturing expansion:Cell therapy facilities in the United States are scaling sterile media bottle procurement to meet FDA 21 CFR Part 211 validation requirements.
- ISO 15378 certification barriers:Primary packaging standards for medicinal products create compliance moats that protect incumbent manufacturers with established quality management systems.
- Borosilicate thermal shock resistance:Enhanced chemical formulations are displacing soda-lime alternatives in high-purity pharmaceutical applications where USP Type I certification commands price premiums.
Market Restraints
- Energy-intensive glass melting:Natural gas price volatility in European manufacturing clusters directly compresses margin structures for borosilicate converters.
- Captive borosilicate sourcing concentration:Germany and Switzerland anchor specialty glass sand supply, exposing downstream molders to geopolitical disruption risk.
- Single-use polymer substitution:HDPE and PET bottles in diagnostic workflows eliminate breakage risk and autoclave burden, constraining glass volume in non-pharmaceutical segments.
Strategic Opportunities
- Asset-light equipment leasing:Pharmaceutical-grade glass molding machinery rental models lower capital barriers for regional entrants targeting GMP-certified contracts.
- EU Green Deal packaging mandates:Recycled content directives create first-mover advantage for suppliers with prepared post-consumer glass supply chains.
- Small-batch decorative positioning:Technical glass specialists occupy premium niche segments that high-volume commodity players cannot replicate profitably.
Industry Challenges
- Cleaning validation documentation:EMA Annex 1 sterile manufacturing guidelines impose extensive extractables and leachables testing burdens that extend supplier onboarding timelines.
- Legacy ERP integration:Serialization track-and-trace systems require substantial middleware investment to connect with existing manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Media Bottles Market |
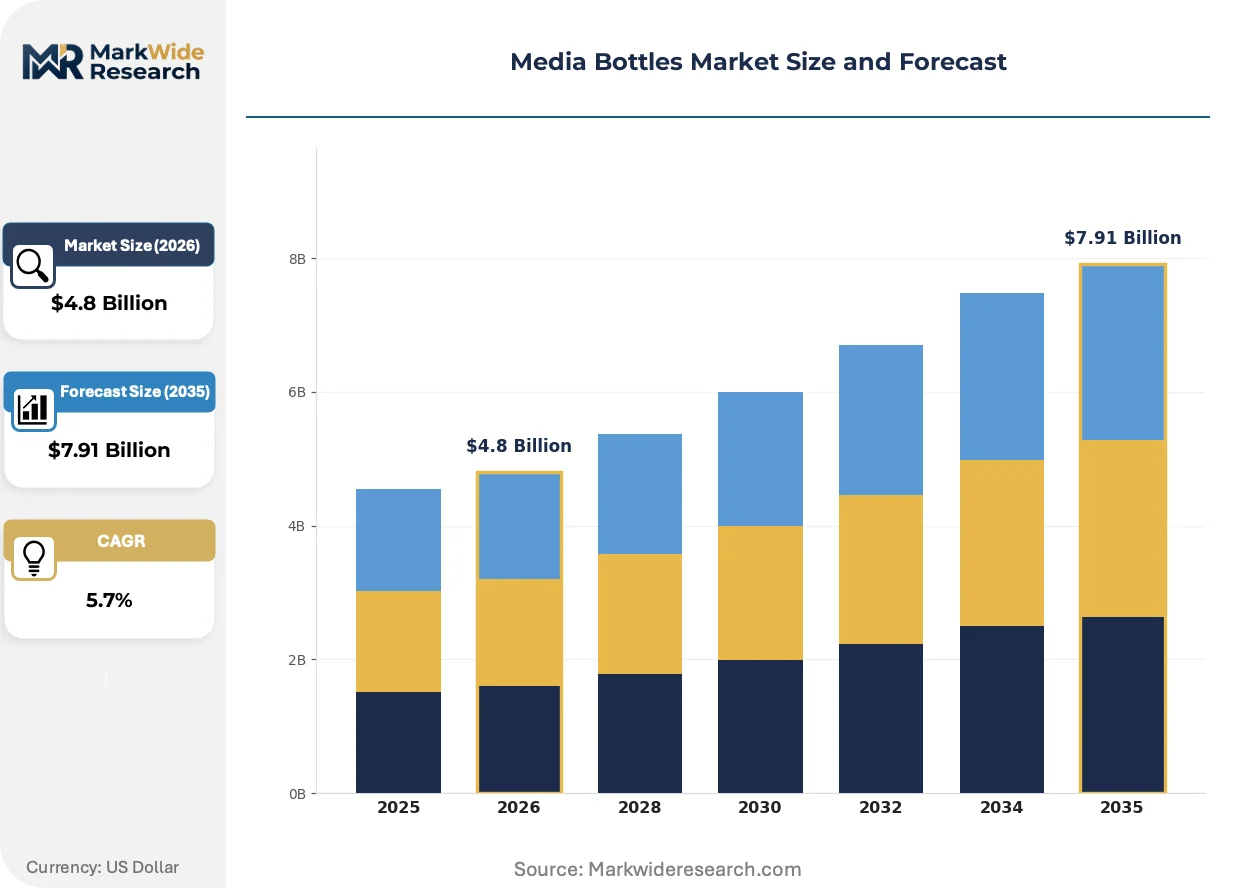
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Aluminum, HDPE Cap Type: Screw Cap, Pump Cap, Flip Top, Stopper End User: Laboratories, Pharmaceutical, Beverage Industry, Food Processing Distribution Channel: Online Retail, Specialty Stores, Distributors, Wholesalers |
| Companies Covered | Vidrala, Stoelzle Glass Group, Owens-Illinois Inc., Bormioli Rocco, Saverglass, Ardagh Group, Saver Glass, Gerresheimer, Verallia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Media Bottles Market Shifts & Advancements
Digital serialization infrastructure and sustainable material formulations are restructuring competitive advantage in media bottle supply chains, with validation protocols and carbon accounting emerging as decisive differentiators.
Tubular borosilicate conversion with precision neck finish tolerances is rendering obsolete traditional molded glass methods in high-throughput pharmaceutical filling lines. Contract manufacturing organizations in the United States and Germany are adopting these formats to minimize particle contamination and reduce line clearance times. The shift is compressing acceptable defect rates and locking in supplier relationships through multi-year validation investments.
EMA Annex 1 sterile manufacturing guidelines now mandate barrier technology and isolator systems for media bottle filling operations. This regulatory pressure is accelerating capital deployment in closed-system processing infrastructure across European biologics facilities. Glass suppliers must now engineer container closure integrity specifications that align with automated isolator handling requirements.
Consolidated buying by large pharmaceutical conglomerates is compressing supplier bases and unbundling after-sales technical service from base container pricing. Procurement teams in United States-based biotech clusters now demand dedicated field application scientists as contract terms rather than optional add-ons. This behavioral shift squeezes mid-tier suppliers lacking technical service infrastructure while rewarding vertically integrated manufacturers with in-house regulatory affairs capabilities.
Media Bottles Market Segmentation
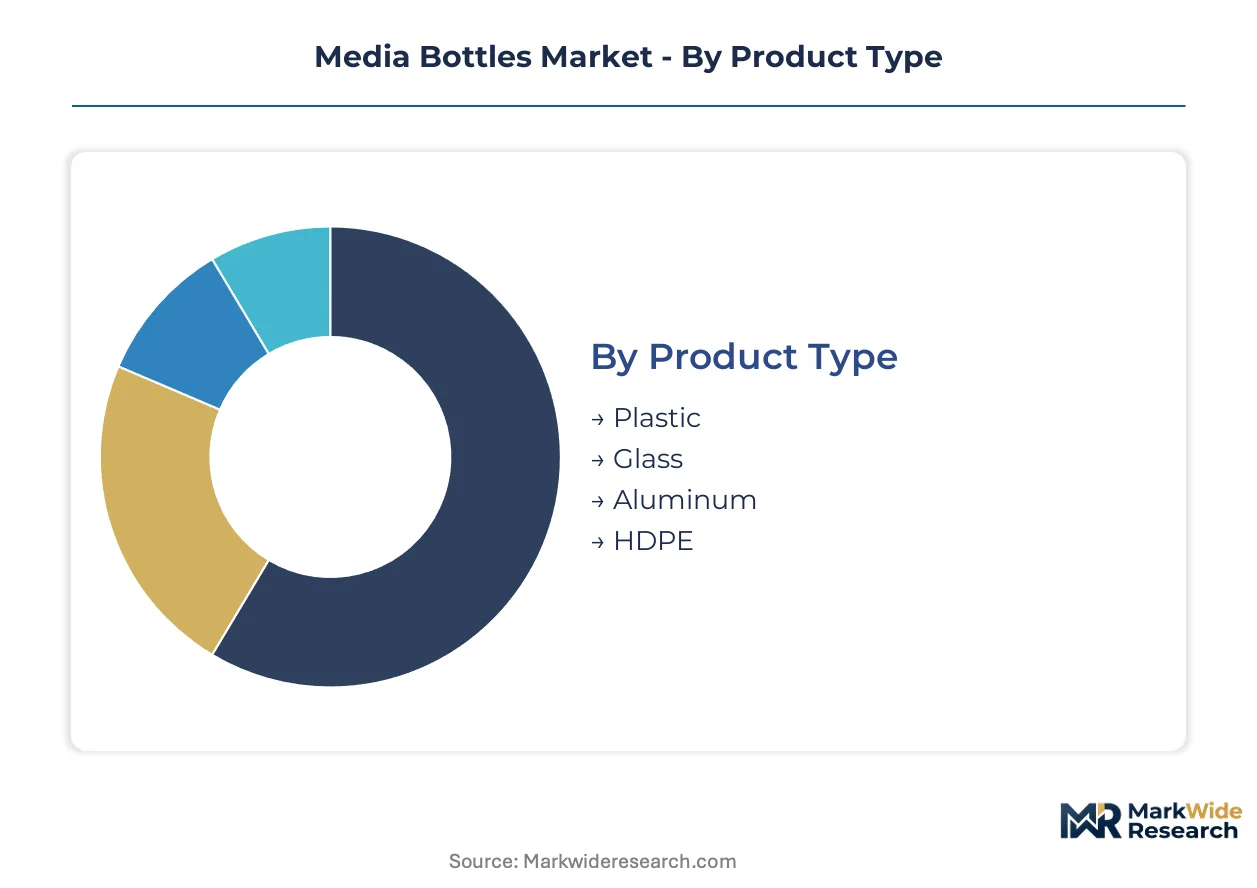
Media bottles serve divergent performance requirements across laboratory, pharmaceutical, and industrial workflows. Material selection and closure design determine sterilization compatibility, barrier integrity, and regulatory qualification pathways for end users.
Product Type:
Glass formulations command extended validation cycles measured in years, while polymer alternatives turn over on monthly procurement schedules in high-throughput diagnostic settings.
- Plastic:Polymer formulations including PET and copolyester deliver shatter resistance and disposability for single-use bioprocessing workflows. Diagnostic laboratories in the United States are scaling HDPE and PET procurement to eliminate autoclave bottlenecks and reduce particle contamination risk in cell culture applications.
- Glass:Borosilicate and soda-lime compositions provide USP Type I certification and thermal shock resistance for parenteral drug storage. EMA serialization mandates and FDA 21 CFR Part 211 requirements are locking pharmaceutical manufacturers into multi-year supplier validation cycles for borosilicate media bottles.
- Aluminum:Lightweight metal containers serve specialized light-sensitive reagent storage with electromagnetic shielding properties.
- HDPE:High-density polyethylene offers chemical resistance and cost efficiency for non-sterile buffer and media preparation in research settings.
Glass dominates installed base in validated pharmaceutical applications. Plastic is where expansion concentrates in high-throughput diagnostic and research workflows.
Cap Type:
Closure selection maps directly to aseptic handling requirements and line automation compatibility, with screw formats anchoring standardization and pump mechanisms commanding specialty premiums.
- Screw Cap:Threaded closures with standardized GL45 and GL38 neck finishes enable automated capping torque validation and secure seal integrity for long-term media storage. Pharmaceutical filling lines in Germany are standardizing screw cap formats to minimize changeover downtime and align with EMA Annex 1 isolator handling requirements.
- Pump Cap:Metered-dispensing closures reduce contamination risk in cell culture media aliquoting. Biologics manufacturing facilities are adopting pump cap configurations for sterile connection systems that eliminate open-vessel transfers.
- Flip Top:Hinged closures enable single-handed access for high-frequency sampling workflows in quality control laboratories.
- Stopper:Elastomeric and aluminum-seal stoppers provide hermetic sealing for lyophilized and parenteral formulations requiring vacuum integrity.
Screw cap formats anchor volume scale across regulated and research segments. Pump cap configurations are climbing the fastest as closed-system processing requirements expand.
End User:
Customer procurement patterns split between validation-intensive pharmaceutical contracts and transactional laboratory supply arrangements with diverging technical service expectations.
- Laboratories:Research and quality control facilities prioritize optical clarity, chemical inertness, and rapid procurement turnaround. Academic and contract research organizations in the United States are consolidating supplier bases to secure volume pricing on borosilicate and plastic media bottles while reducing vendor qualification overhead.
- Pharmaceutical:Drug manufacturers demand documented extractables and leachables profiles, container closure integrity data, and regulatory filing support. FDA cGMP enforcement and EMA serialization mandates are extending supplier onboarding timelines and locking in incumbent relationships through validation protocol alignment.
- Beverage Industry:Flavor and ingredient sampling applications require food-grade compliance and batch traceability for quality assurance programs.
- Food Processing:Microbiological testing workflows utilize sterile media bottles for culture preparation and pathogen detection protocols.
Pharmaceutical end users concentrate value capture through multi-year validation contracts. Laboratory procurement is gaining share fastest as single-use workflows expand in cell therapy research.
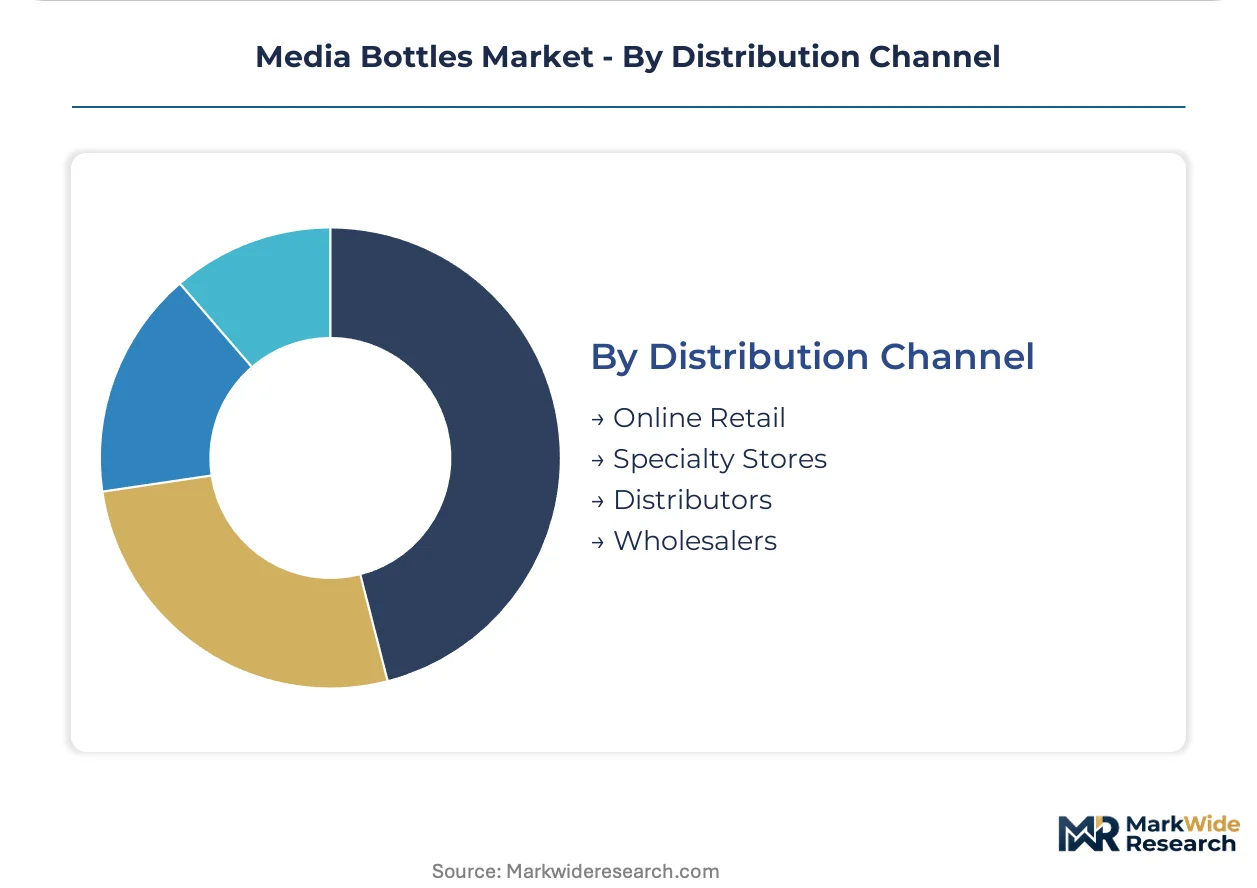
Distribution Channel:
Channel selection reflects order fragmentation patterns, with bulk pharmaceutical procurement favoring direct distributor relationships and research replenishment migrating to digital platforms.
- Online Retail:E-commerce platforms enable rapid replenishment for research laboratories with predictable consumption patterns. Small and mid-sized laboratories in the United States are shifting procurement to online channels to bypass distributor markups and accelerate delivery timelines for standard borosilicate and HDPE formats.
- Specialty Stores:Regional laboratory supply retailers provide same-day availability and technical consultation for urgent replenishment needs.
- Distributors:Authorized distribution partners manage regulatory documentation, lot traceability, and consignment inventory for pharmaceutical manufacturers.
- Wholesalers:Volume aggregators serve price-sensitive research institutions with standardized product configurations and extended payment terms.
Distributors dominate pharmaceutical value capture through validation support services. Online retail is expanding most quickly in research and academic procurement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 211 enforcement and EMA serialization mandates are redirecting procurement toward validated supply chains in jurisdictions with established GMP infrastructure. Biologics manufacturing expansion and laboratory automation are concentrating demand in specific national clusters with ready access to borosilicate glass converters and polymer molding capacity.
United States
Cell therapy facilities in Massachusetts and North Carolina are scaling sterile media bottle procurement to meet FDA validation timelines. The Biologics Price Competition and Innovation Act framework accelerates biosimilar manufacturing, tightening supply chains for USP Type I certified packaging. Greater Boston anchors contract manufacturing demand where multi-year supplier qualification cycles lock in incumbent relationships.
Germany
Pharmaceutical laboratories in Baden-Württemberg and Bavaria are expanding borosilicate media bottle orders to satisfy EMA Annex 1 sterile manufacturing requirements. The EU Green Deal packaging waste directives are pressuring converters to secure post-consumer glass supply chains ahead of recycled content mandates. The Rhine-Main cluster hosts specialized glass molders with captive borosilicate sourcing from domestic sand deposits.
China
Biologics CDMOs in Jiangsu and Zhejiang provinces are upgrading to GMP-certified packaging to serve export markets under NMPA oversight. The 14th Five-Year Plan prioritizes domestic production of high-purity pharmaceutical glass, displacing imported borosilicate in selected applications. The Yangtze River Delta concentrates polymer molding capacity for single-use diagnostic workflows.
India
Vaccine manufacturers in Maharashtra and Telangana are qualifying media bottle suppliers under CDSCO Schedule M requirements for sterile manufacturing. Production-linked incentive schemes for active pharmaceutical ingredients extend to primary packaging components, attracting capital deployment in domestic molding capacity. The Hyderabad-Visakhapatnam corridor anchors biologics fill-finish operations with escalating packaging documentation demands.
Switzerland
Specialty pharmaceutical manufacturers in Basel and Zurich are specifying enhanced chemical resistance formulations for high-value parenteral applications. Swissmedic guidelines on container closure integrity align with EMA standards, extending validation protocol burdens to upstream suppliers. The Basel-Liestal industrial zone concentrates precision glass conversion for clinical trial material packaging.
Media Bottles Market Competitive Landscape
On the supply side, the industry is bifurcated between high-volume commodity converters and validated pharmaceutical specialists with captive quality infrastructure. Tiered competitive positioning separates asset-light regional molders from vertically integrated manufacturers with in-house borosilicate sourcing. Three archetypes dominate: European heritage glass houses with EMA-aligned validation protocols, North American beverage-grade converters competing for crossover pharma contracts, and Asian polymer specialists serving single-use diagnostic workflows. Capacity expansion and strategic partnerships represent the dominant competitive moves, with equipment leasing models lowering regional entry barriers.
Among European heritage specialists, Gerresheimer and Stoelzle Glass Group exemplify divergent positioning within the premium tier. Gerresheimer represents the vertically integrated archetype with captive borosilicate supply chains sustaining margin stability across validation-intensive contracts. Stoelzle occupies a position as technical glass specialist where small-batch decorative and precision capabilities resist commoditization pressures that constrain high-volume competitors. Owens-Illinois Inc. anchors the North American beverage-grade segment while competing for pharmaceutical crossover opportunities where existing furnace capacity can accommodate USP Type I certification requirements.
| Leading Market Players |
|---|
| Vidrala |
| Stoelzle Glass Group |
| Owens-Illinois Inc. |
| Bormioli Rocco |
| Saverglass |
| Ardagh Group |
| Saver Glass |
| Gerresheimer |
| Verallia |
| Others |
Supply & Pricing Matrix
Single-source borosilicate sand dependency in Germany and Switzerland compresses margin buffers for downstream molders while simultaneously widening spreads between validated pharmaceutical-grade and commodity laboratory formats. This concentration dynamic forces buyers into multi-year contract lock-ins for USP Type I certified supply, even as spot-market HDPE alternatives erode pricing power in non-regulated segments.
Pricing Analysis
Certification level creates the primary spread between USP Type I borosilicate and standard soda-lime alternatives, with three-tier pricing structure across premium, standard, and economy levels anchoring the market. Glass converters command sustained premiums through EMA-aligned validation protocols, while HDPE suppliers compete on volume scale and disposability. Cost compression in diagnostic-grade polymer segments is intensifying because single-use workflows eliminate autoclave infrastructure burdens. Academic laboratories exhibit highest price sensitivity, whereas pharmaceutical manufacturers prioritize supplier qualification depth over unit economics.
Supply Chain Analysis
Contract manufacturing organizations in the United States and Germany hold the dominant share of GMP-certified filling capacity, with secondary clusters emerging in Switzerland and India for clinical trial materials. Specialty glass sand deposits in the Rhine-Main and Basel-Liestal corridors feed captive borosilicate conversion, while polymer resin supply draws from petrochemical complexes along the US Gulf Coast and Yangtze River Delta. Single-source vulnerability in European borosilicate sourcing exposes the chain to geopolitical disruption. Distribution runs through authorized partners managing regulatory documentation and consignment inventory for pharmaceutical end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service bundling now expands faster than base container sales, as pharmaceutical procurement teams demand embedded field application scientists and regulatory filing support as standard contract terms rather than optional add-ons.
For Market Incumbents: Entrench position by deepening captive borosilicate sourcing relationships and expanding isolator-compatible container closure engineering capabilities. Single-use polymer substitution in diagnostic workflows threatens glass volume in non-pharmaceutical segments, requiring incumbents to anchor pharmaceutical validation cycles as the defensive moat. Certification investment in EU Green Deal recycled content pathways secures first-mover positioning ahead of mandate implementation.
For New Entrants and Emerging Players: Pursue asset-light equipment leasing models to bypass capital barriers for regional GMP-certified contracts. Small-batch decorative and technical glass niches offer penetrable entry points where Stoelzle-style precision capabilities resist commoditization. Go-to-market through dedicated technical service teams rather than price-competing on standardized formats.
For Investors and Strategic Acquirers: EMA serialization mandate implementation reshapes the acquisition landscape by extending supplier onboarding timelines and inflating the value of incumbent validation relationships. Five-to-ten year viability favors vertically integrated molders with captive sand sourcing and established quality management systems. Watch for consolidation signals among mid-tier distributors lacking technical service infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Sourcing | Captive sand supply from German deposits insulates margin stability against energy price volatility. |
| Isolator-Compatible Container Engineering | EMA Annex 1 compliance requirements lock in multi-year validation relationships with biologics manufacturers. |
| Technical Service Team Expansion | Embedded field application scientists meet pharmaceutical procurement demands for regulatory filing support. |
| Recycled Content Supply Chain Development | EU Green Deal mandates create first-mover advantage for prepared post-consumer glass infrastructure. |
| Asset-Light Equipment Leasing Programs | Regional entrants bypass capital barriers to compete for GMP-certified pharmaceutical contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory procurement managers, pharmaceutical packaging engineers, regulatory affairs specialists, and contract manufacturing executives. Secondary validation drew from FDA 21 CFR filings, EMA serialization guidance documents, ISO 15378 certification registries, and customs trade data on glass and polymer container flows. Bottom-up segmentation modeling triangulated against top-down industry association aggregates to reconcile volume estimates.
Calibration anchored historical shipment data against capacity utilization disclosures from major borosilicate converters and polymer molders. Segmentation dimensions spanned material type, certification grade, end-user regulatory intensity, and geographic production cluster. CAGRs were derived from trend-line extrapolation moderated by scenario-weighted regulatory implementation timelines. Forecast inputs incorporated biologics manufacturing capacity expansion pipelines and EU packaging waste directive compliance schedules.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, freight rate indices, or pharmaceutical R&D expenditure would shift the trajectory. Quarterly review of borosilicate sand spot prices, GMP facility approval cadence, and single-use polymer substitution rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Bullet Bottles Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Cup Carriers Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Self-Chilling Can Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Bottled Water Packaging Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
United States Aluminum Beverage Cans Market
Beverage Packaging
Foldable Bottles Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Sugarcane Bottles Market
Beverage Packaging
Beverage Can Ends Market
Beverage Packaging
Biotainer Market