
 Cup Carriers Market | 2026-2036
Cup Carriers Market Size, Share, and Industry Trends Forecast 2026-2036
Cup Carriers Market Analysis
Aftermarket customization revenue is fragmenting across cup carrier producers as brand owners demand logo-printed, seasonal-design, and limited-run variants alongside standard SKUs. Smurfit Kappa Group leverages its European corrugated network to anchor supply for quick-service chains. Cellulopack specializes in molded fiber formats that compete on compostability credentials with plastic incumbents. Shenzhen CyGedin Printing & Packaging dominates export manufacturing through integrated printing and die-cutting operations.
Cup carriers are rigid or semi-rigid holders engineered to transport one to six beverage cups securely, typically constructed from corrugated cardboard, molded pulp, or expanded polystyrene with die-cut apertures or formed cavities that prevent spillage during transit. Cardboard and biodegradable materials lead volume as quick-service restaurants phase out foam under regulatory pressure, while plastic persists in wet-climate markets where moisture resistance governs procurement. Four-cup and six-cup configurations represent the fastest-growing size category, driven by group-ordering apps and delivery-platform economics that favor consolidated transport.
The EU Single-Use Plastics Directive and REACH chemical frameworks restrict foam and certain plastic additives, while the FDA governs food-contact material safety in the United States and China's SAMR enforces GB standards on packaging recyclability. These overlapping compliance regimes force manufacturers to maintain multi-certificate production lines or risk exclusion from major foodservice accounts. Stakeholders must monitor regulatory divergence between compostability certifications in Europe and the United States to avoid stranded inventory in cross-border supply chains.
Market Dynamics
The EU Single-Use Plastics Directive is compressing foam carrier demand while forcing rapid material substitution across European foodservice supply chains. Quick-service chains now face simultaneous mandates from Brussels and divergent state-level packaging laws in the United States.
Growth Catalysts
- REACH chemical restrictions:ECHA classifications on expanded polystyrene additives are accelerating molded fiber adoption in Germany and France. Foodservice operators preemptively reformulate packaging to avoid downstream liability.
- Delivery-platform economics:Group-ordering apps favor four-cup and six-cup configurations that reduce per-unit delivery costs. Restaurants redesign menus around shareable beverage bundles to capture this traffic.
- Quick-service restaurant expansion:Drive-thru format growth in suburban US markets drives carrier procurement for high-volume beverage transactions. Chains specify carriers compatible with automated handoff systems.
Market Restraints
- Recycled pulp cost volatility:OCC (old corrugated containers) pricing swings compress margins for molded fiber producers. European mills face energy cost premiums that Asian competitors avoid.
- Moisture resistance gap:Biodegradable carriers degrade in humid climates where plastic alternatives maintain structural integrity. Southeast Asian operators retain EPS formats despite regulatory pressure.
- Multi-certificate production burden:Manufacturers serving both EU and US markets must maintain separate compostability certifications. BPI and TÜV Austria OK compost HOME standards lack mutual recognition.
Strategic Opportunities
- India foodservice packaging modernization:FSSAI plastic phaseout timelines create first-mover advantage for fiber-based carriers. Quick-service chains in Mumbai and Bangalore trial molded pulp formats for delivery.
- RFQ-to-delivery platform integration:Digital procurement systems now embed sustainability scoring alongside unit economics. Carriers with blockchain-tracked material origins command placement preference.
- Seasonal customization services:Limited-run printed carriers for holiday promotions generate 3-4x unit premiums over standard SKUs. Brand owners outsource design-to-delivery programs rather than managing inventory.
Industry Challenges
- Composting infrastructure mismatch:Industrial composting facility scarcity in the United States strands biodegradable carriers in landfill streams. Operators face greenwashing litigation risk despite material compliance.
- Die-cutting precision tolerances:Automated beverage dispensing systems require aperture dimensional consistency within 0.5 millimeters. Quality control investments separate contract manufacturers from commodity suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cup Carriers Market |
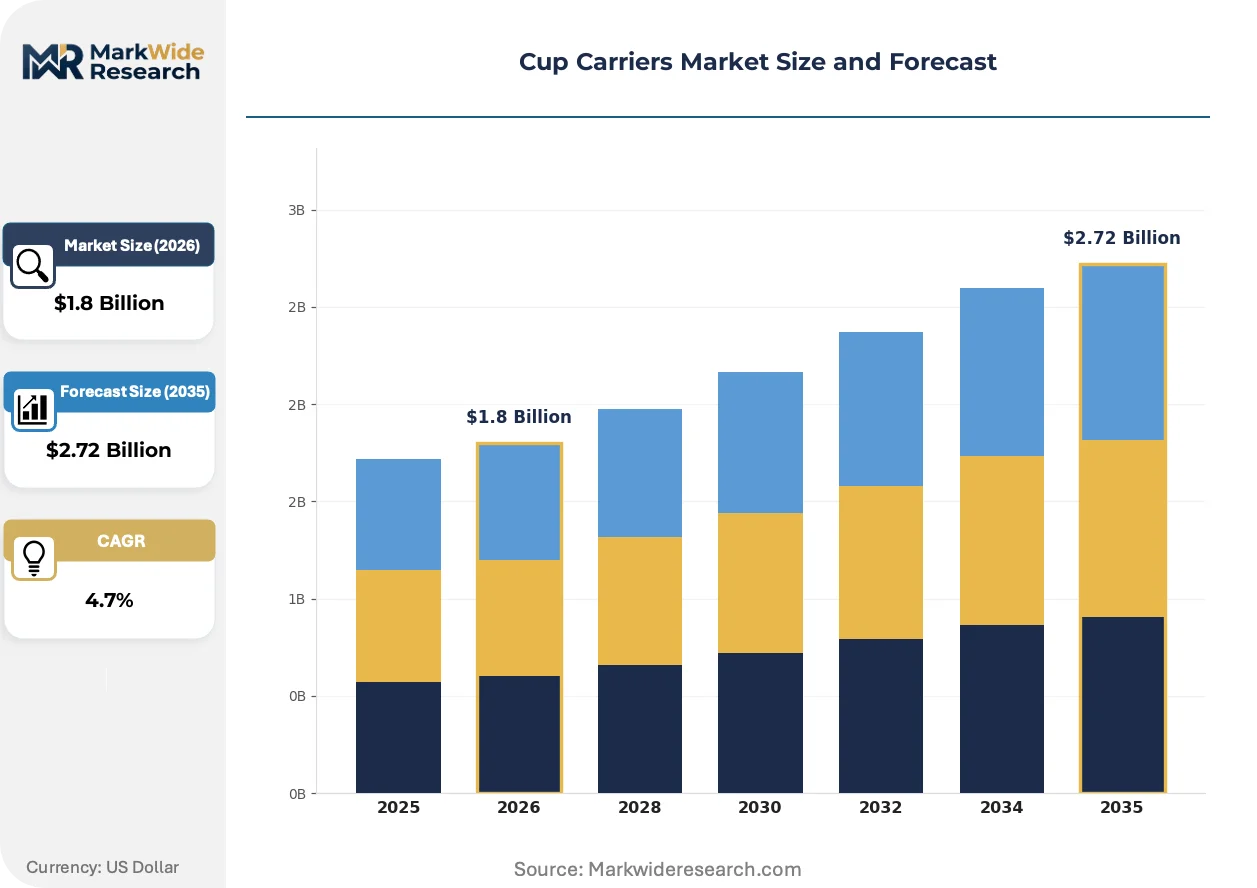
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Plastic, Biodegradable, Foam Size Type: Single Cup, Double Cup, Four Cup, Six Cup End User: Cafes, Restaurants, Food Trucks, Convenience Stores Design Type: Flat, With Handles, Customized, Eco-Friendly |
| Companies Covered | The Paper Cup Company, The VaioPak Group, Southern Champion Tray, Shenzhen CyGedin Printing & Packaging, E-Package Creation & Solution Manufacturing, Cellulopack, Hangzhou Longquan Industrial, Smurfit Kappa Group, The Brenmar Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cup Carriers Market Emerging Trajectories
Material science breakthroughs and regulatory sequencing are compressing product lifecycles while fragmenting procurement specifications across geographies. Carriers must now satisfy functional, aesthetic, and traceability requirements simultaneously.
Smart packaging integration is digitizing supply chain visibility for temperature-sensitive beverage delivery. Quick-service chains in South Korea and Japan embed NFC-enabled carriers that confirm cold-chain integrity upon customer receipt. The data streams compress insurance premiums and liability exposure for delivery platforms.
REACH Annex XVII restrictions on intentionally added microplastics are forcing reformulation of barrier coatings for fiber carriers. German foodservice packaging producers now specify plant-based wax alternatives that maintain grease resistance. The regulatory sequencing creates 12-18 month compliance windows that favor prepared suppliers over reactive competitors.
Consolidated procurement through group purchasing organizations is compressing supplier rosters for multi-chain operators. US-based quick-service holding companies now mandate uniform sustainability specifications across franchise networks. Regional carriers face exclusion unless they achieve national-scale certification and logistics capability.
Cup Carriers Market Segmentation
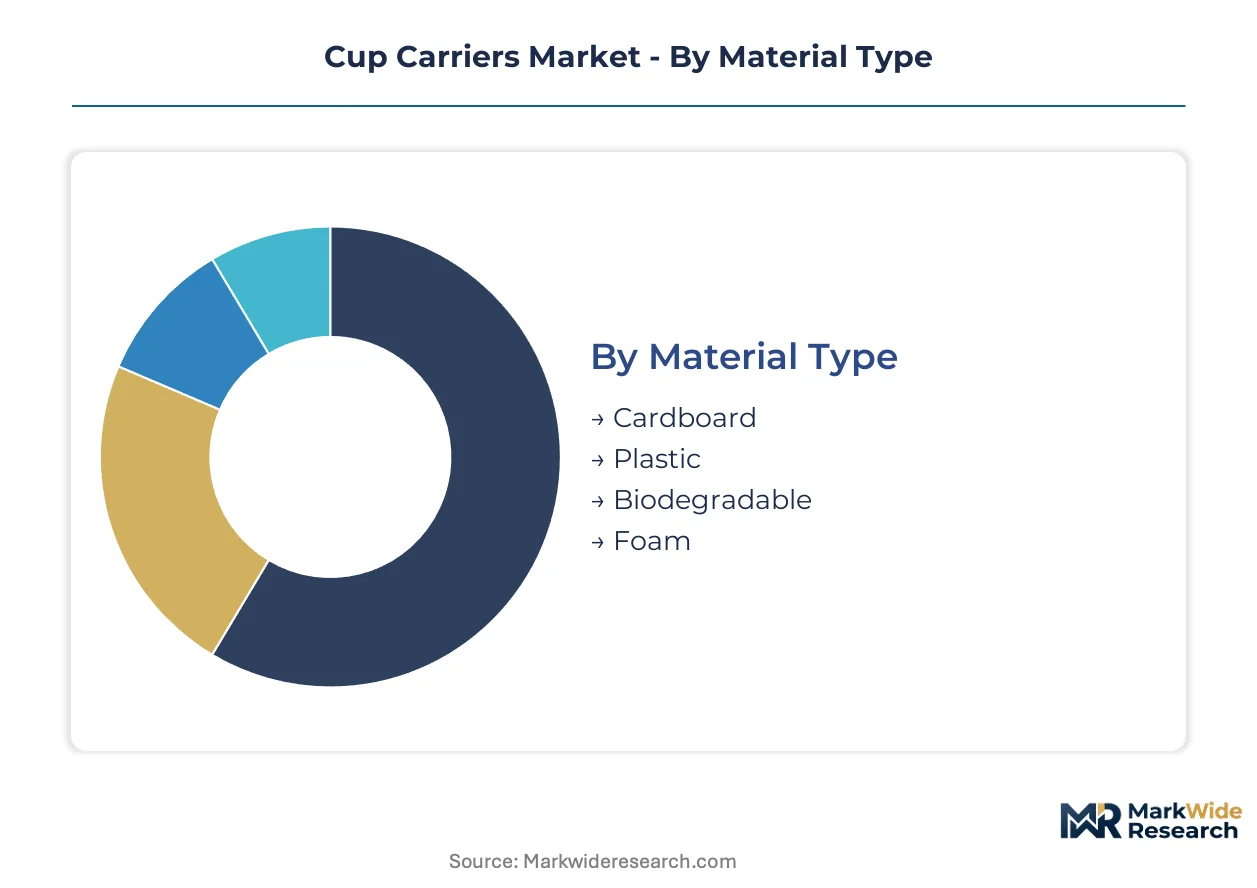
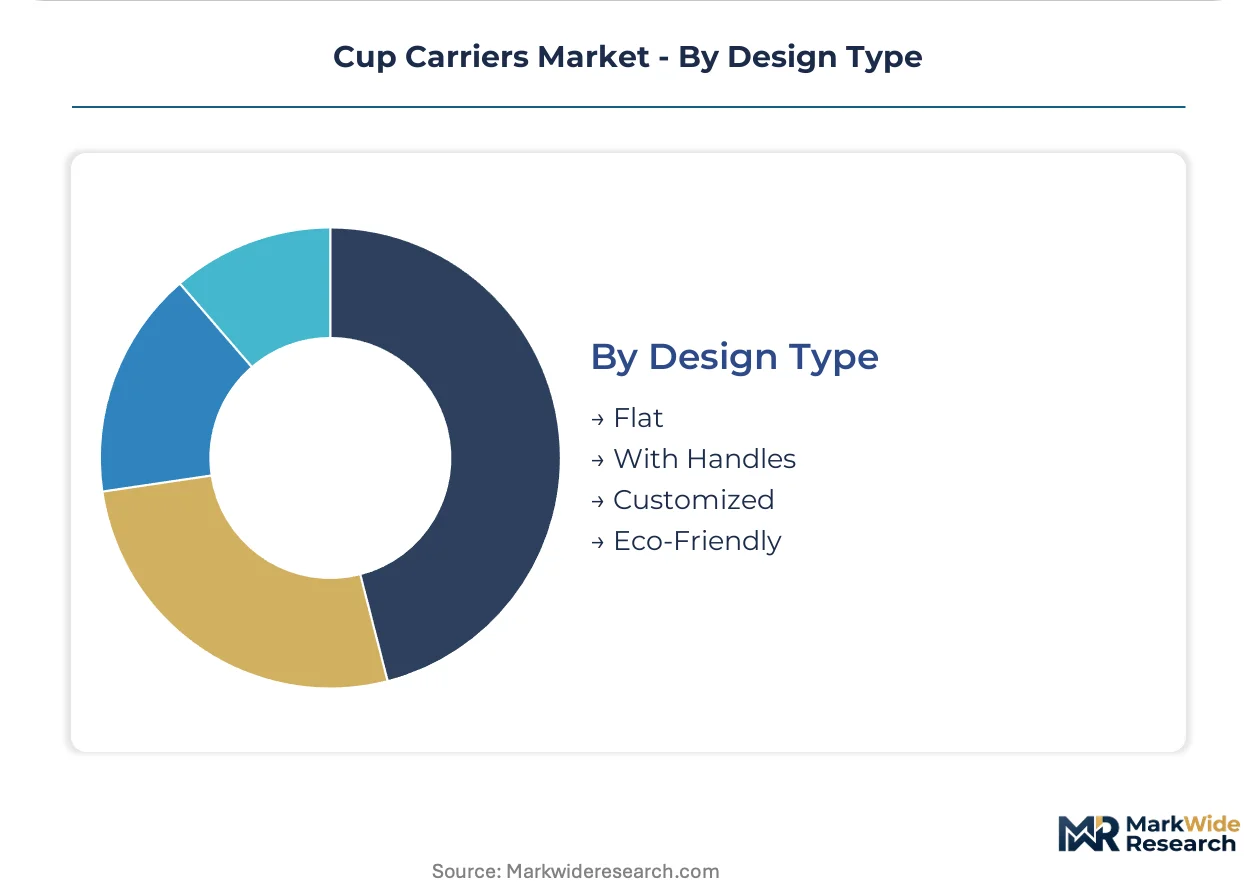
Cup carrier procurement splits across four dimensions that govern manufacturing economics and margin capture. Material and size configurations drive volume concentration, while end-user channel mix and design sophistication determine pricing power.
Material Type:
Corrugated cardboard and molded fiber turn over fastest in procurement cycles, while foam and specialty biopolymers linger in longer contract horizons due to regulatory uncertainty.
- Cardboard:Corrugated fiberboard with die-cut apertures dominates quick-service restaurant procurement in the United States. Major chains specify ECT-32 or higher edge crush ratings to survive automated dispensing systems. OCC supply volatility compresses margins for converters serving California and Texas markets.
- Biodegradable:Molded pulp carriers from bamboo or bagasse fibers command placement preference under Germany's packaging sustainability mandates. Compostability certifications from TÜV Austria OK compost HOME unlock access to Berlin and Munich foodservice accounts. Industrial composting infrastructure gaps in the United States strand some volumes in landfill streams.
- Plastic:PET and PP carriers persist in Southeast Asian wet-climate markets where moisture resistance governs procurement. Thailand and Vietnam operators retain these formats despite phased regulatory pressure.
- Foam:Expanded polystyrene faces accelerating displacement under REACH chemical restrictions and EU Single-Use Plastics Directive enforcement. France and Belgium have accelerated phaseout timelines beyond Brussels minimums.
Cardboard anchors the volume base while biodegradable gains share at the steepest rate.
Size Type:
Single and double cup configurations concentrate in walk-up cafe formats with lower throughput, whereas four-cup and six-cup variants align with delivery-platform economics that reward consolidated transport.
- Four Cup:Die-cut cardboard holders with reinforced corner structures capture group-ordering traffic from delivery aggregators. Seoul and Tokyo quick-service chains specify these for family-bundle beverage promotions.
- Six Cup:Molded fiber formats with integrated stacking ridges serve catering and office-delivery channels. German corporate foodservice providers mandate these for meeting-room beverage service.
- Single Cup:Minimal footprint carriers suit specialty coffee shops with high-margin individual transactions. Melbourne and Sydney cafe chains favor these for brand differentiation.
- Double Cup:Compact formats with interlocking bases target couples and paired commuters. Parisian bakery-cafes specify these for morning rush capture.
Four-cup configurations anchor the volume base while six-cup climbs the fastest as group-ordering apps expand.
End User:
Cafe and restaurant procurement cycles refresh seasonally with menu redesigns, while convenience stores and food trucks operate on longer equipment-refresh horizons tied to vehicle or fixture replacement.
- Cafes:Premium coffee chains in Italy and Spain specify custom-printed carriers with seasonal artwork. Limited-run designs generate 3-4x unit premiums over standard SKUs.
- Restaurants:Quick-service burger and chicken chains in the United States drive standardized four-cup procurement at national scale. Franchise holding companies mandate uniform sustainability specifications across networks.
- Food Trucks:Mobile operators in Mexico City and São Paulo prioritize space-efficient flat-pack carriers that minimize storage footprint. Durability under vibration governs material selection.
- Convenience Stores:Japanese konbini chains integrate carriers with automated beverage dispensers. Die-cutting precision within 0.5 millimeters ensures compatibility with robotic handoff systems.
Restaurants anchor the volume base while cafes gain share fastest on customization premiums.
Design Type:
Flat and handled designs concentrate in high-volume commodity procurement, whereas eco-friendly and customized variants command extended production lead times for brand-specific development.
- Eco-Friendly:Unbleached kraft fiber with visible pulp texture signals sustainability credentials to Copenhagen and Amsterdam consumers. These carriers carry compostability markings required by municipal procurement rules.
- Customized:Full-bleed four-color printing with QR codes for loyalty program integration serves London and New York flagship store openings. Design-to-delivery programs outsource inventory risk from brand owners.
- Flat:Minimal-material die-cut formats minimize shipping cube for distributors serving rural Australian and Canadian markets. These stack efficiently for long-haul logistics.
- With Handles:Integrated die-cut hand holes or attached paperboard straps improve customer ergonomics for heavy six-cup loads. Brazilian and Argentine operators favor these for pedestrian-heavy urban centers.
Flat designs anchor the volume base while eco-friendly climbs the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies. Germany mandates compostable fiber formats under strict sustainability frameworks, while Southeast Asian operators retain moisture-resistant plastics despite regulatory pressure. The United States sits between these poles, with state-level fragmentation complicating national procurement strategies.
Germany
Corporate foodservice providers in Berlin and Munich drive six-cup molded fiber procurement for meeting-room beverage service. The country's packaging sustainability mandates, enforced through ECHA REACH classifications, require TÜV Austria OK compost HOME certification for municipal accounts. Industrial clusters in Bavaria anchor production of unbleached kraft carriers with visible pulp texture signaling environmental credentials.
United States
Drive-thru format expansion in suburban Texas and California markets generates high-volume carrier demand compatible with automated handoff systems. FDA food-contact material safety standards govern procurement specifications, while California's extended producer responsibility laws exceed federal minimums. Quick-service franchise holding companies headquartered in Illinois mandate uniform sustainability specifications across national networks.
China
Shenzhen and Guangzhou export manufacturers integrate printing and die-cutting operations to serve international quick-service chains. SAMR enforces GB standards on packaging recyclability that shape domestic procurement requirements. Yangtze River Delta production clusters specialize in flat-pack formats minimizing shipping cube for long-haul logistics to Australian and Canadian distributors.
Japan
Konbini chains in Tokyo and Osaka integrate carriers with automated beverage dispensers requiring die-cutting precision within 0.5 millimeters. METI industrial standards guide food-contact packaging specifications for convenience store operators. Kanto region manufacturers supply NFC-enabled carriers that confirm cold-chain integrity for delivery platforms.
Brazil
Food truck operators in São Paulo and Rio de Janeiro prioritize space-efficient flat-pack carriers that minimize storage footprint under vibration. ANVISA regulates food-contact material safety for mobile foodservice operations. Urban centers with heavy pedestrian traffic favor handled formats with integrated die-cut hand holes for ergonomic six-cup loads.
Cup Carriers Market Vendor Landscape
Capability concentration sits with specialized fiber-format producers; scale advantage sits with integrated corrugated networks. The market structures around three tiers: multinational packaging conglomerates with continental logistics footprints, mid-cap converters serving regional quick-service networks, and export-focused manufacturers with integrated printing operations. Consolidation pressure intensifies as group purchasing organizations compress supplier rosters. Strategic moves center on compostability certification acquisition and die-cutting precision investments for automated dispensing compatibility.
Within the integrated corrugated tier, Smurfit Kappa Group represents European network scale. Among export manufacturers, Shenzhen CyGedin Printing & Packaging exemplifies integrated production capabilities. Cellulopack occupies a position anchoring the molded fiber specialization vector.
| Leading Market Players |
|---|
| The Paper Cup Company |
| The VaioPak Group |
| Southern Champion Tray |
| Shenzhen CyGedin Printing & Packaging |
| E-Package Creation & Solution Manufacturing |
| Cellulopack |
| Hangzhou Longquan Industrial |
| Smurfit Kappa Group |
| The Brenmar Company |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion feeds directly into cup carrier pricing power, as Shenzhen and Guangzhou export manufacturers pass through freight volatility while European corrugated converters absorb energy cost premiums that Asian competitors avoid. This logistics corridor's cost dynamics concentrate supply-side leverage with integrated printing operations and fragment downstream price differentiation between quick-service procurement tiers.
Pricing Analysis
Long-term offtake agreements anchor procurement for major quick-service chains, while spot purchasing serves seasonal customization programs and limited-run promotional carriers. Three-tier pricing structure across premium, standard, and economy levels separates TÜV Austria OK compost HOME certified fiber formats from unbleached kraft mid-tier options and commodity corrugated economy grades. Cost compression in biodegradable segments is intensifying because OCC supply volatility compresses converter margins. Quick-service franchise holding companies exhibit least price sensitivity due to sustainability mandate compliance requirements, whereas independent food truck operators in São Paulo and Mexico City demonstrate highest sensitivity to per-unit freight costs.
Supply Chain Analysis
Contract manufacturing concentration sits with Shenzhen CyGedin Printing & Packaging, Smurfit Kappa Group's European corrugated network, and specialized molded fiber producers like Cellulopack. Supply concentrates in China, Germany, and the United States, with Yangtze River Delta production clusters feeding export demand and Bavarian industrial clusters serving municipal procurement accounts. Raw material dependencies draw from OCC recycled pulp streams, bamboo and bagasse fiber inputs, and plant-based wax barrier coatings. Single-source vulnerability around TÜV Austria OK compost HOME certification capacity creates bottleneck risk for EU market access. Distribution runs through group purchasing organizations that compress supplier rosters for multi-chain operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precise die-cutting capability within 0.5-millimeter tolerances for automated beverage dispensing systems represents the critical asset gap separating contract manufacturers from commodity suppliers in this market. This technical scarcity concentrates margin capture with prepared suppliers while excluding reactive competitors from quick-service procurement rosters.
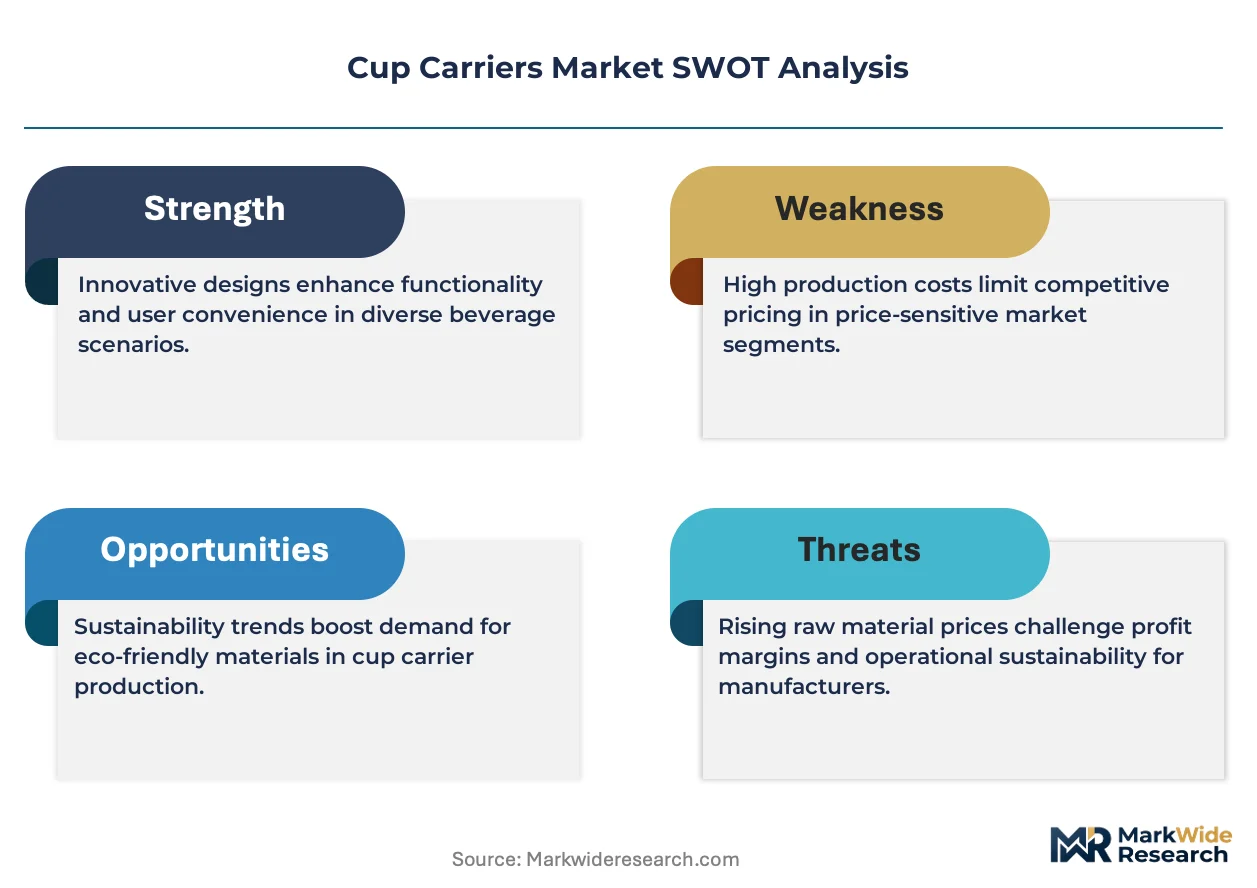
For Market Incumbents: Entrench position through backward integration into OCC pulp supply streams and captive TÜV Austria OK compost HOME certification capacity. Add die-cutting precision investments to defend against substitute technology threats from NFC-enabled smart packaging carriers. Channel control through group purchasing organization placement secures national-scale quick-service accounts against regional competitor encroachment. For New Entrants and Emerging Players: Build out molded fiber production capacity targeting India foodservice packaging modernization under FSSAI plastic phaseout timelines. Mumbai and Bangalore quick-service trials represent the most penetrable geography for fiber-based carrier adoption. Go-to-market angle centers on blockchain-tracked material origins that command placement preference in digital procurement systems embedding sustainability scoring. For Investors and Strategic Acquirers: Specialized fiber-format producers with established compostability certifications and automated dispensing compatibility represent the priority acquisition archetype. Long-term viability favors suppliers positioned across regulatory sequencing windows rather than single-jurisdiction compliance. Watch for REACH Annex XVII microplastic restriction enforcement as inflection indicator accelerating plant-based wax coating adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Compostability Certification Acquisition | TÜV Austria OK compost HOME unlocks Berlin and Munich municipal foodservice procurement accounts under ECHA REACH frameworks. |
| Die-Cutting Precision Investment | 0.5-millimeter aperture tolerance ensures compatibility with Japanese konbini automated beverage dispensers and robotic handoff systems. |
| Backward Integration into Pulp Supply | Captive OCC streams insulate margins from recycled corrugated container pricing volatility in California and Texas markets. |
| Smart Packaging Integration | NFC-enabled carriers compress insurance premiums for South Korean and Japanese delivery platforms through cold-chain verification. |
| Seasonal Customization Service Buildout | Design-to-delivery programs for holiday promotions capture 3-4x unit premiums over standard SKUs from London and New York flagship stores. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and foodservice procurement databases through bottom-up and top-down triangulation. Primary interviews engaged sustainability officers at quick-service chains, packaging procurement managers at group purchasing organizations, plant managers at molded fiber converters, and regulatory affairs leads at compostability certification bodies. Secondary sources incorporated ECHA REACH substance classifications, FDA food-contact material safety guidance, SAMR GB packaging standards, FSSAI plastic phaseout notifications, and customs records from Yangtze River Delta export corridors.
Forecast inputs considered material substitution velocity under regulatory sequencing, delivery-platform group-ordering economics, and quick-service restaurant format expansion patterns across the analysis window. Segmentation dimensions modeled include material type, size configuration, end-user channel, and design sophistication tier. CAGRs derived from volume trajectory analysis reconciled against value capture from customization premiums and certification tier pricing. Industry-specific inputs incorporated composting infrastructure development timelines and automated dispensing system penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by export-focused manufacturers or accelerated REACH enforcement beyond current sequencing would shift outcomes. Quarterly review of ECHA substance restriction proposals, FSSAI implementation timelines, and group purchasing organization sustainability specification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Europe Beverage Packaging Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
North America Soft Drinks Packaging Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Cup Sleeves Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Insulated Cup Sleeves Market
Beverage Packaging
PET Syrup Bottle Market
Beverage Packaging
North America Beverage Packaging Market
Beverage Packaging
Juice Packaging Market