
 Foldable Bottles Market | 2026-2036
Foldable Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Bottles Market Analysis
The EU Green Deal is hardening demand for reusable hydration formats across European retail channels. Hydrapak LLC leverages its technical partnerships with outdoor gear distributors to sustain category leadership in performance-oriented collapsible formats. Nalgene anchors mainstream consumer trust through decades of brand equity in durable drinkware. Stojo Products Inc. differentiates via kitchen-table aesthetics and urban portability, competing for shelf space in lifestyle retailers rather than outdoor specialty stores.
Foldable bottles are compressible liquid containers engineered from silicone, TPU, or food-grade plastics, typically collapsing to one-fifth of their filled volume for transport and storage. Silicone formulations dominate premium positioning due to thermal stability and dishwasher safety, while TPU variants occupy the ultralight backpacking segment where every gram determines packability. The outdoor enthusiast end-user category leads volume, though the everyday use application segment shows the fastest trajectory as commuter culture normalizes pocketable hydration.
FDA food-contact regulations govern material safety for foldable bottles sold in the United States, while REACH compliance in Europe restricts phthalate and BPA content across silicone and plastic supply chains. The EU F-Gas Regulation indirectly shapes manufacturing choices by pressuring suppliers to eliminate fluorinated processing aids from TPU films. Stakeholders must monitor how California's SB 54 extended producer responsibility framework replicates into other state legislatures, as this will determine whether refillable formats gain mandatory retail placement against conventional rigid bottles.
Market Dynamics
The EU Green Deal's single-use plastic restrictions are compressing demand timelines for reusable hydration formats, forcing retailers to accelerate shelf-space reallocation toward collapsible alternatives before mandatory phase-outs take effect.
Growth Catalysts
- REACH compliance mandates:European chemical safety rules restricting phthalate and BPA content in food-contact materials are eliminating inferior rigid plastic competitors from retail channels.
- Ultralight backpacking:Gram-conscious trekkers in alpine regions are adopting TPU-based collapsible formats that compress to one-fifth of filled volume without weight penalty.
- Germany:Dense networks of outdoor specialty retailers in Bavaria and Baden-Württemberg are normalizing premium silicone bottles as standard expedition equipment.
Market Restraints
- Silicone feedstock volatility:Siloxane prices fluctuate with energy costs, compressing margins for dishwasher-safe premium formulations.
- TPU film supply concentration:Three Japanese and German chemical suppliers control fluorinated processing aid alternatives, creating bottleneck risk.
- Taste retention:Porous polymer matrices retain flavor compounds from electrolyte mixes, limiting reuse frequency among fitness users.
Strategic Opportunities
- Japan:METI's circular economy subsidies for reusable consumer goods are opening procurement channels in Tokyo and Osaka corporate wellness programs.
- Connected hydration:Integration of flow sensors with fitness wearables is creating data-monetization potential in athletic segments.
- California SB 54 replication:Extended producer responsibility frameworks spreading to New York and Washington will mandate refillable format placement in convenience retail.
Industry Challenges
- FDA food-contact certification:Substance migration testing timelines stretch 14-18 months, delaying product launches for reformulated materials.
- Co-injection molding expertise:Shortage of technicians capable of bonding rigid bottle necks to collapsible bodies constrains production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Bottles Market |
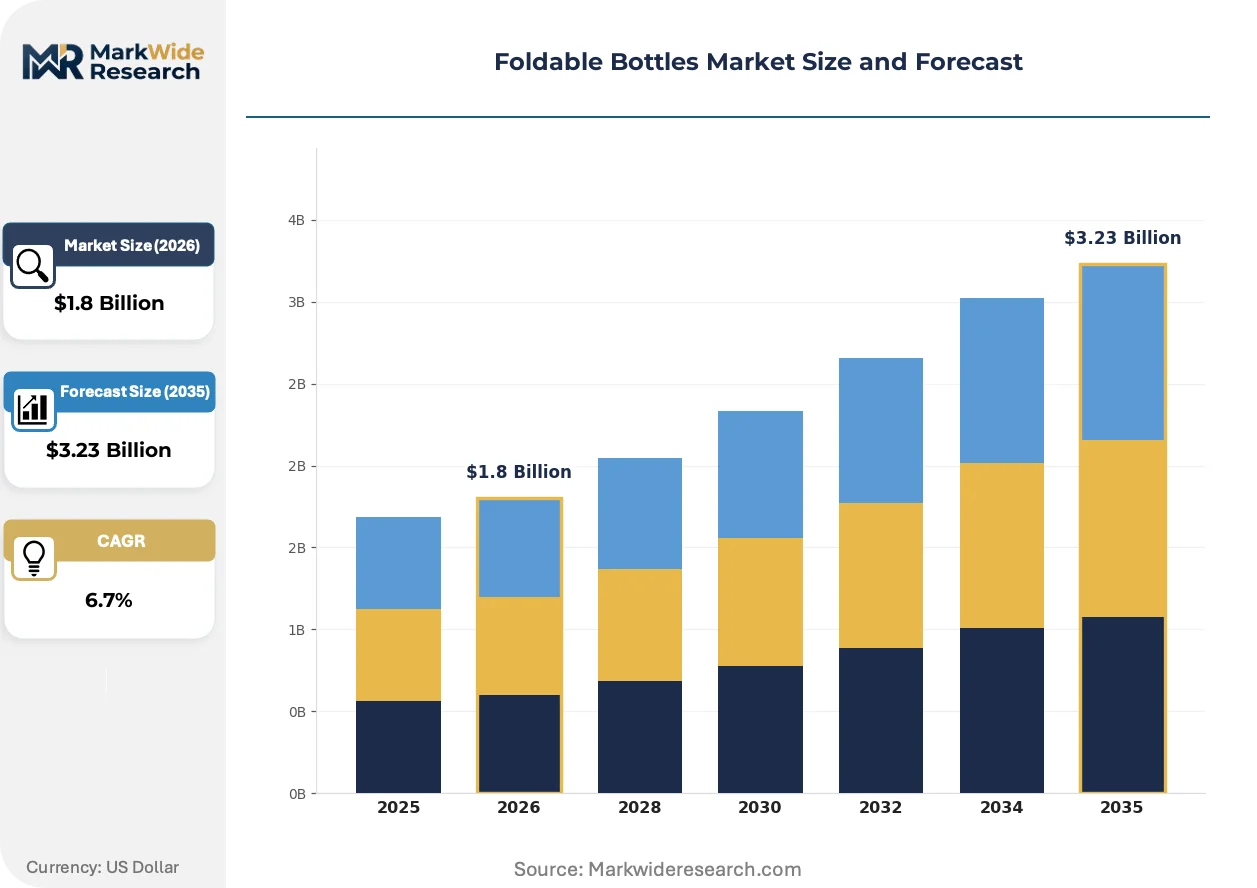
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silicone, Plastic, TPU, Others Design Type: Collapsible, Squeeze, Expandable, Reusable End User: Outdoor Enthusiasts, Travelers, Athletes, Families Application: Sports, Fitness, Camping, Everyday Use |
| Companies Covered | Zoku LLC, Hydrapak LLC, Salomon SAS, Vapur Inc., Stojo Products Inc., Cascade Designs Inc., Nalgene, Hydaway LLC, Lollicup USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Bottles Market Emerging Trajectories
Material science advances and regulatory pressure are converging to redefine performance benchmarks across collapsible hydration, with functionality now inseparable from compliance architecture.
Platinum-cured silicone formulations are expanding into high-temperature applications previously reserved for rigid metal vessels. Alpine expedition outfitters in the Austrian Alps and Colorado Rockies are specifying these variants for glacier meltwater processing. The technology is expanding into medical-adjacent consumer segments where sterilization cycles are non-negotiable.
EU F-Gas Regulation restrictions on fluorinated processing aids are forcing TPU film suppliers to reformulate extrusion chemistry. Manufacturers serving the ultralight backpacking segment face 12-18 month requalification cycles for new film stacks. German and Austrian outdoor brands are responding by consolidating supplier relationships to secure priority allocation of compliant materials.
Urban commuters are fragmenting purchase patterns across multiple channel types rather than defaulting to outdoor specialty retail. Lifestyle concept stores in Berlin, Brooklyn, and Shibuya are capturing trial purchases that previously flowed through REI or Decathlon. Japan's railway station kiosks are piloting compact-format automated dispensing, compressing the path from impulse to ownership for time-constrained professionals.
Foldable Bottles Market Segmentation
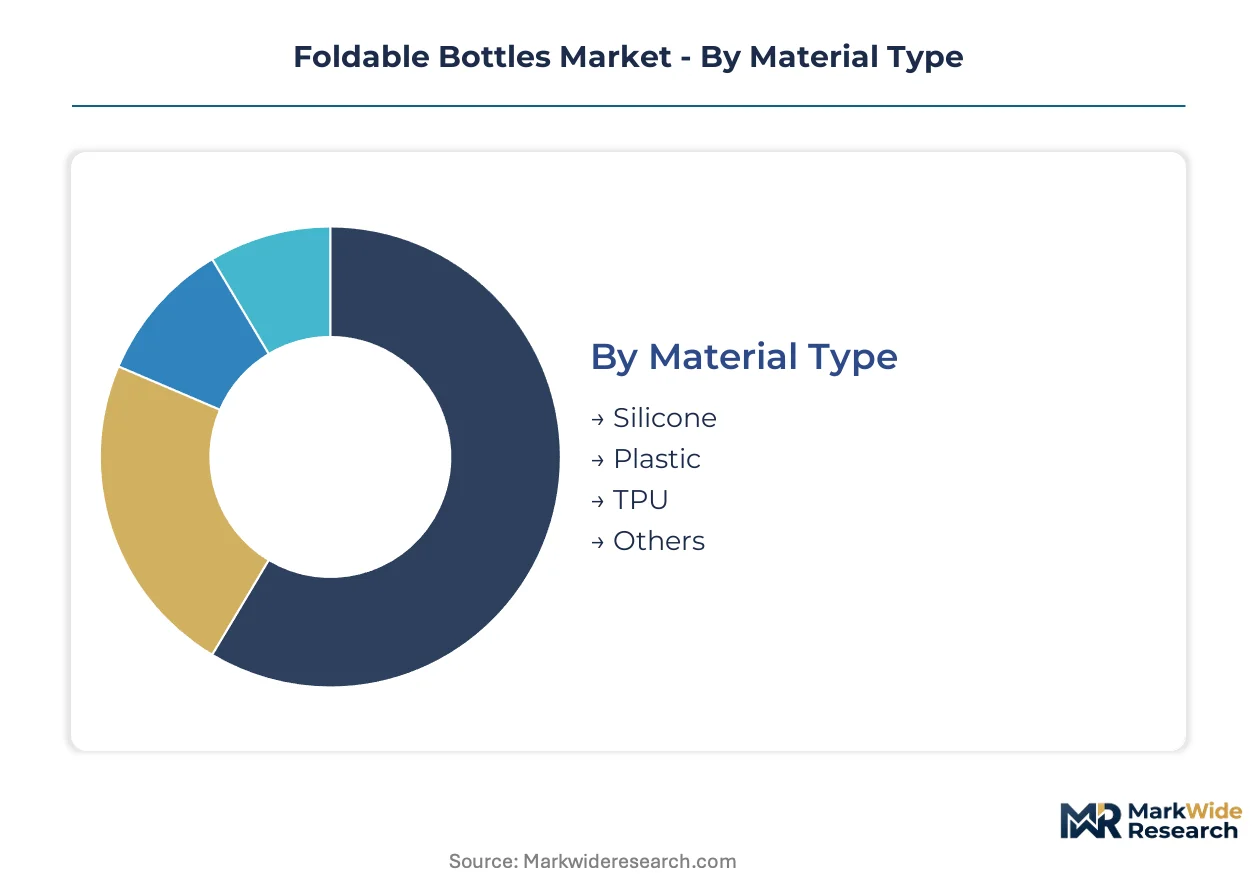
Foldable bottle manufacturers compete across four distinct category axes. Material chemistry determines thermal performance and regulatory compliance. Design architecture governs compression ratios and user ergonomics. End-user targeting shapes channel strategy and price positioning. Application context drives feature prioritization and replacement frequency.
Material Type:
Silicone commands premium shelf space while TPU dominates gram-conscious segments. Plastic formulations serve price-sensitive volume tiers.
- Silicone:Platinum-cured formulations withstand temperatures from -40°C to 230°C, enabling dishwasher sterilization and alpine meltwater processing. Demand concentrates in Germany and Austria where outdoor specialty retailers specify these variants for expedition-grade durability. REACH compliance on siloxane purity eliminates lower-grade competitors from European channels.
- TPU:Thermoplastic polyurethane films achieve sub-30-gram weights for 500ml capacity, compressing to one-fifth of filled volume without structural compromise. Ultralight trekkers in the Colorado Rockies and Japanese alpine clubs drive procurement. EU F-Gas Regulation restrictions on fluorinated processing aids are forcing 12-18 month requalification cycles for film suppliers.
- Plastic:Food-grade polypropylene and copolyester variants occupy entry-level positioning through mass retail channels in the United States and India.
- Others:Hybrid laminates and experimental biodegradable polymers from Korean and Taiwanese material labs target single-use replacement mandates in corporate procurement.
Today's leader: Silicone. Tomorrow's challenger: TPU.
Design Type:
Structural approach determines packability mechanics and manufacturing complexity. Collapsible formats lead outdoor distribution while squeeze variants capture athletic convenience.
- Collapsible:Concertina-fold or roll-up architectures reduce to disk or cylinder forms under 3cm thickness. Bavarian and Baden-Württemberg outdoor retailers normalize these as standard expedition equipment.
- Squeeze:Semi-rigid bodies with flexible sidewalls enable one-handed hydration during activity. Marathon runners and cyclists in Tokyo and Osaka corporate wellness programs drive replacement cycles.
- Expandable:Telescoping rigid segments lock at multiple volume settings, appealing to travelers facing variable liquid restrictions across airport security regimes.
- Reusable:Rigid-necked formats with collapsible bodies bridge durability and packability, requiring co-injection molding expertise that constrains supplier scaling.
Volume concentrates in collapsible formats. Steepest expansion trajectory belongs to squeeze designs.
End User:
Outdoor specialists anchor current revenue while commuter professionals represent the fastest-climbing adoption curve.
- Outdoor Enthusiasts:Backpackers, climbers, and paddlers prioritize weight-to-volume ratios above all other attributes. This segment shows highest willingness-to-pay for TPU ultralight and platinum-cured silicone premium tiers.
- Travelers:International tourists and business travelers demand TSA-compatible empty formats with rapid deployment for airport hydration stations.
- Athletes:Gym members and competitive runners require taste-neutral polymers compatible with electrolyte and protein formulations. Flavor retention in porous matrices limits reuse frequency and drives replacement demand.
- Families:Parents prioritize dishwasher safety and spill-proof rigid necks for school and daycare contexts, accepting weight penalties for durability assurance.
Outdoor enthusiasts defend margin pools. Athletes are gaining share fastest through fitness wearable integration opportunities.
Application:
Activity context determines performance specifications and replacement cadence. Sports and fitness applications show compressed replacement cycles versus camping durability expectations.
- Sports:Team athletics and individual competitive training demand rapid-access squeeze formats with integrated carry loops. Japanese railway station kiosks pilot automated dispensing for impulse procurement.
- Fitness:Gym-based strength and conditioning contexts favor measured intake tracking, creating data-monetization potential through flow sensor integration with wearable ecosystems.
- Camping:Multi-day wilderness exposure requires temperature extremes resistance and contamination-proof sealing. Austrian and Colorado alpine outfitters specify platinum-cured silicone for glacier melt scenarios.
- Everyday Use:Urban commuting and workplace hydration normalize pocketable formats in lifestyle retail channels across Berlin, Brooklyn, and Shibuya.
Camping commands premium positioning. Everyday use climbs the fastest as commuter culture institutionalizes portable hydration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foldable bottle manufacturing scaled initially through German and Austrian alpine outfitters before expanding into North American outdoor retail and Japanese corporate wellness channels. Today, demand concentrates in countries with dense outdoor specialty retail networks and stringent single-use plastic regulations.
United States
Ultralight backpacking communities in Colorado and California drive TPU format adoption, while FDA food-contact certification timelines of 14-18 months constrain new material launches. The EPA's emerging focus on per- and polyfluoroalkyl substances (PFAS) in consumer goods is pressuring fluorinated processing aid elimination. Cascade Designs Inc. and Hydrapak LLC anchor Pacific Northwest manufacturing clusters serving REI's national distribution network.
Germany
Bavarian and Baden-Württemberg outdoor retailers normalize platinum-cured silicone bottles as standard expedition equipment, with consumers showing highest willingness-to-pay for dishwasher-safe premium tiers. REACH compliance mandates on siloxane purity eliminate lower-grade competitors from European channels. The EU Green Deal's single-use plastic restrictions are compressing retailer timelines for shelf-space reallocation toward collapsible alternatives.
Japan
METI's circular economy subsidies for reusable consumer goods are opening procurement channels in Tokyo and Osaka corporate wellness programs. Railway station kiosks in Shibuya and Shinjuku pilot compact-format automated dispensing for time-constrained professionals. Japanese alpine clubs drive ultralight TPU demand where gram-conscious trekkers prioritize packability above all other attributes.
Austria
Alpine expedition outfitters in Tyrol and Salzburg specify platinum-cured silicone variants for glacier meltwater processing in extreme temperature conditions. EU F-Gas Regulation restrictions on fluorinated processing aids force Austrian brands to consolidate supplier relationships with German and Japanese chemical firms. The country's outdoor retail density supports premium positioning unavailable in mass-market channels elsewhere.
United Kingdom
London's lifestyle concept stores in Shoreditch and Notting Hill capture trial purchases that previously flowed through outdoor specialty retailers, fragmenting traditional channel structures. The Environment Agency's implementation of extended producer responsibility frameworks is mandating refillable format placement in convenience retail ahead of continental Europe. British consumers show growing preference for kitchen-table aesthetics over technical outdoor branding.
Foldable Bottles Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material certification tiers, with platinum-cured silicone and REACH-compliant TPU commanding shelf-space priority over entry-grade polypropylene alternatives. The vendor base organizes into three strategic archetypes: technical outdoor specialists leveraging distributor partnerships, lifestyle-oriented brands targeting urban commuters, and legacy durable drinkware manufacturers extending into collapsible formats. Dominant competitive moves include strategic partnerships with outdoor gear distributors and geographic expansion into railway station and airport retail channels.
Within the technical outdoor specialist tier, Hydrapak LLC and Cascade Designs Inc. exemplify performance-oriented positioning through Pacific Northwest manufacturing heritage and alpine distributor relationships. Nalgene occupies a position bridging legacy durable drinkware equity with collapsible format experimentation, while Stojo Products Inc. represents the lifestyle-oriented archetype targeting urban portability rather than outdoor specialty channels. These three anchors illustrate how competitive positioning fragments across end-user contexts rather than consolidating around unified category leadership.
| Leading Market Players |
|---|
| Zoku LLC |
| Hydrapak LLC |
| Salomon SAS |
| Vapur Inc. |
| Stojo Products Inc. |
| Cascade Designs Inc. |
| Nalgene |
| Hydaway LLC |
| Lollicup USA Inc. |
| Others |
Supply Flow & Price Mechanics
Platinum-cured silicone extrusion technology is displacing conventional peroxide-cured methods across premium tier manufacturing, simultaneously elevating FDA certification costs and compressing supplier margins in lower-grade segments. This process transition concentrates pricing power with German and Austrian chemical processors capable of REACH-compliant siloxane purification, while forcing mass-market competitors toward thinner-margin TPU alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates foldable bottle procurement, with platinum-cured silicone commanding shelf-space priority due to dishwasher safety certification, TPU occupying the ultralight performance tier, and polypropylene variants serving price-sensitive volume channels. Price differentiation hinges on material certification grade and geographic delivery cost from Pacific Northwest manufacturing clusters. Cost compression in entry-grade plastic tiers is intensifying because of siloxane feedstock volatility linked to European energy pricing. Mass retailers in the United States exhibit highest price sensitivity, while alpine outfitters in Bavaria demonstrate lowest elasticity for expedition-grade specifications.
Supply Chain Analysis
Direct-to-retail channels through outdoor specialty distributors handle premium buyer demand, while mass-market procurement flows through consolidated lifestyle retail networks in Berlin, Brooklyn, and Tokyo. Manufacturing concentrates in the United States, Germany, and Japan, with TPU film supply anchored in Japanese and German chemical processing facilities. Raw material dependencies include siloxane feedstocks, fluorinated processing aid alternatives, and food-grade colorant formulations. Single-source vulnerability in compliant TPU film supply creates bottleneck risk as EU F-Gas Regulation restrictions force 12-18 month requalification cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foldable bottles represent a late-cycle quality story as commuter culture shifts procurement toward premium platinum-cured silicone specifications that command durable price premiums against commodity alternatives.
For Market Incumbents: Anchor category leadership through backward integration into siloxane purification capacity in Germany and Austria, securing priority allocation as REACH compliance eliminates lower-grade competitors. Invest in co-injection molding technician training programs to overcome production scaling constraints. Defensive consolidation around FDA-certified Pacific Northwest manufacturing clusters protects against emerging Asian material science entrants. For New Entrants and Emerging Players: California SB 54 extended producer responsibility frameworks and their replication into New York and Washington state legislation opens a window for refillable format placement in convenience retail channels previously dominated by rigid bottles. Target corporate wellness programs in Tokyo and Osaka where METI circular economy subsidies reduce procurement friction. Pursue railway station kiosk automated dispensing pilots as a go-to-market angle for time-constrained professional segments. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap technical outdoor specialists because certification scarcity and distributor relationship concentration create defendable local moats. Platform consolidation across REACH-compliant silicone processors and TPU film suppliers offers long-term viability in a market where regulatory compliance barriers compound over time. Watch for EU F-Gas Regulation enforcement acceleration as the inflection indicator for material substitution capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platinum-Cured Silicone Capacity Expansion | Secures FDA and REACH certification tiers that eliminate lower-grade competitors from European and North American retail channels. |
| Co-Injection Molding Technician Training Programs | Addresses production scaling constraints for rigid-neck collapsible body formats demanded by family and commuter segments. |
| Railway Station Automated Dispensing Pilots | Compresses path-to-purchase for impulse procurement among Tokyo and Osaka corporate wellness participants. |
| TPU Film Supplier Consolidation | Mitigates EU F-Gas Regulation requalification risk through priority allocation agreements with German and Japanese chemical processors. |
| Fitness Wearable Flow Sensor Integration | Creates data-monetization potential in athletic segments where measured intake tracking drives replacement demand. |
Methodological Framework
Multiple input streams — primary interviews with outdoor gear distributors, silicone and TPU procurement leads, and category buyers at lifestyle retailers; secondary validation through FDA food-contact filings, REACH compliance databases, and customs trade records; plus patent landscape analysis — were reconciled through bottom-up and top-down triangulation. Conversations with Bavarian alpine outfitters, Colorado ultralight backpacking community leaders, and Tokyo corporate wellness program managers informed demand segmentation. Trade data from German outdoor specialty retail associations and Japanese METI circular economy subsidy disclosures provided supply-side calibration.
Data-stream reconciliation across material chemistry, design architecture, end-user targeting, and application context dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume buildups validated against macroeconomic elasticity assumptions. Industry-specific forecast inputs included EU Green Deal single-use plastic phase-out timelines and California SB 54 extended producer responsibility framework propagation patterns.
Revisions become necessary when regulatory enforcement acceleration, feedstock price shocks, or material science breakthroughs materialize outside modeled trajectories. Forecasts reflect documented assumptions regarding commuter culture normalization and fitness wearable ecosystem integration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Soft Drinks Packaging Market
Beverage Packaging
Beverage Aluminum Cans Market
Beverage Packaging
Beverage Cans Market
Beverage Packaging
Tumblers Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Asia Pacific Beverage Packaging Market
Beverage Packaging
Disposable Tea Flask Market
Beverage Packaging
Can Sleeves Market
Beverage Packaging
Middle East and Africa Soft Drinks Packaging Market
Beverage Packaging
Cup Filler Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Dual Chamber Dispensing Bottles Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Cold Beverage Cups Market
Beverage Packaging
Square Media Bottle Market
Beverage Packaging
Beverage Crates Market