
 Fruit Juice Packaging Market | 2026-2036
Fruit Juice Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Juice Packaging Market Foresight
Packaging engineering talent scarcity is reorganizing competitive dynamics as aseptic filling expertise becomes concentrated among established systems integrators. Tetra Pak sustains technology leadership in laminated carton sterilization and filling line integration. SIG Combibloc differentiates through flexible volume formats and regional manufacturing proximity. Smurfit Kappa anchors European paperboard supply with integrated pulp-to-converting operations.
Fruit juice packaging encompasses primary and secondary containment systems engineered to preserve organoleptic properties, prevent microbial contamination, and extend shelf life through barrier layers typically comprising polyethylene, aluminum foil, and paperboard substrates laminated under sterile conditions. The primary commercial purpose is enabling ambient distribution of pasteurized or cold-pressed juices without refrigeration dependency. Tetra Pak cartons occupy the mature volume tier in ambient retail channels, while aluminum cans represent the fastest-growing format for on-the-go and convenience store distribution. Biodegradable plastics command premium positioning but remain constrained by scale economics and oxygen barrier performance.
FDA food contact substance regulations and EU REACH compliance frameworks govern migration limits and additive approvals for polyethylene and polypropylene layers in direct juice contact. EFSA and EPA standards on recycled content thresholds and per- and polyfluoroalkyl substance restrictions are forcing material reformulation timelines across multinational beverage manufacturers. Stakeholders must monitor evolving extended producer responsibility mandates and deposit-return scheme expansions that will reshape format selection and regional manufacturing footprints.
Market Dynamics
Aseptic carton sterilization expertise has concentrated among a handful of systems integrators, creating bottlenecks as beverage manufacturers race to expand ambient distribution capacity without refrigeration infrastructure.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant restrictions are accelerating investment in shelf-stable packaging formats that eliminate cold-chain dependency across European retail networks.
- India PLI scheme incentives:Domestic manufacturing subsidies are attracting laminated carton converting capacity to Maharashtra and Gujarat, reducing import reliance for juice brands.
- Aluminum can line advancement:Epoxy-phenolic interior coatings with improved acid resistance are expanding metal format viability for high-pulp and cold-pressed juice variants.
Market Restraints
- Aluminum foil supply concentration:European smelter curtailments and Russian supply exclusion have tightened availability of the 6-7 micron barrier layer essential for aseptic cartons.
- Biopolymer oxygen barrier limitation:PLA and PHA films transmit 50-100x more oxygen than aluminum laminates, capping shelf life at 3-6 months versus 12 months for conventional formats.
- Extended producer responsibility mandates:Germany's VerpackG and France's AGEC law impose per-unit fees that compress margins on multi-material laminated structures.
Strategic Opportunities
- Indonesian retail modernization:Convenience store expansion in Jakarta and Surabaya is creating first-mover advantage for ambient single-serve formats in a refrigerated-infrastructure-scarce market.
- Paperboard-aluminum separation technology:Hydrogen peroxide bleaching and eddy-current sorting advances are enabling closed-loop fiber recovery from post-consumer cartons.
- Digital printing on aseptic lines:Electron beam-cured inks allow SKU proliferation and seasonal customization without plate changeover downtime.
Industry Challenges
- Aseptic filling technician scarcity:HEPA filtration maintenance, sterility testing protocols, and CIP/SIP system operation require specialized training pipelines that OEMs and beverage firms struggle to staff.
- Multi-material compliance complexity:REACH substance restrictions, FDA food contact notifications, and evolving state-level PFAS bans force simultaneous reformulation across polyethylene, adhesive, and printing ink layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Juice Packaging Market |
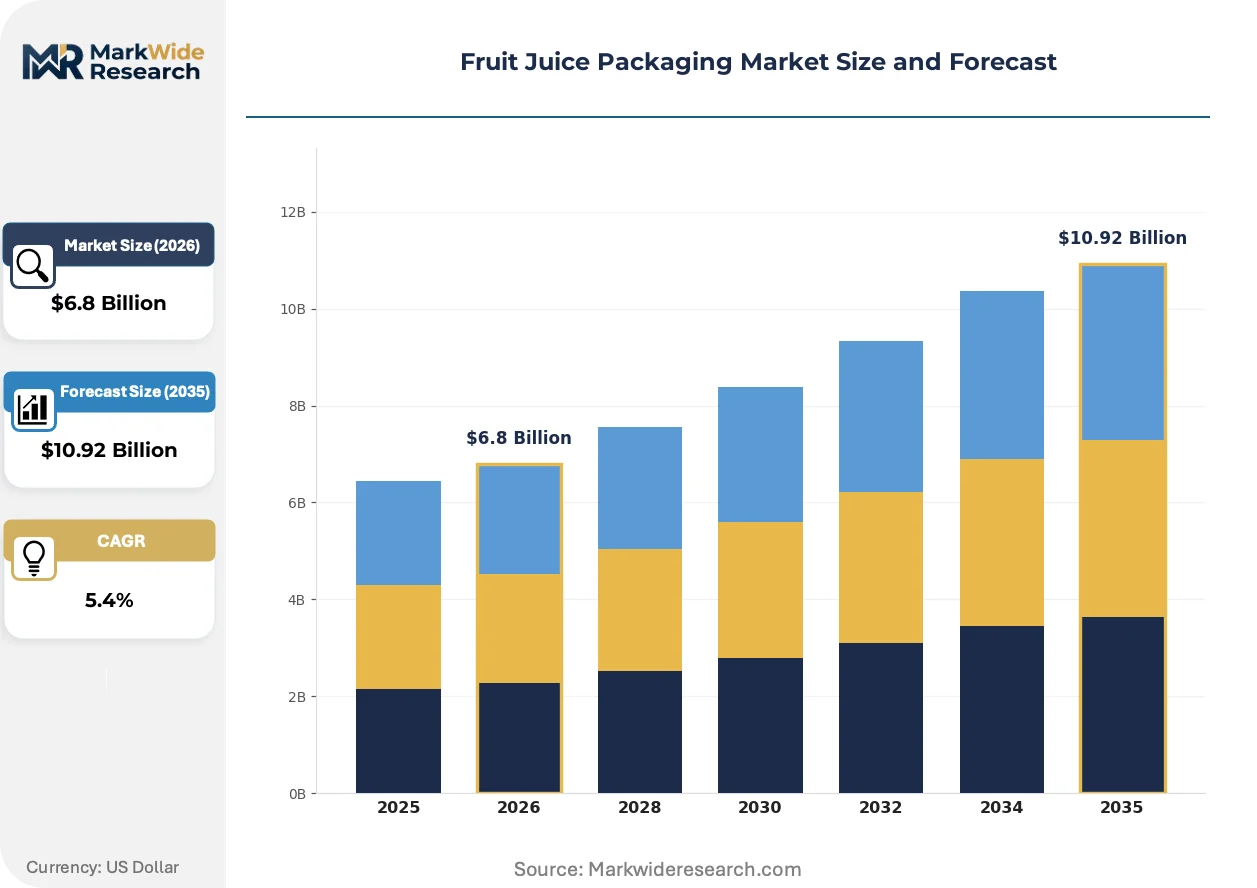
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass Bottles, Tetra Pak Cartons, PET Bottles, Aluminum Cans, Pouches Material: Polyethylene, Polypropylene, Paperboard, Aluminum Foil, Biodegradable Plastics Application: Retail Stores, Food Service, Vending Machines, Online Retailers, Convenience Stores End User: Beverage Manufacturers, Bottlers, Distributors, Wholesalers, Private Labelers |
| Companies Covered | SIG Combibloc, Smurfit Kappa, Tetra Pak, Elopak, Crown Holdings, Amcor, Mondi Group, Ardagh Group, Ball Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Juice Packaging Market Shifts & Advancements
Packaging format selection is decoupling from pure cost optimization toward lifecycle accountability, with recyclability credentials and carbon intensity metrics now embedded in retailer listing requirements and procurement scorecards.
Barrier-coated paperboard without aluminum lamination is displacing conventional aseptic cartons in low-acid juice applications where six-month shelf life suffices. German retailers Aldi and Lidl have adopted these structures for private-label orange juice, accepting modest shelf-life reduction in exchange for fiber-stream recyclability. The displacement is compressing demand for aluminum foil converting capacity in Northern Europe.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant exterior coatings on paperboard sleeves. ECHA's 2023 proposal to classify additional PFAS compounds as substances of very high concern has triggered 18-month substitution timelines for juice packaging converters supplying EU markets. Mid-sized beverage brands lack toxicology testing budgets and are outsourcing compliance verification to third-party laboratories.
Direct-to-retailer procurement contracts are consolidating volume previously fragmented through distributor networks. Brazilian juice processors now negotiate carton supply agreements with Carrefour and GPA rather than regional wholesalers, compressing supplier margins but guaranteeing volume visibility. São Paulo-based converters have reconfigured logistics to accommodate weekly store-direct deliveries with smaller minimum order quantities.
Fruit Juice Packaging Market Segmentation
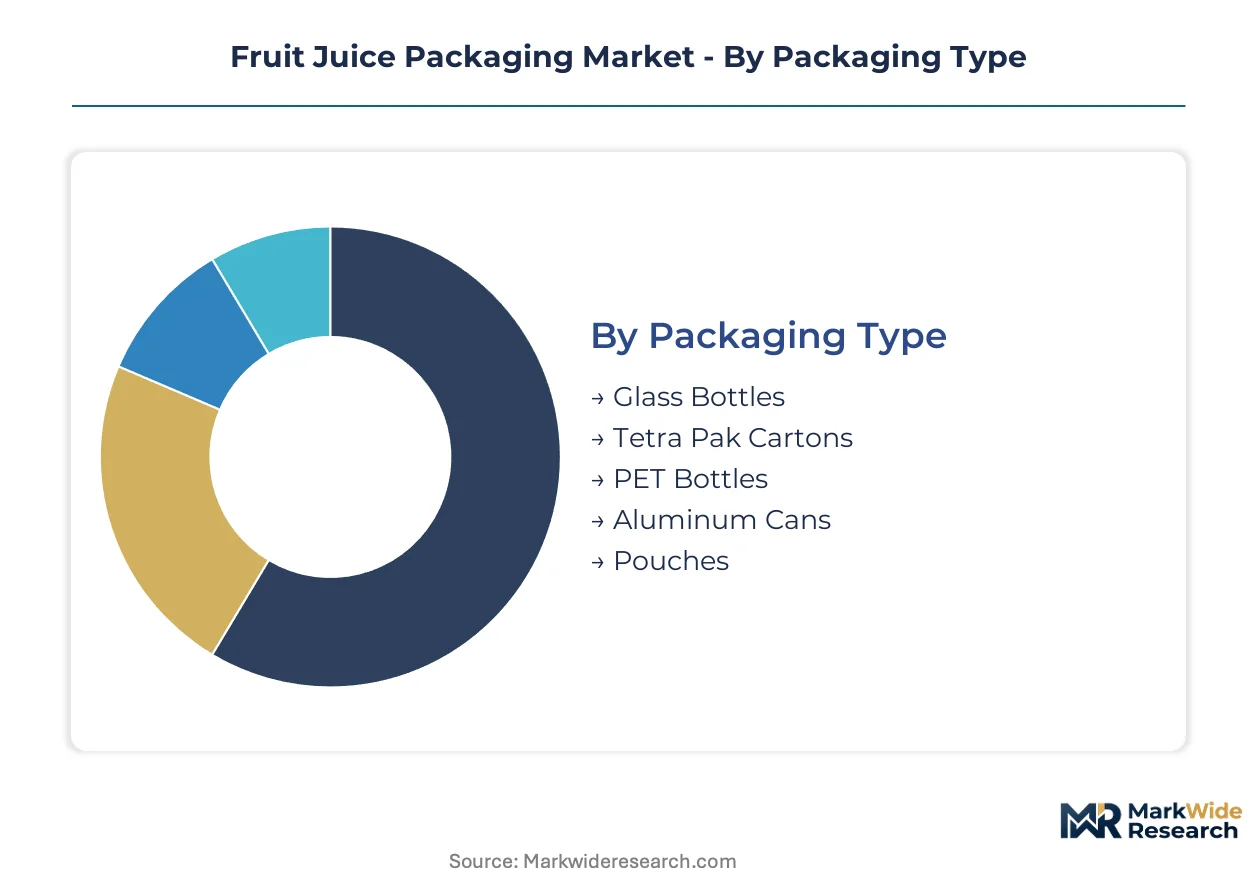
Fruit juice packaging segmentation reveals how format selection varies sharply by distribution temperature requirements, shelf-life targets, and regional recycling infrastructure capabilities. Procurement patterns diverge between ambient-stable formats for emerging markets and refrigerated premium formats for developed retail networks.
Packaging Type:
Domestic production concentrates on Tetra Pak cartons and PET bottles for mass retail, while aluminum cans and glass bottles serve export-led premium positioning in North American and European markets.
- Tetra Pak Cartons:Multi-layer laminated structures with polyethylene, aluminum foil, and paperboard substrates enable 12-month ambient shelf life without refrigeration. Demand clusters in India and Indonesia where cold-chain infrastructure remains underdeveloped and single-serve consumption is accelerating.
- Aluminum Cans:Epoxy-phenolic interior coatings now withstand high-acid and high-pulp juice variants previously restricted to cartons. Momentum is strongest in Brazilian and US convenience store channels where on-the-go consumption dominates.
- PET Bottles:Lightweight, shatter-resistant containers with oxygen scavenger additives for 3-6 month refrigerated distribution. Widely adopted by bottlers in Germany and Japan for premium not-from-concentrate juices.
- Glass Bottles:Inert barrier properties preserve flavor profiles for cold-pressed and organic positioning. Concentrated in Italian and Spanish export markets targeting premium retail tiers.
- Pouches:Flexible multi-layer films with spout fitments for children's portion control and food service dispensing. Expanding in Indonesian school nutrition programs and Indian railway catering.
Tetra Pak cartons hold the largest share; momentum sits with aluminum cans.
Material:
Cost tier differentiation separates commodity polyethylene volumes from aluminum foil premium barriers and experimental biopolymer prototypes.
- Aluminum Foil:6-7 micron barrier layers provide near-zero oxygen and light transmission essential for vitamin C retention in aseptic cartons. European smelter curtailments and Russian supply exclusion have tightened availability, forcing converters toward thinner gauge specifications.
- Biodegradable Plastics:PLA and PHA films derived from corn starch or bacterial fermentation command 40-60% price premiums over conventional polymers. Oxygen transmission rates 50-100x higher than aluminum laminates restrict applications to short-shelf-life refrigerated juices in German and French organic retail.
- Polyethylene:Low-density and linear low-density grades form heat-seal layers and moisture barriers in laminated structures. Indian domestic production under PLI scheme incentives is displacing imported resin for Maharashtra-based converters.
- Paperboard:Bleached kraft pulp provides structural rigidity and printable surfaces for retail branding. Smurfit Kappa's integrated pulp-to-converting operations anchor European supply with FSC-certified fiber sourcing.
- Polypropylene:High-clarity grades for injection-molded closures and thermoformed trays in food service portion packs. Demand is climbing fastest in Indonesian convenience store expansion.
Polyethylene and paperboard dominate volume; aluminum foil commands premium positioning despite supply constraints.
Application:
Customer type stratification separates high-frequency, low-margin food service from planned, high-margin retail purchasing.
- Food Service:Hotels, restaurants, and institutional catering require bulk bag-in-box and single-serve portion formats with extended ambient stability. Tetra Pak's 1-liter and 200-milliliter SKUs lead in Indian quick-service restaurant chains.
- Convenience Stores:Grab-and-go consumption patterns favor aluminum cans and small-format PET bottles with resealable closures. Brazilian chains GPA and Carrefour are consolidating direct procurement from São Paulo converters.
- Retail Stores:Hypermarkets and supermarkets stock multi-pack cartons and premium glass bottles for home consumption. German retailers Aldi and Lidl have adopted aluminum-free barrier-coated paperboard for private-label orange juice.
- Vending Machines:Robust, drop-resistant packaging with 6-12 month shelf life for unmanned distribution. Concentrated in Japanese railway stations and Brazilian workplace catering.
- Online Retailers:E-commerce fulfillment demands damage-resistant formats with compact cube efficiency for last-mile logistics. Expanding in Indian urban markets through Swiggy Instamart and Blinkit platforms.
Retail stores anchor volume; convenience stores are expanding most quickly.
End User:
Supply chain position determines format specification authority, with beverage manufacturers controlling primary packaging design and distributors influencing secondary packaging efficiency.
- Beverage Manufacturers:Coca-Cola, PepsiCo, and regional juice processors specify barrier requirements and shelf-life targets that dictate material selection. Direct-to-retailer contract consolidation in Brazil is compressing supplier margins while guaranteeing volume visibility.
- Private Labelers:Retailer-owned brands such as Aldi's Specially Selected and Lidl's Simply Nature prioritize recyclability credentials and carbon intensity metrics in procurement scorecards. These specifications are accelerating aluminum-free carton adoption in Northern Europe.
- Bottlers:Contract packaging operations filling co-manufactured juice for multiple brands require rapid format changeover capability. SIG Combibloc's flexible volume formats support SKU proliferation without line downtime.
- Distributors:Regional wholesalers managing ambient warehouse networks prioritize cube efficiency and pallet optimization for logistics cost containment. Declining in influence as direct retailer procurement expands.
- Wholesalers:Traditional cash-and-carry operators serving independent retailers in fragmented markets. Concentrated in Indian tier-2 and tier-3 cities where modern trade penetration remains limited.
Beverage manufacturers hold procurement authority; private labelers are gaining specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation phase-down is restructuring European procurement patterns toward shelf-stable formats. Indian PLI scheme incentives are attracting laminated carton converting capacity to domestic manufacturing clusters. Indonesian retail modernization is accelerating single-serve ambient format adoption in refrigerated-infrastructure-scarce markets.
India
Urban retail expansion in Mumbai and Delhi-NCR is driving single-serve carton demand for quick-service restaurant chains. FSSAI food contact material regulations govern polyethylene migration limits in laminated structures. Maharashtra and Gujarat host expanding converting capacity under PLI scheme incentives, reducing import reliance for juice brands.
Germany
Aldi and Lidl private-label procurement prioritizes aluminum-free barrier-coated paperboard for recyclability credentials. VerpackG extended producer responsibility fees compress margins on multi-material laminated structures. Hamburg and North Rhine-Westphalia concentrate carton converting operations serving Northern European retail networks.
Brazil
Carrefour and GPA direct-to-retailer contracts are consolidating volume previously fragmented through distributor networks. ANVISA food contact substance regulations govern epoxy-phenolic interior coatings for aluminum can formats. São Paulo-based converters have reconfigured logistics for weekly store-direct deliveries with reduced minimum order quantities.
Indonesia
Convenience store expansion in Jakarta and Surabaya creates first-mover advantage for ambient single-serve formats. The country's national food safety regulator monitors additive approvals for polyethylene layers in direct juice contact. Java-based converters are scaling flexible film and carton capacity to serve modern trade channel growth.
United States
Convenience store and vending channel expansion favors aluminum cans with improved acid-resistant interior coatings. FDA food contact notifications govern migration limits for laminated carton structures. California and Texas beverage co-manufacturing clusters are integrating digital printing capabilities for SKU proliferation without plate changeover downtime.
Fruit Juice Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the aseptic filling and converting value chain. Systems integrators with sterilization expertise command premium positioning, while scale-driven converters compete on volume throughput and regional manufacturing proximity. Strategic differentiation clusters around flexible format capability, integrated pulp-to-converting operations, and aluminum supply security. Dominant competitive moves include capacity expansion in PLI-incentivized Indian manufacturing zones and strategic partnerships for closed-loop fiber recovery technology.
Within the integrated systems tier, Tetra Pak and SIG Combibloc exemplify contrasting approaches to aseptic technology deployment. Smurfit Kappa anchors European paperboard supply with captive fiber sourcing. Among metal format specialists, Crown Holdings and Ball Corporation occupy positions in aluminum can interior coating advancement for high-pulp juice variants.
| Leading Market Players |
|---|
| SIG Combibloc |
| Smurfit Kappa |
| Tetra Pak |
| Elopak |
| Crown Holdings |
| Amcor |
| Mondi Group |
| Ardagh Group |
| Ball Corporation |
| Others |
Supply & Pricing Matrix
Barrier-coated paperboard substitution for aluminum-laminated cartons simultaneously shifts converting capacity toward Northern Europe and compresses foil-dependent pricing tiers. German retailers Aldi and Lidl now specify aluminum-free structures, forcing margin recalculation across multi-material supply chains while rewarding integrated pulp-to-converting operators with captive fiber sourcing.
Pricing Analysis
Geographic price spreads between European and Indian converting markets have widened as PLI scheme subsidies attract laminated carton capacity to Maharashtra and Gujarat. Three-tier pricing structure across premium, standard, and economy levels separates aseptic cartons with 12-month shelf life from barrier-coated alternatives at six months and basic polyethylene pouches for food service. Cost compression in standard-tier aluminum-foil cartons intensifies because European smelter curtailments tightened 6-7 micron barrier layer availability. Beverage manufacturers exhibit highest price sensitivity for commodity polyethylene volumes, while private labelers absorb modest premiums for recyclability credentials.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian pulp supply routes to Indonesian and Indian converting clusters. Raw material dependencies center on Brazilian bleached kraft pulp, Russian-origin aluminum foil now excluded from European supply, and Saudi Arabian polyethylene resin for heat-seal layers. Single-source vulnerability concentrates in 6-7 micron foil specifications where two European suppliers control qualified aseptic-grade production. Distribution runs through direct-to-retailer contracts consolidating volume previously fragmented through São Paulo and Jakarta distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Format fragmentation creates specialist opportunities as shelf-life requirements diverge between ambient-stable emerging markets and refrigerated premium channels in developed retail networks.
For Market Incumbents: Shield technology leadership in aseptic filling systems by deepening technician training pipelines and securing aluminum foil supply agreements before further European smelter curtailments. Acquire closed-loop fiber recovery technology to defend margin position against aluminum-free barrier-coated paperboard displacement in German and Nordic retail procurement. For New Entrants and Emerging Players: Aseptic filling technician scarcity opens service-layer gaps where incumbents under-serve mid-sized beverage brands in Brazil and Indonesia. Target Indonesian convenience store expansion with flexible-volume carton formats and digital printing capabilities for SKU proliferation without plate changeover downtime. Pursue co-manufacturing partnerships with São Paulo and Jakarta-based juice processors seeking rapid format changeover. For Investors and Strategic Acquirers: The market sits at a substitution phase that favors integrated pulp-to-converting operators with captive fiber sourcing and aluminum supply security. Five-to-ten year viability hinges on closed-loop recycling technology maturation and biopolymer oxygen barrier performance improvement. Monitor ECHA PFAS restriction implementation timelines as inflection indicator for coating reformulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Smurfit Kappa's captive fiber sourcing anchors European paperboard cost position against import-dependent competitors. |
| Digital Printing Line Integration | Electron beam-cured ink adoption enables Tetra Pak and SIG Combibloc customers to proliferate SKUs without sterilization line downtime. |
| Aluminum-Free Barrier Coating Scale-Up | Aldi and Lidl procurement specifications accelerate German converter investment in fiber-stream-recyclable structures. |
| PLI-Incentivized Manufacturing Expansion | Maharashtra and Gujarat capacity additions reduce Indian juice brand import reliance on European and Southeast Asian carton supply. |
| Closed-Loop Fiber Recovery Partnership | Hydrogen peroxide bleaching and eddy-current sorting advances enable post-consumer carton material circularity compliance with EU Green Deal targets. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with packaging engineering directors, beverage procurement managers, aseptic filling technicians, and retail category buyers; and secondary validation through FSSAI additive approval databases, EU REACH substance restriction filings, customs records of aluminum foil trade flows, and SEC disclosures from integrated paperboard producers. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Across the analysis window, forecasts segmented by packaging type, material composition, application channel, and end-user supply chain position. CAGRs derived from installed aseptic filling line capacity expansion schedules, PLI scheme incentive uptake trajectories in Indian states, and convenience store format rollout timelines in Indonesian urban markets. Price elasticity assumptions incorporated retailer private-label procurement scorecard weights for recyclability credentials.
Underlying assumptions cover aluminum foil supply continuity, biopolymer oxygen barrier performance improvement curves, and EFSA migration limit stability, with deviation risk concentrated in European smelter curtailment duration and PFAS substitution timeline acceleration. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down implementation and Indonesian retail modernization pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverage Packaging
Indonesia Plastic Bottles Market
Beverage Packaging
Dispensing Carboy Market
Beverage Packaging
Twin Neck Bottles Market
Beverage Packaging
Pop-Up Pourer Market
Beverage Packaging
Reservoir Media Bottle Market
Beverage Packaging
Water Cooler Market
Beverage Packaging
Biotainer Market
Beverage Packaging
Media Bottles Market
Beverage Packaging
Bottle Pourers Market
Beverage Packaging
Cardboard Flask Market
Beverage Packaging
PET Bottle Market
Beverage Packaging
Beverage Packaging Machine Market
Beverage Packaging
Bottle Dividers Market
Beverage Packaging
Beverage Packaging Market
Beverage Packaging
Disposable Water Bottle Market
Beverage Packaging
Heavy Wall Bottles Market