
 United States Container Glass Market | 2026-2036
United States Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
United States Container Glass Market Insights
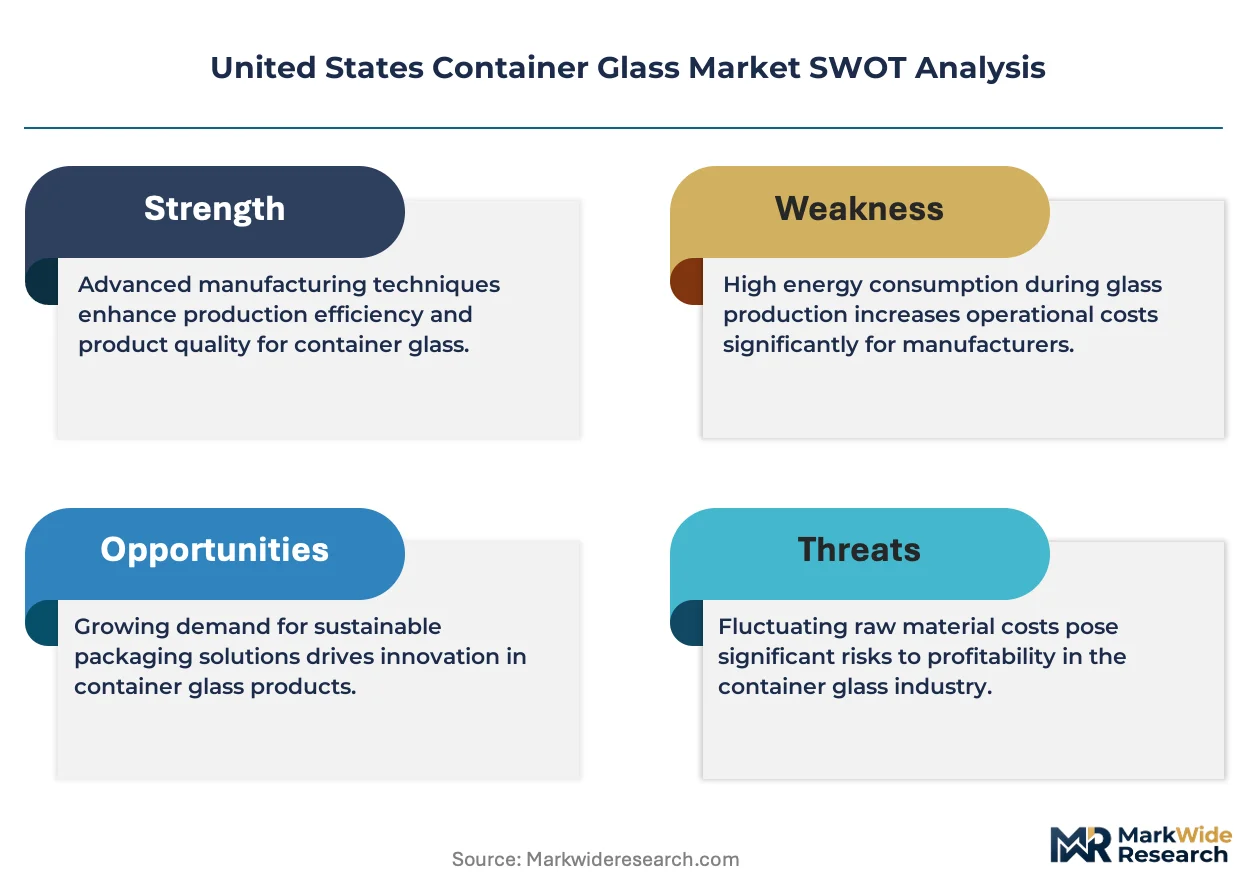
The EPA's recycled content mandates for glass packaging is realigning procurement priorities across beverage and pharmaceutical supply chains. Owens-Illinois, Inc. leverages its furnace modernization programs to sustain energy efficiency leadership in domestic production. Ardagh Group anchors its competitive stance through extensive cullet processing infrastructure across multiple US states. Verallia competes aggressively in the premium spirits segment where weight reduction and aesthetic differentiation command pricing power.
Container glass refers to soda-lime-silica vessels formed through blow-and-blow or press-and-blow processes, typically containing 70-74% silica, 12-16% soda ash, and 10-13% lime for chemical durability and thermal shock resistance. These containers serve as chemically inert barriers for oxygen-sensitive and light-sensitive contents across food, beverage, and pharmaceutical applications. Bottles dominate volume throughput in the product type dimension, while jars capture higher margin pools in specialty food and cosmetics segments. The Food & Beverage end use industry absorbs the majority of domestic tonnage, though Pharmaceuticals generates superior per-unit value through stringent USP Type I borosilicate requirements.
FDA cGMP standards govern pharmaceutical glass container integrity, while OSHA silica exposure limits shape furnace workplace configurations and capital planning. The EPA's Resource Conservation and Recovery Act provisions and state-level bottle bill frameworks directly influence cullet availability and recycling economics for domestic manufacturers. Stakeholders must monitor evolving state legislation on extended producer responsibility and carbon border adjustments that could reshape cost structures for imported versus domestically produced container glass.
Market Dynamics
EPA recycled content mandates are compressing domestic cullet supply chains while furnace electrification investments reshape capital deployment timelines across the Southeast manufacturing corridor.
Growth Catalysts
- State bottle deposit expansions:New York and California deposit law extensions tighten cullet circulation loops and improve feedstock quality for domestic remelting operations.
- Premium spirits packaging commitments:Bourbon and tequila producers anchor demand for heavyweight, embossed bottles with superior oxygen barrier performance.
- Electrified furnace retrofits:Hydrogen-ready and all-electric melting technologies reduce Scope 1 emissions intensity while qualifying manufacturers for IRA clean energy production credits.
Market Restraints
- Soda ash supply concentration:Wyoming trona deposits and limited domestic synthetic soda ash capacity expose manufacturers to rail logistics bottlenecks and energy input volatility.
- Silica exposure compliance:OSHA permissible exposure limits for respirable crystalline silica drive capital-intensive furnace ventilation upgrades and workplace reconfigurations.
- Aluminum can substitution:Beverage brands facing freight cost pressure pivot to lighter metal packaging for single-serve formats, compressing glass volume in mainstream beer segments.
Strategic Opportunities
- Pharmaceutical USP Type I expansion:Injectable biologics growth creates demand for borosilicate vials and ampoules with superior chemical durability and thermal shock resistance.
- Georgia-South Carolina corridor densification:Proximity to Savannah and Charleston port infrastructure enables export-oriented premium spirits packaging for Latin American markets.
- Extended producer responsibility frameworks:Emerging state-level EPR legislation in Oregon and Colorado mandates producer-funded collection infrastructure, stabilizing post-consumer cullet economics.
Industry Challenges
- Furnace refractory engineering talent:Specialized ceramic engineering expertise for 1500°C+ melting environments faces generational workforce gaps as veteran operators retire.
- Multi-year certification timelines:FDA cGMP validation for pharmaceutical container glass requires 18-36 month approval cycles that delay new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Container Glass Market |
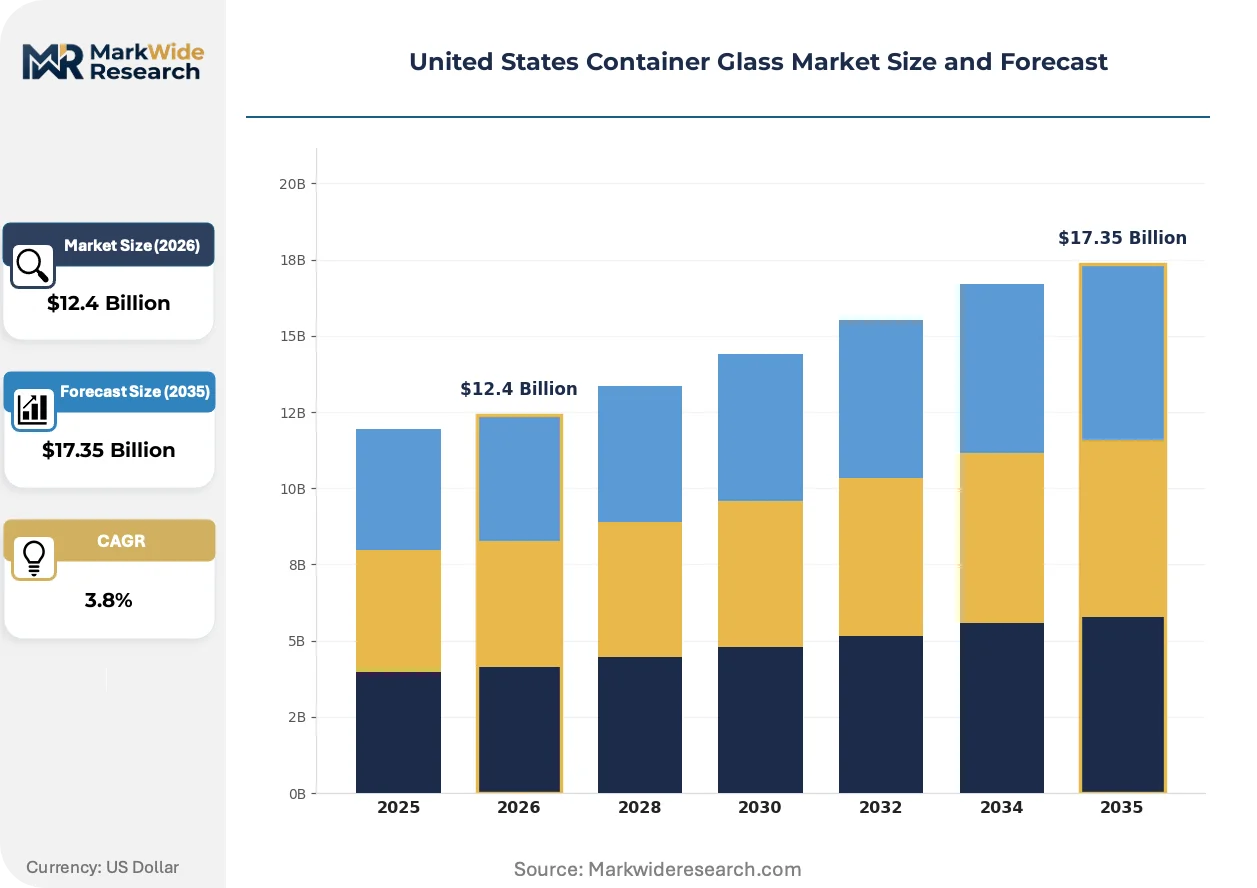
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $17.35 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Household Manufacturing Stage: Primary, Secondary, Tertiary, Specialty Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | Owens-Illinois, Inc., Ardagh Group, Verallia, Anchor Glass Container Corporation, Vitro Packaging, West-Pack, LLC, Gerresheimer AG, Stoelzle Glass USA Inc., Heinz Glas USA Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Container Glass Market Trends and Innovations
Lightweighting technologies and digital printing integration are redefining value capture models across food, beverage, and pharmaceutical packaging tiers.
Electrified melting systems with hydrogen-ready burner configurations are overtaking natural gas-fired furnaces in new capital planning. Spirits producers and pharmaceutical contract packagers are specifying these systems for Scope 3 reporting compliance. The shift is compressing payback period calculations for equipment suppliers while elevating energy engineering capabilities to core competitive differentiators.
The EPA's Resource Conservation and Recovery Act recycled content mandates are tightening cullet procurement specifications for domestic manufacturers. State-level bottle bill expansions in the Northeast and Pacific Coast are redirecting post-consumer glass flows toward certified recycling streams. Food and beverage brand owners are responding by embedding recycled content targets into supplier scorecards and multi-year procurement agreements.
Direct-to-glass digital printing is displacing applied ceramic labeling in premium spirits and craft beverage segments. Brand owners in Kentucky and Tennessee are adopting this technology for short-run customization and regional market testing. The capability is compressing minimum order quantities and enabling geographic versioning without mold changeover costs.
United States Container Glass Market Segmentation
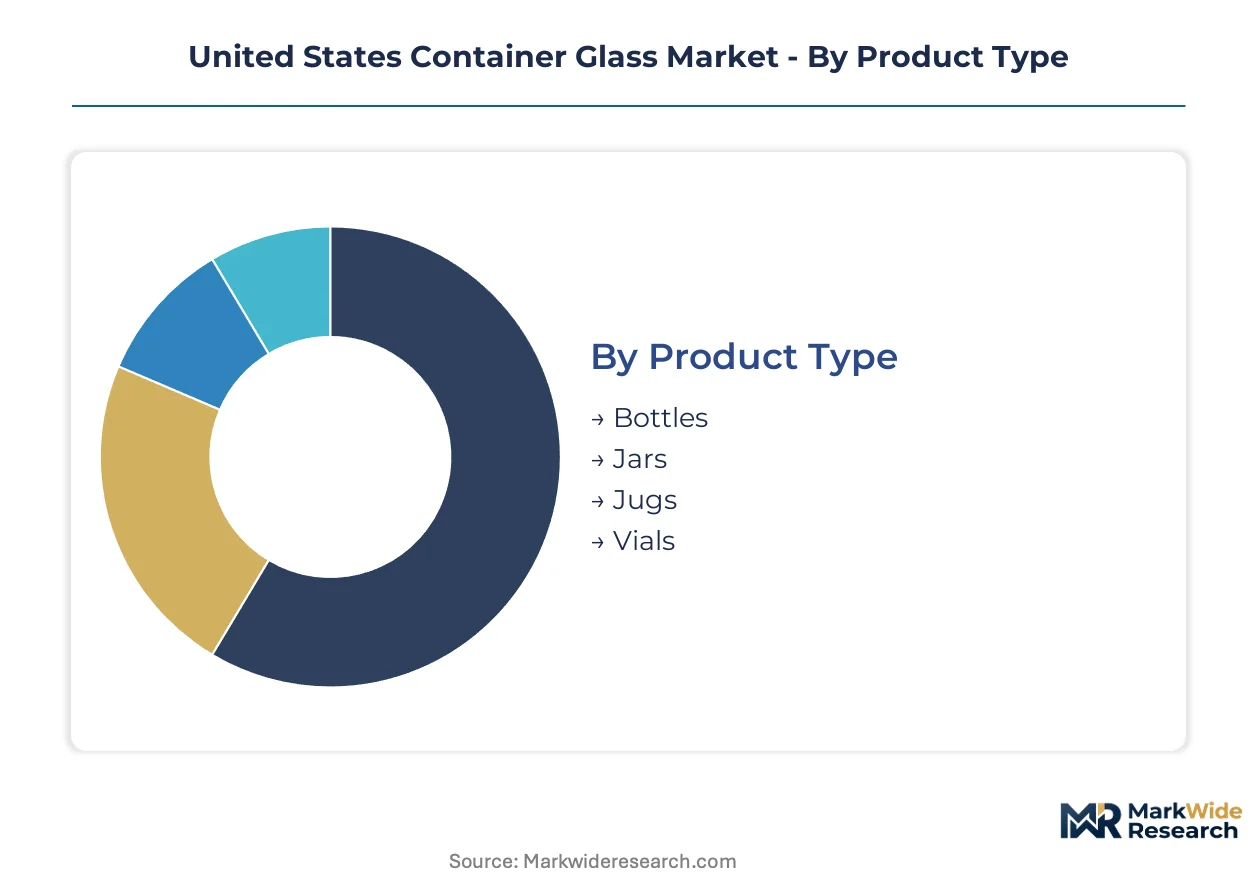
Segmentation in the United States container glass market reveals how furnace configurations, cullet specifications, and regulatory compliance requirements diverge across product tiers. Understanding these divisions exposes where capital deployment and procurement negotiations concentrate leverage for manufacturers and brand owners.
Product Type:
Customization intensity spans from standardized high-volume formats to engineered vessels demanding unique mold investments and surface treatments.
- Bottles:Soda-lime-silica vessels formed through blow-and-blow or press-and-blow processes, typically 70-74% silica composition for chemical durability. Demand concentrates in Kentucky and Tennessee bourbon corridors where heavyweight embossed designs command premium positioning against aluminum can substitution.
- Jars:Wide-mouth containers with higher thermal shock resistance specifications for hot-fill applications. Specialty food packers in the Southeast manufacturing corridor drive specifications for vacuum-seal compatibility and label adhesion surfaces.
- Jugs:High-capacity formats for bulk wine and spirits distribution. California Central Valley wineries anchor procurement volumes with lightweighting targets to offset freight cost pressure.
- Vials:Small-diameter borosilicate or soda-lime containers for pharmaceutical and laboratory applications. USP Type I certification requirements from FDA govern surface chemistry and hydrolytic resistance specifications.
Most installed capacity flows through Bottles. Expansion is steepest in Vials.
End Use Industry:
Margin structures diverge sharply between commodity beverage tonnage and regulated pharmaceutical applications with multi-year certification timelines.
- Food & Beverage:Absorbs majority domestic tonnage across beer, wine, spirits, and specialty food segments. Georgia and North Carolina production corridors serve Southeast bottling operations with proximity to Savannah port infrastructure for Latin American export.
- Pharmaceuticals:Injectable biologics growth creates demand for borosilicate vials and ampoules with superior chemical durability. FDA cGMP validation cycles of 18-36 months delay new product commercialization and lock in supplier relationships.
- Cosmetics:Premium fragrance and skincare brands specify heavy-wall bottles with deep embossing and applied ceramic decoration. Short-run flexibility requirements favor digital printing adoption over traditional label application.
- Household:Standardized containers for cleaning products and industrial chemicals. Price pressure from polyethylene terephthalate and high-density polyethylene alternatives constrains glass penetration in volume segments.
Food & Beverage commands the largest furnace allocation. Pharmaceuticals delivers the steepest margin expansion trajectory.
Manufacturing Stage:
Capital intensity escalates from commodity remelting operations through specialized surface treatment and decoration capabilities.
- Primary:Raw batch melting and forming from virgin soda ash, silica sand, and lime. Wyoming trona deposits and domestic silica mining anchor supply chains with rail logistics exposure.
- Secondary:Cullet-based remelting with EPA recycled content mandates tightening feedstock specifications. State bottle deposit expansions in New York and California improve post-consumer glass quality for certified recycling streams.
- Tertiary:Decoration, labeling, and surface treatment operations including applied ceramic labels and direct-to-glass digital printing. Kentucky spirits producers adopt short-run customization for regional market testing.
- Specialty:Borosilicate conversion and pharmaceutical-grade finishing with USP Type I validation. OSHA silica exposure limits drive capital-intensive ventilation upgrades and workplace reconfigurations.
Primary melting holds the dominant capacity base. Specialty stage operations are climbing the fastest as pharmaceutical outsourcing expands.
Distribution Channel:
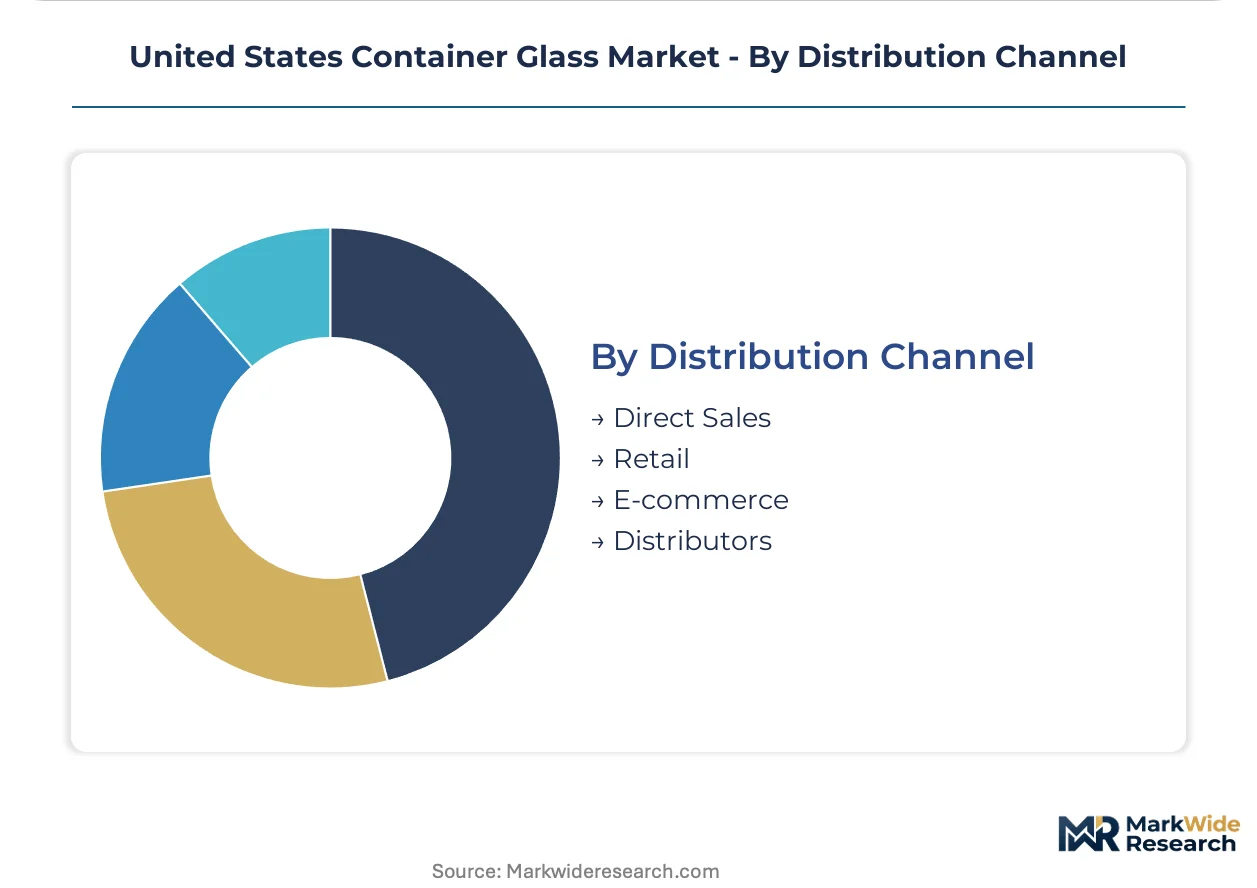
Channel selection reflects order scale, customization requirements, and geographic concentration of end-use manufacturing.
- Direct Sales:Long-term procurement agreements between container manufacturers and national beverage brands. Multi-year contracts embed recycled content targets and carbon accounting requirements.
- Retail:Limited application for container glass given industrial nature of demand. Some craft beverage and specialty food segments source through packaging distributors with stock mold programs.
- E-commerce:Emerging channel for small-batch spirits and cosmetic brands requiring low minimum order quantities. Digital printing capabilities compress order thresholds without mold changeover costs.
- Distributors:Regional packaging suppliers aggregate demand from mid-tier food and beverage producers. Inventory pooling reduces lead times for standard bottle and jar formats.
Direct Sales captures the majority of tonnage. E-commerce is gaining share fastest among emerging craft brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States container glass industry traces its industrial foundation to Pittsburgh's 19th-century furnace corridors, where coal-fired melting technology first achieved commercial scale. Today production concentrates in three distinct manufacturing belts shaped by feedstock access, beverage industry clustering, and port infrastructure for export markets.
Southeast Manufacturing Corridor
Kentucky bourbon distillers and Georgia beverage bottlers anchor regional demand for heavyweight embossed bottles. Georgia and South Carolina legislators are advancing extended producer responsibility frameworks modeled on Oregon's packaging laws. Savannah and Charleston port facilities enable premium spirits exports to Latin American markets, with furnace investments tracking container shipping schedules.
Midwest Industrial Belt
Ohio and Indiana host legacy furnace infrastructure serving national beer and food packaging accounts. OSHA silica exposure enforcement in these states drives capital-intensive ventilation retrofits at aging production sites. Toledo and Muncie manufacturing clusters concentrate secondary cullet processing capacity for EPA-mandated recycled content blending.
California Central Valley
Wine producers in Napa and Sonoma counties specify lightweight jug formats to offset freight cost pressure from distribution distances. California's bottle deposit expansion tightens post-consumer glass circulation loops and improves feedstock quality for certified recycling streams. Modesto and Fresno processing facilities anchor West Coast cullet supply chains.
Northeast Packaging Hub
New York and New Jersey pharmaceutical contract packers generate demand for USP Type I borosilicate vials with 18-36 month FDA validation cycles. New York's deposit law extension redirects municipal glass flows toward domestic remelting operations. Newark and Philadelphia corridor facilities serve injectable biologics manufacturers with specialized borosilicate conversion capabilities.
Texas Gulf Coast
Permian Basin chemical and petroleum operations sustain niche demand for industrial container glass despite polyethylene substitution pressure. Texas environmental regulators are evaluating carbon border adjustment mechanisms that could reshape import economics. Houston-area distribution infrastructure serves Mexican export markets through Laredo and Eagle Pass logistics corridors.
United States Container Glass Market Competitive Landscape
Capital-heavy furnace operators compete with asset-light specialty converters in a bifurcated structure. The market consolidates around three integrated producers controlling primary melting capacity, while fragmented secondary players occupy decoration and pharmaceutical finishing niches. Strategic archetypes include integrated furnace operators with captive cullet networks, pharmaceutical-grade specialists with FDA validation capabilities, and regional converters serving craft beverage short-run requirements. Competitive dynamics center on electrification retrofit timing and multi-year procurement agreements embedding recycled content targets.
Among integrated producers, Owens-Illinois, Inc. and Ardagh Group occupy positions defined by furnace scale and geographic coverage breadth. Verallia represents the premium spirits specialization archetype where aesthetic differentiation commands pricing power. These three entities anchor the competitive structure through their control over primary melting infrastructure and their negotiation leverage with national beverage brand procurement teams.
| Leading Market Players |
|---|
| Owens-Illinois, Inc. |
| Ardagh Group |
| Verallia |
| Anchor Glass Container Corporation |
| Vitro Packaging |
| West-Pack, LLC |
| Gerresheimer AG |
| Stoelzle Glass USA Inc. |
| Heinz Glas USA Inc. |
| Others |
Pricing and Supply Chain Analysis
EPA recycled content mandates are forcing beverage brand procurement teams to rewrite supplier scorecards around certified cullet percentages, compelling furnace operators to absorb higher feedstock costs or risk contract non-compliance. This specification tightening concentrates pricing power with integrated producers controlling captive cullet networks across the Southeast manufacturing corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heavyweight embossed spirits bottles from commodity beer formats and generic food jars. Price differentiation rests on mold complexity and thermal shock certification grade, with bourbon producers in Kentucky showing lowest price sensitivity for oxygen barrier performance. Cost compression in standard-tier beer bottles is intensifying because aluminum can substitution erodes volume leverage. Food packers in the Southeast demonstrate highest price sensitivity due to polyethylene terephthalate alternative availability.
Supply Chain Analysis
Regional distribution centers in Georgia and South Carolina operate hub-and-spoke patterns feeding Southeast bottling corridors with furnace-direct shipments. Geographic supply concentration draws from Wyoming trona deposits, domestic silica mining operations, and post-consumer cullet processing facilities in New York and California. Raw material dependencies rest on soda ash, silica sand, and lime flux. Supply chain risk centers on rail logistics bottlenecks from Wyoming. Distribution runs through direct long-term procurement agreements with national beverage brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States container glass market reads as a late-cycle quality story. Injectable biologics expansion is redirecting capital toward USP Type I borosilicate certification capabilities.
For Market Incumbents: Anchor competitive position through furnace electrification retrofits qualifying for IRA clean energy production credits. Defend against aluminum can substitution by locking multi-year spirits packaging contracts with recycled content targets. Prioritize backward integration into cullet processing infrastructure ahead of state-level extended producer responsibility mandates. For New Entrants and Emerging Players: The EPA's Resource Conservation and Recovery Act recycled content mandates open a window for specialty cullet processors with certified feedstock capabilities. Target pharmaceutical finishing operations in the Northeast corridor where FDA validation timelines lock out commodity competition. Pursue e-commerce channel partnerships with craft spirits brands requiring short-run digital printing flexibility. For Investors and Strategic Acquirers: Asymmetric upside sits with pharmaceutical-grade specialists holding USP Type I validation and borosilicate conversion capabilities. Long-term viability favors assets with hydrogen-ready furnace configurations and Scope 1 emissions reduction trajectories. Watch electrification retrofit completion rates across the Southeast manufacturing corridor as inflection indicator for production cost positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Retrofit | IRA clean energy credits reduce Scope 1 emissions intensity for Owens-Illinois and Ardagh Group operations. |
| Backward Integration into Cullet Processing | Captive feedstock supply secures EPA compliance margins ahead of state bottle deposit expansions. |
| USP Type I Certification Investment | FDA validation capabilities capture injectable biologics growth in Northeast pharmaceutical corridors. |
| Direct-to-Glass Digital Printing Adoption | Kentucky spirits producers leverage short-run customization for regional market testing without mold costs. |
| Extended Producer Responsibility Partnership | Oregon and Colorado legislation stabilizes post-consumer cullet economics for domestic remelting operations. |
Research Methodology
Coverage spans the Southeast manufacturing corridor, Midwest industrial belt, California Central Valley, Northeast packaging hub, and Texas Gulf Coast, with primary inputs from each. The study combines interviews with furnace operations managers, beverage brand procurement directors, pharmaceutical contract packers, and cullet processing facility operators with secondary validation against EPA enforcement data, FDA cGMP guidance documents, state bottle bill legislation, and SEC filings from integrated producers. Bottom-up capacity assessments and top-down demand modeling provide triangulation across the analysis window.
Rate-of-change decomposition separates volume growth from value expansion across product type, end use industry, manufacturing stage, and distribution channel dimensions. CAGRs derive from regression analysis against historical furnace throughput, spirits packaging commitments, and pharmaceutical outsourcing trends. Forecast inputs incorporate electrification retrofit timelines, state-level extended producer responsibility adoption curves, and aluminum substitution elasticity in mainstream beer segments.
Revisions become necessary when EPA recycled content mandates accelerate, state bottle deposit expansions redirect cullet flows, or furnace refractory engineering talent shortages constrain capacity expansion. Forecasts reflect documented assumptions around energy input costs, rail logistics performance, and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Container Glass Coatings Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
France Container Glass Market
Glass Packaging
Europe Cosmetic and Perfumery Glass Bottle Packaging Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Italy Container Glass Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market