
 Treatment Planning Systems and Advanced Image Processing Market | 2026-2036
Treatment Planning Systems and Advanced Image Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Treatment Planning Systems and Advanced Image Processing Market Intelligence
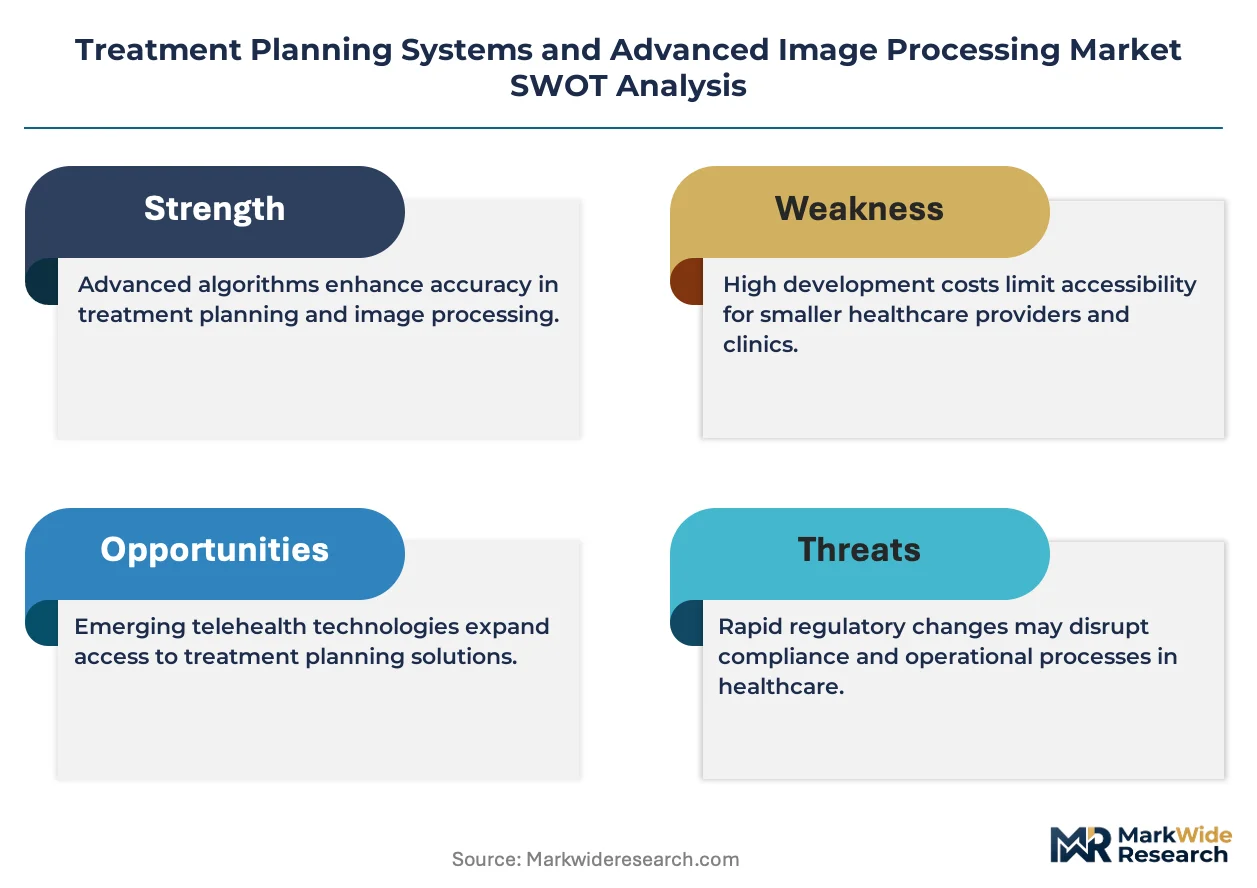
Single-source reliance on proprietary hardware-software bundles is consolidating toward multi-vendor architectures that separate imaging acquisition from planning computation. Siemens Healthineers leverages its MR-linac installed base to sustain recurring software revenue across European proton centers. Varian Medical Systems anchors its position through backward integration into Monte Carlo dose calculation engines, while RaySearch Laboratories competes by offering planning algorithms compatible with rival hardware platforms.
Treatment planning systems and advanced image processing comprise software platforms that fuse multimodal imaging data with computational dose algorithms to generate patient-specific therapeutic protocols, typically processing DICOM datasets through GPU-accelerated rendering pipelines. These systems serve primarily to optimize radiation delivery geometry and quantify tumor response metrics ahead of clinical intervention. Radiation therapy software occupies the dominant revenue position given its embedded role in linear accelerator workflows, whereas image analysis software represents the fastest-expanding margin pool as FDA-cleared AI segmentation tools displace manual contouring in busy hospital departments. Cloud computing infrastructure is displacing on-premise server deployments among mid-size oncology clinics seeking elastic storage for expanding PET-CT imaging volumes.
FDA 510(k) clearance requirements govern algorithmic safety for autonomous contouring modules, while HIPAA mandates encrypt patient data flows between cloud-hosted planning environments and hospital PACS networks. The EU MDR imposes clinical validation burdens on AI-assisted planning tools entering European markets, extending certification timelines for non-European developers. Stakeholders must monitor evolving interoperability standards between competing vendor ecosystems as health systems demand seamless data exchange across heterogeneous device fleets.
Market Dynamics
AI-driven autosegmentation is compressing planning timelines from hours to minutes, forcing vendors to rearchitect software licensing models around per-case rather than perpetual fees. This computational shift redistributes value from hardware bundling toward algorithmic performance guarantees.
Growth Catalysts
- FDA 510(k) De Novo Pathway:Streamlined clearance for AI contouring modules accelerates deployment across US academic medical centers, reducing validation burdens for novel algorithms.
- Proton Therapy Infrastructure:Construction of particle therapy suites in Texas, Florida, and Ohio generates demand for Monte Carlo-compatible planning platforms with multi-criteria optimization.
- CMS Reimbursement Tightening:Quality-based payment programs penalize planning deviations, compelling community oncology practices to adopt automated plan-checking software.
Market Restraints
- GPU Compute Cost Volatility:NVIDIA data center chip shortages inflate cloud rendering expenses for smaller proton centers, squeezing margins on AI-enhanced planning subscriptions.
- Single-Vendor Hardware Lock-in:Linear accelerator manufacturers restrict third-party software API access, fragmenting interoperability across Varian, Elekta, and Siemens installed bases.
- EU MDR Clinical Validation Burden:Extended certification timelines for AI-assisted planning tools delay European market entry for non-European algorithm developers by 18-24 months.
Strategic Opportunities
- India Oncology Network Expansion:Tata Memorial Centre and AIIMS Delhi procurement cycles create entry points for cloud-native planning platforms serving tier-2 cities with limited physicist staffing.
- MR-Guided Adaptive Therapy:Real-time imaging during fractionated delivery converges planning and treatment execution, enabling same-day plan adaptation for mobile tumors.
- HIPAA-Compliant Edge Computing:Federated learning architectures allow model training across hospital networks without centralizing protected health information, reducing data governance friction.
Industry Challenges
- Medical Physics Talent Scarcity:Board-certified dosimetrist shortages in rural US markets limit adoption of complex inverse planning workflows requiring specialized manual oversight.
- Legacy PACS Integration Friction:DICOM-RT compatibility gaps between 1990s-era imaging archives and modern AI planning environments force expensive middleware development.
- Algorithm Liability Ambiguity:Unclear fault allocation between software vendors and treating physicians when autonomous contouring errors propagate into delivered dose distributions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treatment Planning Systems and Advanced Image Processing Market |
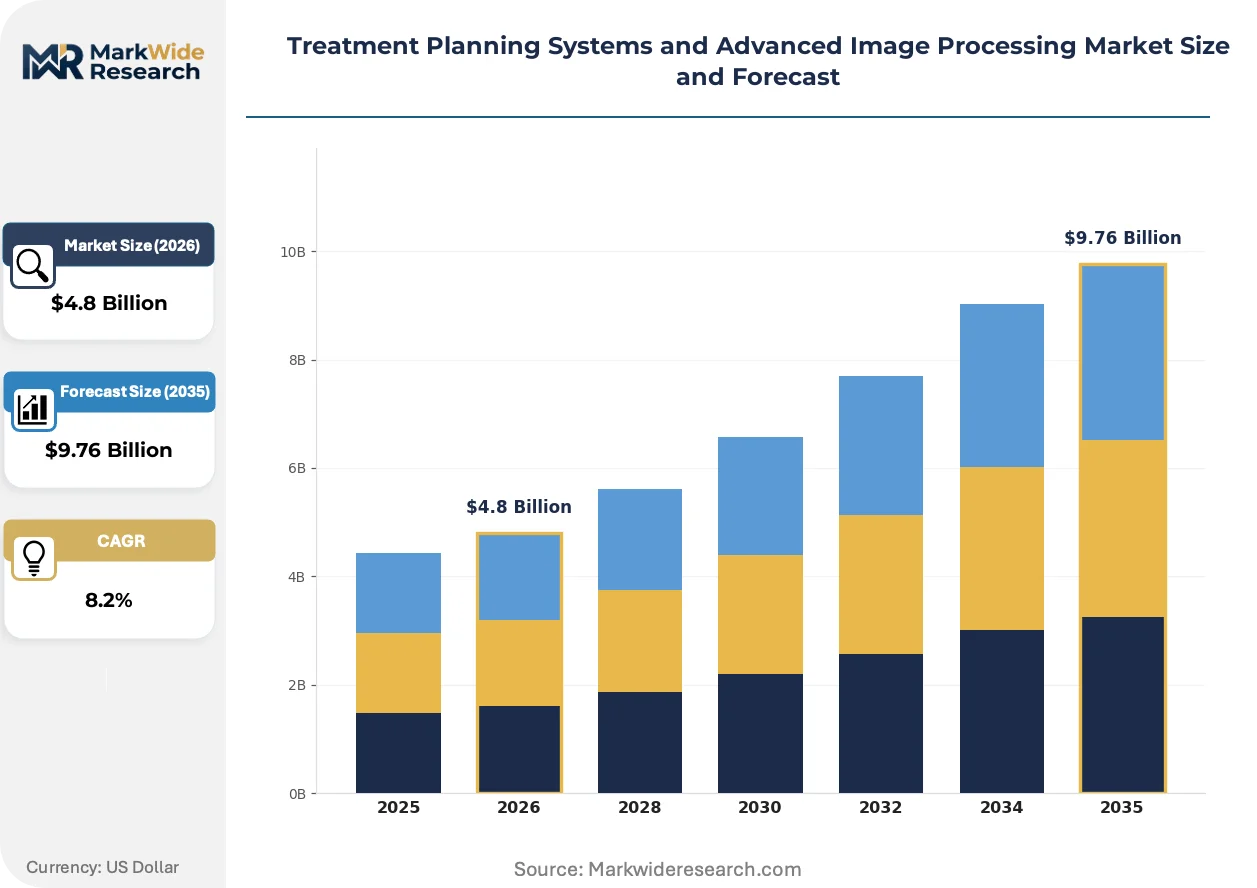
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiation Therapy Software, Surgical Planning Tools, Image Analysis Software, 3D Reconstruction Tools Technology: Machine Learning, Artificial Intelligence, Cloud Computing, Digital Imaging End User: Hospitals, Research Institutions, Diagnostic Centers, Oncology Clinics Application: Radiation Oncology, Surgical Procedures, Diagnostic Imaging, Treatment Assessment |
| Companies Covered | Accuray Incorporated, Elekta AB, RaySearch Laboratories, Brainlab AG, Koninklijke Philips N.V., Varian Medical Systems, Siemens Healthineers AG, GE HealthCare Technologies Inc., MIM Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treatment Planning Systems and Advanced Image Processing Market Strategic Shifts & Innovations
Computational methods are migrating from deterministic algorithms toward probabilistic deep learning models that learn planning patterns from institutional archives. This shift redefines quality assurance protocols and vendor-customer data relationships.
Deep learning-based autosegmentation is absorbing manual contouring workloads previously performed by dosimetrists and radiation oncologists. Community hospitals with limited specialist staffing deploy these tools to maintain plan quality despite workforce constraints. The technology is absorbing planning variability across operators, compressing inter-observer contouring disagreement rates and standardizing target volume definitions for multi-site clinical trials.
The EU MDR's clinical performance documentation requirements for AI-assisted medical devices impose retrospective validation studies on planning algorithm developers. European notified bodies demand real-world evidence of dose prediction accuracy across diverse patient anatomies. Proton therapy planning software faces the steepest compliance burden, as limited European patient volumes complicate statistical powering for equivalence demonstrations.
Subscription pricing for cloud-hosted planning environments displaces capital-intensive on-premise server procurement among mid-size oncology groups. Hospital systems unbundle software licenses from linear accelerator purchase agreements, selecting best-of-breed planning tools independent of hardware vendor. This preference shift concentrates in the southeastern United States, where hospital consolidation creates purchasing entities with sufficient scale to negotiate multi-vendor interoperability mandates.
Treatment Planning Systems and Advanced Image Processing Market Segmentation
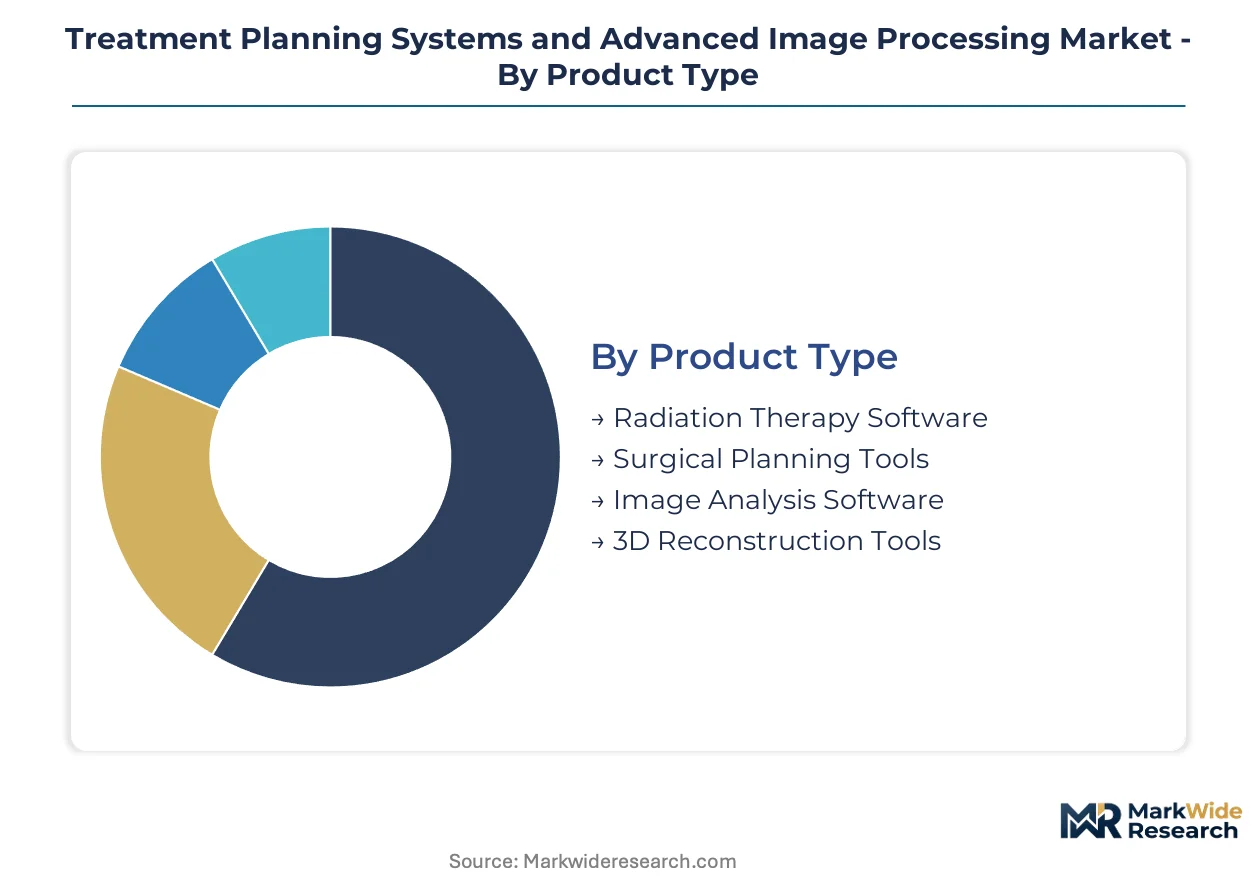
Segmentation reveals how procurement power concentrates across distinct technology tiers and clinical settings. Understanding these divides exposes where margin pools shift and where interoperability requirements create vendor switching costs.
Product Type:
Supply concentration clusters around platforms embedded in linear accelerator workflows, with hardware-software bundling historically locking customers into single-vendor ecosystems.
- Radiation Therapy Software:Computational dose algorithms process DICOM-RT datasets to optimize beam geometry and fractionation schedules. Demand concentrates in United States academic medical centers replacing legacy cobalt systems under tightening CMS quality metrics. This segment absorbs the bulk of installed capacity.
- Image Analysis Software:AI segmentation modules autonomously contour organs-at-risk and target volumes from multimodal imaging. European proton centers and North American community oncology practices deploy these tools to offset medical physics staffing shortages. This segment is expanding most quickly.
- Surgical Planning Tools:Preoperative navigation platforms fuse CT-MRI data for robotic-assisted interventions in neurosurgery and orthopedics.
- 3D Reconstruction Tools:Volume rendering pipelines generate patient-specific anatomical models for procedural simulation and patient education.
Radiation therapy software commands the dominant revenue position; image analysis software captures the steepest expansion trajectory.
Technology:
Cost tier differentiation separates capital-intensive on-premise deployments from subscription-based cloud offerings that reduce upfront infrastructure burdens for mid-size clinics.
- Artificial Intelligence:Deep learning models trained on institutional archives automate contouring and dose prediction, compressing planning timelines from hours to minutes. FDA 510(k) De Novo pathway accelerations in the United States and EU MDR clinical validation requirements in Europe create divergent compliance costs for algorithm developers.
- Cloud Computing:Elastic storage and GPU-accelerated rendering replace on-premise server farms, enabling smaller proton centers to access Monte Carlo dose calculations without capital investment. HIPAA-compliant architectures and federated learning approaches address data governance constraints across hospital networks.
- Machine Learning:Deterministic algorithms with traceable decision pathways persist in regulatory-sensitive applications requiring explicit validation documentation.
- Digital Imaging:DICOM-standardized acquisition and PACS integration pipelines form the foundational infrastructure layer for all downstream planning workflows.
Artificial intelligence and cloud computing together reshape vendor-customer relationships; machine learning retains footholds where interpretability mandates persist.
End User:
Customer type determines purchasing sophistication, with consolidated health systems extracting multi-vendor interoperability concessions unavailable to independent practices.
- Oncology Clinics:Specialized radiation therapy providers drive replacement cycles for planning systems, particularly in United States markets where proton therapy center construction in Texas, Florida, and Ohio generates demand for Monte Carlo-compatible platforms. These clinics unbundle software from linear accelerator purchases to select best-of-breed planning tools.
- Hospitals:Integrated delivery networks negotiate enterprise licenses spanning radiation oncology, surgical services, and diagnostic imaging departments. Southeastern United States health system consolidation creates purchasing entities with scale to mandate cross-vendor data exchange.
- Research Institutions:Academic medical centers validate novel algorithms and train planning models on diverse patient anatomies for regulatory submission.
- Diagnostic Centers:Imaging-focused facilities require planning system compatibility for referral workflows into radiation and surgical treatment settings.
Oncology clinics and hospitals together dominate procurement volume; research institutions anchor algorithm validation pipelines.
Application:
Maturity gradients separate established radiation oncology workflows from emerging adaptive therapy applications requiring real-time imaging integration.
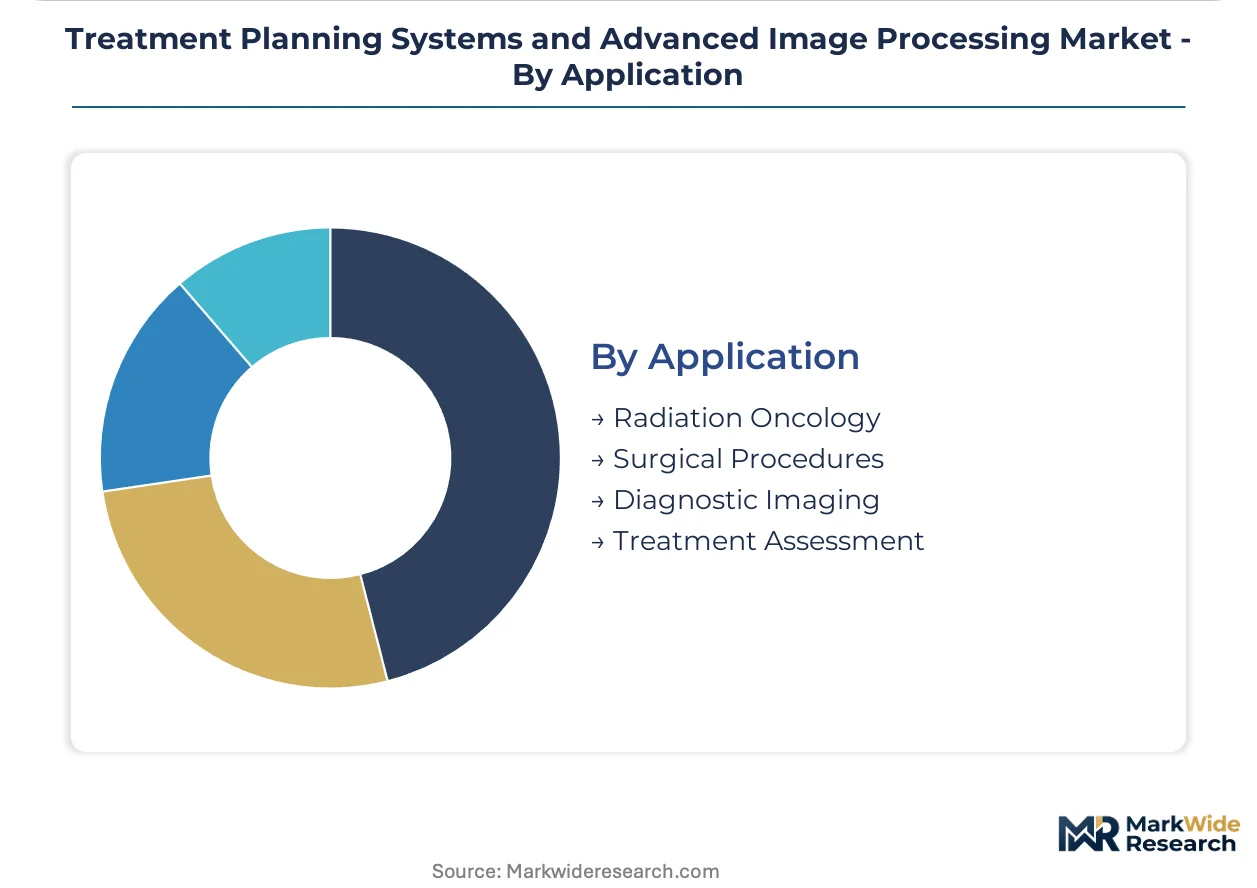
- Radiation Oncology:Fractionated external beam and brachytherapy planning constitute the core installed base, with inverse planning and multi-criteria optimization now standard in United States academic centers. Quality-based payment programs penalize planning deviations, compelling automated plan-checking adoption.
- Treatment Assessment:Response quantification tools measure tumor volume changes and dose delivery accuracy across fractionated courses, enabling same-day plan adaptation for mobile tumors in MR-guided adaptive therapy workflows.
- Surgical Procedures:Preoperative planning integrates with robotic navigation systems for precision tumor resection and anatomical reconstruction.
- Diagnostic Imaging:Quantitative biomarker extraction from PET-CT and MRI supports staging and treatment response monitoring across oncology service lines.
Radiation oncology retains the deepest installed base; treatment assessment capabilities are climbing the fastest as adaptive therapy converges planning with delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU fabrication capacity in Taiwan and South Korea anchors the hardware substrate for AI planning platforms, while proton therapy infrastructure investments concentrate in North American and European metropolitan clusters.
United States
Academic medical centers in Texas, Florida, and Ohio drive procurement of Monte Carlo-compatible planning systems for new proton therapy suites. FDA 510(k) De Novo pathway accelerations compress validation timelines for AI contouring modules. The southeastern hospital consolidation wave creates purchasing entities demanding multi-vendor interoperability across Varian, Elekta, and Siemens installed bases.
Germany
Heidelberg and Munich proton centers sustain demand for multi-criteria optimization platforms with MR-linac integration. EU MDR clinical validation requirements extend certification timelines for non-European algorithm developers by 18-24 months. Siemens Healthineers leverages its domestic installed base to secure recurring software revenue across European particle therapy networks.
India
Tata Memorial Centre and AIIMS Delhi procurement cycles create entry points for cloud-native planning platforms serving tier-2 cities with limited physicist staffing. CDSCO medical device regulations govern AI-assisted planning tool approvals, though enforcement capacity varies across states. Bangalore and Hyderabad imaging technology clusters incubate domestic software vendors targeting cost-sensitive oncology networks.
Japan
PMDA regulatory pathways for AI medical devices require domestic clinical trials, favoring partnerships between global vendors and local distributors. Tokyo and Osaka academic hospitals anchor adoption of adaptive therapy workflows with real-time MR guidance. METI industrial policy supports proton therapy equipment exports, reinforcing domestic planning software development capabilities.
United Kingdom
NHS England proton therapy procurement concentrates demand at Christie Manchester and University College London Hospital sites. MHRA post-Brexit regulatory autonomy diverges from EU MDR timelines, creating parallel certification requirements for algorithm developers. London and Cambridge health technology clusters attract planning software R&D investment targeting European market entry.
Treatment Planning Systems and Advanced Image Processing Market Key Industry Players
Global majors compete with regional champions across hardware-software bundling strategies, with linear accelerator manufacturers historically restricting third-party API access to protect installed base revenue. The vendor landscape organizes into three archetypes: integrated hardware-software conglomerates, independent planning software specialists, and imaging equipment vendors extending into oncology workflows. Dominant competitive moves include backward integration into Monte Carlo dose engines and geographic expansion through proton therapy infrastructure partnerships.
Among integrated hardware-software conglomerates, Siemens Healthineers AG and Varian Medical Systems exemplify archetypes leveraging installed linear accelerator bases to sustain recurring software revenue. RaySearch Laboratories occupies a position as an independent planning software specialist competing through cross-platform algorithm compatibility. Elekta AB represents the European challenger archetype with proton therapy and MR-linac hardware anchoring planning system deployment.
| Leading Market Players |
|---|
| Accuray Incorporated |
| Elekta AB |
| RaySearch Laboratories |
| Brainlab AG |
| Koninklijke Philips N.V. |
| Varian Medical Systems |
| Siemens Healthineers AG |
| GE HealthCare Technologies Inc. |
| MIM Software Inc. |
| Others |
Cost & Logistics Intelligence
NVIDIA data center GPU pricing volatility cascades through cloud rendering services into subscription tiers for AI-enhanced planning platforms, compressing margins for smaller proton centers while consolidating pricing power among hyperscale hospital networks with captive compute infrastructure.
Pricing Analysis
Warranty and service bundling separates perpetual license holders from subscription customers, with the latter receiving automated algorithm updates and regulatory compliance patches as part of recurring fees. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and Monte Carlo dose calculation sophistication. Cost compression in the economy tier intensifies because GPU compute shortages inflate cloud rendering expenses. Community oncology practices exhibit the highest price sensitivity, whereas academic medical centers prioritize algorithmic performance guarantees over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle enterprise license negotiations for consolidated health systems, while value-added distributors serve independent oncology clinics with bundled implementation support. GPU fabrication concentrates in Taiwan and South Korea, with final software assembly and regulatory packaging occurring in the United States and Germany. The supply chain draws from specialized semiconductor foundries, DICOM-standardized imaging equipment, and cloud infrastructure providers. Single-source vulnerability in NVIDIA data center chip supply creates bottleneck risk for AI-accelerated planning deployments. Distribution runs through a hybrid model combining direct vendor relationships for large accounts and regional specialty distributors for mid-size clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a technology-transition phase where deep learning-based autosegmentation displaces deterministic algorithms, redefining vendor-customer relationships around per-case licensing rather than perpetual ownership.
For Market Incumbents: Deepen backward integration into Monte Carlo dose engines to differentiate from hardware-agnostic competitors like RaySearch Laboratories. Consolidate API access restrictions across linear accelerator installed bases to slow interoperability mandates from southeastern United States hospital systems. Prioritize certification investment under EU MDR clinical validation requirements to extend European market protection against non-European algorithm developers.
For New Entrants and Emerging Players: The premium-to-economy price gap in cloud-native planning platforms creates entry opportunity for subscription models targeting tier-2 Indian cities with limited physicist staffing. White-space concentration sits in HIPAA-compliant edge computing architectures enabling federated learning across hospital networks. Target CDSCO regulatory pathways for cost-sensitive oncology networks in Bangalore and Hyderabad imaging technology clusters. Deploy direct-to-clinic digital sales channels bypassing traditional linear accelerator bundling relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor independent planning software specialists with cross-platform algorithm compatibility in European proton center markets. Long-term viability hinges on unbundling momentum from hardware-software conglomerates accelerating across mid-size oncology groups. Monitor FDA 510(k) De Novo pathway clearance velocity as inflection indicator for algorithmic competitive moat durability. Acquisition target archetype: cloud-native platforms with existing hospital network data governance frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | De Novo pathway accelerations compress validation timelines for AI contouring modules entering academic medical centers. |
| CE Marking Pathway | EU MDR clinical performance documentation extends certification timelines but secures European proton center access. |
| Hospital System Partnership | Multi-vendor interoperability mandates from consolidated southeastern United States networks reshape competitive positioning. |
| Software Companion Development | MR-linac integration tools enable same-day adaptive therapy workflows for mobile tumors. |
| Reimbursement Strategy | CMS quality-based payment program alignment drives automated plan-checking adoption in community oncology practices. |
Research Approach
FDA 510(k) clearance databases, CMS reimbursement rulemaking filings, and EU MDR notified body guidance documents formed the secondary backbone, cross-referenced with primary interviews with radiation oncology department chairs, hospital GPO contracts managers, biomedical engineers, and proton center medical physicists. Bottom-up modeling of installed linear accelerator bases and top-down triangulation against health system IT expenditure surveys validated market sizing.
Historical trendline analysis of software licensing transitions from perpetual to subscription models informed projection frameworks across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user consolidation scale, algorithm regulatory clearance tier, and proton therapy infrastructure investment clusters. CAGRs derived from elasticity-adjusted adoption curves incorporating physicist staffing constraints and reimbursement policy phase-ins. Industry-specific forecast inputs encompass GPU compute cost trajectories and EU MDR certification timeline distributions.
Inputs from FDA premarket notification databases and European notified body decision logs were available through the study window; gaps in real-world clinical performance evidence for AI-assisted planning tools introduce uncertainty bands around European market penetration assumptions. Forecasts reflect documented assumptions regarding reimbursement tightening velocity and hardware-software unbundling momentum. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
US Teleradiology Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
Global Closed MRI Systems Market
Medical Imaging
Digital X Ray Market
Medical Imaging
North America Open System MRI Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Ultrasound Systems Market