
 Refurbished Medical Imaging Devices Market | 2026-2036
Refurbished Medical Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished Medical Imaging Devices Market Analytics
Aftermarket service revenue is reconfiguring profit pools across the refurbished imaging value chain. GE HealthCare leverages its OEM refurbishment network to capture recurring service contracts on recertified MRI and CT platforms. Siemens Healthineers anchors European demand through its Ecoline program, which sustains margin density by bundling installation and warranty coverage. Block Imaging International, Inc. competes on North American hospital access, specializing in independent refurbishment of legacy modalities for rural facilities.
Refurbished medical imaging devices are pre-owned diagnostic systems restored to manufacturer-specified performance through component replacement, software recalibration, and safety testing against original equipment benchmarks; these units undergo electrical safety verification, image quality validation, and mechanical refurbishment to deliver clinical functionality at reduced capital outlay. CT scanner refurbishment dominates transaction volume due to shorter technology cycles and standardized gantry architectures that simplify parts sourcing. Ultrasound platforms represent the fastest-expanding segment as point-of-care adoption drives demand for portable, cost-effective systems in clinics and emergency services settings.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation impose stringent quality system documentation on refurbished device commercialization, compelling vendors to maintain traceable refurbishment protocols. India's CDSCO and BIS certification frameworks govern import and resale of pre-owned imaging equipment, shaping market access conditions for international suppliers. Stakeholders must monitor evolving national equivalence agreements between FDA, EMA, and emerging-market regulators that determine cross-border recognition of refurbishment quality standards.
Market Dynamics
Capital scarcity across hospital procurement departments is compressing replacement cycles for diagnostic imaging equipment, forcing administrators to evaluate refurbished alternatives against new system acquisition. This budget constraint is reconfiguring vendor relationships and service contract structures across the value chain.
Growth Catalysts
- EU Medical Device Regulation harmonization:MDR compliance frameworks create transparent quality benchmarks that reduce buyer uncertainty and accelerate cross-border trade in certified refurbished systems.
- Diagnostic center chains in India:Mumbai and Delhi-based networks expand imaging access through structured pre-owned equipment programs that lower per-scan capital costs.
- CT scanner standardization:Modular gantry architectures and interchangeable detector arrays simplify component sourcing and reduce refurbishment turnaround times.
Market Restraints
- Gradient coil supply concentration:Specialized superconducting magnet refurbishment depends on a narrow supplier base concentrated in Germany and Japan, creating input bottlenecks.
- FDA 510(k) documentation burden:Traceable refurbishment protocol requirements impose fixed compliance costs that disadvantage smaller independent refurbishers.
- Digital radiography substitution:Flat-panel detector systems in new equipment configurations reduce residual value for legacy computed radiography platforms.
Strategic Opportunities
- Point-of-care ultrasound expansion:Emergency services and clinic settings drive demand for portable, cost-effective systems that refurbished vendors can supply at sub-premium price points.
- India CDSCO import pathway streamlining:BIS certification alignment with international refurbishment standards reduces customs clearance friction for certified pre-owned equipment.
- AI-assisted image reconstruction integration:Software upgrade capabilities on refurbished MRI platforms enable performance parity with newer hardware generations.
Industry Challenges
- Field service engineer scarcity:Specialized training for superconducting magnet maintenance and RF coil calibration outpaces workforce pipeline development.
- Legacy system software validation:Cybersecurity patch integration on refurbished platforms with outdated operating architectures creates FDA compliance exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished Medical Imaging Devices Market |
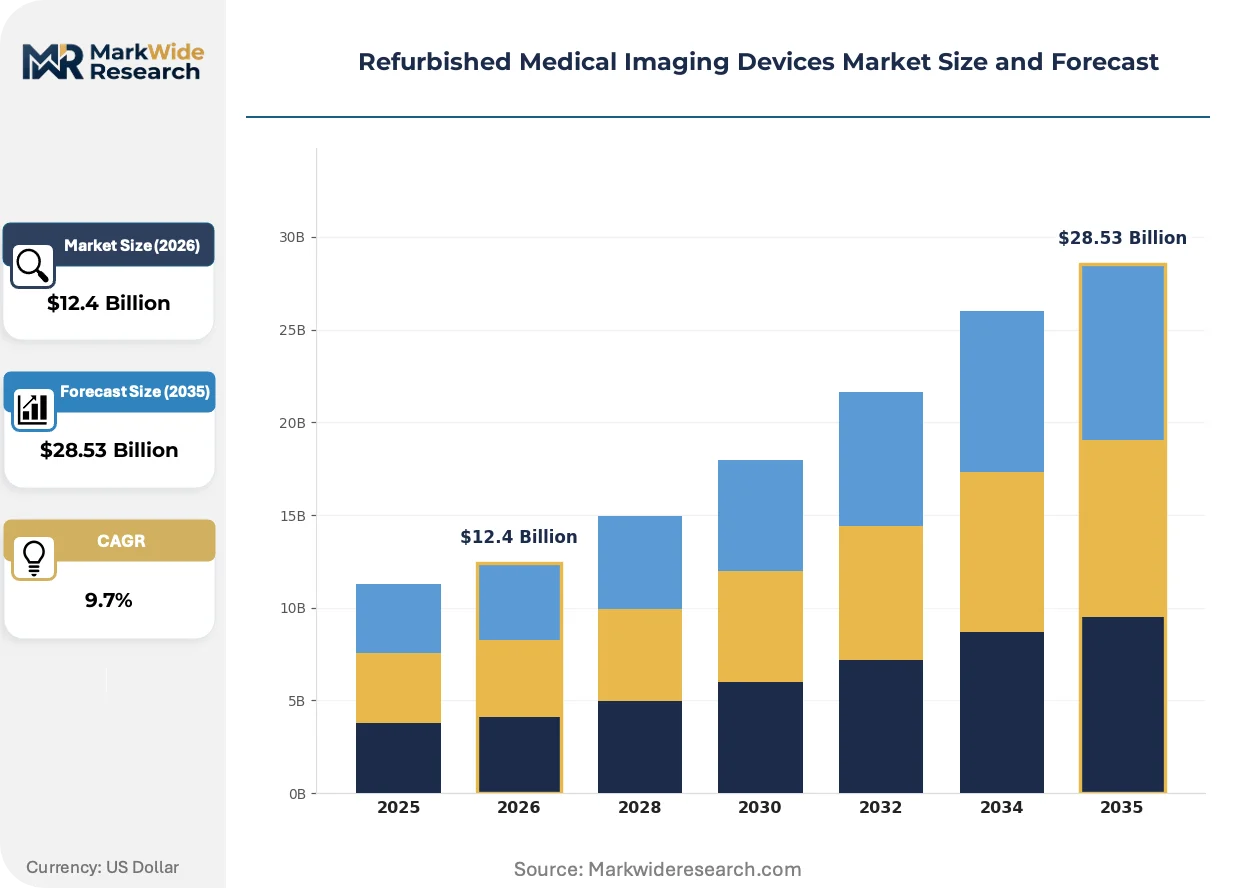
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Ultrasound, MRI, CT Scanner, X-Ray Application: Diagnostic Imaging, Therapeutic Imaging, Preventive Care, Emergency Services End User: Hospitals, Diagnostic Centers, Clinics, Research Laboratories Sales Channel: Direct Sales, Online Platforms, Distributors, Resellers |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, Block Imaging International, Inc., Soma Technology, Inc., Avante Health Solutions, Agito Medical A/S, Hitachi Healthcare Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished Medical Imaging Devices Market Evolving Landscape
Software-defined imaging architectures are separating hardware longevity from functional capability, allowing refurbished platforms to match new equipment performance through modular upgrades. This decoupling is rewriting asset valuation models across the secondary market.
Photon-counting CT detector technology is rendering obsolete energy-integrating detector arrays in refurbished system portfolios. Tertiary care centers in the United States are accelerating adoption timelines for recertified platforms with upgradeable detector substrates. The technology is rendering obsolete traditional refurbishment economics based solely on mechanical restoration rather than digital performance parity.
REACH substance restriction amendments are tightening material compliance for imported imaging components across European refurbishment facilities. Vendors must now document full supply chain substance declarations for detector housing materials and cable insulation. CT gantry manufacturers with integrated European refurbishment operations face accelerated compliance timelines compared to independent importers.
Diagnostic chains are consolidating vendor relationships around single-source service agreements that bundle equipment, maintenance, and upgrade pathways. Independent refurbishers in North America are responding by developing captive installation and warranty capabilities. This consolidation pattern appears most pronounced among rural hospital networks seeking to reduce procurement transaction costs.
Refurbished Medical Imaging Devices Market Segmentation
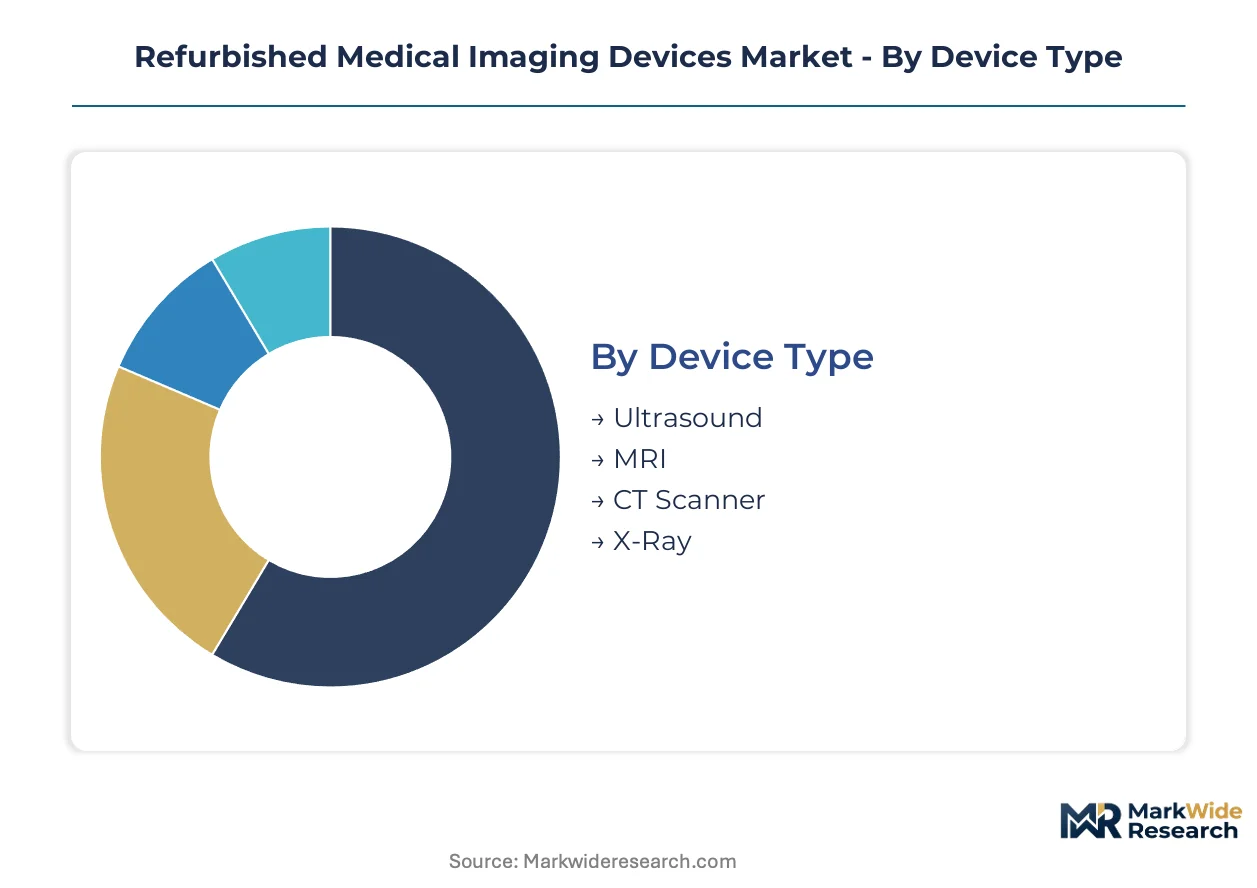
Refurbished medical imaging devices fragment across four distinct dimensions that determine procurement behavior, margin capture, and regulatory exposure. Device type governs refurbishment complexity and residual value curves. Application context shapes performance specifications and software validation requirements. End-user scale dictates service contract structures and financing arrangements. Sales channel selection influences warranty terms and installation support depth.
Device Type:
The use-case spectrum spans portable bedside diagnostics to high-field neuroimaging, with each modality presenting distinct refurbishment economics and technology refresh cycles.
- CT Scanner:Energy-integrating detector arrays and modular gantry architectures simplify component sourcing and shorten refurbishment turnaround. Hospital procurement teams in India favor recertified CT platforms for high-throughput oncology screening programs where capital constraints limit new equipment acquisition.
- Ultrasound:Portable systems with software-defined beamforming enable functional upgrades without hardware replacement. Emergency services and point-of-care clinics in Delhi and Mumbai drive volume for refurbished compact units that balance image quality against per-unit capital outlay.
- MRI:Superconducting magnet refurbishment demands specialized cryogenic handling and gradient coil recalibration against original manufacturer benchmarks. CDSCO import certification requirements add documentation layers for international suppliers serving Indian diagnostic chains.
- X-Ray:Digital radiography flat-panel detectors retain residual value longer than legacy computed radiography systems, though photon-counting technology is accelerating obsolescence curves for energy-integrating platforms.
Established volume favors CT Scanner; emerging adoption favors Ultrasound.
Application:
Clinical purpose determines software validation depth, cybersecurity patch requirements, and AI integration pathways on refurbished platforms.
- Diagnostic Imaging:Routine radiology and cardiology screening represent the core revenue base for refurbished equipment vendors. Mumbai-based diagnostic center chains standardize on recertified CT and MRI platforms for high-volume outpatient services where per-scan economics dominate procurement decisions.
- Emergency Services:Portable ultrasound and mobile X-Ray systems serve triage and trauma settings requiring rapid deployment. Refurbished vendors compete on sub-premium pricing for clinics and ambulance services that prioritize capital efficiency over cutting-edge specifications.
- Therapeutic Imaging:Image-guided intervention and radiation therapy planning demand precise calibration documentation for FDA 510(k) clearance pathways. Refurbishment protocols must maintain traceable quality systems for therapeutic dose verification.
- Preventive Care:Population health screening programs in India leverage refurbished CT for lung and cardiac calcium scoring. BIS certification alignment streamlines import clearance for certified pre-owned equipment serving government-contracted screening initiatives.
Diagnostic Imaging commands current procurement volume; Emergency Services shows the steepest expansion trajectory as point-of-care adoption accelerates.
End User:
Customer scale and technical capability determine service contract structures, training requirements, and upgrade pathway preferences across the refurbished value chain.
- Hospitals:Tertiary care centers with in-house biomedical engineering teams negotiate direct refurbishment relationships and captive maintenance capabilities. Delhi-based hospital networks bundle recertified MRI platforms with multi-year service agreements covering superconducting magnet cryogen management.
- Diagnostic Centers:Chain operators standardize equipment fleets to reduce spare parts inventory and technician training costs. Mumbai's expanding imaging networks drive demand for uniform CT platforms that simplify workflow standardization across multiple sites.
- Clinics:Small-scale operators prioritize turnkey installation and warranty coverage over customization options. Online platforms and distributor networks serve this segment with fixed-price packages that limit procurement transaction complexity.
- Research Laboratories:Academic medical centers seek legacy platforms with validated research sequences and exportable raw data formats. Refurbished vendors differentiate through software preservation and protocol compatibility for longitudinal studies.
Diagnostic Centers concentrate current procurement scale; Clinics represent the fastest-climbing adoption curve as point-of-care imaging expands.
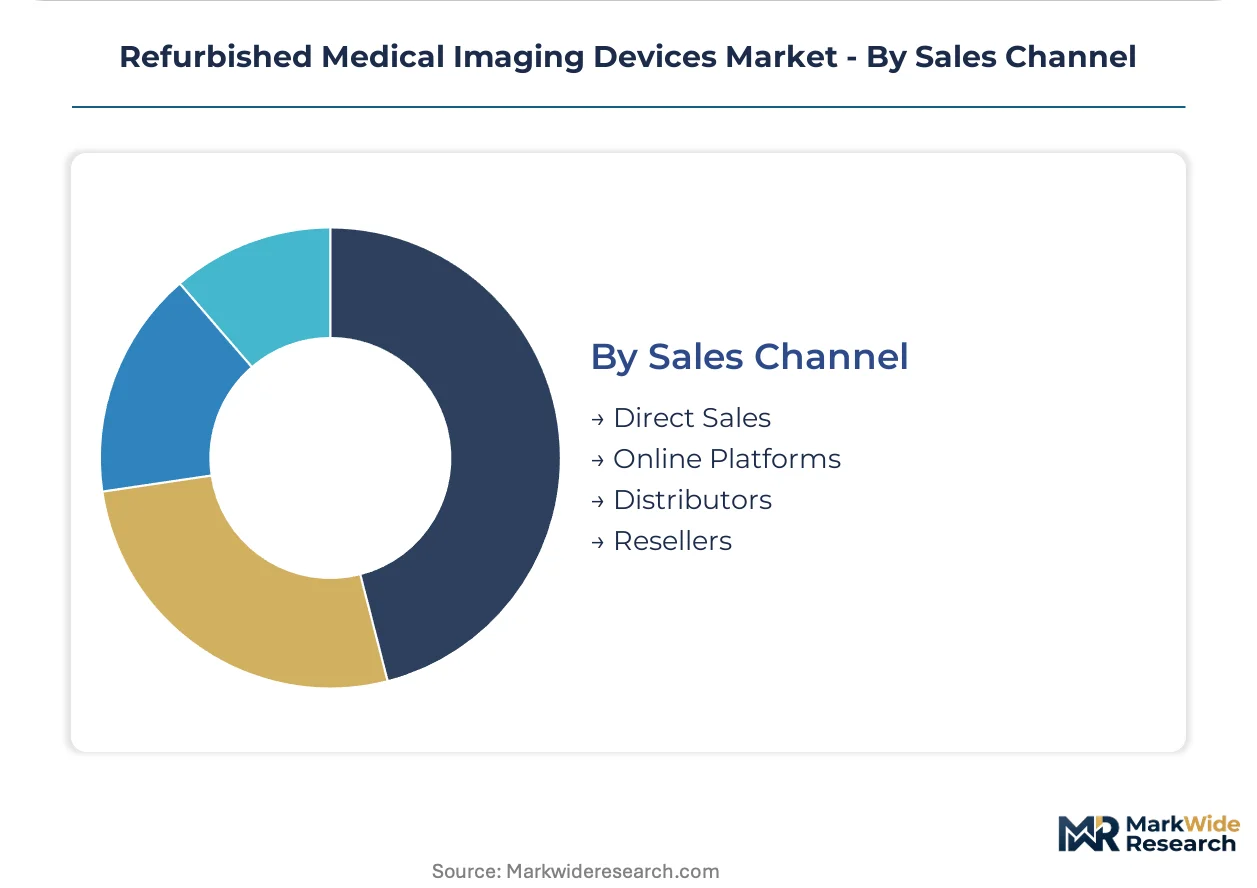
Sales Channel:
Channel selection governs warranty terms, installation support depth, and financing arrangement availability for refurbished equipment buyers.
- Direct Sales:OEM refurbishment programs like GE HealthCare's certified pre-owned network bundle installation, training, and extended service contracts. Hospital procurement teams in India negotiate direct relationships for high-value MRI and CT acquisitions requiring specialized site preparation.
- Distributors:Regional specialists aggregate inventory from multiple refurbishment sources and provide localized installation support. CDSCO import pathway expertise distinguishes distributors serving Indian diagnostic centers against direct international suppliers.
- Resellers:Independent brokers facilitate transactions for legacy platforms with limited OEM support availability. Rural hospital networks in India access refurbished X-Ray and ultrasound systems through reseller networks with flexible financing structures.
- Online Platforms:Digital marketplaces streamline price discovery and specification comparison for standardized modalities. Clinics and small diagnostic centers leverage online channels for portable ultrasound and digital radiography procurement with minimal sales engagement overhead.
Distributors dominate transaction volume today; Online Platforms are gaining share fastest among price-sensitive clinic and small-center segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes refurbished imaging devices primarily through diagnostic center chains seeking capital efficiency, while the United States emphasizes OEM-certified programs with bundled service contracts. Germany anchors European refurbishment quality standards through integrated manufacturer networks. This consumption-mix differential shapes regulatory compliance investments and channel strategies across markets.
United States
Tertiary care centers drive demand for recertified MRI and CT platforms with AI-assisted image reconstruction capabilities. FDA 510(k) premarket notification requirements enforce traceable refurbishment protocols that elevate compliance costs for smaller vendors. The Texas Medical Center in Houston concentrates procurement activity for high-field neuroimaging systems with validated research sequences.
Germany
Hospital networks prioritize OEM refurbishment programs bundling installation, warranty, and upgrade pathways. REACH substance restriction amendments tighten material compliance documentation for detector housing and cable insulation components. The Bavarian medical technology cluster around Munich hosts integrated refurbishment operations serving cross-border demand from Austria and Switzerland.
India
Diagnostic center chains in Mumbai and Delhi expand imaging access through certified pre-owned equipment programs lowering per-scan capital costs. CDSCO import certification and BIS alignment with international refurbishment standards reduce customs clearance friction. The Maharashtra state government contracts refurbished CT platforms for population health lung and cardiac calcium scoring initiatives.
Japan
Superconducting magnet refurbishment demand concentrates among specialized service providers with cryogenic handling capabilities. PMDA quality system documentation requirements parallel FDA stringency for imported recertified systems. The Osaka-Kobe industrial corridor hosts gradient coil suppliers serving regional MRI refurbishment networks.
United Kingdom
NHS procurement frameworks increasingly evaluate refurbished alternatives against new equipment acquisition for diagnostic imaging replacement cycles. MHRA post-market surveillance requirements extend to recertified device traceability. The Greater Manchester hospital network pilots structured pre-owned equipment programs with captive maintenance capabilities.
Refurbished Medical Imaging Devices Market Competitive Landscape
Capability concentration sits with OEM-affiliated refurbishment networks possessing proprietary parts access and specialized engineering training; scale advantage sits with independent operators aggregating multi-brand inventory for price-sensitive segments. The market structures around three tiers: manufacturer-captive programs, regional specialists with installation capabilities, and broker-resellers facilitating legacy platform transactions. Dominant competitive moves include backward integration into component remanufacturing and geographic expansion through distributor partnerships.
Within the OEM-captive tier, GE HealthCare and Siemens Healthineers exemplify integrated refurbishment-to-service models. Block Imaging International, Inc. occupies a position among North American independents specializing in legacy modality access for rural facilities. These three anchors represent contrasting archetypes: manufacturer-controlled quality systems, regional installation expertise, and flexible sourcing networks respectively.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Block Imaging International, Inc. |
| Soma Technology, Inc. |
| Avante Health Solutions |
| Agito Medical A/S |
| Hitachi Healthcare Systems |
| Others |
Value Network & Pricing Analysis
Overcapacity in European refurbishment facilities is compressing margins for independent operators while concentrating pricing power with OEM-captive programs. This utilization imbalance drives tiered contract structures that reward volume commitments and penalize spot-market procurement by small diagnostic centers.
Pricing Analysis
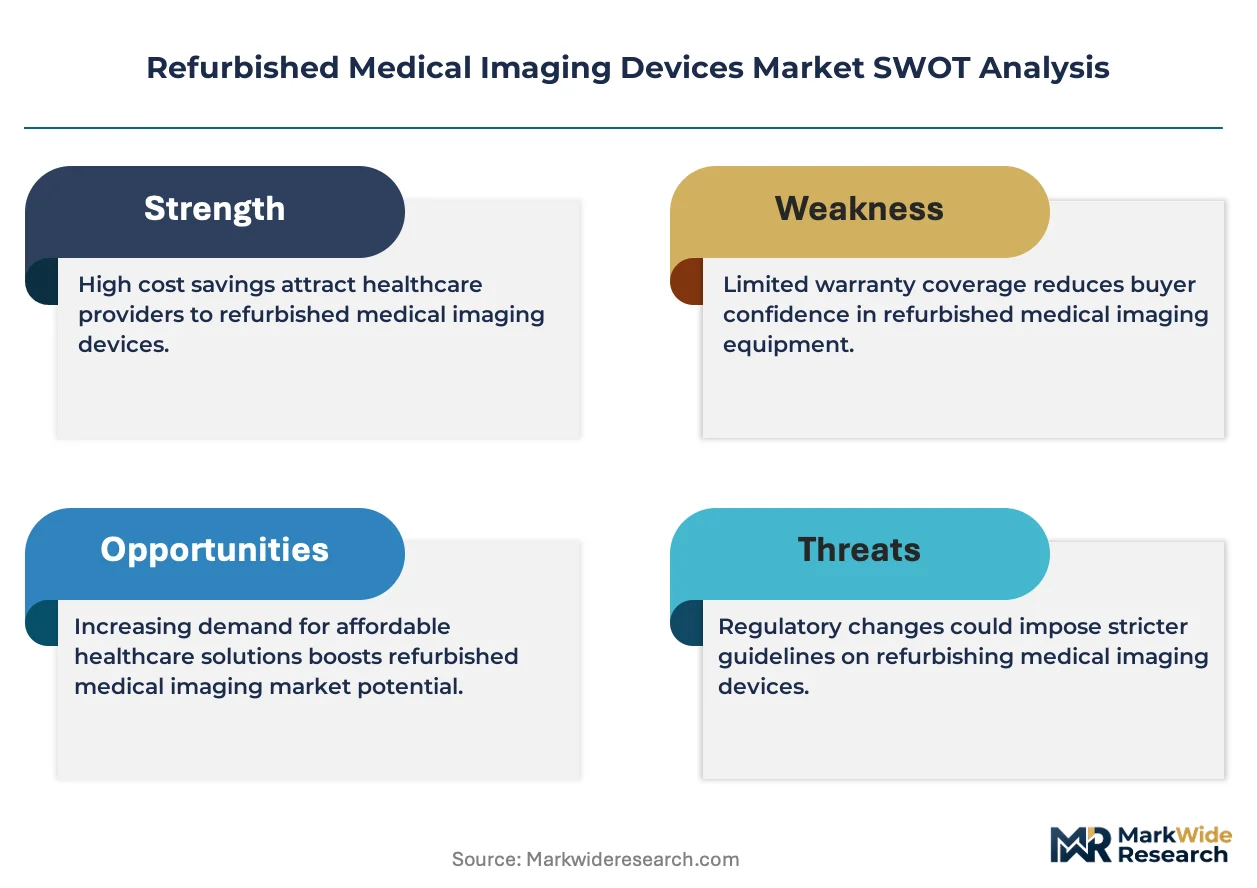
Long-term service contracts dominate high-value MRI and CT transactions, bundling equipment, installation, and multi-year maintenance into fixed-price arrangements. Pricing stratifies across OEM-certified, third-party recertified, and as-is resale tiers, with certification grade and after-sales warranty depth as primary differentiation drivers. Cost compression in the independent refurbisher tier is intensifying because FDA 510(k) documentation burdens impose fixed compliance overhead. Diagnostic center chains in India exhibit highest price sensitivity, while tertiary care centers in the United States prioritize performance parity over capital outlay.
Supply Chain Analysis
Gradient coil and superconducting magnet feedstock concentrates in Germany and Japan, with specialized cryogenic handling capabilities anchoring regional supplier networks. Component sourcing draws from narrow OEM-affiliated channels for RF coils and detector arrays, while standardized gantry architectures enable broader parts aggregation. Single-source vulnerability for specialized magnet refurbishment creates bottleneck exposure during demand surges. Distribution runs through three-tier structures: direct OEM programs, regional distributors with CDSCO pathway expertise, and independent resellers serving price-sensitive clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refurbished medical imaging market is recovering from capital expenditure compression cycles as hospital procurement teams normalize replacement timelines. Budget constraint persistence in emerging economies sustains demand elasticity for certified pre-owned alternatives.
For Market Incumbents: Insulate service contract profitability by deepening captive refurbishment capabilities and locking diagnostic center chains into multi-year maintenance agreements. Photon-counting CT substitution threatens residual value for energy-integrating detector inventories; backward integration into gradient coil remanufacturing secures input cost control against German and Japanese supplier concentration.
For New Entrants and Emerging Players: Rural India diagnostic networks present underpenetrated access points where CDSCO certification expertise differentiates against direct importers. Portable ultrasound for emergency services and point-of-care clinics offers fastest penetration trajectory; online platform partnerships reduce customer acquisition friction for standardized compact systems.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEM-affiliated refurbishment networks with bundled service contracts and proprietary parts access. Five-to-ten year viability favors operators with integrated installation capabilities and regulatory pathway mastery across multiple jurisdictions. Watch FDA 510(k) clearance velocity for refurbished platforms with AI-assisted reconstruction as inflection signal for technology parity acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Import Pathway Mastery | Reduces customs clearance friction for certified pre-owned equipment serving Indian diagnostic chains. |
| AI-Assisted Reconstruction Integration | Enables refurbished MRI performance parity with newer hardware generations for tertiary care centers. |
| Superconducting Magnet Remanufacturing | Captures margin from specialized cryogenic handling and gradient coil recalibration capabilities. |
| Point-of-Care Ultrasound Expansion | Addresses emergency services and clinic demand for portable, cost-effective imaging systems. |
| REACH Substance Compliance Documentation | Meets tightened material declaration requirements for detector housing and cable insulation in European facilities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and refurbishment facility operators; and secondary validation against FDA 510(k) clearance databases, CDSCO import registration records, EU MDR technical documentation filings, and hospital procurement contract disclosures. Bottom-up equipment transaction tracking and top-down market sizing triangulated volume and value estimates.
Forecast inputs incorporated device type segmentation by refurbishment complexity, application context by software validation depth, end-user scale by service contract structure, and sales channel by warranty term differentiation. CAGRs derived from installed base aging curves, replacement cycle compression patterns, and regulatory pathway evolution across the projection horizon. Modeling integrated superconducting magnet supply constraints and photon-counting CT substitution timelines as industry-specific variables.
Practitioners should monitor FDA 510(k) clearance backlog shifts and EU MDR harmonization progress for early signals of competitive access changes. Forecasts reflect assumptions regarding capital budget normalization and certification standard convergence that may revise with macroeconomic or regulatory discontinuities. Cross-checking against hospital procurement database benchmarks and GPO contract award disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Ultrasound Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Global Positron Emission Tomography [PET] Scanners Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
South America Mammography Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
Asia-Pacific CT Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Optical Coherence Tomography Market