
 North America Fetal and Neonatal Monitoring Market | 2026-2036
North America Fetal and Neonatal Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fetal and Neonatal Monitoring Market Analytics
The EPA's strengthened medical device waste reduction targets is restructuring procurement criteria across hospital networks, compelling vendors to redesign disposable sensor portfolios. Koninklijke Philips N.V. anchors its North American position through deep integration of optical sensing platforms with enterprise electronic health record architectures. Drägerwerk AG & Co. KGaA differentiates via manufacturing scale in neonatal ventilation-to-monitoring system bundles. Natus Medical Incorporated specializes in neurophysiological monitoring extensions that complement core fetal heart rate product lines.
North America fetal and neonatal monitoring encompasses electronic systems that capture, process, and display physiological parameters of fetuses and newborns, typically operating at ultrasound frequencies between 1-10 MHz for Doppler-based heart rate detection and incorporating impedance pneumography for respiratory surveillance. These devices serve to reduce perinatal morbidity through early detection of hypoxic events, arrhythmias, and respiratory insufficiency in clinical and transitional care settings. Cardiotocographs retain the largest installed base across hospital labor and delivery units, though Doppler devices are gaining traction in outpatient maternity center expansions. Neonatal intensive care equipment commands premium pricing due to multi-parameter integration requirements and extended FDA 510(k) validation cycles for critical care indications.
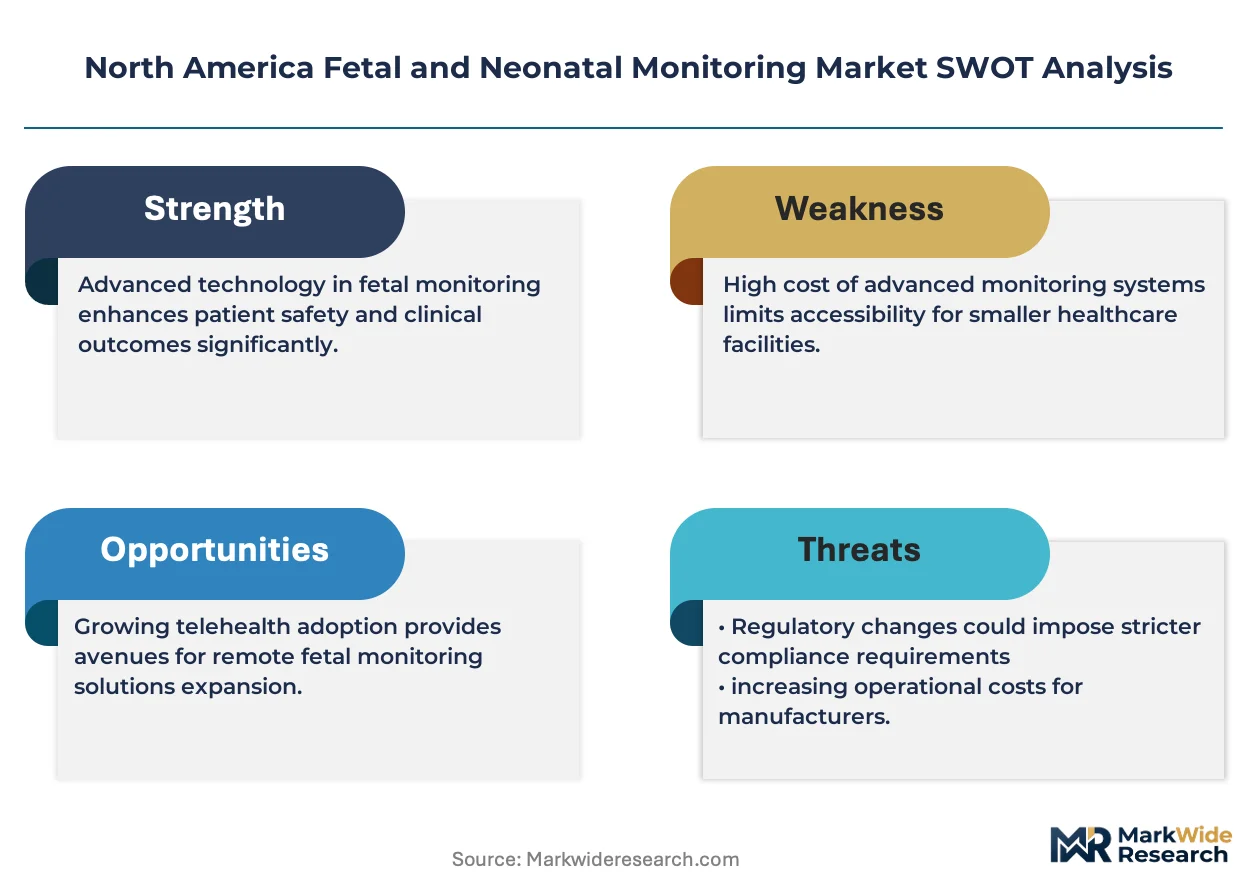
The FDA's Quality System Regulation and premarket notification requirements shape device development timelines and capital allocation priorities for manufacturers seeking U.S. commercialization. Health Canada's Medical Devices Bureau maintains parallel but distinct classification rules that create incremental compliance burdens for cross-border product strategies. Stakeholders must monitor evolving Software as a Medical Device guidance from both regulators, as algorithm-driven risk stratification tools become embedded in standard-of-care protocols.
Market Dynamics
Hospital maternity wards across the United States are consolidating perinatal services into specialized regional centers, concentrating purchasing power and forcing vendors to reconfigure service architectures around enterprise health system contracts rather than individual facility deployments.
Growth Catalysts
- AI-enabled cardiotocography clearance acceleration:FDA's evolving premarket review pathways for Software as a Medical Device compress validation timelines for algorithm-driven fetal heart rate analysis tools.
- Remote monitoring infrastructure expansion:Health systems in the U.S. Southeast are deploying distributed fetal monitoring networks linking outpatient maternity centers to centralized labor and delivery units.
- Neurophysiological monitoring integration:Specialized neonatal intensive care units demand multi-parameter platforms combining cerebral function surveillance with conventional cardiorespiratory tracking.
Market Restraints
- Extended FDA 510(k) validation cycles:Critical care indications for neonatal multi-parameter devices face prolonged regulatory scrutiny that stretches capital recovery timelines.
- Disposable sensor waste compliance costs:EPA medical device waste reduction targets compel manufacturers to redesign single-use electrode portfolios, elevating per-procedure supply expenses.
- Cross-border regulatory fragmentation:Health Canada's Medical Devices Bureau maintains classification rules distinct from FDA frameworks, creating incremental compliance burdens for unified North American product strategies.
Strategic Opportunities
- Outpatient maternity center Doppler expansion:Freestanding birth centers across Texas and Florida present underpenetrated demand for portable fetal heart rate monitoring outside hospital walls.
- Enterprise EHR optical sensing convergence:Deep integration of photoplethysmography platforms with Cerner and Epic architectures creates differentiated positioning against standalone device vendors.
- Regional perinatal service consolidation:Large health systems in Georgia and North Carolina are centralizing high-risk obstetric care, creating concentrated procurement windows for comprehensive monitoring system bundles.
Industry Challenges
- Algorithm validation talent scarcity:Software as a Medical Device submissions require specialized regulatory affairs expertise combining clinical knowledge with machine learning quality system documentation.
- Legacy device interoperability friction:Health systems operating mixed-vendor monitoring fleets face integration complexity when deploying next-generation platforms alongside existing cardiotocograph installations.
- Multi-site service network scaling:Vendors must reconfigure field engineering organizations to support dispersed regional perinatal centers rather than concentrated urban hospital clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fetal and Neonatal Monitoring Market |
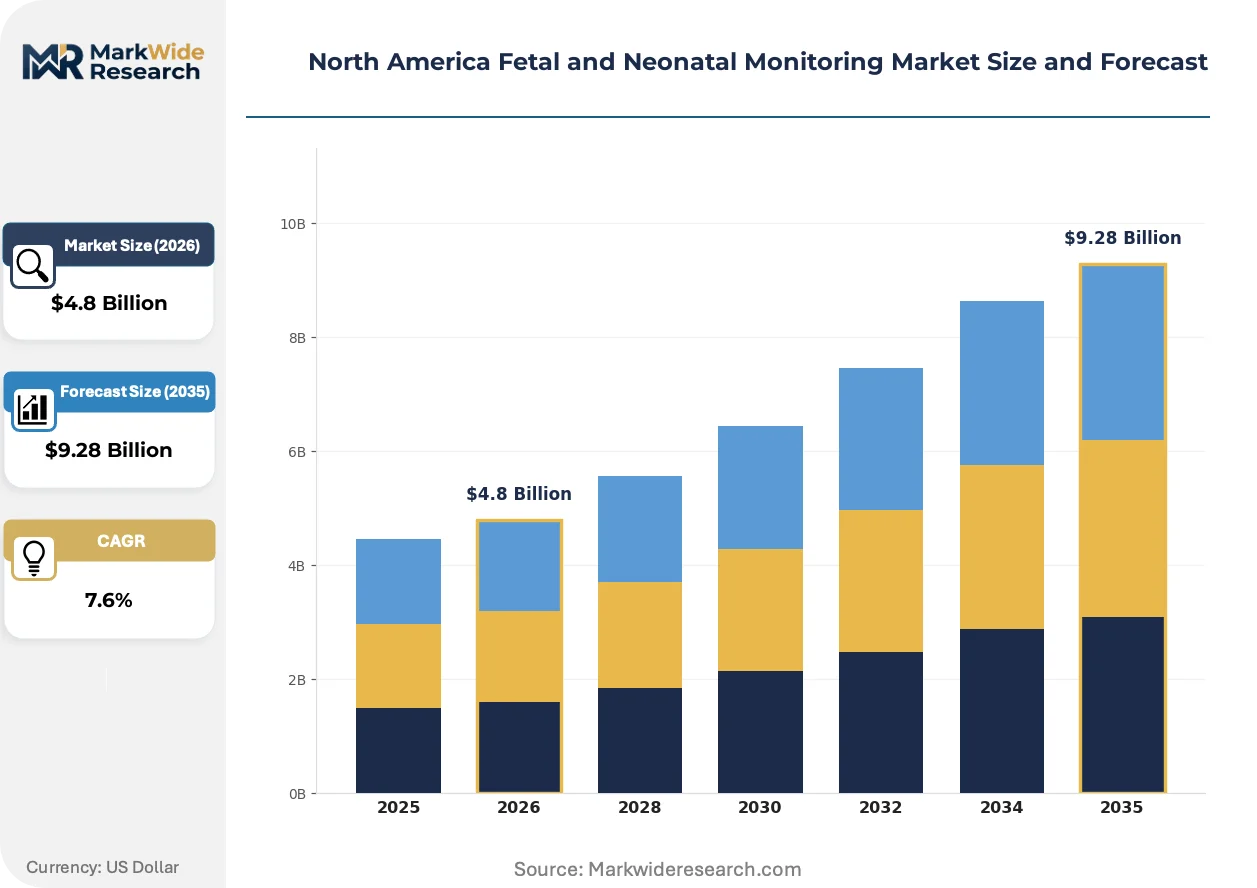
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiotocographs, Fetal Monitors, Neonatal Intensive Care Equipment, Doppler Devices End User: Hospitals, Clinics, Homecare Providers, Maternity Centers Technology: Ultrasound, Electrocardiography, Magnetic Resonance Imaging, Optical Sensors Application: Fetal Heart Rate Monitoring, Neonatal Care, Labor Monitoring, Postnatal Assessment |
| Companies Covered | Becton, Dickinson and Company, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., Fisher & Paykel Healthcare, Masimo, Medtronic PLC, Siemens Healthineers, Natus Medical Incorporated, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fetal and Neonatal Monitoring Market Evolving Landscape
Deep learning architectures are embedding into standard-of-care fetal surveillance protocols, compressing the interval between physiological anomaly detection and clinical intervention while reshaping how health systems evaluate monitoring platform vendors.
Machine learning-based cardiotocograph interpretation is automating risk stratification for fetal hypoxic events, reducing reliance on specialized perinatologist review. Community hospital labor and delivery units in the U.S. Southeast are adopting these tools most aggressively, narrowing the clinical capability gap between regional perinatal centers and smaller facilities.
FDA Quality System Regulation updates are tightening software validation requirements for algorithm-driven monitoring devices, extending development timelines for new submissions. Manufacturers targeting critical care neonatal indications face particular scrutiny around training data diversity and edge-case performance documentation, prompting investment in prospective clinical validation cohorts.
Health system procurement committees are unbundling device acquisition from long-term service contracts, compressing vendor switching cycles and elevating total cost of ownership transparency. This pattern is most pronounced in consolidated systems across the Carolinas and Tennessee, where standardized equipment specifications span multiple formerly independent hospitals.
North America Fetal and Neonatal Monitoring Market Segmentation
Segmentation in the North America fetal and neonatal monitoring market reveals how FDA clearance pathways, clinical setting requirements, and technology integration demands reshape procurement priorities across health systems. Understanding these divisions exposes where capital concentrates and where vendors must reconfigure product architectures to capture enterprise contracts.
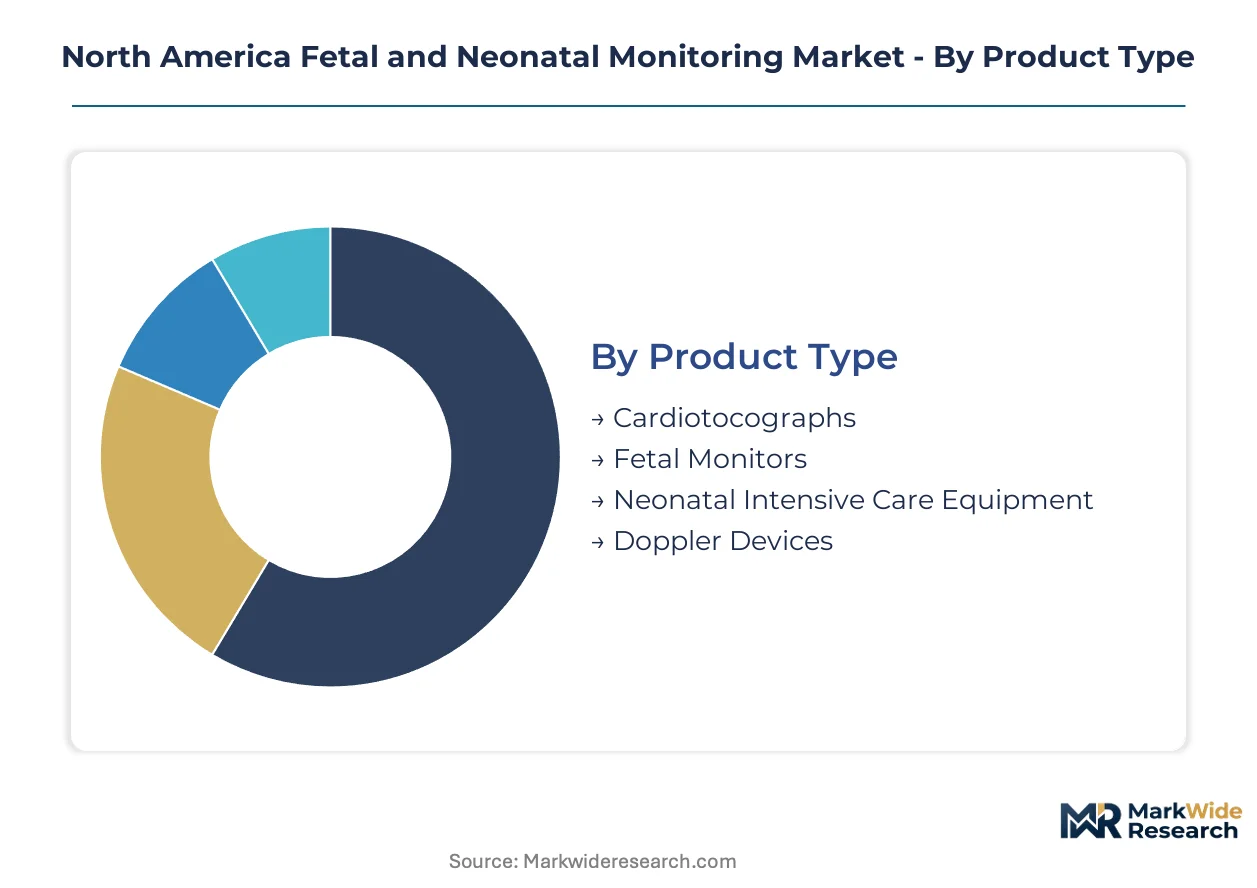
Product Type:
FDA 510(k) pathways vary sharply across this category: cardiotocographs and Doppler devices navigate abbreviated premarket notification, while neonatal intensive care equipment faces extended validation cycles for critical care indications.
- Cardiotocographs:Electronic systems capturing fetal heart rate and uterine contraction patterns through Doppler ultrasound and tocodynamometry. Demand concentrates in U.S. Southeast hospital labor and delivery units consolidating into regional perinatal centers, where enterprise procurement committees standardize on platforms with embedded AI interpretation tools.
- Neonatal Intensive Care Equipment:Multi-parameter platforms integrating cardiorespiratory, cerebral function, and temperature surveillance for critical care newborns. Extended FDA validation timelines for these devices stretch capital recovery periods, concentrating sales in large health systems with dedicated NICU construction budgets across Georgia and North Carolina.
- Fetal Monitors:Portable and bedside systems for antepartum and intrapartum surveillance.
- Doppler Devices:Handheld ultrasound units for fetal heart rate detection in outpatient settings.
Leading the category by volume: Cardiotocographs. Expanding most quickly: Neonatal Intensive Care Equipment.
End User:
Procurement scale and service contract structures diverge dramatically across this dimension, from capital-intensive hospital enterprise agreements to per-procedure rental models in freestanding maternity centers.
- Hospitals:Acute care institutions operating labor and delivery units and neonatal intensive care services. U.S. Southeast health systems in Texas and Florida anchor regional purchasing concentration, consolidating previously independent facility contracts into standardized enterprise specifications spanning multiple sites.
- Maternity Centers:Freestanding birth facilities and outpatient perinatal clinics. Demand clusters in Texas and Florida outpatient expansions, where remote monitoring infrastructure links distributed centers to centralized hospital labor units, creating pull-through for portable Doppler and telemetry systems.
- Clinics:Physician office-based obstetric practices and community prenatal care sites.
- Homecare Providers:Post-discharge neonatal monitoring services and remote fetal surveillance programs.
Dominating procurement value: Hospitals. Gaining share fastest: Maternity Centers.
Technology:
Software as a Medical Device classification risk varies by modality, with algorithm-driven optical sensors facing evolving FDA guidance while established ultrasound platforms operate under clearer predicate pathways.
- Ultrasound:Doppler-based fetal heart rate detection operating at frequencies between 1-10 MHz. Cardiotocograph manufacturers across the U.S. Southeast leverage this mature technology base to accelerate clearance timelines, though EPA waste reduction targets now compel redesign of disposable transducer portfolios.
- Optical Sensors:Photoplethysmography and near-infrared spectroscopy platforms for cerebral and peripheral oxygenation monitoring. Specialized NICUs in consolidated Georgia and North Carolina perinatal centers drive adoption, demanding deep Epic and Cerner EHR integration that favors vendors with enterprise software capabilities.
- Electrocardiography:Surface electrode systems for neonatal cardiac rhythm surveillance.
- Magnetic Resonance Imaging:Fetal anatomical and functional assessment in high-risk pregnancy management.
Holding largest installed base: Ultrasound. Steepest expansion trajectory: Optical Sensors.
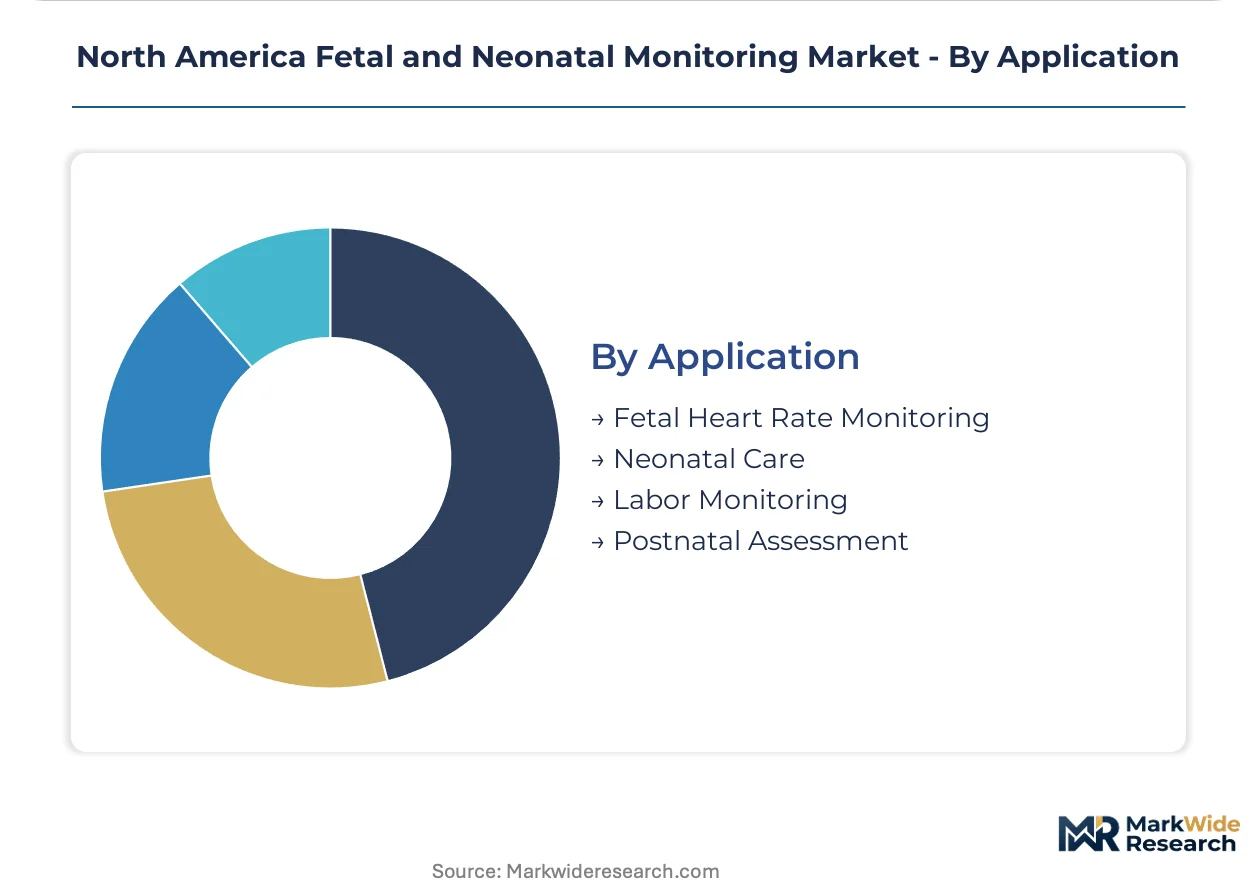
Application:
Clinical workflow integration requirements and reimbursement structures shape how monitoring capabilities bundle across this dimension, with labor surveillance commanding capital budgets and postnatal assessment shifting toward disposable-consumable models.
- Fetal Heart Rate Monitoring:Continuous or intermittent surveillance of fetal cardiac rhythm and variability during pregnancy and labor. Community hospitals across Tennessee and the Carolinas adopt AI-enabled interpretation tools most aggressively, narrowing capability gaps with specialized regional perinatal centers.
- Neonatal Care:Multi-parameter physiological surveillance of newborns in transitional and intensive care settings. Premium pricing reflects extended FDA validation cycles and multi-site service network requirements, concentrating vendor competition in large health system RFPs.
- Labor Monitoring:Integrated uterine activity and fetal status surveillance during delivery.
- Postnatal Assessment:Cardiorespiratory and neurological evaluation in the immediate newborn period.
Commanding greatest revenue concentration: Fetal Heart Rate Monitoring. Climbing the fastest: Neonatal Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the United States, where device manufacturers cluster around FDA regulatory expertise and health system procurement hubs. Consumption spreads across all three North American countries, with demand intensity varying by healthcare infrastructure maturity and perinatal service consolidation patterns.
United States
Hospital maternity wards in Texas and Florida are consolidating perinatal services into specialized regional centers, concentrating purchasing power for multi-parameter monitoring platforms. FDA premarket review pathways for Software as a Medical Device are accelerating clearance timelines for AI-enabled cardiotocography systems. The U.S. Southeast anchors demand concentration, with Georgia and North Carolina health systems centralizing high-risk obstetric care into enterprise procurement networks.
Canada
Health Canada's Medical Devices Bureau maintains classification rules distinct from FDA frameworks, creating incremental compliance burdens for cross-border product strategies. Provincial health authorities in Ontario and Quebec are standardizing neonatal intensive care equipment specifications across formerly independent hospital networks. Vancouver and Toronto clusters concentrate procurement decision-making for optical sensing platforms with enterprise EHR integration requirements.
Mexico
COFEPRIS regulatory alignment initiatives are streamlining device registration for manufacturers seeking Latin American market access through Mexican distribution channels. Private hospital chains in Mexico City and Monterrey are expanding NICU capacity to capture medical tourism flows from Central America. Guadalajara's manufacturing corridor is attracting contract assembly operations for disposable sensor components serving U.S. health systems.
North America Fetal and Neonatal Monitoring Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with enterprise software integration capabilities. Market concentration reflects the capital intensity of FDA validation cycles and multi-site service network requirements. Three archetypes dominate: optical sensing platform specialists, ventilation-to-monitoring system bundlers, and neurophysiological monitoring extension providers. Vertical integration into disposable sensor manufacturing and strategic partnerships with EHR vendors represent the primary competitive vectors reshaping vendor positioning.
Within the diversified health technology tier, Koninklijke Philips N.V. and Siemens Healthineers anchor positions through scale and regulatory expertise. Drägerwerk AG & Co. KGaA exemplifies the ventilation-to-monitoring bundling archetype. Natus Medical Incorporated occupies a specialist position in neurophysiological monitoring extensions. These three represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| Fisher & Paykel Healthcare |
| Masimo |
| Medtronic PLC |
| Siemens Healthineers |
| Natus Medical Incorporated |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
EPA medical device waste reduction targets gate qualified supply for disposable sensor portfolios and tier premium-tier pricing access for vendors demonstrating compliant redesign credentials. Manufacturers lacking validated sustainable material pathways face exclusion from enterprise procurement networks across consolidated U.S. Southeast health systems.
Pricing Analysis
Outcome-linked contracts anchored to perinatal event reduction metrics shape vendor pricing power in enterprise health system negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier differentiation and EHR integration depth. Cost compression in standard-tier cardiotocographs intensifies as offshore manufacturers enter outpatient maternity center channels. Community hospital labor and delivery units exhibit highest price sensitivity; specialized regional perinatal centers prioritize clinical capability over acquisition cost.
Supply Chain Analysis
FDA Quality System Regulation certification requirements filter component suppliers to established medical device manufacturing corridors in the United States, Mexico, and Costa Rica. Disposable electrode assemblies draw from specialized polymer resin suppliers and printed circuit fabrication facilities concentrated in Guadalajara and Tijuana. Single-source vulnerability runs through concentrated ultrasound transducer crystal production. Distribution runs through health system GPO contracts and direct enterprise agreements with regional perinatal service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in algorithm validation talent and extended FDA 510(k) timelines prop pricing power for qualified vendors, creating durable margin structures for incumbents with cleared AI-enabled platforms.
For Market Incumbents: Deepen optical sensing platform integration with Epic and Cerner architectures to lock in enterprise switching costs against standalone device competitors. Expand captive production of disposable transducer components in Mexico to preempt EPA waste compliance cost pass-through. Prioritize FDA Software as a Medical Device pre-submission pathways for next-generation cardiotocograph algorithms. For New Entrants and Emerging Players: Freestanding birth centers in Texas and Florida represent the most penetrable buyer archetype, underserved by legacy vendors focused on hospital enterprise contracts. Portable Doppler devices with remote telemetry capabilities address connectivity gaps in distributed maternity center networks. Direct-to-clinic sales models bypass GPO procurement friction that disadvantages smaller vendors. For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for AI-enabled cardiotocography systems is the leading indicator that algorithm-driven monitoring platforms will capture share from conventional interpretation workflows. Acquisition targets should combine regulatory affairs expertise with machine learning quality system documentation capabilities. Watch for Health Canada harmonization initiatives with FDA Software as a Medical Device frameworks as cross-border consolidation signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Pre-Submission | Accelerated clearance timelines compress competitive windows for AI-enabled cardiotocography platforms. |
| Enterprise EHR Integration Partnership | Deep Cerner and Epic connectivity creates differentiated positioning against standalone monitoring vendors. |
| Disposable Sensor Portfolio Redesign | EPA waste reduction compliance qualifies vendors for standardized health system procurement specifications. |
| Regional Perinatal Service Network Expansion | Multi-site service organizations capture consolidated purchasing power across Georgia and North Carolina systems. |
| Neurophysiological Monitoring Extension Development | Cerebral function surveillance modules command premium pricing in specialized NICU construction budgets. |
Research Methodology
Multi-period observation of FDA 510(k) clearance velocity, health system consolidation patterns, and EPA regulatory implementation timelines anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and perinatal clinical directors. Secondary validation drew from FDA premarket notification databases, hospital procurement records, Health Canada Medical Devices Bureau filings, and CMS Medicare cost report data. Bottom-up equipment shipment estimates and top-down health system capital expenditure analysis were triangulated against vendor-reported installed base metrics.
Input-output matrices modeled demand drivers across product type, end user, technology, and application segmentation dimensions over the projection horizon. CAGRs were derived from regression analysis of historical shipment data against explanatory variables including NICU bed expansion permits, regional perinatal service consolidation announcements, and FDA guidance document publication schedules. Forecast inputs incorporated algorithm validation cohort enrollment rates and health system EHR migration timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA Software as a Medical Device guidance evolution and health system merger regulatory approval timelines. A model refresh is warranted upon material change in EPA medical device waste reduction enforcement intensity or Health Canada classification rule harmonization with FDA frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Intensive Care Market
Neonatal Care
Neonatal Infant Care Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
United States Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Necrotising Enterocolitis (NEC) Market