
 US Teleradiology Market | 2026-2036
US Teleradiology Market Size, Share, and Industry Trends Forecast 2026-2036
US Teleradiology Market Insights
US-based radiologist groups is realigning around distributed reading workflows as health systems confront persistent staffing gaps in emergency and overnight coverage. Virtual Radiologic (vRad) leverages its national network of subspecialty-trained radiologists to sustain turnaround-time guarantees for critical findings. Koninklijke Philips N.V. anchors its position through integrated PACS-to-cloud infrastructure that spans acquisition, transmission, and diagnostic display. Matrix (Teleradiology Division of Radiology Partners) competes on scale, operating one of the largest domestic teleradiology footprints with embedded quality assurance protocols.
Teleradiology denotes the electronic transmission of radiological patient images—X-ray, CT, MRI, and ultrasound—from one location to another for interpretation by remotely stationed radiologists, typically requiring DICOM-compliant data formats and secure HIPAA-grade transmission channels with sub-100-millisecond latency thresholds for real-time consultation. CT scan interpretation commands premium reimbursement rates due to complexity and medicolegal exposure, while cloud-based delivery modes are displacing on-premise architectures as health systems prioritize capital-light scalability. Artificial Intelligence integration within PACS workflows is concentrating margin pools among vendors that bundle diagnostic algorithms with enterprise imaging platforms.
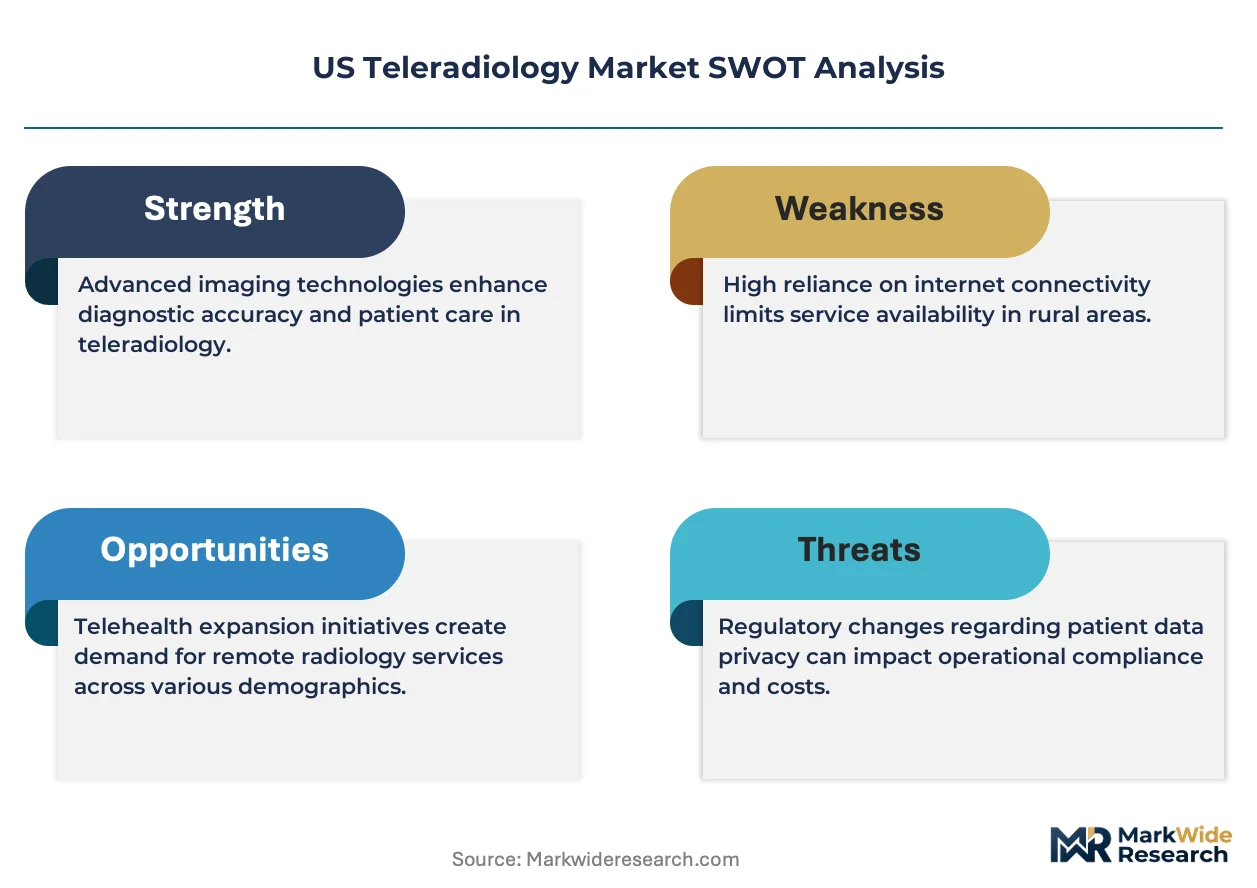
FDA oversight of software-as-a-medical-device, HIPAA security rule enforcement by the Office for Civil Rights, and state-level medical licensure compact participation collectively determine market access velocity and operational compliance burdens for teleradiology providers. Medicare reimbursement policy under CMS, particularly for remote professional component reads in designated health professional shortage areas, directly shapes demand elasticity among rural hospital buyers. Stakeholders must monitor evolving FDA predicate device pathways for AI-augmented diagnostic tools, as clearance complexity will sort vendor viability faster than pure scale metrics.
Market Dynamics
Rural hospital networks across the Southeast and Mountain West are accelerating teleradiology adoption as persistent physician shortages force structural reliance on remote diagnostic coverage. CMS reimbursement expansion for professional component reads in designated shortage areas is compressing procurement cycles.
Growth Catalysts
- CMS Medicare reimbursement expansion:Remote professional component reads in health professional shortage areas now carry favorable reimbursement rates, pulling rural hospital buyers into teleradiology contracts.
- CT scan complexity premiums:Advanced imaging modalities command higher reimbursement due to medicolegal exposure, concentrating demand for subspecialty-trained remote radiologists.
- Cloud-based PACS migration:Health systems are abandoning on-premise architectures for capital-light scalability, accelerating platform consolidation among enterprise imaging vendors.
Market Restraints
- State medical licensure fragmentation:Radiologists must hold licenses in each state where patients reside, creating administrative overhead that limits workforce mobility and coverage flexibility.
- Sub-100-millisecond latency infrastructure:Real-time consultation requirements demand specialized network investments that strain rural hospital IT budgets and constrain vendor selection.
- HIPAA security rule enforcement:OCR audits of business associate agreements impose compliance costs that disproportionately burden smaller teleradiology providers and independent radiology groups.
Strategic Opportunities
- AI-augmented diagnostic workflows:FDA software-as-a-medical-device pathways for algorithm-enabled PACS integration are creating margin pools for vendors bundling diagnostic tools with enterprise platforms.
- Southeast hospital network consolidation:Expanding Medicare Advantage penetration in Florida, Georgia, and North Carolina is concentrating buying power among integrated delivery systems seeking standardized remote coverage.
- Interstate Medical Licensure Compact expansion:Participation growth among western states is reducing credentialing friction and enabling faster radiologist deployment across multi-state coverage pools.
Industry Challenges
- Subspecialty radiologist recruitment:Neuroradiology and pediatric imaging expertise remains scarce, forcing teleradiology groups to compete with academic medical centers for limited fellowship-trained talent.
- DICOM interoperability with legacy modalities:Aging imaging equipment in rural facilities requires costly middleware to achieve compliance with modern teleradiology platforms, delaying contract implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Teleradiology Market |
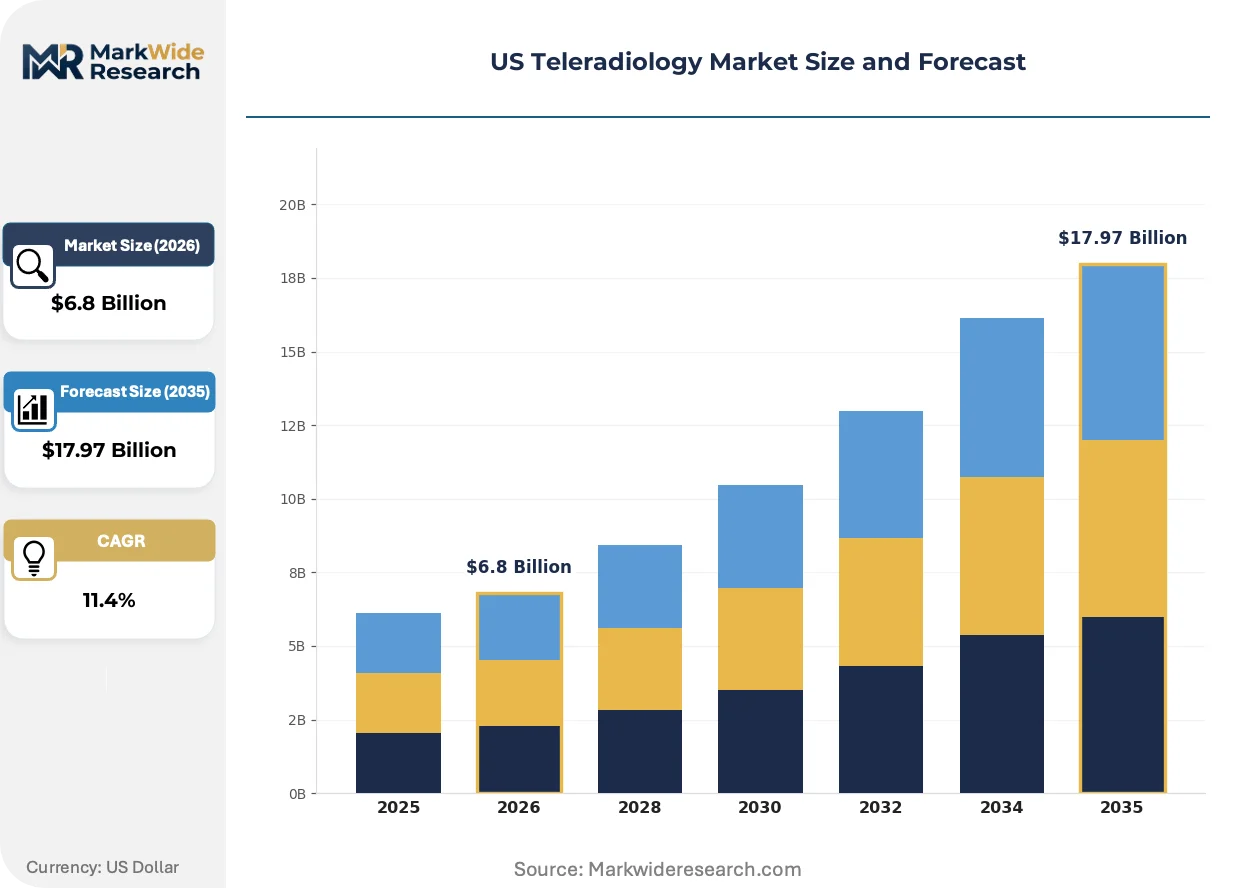
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, CT Scan, MRI, Ultrasound Delivery Mode: Cloud-based, Mobile, On-premise, Hybrid End User: Hospitals, Clinics, Imaging Centers, Telehealth Providers Technology: Artificial Intelligence, PACS, DICOM, 5G |
| Companies Covered | Virtual Radiologic (vRad), ONRAD, Inc., USARAD Holdings, Inc., Everlight Radiology, Agfa-Gevaert Group, Koninklijke Philips N.V., RamSoft, Inc., Matrix (Teleradiology Division of Radiology Partners), RAYUS Radiology Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Teleradiology Market Trends and Innovations
Artificial intelligence integration is restructuring competitive positioning around bundled diagnostic platforms rather than standalone interpretation services. Vendors are racing to embed algorithmic decision support within cloud-native PACS workflows.
Computer-aided detection algorithms for mammography and lung nodule screening are converging with enterprise PACS deployments. Regional hospital networks in Texas and Arizona are adopting these tools at accelerated pace to offset staffing gaps. The technology is converging with quality assurance protocols, compressing turnaround-time guarantees into standard contract terms.
FDA evolving guidance on AI-enabled diagnostic devices is reshaping vendor qualification pathways. Predicate device requirements for software-as-a-medical-device are sorting vendor viability through clearance complexity rather than scale metrics alone. Rural hospital buyers in Medicare shortage areas are prioritizing FDA-cleared algorithms in procurement evaluations to mitigate liability exposure.
Subscription-based platform licensing is displacing per-study fee structures among health systems with predictable imaging volumes. Integrated delivery networks in the Southeast are consolidating vendor relationships around enterprise agreements that bundle PACS, AI tools, and radiologist coverage. This shift is most visible in Florida, where hospital consolidation has concentrated buying power among three dominant systems.
US Teleradiology Market Segmentation
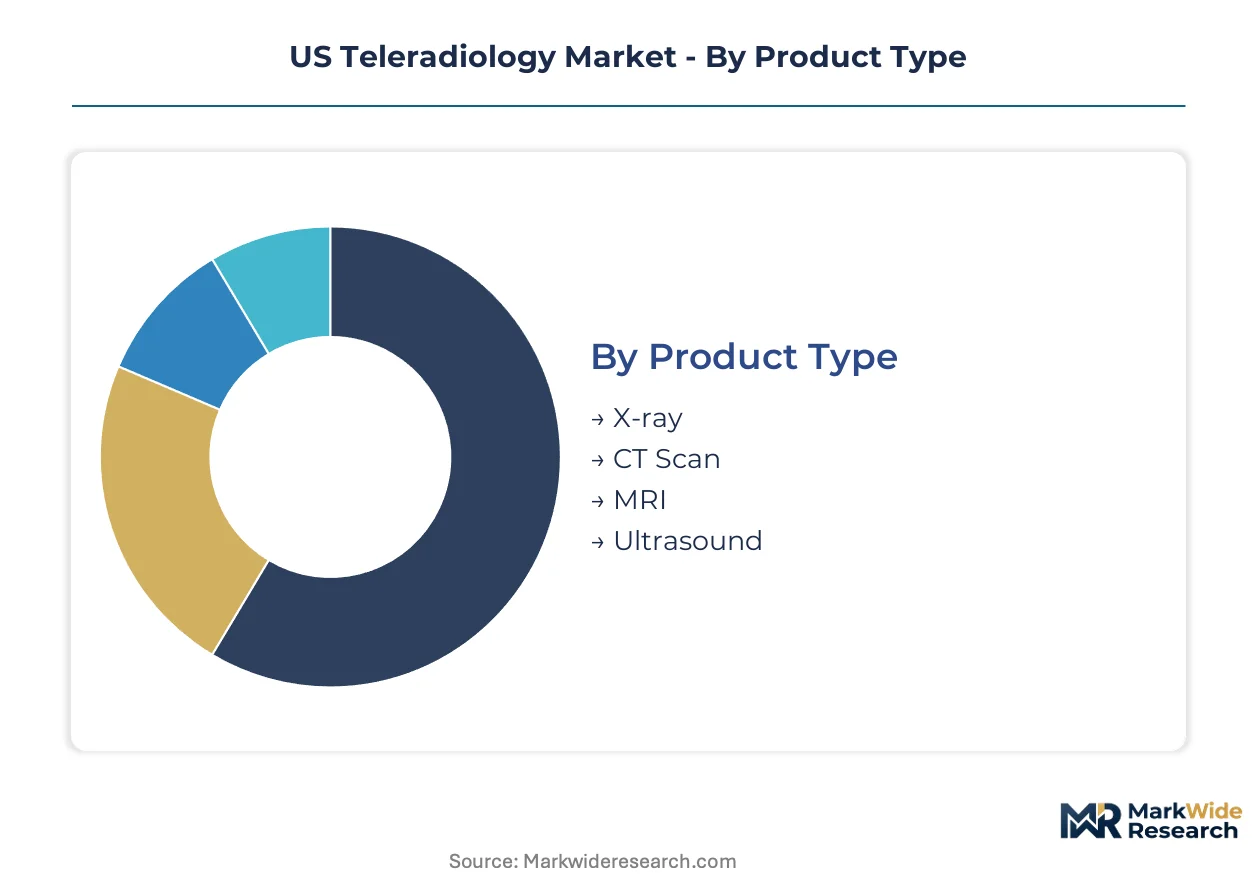
Teleradiology procurement decisions hinge on regulatory clearance requirements, infrastructure constraints, and reimbursement compatibility across distinct product and technology categories. Segmentation reveals where FDA predicate device pathways, HIPAA security rule enforcement, and CMS reimbursement policies create divergent compliance burdens and margin structures for vendors and buyers.
Product Type:
FDA 510(k) clearance requirements vary sharply across modalities, with CT and MRI devices facing stricter predicate device scrutiny than X-ray and ultrasound platforms.
- CT Scan:Complex three-dimensional reconstruction algorithms demand subspecialty neuroradiology expertise and carry elevated medicolegal exposure. Southeast rural hospital networks concentrate procurement here as CMS shortage-area reimbursement premiums offset higher interpretation costs.
- X-ray:High-volume, low-complexity studies dominate emergency department workflows and require minimal subspecialty credentialing. Texas and Florida health systems deploy remote X-ray reads for overnight coverage where physician staffing gaps are most acute.
- MRI:Magnetic resonance studies require DICOM-compliant transmission of large dataset volumes and specialized musculoskeletal or neuroradiology interpretation.
- Ultrasound:Real-time image acquisition demands sub-100-millisecond latency infrastructure that strains rural hospital bandwidth capacities.
X-ray sits at the top of the volume ranking, with CT Scan climbing the fastest.
Delivery Mode:
Capital expenditure profiles and HIPAA business associate agreement complexity sort health systems across deployment architectures, with cloud-native platforms displacing legacy on-premise installations.
- Cloud-based:Subscription licensing eliminates upfront PACS infrastructure investment and enables automatic software updates for FDA-cleared AI algorithms. Southeast integrated delivery networks favor this model for enterprise standardization across consolidated hospital systems.
- Hybrid:Combines on-premise image acquisition with cloud-based interpretation workflows, accommodating legacy DICOM modalities in rural facilities. Arizona and New Mexico hospital networks adopt hybrid architectures to bridge aging equipment with modern teleradiology platforms.
- On-premise:Requires dedicated server infrastructure and internal IT security management that burdens smaller independent radiology groups.
- Mobile:Tablet-based diagnostic access supports point-of-care ultrasound and emergency department consultation where fixed workstation deployment is impractical.
Cloud-based holds the dominant share position, while Hybrid is gaining share fastest among rural buyers with legacy equipment constraints.
End User:
Procurement sophistication and contract scale separate institutional buyers, with hospitals commanding enterprise pricing and telehealth providers driving platform standardization demands.
- Hospitals:Academic medical centers and community hospitals generate the highest study volumes and require 24/7 subspecialty coverage guarantees. Rural hospital networks in Georgia and North Carolina structure multi-year agreements with turnaround-time SLAs for critical findings.
- Telehealth Providers:Virtual-first care models integrate teleradiology into bundled primary care subscriptions, prioritizing API interoperability with electronic health records. Medicare Advantage penetration in Florida accelerates adoption here as risk-bearing entities seek diagnostic cost control.
- Imaging Centers:Independent diagnostic facilities compete on appointment availability and require rapid preliminary reads to maintain patient throughput.
- Clinics:Federally qualified health centers in designated shortage areas leverage CMS reimbursement premiums for remote professional component reads.
Hospitals anchor the volume base, with Telehealth Providers expanding most quickly as virtual care models mature.
Technology:
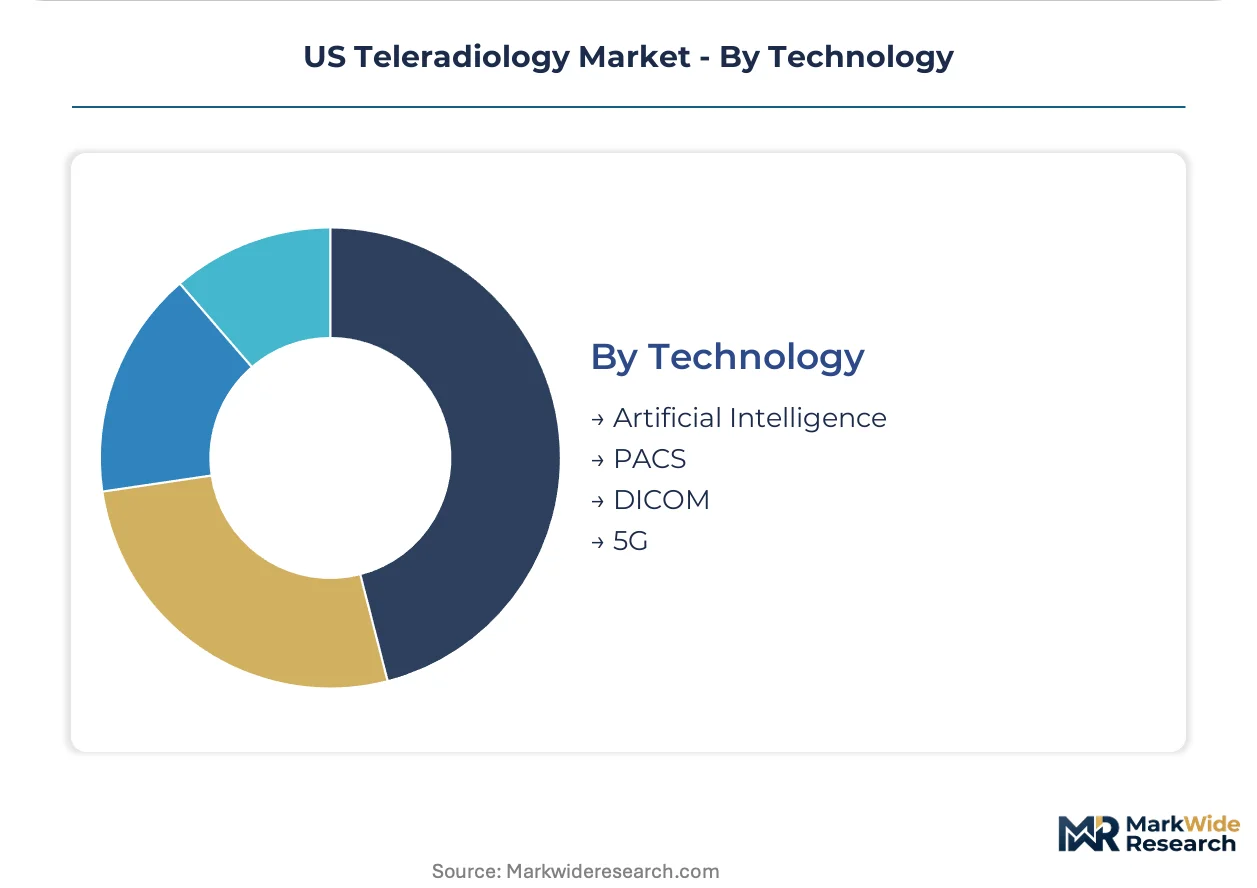
FDA software-as-a-medical-device pathways and FCC spectrum allocation decisions determine which technology investments unlock reimbursable diagnostic capabilities.
- Artificial Intelligence:Computer-aided detection algorithms for mammography and lung nodule screening require FDA 510(k) clearance as software-as-a-medical-device. Texas hospital networks prioritize FDA-cleared AI tools in procurement to mitigate liability exposure and compress radiologist interpretation time.
- PACS:Picture archiving and communication systems form the workflow backbone for image storage, retrieval, and diagnostic display. Cloud-native PACS deployments from enterprise vendors consolidate market position through bundled AI integration.
- DICOM:Digital imaging and communications in medicine standards ensure interoperability between acquisition modalities and interpretation platforms.
- 5G:Ultra-reliable low-latency communication enables real-time consultation and telerobotic ultrasound guidance where fiber infrastructure is unavailable.
PACS maintains the installed base leadership, with Artificial Intelligence showing the steepest expansion trajectory as FDA clearance pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeastern states generate faster teleradiology contract velocity than the Mountain West, though both regions face acute radiologist shortages driving remote coverage adoption.
Southeast
Florida, Georgia, and North Carolina hospital networks concentrate procurement as Medicare Advantage expansion concentrates buying power among integrated delivery systems. CMS reimbursement premiums for professional component reads in designated shortage areas compress vendor selection cycles. Atlanta and Miami metropolitan clusters anchor enterprise agreements bundling PACS, AI tools, and 24/7 subspecialty coverage.
Mountain West
Arizona and New Mexico rural facilities adopt hybrid cloud architectures to bridge legacy DICOM equipment with modern platforms. Interstate Medical Licensure Compact participation among western states reduces credentialing friction for multi-state radiologist deployment. Phoenix and Albuquerque health systems structure turnaround-time SLAs for critical findings across dispersed geographic footprints.
Texas
Independent diagnostic facilities and hospital networks deploy remote X-ray reads for overnight emergency department coverage where staffing gaps peak. FDA-cleared AI algorithms for mammography and lung nodule screening prioritize procurement evaluations to mitigate liability exposure. Dallas-Fort Worth and Houston metropolitan areas drive volume concentration for computer-aided detection platform adoption.
Midwest
Illinois and Ohio academic medical centers compete with teleradiology groups for limited neuroradiology and pediatric imaging fellowship-trained talent. HIPAA security rule enforcement by the Office for Civil Rights imposes compliance costs on smaller independent radiology groups. Chicago anchors subspecialty expertise concentration while rural hospital networks in surrounding states rely on remote coverage contracts.
Northeast Corridor
New York and Massachusetts health systems prioritize cloud-native PACS migrations for capital-light scalability across consolidated hospital networks. State medical licensure fragmentation creates administrative overhead limiting workforce mobility despite high radiologist density in Boston and New York City metropolitan clusters. Subscription-based platform licensing displaces per-study fee structures among systems with predictable imaging volumes.
US Teleradiology Market Competitive Landscape
US-based national networks anchor one tier; European imaging equipment manufacturers hold infrastructure dominance. The vendor base stratifies across interpretation service providers, enterprise PACS platform vendors, and AI algorithm developers. Three archetypes define positioning: scale-driven radiologist networks, integrated imaging infrastructure suppliers, and diagnostic algorithm specialists. Consolidation concentrates among enterprise agreement bundlers while point-solution providers face margin compression.
Within the scale-driven radiologist network tier, Virtual Radiologic (vRad) and Matrix (Teleradiology Division of Radiology Partners) occupy positions defined by national coverage footprints and subspecialty depth. Koninklijke Philips N.V. represents the integrated infrastructure archetype, anchoring enterprise PACS-to-cloud deployments. These three entities exemplify divergent competitive vectors: vRad and Matrix concentrate on workforce scale and turnaround-time guarantees, while Philips leverages hardware-to-software integration across acquisition, transmission, and diagnostic display workflows.
| Leading Market Players |
|---|
| Virtual Radiologic (vRad) |
| ONRAD, Inc. |
| USARAD Holdings, Inc. |
| Everlight Radiology |
| Agfa-Gevaert Group |
| Koninklijke Philips N.V. |
| RamSoft, Inc. |
| Matrix (Teleradiology Division of Radiology Partners) |
| RAYUS Radiology Services |
| Others |
Pricing and Supply Chain Analysis
Cloud-native PACS migration simultaneously compresses capital expenditure thresholds and concentrates purchasing leverage among Southeast integrated delivery networks. Subscription licensing eliminates upfront infrastructure investment while bundling AI algorithms into enterprise agreements, reshaping how rural hospital buyers negotiate coverage contracts and platform access.
Pricing Analysis
Capacity additions in cloud infrastructure are reshaping price floors for teleradiology platform access across the Southeast. Three-tier pricing structure across premium, standard, and economy levels segments buyers by study volume commitments and subspecialty coverage depth. Price differentiation centers on FDA-cleared algorithm bundles and turnaround-time SLA guarantees. Rural hospital networks in Medicare shortage areas exhibit highest price sensitivity, while academic medical centers prioritize subspecialty neuroradiology expertise over cost.
Supply Chain Analysis
Freight costs for specialized diagnostic display hardware and DICOM-compliant networking equipment strain rural hospital IT procurement budgets. Manufacturing concentrates in the United States, Germany, and Japan for enterprise PACS platforms and AI algorithm development. Component dependencies include GPU chipsets for AI inference, high-resolution medical-grade monitors, and fiber-optic transmission infrastructure. Single-source vulnerability in cloud hyperscaler concentration threatens service continuity. Distribution runs through direct enterprise sales teams and GPO contracts for hospital network consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Teleradiology Market functions as a stable compounder, with CMS reimbursement expansion for remote professional component reads generating predictable revenue visibility for platform vendors and interpretation networks.
For Market Incumbents: Anticipate margin compression from AI-augmented workflow automation by deepening subspecialty radiologist pools and embedding quality assurance protocols into standard contract terms. Vertical integration into cloud-native PACS infrastructure protects against disintermediation by standalone algorithm vendors. Lock in multi-year enterprise agreements with Georgia and Florida hospital systems before Interstate Medical Licensure Compact expansion erodes geographic moats. For New Entrants and Emerging Players: Enter via Federally qualified health centers in designated shortage areas, where CMS reimbursement premiums offset initial customer acquisition costs. Target Arizona and New Mexico rural facilities with hybrid cloud architectures bridging legacy DICOM equipment. Lead with API interoperability and rapid credentialing through western state licensure compact participation. For Investors and Strategic Acquirers: Valuations sit cheapest among independent radiology groups lacking AI algorithm bundles or cloud infrastructure ownership. Five-to-ten-year viability hinges on FDA software-as-a-medical-device clearance pipelines and enterprise PACS integration depth. Monitor Interstate Medical Licensure Compact participation rates as inflection signal for workforce mobility and coverage scalability.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm FDA Clearance | FDA 510(k) pathways for mammography and lung nodule detection unlock bundled platform pricing power. |
| Enterprise PACS Integration | Cloud-native deployments from Philips consolidate hospital network relationships across acquisition-to-display workflows. |
| Interstate Licensure Expansion | Compact participation among western states reduces radiologist deployment friction for multi-state coverage pools. |
| Subspecialty Workforce Development | Neuroradiology fellowship partnerships with academic medical centers secure scarce talent against hospital competition. |
| CMS Reimbursement Strategy | Professional component read expansion in shortage areas pulls rural hospital buyers into long-term contracts. |
Research Methodology
Coverage spans the Southeast, Mountain West, Texas, Midwest, and Northeast Corridor, with primary inputs from each region triangulated against secondary validation. Primary interviews engaged teleradiology group executives, hospital purchasing committee members, GPO contracts managers, and CMS policy specialists. Secondary sources included FDA 510(k) device filings, CMS Medicare reimbursement databases, hospital procurement records, and Interstate Medical Licensure Compact participation reports. Bottom-up study volume estimates and top-down market sizing were cross-referenced for convergence.
Rate-of-change decomposition across the analysis window segmented growth by product type, delivery mode, end user, and technology adoption curve. CAGRs were derived from historical trajectory analysis and policy-driven demand elasticity modeling. Forecast inputs incorporated radiologist supply constraints, cloud infrastructure capex cycles, and FDA clearance velocity for AI-enabled diagnostic tools.
The model holds under stable CMS reimbursement policy and continued Interstate Medical Licensure Compact expansion; deviation in FDA software-as-a-medical-device pathway complexity or HIPAA enforcement intensity would shift vendor viability rankings. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Europe Mobile Tomography Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Italy Magnetic Resonance Imaging Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Multiphoton Microscopy Market