
 Heat Therapy Units Market | 2026-2036
Heat Therapy Units Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Therapy Units Market Foresight
The EU Medical Device Regulation is rebalancing the cost-of-entry calculus for manufacturers seeking CE marking approval across European markets. DJO Global leverages its rehabilitation-focused portfolio to sustain channel dominance in clinical settings. Beurer GmbH anchors the home-use segment through specialized consumer distribution networks. Mettler Electronics competes on technology leadership in conductive heating systems for professional physiotherapy applications.
Heat therapy units are electromechanical or thermal devices engineered to deliver controlled temperatures between 40°C and 60°C to targeted body regions via conductive, radiant, or convection mechanisms, primarily serving musculoskeletal treatment, pain management, and tissue healing protocols in clinical and domestic environments. Electric and infrared product types command the dominant installed base, though moist heat systems capture expanding share in rehabilitation centers where penetration of hydrogel-based thermal pads is accelerating. Among end users, home users represent the fastest-growing demand pool, while hospitals retain the deepest margin pools due to procurement scale and device utilization rates.
FDA 510(k) clearances, EU MDR conformity assessments, and ISO 13485 quality management standards collectively govern product design documentation, clinical validation requirements, and post-market surveillance obligations for manufacturers. These frameworks elevate R&D fixed costs but simultaneously compress competitive field density by filtering out undercapitalized entrants. Stakeholders must monitor reimbursement code revisions by CMS and parallel national health authorities, as coverage determinations for thermal modalities directly influence provider purchasing cycles and home-user out-of-pocket willingness.
Market Dynamics
FDA 510(k) clearance timelines for thermal medical devices have lengthened substantially, forcing manufacturers to front-load clinical validation investments and compress product development cycles to maintain commercial viability.
Growth Catalysts
- EU MDR conformity pathways:The Medical Device Regulation's stricter clinical evidence requirements are filtering out marginal competitors and consolidating market share among well-capitalized manufacturers with established quality management systems.
- Post-surgical rehabilitation protocols:Moist heat and infrared systems are embedding into standardized recovery pathways across orthopedic and sports medicine practices, creating recurring procurement cycles.
- Hydrogel-based thermal pads:This material innovation enables sustained temperature control with reduced burn risk, accelerating penetration in professional physiotherapy settings where patient safety liability concentrates.
Market Restraints
- Semiconductor component volatility:Microcontroller and sensor supply shortages from East Asian foundries have extended lead times for precision temperature control systems by 12-18 months.
- Reimbursement code compression:CMS revisions to physical therapy billing codes are narrowing covered indications for thermal modalities, constraining hospital capital expenditure justification.
- Topical analgesic substitution:Transdermal lidocaine and capsaicin patches are capturing low-acuity pain management cases that previously defaulted to electrothermal devices.
Strategic Opportunities
- Home-use channel expansion:Direct-to-consumer distribution via specialized medical supply platforms is bypassing traditional durable medical equipment intermediaries in Germany and Japan.
- ISO 13485 certification arbitrage:Manufacturers with existing quality management infrastructure can accelerate market entry in emerging economies where regulatory harmonization is advancing.
- Wearable thermal integration:Convergence of flexible heating elements with biometric monitoring is opening continuous therapy applications for chronic pain management outside clinical settings.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 validation for skin-contact materials is extending product launch timelines and requiring specialized toxicology partnerships.
- Legacy system integration:New conductive heating platforms must interface with existing electronic health record architectures, complicating hospital sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Therapy Units Market |
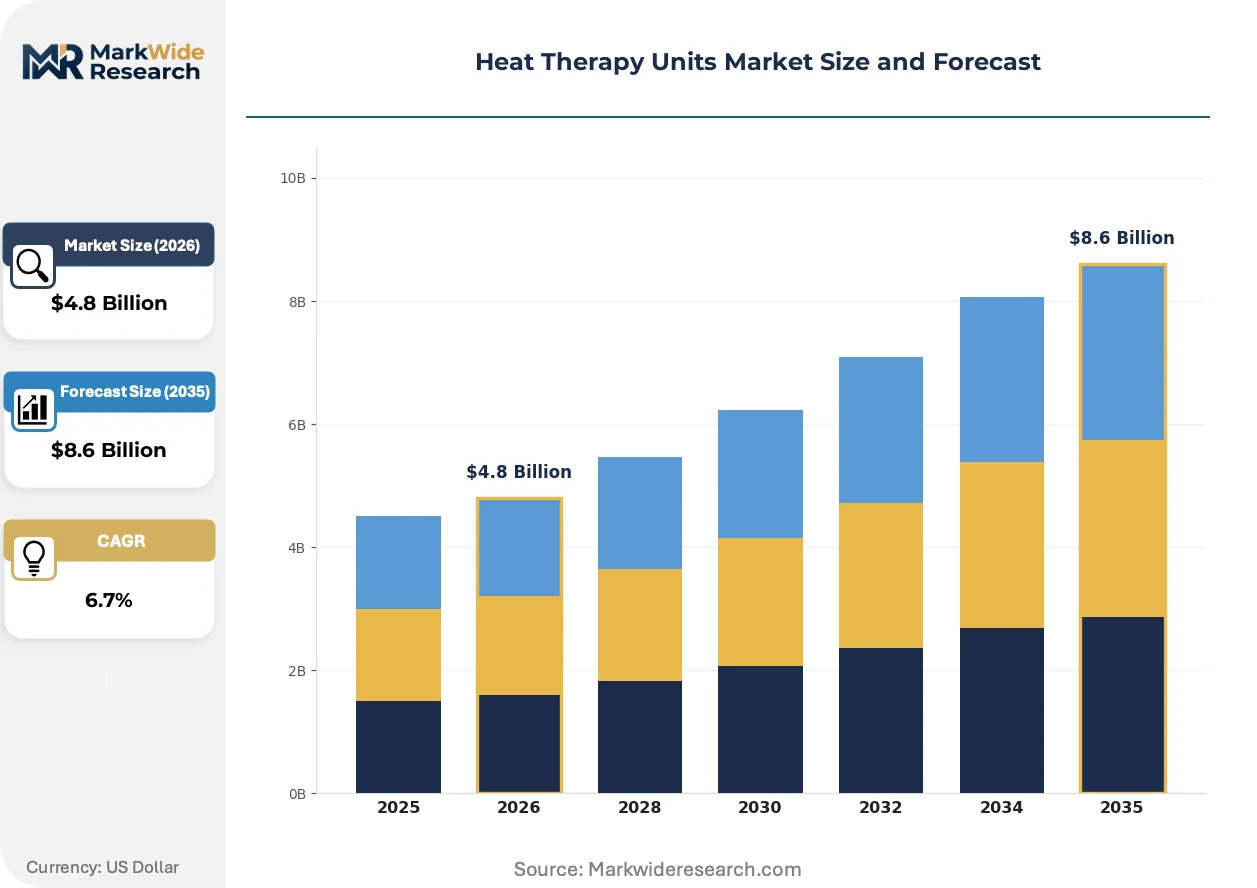
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Electric, Moist Heat, Dry Heat End User: Clinics, Hospitals, Home Users, Rehabilitation Centers Technology: Conductive Heating, Radiant Heating, Convection Heating, Microwave Heating Application: Pain Relief, Muscle Relaxation, Rehabilitation, Injury Recovery |
| Companies Covered | Beurer GmbH, Medline Industries, DJO Global, Mettler Electronics, Performance Health, BTL International, Breg, Chattanooga Group, Zimmer MedizinSysteme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Therapy Units Market Shifts & Advancements
Digital temperature control architectures are displacing analog thermostat systems across both clinical and domestic product tiers, enabling precise thermal profiling that aligns with evidence-based treatment protocols.
Machine learning algorithms embedded in next-generation control units are automating adaptive temperature modulation based on patient feedback loops and treatment duration parameters. Rehabilitation centers in the United States are piloting these systems for post-operative protocols where thermal consistency correlates with recovery velocity. This automation is compressing the clinical training burden and expanding addressable use cases beyond supervised settings.
REACH substance restrictions on phthalates and certain flame retardants are forcing material reformulation across European supply chains, with particular impact on flexible heating element housings and power cord insulation. Manufacturers with early compliance investments are capturing shelf space as retailers accelerate de-listing of non-conforming SKUs ahead of enforcement deadlines.
Subscription-based equipment access models are displacing outright purchase arrangements in multi-site physiotherapy chains, transferring capital burden to manufacturers and distributors. This reconfiguration is most visible in Japan where aging clinic ownership and succession planning challenges favor operational expenditure structures over asset ownership.
Heat Therapy Units Market Segmentation
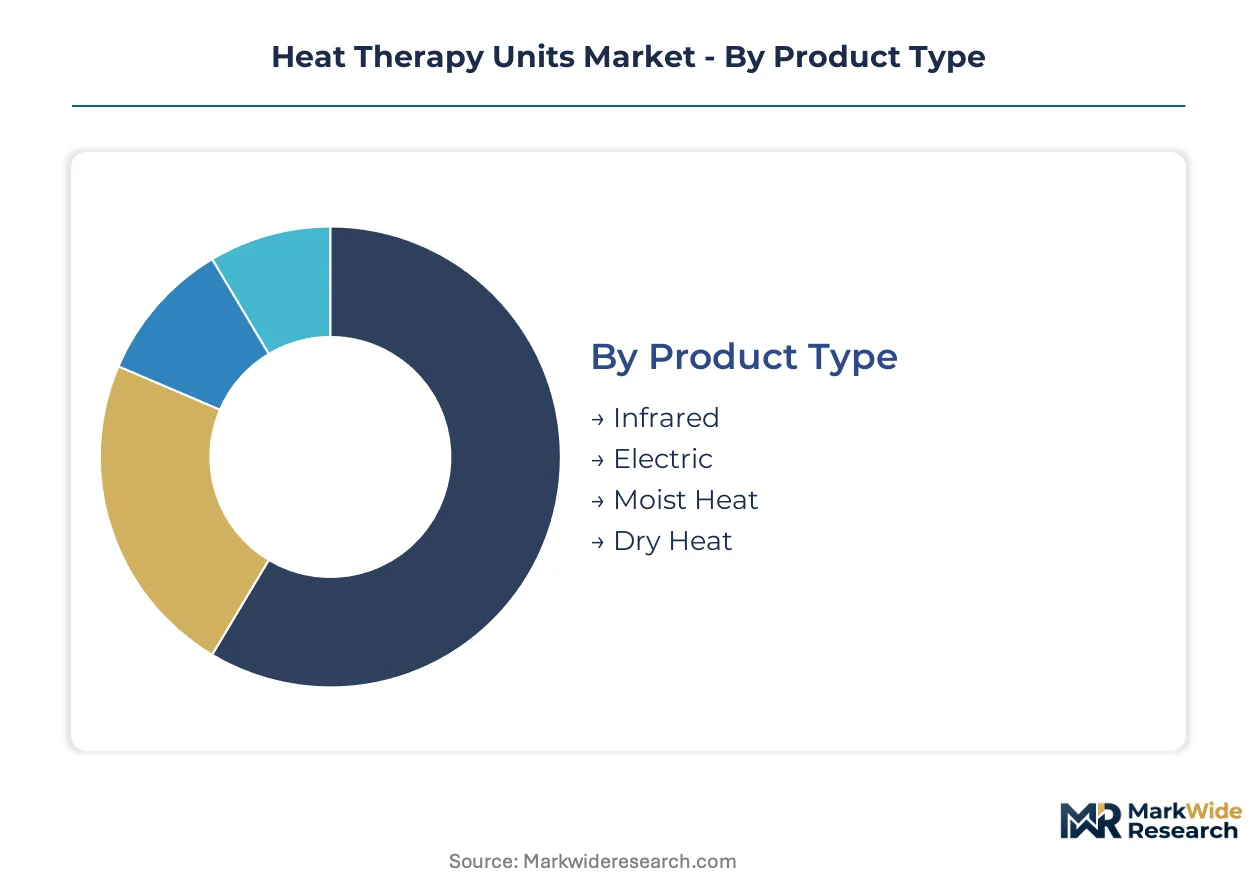
Segmentation in heat therapy units reveals divergent capital requirements and margin profiles across clinical versus domestic applications. Product architecture, distribution channels, and regulatory pathways vary substantially by segment, forcing manufacturers to prioritize investment selectively.
Product Type:
Capital intensity peaks in infrared systems requiring precision optics and semiconductor temperature sensors, while electric heating platforms demand lower upfront tooling investment.
- Infrared:These units deploy ceramic or carbon fiber emitters generating radiant energy at 700-3000nm wavelengths for deep tissue penetration. Demand concentrates in German rehabilitation centers where post-surgical protocols favor non-contact thermal delivery. FDA 510(k) clearance timelines for infrared medical devices have lengthened, elevating clinical validation costs.
- Electric:Resistive wire or PTC ceramic elements deliver conductive heat through direct skin contact, with embedded thermistors enabling closed-loop temperature control. Japanese home users drive volume through retail pharmacy channels, though semiconductor supply volatility has extended controller lead times.
- Moist Heat:Hydrogel-based pads or steam reservoirs combine thermal energy with humidity transfer to enhance tissue permeability. Rehabilitation centers in the United States are standardizing these systems for orthopedic recovery protocols.
- Dry Heat:Air-circulated or direct-contact systems without moisture augmentation serve cost-sensitive clinical environments and basic home applications.
Most installed capacity flows through Electric. Expansion is steepest in Moist Heat.
End User:
Customer-type segmentation separates institutional procurement cycles from consumer purchasing patterns, with reimbursement eligibility determining price elasticity.
- Clinics:Outpatient physiotherapy practices purchase mid-tier systems with programmable treatment protocols and portable form factors. German clinic chains favor subscription-based equipment access models over capital expenditure.
- Hospitals:Acute care facilities demand enterprise-grade units with electronic health record integration and centralized fleet management. Procurement scale yields deepest margin pools, though CMS reimbursement code revisions are narrowing covered thermal modality indications.
- Home Users:Direct-to-consumer channels in Japan and Germany are bypassing durable medical equipment intermediaries. This segment is expanding most quickly as aging populations seek self-managed pain relief outside clinical settings.
- Rehabilitation Centers:Post-acute facilities standardize moist heat and infrared systems into orthopedic and sports medicine recovery pathways, creating recurring procurement cycles.
Procurement volume concentrates in Hospitals. Addressable base is climbing the fastest in Home Users.
Technology:
Technology choice determines sensor architecture, control system complexity, and biocompatibility validation burden.
- Conductive Heating:Direct energy transfer through solid media or skin contact dominates professional physiotherapy applications. Mettler Electronics anchors technology leadership in this architecture for clinical settings.
- Radiant Heating:Electromagnetic wave delivery enables non-contact treatment with reduced burn risk. Japanese rehabilitation centers pilot machine-learning-controlled adaptive modulation for post-operative protocols.
- Convection Heating:Forced air or fluid circulation systems serve institutional environments requiring whole-limb or whole-body thermal coverage.
- Microwave Heating:Dielectric heating at 915MHz or 2.45GHz penetrates deeper tissue layers but requires precise field control to prevent hotspots. Regulatory scrutiny from FDA and Japan's PMDA elevates clinical evidence requirements.
Professional installed base centers on Conductive Heating. Penetration is accelerating fastest in Radiant Heating.
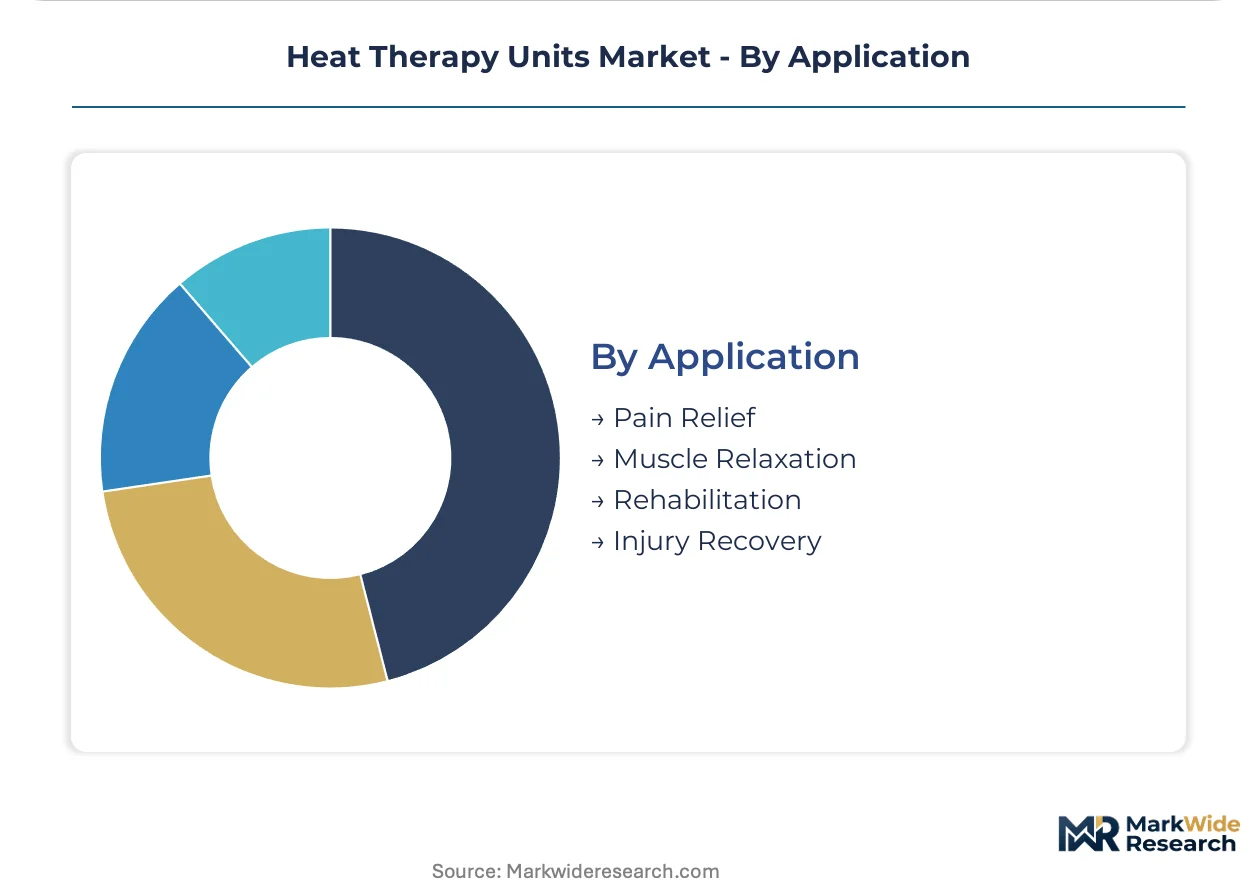
Application:
Application segmentation aligns product specifications with clinical evidence requirements and reimbursement coding.
- Pain Relief:Chronic and acute pain management applications drive consumer purchasing and clinical referral patterns. Transdermal lidocaine patches are capturing low-acuity cases that previously defaulted to electrothermal devices.
- Muscle Relaxation:Spasm reduction and flexibility enhancement protocols in sports medicine and geriatric care. German physiotherapy practices embed these systems into standardized treatment pathways.
- Rehabilitation:Post-surgical and post-injury functional recovery programs. United States orthopedic centers are piloting digital temperature control architectures that correlate thermal consistency with recovery velocity.
- Injury Recovery:Acute trauma management and tissue healing acceleration. REACH substance restrictions on phthalates are forcing material reformulation in European supply chains for skin-contact components.
Volume deployment concentrates in Pain Relief. Protocol integration is advancing most rapidly in Rehabilitation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered electrothermal medical device manufacturing in the 1970s, establishing quality benchmarks that shaped regulatory frameworks across Europe and North America. This industrial heritage continues to concentrate design expertise and precision engineering capacity in Central Europe.
United States
Post-surgical rehabilitation protocols drive institutional procurement, with orthopedic centers standardizing moist heat systems into recovery pathways. FDA 510(k) clearance timelines for thermal medical devices have lengthened substantially, elevating clinical validation costs for entrants. Minneapolis and Boston anchor device development clusters where rehabilitation-focused manufacturers maintain channel dominance.
Germany
Reimbursement coverage for physical therapy converges with aging demographics to sustain clinical demand. EU MDR conformity assessments filter marginal competitors, consolidating share among manufacturers with established quality management systems. The Stuttgart and Munich metropolitan areas concentrate precision heating element fabrication and hydrogel-based thermal pad innovation.
Japan
Home users represent the fastest-growing demand pool as aging populations seek self-managed pain relief outside clinical settings. PMDA regulatory harmonization with ISO 13485 standards accelerates market entry for quality-certified manufacturers. Tokyo and Osaka host pilot programs for machine-learning-controlled adaptive temperature modulation in post-operative protocols.
United Kingdom
Subscription-based equipment access models displace outright purchase arrangements in multi-site physiotherapy chains. NHS reimbursement code revisions influence provider purchasing cycles and capital expenditure justification. London and the Southeast concentrate distribution infrastructure for specialized medical supply platforms serving home-use channels.
South Korea
Flexible heating element convergence with biometric monitoring opens continuous therapy applications for chronic pain management. MFDS alignment with international standards reduces duplicate testing burdens for export-oriented manufacturers. Seoul and Gyeonggi Province anchor semiconductor integration capabilities for next-generation digital temperature control architectures.
Heat Therapy Units Market Competitive Landscape
The competitive structure tilts toward rehabilitation-focused specialists with established clinical channel relationships. Quality management certification density separates viable participants from marginal entrants, particularly under EU MDR and FDA 510(k) frameworks. Three archetypes dominate: diversified medical device conglomerates with rehabilitation portfolios, specialized electrothermal equipment fabricators, and consumer health appliance manufacturers leveraging retail pharmacy networks. Competitive moves center on geographic expansion into reimbursement-favorable markets and portfolio diversification toward wearable thermal integration.
Among diversified medical device conglomerates, DJO Global represents the rehabilitation-centric archetype with channel dominance in clinical settings. Beurer GmbH exemplifies the consumer health appliance model, anchoring home-use segments through specialized distribution networks. Mettler Electronics occupies a position within the specialized equipment tier, with technology leadership associations in conductive heating systems for professional physiotherapy applications.
| Leading Market Players |
|---|
| Beurer GmbH |
| Medline Industries |
| DJO Global |
| Mettler Electronics |
| Performance Health |
| BTL International |
| Breg |
| Chattanooga Group |
| Zimmer MedizinSysteme |
| Others |
Supply & Pricing Matrix
REACH substance restrictions on phthalates and flame retardants gate qualified supply for European markets while simultaneously segmenting pricing access between compliant premium tiers and reformulation-lagged economy offerings. Hydrogel-based thermal pad manufacturers with early toxicology validation investments capture shelf space as retailers accelerate de-listing of non-conforming SKUs ahead of enforcement deadlines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified clinical systems from consumer-grade retail units and unbranded import alternatives. Price differentiation hinges on FDA 510(k) clearance status and after-sales service bundling, with premium tiers commanding substantial markups for EHR-integrated enterprise platforms. Cost compression in the standard tier is intensifying because semiconductor controller shortages have forced manufacturers to absorb component inflation rather than pass through to price-sensitive home users. Rehabilitation centers exhibit the lowest price sensitivity due to reimbursement coverage, while direct-to-consumer channels in Germany and Japan face acute elasticity.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Minneapolis, and Osaka anchor hub-and-spoke patterns that feed specialized medical supply platforms and hospital GPO networks. Manufacturing concentrates in Germany, Japan, and the United States where precision heating element fabrication and hydrogel formulation capabilities cluster. Raw material dependencies draw from East Asian semiconductor foundries for temperature sensors, European chemical suppliers for biocompatible hydrogels, and Chinese wire harness producers for conductive elements. Single-source vulnerability in microcontroller supply creates 12-18 month lead time exposure. Distribution runs through durable medical equipment intermediaries for institutional buyers and direct-to-consumer platforms for home users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's stricter clinical evidence requirements compound competitive advantages for quality-certified manufacturers while filtering marginal entrants from reimbursement-eligible procurement channels.
For Market Incumbents: Lock in channel dominance by deepening backward integration into hydrogel formulation capabilities and securing long-term semiconductor supply agreements with Japanese and Taiwanese foundries. Transdermal lidocaine patch substitution threatens low-acuity electrothermal volumes, requiring incumbents to accelerate wearable thermal integration with biometric monitoring to defend clinical relevance. ISO 10993 validation partnerships with specialized toxicology laboratories represent the critical certification lever for sustaining European market access. For New Entrants and Emerging Players: Specialized medical supply platforms serving German and Japanese home-use channels offer the most penetrable entry vector, bypassing entrenched durable medical equipment intermediaries. White-space concentrates in subscription-based equipment access models for multi-site physiotherapy chains where aging clinic ownership favors operational expenditure structures. Direct-to-consumer positioning through retail pharmacy networks enables rapid volume accumulation without capital-intensive hospital sales cycle investment. For Investors and Strategic Acquirers: Roll-up economics work for specialized electrothermal equipment fabricators because EU MDR compliance investments have consolidated the competitive field and elevated replacement costs for quality management infrastructure. Rehabilitation-focused manufacturers with established clinical channel relationships and existing ISO 13485 certification offer the strongest 5-10 year viability profile. Watch CMS reimbursement code revisions for thermal modalities as the primary inflection signal—coverage expansion would trigger hospital capital expenditure acceleration, while further compression would shift procurement toward lower-margin home-use substitution.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Front-loaded clinical validation investments compress competitive field density by filtering undercapitalized entrants. |
| CE Marking Pathway Optimization | EU MDR conformity assessments consolidate market share among manufacturers with established quality management systems. |
| Hospital System Partnership | EHR-integrated enterprise platforms capture deepest margin pools through procurement scale and utilization rates. |
| Software Companion Development | Machine learning-controlled adaptive temperature modulation expands addressable use cases beyond supervised clinical settings. |
| Reimbursement Strategy | Coverage determinations for thermal modalities directly influence provider purchasing cycles and home-user out-of-pocket willingness. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with rehabilitation center procurement directors, hospital biomedical engineers, GPO contracts managers, and home-use channel distributors with secondary validation against FDA 510(k) clearance databases, EU MDR notified body registers, CMS Medicare reimbursement code filings, and hospital procurement system records. Bottom-up unit economics and top-down macroeconomic triangulation anchored market sizing.
Historical reference periods spanning the pre-pandemic baseline through semiconductor shortage disruption and EU MDR transition anchored the forecast window. Segmentation modeling captured product type, end user archetype, heating technology, and application indication dimensions across the projection horizon. CAGRs derived from fitted growth curves applied to penetration rate assumptions for moist heat systems in orthopedic recovery protocols and home-use channel expansion in aging demographics. Semiconductor lead time normalization and REACH compliance cost trajectories informed scenario-weighted outputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA 510(k) clearance timeline volatility, CMS reimbursement code compression, and hydrogel material innovation disruption. Outputs reflect documented assumptions regarding semiconductor supply recovery and regulatory harmonization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasound Skin Tightening Devices Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Infusion Management Market
Medical Devices
China General Surgical Devices Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Sialendoscopes Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Urethral Bulking System Market