
 Global Closed MRI Systems Market | 2026-2036
Global Closed MRI Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Closed MRI Systems Market Analysis
China's manufacturing corridor is reconfiguring the global supply map for superconducting magnet assemblies and gradient coil subsystems. Siemens Healthineers leverages captive cryogenics production to protect margin pools on 3.0 Tesla platforms. GE HealthCare anchors North American service revenue through long-term fleet management contracts with integrated delivery networks. Koninklijke Philips N.V. competes on compressed-sense acquisition speed across European academic hospital tenders.
Closed MRI systems enclose the patient within a cylindrical bore housing superconducting coils cooled by liquid helium to temperatures near 4 Kelvin, generating static magnetic fields from 1.5 to 7.0 Tesla for high-resolution tomographic imaging of soft tissue pathology. Superconducting technology dominates installed value due to field strength requirements in neurology and oncology protocols, while permanent magnet designs occupy price-sensitive clinic segments where siting costs constrain capital budgets. Hospitals represent the deepest procurement pool, though imaging centers are extending throughput-based financing models that shift ownership risk to vendors.
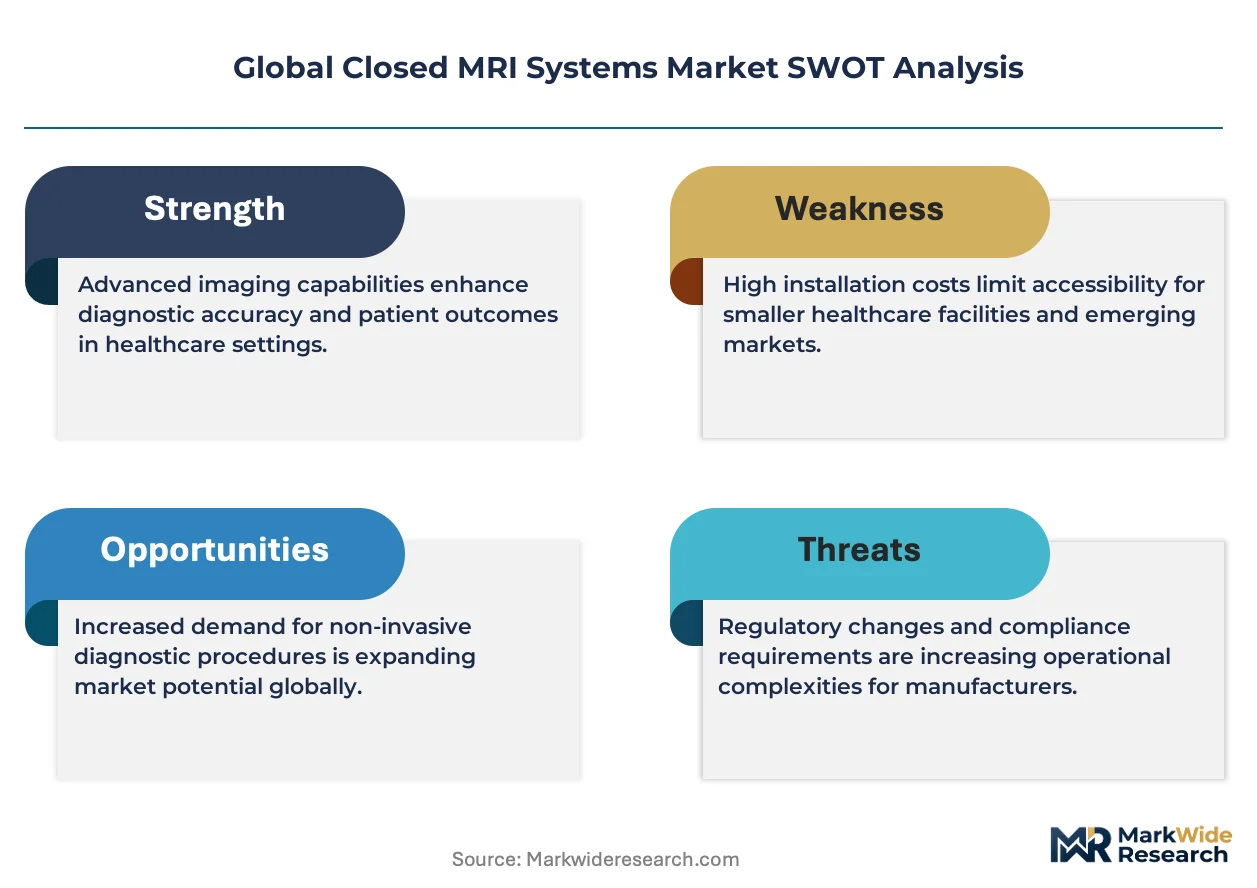
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation's notified body recertification deadlines are extending product approval timelines and concentrating vendor resources on compliance documentation. China's NMPA innovation pathway and Japan's PMDA quality management audits further fragment the regulatory entry landscape for new coil architectures and AI reconstruction modules. Stakeholders must monitor helium supply chain restructuring and alternative cooling technology readiness as sovereign hospital buyers rewrite tender specifications.
Market Dynamics
Helium supply chain restructuring is forcing vendors to reengineer cryogenic cooling architectures and rewrite service contract economics across installed fleets.
Growth Catalysts
- Aging demographics in OECD markets:Japan's Ministry of Health projects diagnostic imaging volumes to rise through 2040 as population median age exceeds 48 years.
- MDR recertification deadlines:Europe's Medical Device Regulation is consolidating vendor resources toward compliance documentation, filtering marginal competitors from tender pools.
- Compressed-sense acquisition protocols:Reduced scan times enable throughput gains in hospital outpatient departments, improving capital efficiency per scanner.
Market Restraints
- Helium price volatility:Qatar's export concentration and Algeria's supply disruptions expose magnet cooling costs to geopolitical shocks.
- Site preparation expenses:Quench vent infrastructure and fringe field shielding add 15-25% to total cost of ownership in urban hospital deployments.
- Permanent magnet substitution:Low-field open systems capture price-sensitive clinic segments where siting constraints override resolution requirements.
Strategic Opportunities
- India's hospital infrastructure build-out:Government health insurance expansion and private chain consolidation concentrate near-term demand for mid-field superconducting platforms.
- Helium recapture and closed-loop cooling:On-site liquefaction systems reduce operating expenditure exposure to noble gas spot markets.
- AI reconstruction module integration:Deep learning-based denoising enables diagnostic-grade imaging at reduced field strengths, opening veterinary and sports medicine applications.
Industry Challenges
- Superconducting magnet engineering talent scarcity:Cryogenics and high-field electromagnet design expertise concentrates in legacy industrial clusters.
- 510(k) documentation burden:FDA software-as-medical-device oversight extends approval timelines for iterative coil and sequence updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Closed MRI Systems Market |
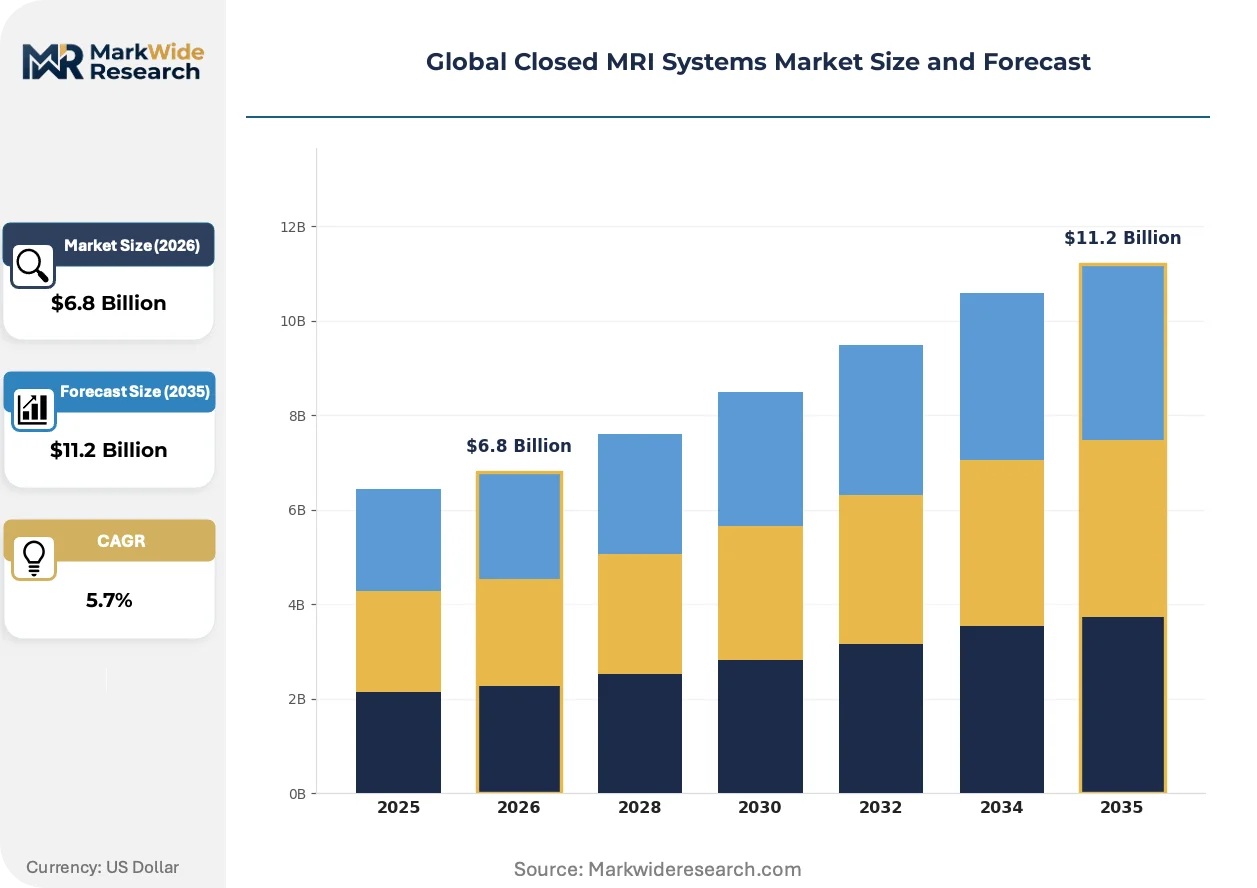
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
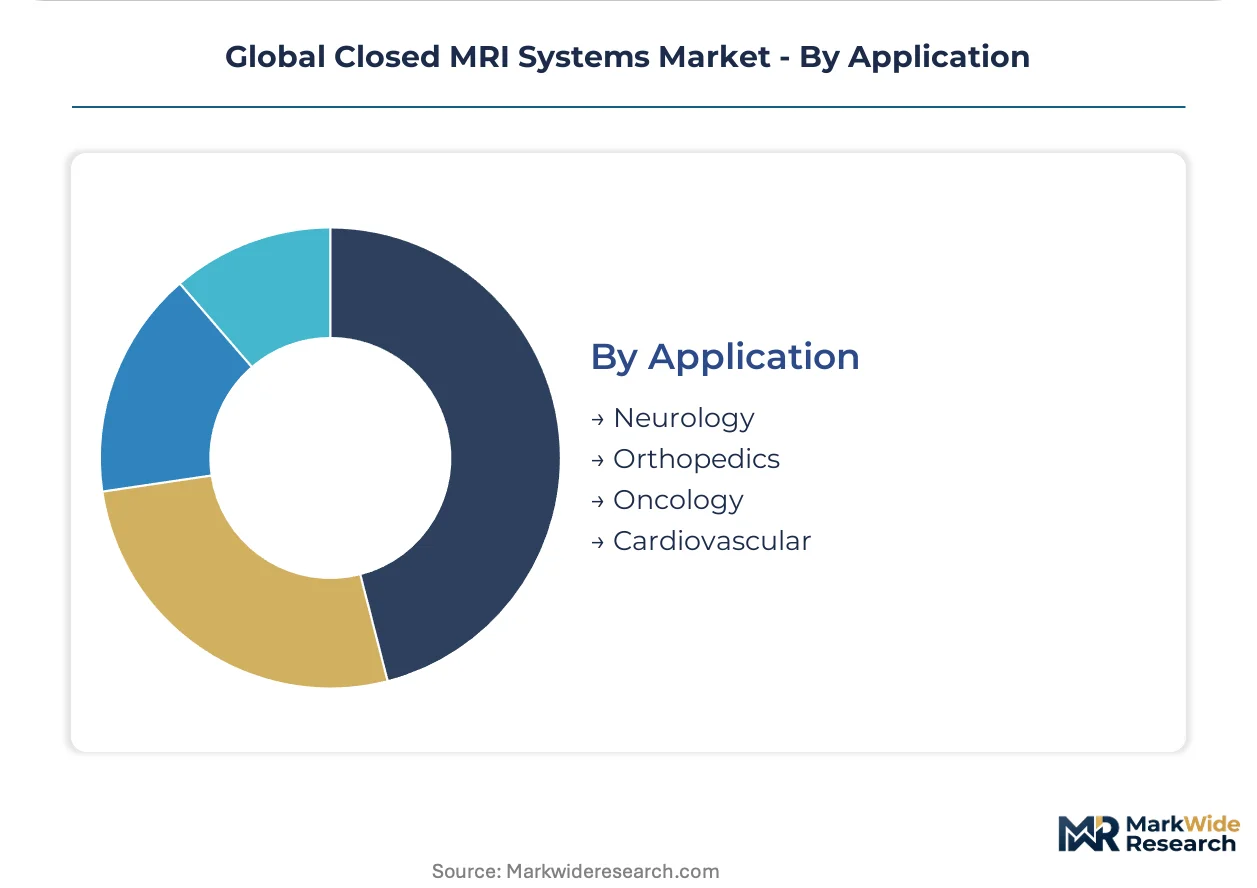
| Segmentation | Product Type: Open MRI, Closed MRI, Extremity MRI, Functional MRI Technology: Superconducting, Permanent Magnet, Resistive Magnet, Hybrid MRI End User: Hospitals, Imaging Centers, Clinics, Research Institutes Application: Neurology, Orthopedics, Oncology, Cardiovascular |
| Companies Covered | Siemens Healthineers, GE HealthCare, Koninklijke Philips N.V., FUJIFILM Holdings Corporation, Canon Medical Systems Corporation, Fonar Corporation, Esaote S.p.A, Shanghai United Imaging Healthcare Co., Ltd, Hitachi Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Closed MRI Systems Market Emerging Trajectories
Conduction-cooled magnet architectures and machine-learning reconstruction pipelines are compressing the traditional trade-off between field strength and operational economics.
Helium-free superconducting magnets employing conduction cooling via cryocooler arrays eliminate quench risks and liquid helium dependency. Siemens Healthineers and Philips have placed initial units in European academic hospitals, with NMPA pathway submissions underway for China. This platform shift is rendering obsolete the decade-old service revenue model tied to helium logistics and cryostat maintenance.
Europe's F-Gas Regulation and its phasedown of hydrofluorocarbon refrigerants is accelerating magnet cooling system redesigns. Vendors must substitute alternative working fluids or abandon vapor-compression pre-cooling stages entirely. Japanese university hospitals are piloting the first compliant installations, with PMDA quality audits validating modified thermal management protocols.
Integrated delivery networks in the United States are unbundling equipment procurement from long-term service agreements. IDN supply chain offices now negotiate scanner purchases through group purchasing organizations while contracting regional service providers for maintenance. This bifurcation concentrates in Texas and Florida health systems, where independent imaging centers compete directly for outpatient referrals.
Global Closed MRI Systems Market Segmentation
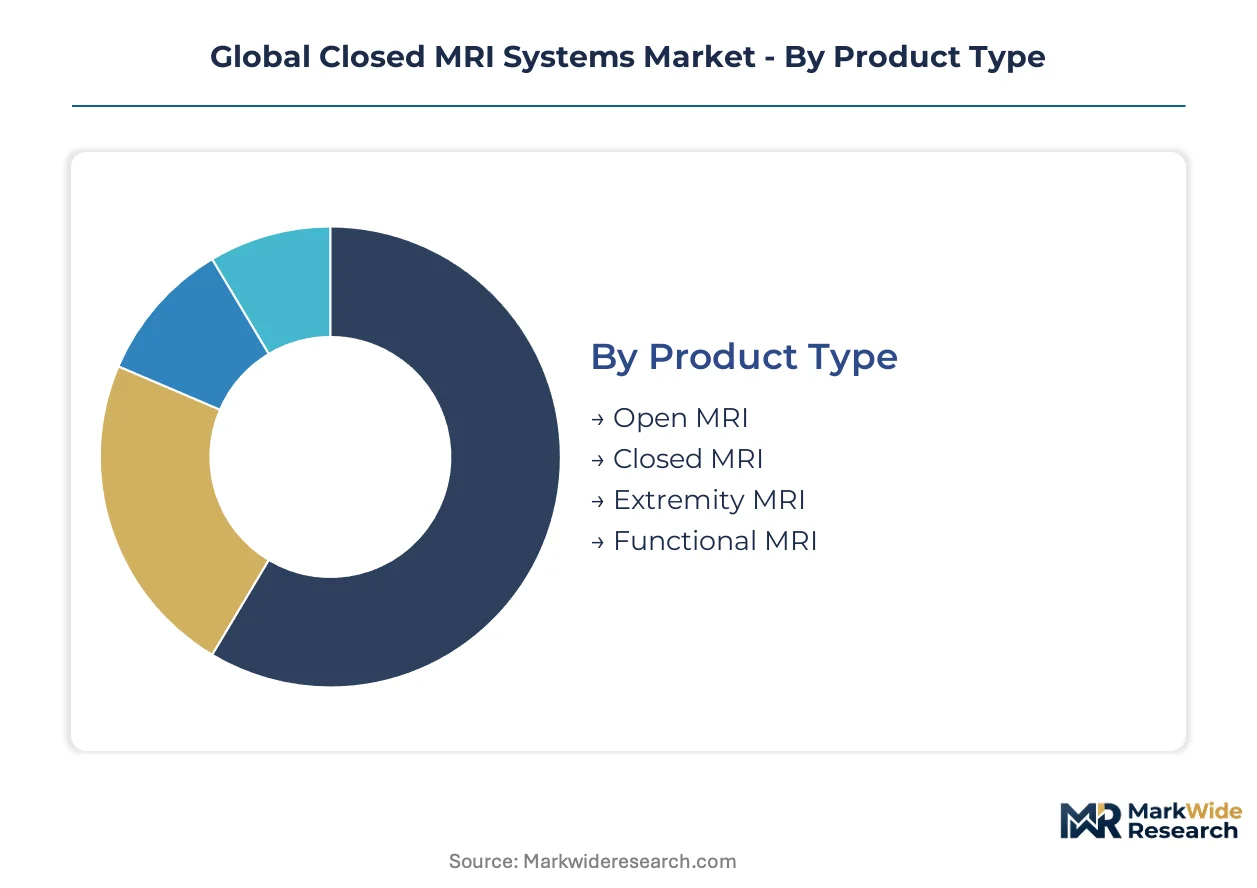
Closed MRI systems fragment across four intersecting dimensions that determine procurement economics and clinical utility. Product architecture dictates siting costs and patient throughput. Magnet technology governs field strength, helium dependency, and service contract structures. End-user concentration shapes financing models and vendor sales cycles.
Product Type:
The use-case spectrum spans full-body diagnostic platforms through specialized extremity scanners, with each configuration optimizing for different patient positioning and anatomical coverage requirements.
- Open MRI:Vertical-field or double-doughnut architectures eliminate cylindrical enclosure, accommodating claustrophobic patients and bariatric cases. Imaging centers in Texas and Florida deploy these systems where outpatient comfort scores drive referral patterns.
- Closed MRI:Cylindrical superconducting bore designs generate 1.5 to 7.0 Tesla fields for high-resolution soft tissue imaging. Academic hospitals in Germany and Japan specify these platforms for advanced neurology and oncology protocols requiring sub-millimeter resolution.
- Extremity MRI:Compact dedicated systems image hands, wrists, feet, and ankles without full-body positioning. Sports medicine clinics in Australia and orthopedics practices in the United Kingdom favor these units for reduced siting footprints and faster patient turnover.
- Functional MRI:Blood-oxygen-level-dependent sequences map neural activation patterns during cognitive tasks. Research institutes at Stanford University and the Max Planck Institute deploy these systems for pre-surgical mapping and psychiatric biomarker studies.
The dominant share belongs to Closed MRI, while Functional MRI is closing the gap fastest as neurosurgical planning protocols expand.
Technology:
Cost tier separation runs from helium-dependent superconducting platforms through maintenance-light permanent magnet designs, with each technology locking in distinct operational expenditure profiles and clinical capabilities.
- Superconducting:Niobium-titanium coils cooled to 4 Kelvin by liquid helium generate fields above 1.5 Tesla. China's NMPA innovation pathway is accelerating approvals for conduction-cooled variants that eliminate helium logistics at Beijing and Shanghai university hospitals.
- Permanent Magnet:Ferrite or rare-earth arrays require no cryogenics and operate at 0.2 to 0.5 Tesla. Clinics in India's tier-2 cities select these systems where capital budgets cannot absorb superconducting infrastructure costs.
- Resistive Magnet:Copper electromagnets with active cooling enable intermediate field strengths without superconducting transition. Veterinary imaging centers in Brazil and small diagnostic chains in Mexico deploy these units for price-sensitive musculoskeletal applications.
- Hybrid MRI:Combined PET-MR or MR-Linac platforms integrate functional imaging with therapeutic delivery. The University of Texas MD Anderson Cancer Center and Heidelberg University Hospital have installed these systems for radiation therapy planning and real-time tumor tracking.
Superconducting platforms command the revenue concentration, though Hybrid MRI is climbing the fastest as precision oncology protocols mature.
End User:
Customer type determines contract structure, with integrated delivery networks negotiating fleet management agreements while independent imaging centers prioritize throughput-based financing.
- Hospitals:Academic medical centers and community hospitals anchor procurement volume through centralized radiology departments. Kaiser Permanente in California and NHS Trusts in England are consolidating scanner purchases through group purchasing organizations.
- Imaging Centers:Independent outpatient facilities compete on appointment availability and patient experience metrics. RadNet and Alliance Healthcare Services in the United States are extending vendor-managed equipment models that transfer ownership risk.
- Clinics:Single-specialty practices and multi-physician groups seek compact systems with minimal siting requirements. Orthopedics clinics in South Korea and cardiology practices in Spain favor permanent magnet or low-field superconducting configurations.
- Research Institutes:University hospitals and government laboratories drive 7.0 Tesla and ultra-high-field adoption. The National Institutes of Health campus in Maryland and RIKEN Brain Science Institute in Japan operate specialized research-dedicated scanners.
Hospitals retain the deepest procurement pool, while Imaging Centers are gaining share fastest as outpatient referral networks fragment.
Application:
Clinical indication determines sequence protocol requirements and reimbursement rates, with neurology and oncology commanding premium field strengths while orthopedics tolerates lower-resolution alternatives.
- Neurology:Brain and spinal cord imaging demands high field homogeneity for detecting demyelinating plaques, tumors, and vascular malformations. The Mayo Clinic in Minnesota and Charité Hospital in Berlin have standardized 3.0 Tesla protocols for multiple sclerosis monitoring.
- Orthopedics:Joint and soft tissue assessment prioritizes anatomical detail over functional sensitivity. Sports medicine facilities in Switzerland and rehabilitation centers in Canada are adopting 1.5 Tesla platforms for ligament and meniscus evaluation.
- Oncology:Tumor staging and treatment response monitoring require contrast-enhanced sequences and diffusion-weighted imaging. Tata Memorial Centre in Mumbai and Gustave Roussy in France have deployed dedicated oncologic MRI suites.
- Cardiovascular:Cardiac MRI competes with CT angiography for coronary and myocardial assessment. Cleveland Clinic and Hamburg University Hospital are expanding stress perfusion and late gadolinium enhancement protocols.
Neurology holds the dominant application share, though Cardiovascular is expanding most quickly as non-invasive cardiac assessment protocols displace diagnostic catheterization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns diverge sharply across geographies. Japanese academic centers prioritize 7.0 Tesla ultra-high-field research systems, while Indian tier-2 cities concentrate demand on mid-field superconducting platforms where infrastructure budgets constrain siting investments.
United States
Integrated delivery networks in Texas and Florida are unbundling equipment procurement from service contracts, negotiating scanner purchases through group purchasing organizations while sourcing regional maintenance providers independently. The FDA's 510(k) software-as-medical-device oversight extends approval timelines for iterative coil updates. Cleveland Clinic and Mayo Clinic anchor demand in the Midwest, deploying 3.0 Tesla platforms for cardiac and neurological protocols.
Germany
University hospitals in Berlin and Heidelberg specify compressed-sense acquisition protocols to maximize outpatient throughput within fixed reimbursement frameworks. The EU's F-Gas Regulation accelerates magnet cooling system redesigns, forcing substitution of hydrofluorocarbon refrigerants. Baden-Württemberg's industrial cluster houses precision engineering suppliers for cryostat subassemblies serving Siemens Healthineers' domestic production.
China
Beijing and Shanghai university hospitals are piloting conduction-cooled helium-free superconducting magnets through the NMPA innovation pathway, eliminating liquid helium dependency. Government health infrastructure investment concentrates procurement in the Yangtze River Delta and Pearl River Delta regions. Domestic manufacturers in Shenzhen and Suzhou are scaling gradient coil subsystem production for mid-field platforms.
Japan
The Ministry of Health projects diagnostic imaging volumes to rise through 2040 as median population age exceeds 48 years. PMDA quality management audits validate modified thermal management protocols for F-Gas-compliant installations. RIKEN Brain Science Institute and University of Tokyo hospitals operate specialized 7.0 Tesla research-dedicated scanners for pre-surgical neural mapping.
India
Government health insurance expansion and private hospital chain consolidation concentrate near-term demand for 1.5 Tesla superconducting systems. CDSCO regulatory pathways for imported coil architectures extend commercialization timelines for multinational vendors. Maharashtra and Karnataka host the deepest procurement pools, with Apollo and Max Healthcare expanding MRI capacity in Mumbai and Bangalore metropolitan corridors.
Global Closed MRI Systems Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three to four global conglomerates with integrated magnet-to-software portfolios, alongside regional specialists and emerging domestic manufacturers in Asia. Two strategic archetypes dominate: full-stack platform vendors controlling cryogenics and coil production, and modular specialists competing on acquisition speed and siting flexibility. Competitive moves concentrate on vertical integration into helium logistics and strategic partnerships for AI reconstruction module integration.
Among German-origin conglomerates, Siemens Healthineers exemplifies the captive-cryogenics archetype, while Koninklijke Philips N.V. anchors the acquisition-speed positioning. GE HealthCare represents the North American full-stack model with integrated service contract structures. These three occupy distinct competitive vectors rather than direct price competition, with Philips compressing scan times through sequence optimization, Siemens protecting margin pools on high-field platforms, and GE anchoring fleet management relationships with integrated delivery networks.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE HealthCare |
| Koninklijke Philips N.V. |
| FUJIFILM Holdings Corporation |
| Canon Medical Systems Corporation |
| Fonar Corporation |
| Esaote S.p.A |
| Shanghai United Imaging Healthcare Co., Ltd |
| Hitachi Medical Systems |
| Others |
Supply Flow & Price Mechanics
Undercapacity in superconducting magnet coil production across Germany and Japan is compressing lead times for 3.0 Tesla platforms and hardening vendor pricing power on high-field systems. This utilization squeeze simultaneously drives hospital buyers toward mid-field alternatives and forces vendors to renegotiate long-term service contract economics.
Pricing Analysis
Long-term fleet management contracts dominate hospital procurement, though spot-market helium pricing increasingly penetrates service agreement renegotiations. Three-tier pricing structure across premium, standard, and economy levels separates 7.0 Tesla research systems from 3.0 Tesla clinical workhorses and 1.5 Tesla mid-field platforms. Price differentiation rests on field strength certification and captive cryogenics integration. Cost compression in the mid-field tier is intensifying because domestic manufacturers in China are scaling gradient coil production. Imaging centers exhibit highest price sensitivity, while academic medical centers prioritize acquisition speed over capital outlay.
Supply Chain Analysis
Export-control regimes limiting superconducting wire and cryocooler technology flows from the United States and Germany are fragmenting magnet assembly sourcing. Supply concentrates in China for rare-earth permanent magnet components, Germany for niobium-titanium superconducting wire, and Japan for cryocooler subsystems. Raw material dependencies span liquid helium from Qatar and Algeria, high-purity copper for gradient coils, and specialized epoxy resins for cryostat insulation. Single-source vulnerability in helium logistics exposes operating expenditure to geopolitical disruption. Distribution runs through direct vendor-hospital contracting augmented by group purchasing organization aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from helium logistics, cryostat maintenance, and software upgrades is expanding faster than hardware sales, reframing vendor economics around recurring income streams rather than capital equipment transactions.
For Market Incumbents: Insulate high-field margin pools by accelerating captive production of conduction-cooled magnet architectures that eliminate helium dependency. Secure backward integration into cryocooler manufacturing before export-control tightening restricts access to Japanese and German suppliers. The FDA's software-as-medical-device oversight extends approval timelines for iterative coil updates, threatening competitive positioning on reconstruction speed. For New Entrants and Emerging Players: Build out extremity MRI and veterinary imaging segments where siting constraints and price sensitivity have kept incumbents from deploying full sales resources. India's tier-2 cities and Brazil's diagnostic chains present the most penetrable white space for mid-field superconducting platforms. A software-first go-to-market emphasizing AI reconstruction modules can bypass capital-intensive magnet manufacturing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors controlling captive helium logistics and long-term service contracts with integrated delivery networks. Long-term viability across the analysis window favors full-stack platform vendors with in-house cryogenics over modular specialists dependent on outsourced magnet supply. The signal to watch is NMPA approval velocity for helium-free conduction-cooled systems in Chinese academic hospitals.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Free Magnet Development | Eliminates liquid helium dependency and quench risks, restructuring service contract economics across installed fleets. |
| AI Reconstruction Module Integration | Enables diagnostic-grade imaging at reduced field strengths, opening veterinary and sports medicine applications. |
| Group Purchasing Organization Partnership | Aggregates hospital procurement volume, compressing vendor margins while securing long-term fleet placement. |
| Conduction-Cooled Cryostat Certification | Satisfies EU F-Gas Regulation phasedown requirements, accelerating magnet cooling system redesigns. |
| Mid-Field Platform Localization | Captures demand from India's hospital infrastructure build-out and China's Yangtze River Delta procurement concentration. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and aftermarket service heads, then refined through secondary validation. Hospital procurement databases, CMS Medicare reimbursement data, FDA 510(k) filings, and EU MDR notified body records anchored quantitative sizing. Bottom-up installed base modeling and top-down vendor revenue triangulation converged on segment-level estimates.
Demand-supply-balance framing structured the forecast framework, with procurement cycle analysis, reimbursement rate trajectories, and regulatory approval velocity as core inputs. Segmentation dimensions spanned product architecture, magnet technology, end-user concentration, and clinical application. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions. Helium spot market volatility and MDR recertification timeline slippage fed scenario-weighted outcomes.
Stress conditions across helium supply disruption severity, FDA software oversight stringency, and Chinese domestic vendor market share capture were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hospital infrastructure investment continuity and sovereign health insurance expansion. Material shifts in export-control regime coverage or alternative cooling technology cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
France Digital Radiology Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Asia-Pacific Nuclear Medicine Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
Portable Ultrasound Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
Medical Radiation Detection Market