
 Cryo-Electron Microscopy Market | 2026-2036
Cryo-Electron Microscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Cryo-Electron Microscopy Market Insights
Software-defined data processing and cloud-based image reconstruction is rebalancing how instrument vendors monetize their installed base. Thermo Fisher Scientific Inc. leverages its Thermo Scientific Tomography software suite to extend recurring revenue beyond hardware placement. JEOL Ltd. anchors its competitive stance through proprietary cold-field emission gun technology that sustains resolution leadership in sub-2 angstrom workflows. Danaher competes by integrating Leica Microsystems cryo-sample preparation with Gatan, Inc. camera systems under a unified service contract model.
Cryo-electron microscopy refers to a structural biology technique where biological specimens are vitrified at cryogenic temperatures and imaged using transmission electron beams, typically operating at 200-300 kV accelerating voltage to preserve native molecular conformations without crystallization. The method enables near-atomic resolution visualization of membrane proteins, viral assemblies, and macromolecular complexes for therapeutic target validation. Cryo-transmission electron microscopy dominates instrument revenue due to its indispensability in resolving de novo protein folds for drug development pipelines, while cryo-scanning electron microscopy occupies a narrower niche in cellular tomography and materials interface studies. Structural biology commands the largest application share, though nanotechnology adoption is accelerating fastest as semiconductor manufacturers adopt cryo-EM for defect characterization at the angstrom scale.
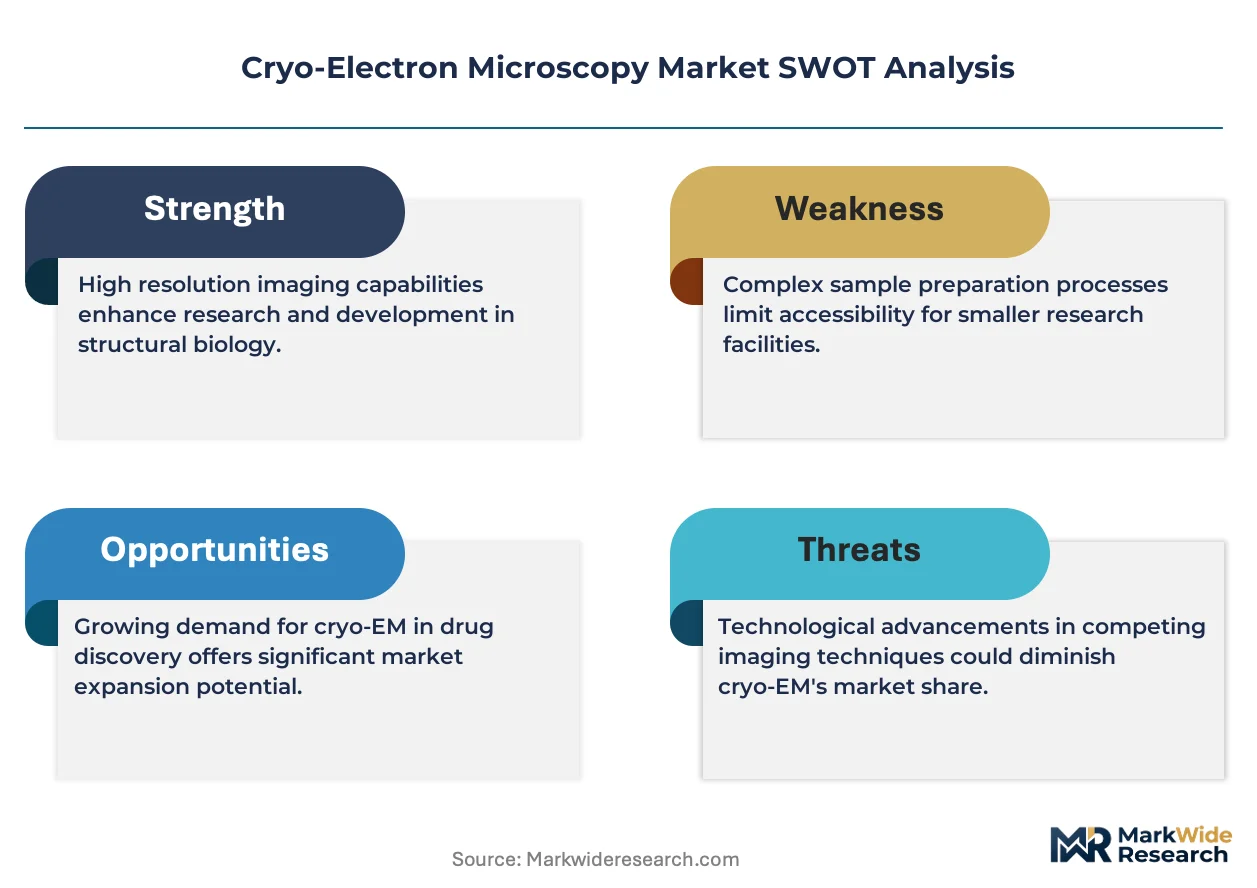
The FDA's structure-based drug design qualification pathway and the EMA's parallel scientific advice on cryo-EM-derived biologic characterization are tightening compliance requirements for pharmaceutical end users, directly shaping instrument validation protocols and data integrity standards. ISO 10993 biocompatibility testing frameworks and NIH shared instrumentation grant programs further regulate how academic and biotechnology firms access and document cryo-EM workflows. Stakeholders must monitor how regulatory convergence between FDA and EMA on molecular structure submission formats reshapes competitive requirements for instrument software validation and data management infrastructure.
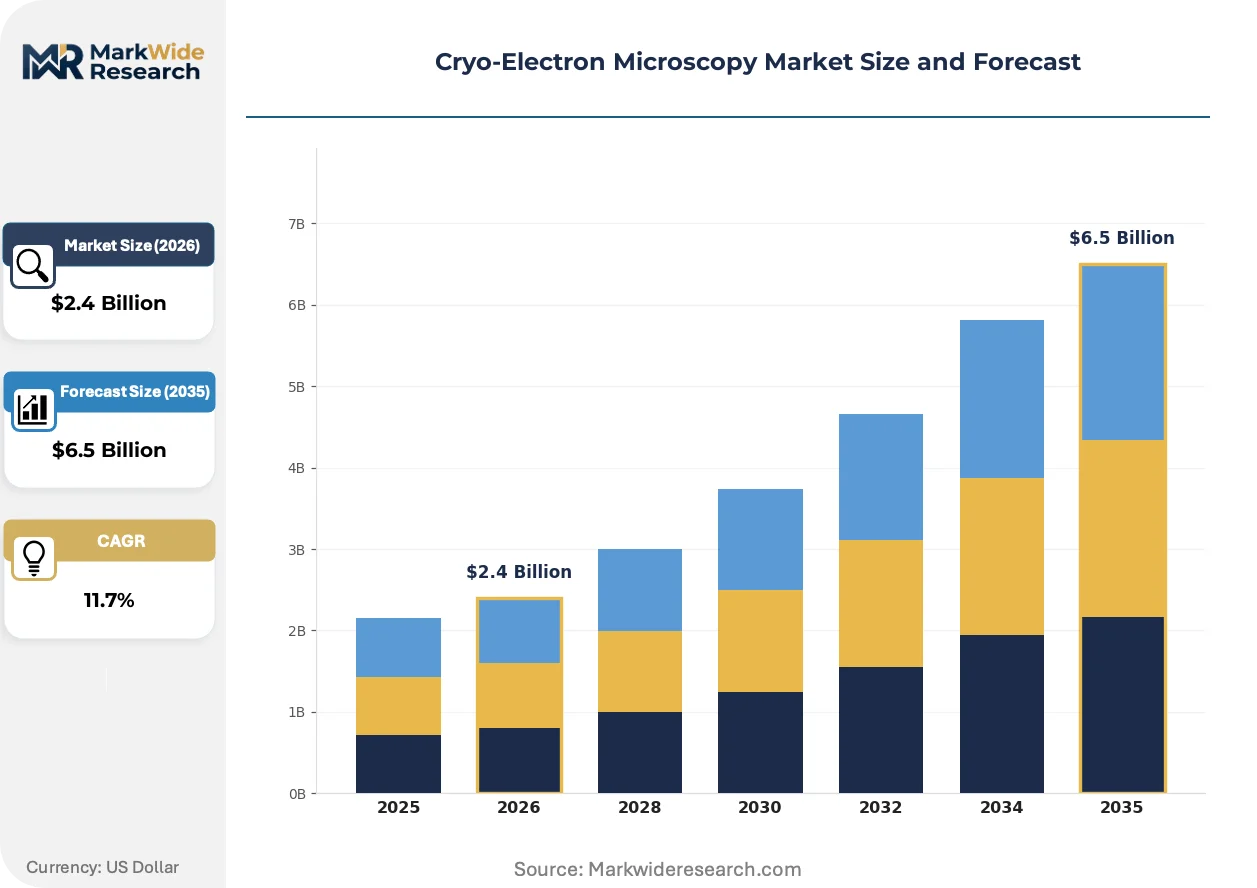
Market Dynamics
Software-defined data processing is modularizing how cryo-EM vendors monetize their installed base, shifting revenue from hardware placement toward recurring software subscriptions and cloud-based image reconstruction services.
Growth Catalysts
- Structure-Based Drug Design Qualification:The FDA's expanding pathway for molecular structure submission accelerates pharmaceutical procurement timelines for high-resolution instruments.
- NIH Shared Instrumentation Grants:Federal funding programs at Stanford, Harvard, and other national centers anchor academic adoption and train specialized operator pipelines.
- Angstrom-Scale Semiconductor Defect Characterization:Chip manufacturers deploy cryo-EM for native-state failure analysis of three-dimensional nanoscale architectures.
Market Restraints
- Liquid Helium Supply Concentration:Qatar and the United States control over 75% of global helium production, exposing cryo-EM facilities to price volatility and export restriction risk.
- Field Emission Gun Technical Limitations:Cold-source stability requirements constrain continuous operation windows and increase maintenance downtime below 2.0 angstrom resolution thresholds.
- EMA Parallel Scientific Advice Complexity:Divergent documentation standards between European and American regulators create redundant validation protocols for multinational biologic submissions.
Strategic Opportunities
- India Biopharma Manufacturing Expansion:CDSCO's accelerated approval pathways for biosimilars create demand for localized cryo-EM infrastructure in Hyderabad and Bangalore clusters.
- AI-Accelerated Image Reconstruction Convergence:Deep learning particle-picking algorithms compress processing timelines from weeks to days, enabling service-based business models.
- Cloud-Based Remote Operation Channels:Distributed access models allow smaller biotechnology firms to rent instrument time at national centers without capital deployment.
Industry Challenges
- Computational Microscopist Talent Scarcity:The intersection of structural biology, physics, and machine learning creates a narrow hiring funnel for qualified image analysis specialists.
- ISO 10993 Biocompatibility Certification Timelines:Extended validation cycles for sample preparation workflows delay instrument commissioning in regulated pharmaceutical environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryo-Electron Microscopy Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryo-Transmission Electron Microscopy, Cryo-Scanning Electron Microscopy, Accessories, Detectors Application: Structural Biology, Material Science, Nanotechnology, Drug Development End User: Research Institutes, Pharmaceutical Companies, Academic Institutions, Biotechnology Firms Delivery Mode: In-house, Contract Research, On-site Services, Remote Access |
| Companies Covered | Thermo Fisher Scientific Inc., JEOL Ltd., Danaher, Olympus Corporation, Leica Microsystems, ZEISS International, Gatan, Inc., Hitachi High-Tech Corporation, Oxford Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryo-Electron Microscopy Market Trends and Innovations
Three forces are actively reshaping competitive positioning in cryo-EM: hardware modularity enabling field upgrades, regulatory convergence on data integrity standards, and procurement fragmentation toward distributed access models.
Direct electron detection hardware is modularizing, allowing laboratories to upgrade camera systems without full instrument replacement. Pharmaceutical quality control departments adopt this path to preserve capital while accessing sub-2 angstrom resolution. The approach compresses vendor replacement cycles and extends service contract durations.
EMA and FDA alignment on cryo-EM-derived biologic characterization formats is tightening data integrity requirements. Instrument software must now embed audit trails and electronic signatures compliant with 21 CFR Part 11. European biotechnology firms face the steepest compliance curve as they retrofit legacy installations.
Facility access models are fragmenting traditional capital procurement patterns. Smaller drug discovery firms now prioritize time-reserved contracts at national centers over instrument ownership. This behavioral shift concentrates most visible in the United States, where NIH-funded regional hubs in Massachusetts and California absorb unmet demand from undercapitalized entrants.
Cryo-Electron Microscopy Market Segmentation
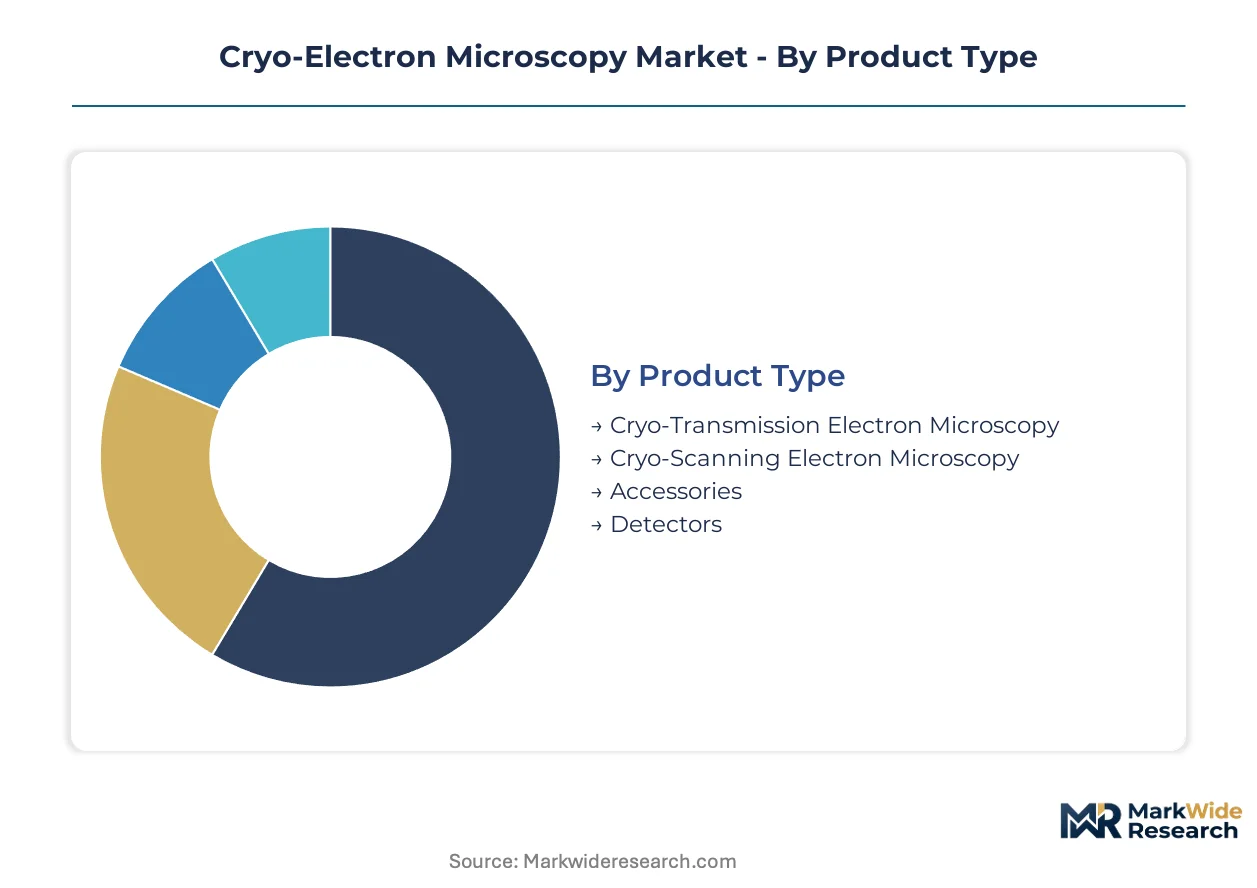
Cryo-EM procurement patterns diverge sharply between capital-intensive instrument ownership and distributed access models. Understanding these splits reveals where vendor monetization strategies concentrate versus where service-based disruption is penetrating.
Product Type:
Standalone instruments dominate facility footprints while embedded detection systems enable modular upgrade paths that extend instrument lifecycles.
- Cryo-Transmission Electron Microscopy:These 200-300 kV instruments embed direct electron detectors and cold-field emission guns for sub-2 angstrom resolution workflows. Demand clusters at NIH-funded national centers in Stanford and Harvard where pharmaceutical structural biology programs anchor procurement.
- Cryo-Scanning Electron Microscopy:Lower-resolution systems optimized for cellular tomography and materials interface characterization occupy narrower niches. Semiconductor manufacturers in the United States deploy these for native-state defect analysis of three-dimensional nanoscale architectures.
- Accessories:Vitrification robots, sample preparation stations, and cryo-transfer systems extend instrument functionality.
- Detectors:Direct electron detection hardware modularizes field upgrades without full instrument replacement.
Volume placements concentrate in Cryo-Transmission Electron Microscopy; the faster expansion belongs to Detectors as pharmaceutical quality control departments prioritize modular upgrade paths.
Application:
Cost tier stratification separates high-budget therapeutic discovery from lower-budget academic characterization workflows.
- Structural Biology:Near-atomic resolution visualization of membrane proteins and macromolecular complexes for therapeutic target validation commands the largest budget allocation. FDA structure-based drug design qualification pathways tighten data integrity requirements for submissions.
- Drug Development:Antibody and vaccine programs leverage cryo-EM for de novo protein fold resolution, with procurement timelines accelerating under regulatory pressure. EMA parallel scientific advice creates redundant validation protocols for multinational biologic submissions.
- Material Science:Native-state failure analysis supports semiconductor process development with narrower resolution requirements.
- Nanotechnology:Angstrom-scale defect characterization for chip manufacturing represents the steepest expansion trajectory as process nodes shrink.
Budget concentration sits with Structural Biology; Nanotechnology climbs the fastest as semiconductor manufacturers internalize cryo-EM capabilities.
End User:
Customer type determines procurement mode—capital ownership versus time-reserved access contracts.
- Pharmaceutical Companies:These entities now rank among the fastest-growing end users as cryo-EM resolves protein structures for antibody and vaccine programs. The FDA's expanding qualification pathway accelerates instrument procurement timelines and tightens software validation requirements.
- Biotechnology Firms:Smaller drug discovery operations prioritize time-reserved contracts at national centers over instrument ownership, fragmenting traditional capital procurement patterns.
- Research Institutes:NIH shared instrumentation grant programs anchor academic adoption and train specialized operator pipelines.
- Academic Institutions:University laboratories access cryo-EM through regional hub networks rather than standalone installation.
Instrument ownership concentrates in Pharmaceutical Companies; Biotechnology Firms gain share fastest through distributed access models.
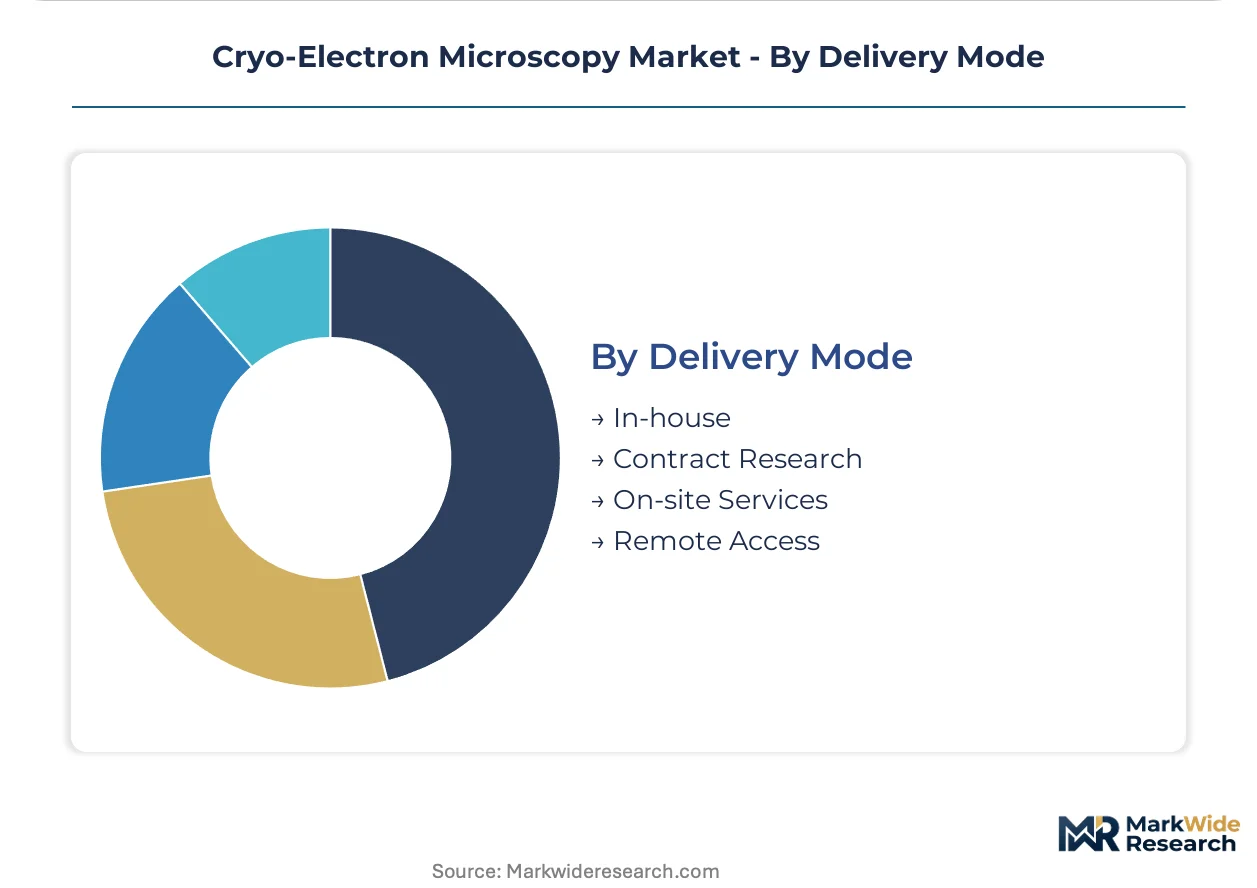
Delivery Mode:
Maturity stratification separates established in-house operations from emerging remote and service-based alternatives.
- In-house:Full instrument ownership with dedicated technical staff remains the dominant configuration for high-throughput pharmaceutical operations requiring continuous access and proprietary workflow control.
- Contract Research:Outsourced sample analysis and data processing enables smaller entities to access cryo-EM capabilities without capital deployment or specialized staffing.
- On-site Services:Vendor technical personnel embed at client facilities for installation, maintenance, and training support.
- Remote Access:Cloud-based instrument control and data reconstruction services allow distributed operation of national center equipment.
Service revenue concentrates in In-house support contracts; Remote Access expands most quickly as AI-accelerated image reconstruction compresses processing timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors global cryo-EM infrastructure density, with MIT and Harvard hosting NIH-funded national centers that train specialized operators and absorb demand from undercapitalized biotechnology entrants across the eastern United States.
United States
Pharmaceutical structural biology programs at Stanford and Harvard drive instrument procurement, while the FDA's structure-based drug design qualification pathway tightens software validation timelines. NIH shared instrumentation grants sustain academic adoption clusters in California and Massachusetts. Cloud-based remote access models at these national centers allow smaller drug discovery firms to rent instrument time without capital deployment.
Germany
Max Planck Institute installations and pharmaceutical quality control departments prioritize modular detector upgrades over full instrument replacement. EMA parallel scientific advice on cryo-EM-derived biologic characterization creates redundant validation protocols for multinational submissions. The Heidelberg and Munich metropolitan areas concentrate service contract demand for integrated sample preparation and camera systems.
China
Domestic semiconductor manufacturers deploy cryo-EM for angstrom-scale defect characterization as process nodes shrink below 7 nanometers. NMPA expanding qualification pathways for structure-based drug design accelerates procurement timelines for high-resolution instruments. Beijing and Shanghai anchor regional adoption through national laboratory networks and biopharma manufacturing expansion.
United Kingdom
Structural biology research councils fund cryo-EM facility access for university laboratories lacking standalone installation capital. MHRA alignment with FDA data integrity standards pressures instrument software vendors to embed 21 CFR Part 11 compliant audit trails. The Cambridge-Oxford-London triangle concentrates demand from antibody and vaccine development programs.
India
CDSCO accelerated approval pathways for biosimilars create demand for localized cryo-EM infrastructure in Hyderabad and Bangalore manufacturing clusters. Contract research organizations expand service-based access models to serve undercapitalized domestic biotechnology entrants. IIT Bombay and IISc Bangalore anchor academic operator training pipelines through shared instrumentation programs.
Cryo-Electron Microscopy Market Competitive Landscape
Capital-heavy instrument manufacturers compete with asset-light software and service providers for recurring revenue beyond hardware placement. The vendor base stratifies across three tiers: integrated platform specialists controlling full workflow stacks, modular component suppliers enabling field upgrades, and cloud-based service operators monetizing remote access. Thermo Fisher Scientific Inc. exemplifies the integrated archetype through unified hardware-software-service contracts. Danaher occupies a hybrid position linking sample preparation with detection hardware under single service agreements. JEOL Ltd. anchors the precision-engineering tier through proprietary cold-field emission gun technology. Consolidation pressure intensifies as pharmaceutical procurement timelines compress and regulatory validation requirements tighten.
Among integrated platform specialists, Thermo Fisher Scientific Inc. and Danaher represent the dominant configuration for high-throughput pharmaceutical operations requiring continuous access and proprietary workflow control. JEOL Ltd. sits within the precision-engineering tier where resolution leadership below 2.0 angstroms commands premium positioning. These three companies illustrate how competitive positioning diverges between full-stack integration and specialized component excellence.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| JEOL Ltd. |
| Danaher |
| Olympus Corporation |
| Leica Microsystems |
| ZEISS International |
| Gatan, Inc. |
| Hitachi High-Tech Corporation |
| Oxford Instruments |
| Others |
Pricing and Supply Chain Analysis
Liquid helium feedstock costs cascade through instrument manufacturing tiers, with Qatar and United States production concentration compressing margins for sub-2 angstrom resolution systems while pharmaceutical buyers absorb premium pricing for FDA-qualified workflows.
Pricing Analysis
Resolution-guarantee contracts anchor value-based pricing for pharmaceutical quality control departments, with throughput commitments and uptime SLAs differentiating premium tiers from standard service bundles. Price differentiation separates FDA-validated software suites from academic-grade configurations, with helium supply volatility intensifying cost compression in detector upgrade paths. Biotechnology firms exhibit highest price sensitivity, prioritizing time-reserved access contracts over capital deployment.
Supply Chain Analysis
Specialized cryogenic engineer availability constrains manufacturing scale-up in Massachusetts and California instrument assembly clusters. Cold-field emission gun fabrication draws from Japanese precision machining and German vacuum technology suppliers, with single-source vulnerability in direct electron detector sensor arrays. Distribution runs through vendor-embedded service personnel at pharmaceutical client sites rather than third-party logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA structure-based drug design qualification creates a compliance moat where 21 CFR Part 11 software validation investments separate viable vendors from displaced legacy installations.
For Market Incumbents: Deploy helium recovery system backward integration to neutralize feedstock volatility exposure from Qatar supply concentration. Consolidate service contract density around NIH-funded national centers before cloud-based remote access models commoditize instrument ownership economics. For New Entrants and Emerging Players: Undercapitalized biotechnology firms in Hyderabad and Bangalore clusters represent the most penetrable buyer archetype, with CDSCO accelerated biosimilar pathways creating localized infrastructure demand. Pursue detector-only upgrade paths rather than full instrument competition against integrated platform specialists. For Investors and Strategic Acquirers: Distressed-cycle entries favor AI-accelerated image reconstruction software specialists in United States and Germany geographies where computational microscopist talent scarcity sustains premium valuations. Monitor EMA-FDA regulatory convergence timelines as inflection signal for validation service provider consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery System Integration | Captive supply of liquid helium insulates margins from Qatar export restriction volatility. |
| AI-Accelerated Image Reconstruction Platform | Deep learning particle-picking compresses processing timelines from weeks to days for service models. |
| 21 CFR Part 11 Software Validation Suite | FDA-compliant audit trails embed switching costs for pharmaceutical quality control departments. |
| Cloud-Based Remote Access Infrastructure | NIH-funded national centers absorb undercapitalized biotechnology firm demand without instrument ownership. |
| Cryo-Sample Preparation Automation | Vitrification robot integration with Leica Microsystems workflows tightens vendor service contract renewal rates. |
Research Methodology
Independent corroboration across cryo-EM facility directors, pharmaceutical structural biology program leads, and semiconductor process engineers underwrites the qualitative findings. Primary interviews with NIH shared instrumentation grant administrators, EMA parallel scientific advice recipients, and CDSCO biosimilar approval specialists combined with secondary validation from FDA structure-based drug design pathway documentation, ISO 10993 biocompatibility framework updates, and helium supply trade data. Bottom-up instrument placement counts and top-down pharmaceutical R&D expenditure patterns triangulate market sizing.
Comparable-period anchoring to NIH funding cycle windows and FDA qualification pathway expansion phases structured the projection horizon. Segmentation modeling spanned product type, application, end user, and delivery mode dimensions, with regulatory cluster geography and resolution tier performance specifications as industry-specific variables. CAGRs derived from instrument procurement timeline compression rates and software subscription revenue mix shifts, incorporating helium price volatility scenarios and AI-accelerated image reconstruction adoption curves as forecast inputs.
Revisions become necessary when FDA-EMA regulatory divergence intensifies, helium supply export restrictions materialize, or cold-field emission gun technical limitations stall sub-2 angstrom resolution workflows. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
Radiology Services Market
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
Europe Intraoperative Imaging Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
Middle East and Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market