
 Canada Digital Radiology Market | 2026-2036
Canada Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Digital Radiology Market Insights
The Medical Devices Directorate is restructuring cost-of-entry calculus for foreign and domestic manufacturers seeking Canadian market authorization. GE Healthcare leverages its established service infrastructure to sustain long-term hospital contracts across provincial health systems. Siemens Healthineers anchors its position through R&D intensity in detector technology and AI-embedded workflow platforms. Fujifilm Holdings Corporation differentiates via specialized digital X-ray portfolios optimized for high-throughput diagnostic clinics.
Canada digital radiology encompasses computed radiography and direct digital radiography systems utilizing flat-panel detectors with cesium iodide or amorphous silicon layers to capture and convert X-ray photons into electronic images for diagnostic interpretation, replacing film-based workflows with immediate image availability and dose optimization algorithms. CT scanners dominate capital expenditure allocations among hospitals seeking trauma and oncology diagnostic capacity, while AI integration represents the fastest-expanding technology dimension as radiology departments prioritize automated lesion detection and workflow triage. Cloud storage adoption remains concentrated in multi-site hospital networks requiring centralized image archiving and remote consultation capabilities.
Health Canada, the Canadian Standards Association, and provincial health technology assessment bodies collectively shape equipment procurement through safety certification, reimbursement eligibility, and evidence-based technology adoption frameworks. Health Canada's radiation-emitting devices regulations mandate specific performance and safety standards that filter market access for non-compliant suppliers. Stakeholders must monitor evolving provincial funding mechanisms and interoperability mandates as determinants of replacement cycle timing and vendor selection criteria.
Market Dynamics
Health Canada's Medical Devices Directorate licensing requirements are forcing equipment vendors to accelerate compliance investments, restructuring capital allocation across Ontario's hospital networks as they replace aging analog infrastructure.
Growth Catalysts
- Provincial Procurement Mandates:Ontario's hospital networks are expanding digital imaging procurement to replace aging analog systems, creating sustained equipment demand across acute-care centers.
- Detector Technology Advancement:Flat-panel detectors with cesium iodide layers are capturing X-ray photons with superior efficiency, enabling immediate image availability and dose optimization algorithms.
- AI-Embedded Workflow Platforms:Radiology departments are prioritizing automated lesion detection and workflow triage, compressing diagnostic timelines and reducing radiologist reading burden.
Market Restraints
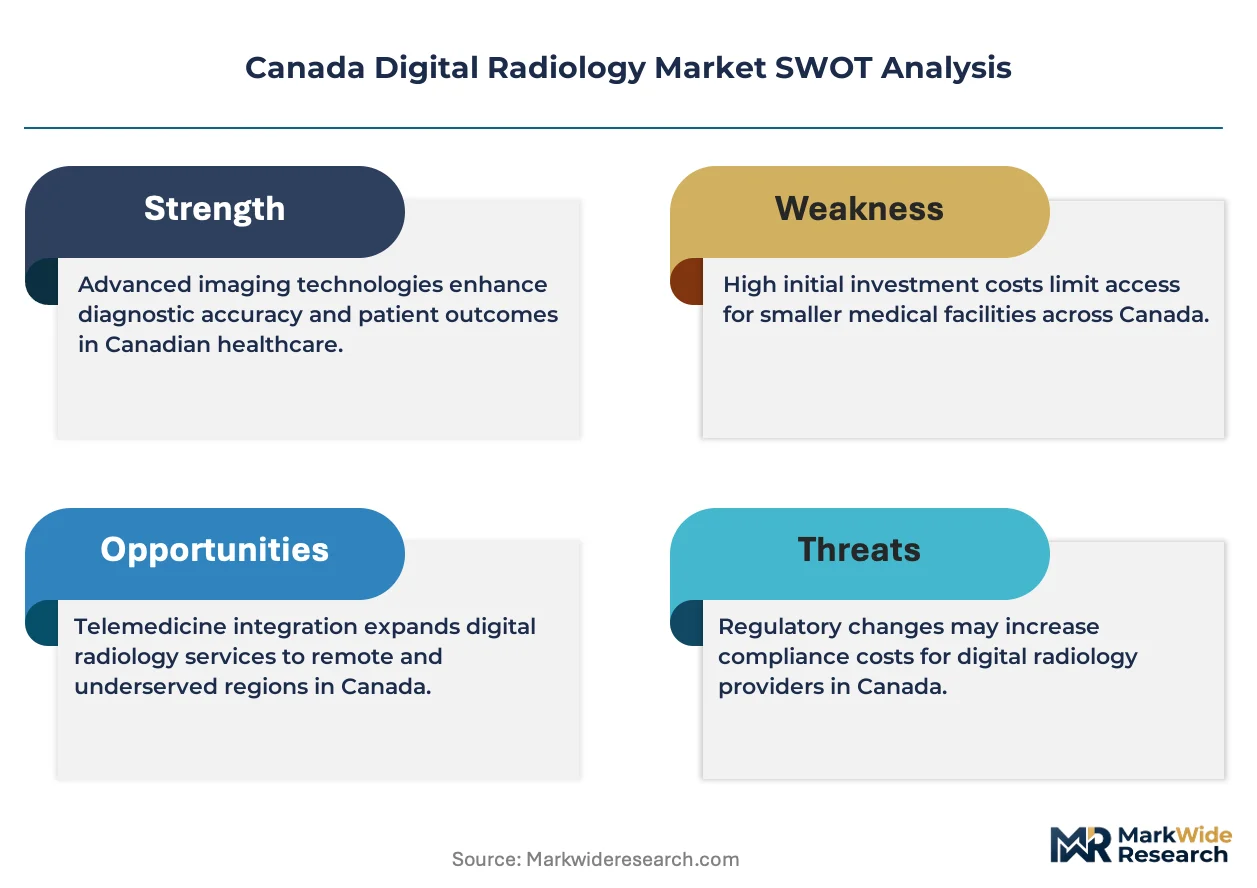
- Capital Expenditure Intensity:CT scanners dominate hospital capital allocation, squeezing available budgets for complementary digital radiography system upgrades.
- Compliance Cost Burden:Health Canada's radiation-emitting devices regulations mandate specific performance standards that filter market access for smaller non-compliant suppliers.
- Technical Integration Complexity:Cloud storage adoption requires centralized image archiving infrastructure that many standalone diagnostic clinics lack capital to deploy.
Strategic Opportunities
- Multi-Site Network Expansion:Cloud storage adoption remains concentrated in urban hospital networks, creating white space for centralized archiving solutions in regional health authorities.
- Diagnostic Clinic Specialization:High-throughput diagnostic clinics represent an underpenetrated segment optimized for specialized digital X-ray portfolios with rapid patient turnover.
- Interoperability Mandates:Evolving provincial interoperability requirements are creating procurement windows for vendors with integrated PACS connectivity and remote consultation capabilities.
Industry Challenges
- Radiologist Workforce Constraints:Automated lesion detection deployment requires specialized AI-interpretation skills that existing radiology departments struggle to source.
- Legacy System Integration:Film-based workflow replacement demands extensive staff retraining and temporary productivity disruption during digital transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Digital Radiology Market |
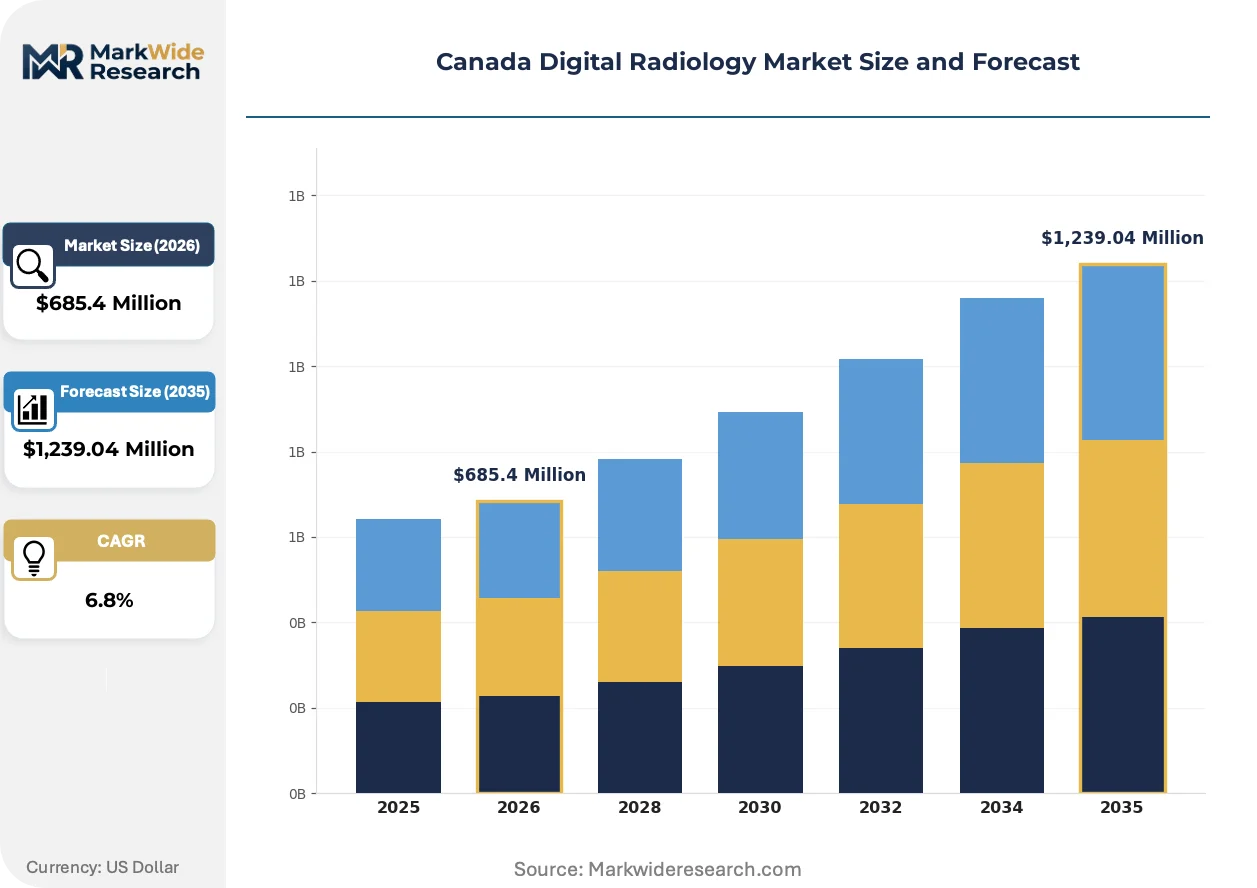
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, Ultrasound, MRI, CT Scanners Technology: Digital Imaging, Cloud Storage, AI Integration, Mobile Imaging Application: Diagnostic Imaging, Therapeutic Applications, Research Studies, Patient Monitoring End User: Hospitals, Diagnostic Clinics, Radiology Centers, Research Institutions |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Carestream Health, Mindray Medical International, Shimadzu Corp, Agfa-Gevaert Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Digital Radiology Market Trends and Innovations
Artificial intelligence integration is compressing diagnostic timelines across Canadian radiology departments, unifying image acquisition with automated interpretation workflows.
Detector technology is unifying image capture and conversion processes through flat-panel systems utilizing amorphous silicon layers. Urban acute-care centers in Toronto and Vancouver are adopting these systems at accelerated replacement cycles. This convergence is compressing vendor selection criteria toward integrated hardware-software platforms.
Health Canada's Medical Devices Directorate is tightening radiation-emitting device performance standards. Equipment vendors are redirecting R&D resources toward compliance documentation and safety certification processes. CT scanner manufacturers face the steepest compliance burden due to higher radiation emission profiles.
Hospital procurement patterns are consolidating vendor relationships around long-term service contracts. Ontario's provincial health systems are displacing transactional equipment purchases with multi-year managed service agreements. This shift is most visible in Toronto's hospital networks seeking predictable operational expenditure structures.
Canada Digital Radiology Market Segmentation
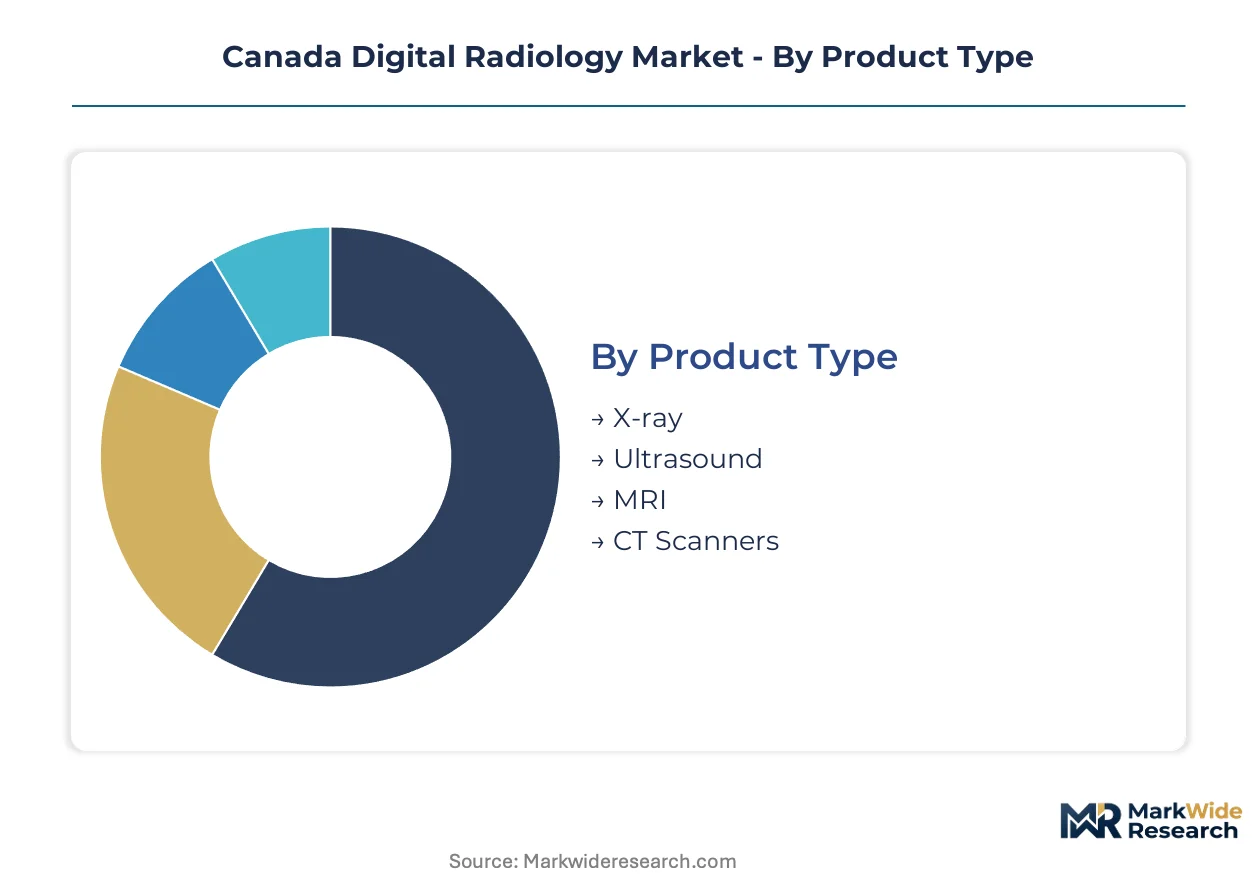
Canada's digital radiology market fragments across equipment modality, deployment architecture, clinical use case, and care setting. Each dimension carries distinct procurement rhythms and regulatory exposure under Health Canada's Medical Devices Directorate.
Product Type:
CT scanners command premium capital allocations while X-ray systems deliver volume throughput across Ontario's hospital replacement cycles.
- CT Scanners:These systems deploy rotating X-ray tubes and detector arrays to generate cross-sectional anatomical reconstructions. Toronto's trauma centers and Vancouver's oncology hubs prioritize 256-slice configurations for cardiac and perfusion imaging, though capital intensity limits replacement frequency to eight-to-ten-year cycles.
- X-ray:Fixed and portable digital radiography units utilize flat-panel detectors with cesium iodide scintillators for immediate image capture. Montreal's acute-care networks and Calgary's emergency departments are standardizing on wireless detector plates to accelerate bedside imaging workflows.
- MRI:Superconducting magnet systems with 1.5T and 3T field strengths enable soft-tissue visualization without ionizing radiation.
- Ultrasound:Piezoelectric transducer arrays generate real-time anatomical imaging through acoustic wave reflection.
Mature deployment sits with X-ray systems across Quebec's community hospitals. Newer deployment is concentrated in CT scanners at Ontario's regional trauma centers.
Technology:
Cloud infrastructure and embedded intelligence are displacing standalone acquisition hardware as the primary value determinant in vendor selection.
- AI Integration:Machine learning algorithms automate lesion detection, organ segmentation, and workflow triage. Vancouver General Hospital and Sunnybrook Health Sciences Centre have deployed FDA-cleared and Health Canada-authorized tools for pulmonary nodule and intracranial hemorrhage screening.
- Digital Imaging:Direct radiography with amorphous silicon flat-panel detectors replaces computed radiography cassette workflows. Alberta Health Services has accelerated province-wide DR conversion to eliminate phosphor plate processing delays.
- Cloud Storage:Vendor-neutral archive architectures enable multi-site image sharing across provincial health networks.
- Mobile Imaging:Self-contained radiography and CT units deploy to remote communities and emergency surge scenarios.
Digital imaging foundations anchor established procurement. AI integration is climbing the fastest as radiology departments confront workforce constraints.
Application:
Diagnostic volume dominates equipment utilization while therapeutic guidance commands specialized configuration premiums.
- Diagnostic Imaging:Anatomical visualization for disease detection and treatment planning consumes the majority of scanner operating hours. Ontario's centralized referral patterns concentrate high-complexity cases at Toronto's academic medical centers.
- Patient Monitoring:Serial imaging tracks treatment response and disease progression in oncology and critical care settings. BC Cancer and Princess Margaret Cancer Centre have integrated imaging biomarkers into clinical trial protocols.
- Therapeutic Applications:Image-guided intervention supports biopsy, ablation, and radiation therapy delivery.
- Research Studies:Quantitative imaging biomarkers enable multi-center clinical trials and population health studies.
Diagnostic imaging absorbs mature infrastructure capacity. Patient monitoring is gaining share fastest as value-based care models emphasize treatment response verification.
End User:
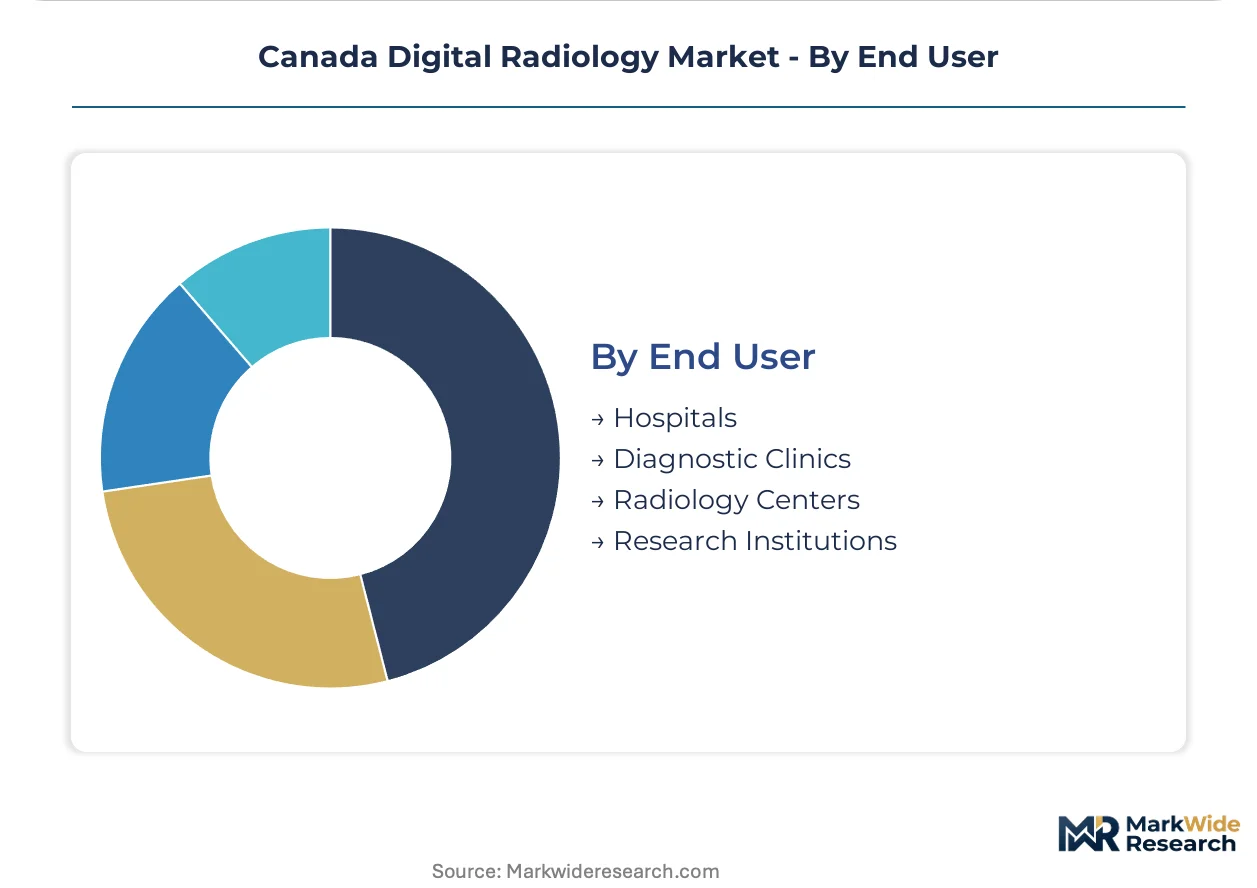
Hospital networks consolidate purchasing power while diagnostic clinics fragment across independent operator models.
- Hospitals:Acute-care institutions with emergency departments, surgical services, and intensive care units require 24/7 imaging availability. Ontario's fourteen Local Health Integration Networks coordinate centralized procurement for 141 hospital corporations.
- Diagnostic Clinics:Outpatient-focused facilities perform high-throughput elective imaging with rapid turnaround requirements. CCL Medical Imaging and Canada Diagnostic Centres operate multi-site networks across Toronto, Vancouver, and Calgary.
- Radiology Centers:Subspecialty-focused practices concentrate advanced interpretation expertise in neuroradiology, musculoskeletal, and interventional disciplines.
- Research Institutions:Academic medical centers and contract research organizations deploy imaging for protocol development and regulatory submission support.
Hospital networks represent mature procurement relationships with established service contracts. Diagnostic clinics present the steepest expansion trajectory as provincial governments license independent health facilities to reduce emergency department imaging backlogs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's hospital procurement zones concentrate equipment demand through the Local Health Integration Networks, channeling capital toward digital imaging replacement cycles.
Ontario
Toronto's academic medical centers drive CT scanner procurement for trauma and oncology capacity, while Hamilton and Ottawa hospital networks expand flat-panel detector deployment. Health Canada's Medical Devices Directorate licensing requirements filter vendor participation in provincial tenders. The Greater Toronto Area anchors replacement demand as fourteen Local Health Integration Networks coordinate centralized purchasing for 141 hospital corporations.
Quebec
Montreal's acute-care networks standardize on wireless digital radiography for emergency department throughput, with Quebec City hospitals following suit in detector technology procurement. The province's health technology assessment frameworks shape reimbursement eligibility for equipment vendors. McGill University Health Centre and CHUM drive adoption concentration in Montreal's hospital corridor.
British Columbia
Vancouver General Hospital and BC Cancer deploy AI-embedded imaging for pulmonary nodule screening and treatment response monitoring. Vancouver Coastal Health and Fraser Health authorities coordinate multi-site cloud archiving infrastructure. The Lower Mainland concentrates procurement authority for province-wide digital radiology standardization.
Alberta
Calgary's emergency departments accelerate wireless detector plate adoption for bedside imaging workflows, while Edmonton hospitals prioritize CT capacity for trauma networks. Alberta Health Services drives province-wide direct radiography conversion to eliminate phosphor plate processing delays. The Calgary-Edmonton corridor channels equipment demand through centralized provincial procurement.
Atlantic Canada
Halifax's Queen Elizabeth II Health Sciences Centre anchors imaging capacity for Maritime provinces, with Saint John and Moncton hospitals dependent on regional referral patterns. Atlantic Canada Opportunities Agency infrastructure programs support diagnostic clinic expansion in underserved markets. The Halifax hub concentrates specialized interpretation expertise for Maritime patient populations.
Canada Digital Radiology Market Competitive Landscape
North American service infrastructure anchors one tier; European detector specialists hold technology leadership positions. The vendor base consolidates around long-term managed service agreements rather than transactional equipment sales. Three archetypes dominate: diversified conglomerates with hospital system relationships, pure-play imaging technology developers, and regional service integrators. Strategic moves center on multi-year contract consolidation and AI-embedded workflow platform differentiation.
Within the diversified conglomerate tier, GE Healthcare and Siemens Healthineers exemplify vendors leveraging established provincial health system relationships. Fujifilm Holdings Corporation occupies a position among specialized digital X-ray portfolio developers optimized for high-throughput clinic segments. These three represent distinct competitive positioning vectors across Ontario's procurement cycles.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Carestream Health |
| Mindray Medical International |
| Shimadzu Corp |
| Agfa-Gevaert Group |
| Others |
Pricing and Supply Chain Analysis
Provincial health system consolidation through Ontario's Local Health Integration Networks concentrates buyer power and compresses vendor margins, while sovereign-backed hospital financing through Canada Infrastructure Bank programs sustains equipment procurement volumes despite capital expenditure pressures. This ownership pattern enforces multi-year managed service agreements that displace transactional sales and anchor pricing discipline across detector technology and AI-embedded platform tiers.
Pricing Analysis
Short lead-time premiums apply to wireless flat-panel detector plates and AI-embedded workflow modules needed for emergency department replacement cycles, while spot inventory discounts emerge for end-of-lifecycle CT gantries and computed radiography cassettes. Three-tier pricing structure across premium, standard, and economy levels separates 256-slice CT configurations with embedded lesion detection algorithms from 128-slice trauma systems and refurbished analog-to-digital conversion kits. Price differentiation rests on Health Canada Medical Devices Directorate licensing status and ISO 13485 certification tier. Pricing pressure stems from Alberta Health Services' province-wide direct radiography conversion mandates squeezing detector plate margins. Community diagnostic clinics exhibit highest price sensitivity due to independent operator financing constraints, while Toronto's academic medical centers prioritize integrated PACS connectivity over unit cost.
Supply Chain Analysis
Specialized electronics manufacturing workforce availability in Japan, Germany, and the United States constrains amorphous silicon flat-panel detector production capacity for Canadian hospital procurement cycles. Cesium iodide scintillator crystals draw from Japanese and Belgian specialty chemical suppliers, while superconducting magnet wire for MRI systems sources from European precision metalwork clusters. Single-source vulnerability concentrates in AI algorithm training data partnerships with limited Health Canada-authorized vendors. Distribution runs through provincial health authority tender processes and group purchasing organizations rather than direct manufacturer-to-hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's Medical Devices Directorate radiation-emitting device regulations erect a compliance barrier-to-entry moat that rewards vendors with established licensing documentation and punishes capital-constrained challengers, consolidating procurement access around incumbent service infrastructure.
For Market Incumbents: Lock in long-term managed service agreements across Ontario's fourteen Local Health Integration Networks before provincial interoperability mandates consolidate vendor selection criteria. Expand detector technology R&D partnerships with McGill University Health Centre and Sunnybrook Health Sciences Centre to anchor AI-embedded workflow platform differentiation. Counter emerging pure-play AI software entrants by bundling hardware refresh cycles with automated lesion detection licensing.
For New Entrants and Emerging Players: Health Canada's Medical Devices Directorate licensing requirements in Canada open a window for regulatory-affairs-specialized entrants offering compliance-documentation-as-a-service to smaller diagnostic clinic operators. Target Atlantic Canada's underserved Maritime provinces where Halifax's Queen Elizabeth II Health Sciences Centre concentrates interpretation expertise and regional referral patterns create equipment leasing demand. Pursue mobile imaging unit deployment partnerships with Alberta Health Services for remote community surge capacity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional service integrators with established Health Canada quality system documentation in Quebec and British Columbia hospital corridors. Long-term viability hinges on AI-embedded platform recurring revenue streams displacing capital-intensive hardware transaction cycles. Watch provincial cloud archiving infrastructure procurement announcements as inflection indicators for multi-site network expansion trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Licensing Pathway Investment | Medical Devices Directorate authorization accelerates hospital procurement access across Ontario LHIN tenders. |
| AI-Embedded Workflow Platform Development | Automated lesion detection algorithms reduce radiologist reading burden at Vancouver General Hospital. |
| Provincial Cloud Archiving Partnership | Vendor-neutral archive infrastructure enables multi-site image sharing for British Columbia health authorities. |
| Wireless Detector Plate Product Launch | Bedside imaging workflow acceleration targets Montreal emergency department replacement cycles. |
| Diagnostic Clinic Network Acquisition | High-throughput outpatient imaging capacity addresses Ontario emergency department backlog reduction mandates. |
Research Methodology
Independent corroboration across hospital procurement committee interviews, biomedical engineering directors, and GPO contracts managers underwrites the qualitative findings in this study. Primary fieldwork with radiology department heads at Toronto's academic medical centers and Vancouver's oncology hubs combined with secondary validation from Health Canada Medical Devices Directorate licensing databases, provincial tender documentation, and hospital capital expenditure disclosures. Bottom-up equipment shipment analysis and top-down health system budget allocation triangulation anchored market sizing across detector technology and AI-embedded platform segments.
Comparable-period anchoring tied projection assumptions to historical replacement cycle timing observed through Ontario's analog-to-digital conversion waves and Alberta's phosphor plate elimination mandates. The analytical framework modeled equipment modality, deployment architecture, clinical use case, and care setting dimensions throughout the forecast period. CAGRs derived from provincial health authority capital plan trajectories and vendor service contract renewal rates, with AI integration adoption curves and cloud storage infrastructure buildout schedules as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for AI-embedded lesion detection would alter the outlook if Health Canada authorization timelines extend or radiologist workforce constraints accelerate automated interpretation deployment. Forecasts reflect assumptions regarding provincial interoperability mandate timing and diagnostic clinic licensing expansion rates. Material deviation in Health Canada regulatory enforcement intensity or Canada Infrastructure Bank hospital financing program scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Closed MRI Systems Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
UK Digital Radiology Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
UK Imaging Services Market
Medical Imaging
Contrast Media Market
Medical Imaging
PSMA-PET Imaging Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
US Medical Imaging Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Italy Mammography Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
Next Generation Ultrasound Systems Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market