
 North America Open System MRI Market | 2026-2036
North America Open System MRI Market Size, Share, and Industry Trends Forecast 2026-2036
North America Open System MRI Market Analytics
Canadian component suppliers is realigning magnet coil sourcing toward domestic rare-earth processing partnerships. Siemens Healthineers leverages its established installed base in academic medical centers to sustain service contract renewal rates. GE Healthcare anchors its competitive stance through proprietary superconducting wire manufacturing that reduces helium dependency. Koninklijke Philips N.V. differentiates via integrated diagnostic workflow software that connects open MRI scanners to enterprise imaging archives.
Open system MRI denotes a diagnostic imaging modality employing vertically or horizontally oriented magnetic fields with non-enclosed gantry architectures, typically operating at field strengths below 1.0 Tesla to accommodate obese, pediatric, or claustrophobic patients who cannot tolerate conventional closed-bore systems. The technology relies on permanent magnet or resistive electromagnet configurations rather than superconducting solenoids, producing lower signal-to-noise ratios that manufacturers offset through advanced gradient coil design and proprietary pulse sequences. Open MRI systems command the largest share of the product type landscape due to their established reimbursement codes and broad clinical acceptance, while extremity MRI represents the fastest-growing configuration as orthopedic practices seek dedicated extremity scanners to decompress hospital radiology departments. Among end users, imaging centers capture the most favorable margin pools through volume-based contracts with payers, whereas research institutions drive technology validation for emerging low-field applications.
FDA 510(k) premarket notification requirements govern device clearance timelines and predicate device selection strategies for manufacturers seeking to introduce modified open MRI platforms. The Centers for Medicare & Medicaid Services physician fee schedule directly shapes demand by setting reimbursement differentials between hospital-based and freestanding imaging procedures. Stakeholders must monitor how CMS site-neutral payment proposals alter capital deployment calculations for outpatient open MRI investments.
Market Dynamics
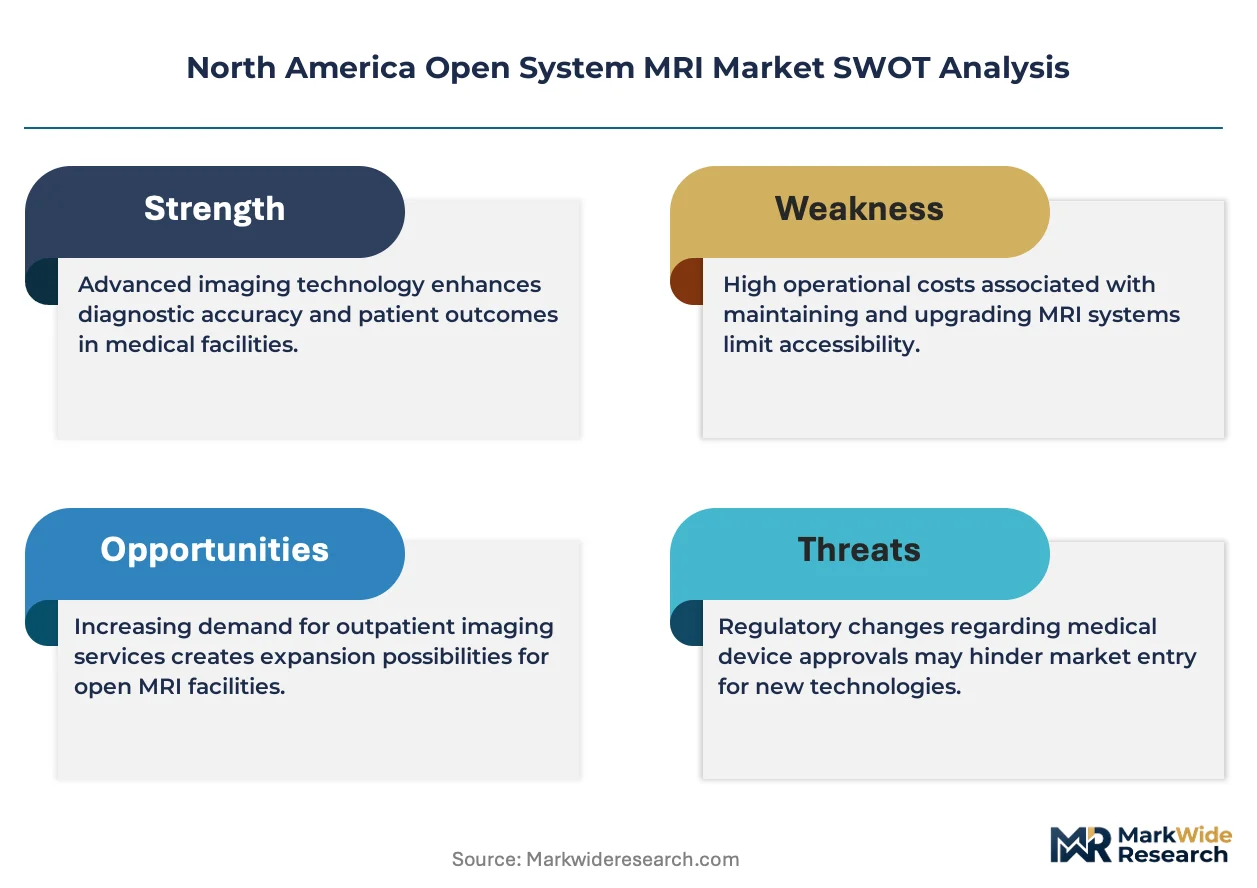
Site-neutral payment pressure from CMS is compressing margin differentials between hospital-based and freestanding imaging procedures, forcing capital deployment toward lower-cost open MRI configurations that maintain reimbursement parity.
Growth Catalysts
- CMS Site-Neutral Payment Parity:The physician fee schedule eliminates reimbursement gaps between hospital outpatient departments and ambulatory surgery centers, redirecting capital toward freestanding open MRI installations in the southeastern United States.
- Pediatric Sedation Reduction Mandates:Children's hospital networks are procuring open architecture systems to cut anesthesia exposure in claustrophobic patients, with procurement committees weighting patient throughput metrics heavily.
- Helium Conservation Technologies:Closed-loop cryogenic cooling systems and conduction-cooled magnet designs are slashing operational helium dependency, reducing supply chain vulnerability for imaging center operators.
Market Restraints
- Permanent Magnet Rare-Earth Concentration:Neodymium and samarium supply chains concentrate in Chinese processing facilities, exposing North American manufacturers to export quota volatility and price spikes.
- Signal-to-Noise Ratio Ceiling:Low-field open architectures cannot achieve the spatial resolution of 1.5 Tesla closed-bore systems, limiting diagnostic confidence in neurologic and oncologic applications.
- FDA Predicate Device Pathway Friction:510(k) clearance requires demonstration of substantial equivalence to legacy systems, slowing iterative hardware improvements that lack direct predicate matches.
Strategic Opportunities
- Extremity-Dedicated Scanner Deployment:Orthopedic practices in Texas and Florida are leasing compact open systems to decompress hospital radiology queues, creating recurring revenue streams through volume-based service contracts.
- AI-Accelerated Image Reconstruction:Deep learning algorithms trained on low-field acquisitions are compensating for raw signal limitations, enabling diagnostic equivalence claims that expand reimbursable indications.
- Veterans Affairs Mobile Screening Programs:The VA health system is piloting trailer-mounted open MRI units for rural access initiatives, establishing procurement templates that private payers may adopt.
Industry Challenges
- Superconducting Wire Fabrication Talent Scarcity:Domestic manufacturers lack sufficient trained technicians for niobium-titanium filament drawing and cable assembly, constraining in-house magnet production scale-up.
- Legacy PACS Integration Complexity:Open MRI vendors must maintain backward compatibility with decade-old DICOM routing infrastructure prevalent in community hospital networks, delaying software modernization roadmaps.
- Helium Stewardship Compliance Burden:EPA reporting requirements for cryogen venting and recovery systems add operational overhead that smaller imaging center operators struggle to absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Open System MRI Market |
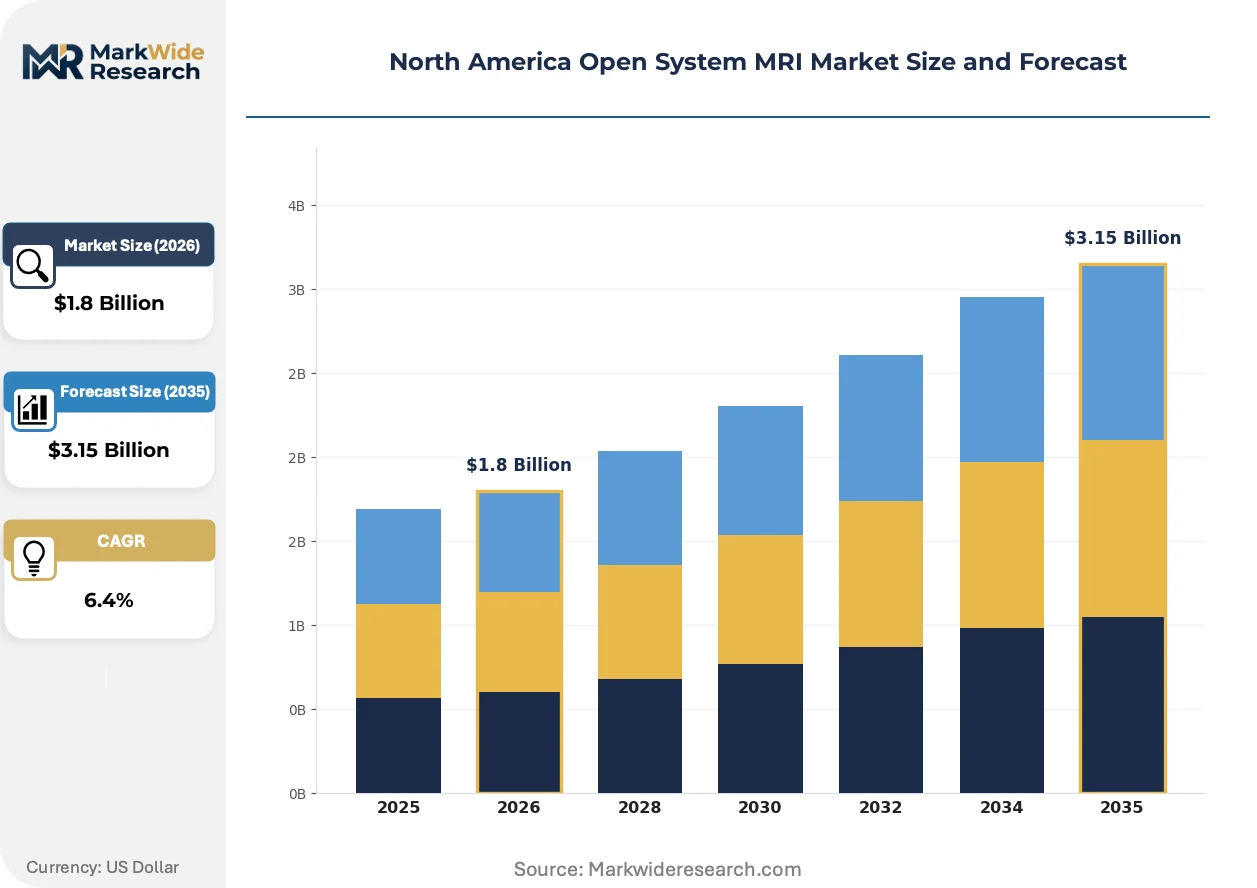
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Imaging Centers, Research Institutions, Outpatient Clinics Technology: MRI Software, Image Reconstruction, Wireless MRI, Contrast Agents Application: Neurology, Oncology, Orthopedics, Cardiovascular |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Esaote SPA, FUJIFILM Corporation, Hitachi Healthcare, Hyperfine, Inc., Neusoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Open System MRI Market Evolving Landscape
Workflow automation and artificial intelligence are compressing scan acquisition times while expanding the clinical utility of low-field magnetic resonance platforms beyond traditional niche applications.
Permanent magnet arrays with active shimming coils are decentralizing diagnostic imaging capacity into retail health clinics and urgent care settings. Walmart Health and CVS MinuteClinic pilot programs in Georgia and North Carolina are deploying these systems for same-day musculoskeletal evaluations. The technology is decentralizing referral patterns that previously funneled all MRI demand into hospital radiology departments.
FDA 510(k) premarket notification pathways for AI-enabled image reconstruction software are accelerating clearance timelines for low-field system manufacturers. The agency's predetermined change control plans allow iterative algorithm updates without full resubmission, reducing regulatory friction. Diagnostic imaging centers are responding by front-loading capital into software-upgradable hardware platforms rather than locked-configuration purchases.
Subscription-based equipment access models are displacing traditional capital purchase arrangements across independent imaging center networks. Third-party financing entities are acquiring scanner fleets and charging per-scan usage fees, transferring obsolescence risk from clinic operators to lessors. This shift concentrates most visibly in Arizona and Nevada, where private equity-backed radiology groups are consolidating through asset-light expansion strategies.
North America Open System MRI Market Segmentation
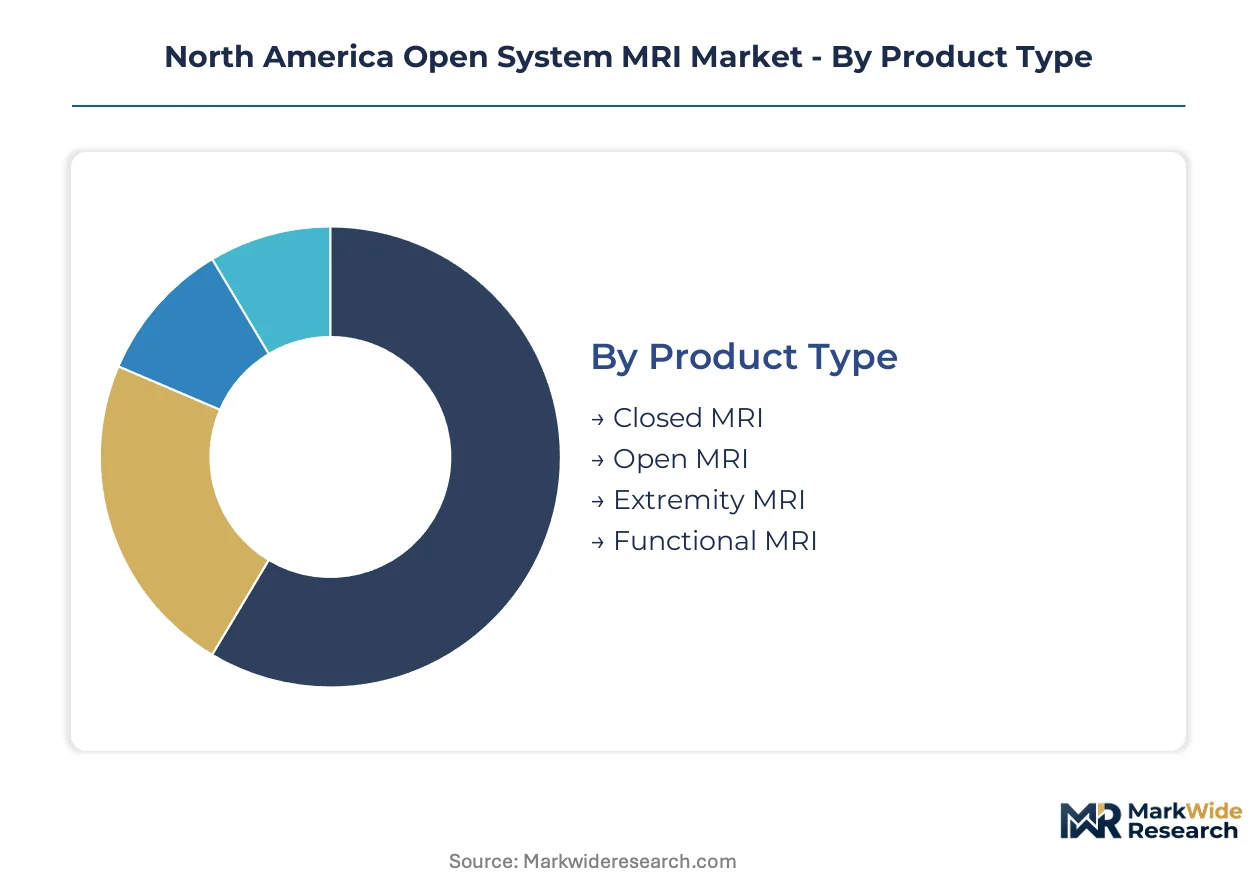
Segmentation in the North America Open System MRI Market reveals how architectural preferences, reimbursement site neutrality, and clinical specialization reshape procurement priorities across hospital networks and independent operators. Understanding these divisions exposes where capital deployment concentrates and which configurations command sustainable margin structures.
Product Type:
Magnetic field architecture and patient accessibility define the primary technology axis, with gantry design directly determining addressable patient populations and operational helium requirements.
- Open MRI:Non-enclosed gantry systems employing permanent magnets or resistive electromagnets below 1.0 Tesla field strength accommodate obese, pediatric, and claustrophobic patients. Demand concentrates in southeastern United States ambulatory imaging centers where site-neutral CMS reimbursement parity favors lower-capital configurations that maintain procedural payment equivalence with hospital outpatient departments.
- Extremity MRI:Compact dedicated scanners isolate magnetic fields to limbs and joints, eliminating whole-body enclosure requirements entirely. Orthopedic practices in Texas and Florida are leasing these systems to decompress hospital radiology queues, creating recurring revenue streams through volume-based service contracts that bypass traditional capital purchase burdens.
- Closed MRI:Cylindrical superconducting solenoid architectures achieve superior signal-to-noise ratios at 1.5 Tesla and above. Academic medical centers in the United States and Canada retain these for neurologic and oncologic applications where spatial resolution thresholds prove non-negotiable.
- Functional MRI:Blood-oxygen-level-dependent imaging sequences map neural activation patterns during cognitive tasks. Research institutions in Massachusetts and California drive validation protocols for emerging low-field applications that could eventually migrate to open architectures.
Open MRI leads on installed scale across hospital networks and imaging centers; Extremity MRI leads on deployment momentum as orthopedic specialists seek dedicated capacity.
End User:
Capital access and reimbursement mechanics split demand between integrated health systems and independent operators, with site ownership determining equipment financing strategies.
- Imaging Centers:Freestanding facilities capture favorable margin pools through volume-based contracts with commercial payers, leveraging CMS site-neutral payment parity to match hospital outpatient reimbursement rates while operating lower-overhead real estate footprints concentrated in Arizona and Nevada.
- Hospitals:Integrated delivery networks anchor procurement volume through pediatric sedation reduction mandates, with children's hospital networks specifically weighting patient throughput metrics and anesthesia exposure minimization in open architecture system selection committees.
- Research Institutions:Academic medical centers validate emerging low-field diagnostic applications, generating predicate device pathways and algorithm training datasets that downstream commercial deployments depend upon for FDA 510(k) clearance substantiation.
- Outpatient Clinics:Retail health pilots at Walmart Health and CVS MinuteClinic locations in Georgia and North Carolina deploy permanent magnet arrays with active shimming coils for same-day musculoskeletal evaluations, decentralizing referral patterns from traditional hospital radiology departments.
Imaging centers command the most favorable margin economics; outpatient clinics are gaining share fastest through retail health expansion.
Technology:
Software and acquisition methodology differentiation increasingly determines competitive positioning as hardware commoditizes across field strength tiers.
- Image Reconstruction:Deep learning algorithms trained on low-field acquisitions compensate for raw signal limitations, enabling diagnostic equivalence claims that expand reimbursable indications and accelerate FDA 510(k) clearance timelines through predetermined change control plans.
- MRI Software:Integrated diagnostic workflow platforms connect open MRI scanners to enterprise imaging archives, with proprietary DICOM routing infrastructure determining backward compatibility requirements for decade-old PACS installations prevalent in community hospital networks.
- Wireless MRI:Untethered coil arrays and data transmission architectures reduce patient positioning constraints and scanning room infrastructure requirements. Development concentrates in Canadian and United States research corridors seeking to eliminate cable-related artifacts and improve pediatric compliance.
- Contrast Agents:Gadolinium-based and emerging iron oxide nanoparticle formulations enhance tissue differentiation in low-field environments where native contrast proves insufficient for diagnostic confidence in oncologic staging protocols.
MRI Software anchors current procurement decisions; Image Reconstruction commands the steepest expansion trajectory as AI-enabled platforms mature.
Application:
Clinical indication requirements dictate field strength minimums and gantry accessibility tradeoffs that segment addressable hardware configurations.
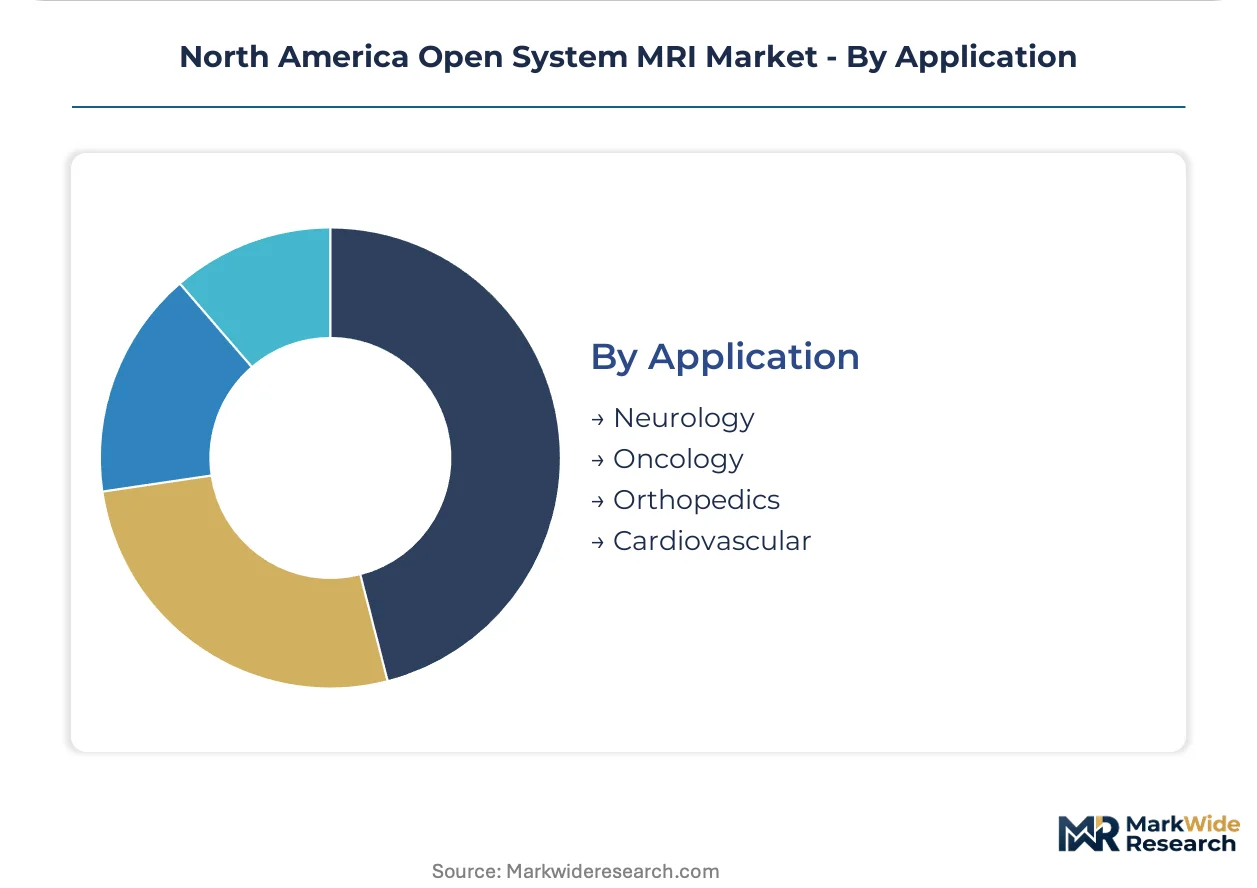
- Orthopedics:Joint and soft tissue imaging tolerates lower signal-to-noise ratios, making open and extremity-dedicated systems clinically viable while supporting same-day diagnostic workflows in ambulatory settings that hospital-based departments cannot match.
- Neurology:Brain parenchyma and white matter tract visualization demands spatial resolution that low-field open architectures struggle to achieve, limiting penetration to screening protocols and claustrophobic patient populations unable to tolerate closed-bore examinations.
- Oncology:Tumor delineation and treatment response monitoring require consistent slice thickness and contrast resolution that currently favor higher-field closed systems, though AI reconstruction advances are gradually eroding this technical barrier.
- Cardiovascular:Cardiac gating and flow quantification sequences impose temporal resolution constraints that stress gradient coil performance in permanent magnet configurations, restricting open MRI penetration to peripheral vascular and structural screening applications.
Orthopedics dominates current open system deployment; cardiovascular applications are climbing the fastest as conduction-cooled magnet designs improve gradient fidelity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between jurisdictions are redirecting capital deployment across North American markets, with regulatory arbitrage favoring sub-regions offering streamlined FDA predicate pathways and favorable CMS reimbursement mechanics.
United States
Pediatric sedation reduction mandates and site-neutral payment parity are accelerating open MRI procurement in children's hospital networks and freestanding imaging centers. FDA 510(k) clearance pathways for low-field portable systems concentrate development activity in Massachusetts and California research corridors. The southeastern United States dominates ambulatory imaging center construction, with Georgia and Florida outpacing other sub-regions in scanner installations.
Canada
Domestic rare-earth processing partnerships are reorienting magnet coil supply chains away from concentrated Chinese sources toward integrated North American suppliers. Health Canada regulatory frameworks govern device approval timelines for provincial health system procurement. Ontario and Quebec anchor manufacturing partnerships with academic medical centers validating low-field diagnostic applications.
Southeast United States
Walmart Health and CVS MinuteClinic pilot programs in Georgia and North Carolina are deploying permanent magnet arrays for same-day musculoskeletal evaluations. CMS site-neutral reimbursement parity eliminates payment gaps between hospital outpatient departments and ambulatory surgery centers. Retail health expansion is decentralizing referral patterns from traditional hospital radiology departments.
Texas and Florida
Orthopedic practices are leasing compact extremity-dedicated systems to decompress hospital radiology queues through volume-based service contracts. Private equity-backed radiology groups are consolidating through asset-light expansion strategies concentrated in Arizona and Nevada. Conduction-cooled magnet designs are improving gradient fidelity for cardiovascular screening applications.
California and Massachusetts
Research institutions are validating emerging low-field applications and generating predicate device pathways for FDA 510(k) clearance substantiation. Deep learning algorithm development for AI-accelerated image reconstruction concentrates in Boston and San Francisco technology corridors. Academic medical centers retain higher-field closed systems for neurologic and oncologic applications where spatial resolution thresholds remain non-negotiable.
North America Open System MRI Market Competitive Landscape
United States and German producers anchor the premium-tier equipment segment; Japanese and Italian specialists hold positions in compact dedicated configurations. The vendor base clusters around three strategic archetypes: diversified imaging conglomerates with established installed bases, mid-scale manufacturers emphasizing helium-conservation technologies, and emerging entrants pursuing AI-enabled software differentiation. Capacity expansion through domestic magnet production and strategic partnerships for rare-earth supply security represent dominant competitive moves.
Among diversified imaging conglomerates, Siemens Healthineers and GE Healthcare exemplify archetypes built on superconducting wire manufacturing and service contract renewal strategies. Koninklijke Philips N.V. occupies a position emphasizing integrated diagnostic workflow software. These three companies represent the established tier against which emerging low-field specialists benchmark platform development.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Esaote SPA |
| FUJIFILM Corporation |
| Hitachi Healthcare |
| Hyperfine, Inc. |
| Neusoft Corporation |
| Others |
Value Network & Pricing Analysis
Freestanding imaging center operators in Arizona and Nevada anchor procurement volume for open MRI systems, driving subscription-based equipment access models that displace traditional capital purchase arrangements. The southeastern United States ambulatory construction boom concentrates buyer leverage, pressuring manufacturers toward per-scan usage fee structures that transfer obsolescence risk from clinic operators to third-party lessors.
Pricing Analysis
Distributor margins for permanent magnet arrays compress as direct-to-imaging-center leasing arrangements bypass traditional equipment financing intermediaries. Three-tier pricing structure across premium superconducting configurations, standard resistive electromagnet platforms, and economy-grade permanent magnet systems stratifies by helium dependency and field strength. Cost compression in low-field segments intensifies because CMS site-neutral payment parity eliminates reimbursement premiums that previously justified higher capital outlays. Pediatric hospital networks exhibit least price sensitivity due to sedation reduction mandates, while independent orthopedic practices in Texas and Florida demonstrate highest sensitivity as they evaluate extremity-dedicated scanner leases against hospital radiology queue decompression economics.
Supply Chain Analysis
Trained technician scarcity for niobium-titanium filament drawing and cable assembly constrains domestic superconducting wire fabrication scale-up in the United States and Canada. Magnet coil production draws from Chinese rare-earth processing facilities for neodymium and samarium, Japanese precision manufacturing for gradient coil assemblies, and German engineering centers for cryogenic cooling system components. Single-source vulnerability in Chinese export quota administration for rare-earth elements exposes North American manufacturers to price spike and supply interruption risk. Distribution runs through OEM direct sales forces for hospital networks, third-party financing entities for imaging center fleets, and specialized orthopedic distributor channels for extremity-dedicated configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA 510(k) clearance timelines in the United States and Health Canada provincial procurement frameworks creates geographic cost differentials for manufacturers seeking optimal market entry sequencing. The southeastern United States offers streamlined predicate device pathways and favorable CMS reimbursement mechanics that accelerate capital deployment returns relative to Canadian provincial health system procurement cycles.
For Market Incumbents: Lock in service contract renewal rates at academic medical centers by embedding proprietary superconducting wire manufacturing capabilities that reduce helium dependency and operational disruption risk. Defend against AI-enabled image reconstruction specialists by front-loading capital into software-upgradable hardware platforms rather than locked-configuration purchases, preserving upgrade revenue streams through predetermined change control plans that accommodate iterative algorithm deployment without full FDA resubmission. For New Entrants and Emerging Players: Direct-to-imaging-center digital sales channels bypass established OEM distributor relationships and concentrate initial penetration in Arizona and Nevada where private equity-backed radiology groups pursue asset-light expansion. White-space targets include trailer-mounted mobile screening units for Veterans Affairs rural access initiatives and permanent magnet arrays for Walmart Health and CVS MinuteClinic retail health pilots in Georgia and North Carolina. The most penetrable segment comprises orthopedic practices in Texas and Florida seeking extremity-dedicated scanner leases to decompress hospital radiology queues. For Investors and Strategic Acquirers: Private equity-backed radiology groups are the most active acquirer in this space, consolidating independent imaging center networks through subscription-based equipment access models that concentrate obsolescence risk with lessors. Long-term viability over the five-to-ten year window hinges on AI reconstruction algorithm validation achieving diagnostic equivalence claims that expand reimbursable indications for low-field platforms. Acquisition target archetypes include mid-scale manufacturers emphasizing helium-conservation technologies and emerging entrants with FDA-cleared AI-enabled image reconstruction software. Watch FDA predetermined change control plan adoption rates as the signal indicating when software-upgradable hardware platforms achieve procurement preference over locked-configuration alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates time-to-market for low-field portable systems through predicate device selection strategies. |
| Helium Conservation Technology | Closed-loop cryogenic cooling reduces supply chain vulnerability for imaging center operators. |
| AI-Accelerated Image Reconstruction | Deep learning algorithms compensate for raw signal limitations in permanent magnet configurations. |
| Hospital System Partnership | Children's hospital networks weight patient throughput metrics in open architecture procurement committees. |
| Reimbursement Strategy | CMS site-neutral payment parity redirects capital toward freestanding southeastern installations. |
Research Methodology
Coverage spans the United States and Canada, with primary inputs from each jurisdiction's hospital procurement committees, biomedical engineers at academic medical centers, GPO contracts managers, and imaging center operators. The analysis combines structured interviews with these stakeholders against secondary validation from FDA 510(k) premarket notification databases, CMS physician fee schedule publications, hospital procurement databases, and Health Canada device approval records. Bottom-up scanner installation tracking and top-down capital expenditure triangulation reconcile volume estimates across the analysis window.
Rate-of-change decomposition separates volume growth from price evolution across product type, end user, technology, and application dimensions. Segmentation modeling incorporates magnetic field architecture, gantry accessibility design, helium dependency tier, and reimbursement site classification. CAGRs derive from installed base replacement cycles, ambulatory construction permit flows, and pediatric sedation reduction mandate adoption curves. Industry-specific forecast inputs include FDA clearance timeline distributions for AI-enabled reconstruction software and provincial health system procurement queue depths in Ontario and Quebec.
The model assumes a particular technology adoption path; alternative pathways for conduction-cooled magnet designs achieving diagnostic equivalence in neurologic applications would alter the outlook. Forecasts reflect assumptions regarding CMS site-neutral payment parity maintenance, rare-earth export quota stability, and AI reconstruction algorithm validation timelines. Material deviation in FDA predetermined change control plan adoption rates, Health Canada provincial procurement acceleration, or helium spot price volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Brazil Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
South America CT Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Europe Intraoperative Imaging Market