
 Ultrasound Systems Market | 2026-2036
Ultrasound Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Systems Market Outlook
Market Context
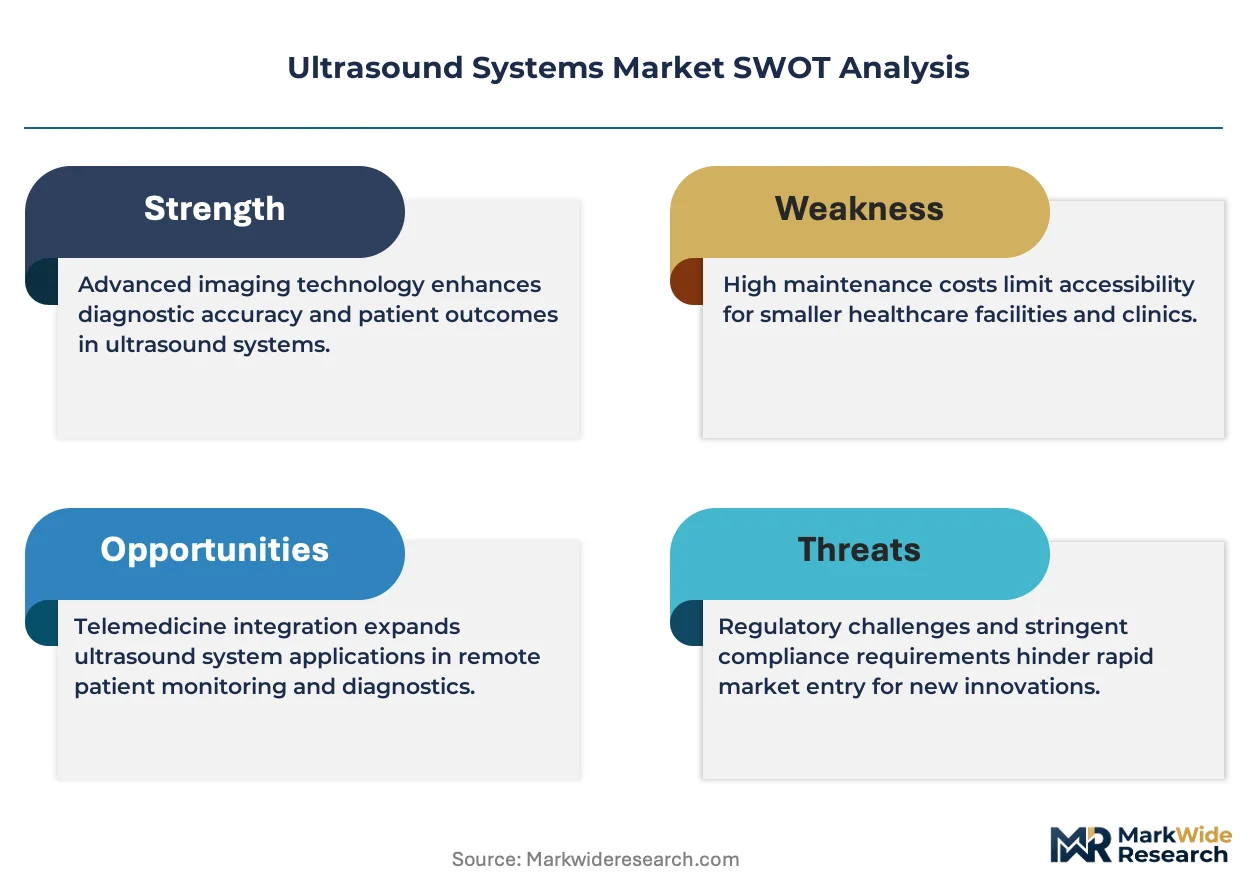
Radiologist workforce shortages across developed health systems is unwinding traditional deployment models for ultrasound equipment. GE Healthcare leverages its installed base of cart-based systems to sustain recurring service revenue across North American hospital networks. Siemens Healthineers anchors its competitive stance through proprietary transducer manufacturing and AI-enhanced imaging workflows. Mindray Medical International Limited competes aggressively on portable system cost structures, particularly in price-sensitive clinical environments.
Technical Definition and Segment Structure
Ultrasound systems generate diagnostic images through the transmission of high-frequency sound waves, typically operating at frequencies between two and eighteen megahertz, with piezoelectric crystals converting electrical pulses into acoustic energy and returning echoes into visual data. These systems serve primarily non-invasive diagnostic functions across obstetric monitoring, cardiac assessment, and guided interventional procedures. Cart-based systems dominate hospital capital budgets and absorb the majority of premium imaging expenditure, while portable systems and handheld devices represent the fastest-expanding margin pool as point-of-care protocols expand beyond radiology departments. Doppler ultrasound technology commands sustained clinical preference in cardiology and vascular applications where hemodynamic measurement determines diagnostic value.
Regulatory Framework and Outlook
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation and CE marking framework dictate conformity assessment across European markets. Japan's PMDA enforces stringent quality management system audits that extend approval timelines but elevate product reliability benchmarks for manufacturers seeking market access. Stakeholders must monitor evolving AI diagnostic algorithm classification rules as regulators distinguish between decision-support tools and autonomous diagnostic outputs.
Market Dynamics
Point-of-care diagnostic protocols are compressing deployment timelines for portable ultrasound devices, forcing manufacturers to reconfigure product portfolios around mobility-first architectures rather than traditional cart-based hospital installations.
Growth Catalysts
- FDA 510(k) Clearance Streamlining:Accelerated premarket notification pathways for AI-enabled imaging algorithms reduce time-to-market for software-integrated systems. Diagnostic workflows in emergency medicine absorb these capabilities fastest.
- Radiologist Workforce Compression:Persistent staffing gaps across developed health systems drive automation demand. Automated measurement tools and AI-assisted interpretation protocols expand operational capacity without proportional headcount expansion.
- Obstetric Monitoring Protocol Expansion:Maternal health initiatives in low-resource clinical environments create demand for battery-operated portable systems. Primary care facilities in rural India and sub-Saharan Africa deploy handheld devices for prenatal screening programs.
Market Restraints
- Piezoelectric Crystal Supply Concentration:Single-source dependencies for high-purity ceramic substrates create input volatility. Japanese and German specialty material suppliers control critical feedstock channels.
- EU Medical Device Regulation Compliance Burden:Extended conformity assessment timelines and notified body capacity constraints delay product introductions. Small and mid-sized manufacturers face disproportionate quality management system audit costs.
- CT and MRI Substitution Pressure:Advanced cross-sectional imaging modalities capture complex diagnostic cases previously referred to ultrasound. Cardiac and abdominal imaging indications face particular erosion where reimbursement favors alternative technologies.
Strategic Opportunities
- AI Algorithm Autonomy Classification:Regulatory frameworks distinguishing decision-support from autonomous diagnostic outputs create first-mover advantages. Manufacturers securing autonomous-classification clearances capture premium positioning.
- Veterinary and Equine Applications:Companion animal diagnostics and equine reproductive medicine represent underpenetrated verticals. Portable systems with species-specific preset configurations address veterinary clinic workflows.
- Home-based Dialysis Monitoring:Renal care patients requiring vascular access surveillance create ambulatory monitoring demand. Wearable Doppler prototypes under development target this chronic disease management pathway.
Industry Challenges
- Sonographer Training Pipeline Constraints:Accredited ultrasound technologist programs produce insufficient graduates to match point-of-care expansion. Clinical credentialing bodies struggle to standardize competency certification across handheld device operators.
- Legacy PACS Integration Complexity:Hospital information system architectures built around DICOM standards from cart-based systems resist seamless portable device data incorporation. IT departments face middleware development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Systems Market |
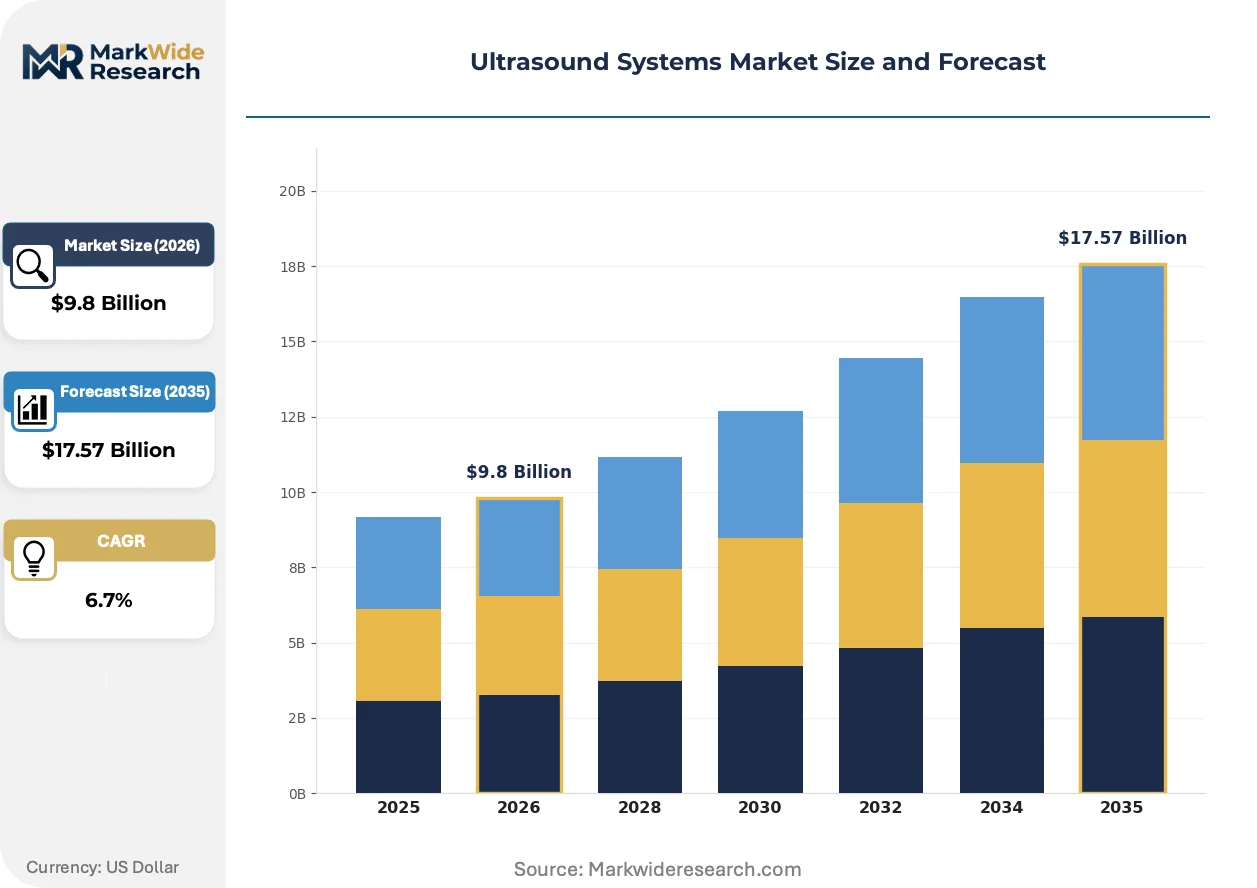
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Cart-based Systems, Handheld Devices, Tabletop Units End User: Hospitals, Diagnostic Centers, Clinics, Ambulatory Surgery Centers Application: Obstetrics, Cardiology, Urology, Musculoskeletal Technology: 2D Imaging, 3D Imaging, Doppler Ultrasound, Contrast-enhanced Ultrasound |
| Companies Covered | Canon Medical Systems Corporation, Samsung Medison, GE Healthcare, Hitachi, Mindray Medical International Limited, Koninklijke Philips N.V., Siemens Healthineers AG, Esaote, FUJIFILM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Systems Market Strategic Shifts
Semiconductor integration and edge-computing architectures are fundamentally reconfiguring device form factors, collapsing the traditional distinction between high-performance hospital systems and limited-function portable alternatives.
Capacitive micromachined ultrasonic transducer (CMUT) technology is miniaturizing probe electronics while preserving acoustic performance. Emergency departments and ambulatory surgical centers adopt these silicon-based alternatives to conventional piezoelectric arrays. The technology is miniaturizing transducer footprints sufficiently to embed diagnostic-grade imaging into catheter-based and intravascular applications previously inaccessible to external ultrasound.
Japan's PMDA has tightened quality management system audit requirements for software-as-a-medical-device classifications. Extended approval timelines elevate reliability benchmarks but compress competitive windows for algorithm updates. AI-enabled imaging workflows face particular scrutiny as regulators distinguish training-data provenance from real-world performance validation.
Hospital procurement departments now unbundle capital equipment acquisition from mandatory multi-year service contracts. Independent third-party maintenance providers capture post-warranty service revenue previously retained by original equipment manufacturers. This disintermediation is most visible in United States health systems where group purchasing organizations negotiate device-only pricing with separate competitive bidding for technical support.
Ultrasound Systems Market Segmentation
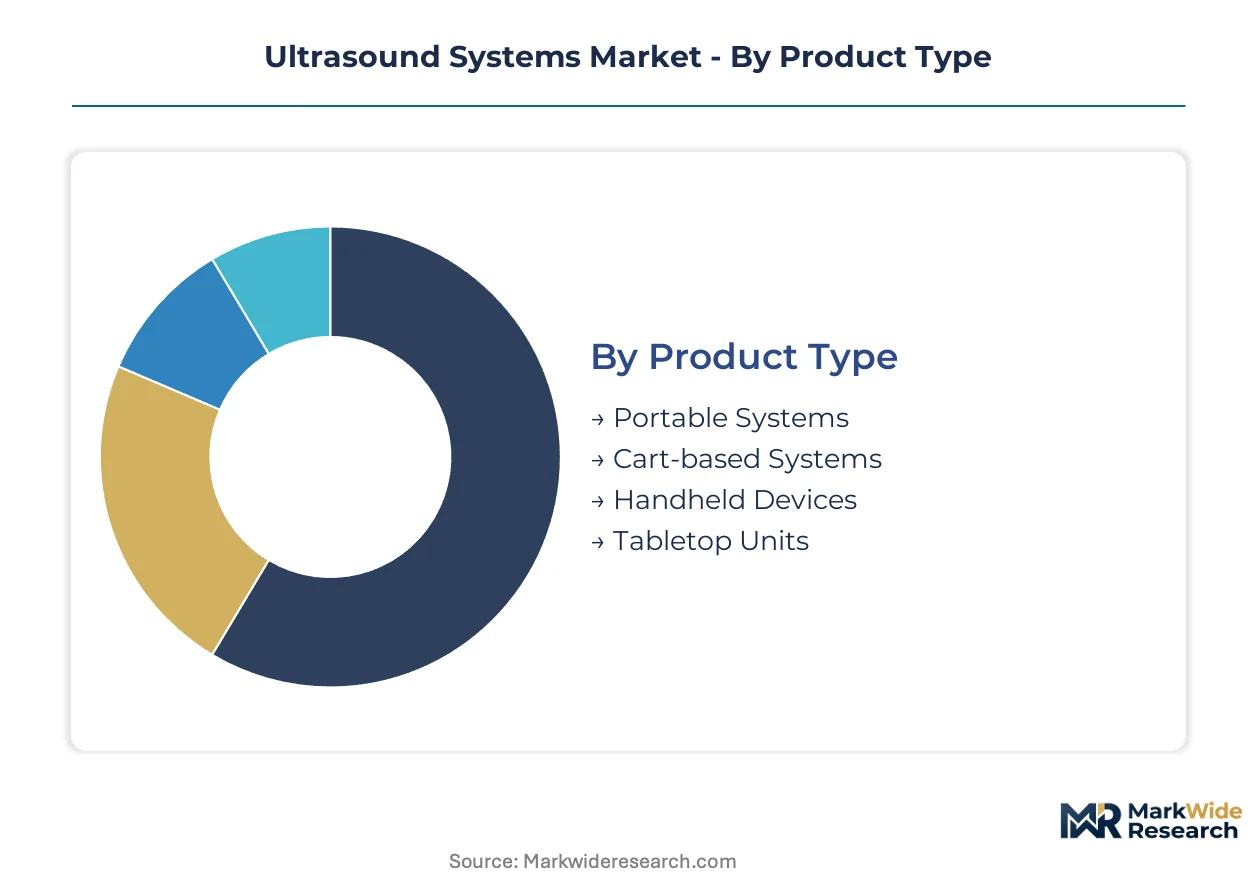
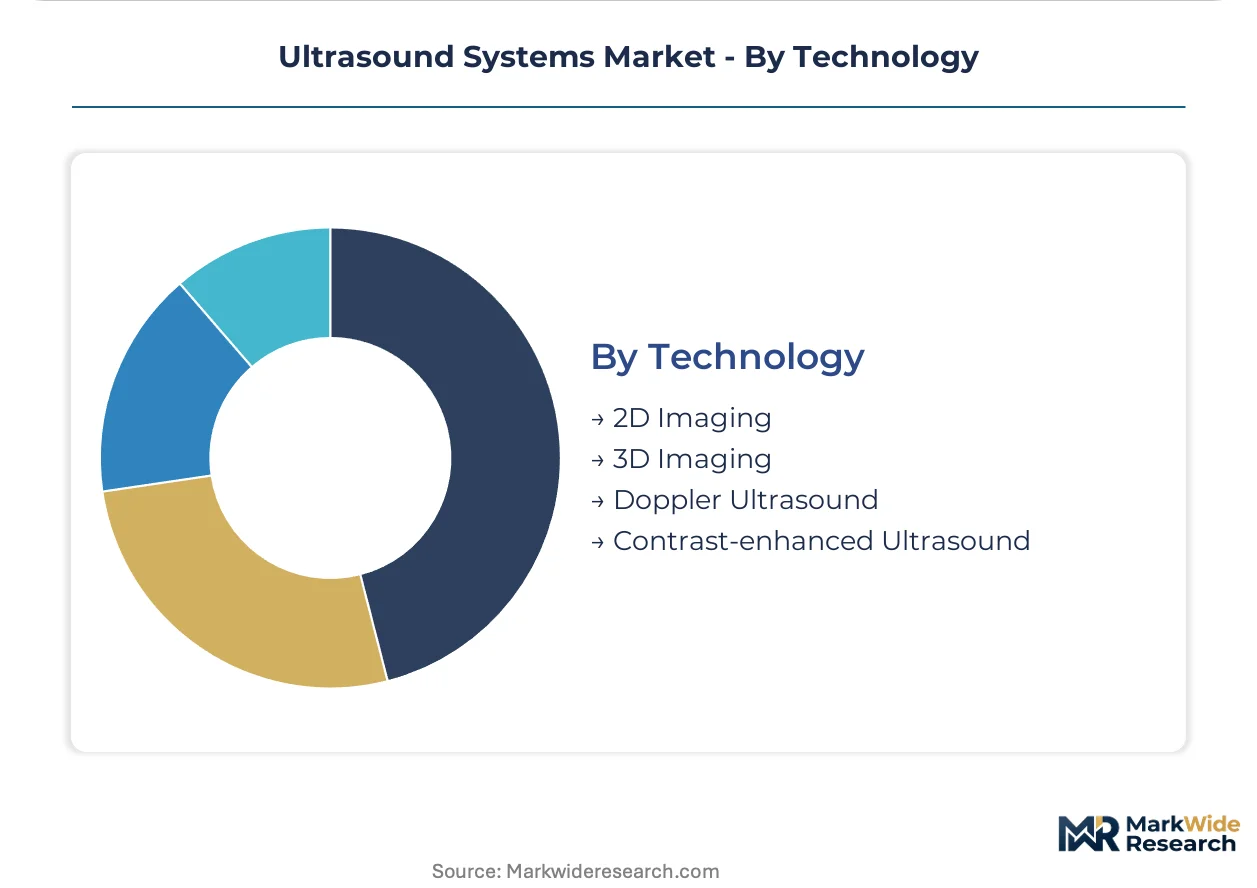
Ultrasound systems fragment across four critical dimensions that determine procurement patterns, reimbursement pathways, and manufacturer R&D allocation. Product type defines capital intensity and mobility profiles. End user concentration shapes service contract structures. Application focus dictates transducer specialization and software workflows. Technology tier governs regulatory clearance complexity and pricing premiums.
Product Type:
Premium margins concentrate in systems that balance imaging fidelity with deployment flexibility across acute care environments.
- Cart-based Systems:These floor-standing units integrate high-channel-count beamformers and multi-frequency transducer arrays for comprehensive diagnostic protocols. United States hospital networks absorb the majority of capital expenditure here, driven by cardiac and abdominal imaging reimbursement differentials that favor high-resolution acquisitions.
- Portable Systems:Battery-powered units with collapsible form factors deliver diagnostic-grade imaging at bedside and in transit. Demand clusters in German emergency medical services and United States critical access hospitals where space constraints and patient throughput pressures override traditional capital equipment preferences.
- Handheld Devices:Smartphone-connected probes enable point-of-care screening in resource-limited settings. Primary care deployments in rural India leverage these for maternal health initiatives.
- Tabletop Units:Compact stationary systems serve specialty practices with moderate throughput requirements. United States urology and vascular clinics favor these for dedicated examination rooms.
The dominant share belongs to Cart-based Systems, while Portable Systems is closing the gap fastest.
End User:
Procurement authority and service contract duration vary sharply across facility types, with hospitals commanding multi-year bundled agreements.
- Hospitals:Academic medical centers and community hospitals deploy comprehensive ultrasound fleets across radiology, cardiology, and emergency departments. China's tier-1 municipal hospitals drive replacement cycles as health system modernization programs refresh aging installed bases.
- Diagnostic Centers:Independent imaging facilities optimize equipment utilization through high patient volumes and specialized technologist staffing. German outpatient radiology chains concentrate demand for premium 3D and elastography capabilities.
- Clinics:Primary care and specialty practices adopt portable systems for in-house diagnostics. United States accountable care organizations incentivize point-of-care adoption to reduce referral leakage.
- Ambulatory Surgery Centers:Same-day surgical facilities require compact systems for preoperative assessment and procedural guidance. United States Medicare reimbursement expansions for ASC-eligible procedures expand addressable demand.
Hospitals retain the largest procurement volume, though Diagnostic Centers achieve the highest equipment utilization rates per installed unit.
Application:
Clinical indication determines transducer frequency requirements, software measurement packages, and operator training pathways.
- Obstetrics:Fetal biometric assessment and anatomical screening protocols demand specific preset configurations and gestational age calculation algorithms. China's two-child policy transition and India's maternal health programs sustain portable system demand for prenatal screening expansion.
- Cardiology:Echocardiography and hemodynamic assessment require phased-array transducers and Doppler processing capabilities. United States heart failure management protocols and German preventive cardiology guidelines elevate system specifications.
- Urology:Prostate imaging and renal assessment utilize high-frequency linear and curvilinear probes. Transrectal biopsy guidance applications in United States urology practices drive contrast-enhanced adoption.
- Musculoskeletal:Tendon, ligament, and joint evaluation employs high-resolution linear arrays with extended field-of-view stitching. Sports medicine clinics in Germany and United States physical therapy settings expand handheld device penetration.
Obstetrics commands the broadest geographic deployment, yet Cardiology generates the highest per-procedure reimbursement and software attach rates.
Technology:
Imaging modality sophistication determines regulatory classification, algorithm training requirements, and competitive differentiation potential.
- 2D Imaging:Conventional grayscale anatomical visualization remains the foundational capability across all system tiers. Screening programs in India's public health infrastructure and China's county-level hospitals depend on cost-optimized 2D platforms.
- 3D Imaging:Volume acquisition and multiplanar reconstruction enable fetal face rendering and cardiac structural assessment. United States maternal-fetal medicine subspecialists and German prenatal diagnostic centers drive premium system specifications.
- Doppler Ultrasound:Color flow and spectral Doppler quantify blood velocity and vascular resistance. Cardiology and vascular surgery departments in United States health systems mandate these capabilities for hemodynamic triage.
- Contrast-enhanced Ultrasound:Microbubble-based perfusion imaging expands lesion characterization without ionizing radiation. United States liver imaging and German kidney transplant surveillance protocols adopt these workflows as CT/MRI alternatives face reimbursement constraints.
2D Imaging underpins the majority of installed units, though 3D Imaging carries the steepest expansion trajectory in high-acuity subspecialty settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultrasound deployment patterns diverge sharply by geography: United States hospitals favor premium cart-based systems for cardiac subspecialty reimbursement, while emerging health systems in India and sub-Saharan Africa prioritize handheld portability for maternal screening outreach.
United States
Academic medical centers and community hospital networks drive replacement demand for AI-integrated echocardiography platforms. FDA 510(k) clearance pathways for autonomous diagnostic algorithms compress software update cycles. Major procurement clusters concentrate in Texas Medical Center and Greater Boston, where accountable care organizations incentivize point-of-care adoption to reduce specialist referral leakage.
Germany
Outpatient radiology chains and emergency medical services sustain premium portable system demand through preventive cardiology guidelines. EU Medical Device Regulation conformity assessments extend approval timelines but elevate reliability benchmarks for manufacturers. Industrial concentration centers on Erlangen and Munich, where Siemens Healthineers anchors proprietary transducer manufacturing and AI-enhanced imaging workflows.
China
Tier-1 municipal hospitals in Beijing, Shanghai, and Guangzhou refresh aging installed bases under health system modernization programs. NMPA regulatory frameworks accelerate domestic manufacturer approvals while maintaining stringent quality audits for imported systems. The Yangtze River Delta cluster houses Mindray Medical International Limited's cost-optimized portable production for price-sensitive clinical environments.
India
Rural maternal health initiatives and primary care expansion create sustained demand for battery-operated handheld devices. CDSCO medical device registration requirements are streamlining for Class B and C diagnostics. Procurement concentrates in Maharashtra and Karnataka, where public-private partnerships deploy portable systems for prenatal screening in district hospitals.
Japan
PMDA quality management system audits enforce extended approval timelines that elevate product reliability benchmarks for manufacturers seeking market access. Aging demographics and preventive cardiology protocols sustain echocardiography demand in Tokyo and Osaka metropolitan hospitals. The Kanto region hosts concentrated R&D activity for CMUT silicon-based transducer alternatives to conventional piezoelectric arrays.
Ultrasound Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum controlling proprietary beamformer architectures and transducer manufacturing while mid-scale competitors differentiate through portable form-factor cost engineering. The competitive terrain separates into three archetypes: diversified health technology conglomerates with installed base leverage, dedicated imaging specialists with vertical transducer control, and emerging portable-first challengers with semiconductor integration capabilities. Dominant competitive moves include unbundling capital equipment from mandatory service contracts and securing autonomous-classification AI clearances for premium positioning.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers exemplify the integrated leader archetype through captive supply of critical imaging components and recurring service revenue capture. Within the portable-specialist tier, Mindray Medical International Limited occupies a position representing aggressive cost-structure competition for point-of-care deployments. Japanese manufacturers including Canon Medical Systems Corporation and Hitachi sit within the precision-component specialist category, leveraging domestic piezoelectric material supply chains.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Samsung Medison |
| GE Healthcare |
| Hitachi |
| Mindray Medical International Limited |
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| Esaote |
| FUJIFILM Corporation |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance tiers gate both supplier qualification and price differentiation simultaneously, with autonomous-classification pathways commanding premium positioning while standard decision-support tools compete on portable system cost structures in price-sensitive clinical environments.
Pricing Analysis
Long-term service contracts dominate hospital procurement, though independent third-party maintenance providers increasingly capture post-warranty revenue through unbundled technical support bidding. Three-tier pricing structure across premium cart-based, standard portable, and economy handheld levels reflects imaging fidelity, AI integration depth, and after-sales bundling intensity. Cost compression in handheld tiers intensifies because Mindray and domestic Chinese manufacturers compete aggressively on semiconductor integration costs. Diagnostic centers exhibit least price sensitivity due to high equipment utilization rates, while rural primary care facilities in India and sub-Saharan Africa demand lowest acquisition costs.
Supply Chain Analysis
Strategic stockpiling of piezoelectric ceramic substrates persists among Japanese and German manufacturers facing single-source feedstock vulnerabilities, while portable system assemblers maintain leaner just-in-time inventories of CMUT silicon wafers. Critical component concentration centers on Japan for high-purity ceramic crystals, Germany for specialty transducer manufacturing, and China for cost-optimized portable assembly. Raw material dependencies encompass lead zirconate titanate ceramics, silicon-on-insulator wafers, and lithium niobate substrates. Tariff exposure on semiconductor components threatens margin stability for manufacturers with China-centric assembly footprints. Distribution runs through group purchasing organizations in United States hospital networks, direct hospital sales in Germany, and public-private procurement partnerships in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care protocol expansion across emergency medicine and maternal health programs positions ultrasound systems for early-cycle penetration growth, with handheld device adoption in low-resource settings representing the most visible tailwind.
For Market Incumbents: Consolidate installed base leverage through captive transducer supply and multi-year service contract retention against disintermediation threats from independent maintenance providers. Deepen backward integration into CMUT semiconductor fabrication to defend component cost position against portable-first challengers. Prioritize autonomous-classification AI clearances to sustain premium pricing tiers as decision-support tools commoditize.
For New Entrants and Emerging Players: Lead with veterinary and equine reproductive medicine applications where species-specific preset configurations address underpenetrated clinic workflows. Target home-based dialysis monitoring for ambulatory Doppler surveillance of vascular access in renal patient populations. Pursue direct-to-veterinarian digital sales channels bypassing traditional hospital GPO procurement structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health technology conglomerates seeking to divest non-core imaging divisions amid portfolio rationalization pressures. Five-to-ten year viability hinges on semiconductor integration capabilities and AI algorithm autonomy clearances rather than legacy beamformer architectures. Monitor FDA autonomous-classification clearance velocity as inflection indicator for premium positioning sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous AI Classification Pursuit | FDA 510(k) autonomous clearances separate premium tier from commoditized decision-support tools. |
| CMUT Transducer Manufacturing Scale-Up | Silicon-based probe miniaturization enables catheter-based applications previously inaccessible to external ultrasound. |
| Veterinary Preset Configuration Development | Companion animal diagnostics and equine reproductive medicine represent underpenetrated vertical expansion pathways. |
| Service Contract Unbundling Response | Independent third-party maintenance capture necessitates defensive pricing on post-warranty technical support. |
| Home Dialysis Monitoring Wearable Development | Ambulatory Doppler prototypes target chronic renal care vascular access surveillance outside hospital settings. |
Study Parameters
Operator-level perspectives from hospital purchasing committees, biomedical engineers, emergency department clinicians, and GPO contracts managers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, NMPA registration filings, hospital procurement records, and CMS reimbursement schedules. Bottom-up unit economics triangulated against top-down health system capital expenditure patterns across the analysis window.
Sensitivity analysis tested forecast robustness across alternative regulatory approval timelines, piezoelectric supply disruption scenarios, and AI algorithm classification pathway assumptions. Segmentation modeling incorporated product type mobility profiles, end-user procurement authority structures, application-specific transducer requirements, and technology tier regulatory complexity. CAGRs derived from installed base replacement cycles, point-of-care protocol expansion rates, and emerging market penetration trajectories. Forecast inputs encompassed radiologist workforce shortage projections, semiconductor cost curves, and maternal health initiative funding flows.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and NMPA frameworks; material policy shifts on AI algorithm classification would require re-modeling. Supply concentration in Japanese and German piezoelectric feedstock channels, PMDA audit timeline extensions, and CT/MRI reimbursement favorability represent specific revision triggers. Revision becomes warranted when portable system cost compression accelerates beyond semiconductor integration pace or autonomous AI clearances stall relative to decision-support tool proliferation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Industrial Radiography Equipment Market
Medical Imaging
Medical Digital Imaging Devices Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Canada Digital Radiology Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Industrial X-Ray Machine Market